
 DC Distribution Network Market | 2026-2036
DC Distribution Network Market Size, Share, and Industry Trends Forecast 2026-2036
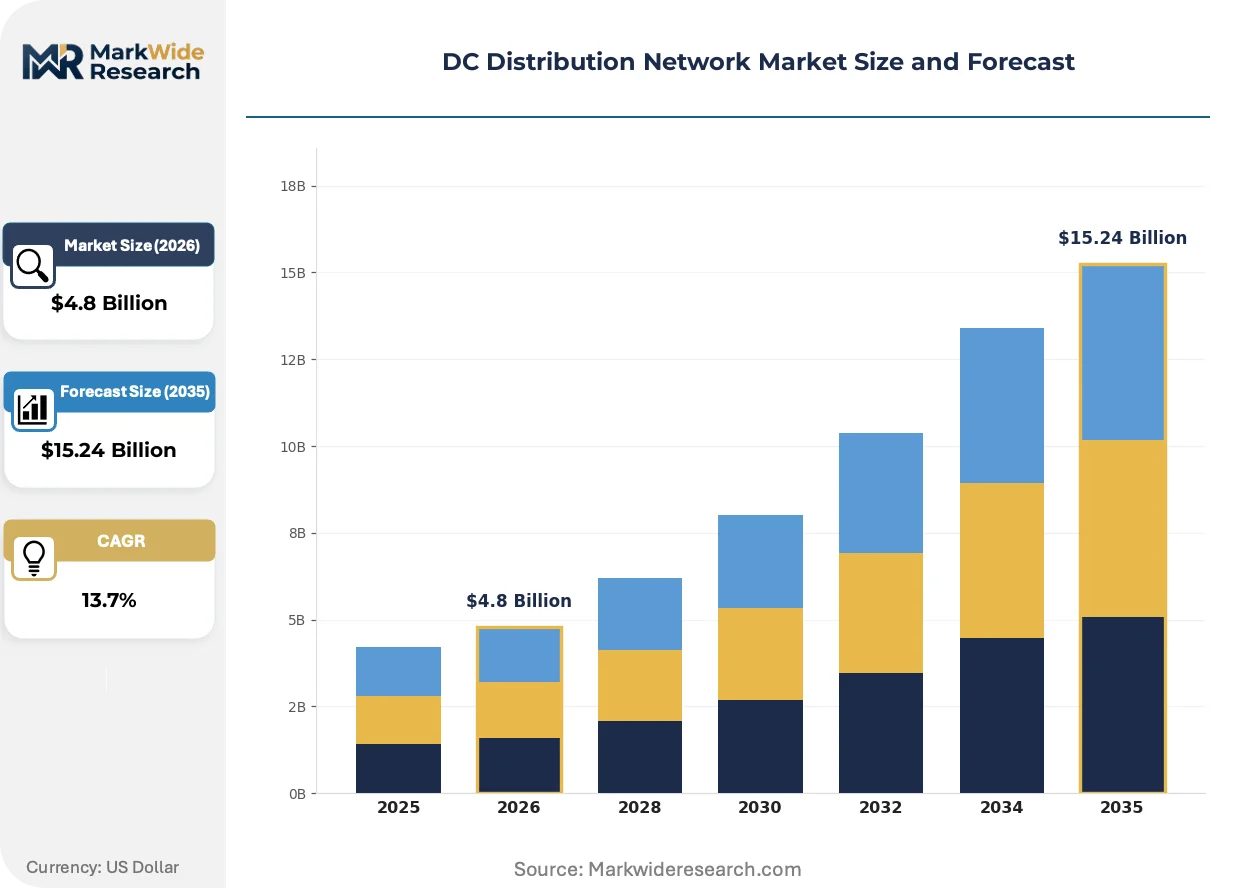
DC Distribution Network Market Outlook
Utility-grade reliability specifications are redrawing competitive boundaries in DC distribution. Eaton Corporation leverages its circuit protection portfolio to anchor utility-scale microgrid deployments across North America. ABB Ltd sustains technology leadership through its 1,500 V DC switchgear platforms designed for photovoltaic integration. Siemens AG competes on manufacturing scale, operating dedicated production lines for data center busway systems in Nuremberg.
A DC distribution network is an electrical infrastructure that transmits power using direct current at voltages typically ranging from 380 V to 1,500 V, eliminating AC-DC conversion stages that introduce energy losses in renewable and digital loads. These systems serve industrial facilities, hyperscale computing campuses, and EV charging hubs where load profiles favor native DC consumption. Circuit breakers and switchgear represent the most mature product categories, with established margin pools in retrofit installations, while solid-state battery inverters are capturing accelerated investment as storage durations extend beyond four hours. Data centers and telecommunications end users are driving the fastest technology uptake, particularly for backup power applications where lithium-titanate configurations replace legacy lead-acid strings.
FERC Order 2222 enables aggregated distributed energy resources to participate in wholesale markets, directly expanding addressable revenue for DC network operators in the United States. The EU F-Gas Regulation and REACH chemical restrictions are tightening insulation and coolant specifications for switchgear deployed across European industrial zones. IEC 61215-1 testing protocols for photovoltaic modules indirectly shape DC distribution design by validating string-level voltage tolerances. Stakeholders must monitor evolving interconnection standards and carbon border adjustment mechanisms to align product roadmaps with compliance timelines.
Market Dynamics
Data center operators are eliminating AC-DC conversion stages entirely, rewiring power delivery architectures around native DC consumption to capture efficiency gains and reduce thermal load. This voltage-standard consolidation is compressing equipment procurement cycles and forcing incumbent suppliers to recertify product portfolios.
Growth Catalysts
- FERC Order 2222:Aggregated distributed energy resources gain wholesale market participation rights in the United States, expanding revenue pathways for DC microgrid operators and storage-integrated network developers.
- Hyperscale computing load concentration:Cloud infrastructure providers in Northern Virginia and Frankfurt are specifying 750 V DC bus architectures for new campus construction, creating pull-through demand for compatible switchgear and protection equipment.
- Lithium-titanate battery chemistry:Four-hour discharge configurations are displacing legacy lead-acid strings in telecommunications backup applications, requiring DC distribution networks with higher fault-current tolerance and faster protection coordination.
Market Restraints
- Copper price volatility:Busway and cable conductor costs fluctuate with London Metal Exchange pricing, compressing margins for fixed-price infrastructure contracts in industrial retrofit segments.
- SF6 insulation dependency:European switchgear manufacturers face supply constraints and substitution complexity under the EU F-Gas Regulation phase-down schedule for medium-voltage DC circuit breakers.
- AC infrastructure lock-in:Existing transformer substations and protection relay schemes in mature industrial zones create path dependency that slows greenfield DC adoption despite lifecycle cost advantages.
Strategic Opportunities
- India industrial corridor electrification:PLI scheme incentives for domestic manufacturing are drawing DC microgrid developers to Gujarat and Tamil Nadu textile clusters seeking captive renewable integration.
- Vehicle-to-grid convergence:Bidirectional charging protocols for heavy-duty electric trucks are creating demand for 1,000 V DC distribution networks at logistics depots and port terminals.
- EU carbon border adjustment mechanism:Embodied carbon accounting for imported electrical equipment is creating preference for locally manufactured DC switchgear with verified supply chain emissions data.
Industry Challenges
- IEC 61215-1 validation bottlenecks:String-level voltage tolerance testing for photovoltaic modules creates certification delays for DC distribution equipment intended for solar-direct coupling.
- Protection coordination expertise scarcity:Solid-state circuit breaker deployment requires power electronics specialists familiar with wide-bandgap semiconductor failure modes, a skill set concentrated among limited engineering consultancies.
- Legacy AC protection interoperability:Hybrid networks with mixed DC-AC zones demand dual-protocol monitoring systems that increase commissioning complexity and commissioning timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DC Distribution Network Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Supply Units, Transformers, Circuit Breakers, Switchgear Technology: Supercapacitors, Flywheel Storage, Solid-State Batteries, Inverters End User: Data Centers, Telecommunications, Renewable Energy, Industrial Facilities Application: Power Distribution, Energy Storage, Backup Power, Grid Integration |
| Companies Covered | Eaton Corporation, Mitsubishi Electric Corporation, ABB Ltd, Huawei Digital Power Technologies Co., Ltd., Delta Electronics, Inc., Schneider Electric, Vertiv Group Corp, Cummins Inc., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DC Distribution Network Market Strategic Shifts
Solid-state power electronics are displacing electromechanical switching across voltage classes, while regulatory pressure on fluorinated greenhouse gases accelerates insulation material substitution. These forces are fragmenting supplier capabilities and creating new certification gatekeepers.
Silicon carbide MOSFETs are replacing insulated-gate bipolar transistors in DC circuit breaker applications above 1,000 V, delivering faster fault interruption and reduced arc energy. Data center operators in Singapore and Ireland are specifying SiC-based protection for new hyperscale builds. The technology is bifurcating procurement specifications between premium solid-state platforms and cost-optimized hybrid electromechanical alternatives.
REACH chemical restrictions and the EU F-Gas Regulation are forcing reformulation of switchgear dielectric media and arc-quenching gases across European industrial zones. Manufacturers are accelerating dry air and vacuum insulation qualification programs to maintain market access. German industrial clusters in the Ruhr and Bavaria are piloting fluorine-free DC switchgear retrofits ahead of 2030 phase-down deadlines.
Power purchase agreement structures are migrating from capacity-based to energy-as-a-service models for microgrid deployments, transferring operational risk to equipment financiers and specialized operators. C&I buyers in California and Texas are favoring contracts with guaranteed uptime SLAs over capital ownership. This reconfiguration concentrates vendor relationships among integrated platform providers with balance-sheet capacity to underwrite performance guarantees.
DC Distribution Network Market Segmentation
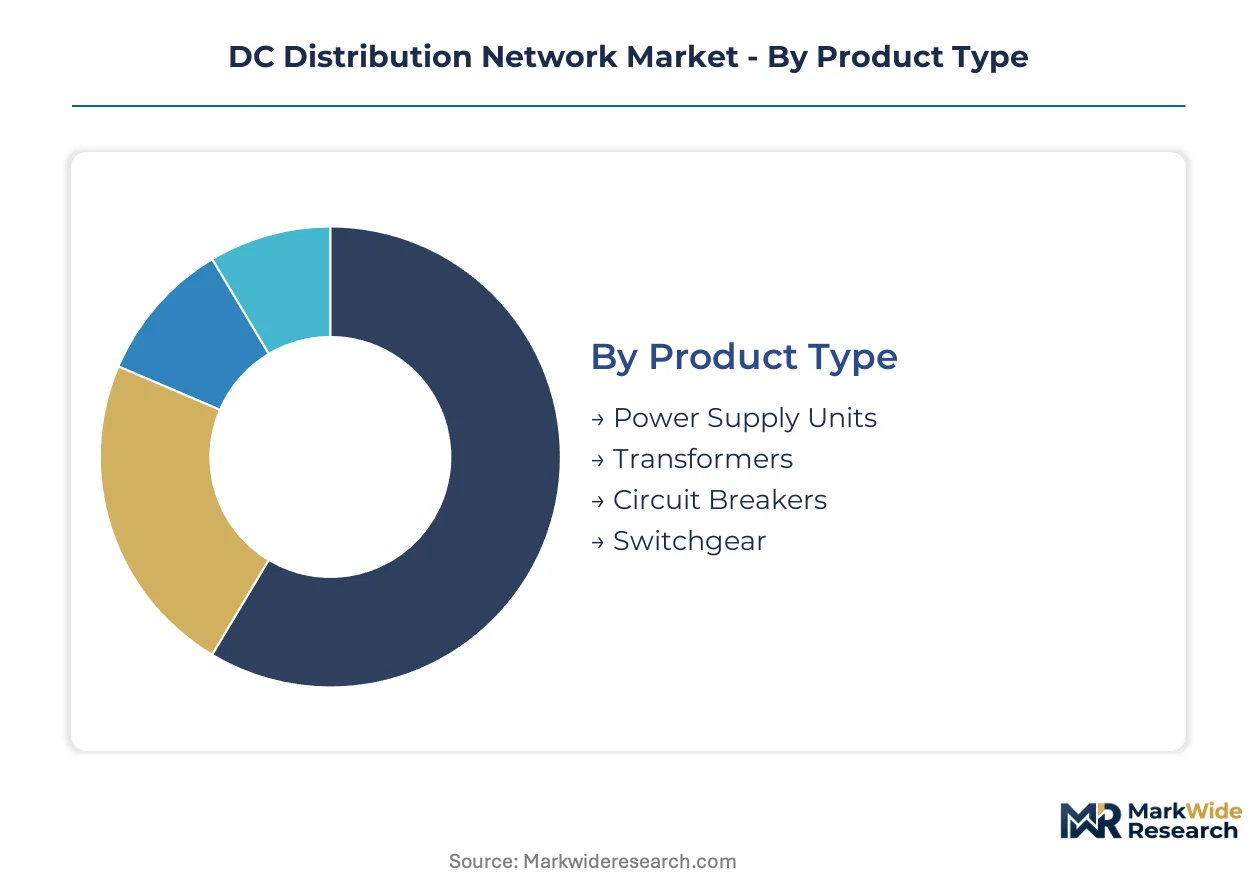
Segmentation in DC distribution networks reveals distinct procurement patterns across voltage classes and duty cycles. Equipment buyers in hyperscale computing and heavy industry prioritize fault-current tolerance and conversion efficiency over upfront capital cost, reshaping supplier engagement models.
Product Type:
Channel mix varies sharply by voltage rating and retrofit complexity. Circuit breakers and switchgear flow through electrical distributors with field engineering support, while power supply units and transformers concentrate in direct OEM relationships.
- Circuit Breakers:Solid-state silicon carbide platforms above 1,000 V deliver microsecond fault interruption for data center bus architectures. Northern Virginia and Frankfurt hyperscale operators specify these for new campus construction, driven by thermal load reduction targets and warranty cost compression.
- Switchgear:1,500 V DC platforms integrate photovoltaic string-level protection with utility-scale microgrid control. German industrial clusters in the Ruhr retrofit legacy AC substations with fluorine-free alternatives ahead of EU F-Gas Regulation deadlines.
- Power Supply Units:Rectifier modules rated 380-750 V serve telecommunications central offices with lithium-titanate battery coupling.
- Transformers:DC-DC conversion stages for renewable coupling face copper price volatility in fixed-price industrial contracts.
By volume, circuit breakers lead. By growth pace, switchgear is ahead.
Technology:
Cost tiers separate utility-grade solid-state platforms from electromechanical alternatives in backup power applications. Premium silicon carbide configurations command manufacturing scale advantages in automotive-qualified fabs.
- Solid-State Batteries:Lithium-titanate chemistry enables four-hour discharge configurations that displace lead-acid strings in telecommunications backup. Singapore data centers specify these for fire-safety compliance alongside rapid cycling durability.
- Inverters:Wide-bandgap semiconductor architectures convert native DC from solar arrays without AC staging losses. Texas and California C&I microgrid developers favor these under FERC Order 2222 aggregation structures.
- Supercapacitors:Sub-second response times bridge to battery storage in grid frequency regulation services.
- Flywheel Storage:Mechanical kinetic systems serve short-duration ride-through for semiconductor fabrication voltage sag protection.
Solid-state batteries capture the steepest expansion trajectory as discharge durations extend. Inverters maintain the largest installed base.
End User:
Application-specific duty cycles dictate voltage standard selection and protection coordination complexity. Continuous operation environments prioritize efficiency gains over intermittent-use cost optimization.
- Data Centers:Hyperscale operators in Ireland and Singapore eliminate AC-DC conversion entirely, rewiring 750 V DC bus architectures to reduce cooling loads and capture efficiency margins. Procurement cycles compress as voltage standards consolidate around native DC consumption.
- Industrial Facilities:Textile and chemical clusters in Gujarat and Tamil Nadu under India's PLI scheme deploy captive renewable microgrids with 1,000 V DC distribution for process motor drives.
- Telecommunications:Central office backup power specifications favor lithium-titanate configurations with 15-year cycle life over lead-acid replacement schedules.
- Renewable Energy:Utility-scale solar and offshore wind direct-couple to DC collection networks, bypassing inverter staging at the array level.
Data centers lead absolute spending. Industrial facilities are expanding most quickly in corridor electrification programs.
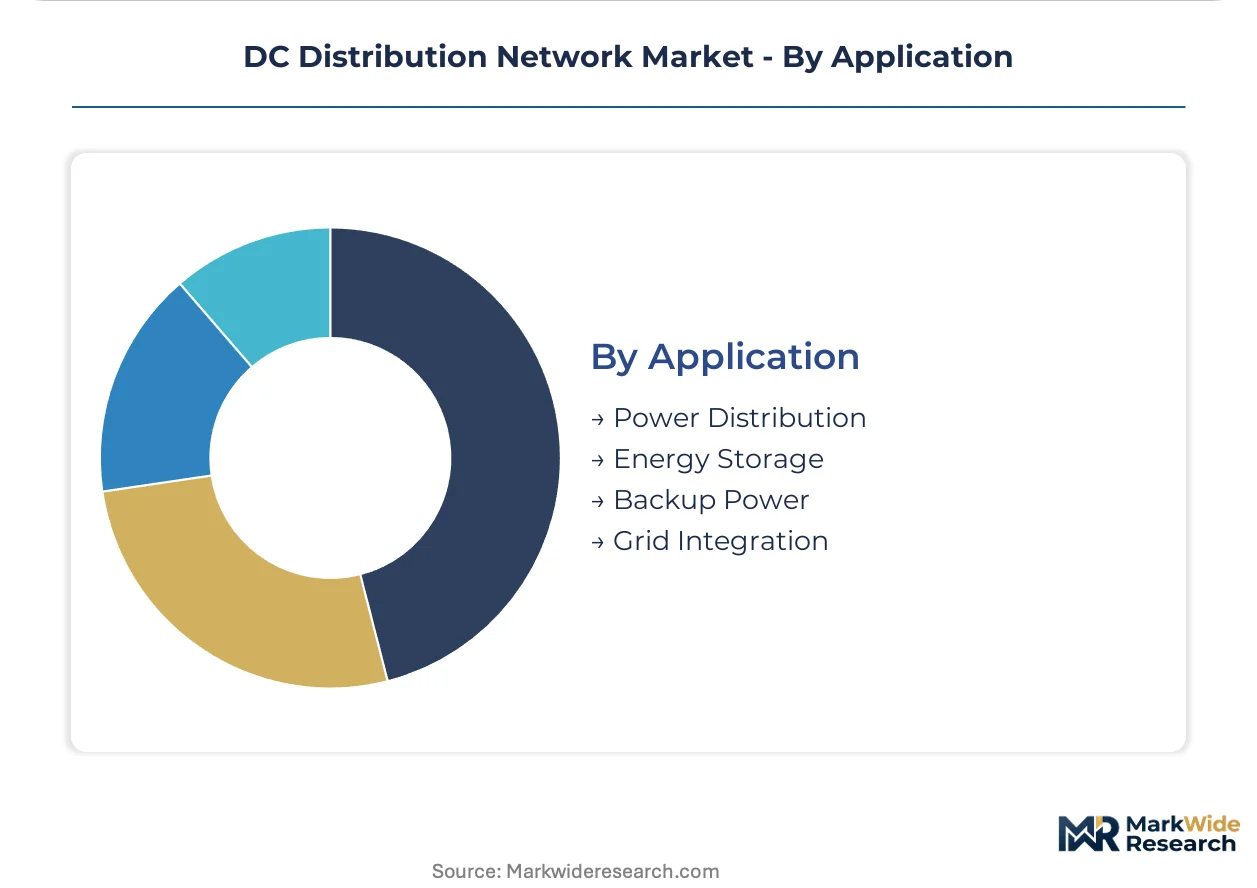
Application:
Maturity gradients separate established power distribution equipment from emerging grid integration protocols requiring certification alignment with evolving interconnection standards.
- Energy Storage:Four-hour lithium-titanate configurations aggregate behind FERC Order 2222 structures for wholesale market participation. California and Texas lead deployment with performance-guaranteed energy-as-a-service contracts.
- Grid Integration:Bidirectional vehicle-to-grid protocols for heavy-duty electric trucks demand 1,000 V DC networks at logistics depots. Port terminals in Rotterdam and Hamburg pilot these for shore power and charging convergence.
- Power Distribution:Busway and cable systems face copper price volatility in fixed-price retrofit contracts.
- Backup Power:Telecommunications central offices specify solid-state battery configurations with faster protection coordination than legacy electromechanical schemes.
Power distribution holds the largest installed capacity. Grid integration is gaining share fastest as vehicle electrification protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. Data center operators in Ireland and Singapore prioritize efficiency gains over capital cost, while Indian textile clusters under PLI schemes face hard budget ceilings for captive renewable integration.
United States
FERC Order 2222 aggregation structures and hyperscale computing load concentration in Northern Virginia drive wholesale market participation for DC microgrid developers. The regulation enables distributed energy resources to stack revenue streams beyond energy arbitrage. Northern Virginia cloud campuses specify 750 V DC bus architectures for new construction.
Germany
Ruhr Valley industrial retrofits and Bavarian manufacturing automation anchor European demand for fluorine-free DC switchgear. The EU F-Gas Regulation phase-down schedule accelerates substitution timelines for medium-voltage circuit breakers. Dortmund and Essen textile clusters pilot 750 V DC bus systems ahead of 2030 deadlines.
India
PLI scheme incentives for domestic manufacturing and captive renewable mandates in Gujarat textile corridors attract DC microgrid developers. The Central Electricity Authority issues technical standards for industrial microgrid interconnection. Surat and Ahmedabad chemical clusters deploy 1,000 V DC distribution for process motor drives.
China
Dual carbon goals and data center efficiency mandates in the Yangtze River Delta compress procurement cycles for native DC architectures. MIIT efficiency standards eliminate AC-DC conversion stages in new hyperscale builds. Shanghai and Hangzhou cloud campuses rewire around 750 V DC consumption.
Singapore
Tropical climate constraints and fire-safety regulations for battery storage create premium demand for solid-state protection coordination. The Energy Market Authority licenses aggregated distributed resources for grid services. Tuas data center precincts specify silicon carbide-based circuit breakers for thermal load reduction.
DC Distribution Network Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Premium solid-state platforms command manufacturing scale advantages in automotive-qualified fabs, while electromechanical alternatives compete on retrofit compatibility and field service density. Three archetypes dominate: integrated electrical conglomerates with circuit protection heritage, power electronics specialists with wide-bandgap semiconductor capabilities, and energy infrastructure operators with microgrid financing capacity. Competitive moves concentrate on M&A for protection coordination expertise and strategic partnerships for energy-as-a-service contract underwriting.
Within the integrated conglomerate tier, Eaton Corporation and ABB Ltd occupy positions anchored by circuit protection portfolios and utility-scale deployment experience. Siemens AG exemplifies the manufacturing-scale archetype through dedicated production lines for data center busway systems. Huawei Digital Power Technologies Co., Ltd. represents the power electronics specialist vector with digital power integration capabilities.
| Leading Market Players |
|---|
| Eaton Corporation |
| Mitsubishi Electric Corporation |
| ABB Ltd |
| Huawei Digital Power Technologies Co., Ltd. |
| Delta Electronics, Inc. |
| Schneider Electric |
| Vertiv Group Corp |
| Cummins Inc. |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
Twenty-six-week lead times for silicon carbide MOSFETs from automotive-qualified fabs concentrate pricing power among integrated semiconductor suppliers, forcing DC circuit breaker manufacturers to absorb cost volatility or surrender margin to secure allocation. This inventory scarcity amplifies the premium commanded by solid-state protection platforms while compressing electromechanical alternatives into commodity procurement cycles.
Pricing Analysis
After-market service contracts and extended warranty tiers drive lifetime value for DC switchgear suppliers, with maintenance bundling separating premium silicon carbide platforms from standard electromechanical alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—UL 489B listings for data center applications command substantial premiums over industrial retrofit specifications. Pricing pressure stems from copper price volatility in fixed-price busway contracts, squeezing margins for EPC contractors serving Indian textile clusters under PLI scheme budgets. Industrial facility buyers exhibit highest price sensitivity due to captive renewable mandates with hard capital ceilings, while hyperscale operators in Singapore and Ireland prioritize efficiency gains over upfront cost.
Supply Chain Analysis
China and Germany anchor DC switchgear fabrication, with China concentrating mass production of 750 V busway systems and Germany specializing in fluorine-free medium-voltage platforms for EU F-Gas Regulation compliance. Wide-bandgap semiconductor substrates draw from Taiwan and South Korea wafer fabrication, while copper conductors and rare-earth magnetic materials feed from Chilean mining and Chinese processing operations. Single-source vulnerability in silicon carbide epitaxy equipment creates bottleneck risk for solid-state circuit breaker scaling. Distribution runs through electrical distributors with field engineering capabilities for retrofit installations, bypassing direct OEM relationships except in hyperscale data center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DC distribution networks represent a high-growth infrastructure disruption as FERC Order 2222 and EU Green Deal regulations simultaneously unlock wholesale market participation and mandate fluorine-free equipment substitution, compressing technology transition timelines.
For Market Incumbents: Shield core circuit protection margins by accelerating backward integration into silicon carbide semiconductor supply, securing allocation from automotive-qualified fabs before capacity constraints harden. Invest in IEC 61215-1 certification pre-positioning to capture solar-direct coupling demand as string-level voltage tolerance standards mature, defending against power electronics specialists with native wide-bandgap capabilities. For New Entrants and Emerging Players: Protection coordination engineering services present the most penetrable white-space, as incumbent manufacturers under-serve commissioning complexity for hybrid DC-AC networks. Target Indian industrial corridor electrification under PLI scheme incentives, where domestic manufacturing requirements disadvantage foreign equipment suppliers lacking local assembly partnerships. Lead with energy-as-a-service contract underwriting to bypass capital ownership barriers in California and Texas C&I microgrid markets. For Investors and Strategic Acquirers: Long-term, this sits as a utility infrastructure modernization play because grid-edge decentralization and renewable integration mandates create durable equipment replacement cycles. Acquisition targets should concentrate on power electronics engineering consultancies with solid-state circuit breaker commissioning expertise, as protection coordination skill scarcity concentrates value capture. Monitor FERC Order 2222 implementation velocity across ISO/RTO territories as the primary inflection signal for storage-integrated network deployment scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures MOSFET allocation from automotive-qualified fabs for data center circuit breaker production. |
| Fluorine-Free Switchgear Qualification | Maintains EU market access ahead of F-Gas Regulation phase-down deadlines in German industrial zones. |
| Protection Coordination Engineering Acquisition | Addresses skill scarcity in solid-state circuit breaker deployment for hybrid network commissioning. |
| Energy-as-a-Service Platform Launch | Transfers operational risk to equipment financiers under FERC Order 2222 aggregation structures. |
| Indian PLI Scheme Manufacturing Footprint | Captures captive renewable microgrid demand in Gujarat and Tamil Nadu textile corridors. |
Study Parameters
Initial hypotheses were tested against primary input from data center infrastructure directors, utility interconnection planners, EPC contractors specializing in industrial microgrids, and power electronics procurement leads at semiconductor fabs, then refined through secondary validation against FERC Order 2222 implementation dockets, EU F-Gas Regulation compliance filings, IEC 61215-1 testing protocols, and copper price volatility indices from the London Metal Exchange. Bottom-up equipment shipment analysis and top-down infrastructure investment forecasting were triangulated to reconcile segmentation outputs.
Variance decomposition across voltage class, technology maturity, and end-user duty cycle shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, solid-state versus electromechanical technology, application-specific discharge duration, and regional regulatory framework cluster. CAGRs were derived from equipment procurement cycle analysis and renewable integration mandate velocity, with hyperscale computing load concentration and lithium-titanate battery chemistry substitution serving as key forecast inputs.
Underlying assumptions cover FERC Order 2222 aggregation participation rates, EU F-Gas substitution timelines, and silicon carbide manufacturing scale-up trajectories, with deviation risk concentrated in copper price volatility for fixed-price contracts and IEC certification bottlenecks for solar-direct coupling equipment. Recalibration cycles align with material shifts in interconnection standard revisions and carbon border adjustment mechanism implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Wireless Power Transmission Market
Transmission and Distribution
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
Electric Power Transmission and Distribution Equipment Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Transmission Line Market