
 Power Transmission Cables Market | 2026-2036
Power Transmission Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Power Transmission Cables Market Outlook
A widening capital-intensity divergence between integrated manufacturers and assembly-focused competitors is rotating competitive advantage toward firms with captive metal processing and compound formulation capabilities. Prysmian Group leverages vertical integration across submarine cable value chains from fiber drawing to armoring. Nexans anchors its position through specialized high-temperature superconducting R&D programs in European markets. Southwire Company sustains manufacturing scale advantages across copper rod and continuous casting operations in North America.
Power transmission cables are insulated conductor assemblies engineered to transport electrical energy across distances exceeding one kilometer, typically employing cross-linked polyethylene or ethylene propylene rubber insulation rated for thermal endurance above 90 degrees Celsius. Their primary purpose is to connect generation assets, substations, and load centers with minimal resistive losses. High voltage and extra high voltage categories command the dominant share of project value due to polymer insulation thickness requirements and specialized jointing systems. Aluminum material configurations are gaining structural share in long-distance overhead corridors where weight reduction offsets conductivity penalties against copper. Submarine installation types represent the fastest-expanding margin pool, driven by offshore wind farm export cables requiring lead alloy sheathing and polyethylene protective layers.
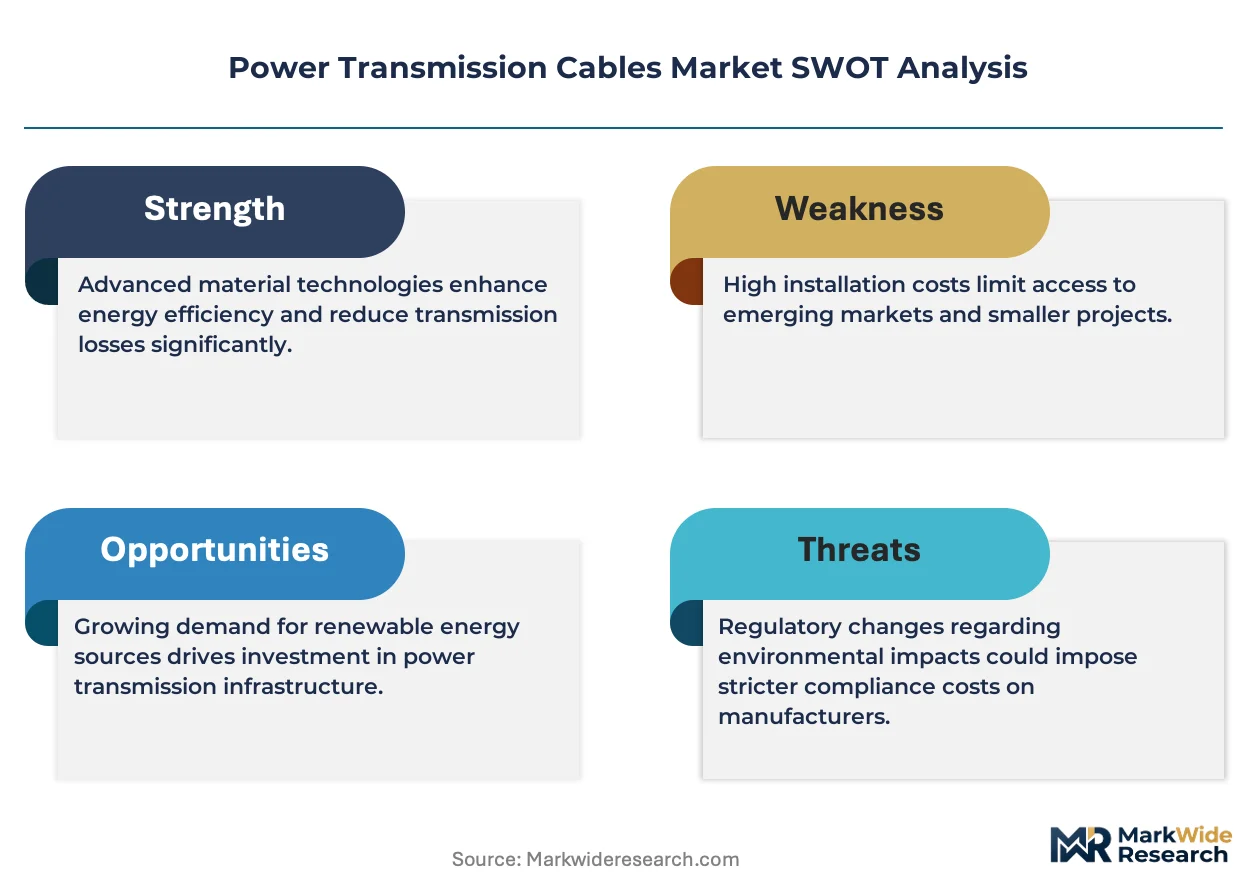
The US Federal Energy Regulatory Commission and the EPA coordinate grid reliability standards with environmental permitting for cross-state transmission corridors, while China's National Energy Administration enforces GB standards for 1100 kV ultra-high voltage compatibility. The EU F-Gas Regulation restricts sulfur hexafluoride use in gas-insulated transmission lines, redirecting investment toward solid-dielectric alternatives. Stakeholders must monitor regulatory divergence between jurisdictions on fire performance standards and recyclability mandates to avoid stranded inventory in multi-region project portfolios.
Market Dynamics
Grid interconnection mandates across emerging economies are compressing project timelines and forcing procurement centralization toward state transmission utilities with direct access to sovereign financing facilities.
Growth Catalysts
- India's 765 kV tender acceleration:State transmission utilities are releasing record procurement volumes for extra high voltage corridors connecting renewable generation zones to load centers.
- China's dual carbon policy framework:Grid modernization mandates under the National Energy Administration are redirecting utility capex toward ultra-high voltage infrastructure compatible with 1100 kV standards.
- Offshore wind export cable demand:Lead alloy sheathing and polyethylene protective layers for submarine installations are commanding premium margins as North Sea and East Asian wind farms scale.
Market Restraints
- Copper and aluminum price volatility:Metal rod feedstock costs oscillate with LME trading patterns, compressing margin visibility for continuous casting operations.
- Specialized jointing system scarcity:Qualified installation crews for cross-linked polyethylene terminations concentrate in Germany, Japan, and South Korea.
- Sulfur hexafluoride restrictions:The EU F-Gas Regulation limits gas-insulated line deployment, forcing project redesign toward solid-dielectric alternatives with longer lead times.
Strategic Opportunities
- Brazil's underpenetrated 500 kV network:Transmission expansion plans for Amazon basin hydroelectric integration lack domestic high-capacity conductor manufacturing capacity.
- High-temperature superconducting R&D programs:European utility consortia are funding liquid nitrogen-cooled cable pilots for urban density corridors.
- Direct utility channel bypass:Engineering-procurement-construction contractors are consolidating cable specification authority away from fragmented distributor networks.
Industry Challenges
- Cross-linked polyethylene compounding expertise gap:Thermal endurance formulation chemists with 90-degree Celsius rating experience are concentrated among a handful of compound suppliers.
- Multi-jurisdiction fire performance certification:IEC, GB, and UL testing protocols for flame propagation and smoke density lack harmonization, duplicating qualification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Transmission Cables Market |
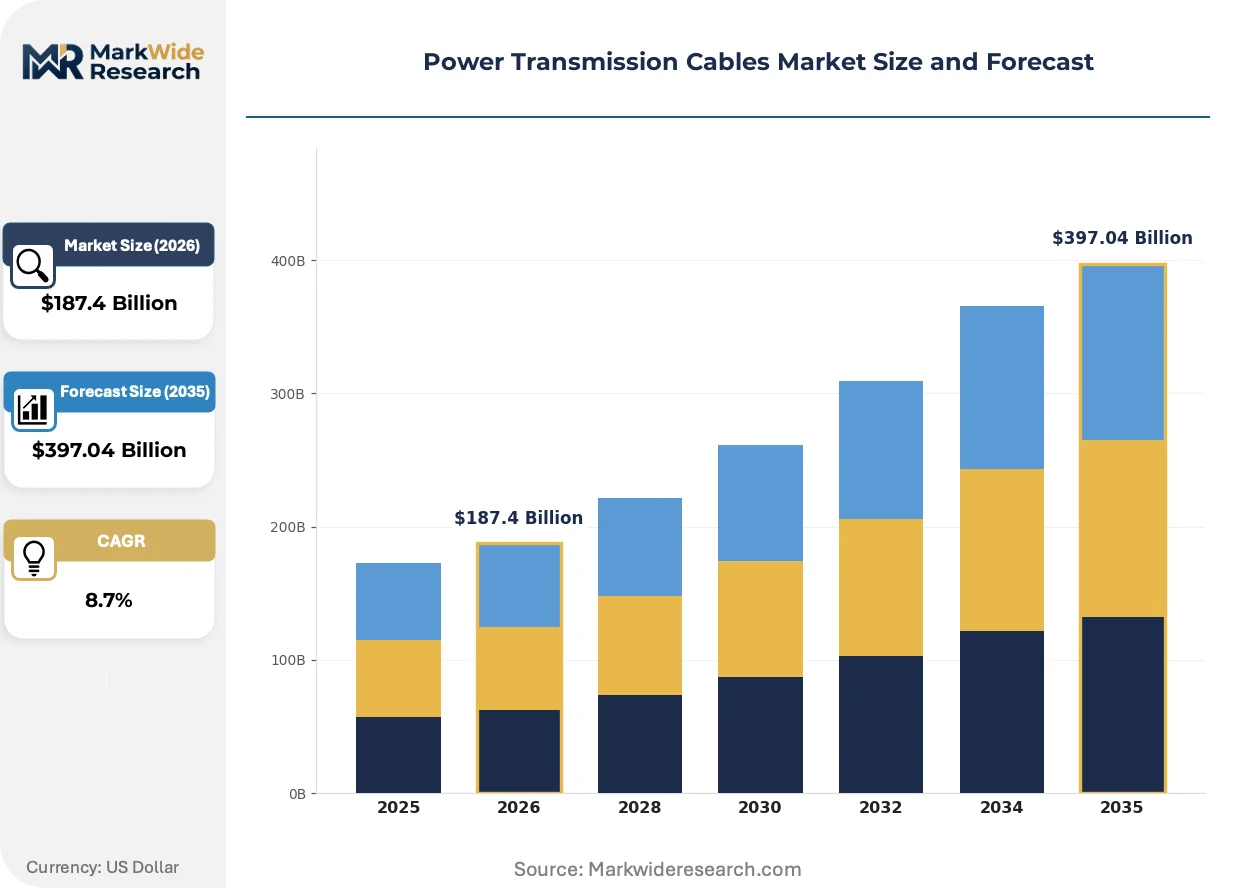
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Voltage, Medium Voltage, Low Voltage, Extra High Voltage Material: Copper, Aluminum, Fiber Optic, Composite Installation Type: Aerial, Underground, Submarine, Indoor End User: Utilities, Industrial, Commercial, Renewable Energy |
| Companies Covered | Prysmian Group, Nexans, Southwire Company, Sumitomo Electric Industries, LS Cable & System, NKT A/S, Furukawa Electric, General Cable, Riyadh Cables Group Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Transmission Cables Market Strategic Shifts
Material science advances and installation methodology shifts are redistributing value capture across the conductor-insulation-jointing value chain, favoring firms with integrated polymer formulation capabilities.
Aluminum conductor composite core technology is fragmenting traditional steel-reinforced overhead line markets. Regional transmission organizations in Texas and the US Southwest are specifying ACCC conductors for 345 kV reconductoring projects to double thermal capacity without tower replacement. This thermal upgrade pathway is fragmenting capital allocation between new-build corridors and existing right-of-way optimization.
The EU F-Gas Regulation is compressing deployment timelines for sulfur hexafluoride-insulated transmission infrastructure. Project developers must now specify solid-dielectric or vacuum-insulated alternatives for urban substation connections, extending engineering cycles by eight to fourteen months. German transmission system operators are absorbing these delays through accelerated front-end loading of route permitting.
Buyer consolidation toward national transmission utilities is compressing distributor margins and fragmenting regional cable stockist networks. India's Power Grid Corporation and state transmission utilities now specify directly with Prysmian, Nexans, and domestic manufacturers, bypassing traditional electrical wholesaler channels. This disintermediation concentrates in emerging economies where sovereign-backed project finance reduces working capital requirements for direct procurement.
Power Transmission Cables Market Segmentation
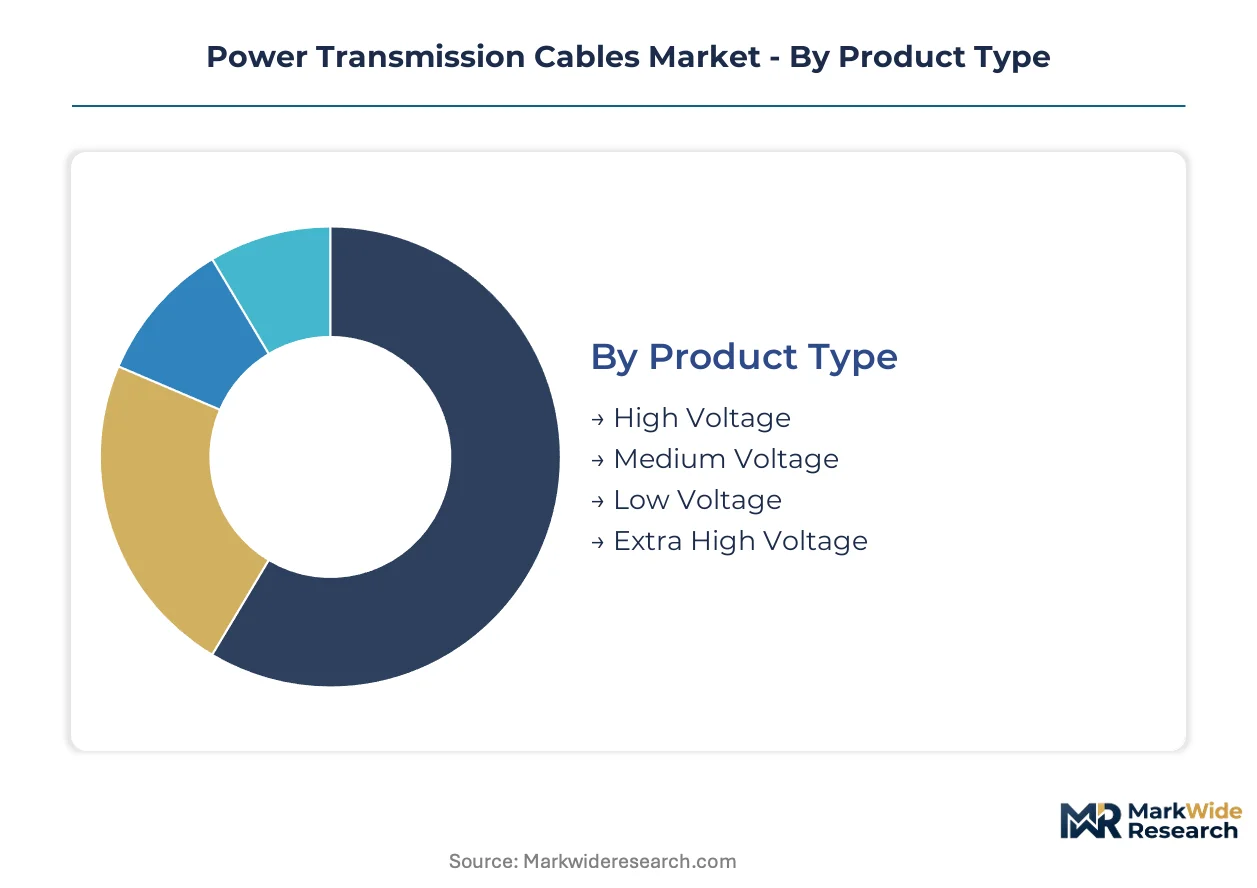
Segmentation in power transmission cables determines procurement channels, margin structures, and technical qualification requirements. Utility direct-buy patterns favor extra high voltage and submarine categories, while distributor networks handle lower voltage specifications for commercial and industrial accounts.
Product Type:
Channel concentration varies sharply by voltage class, with state transmission utilities dominating procurement above 220 kV and electrical wholesalers retaining influence below 66 kV.
- Extra High Voltage:765 kV and 1100 kV systems employ cross-linked polyethylene insulation with specialized jointing systems. India's Power Grid Corporation and China's State Grid tender these directly to manufacturers with GB and IEC certification, bypassing traditional distribution channels.
- High Voltage:220-400 kV corridors connect renewable generation zones to load centers. Brazil's Amazon basin hydroelectric integration and India's interstate green energy highways are driving procurement centralization toward sovereign-backed utilities with direct manufacturer relationships.
- Medium Voltage:Distribution utilities and industrial complexes specify these through regional electrical distributors. Urban underground networks in European cities favor solid-dielectric alternatives as EU F-Gas Regulation restricts gas-insulated line deployment.
- Low Voltage:Commercial building automation and campus distribution systems flow through electrical wholesaler networks. Margin compression here reflects fragmented buyer bases and commodity insulation specifications.
By volume, Medium Voltage leads distribution utility procurement cycles. By growth pace, Extra High Voltage is climbing the fastest as emerging economies expand inter-regional transmission corridors.
Material:
Cost tier positioning separates premium conductor systems from commodity alternatives, with metal processing capabilities determining competitive advantage.
- Aluminum:Long-distance overhead corridors in Texas and the US Southwest specify aluminum conductor composite core technology for 345 kV reconductoring without tower replacement. Weight reduction offsets conductivity penalties against copper across spans exceeding 500 kilometers.
- Copper:Underground urban networks and submarine installations demand copper's superior conductivity for thermal endurance above 90 degrees Celsius. Continuous casting operations in North America and Germany supply rod feedstock to integrated manufacturers.
- Fiber Optic:Optical ground wire and all-dielectric self-supporting cables integrate communication channels into transmission infrastructure. Smart grid monitoring requirements in European and East Asian markets favor these composite specifications.
- Composite:Carbon fiber and glass fiber reinforced cores enable thermal capacity doubling in existing rights-of-way. Regional transmission organizations specify these for reconductoring projects where new corridor permitting faces multi-year delays.
By installed length, Aluminum dominates overhead transmission. By project value concentration, Copper captures premium margin pools in submarine and dense urban applications.
Installation Type:
Application environment dictates engineering complexity, with submarine and underground installations commanding specialized armoring and protective layer specifications.
- Submarine:Offshore wind farm export cables require lead alloy sheathing and polyethylene protective layers for mechanical protection against seabed abrasion. North Sea and East Asian wind farm scaling is expanding this fastest-growing margin pool.
- Aerial:Steel-reinforced and composite-core overhead lines span rural and inter-regional corridors. Brazil's underpenetrated 500 kV network and India's renewable energy highways rely on these for cost-efficient long-distance transport.
- Underground:Urban density corridors and environmentally sensitive areas mandate buried installation with cross-linked polyethylene insulation. German transmission system operators are accelerating route permitting to absorb extended engineering cycles for solid-dielectric alternatives.
- Indoor:Gas-insulated lines and solid-dielectric buswork serve substation interconnections and industrial facility distribution. EU F-Gas Regulation is compressing sulfur hexafluoride deployment timelines and redirecting specification toward vacuum-insulated alternatives.
By capital deployment, Aerial infrastructure retains the largest share. By margin expansion, Submarine installations are gaining share fastest as offshore wind scales beyond 50 kilometers from shore.
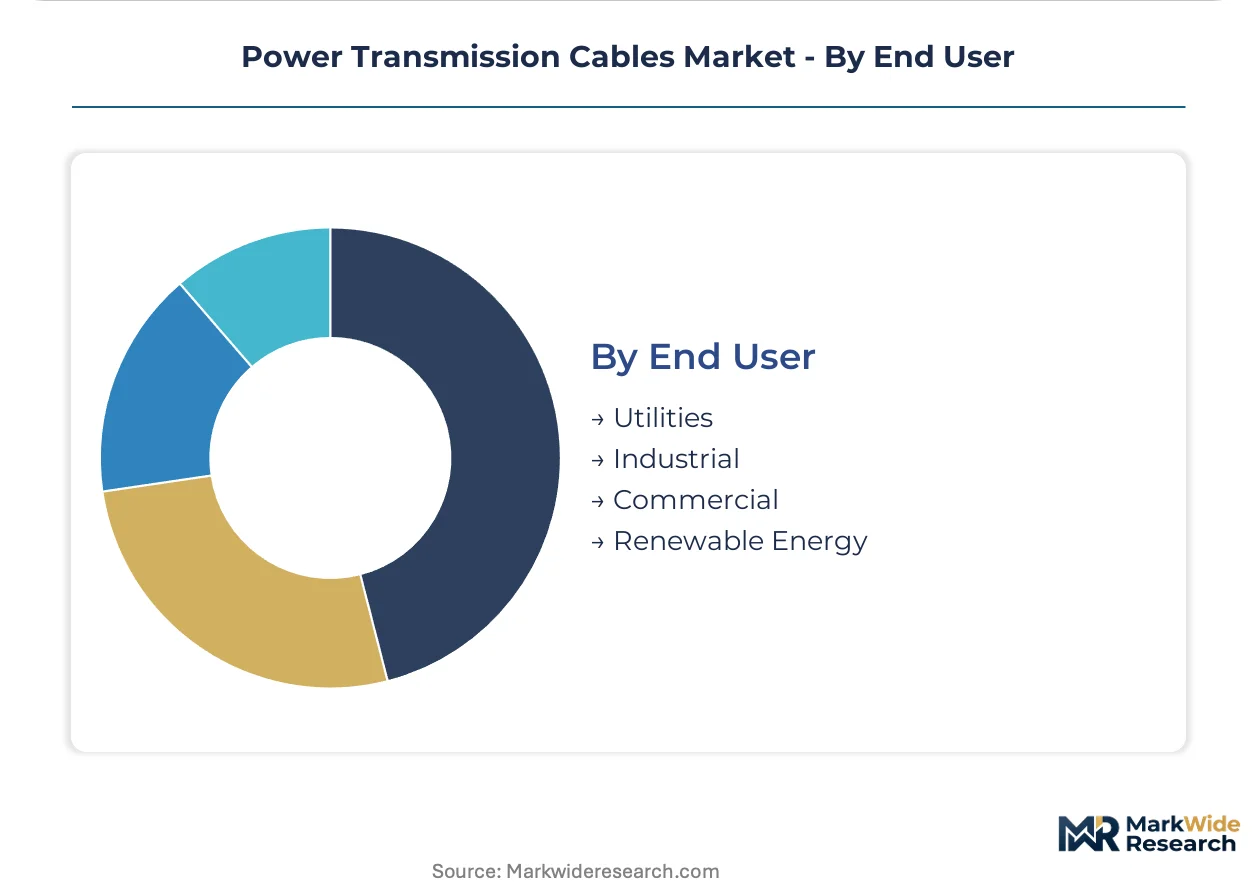
End User:
Customer type determines financing structure, with sovereign-backed utilities offering payment security that attracts direct manufacturer engagement.
- Utilities:National and state transmission utilities with access to sovereign financing facilities centralize procurement for high-capacity corridors. India's tender acceleration for 765 kV lines and China's grid modernization mandates under the National Energy Administration exemplify this channel.
- Renewable Energy:Wind and solar developers require collection systems and export cables for generation integration. Offshore wind farm developers in the North Sea and East Asia specify submarine cables directly with integrated manufacturers.
- Industrial:Mining, petrochemical, and heavy manufacturing facilities procure medium voltage distribution through engineering-procurement-construction contractors. These intermediaries are consolidating cable specification authority away from fragmented distributor networks.
- Commercial:Data centers, hospitals, and large commercial complexes specify low voltage and medium voltage distribution through regional electrical wholesalers. Working capital constraints here favor distributor stocking programs over direct manufacturer relationships.
By project value, Utilities command the dominant share of high-voltage procurement. By specification evolution, Renewable Energy developers are driving the steepest demand shift as offshore wind export cable requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in high-capacity conductor systems tilt toward net-importing markets across emerging economies, while integrated manufacturers in Germany, Japan, and South Korea supply specialized jointing systems and polymer compounds to project developers worldwide.
China
State Grid Corporation tenders ultra-high voltage corridors at 1100 kV under National Energy Administration mandates tied to dual carbon goals. GB standards enforcement for 1100 kV compatibility redirects utility capex toward domestic extra high voltage infrastructure. Jiangsu and Shandong provinces host concentrated manufacturing clusters for cross-linked polyethylene insulation systems serving both domestic grid expansion and Belt and Road export projects.
India
Power Grid Corporation and state transmission utilities release record procurement volumes for 765 kV and 400 kV renewable energy highways connecting solar zones to load centers. Central Electricity Authority technical standards govern insulation ratings and thermal endurance specifications for interstate corridors. Gujarat and Rajasthan concentrate tender activity for desert solar park integration requiring aluminum conductor composite core technology for spans exceeding 500 kilometers.
Germany
Transmission system operators absorb extended engineering cycles for solid-dielectric alternatives as EU F-Gas Regulation compresses sulfur hexafluoride deployment timelines for urban substation connections. Federal Network Agency permitting procedures coordinate with environmental regulators for cross-state corridor approvals. North Rhine-Westphalia and Bavaria host specialized jointing system providers and high-temperature superconducting R&D consortia serving North Sea offshore wind export cable specifications.
United States
Regional transmission organizations in Texas and the Southwest specify aluminum conductor composite core technology for 345 kV reconductoring projects without tower replacement. Federal Energy Regulatory Commission reliability standards coordinate with EPA environmental permitting for interstate transmission corridors. California and the Pacific Northwest concentrate procurement for wildfire-hardened overhead lines requiring upgraded thermal capacity ratings.
Brazil
Amazon basin hydroelectric integration drives transmission expansion plans for 500 kV corridors lacking domestic high-capacity conductor manufacturing capacity. National Electric Energy Agency concession frameworks govern interstate transmission asset procurement and tariff regulation. São Paulo and Minas Gerais industrial clusters rely on imported extra high voltage systems for grid interconnection with remote generation assets.
Power Transmission Cables Market Competitive Environment
Concentration sits with integrated manufacturers possessing captive metal processing and compound formulation capabilities, while assembly-focused competitors face margin compression from raw material price volatility and buyer consolidation toward sovereign-backed utilities. Strategic archetypes span vertically integrated cable-lifecycle providers, specialized submarine installation specialists, and regional scale players anchored in continuous casting operations. Dominant competitive moves include backward integration into copper rod and aluminum smelting operations, plus strategic partnerships with offshore wind developers for long-term export cable supply agreements.
Within the integrated-manufacturer tier, Prysmian Group, Nexans, and Southwire Company exemplify divergent capability configurations. Prysmian anchors European submarine cable value chains through in-house production of fiber drawing to armoring stages. Nexans occupies a position within high-temperature superconducting R&D programs funded by utility consortia. Southwire represents North American scale advantages across continuous casting and copper rod processing operations. These three entities illustrate how metal processing depth and polymer formulation control separate premium-tier positioning from commodity assembly margins.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Southwire Company |
| Sumitomo Electric Industries |
| LS Cable & System |
| NKT A/S |
| Furukawa Electric |
| General Cable |
| Riyadh Cables Group Company |
| Others |
Value Chain & Pricing Dynamics
Continuous casting capacity utilization above 85% in North American and German integrated manufacturers creates asymmetric scale economies that compress price floors for aluminum rod feedstock while elevating margin capture for cross-linked polyethylene compound formulation. State transmission utilities with sovereign financing access exploit this concentration through direct procurement centralization, forcing assembly-focused competitors toward distributor-channel commoditization.
Pricing Analysis
Industrial OEM buyers anchor project-based contract pricing for extra high voltage corridors, with three-tier pricing structure across premium, standard, and economy levels differentiated by IEC certification tier and thermal endurance rating. Price differentiation hinges on GB standard compliance for 1100 kV ultra-high voltage compatibility versus UL-listed alternatives for North American reconductoring. Pricing pressure stems from LME copper and aluminum volatility compressing margin visibility for continuous casting operations. Commercial and industrial segments exhibit highest price sensitivity due to working capital constraints favoring distributor stocking programs.
Supply Chain Analysis
China and Germany anchor cross-linked polyethylene insulation compound production, with Jiangsu and North Rhine-Westphalia hosting concentrated manufacturing clusters for thermal endurance formulations rated above 90 degrees Celsius. Raw material dependencies draw from Chilean copper concentrate, Australian alumina, and Saudi petrochemical feedstock for ethylene propylene rubber. Supply chain risk centers on single-source vulnerability for qualified jointing system installation crews concentrated in Germany, Japan, and South Korea. Distribution runs through engineering-procurement-construction contractors consolidating specification authority away from fragmented electrical wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid interconnection platform economics are reaching an inflection as interoperability mandates across emerging economies force standardization on IEC and GB protocols, consolidating procurement authority toward sovereign-backed utilities with direct manufacturer channel access.
For Market Incumbents: Secure backward integration into copper rod continuous casting and aluminum smelting operations to defend margin position against LME price volatility. Prioritize captive cross-linked polyethylene compounding capabilities to differentiate from assembly-focused competitors facing thermal endurance formulation expertise gaps. For New Entrants and Emerging Players: Differentiate on high-temperature superconducting cable pilots for urban density corridors in European utility consortia funding liquid nitrogen-cooled infrastructure. Target Brazil's underpenetrated 500 kV Amazon basin hydroelectric integration lacking domestic high-capacity conductor manufacturing capacity. Pursue direct utility channel partnerships bypassing traditional electrical wholesaler networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with captive metal processing and polymer formulation capabilities over assembly-focused competitors. Long-term viability across the projection horizon rests on firms controlling cross-linked polyethylene compounding expertise and qualified jointing system installation networks. Monitor tender acceleration patterns from India's Power Grid Corporation and China's State Grid as inflection indicators for capacity utilization and pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metal Processing | Captive copper rod and aluminum smelting operations insulate margin from LME volatility and secure feedstock for continuous casting. |
| High-Temperature Superconducting R&D Partnership | Liquid nitrogen-cooled cable pilots with European utility consortia capture premium positioning in urban density corridor upgrades. |
| Direct Utility Channel Development | Bypassing electrical wholesaler networks concentrates procurement relationships with India's Power Grid Corporation and state transmission utilities. |
| GB and IEC Certification Investment | Dual standard compliance unlocks tender participation for China's 1100 kV ultra-high voltage corridors and Belt and Road export projects. |
| Submarine Cable Armoring Capacity Expansion | Lead alloy sheathing and polyethylene protective layer production captures fastest-growing margin pool in North Sea and East Asian offshore wind. |
Study Parameters
Desk research of customs and trade flow databases, FERC interstate transmission corridor filings, and CEA technical standards documentation preceded structured interviews with utility planning officers at state transmission utilities, EPC contractor procurement leads, and grid operator interconnection specialists. Primary fieldwork with compound formulation chemists and continuous casting operations managers validated secondary data on thermal endurance rating capabilities and metal processing capacity utilization. Bottom-up tender volume aggregation from India's Power Grid Corporation and China's State Grid triangulated against top-down infrastructure capex forecasts from national energy administration mandates.
Variance decomposition across voltage class, material configuration, installation environment, and end-user financing structure informed the analytical framework throughout the forecast period. Segmentation dimensions modeled include extra high voltage versus medium voltage procurement channels, aluminum conductor composite core versus traditional steel-reinforced overhead specifications, and sovereign-backed utility direct-buy versus commercial distributor-channel patterns. CAGRs derived from installed base replacement cycles for 345 kV reconductoring projects and greenfield corridor additions for renewable energy highway integration.
Material uncertainties — copper and aluminum LME price volatility, EU F-Gas Regulation enforcement timelines, and qualified jointing system crew availability — sit outside the modeled envelope. Forecasts reflect assumptions on grid interconnection mandate continuity and sovereign financing facility access for emerging economy utilities. Recalibration cycles align with material shifts in tender release patterns from India's Central Electricity Authority and China's National Energy Administration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Energy Cable Market
Transmission and Distribution
Gas Insulated Substation Market
Transmission and Distribution
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Power Transmission Tower Market
Transmission and Distribution
Wireless Power Transmission Market
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Electrical Transmission Azimuth Thruster Market
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Power Transmission Lines and Towers Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
Pipeline Transportation Market