
 Canada High-Voltage Direct Current (HVDC) Transmission Systems Market | 2026-2036
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market Outlook
Aftermarket service revenue for converter stations and submarine cable terminations is rewriting margin economics for incumbent suppliers. Hitachi Energy Ltd leverages its installed base of line-commutated converter platforms across Quebec to capture recurring maintenance contracts. Siemens Energy AG anchors its Canadian position through voltage source converter technology leadership and localized engineering support. Nexans SA specializes in high-voltage DC cable manufacturing, competing on material science and installation expertise for subsea interconnection projects.
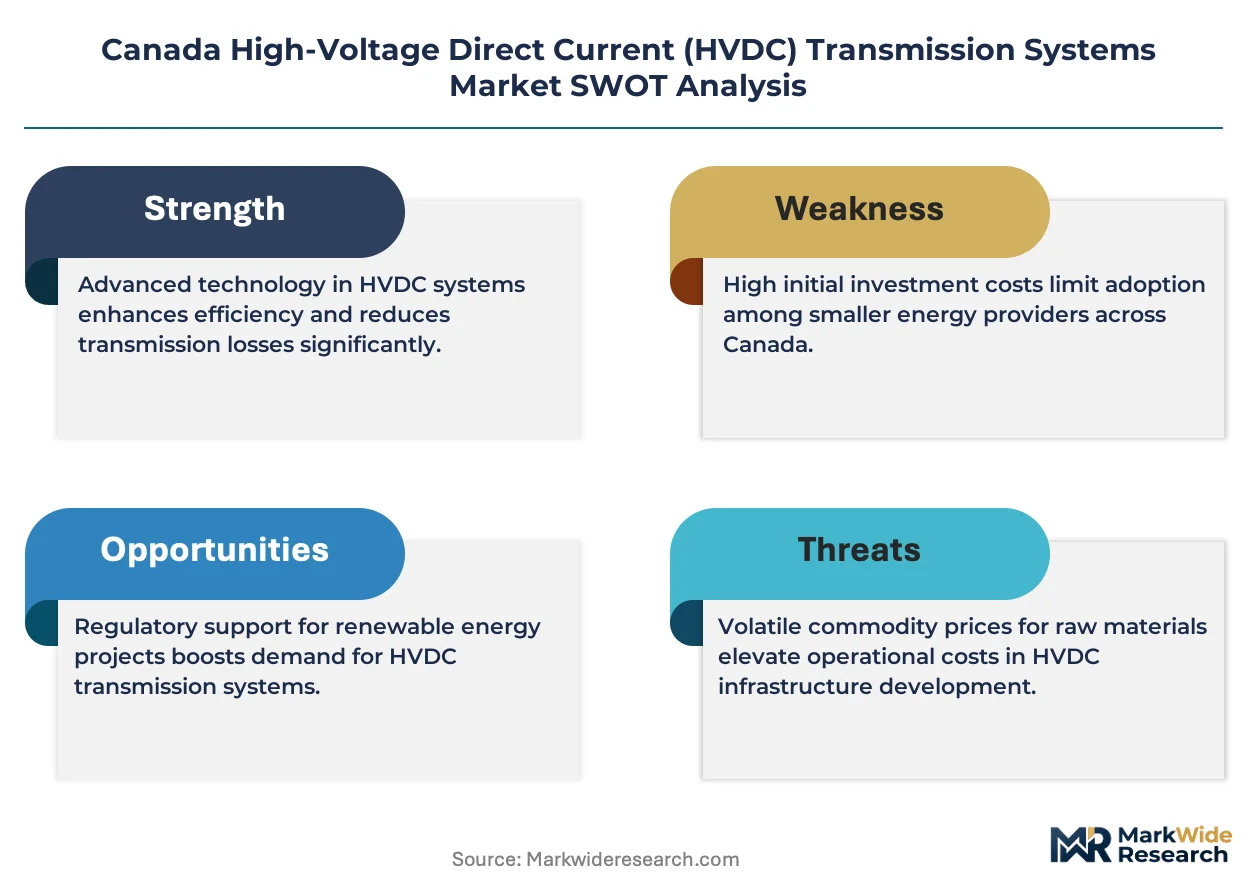
High-voltage direct current transmission systems transfer bulk electrical power over long distances using direct current at voltages typically exceeding 100 kV, with converter stations at each terminus transforming AC to DC and back to AC. These systems reduce resistive losses compared to alternating current equivalents, enabling economical interconnection of asynchronous grids and integration of remote renewable generation. Voltage source converter technology leads new project awards due to superior grid-forming capabilities and black-start functionality, while line-commutated converter installations retain dominance in legacy high-capacity corridors. The component segment concentrates margin pools in converter valves and high-voltage DC cables, where manufacturing complexity limits supplier entry.
Health Canada and Environment and Climate Change Canada shape environmental assessment requirements for cross-provincial transmission corridors, while the Canadian Electricity Association coordinates reliability standards adoption across provincial regulators. The Canadian Standards Association and IEEE standards govern equipment certification and interoperability, directly influencing procurement specifications for converter stations and cable systems. Provincial regulators in Quebec, British Columbia, and Manitoba enforce grid codes that mandate HVDC capability for remote resource integration. Stakeholders must monitor evolving federal clean electricity regulations and provincial interconnection queue reforms to anticipate project approval timelines and equipment procurement cycles.
Market Dynamics
Voltage source converter technology is displacing legacy line-commutated platforms across Canadian utility procurement cycles, compressing supplier margins while expanding grid-forming functionality requirements for remote renewable integration.
Growth Catalysts
- Clean Electricity Regulations:Federal mandates under Environment and Climate Change Canada accelerate converter station deployments for interprovincial grid integration, creating equipment procurement pull-through.
- Remote Hydroelectric Expansion:Provincial utilities in Quebec and British Columbia require HVDC corridors to transport bulk power from northern generation sites to southern urban load centers.
- Wind Integration Mandates:Manitoba Hydro and BC Hydro grid codes specify HVDC capability for asynchronous renewable resource connection, standardizing converter procurement specifications.
Market Restraints
- Converter Valve Supply Concentration:Manufacturing complexity for insulated-gate bipolar transistor modules limits qualified suppliers to European and Japanese semiconductor fabs, creating single-source vulnerability.
- Environmental Assessment Friction:Health Canada and provincial environmental review boards impose multi-year approval timelines for cross-provincial transmission corridors, delaying project sanctioning.
- Copper and Rare Earth Input Volatility:High-voltage DC cable production depends on copper price stability and dysprosium/terbium availability for permanent magnet converters, compressing project economics during commodity spikes.
Strategic Opportunities
- Submarine Interconnection White Space:Atlantic Canada offshore wind development creates demand for subsea HVDC links to mainland grids, opening cable installation and termination service markets.
- Grid-Forming Black-Start Services:Voltage source converter platforms enable islanded operation and grid restoration capabilities, allowing utilities to monetize ancillary services beyond energy transmission.
- Converter Station Digitalization:Integration of predictive maintenance analytics and digital twin modeling creates aftermarket software and service revenue streams for incumbent equipment suppliers.
Industry Challenges
- Specialized Commissioning Expertise Gap:Converter station startup and harmonic filter tuning require scarce power electronics engineers, extending project handover timelines and inflating labor costs.
- Legacy LCC System Interoperability:Mixed-technology corridors combining existing line-commutated converter assets with new voltage source converter terminals create control coordination complexity and protection setting conflicts.
- CSA and IEEE Certification Delays:Equipment qualification testing for Canadian Standards Association and Institute of Electrical and Electronics Engineers standards extends procurement cycles by six to twelve months for non-domestic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada High-Voltage Direct Current (HVDC) Transmission Systems Market |
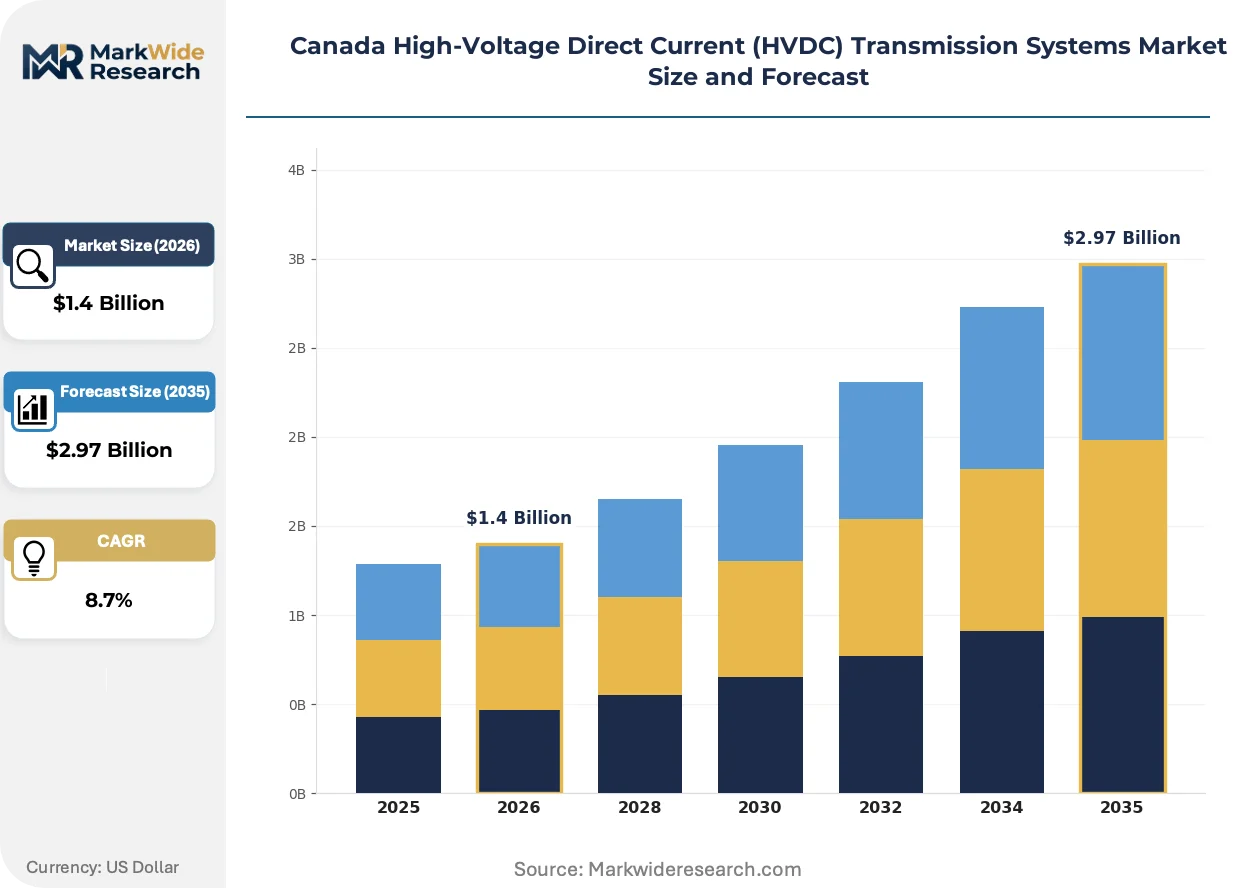
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Line Commutated Converter, Voltage Source Converter, Hybrid Converter, Others End User: Utilities, Industrial, Renewable Energy, Railways Application: Offshore Transmission, Onshore Transmission, Interconnection, Power Supply Stabilization Component: Transformers, Switchgear, Converters, Cables |
| Companies Covered | Hitachi Energy Ltd, Siemens Energy AG, General Electric Company, Nexans SA, Prysmian SpA, Toshiba Corporation, Mitsubishi Corp, LS Corp, J-Power Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market Strategic Shifts
Digital twin technology and modular converter architectures are compressing project delivery timelines while enabling predictive maintenance models that shift supplier revenue toward recurring service contracts.
Modular multilevel converter designs are virtualizing traditional converter station footprints by eliminating AC filters and reducing harmonic compensation requirements. Hydro-Québec and BC Hydro specify these platforms for greenfield corridor projects, enabling compact urban substation siting where land constraints previously blocked HVDC termination points.
Environment and Climate Change Canada's evolving federal clean electricity regulations are mandating grid-forming inverter capabilities for all new transmission assets connecting remote renewable generation. This regulatory pressure forces converter station procurement specifications to prioritize black-start functionality and synthetic inertia provision, disqualifying legacy line-commutated converter bids from new project awards.
Utility procurement departments are consolidating equipment and long-term service contracts into single-source agreements, displacing traditional component-by-component tendering. This behavioral shift concentrates supplier relationships around full-lifecycle performance guarantees, with Quebec and British Columbia utilities leading the transition toward availability-based contracting models.
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market Segmentation
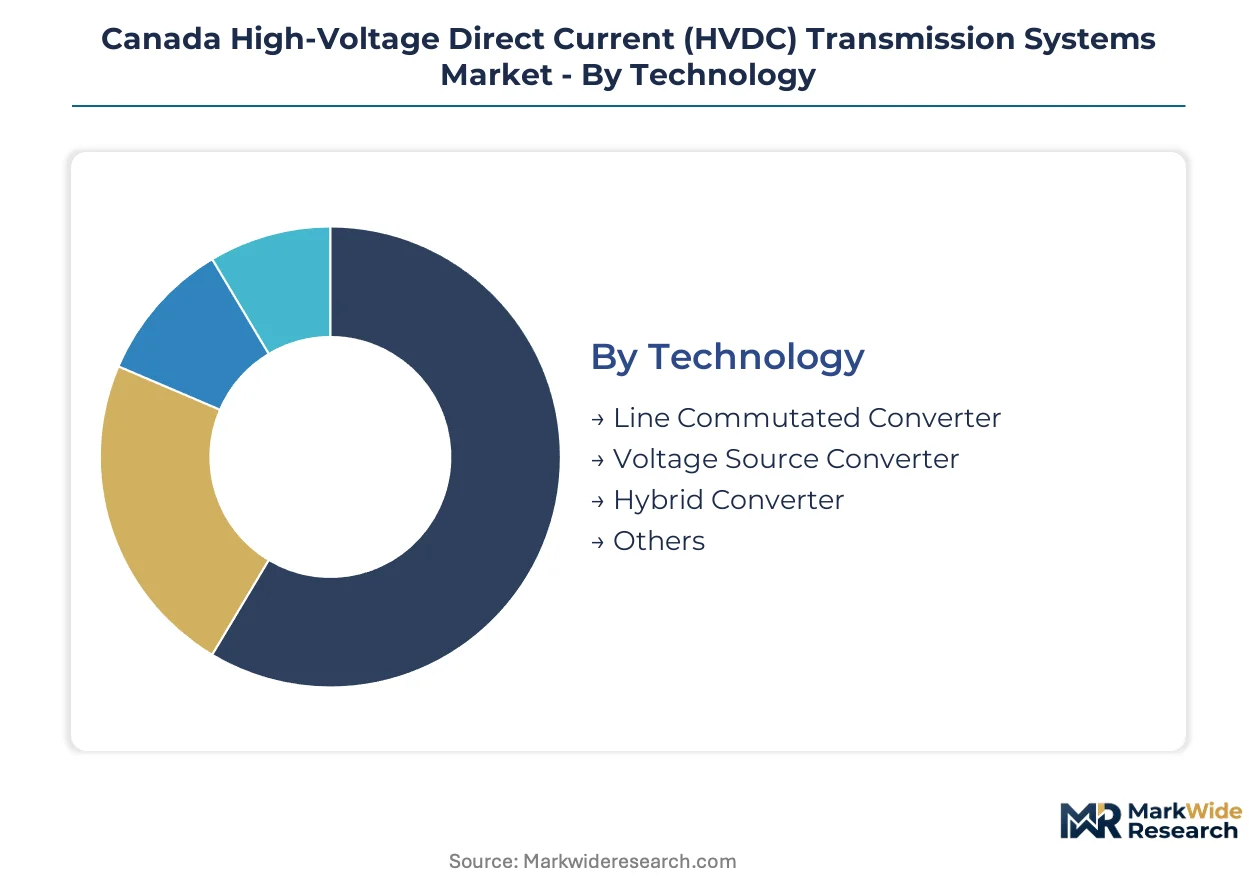
HVDC system segmentation reveals how procurement specifications diverge across converter technologies, end-use requirements, and component hierarchies. Each dimension shapes supplier positioning and margin capture differently across Quebec's hydro corridors and British Columbia's intertie projects.
Technology:
Cost tier segmentation separates legacy infrastructure from next-generation converter platforms, with procurement budgets determining technology access for provincial utilities.
- Line Commutated Converter:Thyristor-based rectification technology dominates installed capacity across Hydro-Québec's legacy corridors. Quebec and Manitoba utilities specify LCC platforms for bulk power transfer exceeding 1000 MW where black-start capability is less critical than capital efficiency.
- Voltage Source Converter:Insulated-gate bipolar transistor modules enable independent reactive power control and grid-forming functionality. British Columbia and Atlantic Canada project pipelines specify VSC exclusively for offshore wind interconnection and weak grid support applications.
- Hybrid Converter:Combines thyristor economics with IGBT flexibility for corridor upgrades. Hydro-Québec's multi-terminal projects evaluate hybrid architectures for retrofit compatibility.
- Others:Emerging modular multilevel and resonant converter topologies occupy pilot demonstration budgets.
Line Commutated Converter holds installed capacity. Voltage Source Converter is rotating up the share rankings.
End User:
Application context varies sharply across customer types, with grid code mandates and financing structures driving divergent procurement behaviors.
- Utilities:Provincial crown corporations dominate HVDC deployment through integrated resource planning mandates. Hydro-Québec, BC Hydro, and Manitoba Hydro specify converter stations for interprovincial bulk transfer and remote generation integration, with procurement cycles tied to five-year capital plans.
- Industrial:Mining and smelting operations in northern Quebec and British Columbia procure dedicated HVDC taps for remote facility electrification. Aluminum sector demand concentrates around low-cost hydro access contracts.
- Renewable Energy:Offshore wind developers in Atlantic Canada and run-of-river hydro projects in British Columbia specify HVDC export capacity for asynchronous resource connection.
- Railways:Electrified freight corridors evaluate DC traction supply through converter station taps, with limited deployment outside core networks.
Utilities anchor procurement volume. Renewable Energy is climbing the fastest as Atlantic offshore wind queues mature.
Application:
Geography determines technical specification intensity, with marine environments and terrestrial corridors imposing distinct engineering constraints.
- Offshore Transmission:Subsea cable systems connect islanded generation to mainland grids. Atlantic Canada offshore wind leases specify HVDC export for distances exceeding 50 kilometers where AC capacitance losses become prohibitive.
- Onshore Transmission:Overhead line corridors traverse remote terrain with converter stations at generation and load termini. Quebec's northern hydro expansion and BC's Site C intertie exemplify high-capacity terrestrial deployment.
- Interconnection:Asynchronous grid links between provinces or with US markets require back-to-back converter stations. Manitoba-Minnesota and Quebec-New England interties operate under FERC and provincial joint operating agreements.
- Power Supply Stabilization:Dynamic voltage support and frequency regulation services through HVDC taps address weak grid conditions in remote load centers.
Onshore Transmission holds deployed kilometers. Offshore Transmission is expanding most quickly with lease round acceleration.
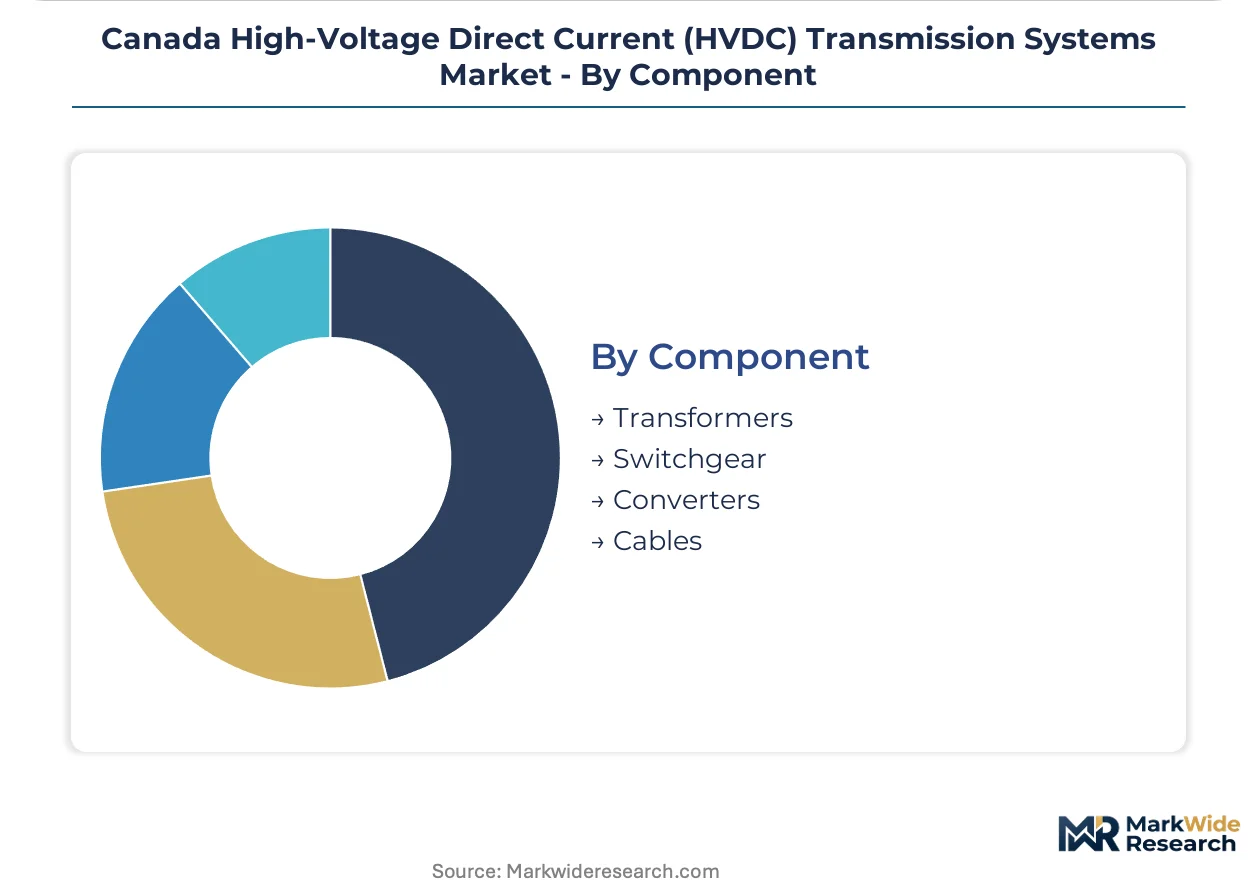
Component:
Supply concentration and manufacturing complexity concentrate margin capture differently across the component stack.
- Converters:Valve halls and control systems represent 35-45% of station capital cost. IGBT module supply from European and Japanese fabs constrains delivery timelines for VSC projects.
- Cables:Extruded DC insulation systems for subsea and underground routes require specialized manufacturing. Nexans and Prysmian dominate high-voltage DC cable qualification for Canadian projects.
- Transformers:Converter transformers match AC grid voltage to valve hall requirements. Domestic manufacturing capacity limits procurement flexibility for 500 kV+ units.
- Switchgear:DC circuit breakers and disconnectors protect against fault conditions. Hybrid mechanical-semiconductor breaker technology is displacing pure mechanical solutions for multi-terminal networks.
Converters dominate capital allocation. Cables are gaining share fastest with subsea project proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quebec and British Columbia deploy HVDC corridors for bulk hydroelectric transfer, while Atlantic Canada pursues offshore wind interconnection using submarine cable systems. Provincial regulatory frameworks and federal clean electricity mandates create divergent procurement timelines across these markets.
Quebec
Hydro-Québec's northern hydroelectric expansion drives converter station procurement for 735 kV DC corridors connecting La Grande complex to Montreal load centers. Environment and Climate Change Canada's federal clean electricity regulations mandate grid-forming inverter capabilities for new transmission assets. The James Bay region anchors project development with multi-terminal HVDC configurations under active evaluation.
British Columbia
BC Hydro's Site C intertie and Peace River corridor projects require voltage source converter platforms for asynchronous grid support. The Canadian Electricity Association coordinates reliability standards adoption with provincial grid codes specifying black-start functionality. Vancouver and the Lower Mainland concentrate urban substation siting where modular converter architectures address land constraints.
Manitoba
Manitoba Hydro's Nelson River transmission system upgrades sustain line-commutated converter procurement for bulk power export to Minnesota. The province's renewable integration mandates standardize HVDC capability specifications for run-of-river hydro connections. Winnipeg serves as the engineering coordination hub for cross-border intertie operations under joint FERC-provincial agreements.
Atlantic Canada
Offshore wind lease rounds in Newfoundland and Labrador create demand for subsea HVDC export cables exceeding 50 kilometers. Health Canada environmental assessments govern marine corridor permitting timelines for submarine interconnection projects. Halifax and St. John's emerging as cable termination service hubs for Atlantic offshore grid integration.
Alberta
Alberta Utilities Commission interconnection queue reforms accelerate converter station procurement for wind and solar export to British Columbia and US markets. The province's grid code amendments specify HVDC capability for asynchronous renewable resource connection. Calgary anchors project development coordination with transmission planners evaluating back-to-back converter configurations for interprovincial links.
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market Competitive Environment
Capability concentration sits with specialized converter valve manufacturers; scale advantage sits with integrated electrical equipment conglomerates. The Canadian market structures around three supplier tiers: European-Japanese semiconductor fabs controlling insulated-gate bipolar transistor module supply, cable specialists dominating subsea insulation systems, and diversified industrial groups bundling converter stations with long-term service contracts. Strategic moves concentrate on availability-based contracting consolidation and predictive maintenance software integration.
Within the integrated equipment tier, Hitachi Energy Ltd and Siemens Energy AG exemplify full-lifecycle positioning through converter platform engineering and localized service networks. Nexans SA occupies a specialist position in high-voltage DC cable manufacturing for subsea and underground routes. These three anchors represent divergent competitive vectors: integrated station supply, component specialization, and service contract capture.
| Leading Market Players |
|---|
| Hitachi Energy Ltd |
| Siemens Energy AG |
| General Electric Company |
| Nexans SA |
| Prysmian SpA |
| Toshiba Corporation |
| Mitsubishi Corp |
| LS Corp |
| J-Power Group |
| Others |
Value Chain & Pricing Dynamics
The St. Lawrence Seaway freight corridor's bulk cargo rates influence converter station component logistics costs, amplifying pricing power for European IGBT module suppliers while forcing tiered contract structures that separate premium voltage source converter platforms from legacy line-commutated alternatives.
Pricing Analysis
Long-term offtake agreements dominate procurement for Hydro-Québec and BC Hydro corridor projects, embedding availability-based payments that reward grid-forming performance over capital expenditure minimization. Price differentiation separates premium voltage source converter platforms with black-start certification from standard line-commutated alternatives lacking synthetic inertia provision. Pricing pressure intensifies in the converter valve segment as European and Japanese semiconductor fabs consolidate insulated-gate bipolar transistor supply, squeezing margins for station integrators. Provincial crown corporations exhibit lowest price sensitivity due to integrated resource planning mandates, while Atlantic Canada offshore wind developers face acute capital constraints that favor equipment leasing structures over outright purchase.
Supply Chain Analysis
High-purity copper cathode feedstock draws from Chilean and Peruvian mining operations, with dysprosium and terbium for permanent magnet converters anchored in Chinese rare earth processing facilities. Insulated-gate bipolar transistor modules rest on Japanese and European semiconductor fabrication, while extruded DC cable insulation systems concentrate manufacturing in France and Italy. Single-source vulnerability pervades the IGBT supply tier, where qualified fabs number fewer than five globally. Distribution runs through engineering-procurement-construction contractors with established relationships to provincial utilities, limiting direct equipment procurement by project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's HVDC market sits in early-cycle expansion as federal clean electricity regulations mandate grid-forming inverter capabilities for all new remote generation interconnection, accelerating converter station deployment timelines across provincial utility capital plans.
For Market Incumbents: Pre-empt voltage source converter platform commoditization by embedding predictive maintenance software and digital twin capabilities into long-term service contracts, locking in recurring revenue streams before European competitors establish localized engineering support. Defend position against emerging modular multilevel converter specialists through backward integration into converter transformer manufacturing, addressing domestic capacity constraints that delay 500 kV+ unit delivery. Prioritize certification investment for CSA and IEEE standards compliance to compress procurement cycles for non-domestic suppliers. For New Entrants and Emerging Players: Atlantic Canada submarine cable termination services represent the most penetrable entry point, where Health Canada environmental assessment expertise creates barriers for European incumbents lacking Canadian regulatory navigation experience. Grid-forming black-start ancillary services in British Columbia's weak grid zones offer second-mover opportunity, with BC Hydro's grid code amendments standardizing procurement specifications that reduce incumbent relationship advantages. Pursue joint venture structures with established cable installation contractors to bypass direct converter valve supply concentration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded converter station engineering capabilities but insufficient scale to compete for full-lifecycle availability contracts. Long-term viability centers on suppliers with demonstrated grid-forming platform deployment and localized service network density across Quebec and British Columbia. Monitor provincial interconnection queue reform announcements as inflection indicators for project sanctioning velocity and equipment procurement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Platform Certification | CSA and IEEE compliance enables participation in Hydro-Québec's 735 kV corridor procurement cycles. |
| Predictive Maintenance Software Integration | Digital twin capabilities shift revenue toward recurring service contracts with provincial crown corporations. |
| Submarine Cable Manufacturing Scale-Up | Atlantic Canada offshore wind leases demand extruded DC insulation systems for 50+ kilometer export routes. |
| Converter Transformer Domestic Capacity | In-house production of 500 kV+ units addresses procurement bottlenecks constraining project delivery timelines. |
| Long-Term Service Agreement Consolidation | Availability-based contracting with BC Hydro and Manitoba Hydro locks in multi-decade revenue streams. |
Study Parameters
A standing panel of utility planning officers, EPC contractor project directors, converter station commissioning engineers, and provincial regulator interconnection queue administrators provided ongoing calibration across primary interview cycles. Secondary validation drew from Canadian Electricity Association reliability standards documentation, Environment and Climate Change Canada clean electricity regulation filings, CSA equipment certification databases, and IEEE transmission standards publications. Bottom-up project pipeline enumeration triangulated against top-down provincial capital expenditure forecasts to establish market sizing boundaries.
Scenario-bracketing framed low, base, and high cases across commodity price volatility for copper and rare earth inputs, environmental assessment timeline variation, and voltage source converter technology adoption curves. Segmentation dimensions modeled encompassed converter technology tier, end-user utility type, application geography, and component hierarchy across the analysis window. CAGRs derived from equipment procurement cycle analysis and project sanctioning probability assessments, with inputs from converter valve delivery lead times and cable manufacturing capacity utilization.
Stress conditions across IGBT supply disruption, copper price spikes, and multi-year environmental assessment delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding federal regulation enforcement timelines and provincial grid code amendment adoption. Cross-checking against Canadian Electricity Association interconnection queue data and provincial utility integrated resource plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
DC Distribution Network Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Flexible AC Transmission Systems Market
Transmission and Distribution
Power Transmission Lines and Towers Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
Electric Power Transmission and Distribution Equipment Market
Transmission and Distribution
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Natural Gas Storage Technologies Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
Pipeline Transportation Market