
 United States Oil and Gas Upstream Market | 2026-2036
United States Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
United States Oil and Gas Upstream Market Analytics
Multi-source procurement for pressure pumping and directional drilling services is hardening across the Lower 48. EOG Resources anchors its cost position through in-house geosteering and proprietary well completion designs. Pioneer Natural Resources dominates the Midland Basin with contiguous acreage that sustains extended lateral lengths. Exxon Mobil Corporation leverages its integrated logistics network to compete on delivered cost in the Delaware Basin.
United States oil and gas upstream encompasses the identification, drilling, and extraction of crude oil and natural gas from subsurface reservoirs, typically targeting formations at depths of 5,000 to 15,000 feet with bottom-hole temperatures exceeding 250°F. The primary purpose is to deliver hydrocarbon feedstocks to refineries, petrochemical complexes, and LNG export terminals. Horizontal drilling leads capital deployment due to its productivity multiplier in unconventional reservoirs, while hydraulic fracturing commands the largest share of variable operating expenditure. Enhanced oil recovery represents the fastest-growing technology segment as operators revisit mature waterfloods with CO2 injection.
The EPA enforces methane performance standards under the Clean Air Act, compelling operators to deploy continuous monitoring equipment or face escalating fees. The Bureau of Land Management regulates drilling permits and bonding requirements on federal acreage, directly shaping pace of development in the Rocky Mountain region. OSHA mandates process safety management for drilling contractors, filtering market access to firms with certified training programs. Stakeholders must monitor how the Federal Energy Regulatory Commission balances pipeline certification timelines against environmental review demands.
Market Dynamics
EPA methane performance standards under the Inflation Reduction Act are forcing capital reallocation toward continuous emissions monitoring infrastructure, compressing drilling economics and favoring operators with integrated leak detection capabilities.
Growth Catalysts
- Power generation offtake expansion:Utilities are contracting dedicated volumes from Permian Basin tight oil plays, securing baseload feedstock for combined-cycle gas turbines.
- Enhanced oil recovery technology maturation:CO2 injection systems are revisiting mature waterfloods in the Permian and Gulf Coast, unlocking stranded reserves.
- IRA methane fee structure:The escalating fee schedule above 25,000 metric tons CO2-equivalent is accelerating LDAR system deployment.
Market Restraints
- Proppant supply concentration:Northern White Sand deposits in Wisconsin and Minnesota face rail capacity constraints, elevating delivered costs to Permian well sites.
- Federal acreage permitting delays:Bureau of Land Management bonding requirements and environmental review timelines stretch development schedules in the Rocky Mountain region.
- Geothermal heat pump substitution:Residential and commercial building electrification is eroding long-term natural gas demand growth in heating applications.
Strategic Opportunities
- Delaware Basin sub-salt imaging:Advanced seismic processing is revealing untapped pay zones beneath existing production horizons in southeastern New Mexico.
- Hydrogen blending infrastructure:Pipeline operators are retrofitting gathering systems for hydrogen-natural gas mixtures, creating new offtake pathways.
- Carbon capture utilization:45Q tax credit expansion under the IRA is incentivizing CO2-EOR projects with permanent sequestration certification.
Industry Challenges
- Geosteering talent scarcity:Horizontal drilling complexity demands specialized petrophysicists and directional drillers, with training pipelines failing to match replacement rates.
- Legacy SCADA integration:Continuous methane monitoring systems must interface with decades-old wellhead automation infrastructure, creating cybersecurity vulnerabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Oil and Gas Upstream Market |
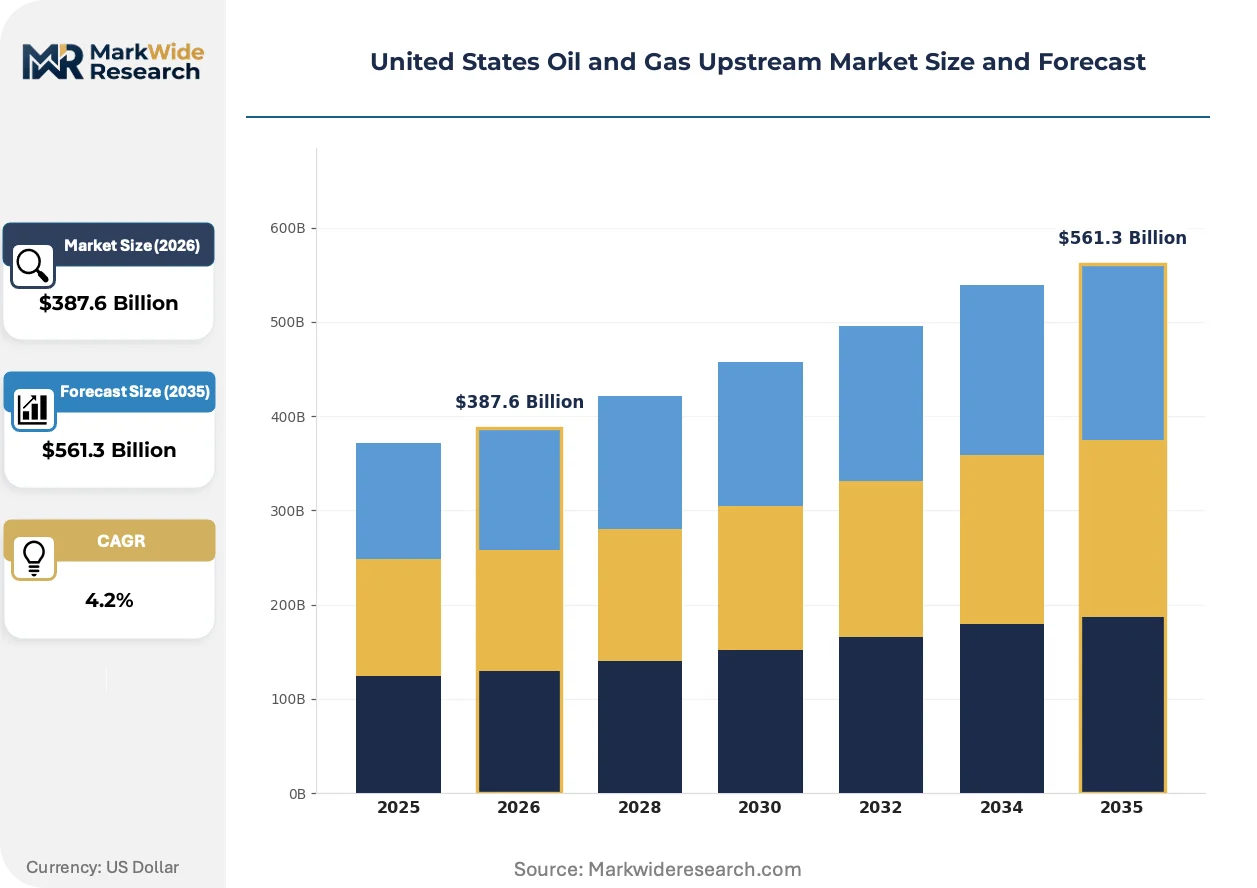
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $561.3 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Exploration, Drilling, Production, Completion Service Type: Well Services, Seismic Services, Reservoir Management, Project Management Technology: Horizontal Drilling, Hydraulic Fracturing, Blowout Preventers, Enhanced Oil Recovery End User: Independent Producers, National Oil Companies, Oilfield Services, Integrated Energy Firms |
| Companies Covered | EOG Resources, Pioneer Natural Resources, Exxon Mobil Corporation, Hess Corporation, Devon Energy, Chevron Corporation, Occidental Petroleum Corporation, Diamondback Energy, ConocoPhillips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Oil and Gas Upstream Market Evolving Landscape
Digital twin modeling and autonomous drilling systems are compressing well construction timelines while regulatory pressure on emissions intensifies hardware refresh cycles across the Lower 48.
Electrified pressure pumping fleets are converging with grid-connected power purchase agreements, enabling operators to substitute natural gas-fired prime movers with utility-scale electricity. EOG Resources and Pioneer Natural Resources are piloting turbine-electric fracturing spreads in the Midland Basin. This convergence is compressing fuel cost volatility exposure while tethering operational uptime to regional transmission reliability.
EPA's methane performance standards under the Clean Air Act now mandate quarterly optical gas imaging surveys or continuous monitoring for all new and modified facilities. Operators face escalating fees starting at $900 per metric ton of excess emissions. The Delaware Basin sub-segment is responding fastest, with integrated producers deploying aerial LiDAR and satellite-based detection to minimize manual survey labor.
Long-term offtake contracting is displacing spot market sales for Permian Basin producers, with power utilities and LNG export terminals seeking 10-15 year volume commitments. This shift transfers price risk to upstream operators while securing capital for extended lateral development. The phenomenon is most visible in West Texas, where pipeline-connected volumes command premiums over basin-remote supply.
United States Oil and Gas Upstream Market Segmentation
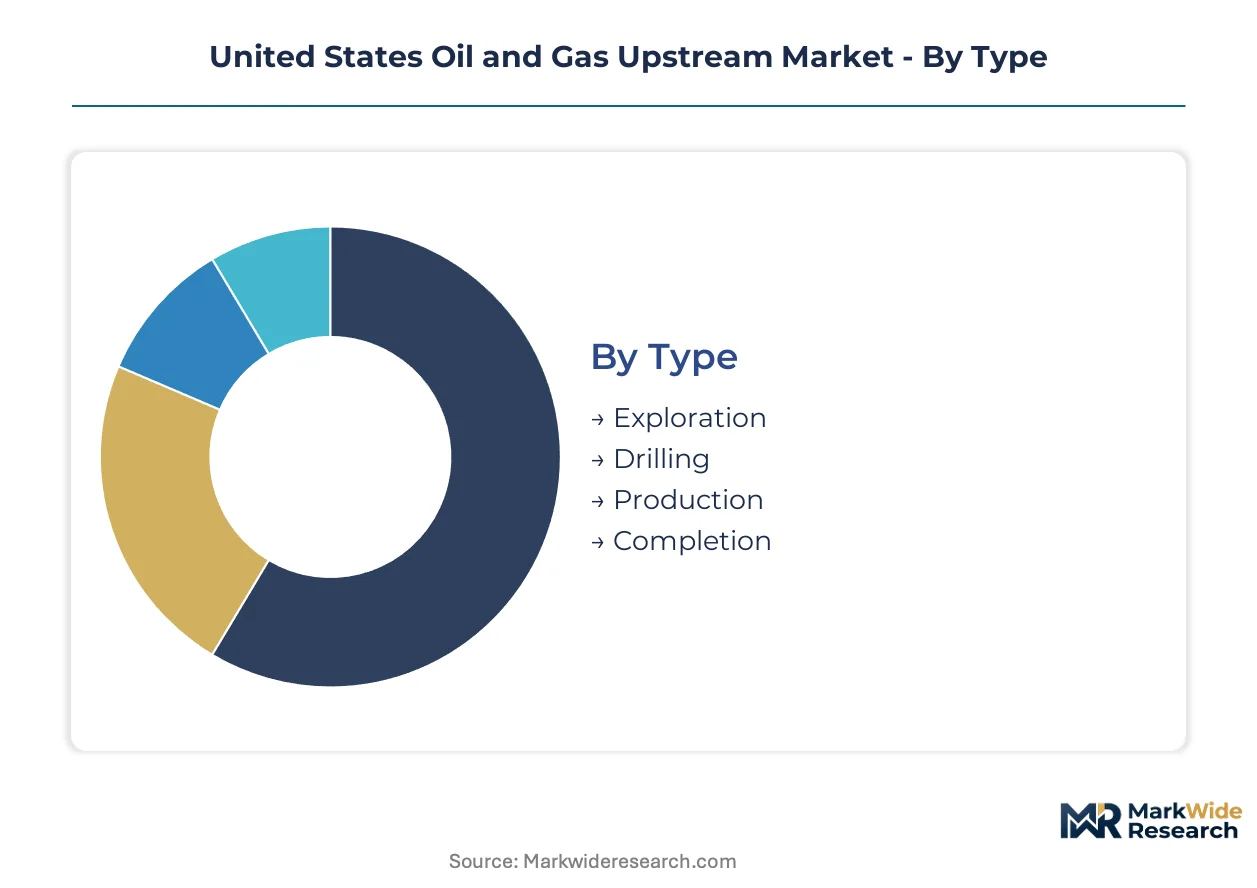
Upstream segmentation reveals how capital allocation priorities differ across operational phases, service models, and technological approaches. Understanding these divides clarifies where EPA methane compliance costs concentrate and which buyer types drive contracting innovation in the Permian Basin.
Type:
Capital intensity and regulatory exposure vary sharply across the operational lifecycle, with late-stage phases commanding premium pricing due to specialized equipment requirements.
- Exploration:Geophysical surveys and wildcat drilling target untested formations at depths exceeding 12,000 feet in the Delaware Basin. Operators in southeastern New Mexico concentrate activity here as sub-salt imaging improves recoverable reserve estimates.
- Drilling:Extended-reach horizontal laterals now exceed 15,000 feet in the Midland Basin, demanding high-specification rigs and directional drilling expertise. Demand clusters with contiguous acreage holders who can maximize lateral length without crossing lease boundaries.
- Production:Artificial lift systems and surface facility operations dominate variable opex in mature fields. EPA methane monitoring mandates are compressing margins here, favoring operators with integrated SCADA infrastructure.
- Completion:Multi-stage hydraulic fracturing and wellhead assembly represent the most equipment-intensive phase. Proppant logistics and pressure pumping availability determine development pace in West Texas tight oil plays.
Volume sits with Production; growth tilts toward Completion.
Service Type:
Procurement patterns are fragmenting as operators unbundle integrated service packages to optimize specific technical capabilities.
- Well Services:Workover rigs, well intervention, and maintenance operations sustain production from existing assets. The Permian Basin's aging vertical well inventory generates recurring demand for recompletion and artificial lift optimization.
- Seismic Services:3D and 4D seismic acquisition plus advanced processing reveal untapped pay zones beneath existing production horizons. Delaware Basin operators are deploying this capability fastest to identify sub-salt opportunities.
- Reservoir Management:Simulation modeling and production optimization integrate geological data with real-time well performance. CO2-EOR projects in the Permian require specialized expertise in miscible flood design and plume monitoring.
- Project Management:Integrated drilling and completion coordination reduces non-productive time across multi-well pads. Large-scale development programs in the Midland Basin favor operators with captive project management capabilities.
Revenue concentrates in Well Services; capability premiums accrue to Reservoir Management.
Technology:
Technology selection directly determines regulatory compliance pathways and recovery factors in unconventional reservoirs.
- Horizontal Drilling:Directional steering through target zones maximizes reservoir contact per wellbore. The technology enables extended lateral development that transforms Midland Basin economics through scale efficiencies.
- Hydraulic Fracturing:High-pressure fluid injection creates conductive fracture networks in tight formations. Electrified pressure pumping spreads are emerging in West Texas as operators seek to reduce emissions intensity and fuel cost volatility.
- Blowout Preventers:Subsurface safety systems with shear ram capabilities protect against uncontrolled formation pressure releases. BSEE regulations mandate redundant configurations for offshore and high-pressure onshore applications.
- Enhanced Oil Recovery:CO2 injection and thermal methods unlock stranded reserves from mature waterfloods. IRA 45Q tax credits are accelerating deployment in the Permian, where pipeline-connected CO2 supply enables permanent sequestration certification.
Deployment volume favors Hydraulic Fracturing; regulatory tailwinds are expanding fastest for Enhanced Oil Recovery.
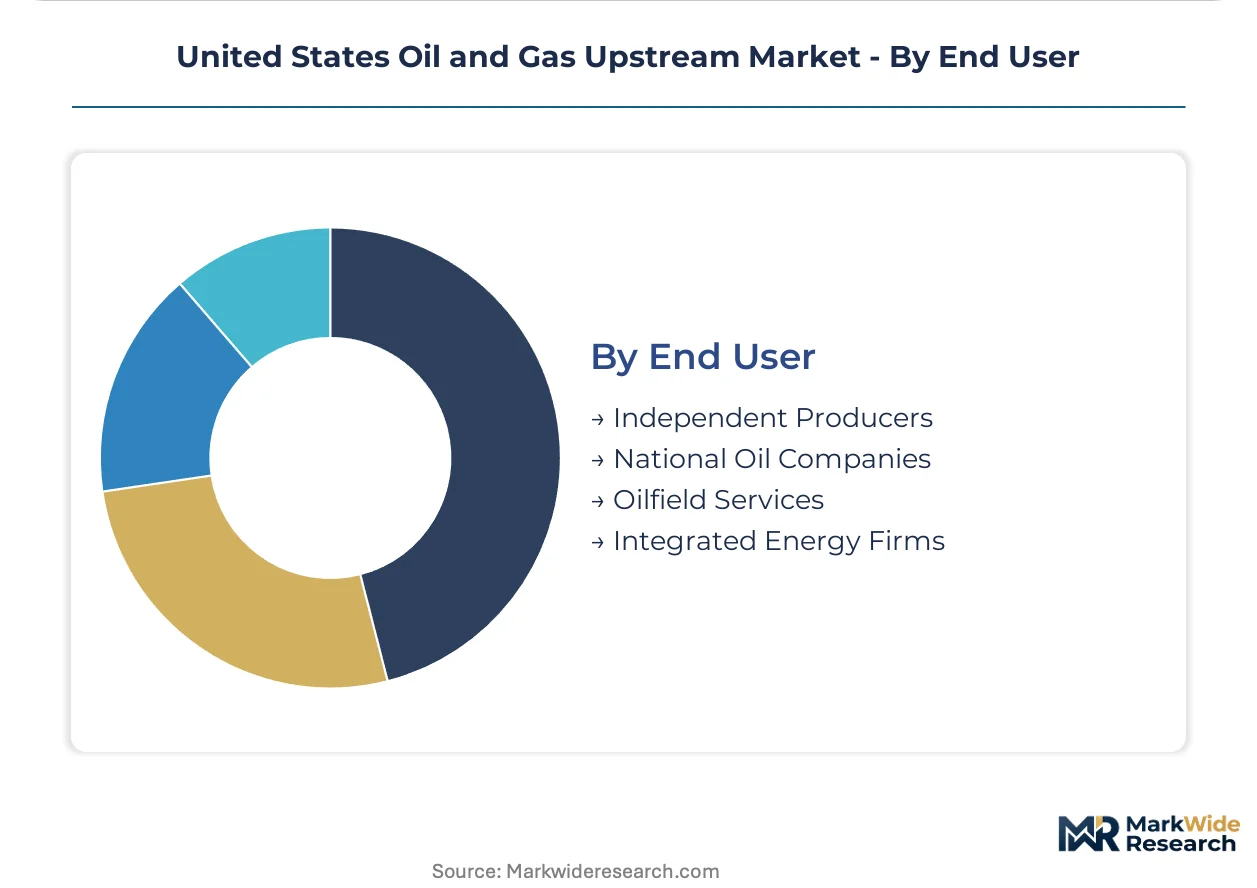
End User:
Buyer sophistication and contracting horizons diverge substantially across organizational types, shaping supplier relationship strategies.
- Independent Producers:Privately held and publicly traded E&Ps without downstream assets focus exclusively on reserve replacement and production growth. These operators dominate Permian Basin drilling activity and are most exposed to spot commodity price cycles.
- National Oil Companies:State-owned entities with US upstream positions prioritize long-term reserve access over short-term returns. Their capital allocation remains insulated from quarterly earnings pressure affecting domestic independents.
- Oilfield Services:Schlumberger, Halliburton, and specialized contractors purchase technology and equipment for re-sale to upstream operators. Their procurement decisions aggregate demand across multiple producer relationships.
- Integrated Energy Firms:Majors with refining, chemicals, and marketing operations optimize upstream production for feedstock security rather than pure price exposure. Exxon Mobil Corporation leverages this structure to compete on delivered cost in the Delaware Basin.
Activity volume concentrates with Independent Producers; contract duration extends longest with Integrated Energy Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin tight oil deposits anchor upstream activity across the Lower 48, with West Texas and southeastern New Mexico commanding the dominant share of drilling permits and capital deployment.
West Texas
Midland Basin operators deploy extended-reach horizontal laterals exceeding 15,000 feet to maximize reservoir contact per wellbore. EPA methane performance standards under the Inflation Reduction Act are compressing margins for producers lacking integrated leak detection infrastructure. The Permian Basin's Delaware sub-basin in Reeves and Loving counties is seeing accelerated seismic imaging investment to identify sub-salt pay zones.
Southeastern New Mexico
Delaware Basin drilling targets untested formations beneath existing production horizons as advanced seismic processing improves recoverable reserve estimates. Bureau of Land Management bonding requirements and environmental review timelines are stretching development schedules on federal acreage. Lea and Eddy counties concentrate CO2-EOR project deployment where pipeline-connected supply enables permanent sequestration certification.
Gulf Coast
Offshore operators in federal waters face BSEE-mandated redundant blowout preventer configurations for high-pressure applications. The region's mature waterflood inventory generates demand for recompletion and artificial lift optimization services. Louisiana's onshore coastal zone is seeing hydrogen blending infrastructure pilots as pipeline operators retrofit gathering systems for mixed-gas offtake.
Rocky Mountain Region
Federal acreage permitting delays under BLM jurisdiction are constraining pace of development across Wyoming and Colorado. Operators here concentrate enhanced oil recovery technology deployment to revisit mature fields with CO2 injection systems. The Denver-Julesburg Basin is experiencing geosteering talent scarcity as horizontal drilling complexity outpaces training pipeline output.
United States Oil and Gas Upstream Market Competitive Landscape
Global majors compete with regional champions across capital allocation discipline and operational integration depth. The vendor base clusters around three tiers: integrated energy firms with downstream feedstock security, large-cap independents with contiguous acreage positions, and specialized operators with technology-led cost structures. Consolidation pressure is intensifying as contiguous acreage premiums rise and methane compliance costs compress sub-scale economics. Dominant competitive moves include multi-billion-dollar acreage acquisitions and captive deployment of continuous emissions monitoring infrastructure.
Within the integrated tier, Exxon Mobil Corporation and Chevron Corporation anchor positions through logistics networks that optimize delivered cost across basin-remote supply. Among large-cap independents, EOG Resources exemplifies technology-led differentiation through proprietary well completion designs and in-house geosteering capabilities. Pioneer Natural Resources occupies a position defined by Midland Basin contiguous acreage that sustains extended lateral development without lease boundary constraints.
| Leading Market Players |
|---|
| EOG Resources |
| Pioneer Natural Resources |
| Exxon Mobil Corporation |
| Hess Corporation |
| Devon Energy |
| Chevron Corporation |
| Occidental Petroleum Corporation |
| Diamondback Energy |
| ConocoPhillips |
| Others |
Value Network & Pricing Analysis
EPA methane performance standards under the Inflation Reduction Act gate qualified supply access and premium-tier pricing power, compressing margins for operators lacking integrated leak detection and repair infrastructure while rewarding those with certified continuous monitoring capabilities.
Pricing Analysis
Service bundling separates integrated LDAR-inclusive contracts from unbundled equipment-only transactions. The dominant structure runs through long-term offtake agreements with embedded methane compliance costs, where price differentiation rests on certification tier and contiguous acreage scale. Cost compression in spot-market sales is intensifying because utilities prefer contracted volumes with emissions guarantees. Independent producers show highest price sensitivity; integrated energy firms with captive downstream demand exhibit lowest.
Supply Chain Analysis
Multi-supplier qualification mandates from Permian Basin operators fragment procurement across pressure pumping and directional drilling vendors. Geographic concentration centers on Texas, New Mexico, and Louisiana for rig mobilization and proppant staging. Raw material dependencies include Northern White Sand, high-grade steel for drill pipe, and specialized elastomers for blowout preventers. Single-source vulnerability in Wisconsin sand deposits elevates delivered costs. Distribution runs through pipeline-connected gathering systems and rail-fed transload terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States oil and gas upstream market sits in a technology-transition phase, with electrified pressure pumping fleets displacing natural gas-fired prime movers and tethering operational economics to regional grid reliability.
For Market Incumbents: Anchor contiguous acreage positions through targeted acquisitions in the Midland Basin, where extended lateral development transforms unit economics. Defend against margin compression from EPA methane fees by deploying captive continuous monitoring infrastructure. Prioritize in-house geosteering capabilities to reduce reliance on scarce directional drilling talent.
For New Entrants and Emerging Players: Launch via specialized CO2-EOR service models targeting mature Permian waterfloods eligible for 45Q tax credits. White-space opportunity concentrates in Delaware Basin sub-salt imaging and hydrogen blending infrastructure retrofits. Pursue power utility offtake partnerships to secure decade-long volume commitments that transfer price risk.
For Investors and Strategic Acquirers: Electrified fracturing spread deployment announcements from major independents are the leading indicator that operational emissions intensity is becoming a capital allocation filter. Long-term viability favors operators with integrated logistics networks and certified sequestration pathways. Monitor Bureau of Land Management permitting velocity as the inflection signal for Rocky Mountain development pace.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Pressure Pumping Deployment | Substitutes utility-scale electricity for natural gas prime movers, compressing fuel cost volatility exposure. |
| Contiguous Acreage Acquisition | Enables extended-reach horizontal laterals exceeding 15,000 feet without lease boundary constraints. |
| Continuous Emissions Monitoring Integration | Satisfies EPA quarterly optical gas imaging mandates while minimizing manual survey labor costs. |
| CO2-EOR with Permanent Sequestration | Captures IRA 45Q tax credits by certifying carbon dioxide injection for stranded reserve recovery. |
| Power Utility Long-Term Offtake Contracting | Secures baseload feedstock commitments for combined-cycle gas turbines across 10-15 year horizons. |
Research Methodology
Multi-period observation of drilling permit filings, rig count trajectories, and methane emissions disclosure trends anchored the trend analysis, supplemented by interviews with upstream operations executives, reservoir engineers, EPA compliance officers, and power utility fuel procurement directors. Secondary validation drew from EIA production databases, FERC pipeline certification records, SEC 10-K filings, and Bureau of Land Management lease sale results. Bottom-up well-level economics and top-down basin-wide supply models were triangulated to cross-check volume and value estimates.
Input-output matrices mapped capital deployment across exploration, drilling, completion, and production phases against regulatory cost overlays and technology adoption curves. Segmentation dimensions spanned operational lifecycle stage, service unbundling depth, technology type, and end-user organizational structure. CAGRs were derived from regression analysis of historical capital expenditure patterns and projected activity levels. Forecast inputs incorporated electrification infrastructure buildout timelines and CO2 pipeline network expansion trajectories.
The model assumes a particular technology adoption path for electrified pressure pumping; alternative pathways for turbine-electric fracturing spreads would alter the outlook if regional transmission reliability constraints persist. Forecasts reflect assumptions about EPA methane fee enforcement intensity and BLM permitting velocity. Deviation in IRA 45Q credit permanence or power utility offtake contracting appetite would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Oil and Gas Midstream Market
Oil & Gas
LNG Storage Tank Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Drilling Services Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Well Casing Market
Oil & Gas
Riserless Light Well Intervention Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Colombia Oil and Gas Midstream Market
Oil & Gas
Integrated Gas System Market
Oil & Gas
Modular Gas Processing Plants Market