
 North America DC Distribution Network Market | 2026-2036
North America DC Distribution Network Market Size, Share, and Industry Trends Forecast 2026-2036
North America DC Distribution Network Market Analytics
Multi-source procurement for power conversion hardware is restructuring supply relationships across the North America DC Distribution Network Market. ABB Ltd. leverages its installed base in industrial DC systems to sustain renewal cycles in manufacturing plants. Siemens AG anchors its position through integrated digital twin platforms that span design-to-operations workflows. Schneider Electric SE competes by specializing in modular DC switchgear architectures for colocation facilities.
A DC distribution network transmits electrical power using direct current rather than alternating current, typically operating at voltage levels from 380V to 1500V in commercial and industrial settings, with solid-state power converters replacing traditional transformer-based stepping. These systems serve primary industrial and commercial purposes by eliminating AC-DC conversion losses in data centers, renewable integration points, and electrified manufacturing processes. Circuit breakers and switchgear command the deepest margin pools within product categories due to arc-quenching complexity and safety certification requirements. Smart grids and automated systems represent the fastest-expanding technology dimension as utilities deploy sensor-rich DC feeders for real-time load balancing. Data centers dominate end-user demand concentration, with government facilities representing a smaller but structurally growing segment driven by federal resilience mandates.
The US Federal Energy Regulatory Commission and Canada's National Energy Board jointly shape interconnection standards for cross-border DC transmission projects, while the US EPA efficiency regulations and Canadian Standards Association certification requirements dictate converter efficiency minimums and electromagnetic compatibility thresholds. State-level renewable portfolio standards in California, New York, and Texas create fragmented but substantial procurement incentives that vendors must navigate. Stakeholders should monitor how evolving IEEE 1547 interconnection standards and emerging UL safety certifications for high-voltage DC residential applications will redraw competitive boundaries between incumbent electrical equipment suppliers and specialized power electronics entrants.
Market Dynamics
AI compute clusters are forcing hyperscale data center operators to abandon traditional AC distribution architectures in favor of native DC microgrids that eliminate conversion losses at the rack level.
Growth Catalysts
- US Inflation Reduction Act tax credits:Clean energy infrastructure incentives accelerate utility-scale DC distribution investments across Texas and Virginia corridors.
- Hyperscale facility construction:California, Texas, and Virginia concentrate data center builds requiring 380V-1500V DC architectures for AI workload support.
- Renewable integration mandates:State-level renewable portfolio standards in California, New York, and Texas create fragmented but substantial procurement pull for DC-coupled solar and storage.
Market Restraints
- Copper and silicon carbide supply concentration:Power semiconductor substrate supply chains concentrate in East Asian foundries, exposing North American converter manufacturers to input volatility.
- IEEE 1547 interconnection delays:Evolving grid-tie standards create regulatory friction for DC feeder deployments, extending project approval timelines.
- AC infrastructure lock-in:Existing transformer-based distribution networks create substitution resistance in industrial retrofit applications.
Strategic Opportunities
- Federal resilience mandates:Government facilities face structurally growing DC microgrid requirements for critical infrastructure hardening.
- Solid-state circuit breaker convergence:Power electronics and arc-quenching technologies merge to enable faster fault isolation in high-voltage DC feeders.
- Canadian cross-border projects:Joint FERC-NEB interconnection standards create white space for utility-scale DC transmission spanning US-Canada corridors.
Industry Challenges
- UL safety certification timelines:High-voltage DC residential applications lack established testing protocols, delaying product commercialization.
- Power electronics talent scarcity:Converter design and grid integration expertise concentrates among a narrow specialist workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America DC Distribution Network Market |
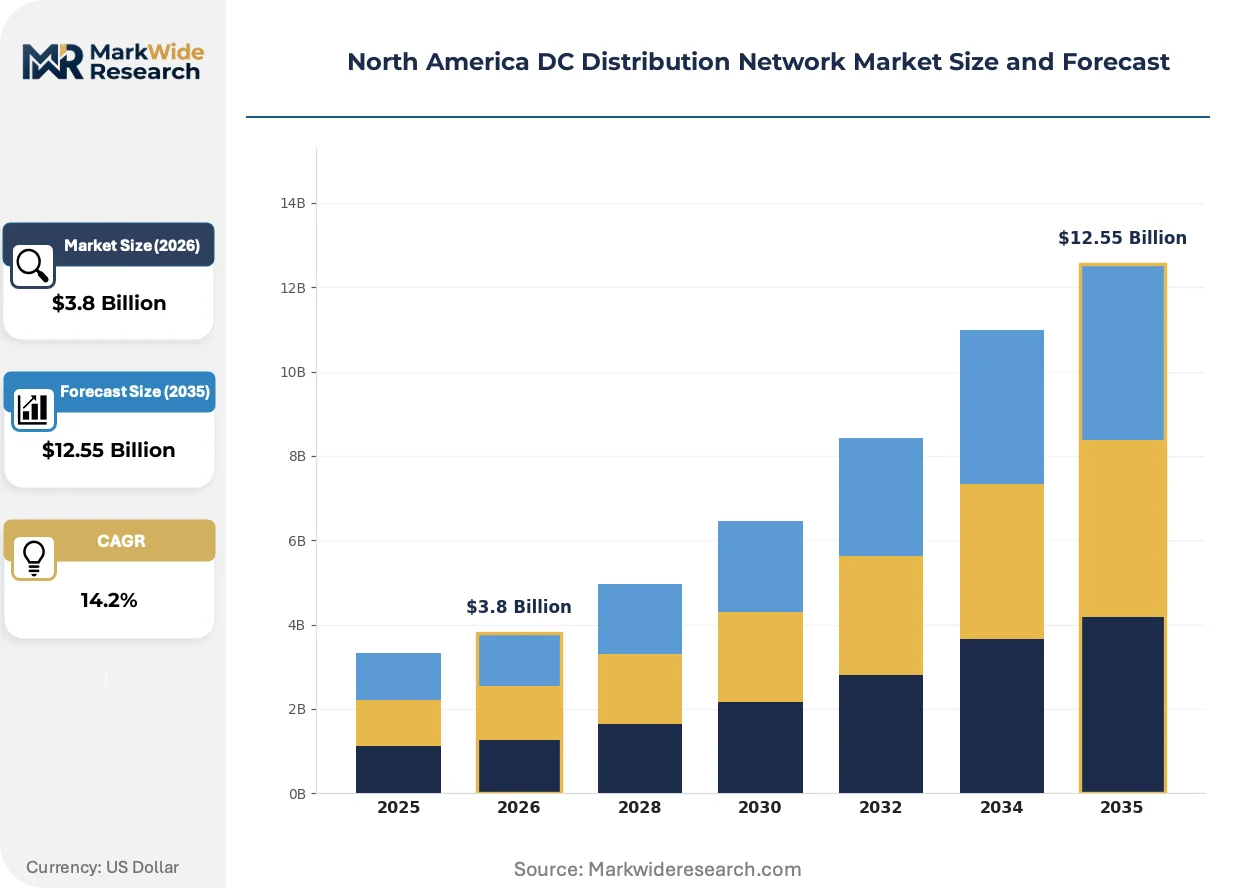
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transformers, Circuit Breakers, Switchgear, Distribution Boards Technology: Smart Grids, Automated Systems, Conventional Grids, Hybrid Solutions End User: Retailers, Data Centers, Manufacturing Plants, Government Facilities Service Type: Installation, Maintenance, Consulting, System Integration |
| Companies Covered | ABB Ltd., Siemens AG, Vertiv Group Corp., Eaton Corporation PLC, Secheron SA, Schneider Electric SE, Delta Electronics, Inc., Mitsubishi Electric Corporation, Alpha Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America DC Distribution Network Market Evolving Landscape
Silicon carbide power semiconductors are compressing converter footprints while solid-state protection devices rewrite arc-fault management protocols across commercial and industrial DC networks.
Wide-bandgap semiconductor technology is expanding into data center power distribution units, replacing silicon IGBTs with silicon carbide MOSFETs that slash switching losses. Hyperscale operators in Northern Virginia and Dallas-Fort Worth are retrofitting facilities at accelerated pace. This transition is expanding into 1500V DC bus architectures that compress copper conductor requirements by thirty percent.
The US EPA efficiency regulations and Canadian Standards Association certification requirements now mandate minimum converter efficiency thresholds and electromagnetic compatibility testing for grid-interactive equipment. Industrial consequence includes forced obsolescence of legacy thyristor-based rectifier systems. Data center switchgear manufacturers face the steepest compliance burden as they race to certify modular DC breaker assemblies.
After-sales service unbundling is fragmenting traditional equipment vendor relationships across the North America DC Distribution Network Market. Colocation operators now contract converter maintenance separately from original hardware procurement, compressing vendor margin pools. This pattern concentrates most visibly in California's Silicon Valley corridor where facility managers prioritize uptime guarantees over bundled service agreements.
North America DC Distribution Network Market Segmentation
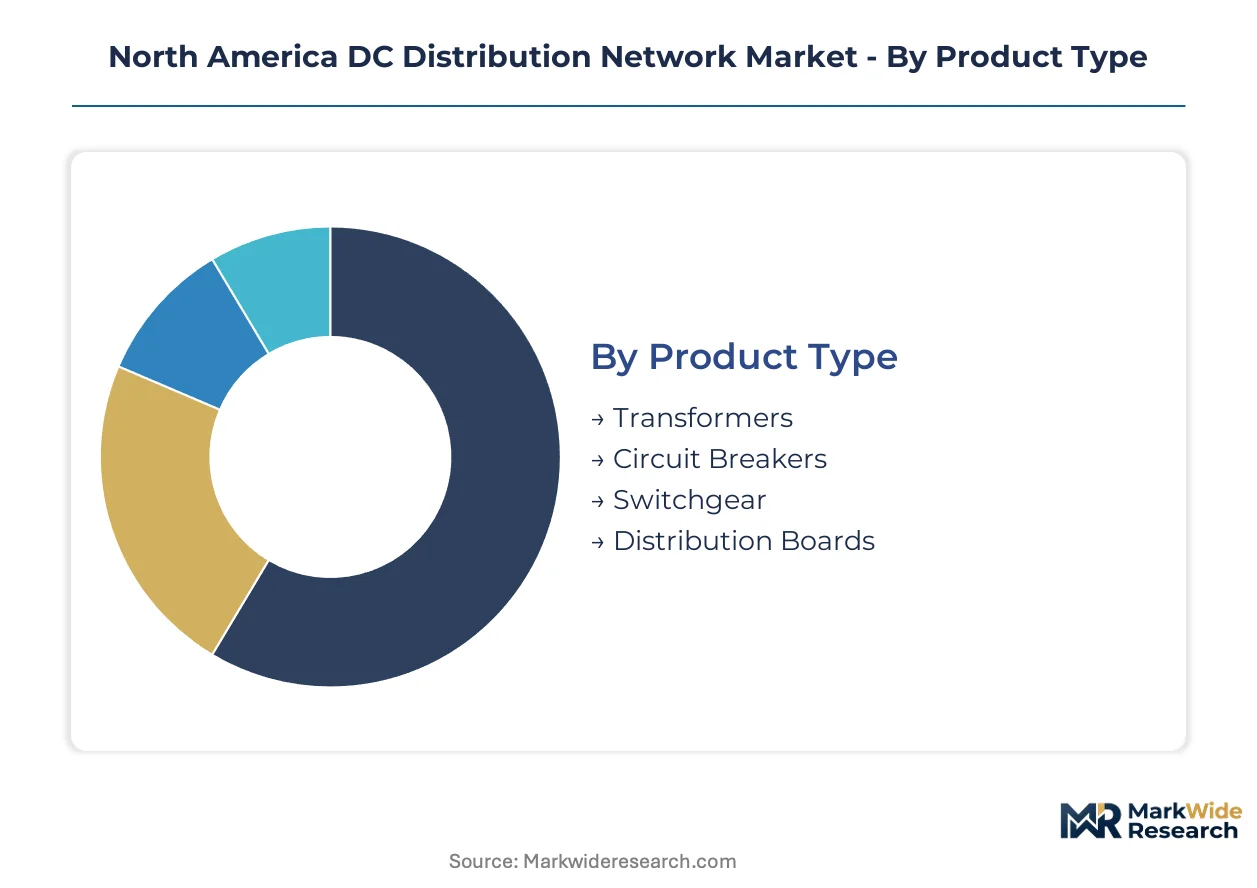
DC distribution architectures fragment across voltage classes, automation tiers, and buyer sophistication levels that dictate procurement patterns. Segmentation reveals where UL certification burdens concentrate and which customer types drive premium pricing for integrated service bundles.
Product Type:
UL 489 and IEEE C37 certification requirements split unevenly across hardware categories, with arc-quenching equipment demanding the most extensive safety validation cycles.
- Circuit Breakers:Solid-state and electromechanical variants handle fault isolation in 380V-1500V DC buses. Hyperscale data centers in Northern Virginia specify these for rack-level protection, with silicon carbide-based designs compressing response times below 10 microseconds.
- Switchgear:Modular DC switchgear assemblies integrate busbars, breakers, and monitoring in factory-tested enclosures. California colocation facilities favor these for rapid deployment, though CSA C22.2 No. 31 certification adds 8-12 weeks to delivery schedules.
- Transformers:DC-DC converter modules replace traditional magnetics in native DC architectures, with efficiency mandates from the US EPA driving obsolescence of thyristor-based rectifiers.
- Distribution Boards:Panel-mounted bus systems distribute power to final circuits in industrial and commercial settings, with Texas manufacturing plants specifying 1000V DC ratings for welding and plating lines.
Leading the category by volume: Circuit Breakers. Growing fastest: Switchgear.
Technology:
Automation intensity correlates directly with customer scale, with hyperscale operators absorbing sensor and control costs that smaller facilities defer.
- Smart Grids:Sensor-rich DC feeders enable real-time load balancing and predictive maintenance through edge computing nodes. Texas utility-scale solar-plus-storage projects deploy these for ramp-rate control and grid-forming inverter coordination.
- Automated Systems:Programmable protection relays and remote-controlled breaker operations reduce manual switching in hazardous environments. Canadian mining operations in Ontario and Quebec specify these for underground DC trolley systems.
- Hybrid Solutions:AC-DC interface equipment bridges legacy infrastructure with native DC zones, with Virginia data centers using these during phased retrofit schedules.
- Conventional Grids:Passive distribution without embedded intelligence persists in cost-sensitive industrial retrofits where downtime tolerance permits manual operations.
Smart Grids command the steepest price premium per feeder mile. Automated Systems are climbing the fastest as labor costs rise.
End User:
Buyer sophistication spans from procurement-driven retailers to engineering-centric data center operators with dedicated power teams.
- Data Centers:Hyperscale and colocation facilities drive native DC microgrid adoption for AI compute clusters, with 380V DC rack architectures eliminating conversion losses. Northern Virginia, Dallas-Fort Worth, and Silicon Valley concentrate demand.
- Government Facilities:Federal resilience mandates under the US Inflation Reduction Act accelerate DC microgrid deployments for critical infrastructure hardening, with defense installations leading procurement.
- Manufacturing Plants:Electrified processes in automotive welding, semiconductor fabrication, and metal plating specify 750V-1500V DC distribution for precision power quality.
- Retailers:Big-box and grocery chains deploy DC microgrids for rooftop solar integration and EV charging hubs, with California's Title 24 building codes driving compliance-driven upgrades.
Data Centers dominate absolute spending. Government Facilities are gaining share fastest on federal procurement timelines.
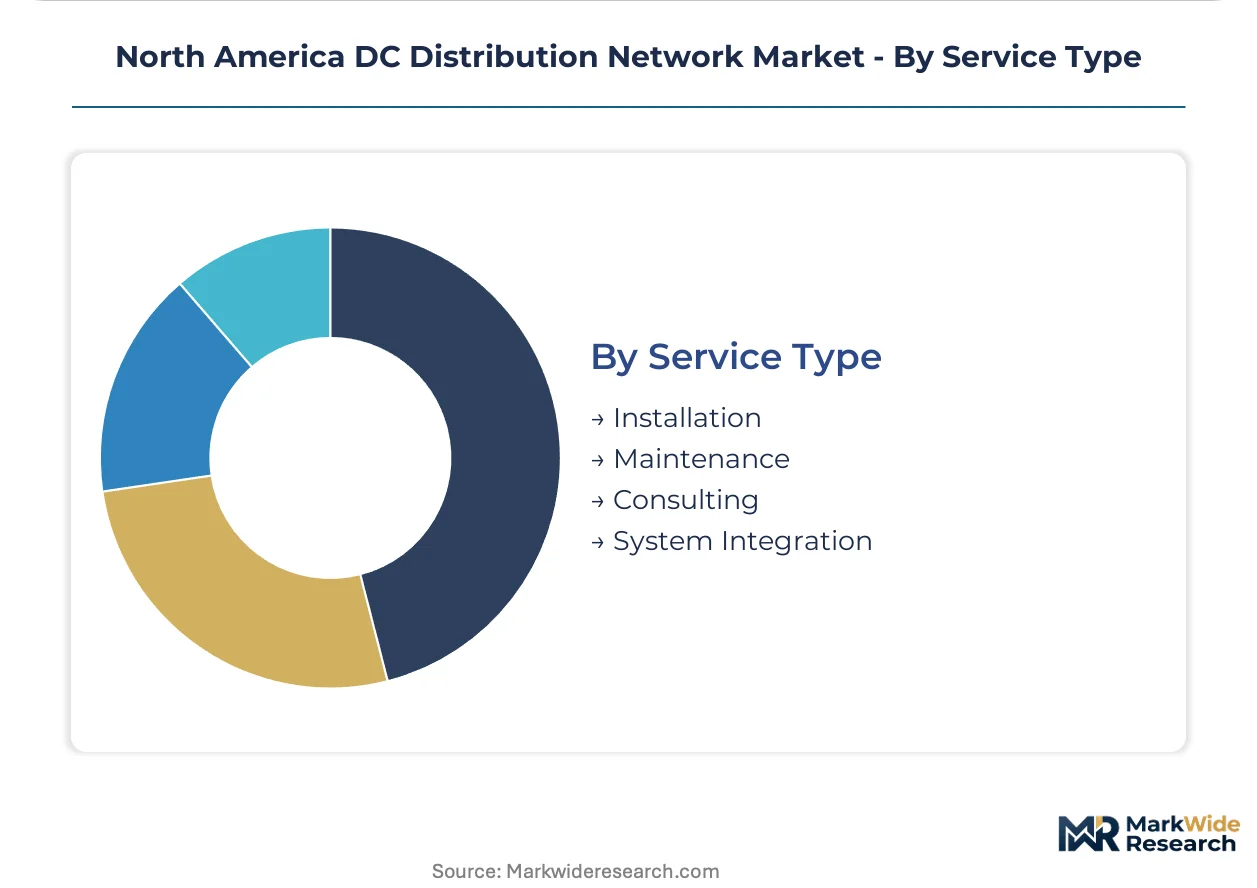
Service Type:
Service bundling unravels as colocation operators unbundle maintenance from original equipment procurement, fragmenting vendor margin pools.
- System Integration:Turnkey design-build services spanning protection coordination studies, commissioning, and utility interconnection. Texas renewable developers favor these for ERCOT registration compliance.
- Maintenance:After-sales service contracts now compete with third-party specialists, with California facility managers prioritizing uptime guarantees over OEM service agreements.
- Installation:Electrical contractor labor for conduit, terminations, and field testing, with union jurisdictions in New York and Illinois adding cost premiums.
- Consulting:Engineering studies for protection settings, arc flash analysis, and IEEE 1547 interconnection documentation.
System Integration captures the largest project value share. Maintenance is expanding most quickly as installed base ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center construction concentrates demand across three distinct North American corridors, with each sub-region exhibiting unique procurement patterns shaped by local energy policy and land availability constraints.
United States
Virginia's Loudoun County and Texas's Dallas-Fort Worth metro anchor hyperscale facility expansion for AI compute loads. FERC interconnection standards govern cross-border DC transmission feasibility studies. Northern Virginia data center operators specify 380V DC rack architectures to eliminate conversion losses at the server level.
Canada
Ontario and Quebec mining operations deploy DC trolley systems for underground electrification with automated protection relays. The National Energy Board coordinates joint standards with FERC for utility-scale DC projects spanning the US-Canada border. Toronto-area colocation facilities favor modular DC switchgear for rapid deployment timelines.
Mexico
Nuevo León's industrial corridor attracts manufacturing plants specifying 750V DC distribution for welding and metal plating precision. Mexican energy regulators align converter efficiency standards with EPA thresholds to maintain export compatibility. Mexico City metro data centers pilot hybrid AC-DC architectures during phased infrastructure retrofits.
North America DC Distribution Network Market Competitive Landscape
Capacity expansion dominates the current landscape as incumbent electrical equipment suppliers race to certify silicon carbide-based converter portfolios for 1500V DC bus applications. The vendor base stratifies across three tiers: diversified industrial conglomerates with installed base advantages, power electronics specialists with semiconductor substrate partnerships, and regional system integrators with utility interconnection expertise. Strategic archetypes include integrated platform providers bundling digital twin software with hardware, and modular component suppliers unbundling after-sales service from original procurement. M&A activity and technology licensing agreements represent the dominant competitive vectors as players seek wide-bandgap semiconductor capabilities.
Among European-headquartered industrial conglomerates, ABB Ltd. and Siemens AG occupy positions exemplifying the integrated platform archetype, leveraging legacy industrial DC system footprints to sustain renewal cycles. Schneider Electric SE represents the modular specialization vector, with its SE suffix indicating a French société européenne structure. These three entities anchor the premium tier through combined hardware-software-service bundling that smaller competitors struggle to replicate.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Vertiv Group Corp. |
| Eaton Corporation PLC |
| Secheron SA |
| Schneider Electric SE |
| Delta Electronics, Inc. |
| Mitsubishi Electric Corporation |
| Alpha Technologies Inc. |
| Others |
Value Network & Pricing Analysis
Silicon carbide MOSFET premium tiers diverge sharply from silicon IGBT commodity offerings across the North America DC Distribution Network Market, with that divergence manifesting in both component pricing power and East Asian foundry allocation priority. UL 1741 certification requirements for grid-interactive converters impose additional cost layers that concentrate margin capture among tier-one electrical equipment suppliers.
Pricing Analysis
Volume concentration in circuit breakers runs against margin depth in solid-state protection modules. Pricing stratifies across UL-certified premium tiers, IEEE 1547-compliant mid-market offerings, and non-certified economy alternatives for captive industrial use. Cost compression in silicon IGBT-based switchgear intensifies as Texas hyperscale operators drive standardization. Government facilities show least price sensitivity due to federal resilience mandate funding.
Supply Chain Analysis
Domestic-content thresholds under the US Inflation Reduction Act reshape sourcing for converter assembly and switchgear fabrication. Silicon carbide substrates draw from Japan, South Korea, and the United States, while copper busbar fabrication and electromechanical breaker components rest on Mexican and Canadian manufacturing. Single-source vulnerability concentrates in wide-bandgap semiconductor foundries. Distribution runs through authorized electrical distributor networks serving contractor and EPC channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America DC Distribution Network Market has become a vertical-integration race, with silicon carbide substrate supply emerging as the decisive upstream lever for converter margin defense.
For Market Incumbents: Extend digital twin platform bundling to lock in renewal cycles at Virginia and Texas hyperscale facilities. Acquire specialized power electronics design houses to narrow the talent gap threatening grid integration timelines. Solid-state circuit breaker convergence represents the most urgent certification battleground. For New Entrants and Emerging Players: Silicon carbide-based 1500V DC protection modules offer the clearest technology-first wedge into California colocation and Canadian mining verticals. Canadian cross-border utility projects present underpenetrated white space given joint FERC-NEB standardization. Lead with rapid CSA certification timelines as the go-to-market angle against incumbent delivery schedules. For Investors and Strategic Acquirers: Re-rating potential sits with power electronics specialists possessing wide-bandgap semiconductor partnerships given silicon carbide supply scarcity. Long-term viability hinges on backward integration into substrate sourcing or captive foundry arrangements. Watch IEEE 1547 revision timelines as the inflection signal for regulatory-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Converter Certification | UL 1741-SA certification unlocks grid-forming revenue in ERCOT and CAISO markets. |
| Digital Twin Platform Integration | Siemens and ABB leverage design-to-operations software to sustain renewal pricing power. |
| Modular Switchgear Manufacturing Scale-Up | Schneider Electric's factory-tested enclosures compress California deployment timelines. |
| Cross-Border Transmission Joint Venture | FERC-NEB coordinated standards enable utility-scale DC projects spanning Ontario-New York corridors. |
| Solid-State Circuit Breaker Development | Secheron and Eaton race to sub-10 microsecond fault isolation for 1500V DC bus protection. |
Research Methodology
Document review covered FERC interconnection filings, EPA efficiency regulation dockets, and IEEE standards documentation, complemented by interviews with data center power engineering directors, utility planning officers at ERCOT and CAISO, EPC contractors specializing in renewable integration, and electrical distributor procurement leads. Secondary validation drew from EIA power plant databases, customs records for power semiconductor imports, and SEC 10-K disclosures from listed electrical equipment suppliers. Bottom-up project pipeline analysis and top-down utility capex forecasting were triangulated against vendor shipment data.
The modeling framework produced volume and value estimates across voltage class, automation tier, and end-user sophistication dimensions throughout the projection horizon. CAGRs were derived from regression analysis of historical utility-scale solar-plus-storage deployment rates and hyperscale data center construction permits. Key inputs included silicon carbide foundry capacity expansion schedules and IEEE 1547 revision implementation timelines.
Several conditions sit outside the modeled scope, including potential tariff modifications affecting Mexican electrical component imports and unannounced EPA efficiency threshold adjustments. Forecasts reflect documented assumptions regarding renewable portfolio standard compliance deadlines and federal tax credit continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
High Voltage Transmission Substation Market
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
Transmission Housing Demand Market
Transmission and Distribution
South America City Gas Distribution Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
Gas Insulated Substation Market
Transmission and Distribution
Transmission and Distribution Fault Detection Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
HVDC Transmission Systems Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Series Compensation System Sales Market