
 Power Over Ethernet (Poe) Solutions Market | 2026-2036
Power Over Ethernet (Poe) Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Power Over Ethernet (Poe) Solutions Market Intelligence
Competitive Dynamics
Distribution through systems integrators and value-added resellers is fragmenting as direct-to-enterprise digital procurement channels gain share. Cisco Systems leverages its installed base of network infrastructure to bundle PoE switches with software-defined management platforms. Broadcom anchors the semiconductor layer through proprietary power management ICs that support IEEE 802.3bt classifications. Microchip Technology specializes in midspan injectors and power-sourcing equipment for retrofit installations where switch replacement proves cost-prohibitive.
Technology and Segmentation
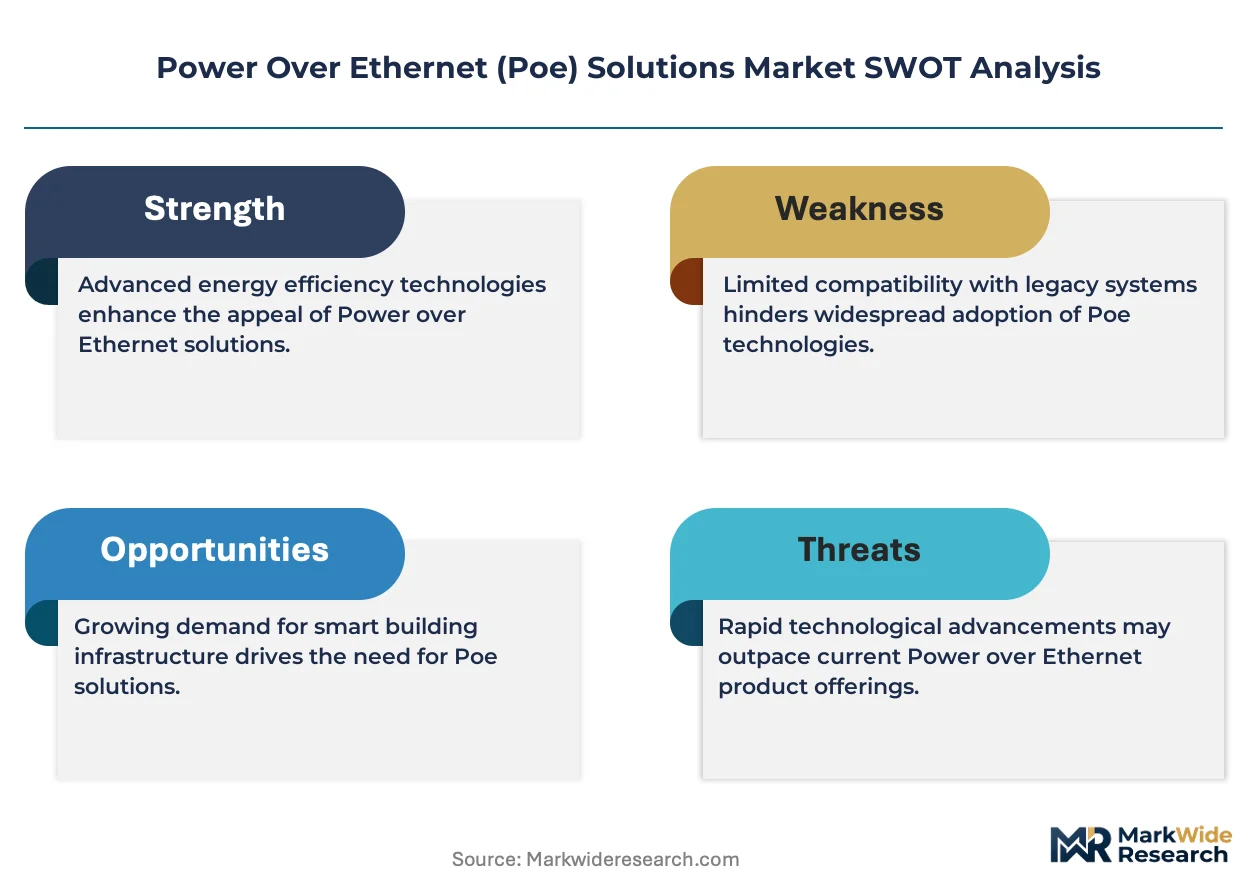
Power over Ethernet solutions deliver DC power alongside data on twisted-pair Ethernet cabling, with IEEE 802.3bt enabling up to 90 watts over four-pair Cat5e or higher-grade infrastructure to drive pan-tilt-zoom cameras, digital signage, and small-cell wireless nodes. PoE Switches capture the dominant value share as edge-network upgrades prioritize integrated power-data delivery over discrete injector deployments. Wireless Access Points represent the fastest-expanding application segment as Wi-Fi 6E and eventual Wi-Fi 7 rollouts demand sustained higher-wattage power budgets per port.
Regulatory Environment
The FCC governs electromagnetic compatibility and conducted emissions for PoE equipment marketed in the United States, while the EU's CE marking framework incorporates Low Voltage Directive and RoHS substance restrictions for power-sourcing hardware. IEEE standards development through the 802.3 working group shapes interoperability mandates that determine product certification paths and market access eligibility. Stakeholders must monitor evolving efficiency regulations from the DOE and EU Ecodesign requirements that will tighten standby-loss thresholds for powered network equipment.
Market Dynamics
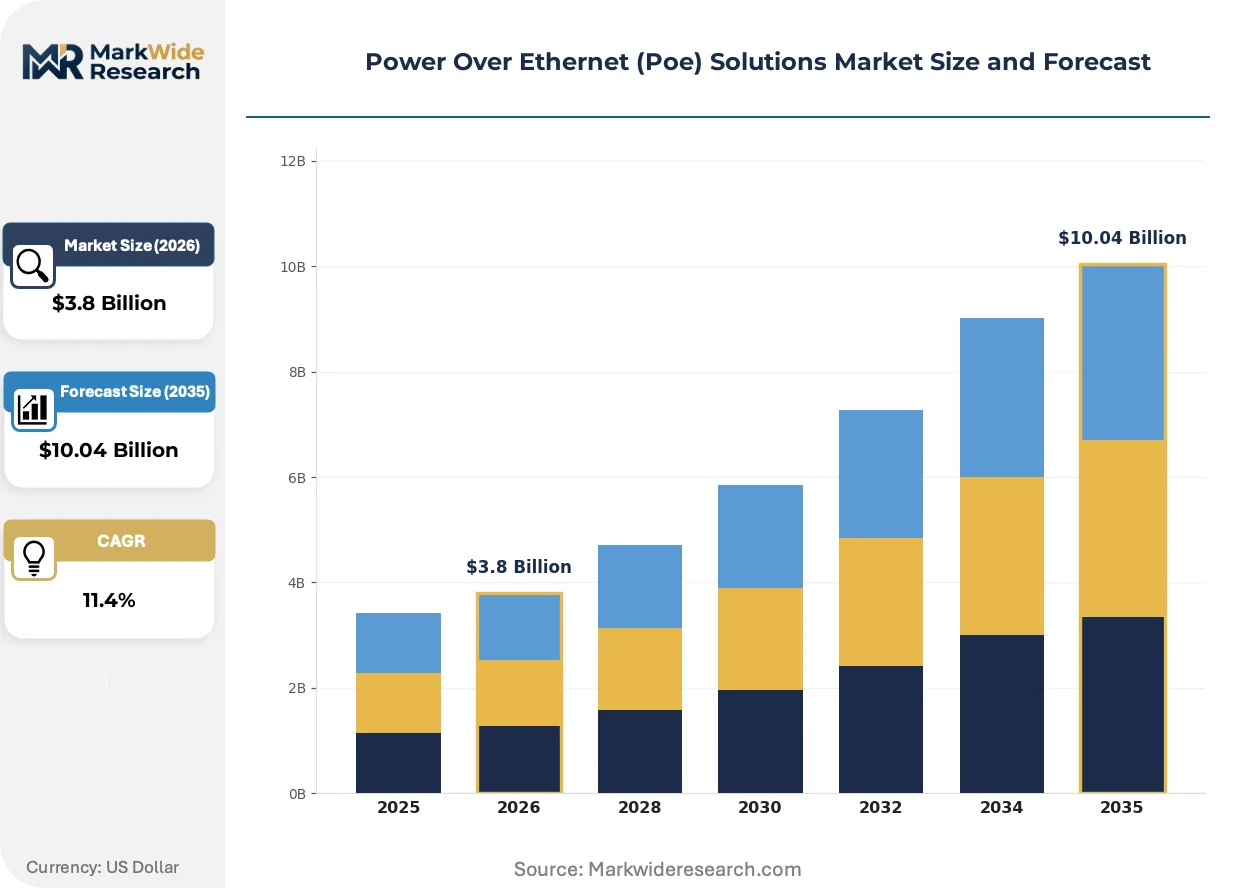
IEEE 802.3bt standardization for 90-watt power delivery is compressing upgrade cycles across commercial real estate, forcing infrastructure owners to recertify cabling and power-sourcing equipment for higher thermal loads and four-pair current distribution.
Growth Catalysts
- Smart building mandates:Municipal energy codes in California, New York, and Germany now require intelligent lighting controls that PoE infrastructure uniquely enables, accelerating retrofit specifications.
- Wi-Fi 6E/7 power budgets:Next-generation wireless access points draw sustained 51-71 watts, exceeding legacy 802.3at limits and mandating 802.3bt-compliant switch infrastructure.
- REACH substance restrictions:EU RoHS and REACH compliance deadlines are phasing out legacy halogenated cabling, creating replacement demand for certified PoE-compatible copper infrastructure.
Market Restraints
- Copper price volatility:Raw material swings in copper cathode markets directly compress margins for cable manufacturers and power-sourcing equipment vendors.
- Taiwan semiconductor concentration:Power management IC fabrication for PoE controllers remains concentrated in Taiwanese foundries, exposing supply continuity to geopolitical friction.
- Heat dissipation physics:90-watt delivery over bundled Cat6A cables creates thermal derating constraints that limit port density in legacy conduit installations.
Strategic Opportunities
- India smart city infrastructure:The country's urban renewal programs under the Smart Cities Mission represent underpenetrated demand for converged power-data networks in municipal buildings.
- Healthcare IoT convergence:Patient monitoring, asset tracking, and clinical environmental controls are converging on single PoE infrastructure, displacing separate electrical and data installations.
- US IRA efficiency incentives:Commercial building energy improvement tax deductions under the Inflation Reduction Act subsidize PoE LED retrofits that cut HVAC loads.
Industry Challenges
- Field technician certification gaps:Shortage of installers qualified to test four-pair power delivery and diagnose thermal performance in bundled cable runs.
- Legacy analog device integration:Interoperability friction between new PoE endpoints and existing BAS, fire safety, and security systems requiring protocol translation gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Over Ethernet (Poe) Solutions Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poe Switches, Poe Injectors, Poe Splitters, Poe Extenders, Poe Midspans Technology: Poe, Poe Plus, Poe Ultra, Poe High Power, Passive Poe Application: IP Cameras, VoIP Phones, Wireless Access Points, Network Routers, LED Lighting End User: Telecommunication Providers, Data Centers, Commercial Enterprises, Government Agencies |
| Companies Covered | Cisco Systems, Broadcom, Microchip Technology, STMicroelectronics, Texas Instruments, Analog Devices, CommScope Holding, Hewlett Packard Enterprise, Silicon Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Over Ethernet (Poe) Solutions Market Strategic Shifts & Innovations
Power architecture is shifting from discrete electrical and data infrastructures toward unified cabling systems that collapse installation labor and material costs while enabling granular energy monitoring.
Autonomous power negotiation chips are digitizing endpoint detection and classification. These ICs enable real-time power budget reallocation across switch ports. Healthcare facilities and data centers are adopting them fastest. The technology is digitizing how facility managers provision capacity, replacing manual spreadsheet planning with automated load balancing.
The EU Ecodesign Directive is tightening standby-loss thresholds for network equipment sold in member states. Manufacturers must redesign power-sourcing equipment to meet sub-1-watt idle consumption limits. PoE switch vendors serving Germany, France, and the Netherlands are accelerating GaN-based power supply designs to maintain market access.
Enterprise buyers are consolidating vendor relationships for network infrastructure. Procurement teams now specify single-source accountability for switches, cabling, and endpoint power rather than fragmenting across electrical contractors and IT integrators. This pattern is most pronounced in US commercial real estate and German industrial facilities, where total cost of ownership models dominate capital planning.
Power Over Ethernet (Poe) Solutions Market Segmentation
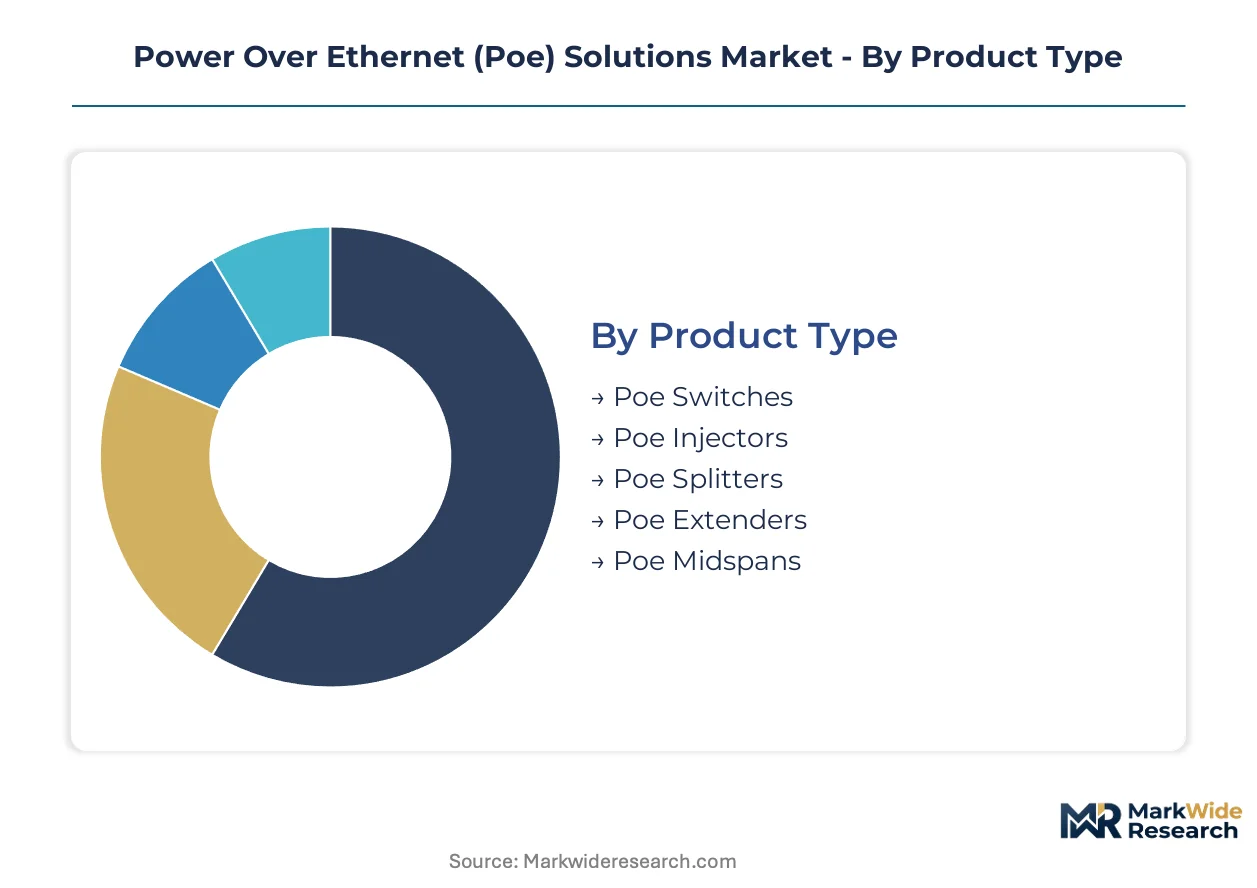
Segmentation in the Power over Ethernet market reveals distinct procurement rhythms across hardware categories, with infrastructure equipment commanding longer replacement cycles than endpoint accessories. Understanding these temporal patterns helps vendors align inventory and certification investments with actual refresh demand.
Product Type:
Replacement cycles vary dramatically across hardware tiers, with core infrastructure spanning 5-7 years while accessories turn over every 2-3 years as standards evolve.
- Poe Switches:Integrated power-sourcing equipment combining data switching with IEEE-compliant power delivery across 4-pair copper infrastructure. Enterprise IT refresh programs in the United States and Germany concentrate demand for 802.3bt-capable models as Wi-Fi 6E rollouts strain legacy power budgets.
- Poe Injectors:Standalone midspan devices that retrofit power onto existing Ethernet runs without switch replacement. Commercial real estate retrofits in aging urban buildings drive steady procurement where full infrastructure overhaul proves cost-prohibitive.
- Poe Splitters:Devices separating data and power for non-PoE endpoints. Common in legacy device integration scenarios.
- Poe Extenders:Signal amplification hardware extending power-data reach beyond standard 100-meter limits. Deployed in campus and industrial environments.
- Poe Midspans:Rack-mounted power insertion equipment for high-density installations. Favored by data center operators scaling port counts rapidly.
Poe Switches anchor the volume base while Poe Injectors gain share at the steepest rate as retrofit economics favor incremental upgrades.
Technology:
Cost tiers stratify sharply across power standards, with premium 90-watt solutions commanding 3-4x the unit economics of passive alternatives.
- Poe Ultra:IEEE 802.3bt implementations delivering up to 90 watts over four-pair cabling for pan-tilt-zoom cameras and digital signage. German industrial facilities and US healthcare campuses lead adoption as single-cable installations displace separate electrical runs.
- Poe Plus:802.3at standard providing 30 watts, now the baseline for enterprise wireless access points. Volume concentrates in China and the United States where Wi-Fi 5 infrastructure still dominates installed base.
- Poe:Original 802.3af standard limited to 15.4 watts. Remains viable for VoIP phones and basic sensors.
- Poe High Power:Proprietary implementations bridging gaps between standards. Common in specialized industrial applications.
- Passive Poe:Non-standard fixed-voltage injection without negotiation protocols. Lowest-cost option for closed-system deployments.
Poe Plus maintains the largest installed base while Poe Ultra climbs the fastest as endpoint power requirements escalate.
Application:
Customer maturity varies across use cases, with surveillance networks representing established demand and lighting controls still proving ROI models.
- Wireless Access Points:Wi-Fi 6E and emerging Wi-Fi 7 infrastructure requiring sustained 51-71 watt delivery. Campus networks in the United States and Chinese smart city projects drive the steepest procurement acceleration.
- IP Cameras:Surveillance endpoints spanning fixed domes to high-power pan-tilt-zoom units. Government security mandates in Germany and commercial loss-prevention programs sustain steady replacement demand.
- VoIP Phones:Established enterprise telephony with modest power requirements. Replacement cycles lengthen as UCaaS migration slows on-premise refresh.
- Network Routers:Edge routing equipment in distributed enterprise topologies. Demand correlates with branch expansion activity.
- LED Lighting:Intelligent fixture control enabling granular dimming and occupancy response. California Title 24 and New York Local Law 88 compliance deadlines compress decision timelines.
IP Cameras generate the most consistent procurement volume while LED Lighting expands most quickly as building codes mandate intelligent controls.
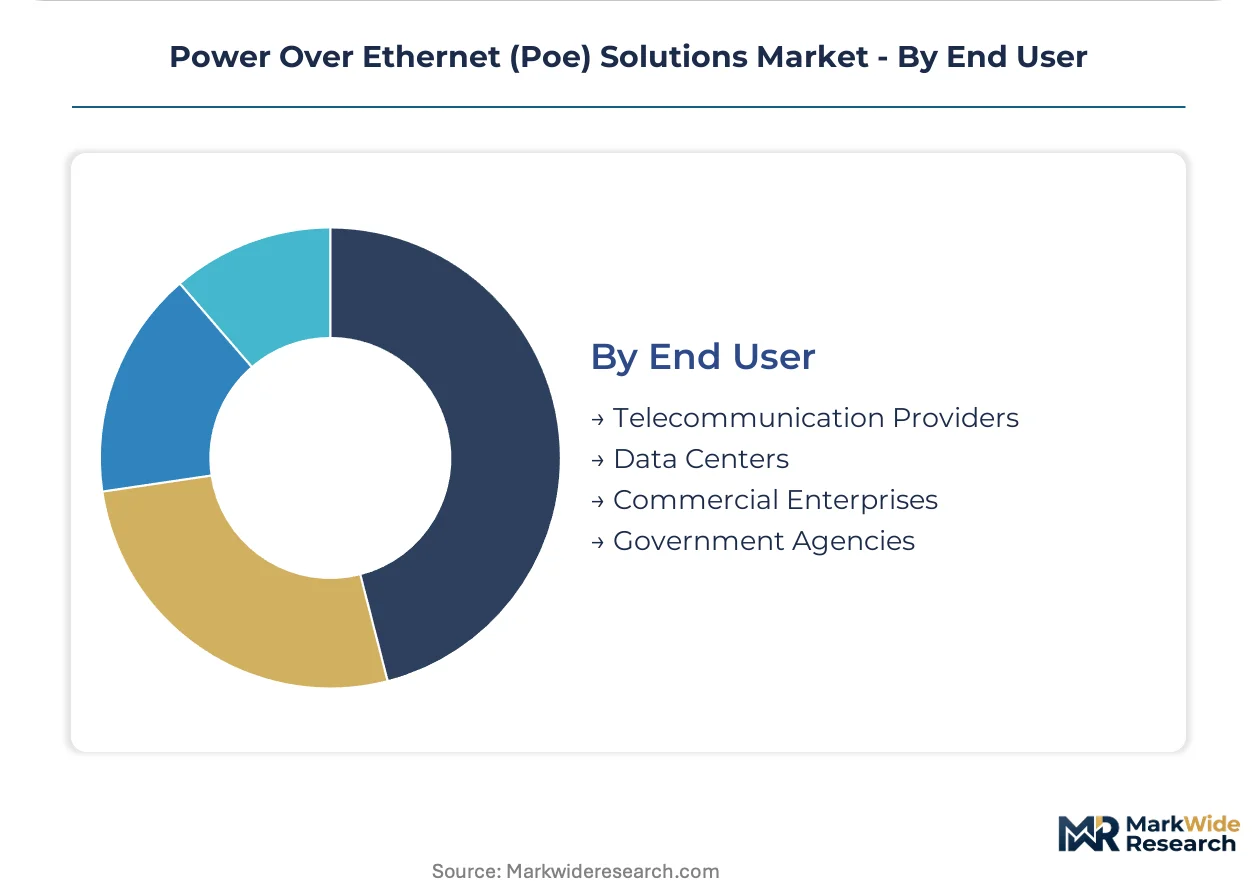
End User:
Procurement sophistication diverges across buyer types, with hyperscale operators driving technical specifications that cascade to smaller enterprises.
- Data Centers:Hyperscale and colocation facilities demanding highest port densities with autonomous power management. Northern Virginia, Frankfurt, and Singapore clusters set thermal and efficiency benchmarks that equipment vendors must meet.
- Commercial Enterprises:Office, retail, and hospitality portfolios balancing first-cost constraints against operational flexibility. US commercial real estate investment trusts increasingly specify single-vendor accountability for infrastructure.
- Telecommunication Providers:Carrier-grade deployments for small-cell backhaul and customer premises equipment. 5G densification programs in China and Germany shape volume timing.
- Government Agencies:Municipal, federal, and defense installations with extended procurement cycles and stringent certification requirements. Cybersecurity supply chain vetting adds qualification friction.
Data Centers anchor capital deployment scale while Commercial Enterprises drive the broadest geographic penetration as smart building specifications standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and the United States where IEEE 802.3bt certification requirements create premium capture for compliant equipment, while Chinese manufacturers compete on volume economics for PoE Plus infrastructure.
United States
Commercial real estate investment trusts in Northern Virginia and Dallas-Fort Worth drive 802.3bt switch procurement for smart building retrofits. The Inflation Reduction Act's commercial building energy improvement tax deductions subsidize PoE LED installations that reduce HVAC loads. Cisco Systems anchors the Bay Area cluster where software-defined management platforms bundle with power-sourcing hardware.
Germany
Industrial facilities in Bavaria and Baden-Württemberg deploy 90-watt PoE Ultra for machine vision and environmental monitoring on converged IT-OT networks. The EU Ecodesign Directive mandates sub-1-watt standby consumption for network equipment sold in member states. Frankfurt's data center corridor sets thermal efficiency benchmarks that equipment vendors must meet for hyperscale qualification.
China
Smart city infrastructure projects in Shenzhen and Hangzhou scale PoE port density for surveillance networks and municipal Wi-Fi backhaul. MIIT certification requirements govern electromagnetic compatibility for power-sourcing equipment marketed domestically. The Yangtze River Delta manufacturing cluster produces midspan injectors and power management ICs for regional and export markets.
India
The Smart Cities Mission creates procurement demand for converged power-data networks in municipal buildings across Maharashtra and Karnataka. Bureau of Indian Standards certification creates compliance friction for imported power-sourcing equipment. Bengaluru's technology corridor hosts systems integrators specifying PoE infrastructure for commercial office developments.
Japan
Tokyo's dense commercial districts prioritize space-efficient single-cable installations for digital signage and security endpoints. METI efficiency regulations shape standby-loss thresholds for network equipment sold in the domestic market. Osaka-based manufacturers specialize in compact midspan injectors for retrofit scenarios where switch replacement is impractical.
Power Over Ethernet (Poe) Solutions Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying power management semiconductors and discrete insertion hardware. The market structures around three distinct tiers: network infrastructure vendors bundling switches with software platforms, semiconductor firms anchoring the power delivery layer through proprietary ICs, and midspan specialists serving retrofit economics where full infrastructure replacement is cost-prohibitive. Dominant competitive moves include strategic partnerships between switch vendors and cabling manufacturers, plus portfolio diversification into autonomous power negotiation chips that enable real-time load balancing.
Within the platform integrator tier, Cisco Systems and Hewlett Packard Enterprise exemplify network infrastructure vendors leveraging installed base relationships. Among semiconductor specialists, Broadcom and Texas Instruments occupy positions supplying power management ICs that support IEEE 802.3bt classifications. Microchip Technology represents the retrofit-focused archetype, anchoring midspan injector supply for commercial real estate scenarios where legacy switch preservation drives procurement decisions.
| Leading Market Players |
|---|
| Cisco Systems |
| Broadcom |
| Microchip Technology |
| STMicroelectronics |
| Texas Instruments |
| Analog Devices |
| CommScope Holding |
| Hewlett Packard Enterprise |
| Silicon Laboratories |
| Others |
Cost & Logistics Intelligence
Taiwanese foundry concentration for power management ICs feeds directly into margin capture by semiconductor specialists, while cabling manufacturers absorb copper volatility through contract structures that shift risk downstream to systems integrators.
Pricing Analysis
Configured-to-order pricing for 802.3bt-certified switches commands a 40-60% premium over standard 802.3at equivalents, with differentiation driven by thermal certification grade and software-defined management bundling. Pricing pressure stems from Chinese manufacturers scaling PoE Plus volume production for Wi-Fi 5 infrastructure replacement. Small and mid-sized commercial real estate buyers exhibit highest price sensitivity, prioritizing midspan injector economics over full switch replacement, while data center operators show lowest sensitivity as efficiency metrics dominate total cost of ownership calculations.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for power-sourcing equipment vendors serving North American enterprise accounts. Manufacturing concentrates in China, Taiwan, and Vietnam, with power management IC fabrication anchored in Taiwanese foundries and final assembly distributed across Southeast Asian electronics clusters. Raw material dependencies span copper cathode for cabling, gallium nitride substrates for next-generation power supplies, and epoxy resins for PCB substrates. Distribution runs through systems integrators and value-added resellers, though direct-to-enterprise digital procurement channels are gaining share in repeat-buy scenarios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as IEEE 802.3bt standardization forces infrastructure recertification across commercial real estate portfolios, compressing replacement timelines that historically spanned seven-to-ten years into five-to-seven year windows.
For Market Incumbents: Insulate switch port margins by deepening captive supply of autonomous power negotiation chips that enable real-time load balancing, while accelerating GaN-based power supply designs to meet EU Ecodesign sub-1-watt standby thresholds before compliance deadlines eliminate non-compliant products from German and French markets. For New Entrants and Emerging Players: Pursue midspan injector specialization for aging urban commercial real estate where full infrastructure overhaul proves cost-prohibitive, targeting California and New York municipal buildings facing Title 24 and Local Law 88 intelligent lighting mandates, with go-to-market positioning around rapid deployment timelines that minimize tenant disruption. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed midspan specialists possessing established relationships with commercial real estate investment trusts but lacking 802.3bt certification capabilities. Long-term viability hinges on convergence of IT-OT networks in industrial facilities, with the inflection signal to monitor being German automotive OEM specifications for single-cable machine vision installations.| Strategic Initiative | Industry Significance |
|---|---|
| 802.3bt Certification Investment | Unlocks 90-watt delivery for pan-tilt-zoom cameras and digital signage in German industrial facilities. |
| GaN Power Supply Transition | Enables compliance with EU Ecodesign standby-loss thresholds for network equipment sold in member states. |
| Autonomous Power Negotiation Chip Development | Digitizes real-time power budget reallocation across switch ports for healthcare and data center verticals. |
| Direct-to-Enterprise Digital Channel Buildout | Captures repeat procurement from US commercial real estate investment trusts consolidating vendor relationships. |
| India Smart City Systems Integration Partnership | Positions for Bureau of Indian Standards-compliant deployments across Maharashtra and Karnataka municipal infrastructure. |
Research Approach
A spread of perspectives from network infrastructure procurement officers, commercial real estate facility managers, semiconductor product marketing directors, and systems integration specialists converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation against IEEE standards documentation, FCC equipment authorization databases, EU Ecodesign implementing measures, and hyperscaler capital expenditure disclosures. Bottom-up triangulation across port shipment estimates and top-down reconciliation against enterprise IT spending patterns anchored the analytical framework.
Demand-supply balance modeling across the projection horizon incorporated segmentation by power standard tier, application endpoint type, and regional regulatory cluster. CAGRs were derived from install-base replacement dynamics and net-new deployment intensity across smart building mandates. Industry-specific forecast inputs included Wi-Fi 6E/7 rollout schedules, municipal energy code compliance deadlines, and copper price trajectory assumptions from futures market data.
Macroeconomic conditions sit as an overlay; deviation in commercial construction spending, semiconductor foundry utilization rates, or cross-border tariff regimes would shift the trajectory. Forecasts embed assumptions regarding IEEE standards evolution and efficiency regulation tightening that continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
5G CPE Device Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Managed Switches Market
Network Technology
Fiber to the Premises Market
Network Technology
Global Self-Organizing Network Market
Network Technology
Network Telemetry Market
Network Technology
CPE Router Market
Network Technology
Malaysia Wireless Router Market
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
Router and Switch Market
Network Technology
Network Devices Market
Network Technology
Dark Fiber Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
Global Network Management Market