
 Europe Data Center Colocation Market | 2026-2036
Europe Data Center Colocation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Center Colocation Market Intelligence
The EU Green Deal is expanding requirements for energy-efficient data center operations across member states. Data4 Group leverages its hyperscale campus strategy to anchor capacity in Paris and other key metros. Equinix sustains interconnection density through its platform of carrier-neutral facilities. Vantage Data Centers specializes in wholesale deployments with scalable power architectures.
Europe data center colocation provides third-party leased space, power, cooling, and physical security for IT infrastructure, typically delivering redundant electrical systems with uptime tiers from 99.671% to 99.995% availability. The primary purpose is to eliminate capital expenditure on facility construction while maintaining operational control over servers and storage. Wholesale colocation dominates margin pools as cloud service providers and hyperscalers commit to multi-megawatt deployments with long-term contracts. Retail colocation competes on proximity to enterprise clusters and network exchange density. Managed colocation is accelerating as buyers seek operational offload without full cloud migration.
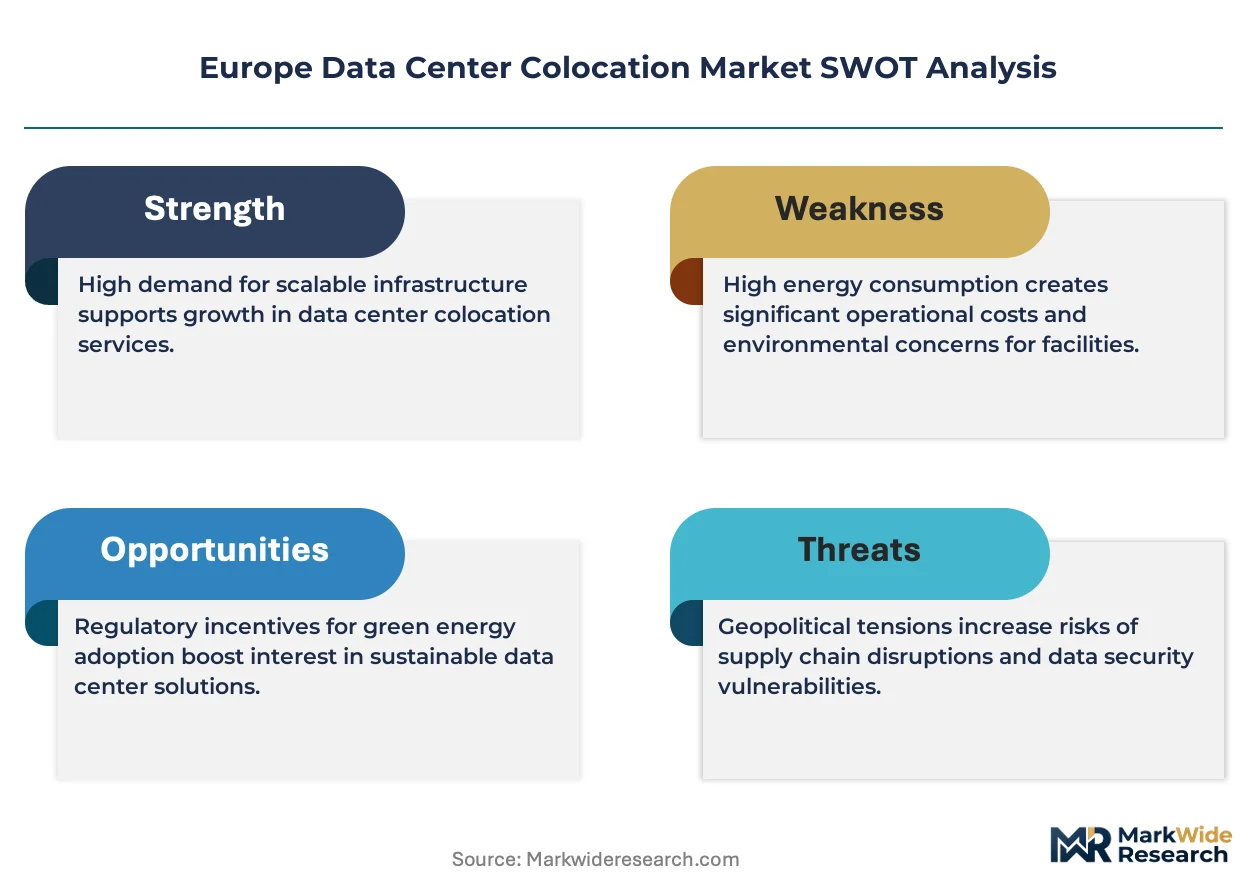
EMA efficiency guidelines, the EU Green Deal's carbon reduction frameworks, and national building codes in Germany and France shape facility design standards and energy sourcing requirements across the region. CSRD disclosure mandates are forcing operators to document Scope 1, 2, and 3 emissions with granular facility-level reporting. Stakeholders must monitor how evolving EU AI Act infrastructure requirements and national permitting timelines interact with power grid constraints in key deployment zones.
Market Dynamics
Power grid saturation in Frankfurt, Amsterdam, and London is forcing operators into secondary metros where land and substation capacity remain available. The EU Green Deal's carbon reduction mandates are compressing deployment timelines while hyperscalers pre-commit multi-megawatt blocks years ahead of construction completion.
Growth Catalysts
- EMA efficiency guidelines:These standards mandate power usage effectiveness thresholds that accelerate facility modernization across member states. Operators retrofit existing stock to avoid regulatory penalties.
- Hyperscale cloud expansion:Cloud service providers pre-lease entire data halls before concrete pours, de-risking developer financing and compressing payback periods.
- CSRD disclosure mandates:Scope 1, 2, and 3 emissions reporting requirements force enterprises to outsource carbon-intensive infrastructure to specialized operators with verified renewable energy sourcing.
Market Restraints
- Grid interconnection queues:Transmission operators in Germany and the Netherlands face multi-year backlogs for new substation connections, delaying facility energization regardless of construction status.
- Liquid cooling infrastructure capex:High-density GPU deployments require chilled water loops and heat rejection systems that add 15-25% to mechanical plant costs versus traditional air-cooled designs.
- Permitting fragmentation:National building codes and local zoning authorities in France and Italy impose inconsistent environmental impact review timelines that extend project development cycles.
Strategic Opportunities
- Nordic renewable energy surplus:Norway and Sweden offer hydroelectric and wind power at sub-market rates, attracting carbon-conscious hyperscalers seeking zero-carbon compute.
- Edge computing integration:5G network densification creates demand for micro-data centers in secondary cities, extending colocation footprints beyond traditional hub markets.
- Waste heat recovery mandates:Danish and Finnish regulations require data centers to supply district heating systems, opening revenue streams from thermal energy sales.
Industry Challenges
- Critical facilities engineering talent:Specialized expertise in high-voltage electrical distribution and mission-critical cooling design concentrates among a narrow contractor base, inflating construction labor costs.
- Legacy facility retrofit complexity:Older facilities built for 5-8 kilowatts per rack lack structural capacity and cooling density for AI training clusters, forcing expensive structural reinforcement or write-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Center Colocation Market |
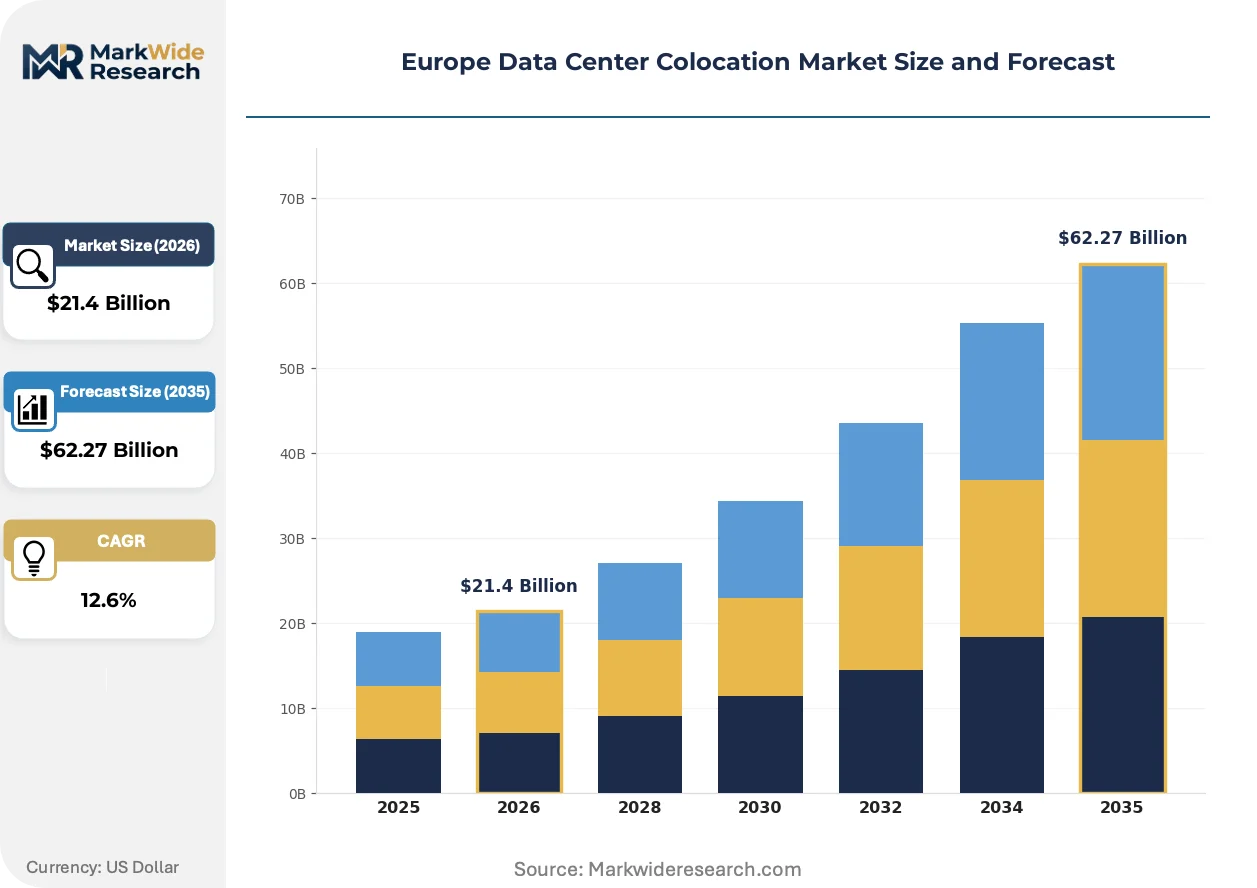
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $62.27 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Retail Colocation, Wholesale Colocation, Managed Colocation, Interconnection Services End User: SMBs, Enterprises, Government, Cloud Service Providers Technology: Hybrid Cloud, Dedicated Hosting, Bare Metal Servers, Virtual Private Cloud Capacity: Small Scale, Medium Scale, Large Scale, Hyper Scale |
| Companies Covered | Data4 Group, EdgeConneX, Digital Realty, Colt Data Centre Services, Global Switch, Equinix, Vantage Data Centers, Interxion, NTT Global Data Centers, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Center Colocation Market Strategic Shifts & Innovations
Operational technology is merging with energy management systems as operators pursue simultaneous uptime guarantees and carbon intensity targets. Three developments are compressing competitive differentiation windows across the European footprint.
Liquid immersion cooling is converging with high-performance computing deployments to manage thermal loads exceeding 50 kilowatts per rack. Hyperscalers piloting AI training infrastructure in Amsterdam and Frankfurt are adopting dielectric fluid baths that eliminate mechanical refrigeration. This convergence is compressing power usage effectiveness ratios below 1.1, redefining facility efficiency benchmarks.
CSRD mandates now require granular Scope 3 emissions disclosure from listed companies and their supply chains. Facility operators must document embodied carbon in construction materials and renewable energy certificate provenance. Wholesale colocation contracts in Germany and France increasingly specify hourly matching of consumption with zero-carbon generation rather than annual averages.
Enterprise procurement teams are consolidating vendor relationships from multi-site retail contracts to single wholesale agreements with operational control retained. Financial services and pharmaceutical buyers in the Netherlands and Switzerland are abandoning fragmented colocation portfolios for campus-scale deployments. This concentration is visible in contract structures that prioritize long-term capacity reservations over short-term price optimization.
Europe Data Center Colocation Market Segmentation
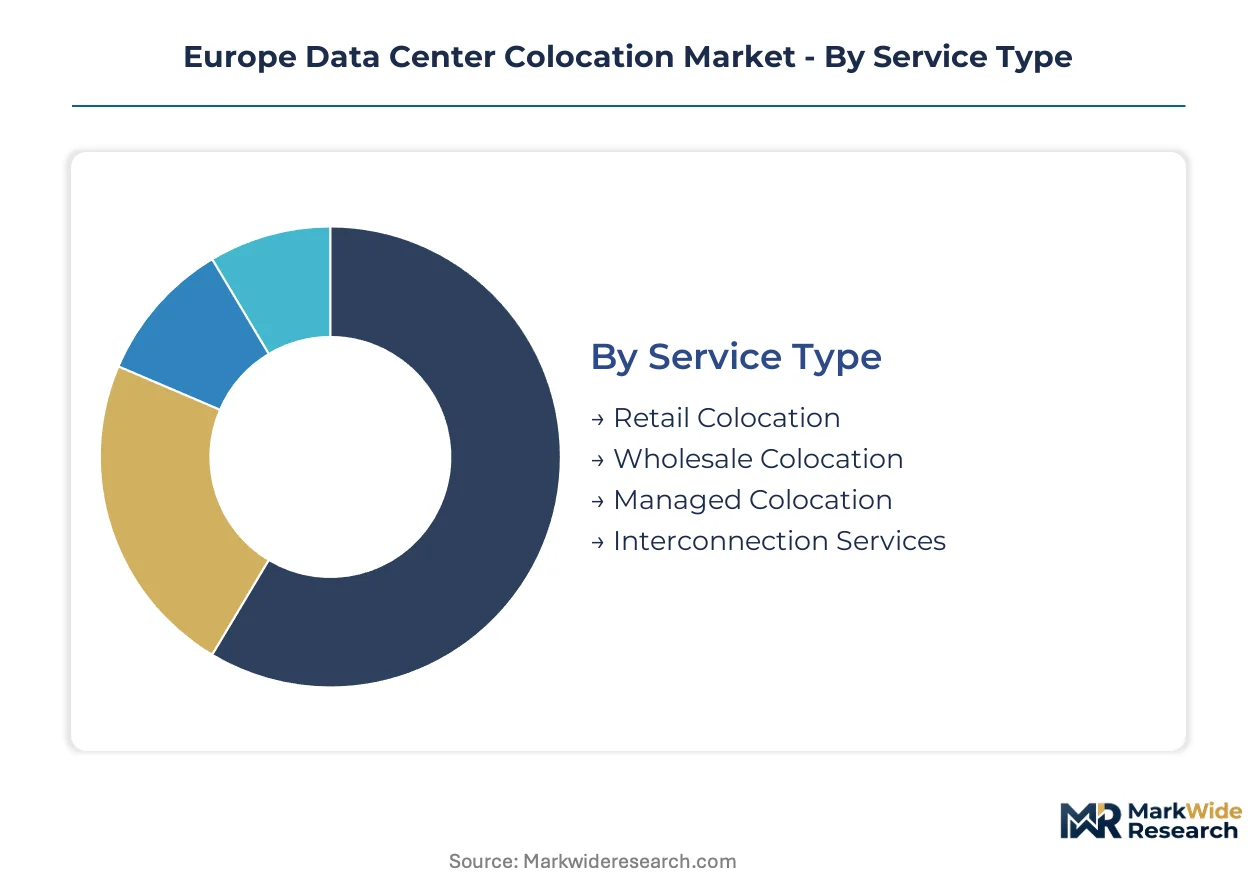
Segmentation reveals how colocation buyers trade off control, capital efficiency, and operational flexibility across deployment scales. Each axis—service model, end-user profile, technology stack, and facility capacity—carries distinct margin structures and regulatory exposure across European jurisdictions.
Service Type:
Technical specifications around power density, cross-connect availability, and operational responsibility define competitive positioning within each service tier.
- Wholesale Colocation:Entire data halls or buildings leased to single tenants with tenant-controlled fit-out and dedicated substations. Cloud service providers in Frankfurt and Amsterdam pre-commit multi-megawatt blocks years ahead of energization to secure scarce grid capacity.
- Retail Colocation:Individual rack or cage deployments with shared mechanical infrastructure and standardized SLAs. Financial services firms in London and Zurich concentrate here for proximity to network exchanges and low-latency connectivity.
- Managed Colocation:Operational offload including remote hands, hardware maintenance, and monitoring layered atop physical space. German and French enterprises adopt this to satisfy CSRD reporting burdens without full cloud migration.
- Interconnection Services:Cross-connects and peering fabrics enabling direct traffic exchange between networks. Neutral exchange density in Paris and Amsterdam drives carrier participation and enterprise demand.
Wholesale colocation leads on scale; managed colocation leads on momentum.
End User:
Procurement sophistication and contract duration vary sharply across buyer categories, reshaping sales motion and facility design requirements.
- Cloud Service Providers:Hyperscalers negotiating 10-15 year leases with renewable energy guarantees and liquid cooling readiness clauses. Their pre-leasing activity in Frankfurt de-risks developer financing for entire campus phases.
- Enterprises:Mid-market and large corporations seeking operational control without facility ownership. Pharmaceutical and automotive clusters in Germany and Switzerland drive demand for certified, compliant environments.
- SMBs:Smaller deployments prioritizing proximity over scale, often consolidating from fragmented server closets. Price sensitivity pushes these buyers toward secondary metros with available retail capacity.
- Government:Sovereign cloud and classified workloads with national security-driven data residency requirements. French and German public sector procurement increasingly mandates EU-operated facilities with local staff.
Cloud service providers anchor volume; government verticals are expanding most quickly amid sovereignty mandates.
Technology:
Infrastructure abstraction layers determine tenant control depth, workload portability, and integration complexity with existing enterprise systems.
- Hybrid Cloud:Interoperability frameworks connecting on-premises, colocated, and public cloud resources. German manufacturers leverage this for production systems requiring sub-10 millisecond latency to factory floors.
- Bare Metal Servers:Single-tenant physical hardware without virtualization overhead. AI training workloads in Amsterdam and London concentrate here for direct GPU access and deterministic performance.
- Dedicated Hosting:Managed physical infrastructure with provider-administered operating systems and middleware. French mid-market enterprises favor this for legacy application migration without re-architecture.
- Virtual Private Cloud:Logically isolated network segments atop shared compute pools. Scalable burst capacity appeals to seasonal retail and media workloads across Nordic facilities.
Hybrid cloud dominates current deployment value; bare metal servers show steepest expansion trajectory with AI infrastructure buildouts.
Capacity:
Power provisioning thresholds segment facilities by land intensity, substation requirements, and construction capital deployment profiles.
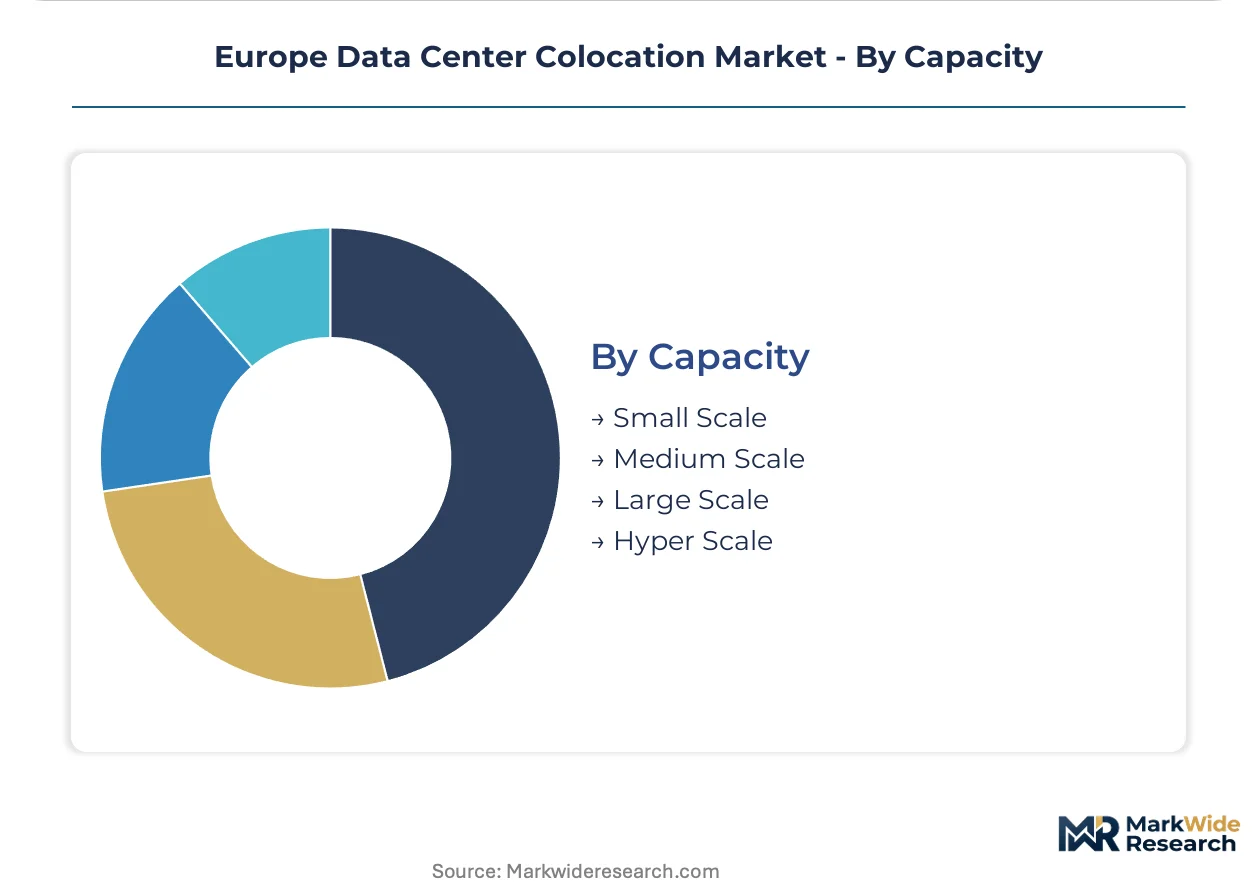
- Hyper Scale:Campuses exceeding 100 megawatts with dedicated grid infrastructure and on-site substations. Norway and Sweden attract these deployments through hydroelectric surplus and sub-market power pricing.
- Large Scale:Facilities between 20-100 megawatts serving regional cloud nodes or enterprise consolidation. Grid interconnection queues in Germany and the Netherlands constrain new large-scale development timelines.
- Medium Scale:5-20 megawatt deployments in secondary metros where land and power remain available. Italian and Spanish markets see accelerating medium-scale investment as primary hubs saturate.
- Small Scale:Sub-5 megawatt edge facilities supporting 5G densification and latency-sensitive applications. Micro-data centers in secondary cities extend colocation footprints beyond traditional hub markets.
Hyper scale commands capital deployment; small scale is gaining share fastest with edge computing integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineering talent in high-voltage electrical distribution and mission-critical cooling design concentrates among narrow contractor pools across Frankfurt, Amsterdam, and London. This scarcity inflates construction labor costs and extends project timelines. Grid interconnection backlogs force operators toward secondary metros where substation capacity remains available.
Germany
Hyperscalers pre-commit multi-megawatt blocks in Frankfurt years ahead of energization to secure scarce grid capacity. The EU Green Deal's carbon reduction frameworks mandate power usage effectiveness thresholds that accelerate facility modernization. Bavaria and North Rhine-Westphalia host expanding campus developments as primary hub saturation pushes investment toward secondary metros.
Netherlands
Amsterdam's power grid saturation forces operators into surrounding provinces where land and substation capacity remain accessible. CSRD disclosure mandates require granular Scope 1, 2, and 3 emissions reporting with facility-level documentation. Eindhoven and Brabant regions attract medium-scale deployments as enterprises seek proximity without primary market constraints.
France
Financial services and pharmaceutical clusters in Paris drive demand for carrier-neutral facilities with low-latency connectivity. National building codes and local zoning authorities impose environmental impact review timelines that extend project development cycles. Île-de-France anchors hyperscale campus strategies while Auvergne-Rhône-Alpes emerges as a secondary concentration for enterprise consolidation.
United Kingdom
London's interconnection density sustains retail colocation demand from network-dependent enterprises. Grid interconnection queues delay facility energization regardless of construction completion status. Slough and Greater London host wholesale deployments as cloud service providers seek scalable power architectures with renewable energy guarantees.
Nordic Region
Norway and Sweden offer hydroelectric and wind power at sub-market rates, attracting carbon-conscious hyperscalers seeking zero-carbon compute. Danish and Finnish regulations require data centers to supply district heating systems, opening revenue streams from thermal energy sales. Oslo and Stockholm campuses exceed 100 megawatts with dedicated grid infrastructure and on-site substations.
Europe Data Center Colocation Market Key Industry Players
Capital-heavy facility developers compete with asset-light interconnection platform operators across the European footprint. The market structures around three tiers: hyperscale campus developers with dedicated substations, carrier-neutral exchange operators with dense cross-connect fabrics, and wholesale specialists with scalable power architectures. Strategic moves concentrate on long-term capacity reservations with renewable energy guarantees and liquid cooling readiness clauses.
Within the hyperscale campus tier, Data4 Group and Vantage Data Centers exemplify operators anchoring multi-megawatt deployments in Paris and Frankfurt. Equinix occupies a position representing carrier-neutral density with interconnection-focused platforms across Amsterdam and London. These three sit within distinct strategic archetypes: pure-play wholesale development, integrated exchange and colocation, and hyperscale-specialized infrastructure.
| Leading Market Players |
|---|
| Data4 Group |
| EdgeConneX |
| Digital Realty |
| Colt Data Centre Services |
| Global Switch |
| Equinix |
| Vantage Data Centers |
| Interxion |
| NTT Global Data Centers |
| Others |
Cost & Logistics Intelligence
The wholesale-retail service divergence separates multi-megawatt hyperscale commitments from fragmented rack-level deployments, concentrating pricing power with campus developers in Frankfurt and Amsterdam while compressing margins for shared-facility operators in secondary metros. This bifurcation manifests in supply chain configurations where wholesale specialists source dedicated substation equipment through long-lead procurement channels, and retail operators compete for scarce cross-connect capacity in carrier-dense exchange buildings.
Pricing Analysis
Bundled power-plus-space contracts dominate wholesale transactions, while unbundled metered utility arrangements persist in retail colocation. Three-tier pricing structure across premium Tier IV, standard Tier III, and economy Tier II availability levels differentiates contracts by redundancy architecture and uptime guarantees. Cost compression in retail tiers is intensifying because hyperscalers absorb available substation capacity, leaving smaller buyers competing for residual power allocations. Cloud service providers exhibit lowest price sensitivity due to long-term capacity reservations, while mid-market enterprises in secondary metros face acute budget constraints.
Supply Chain Analysis
Freight costs for oversized electrical equipment—switchgear, transformers, and UPS modules—concentrate procurement geography around German, Dutch, and Chinese manufacturing clusters. Critical facility infrastructure draws from steel fabrication in Germany, precision cooling systems from the Netherlands, and electrical components from China. Single-source vulnerability runs through high-voltage switchgear where European OEMs maintain limited qualified supplier bases. Distribution runs through engineering-procurement-construction contractors who bundle mechanical and electrical packages for campus developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in wholesale colocation as liquid cooling readiness commands premium pricing and renewable energy guarantees justify long-term contract escalators above inflation-indexed baselines.
For Market Incumbents: Lock in multi-year substation interconnection reservations before grid queues extend further in Frankfurt, Amsterdam, and London. Secure exclusive relationships with mission-critical cooling contractors to defend against construction labor scarcity. Vertical integration into on-site battery storage and renewable generation assets mitigates exposure to volatile utility pricing and CSRD-mandated carbon accounting complexity. For New Entrants and Emerging Players: Direct sales through hyperscaler procurement portals offers the most penetrable route for Nordic campus developers seeking to displace incumbent positioning in carbon-conscious compute. Target medium-scale deployments in Italian and Spanish secondary metros where land and substation availability exceeds primary hub constraints. Position around hourly renewable energy matching and waste heat recovery integration to differentiate from established wholesale operators. For Investors and Strategic Acquirers: Asymmetric upside sits with hyperscale-specialized developers holding pre-leased campus phases with energization timelines inside 24 months. Long-term viability rests on contracted revenue visibility through the next infrastructure replacement cycle. Monitor grid interconnection queue clearance rates in Germany and the Netherlands as the primary inflection signal for development timeline compression or extension.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Dielectric fluid bath installations in Amsterdam and Frankfurt compress PUE below 1.1 for AI training clusters. |
| Renewable Energy Certificate Procurement | Hourly matching contracts with Norwegian hydroelectric and Swedish wind generators satisfy CSRD Scope 2 disclosure requirements. |
| Grid Interconnection Reservation | Multi-year substation queue positions in Germany and the Netherlands de-risk campus phase financing for hyperscale pre-leases. |
| Waste Heat Recovery Integration | District heating supply agreements in Denmark and Finland transform thermal rejection into revenue-generating energy sales. |
| Secondary Metro Campus Expansion | Bavaria and North Rhine-Westphalia developments capture enterprise demand fleeing Frankfurt power saturation. |
Research Approach
Direct dialogue with data center development executives, hyperscaler infrastructure procurement leads, utility grid interconnection planners, and mission-critical engineering contractors grounded qualitative findings in operational reality. Secondary validation drew from EMA efficiency guideline documentation, EU Green Deal regulatory filings, national building code repositories in Germany and France, and hyperscaler capital expenditure disclosures. Bottom-up facility-level capacity tracking and top-down regional demand modeling enabled cross-verification of market size estimates.
Bottom-up analysis aggregated individual facility power provisioning, occupancy rates, and contracted pricing tiers across identified campuses. Segmentation dimensions modeled include service type, end-user category, technology stack abstraction layer, and facility capacity tier. CAGRs were derived from trend extrapolation of pre-lease activity, grid interconnection timelines, and carbon regulation compliance cost trajectories. Forecast inputs incorporated AI infrastructure deployment curves and renewable energy certificate market liquidity assumptions.
The model assumes a particular technology adoption path; alternative pathways for direct liquid cooling versus air-cooled retrofits would alter the outlook for legacy facility valuations and new construction capital intensity. Forecasts reflect documented assumptions about grid expansion timelines, carbon border adjustment implementation, and hyperscaler geographic diversification patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Saudi Arabia Data Center Physical Security Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
New Jersey Data Center Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Belgium Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
Germany Data Center Rack Market
Data Center Infrastructure
Mexico Data Center Physical Security Market
Data Center Infrastructure
Belgium Data Center Rack Market