
 Malaysia Wireless Router Market | 2026-2036
Malaysia Wireless Router Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Wireless Router Market Foresight
MCMC's mandatory IPv6 transition is realigning the cost-of-entry calculus for equipment vendors seeking public-sector and large carrier contracts. Huawei Technologies leverages its integrated chipset-to-system design to sustain price competitiveness in carrier-grade deployments. TP-Link anchors the mass-market residential tier through aggressive channel control across Malaysian electronics retail chains. Edimax Technology specializes in small-business routing solutions that navigate the technical gap between consumer and enterprise segments.
A wireless router is a network device that forwards data packets between computer networks using radio frequency bands, typically operating at 2.4 GHz and 5 GHz with throughput specifications ranging from AC1200 to AX6000 under IEEE 802.11 standards, serving to distribute internet connectivity to multiple endpoints in homes, offices, and institutions. The product-type dimension shows dual-band units still dominate unit volumes in Malaysian retail, while tri-band and 5G routers represent the fastest-growing margin pools as fiber-to-home penetration deepens in urban corridors. Wi-Fi 6 technology leads enterprise refresh cycles, whereas mesh networking captures premium residential demand in multi-story dwellings across Kuala Lumpur's condominium market.
MCMC, the Malaysian Communications and Multimedia Commission, enforces technical standards and spectrum allocation rules that directly shape product certification requirements and market access timelines. BIS-equivalent local testing protocols and SIRIM certification create compliance layers that favor established vendors with dedicated Malaysian regulatory affairs teams. Stakeholders must monitor the interplay between national 5G rollout pace and enterprise router upgrade cycles to time inventory and channel investments.
Market Dynamics
MCMC's mandatory IPv6 transition is compressing vendor certification timelines and forcing simultaneous hardware refreshes across Malaysian carrier and enterprise networks, creating a synchronized procurement wave that favors established players with dedicated regulatory affairs teams.
Growth Catalysts
- JENDELA national broadband initiative:Government-funded fiber-to-home rollout in urban corridors is generating concentrated demand for Wi-Fi 6 and mesh router systems among residential subscribers upgrading from legacy copper connections.
- 5G network densification:Telekom Malaysia and DNB's infrastructure buildout is accelerating enterprise edge-router replacements to support higher backhaul throughput and lower latency requirements in manufacturing and logistics facilities.
- Condominium densification in Kuala Lumpur:Multi-dwelling unit construction is driving premium residential demand for whole-home coverage solutions that eliminate dead zones across stacked floor plans.
Market Restraints
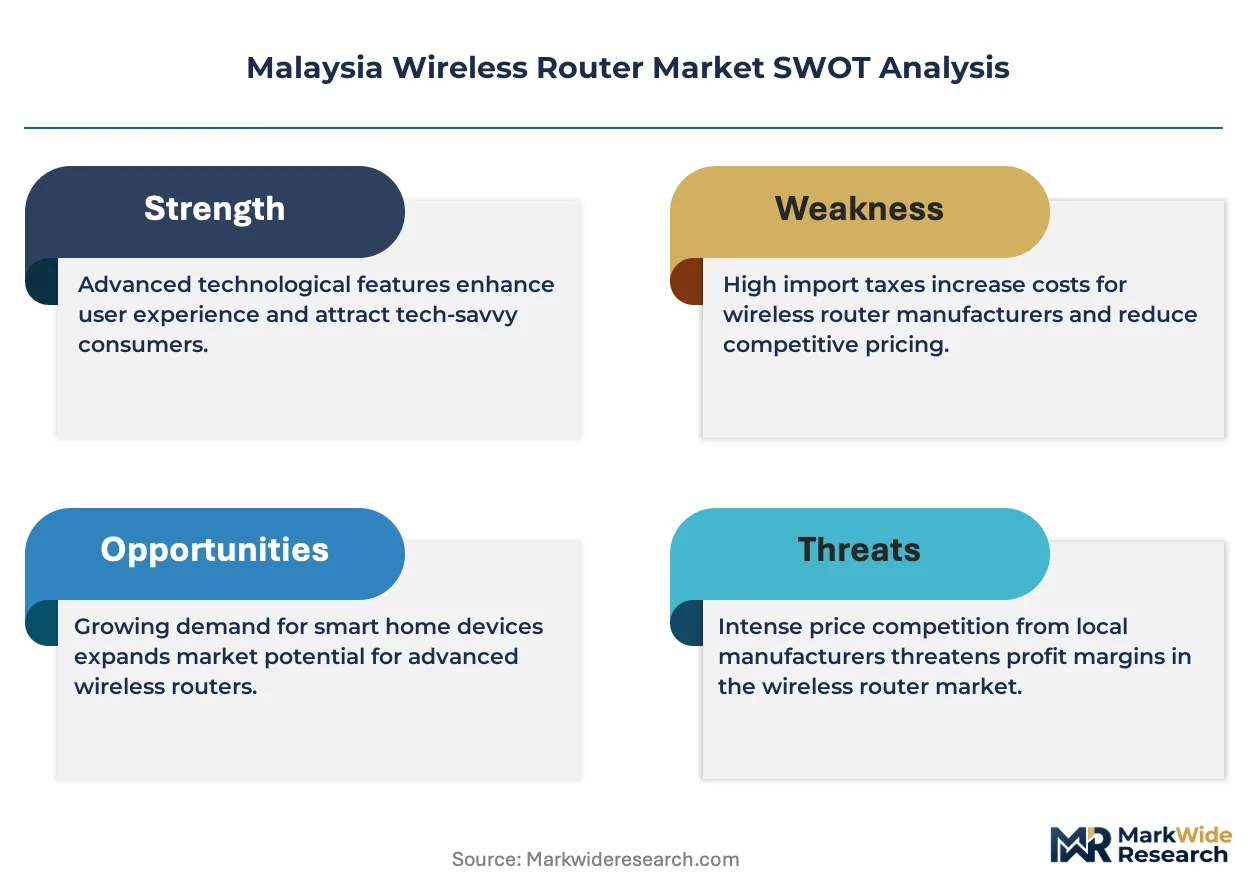
- Semiconductor supply concentration:Dependence on Taiwan-based foundries for Wi-Fi 6/6E chipsets creates vulnerability to geopolitical disruption and foundry allocation decisions.
- SIRIM certification backlog:Local testing protocol capacity constraints extend product approval timelines by 8-12 weeks, delaying market entry for new entrants.
- Copper-to-fiber transition lag:Rural broadband infrastructure remains sub-gigabit, limiting addressable market for premium router tiers outside Klang Valley and Penang corridors.
Strategic Opportunities
- SME digitalization incentives:MDEC's technology adoption grants for small businesses create subsidized demand for enterprise-grade routing equipment previously unattainable for this segment.
- East Malaysia connectivity gap:Sarawak and Sabah's underserved fixed-broadband markets present first-mover potential as submarine cable investments reach completion.
- Wi-Fi 7 pre-positioning:Early certification and channel stocking ahead of 2026 spectrum allocation decisions could capture upgrade cycles from early-adopter residential and gaming segments.
Industry Challenges
- Embedded systems engineering scarcity:Shortage of firmware developers with OpenWRT and proprietary SDK experience constrains product differentiation timelines for local assembly operations.
- Legacy IPv4 estate integration:Enterprise IT teams face complex dual-stack configuration requirements during transition periods, elevating support costs and return rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Wireless Router Market |
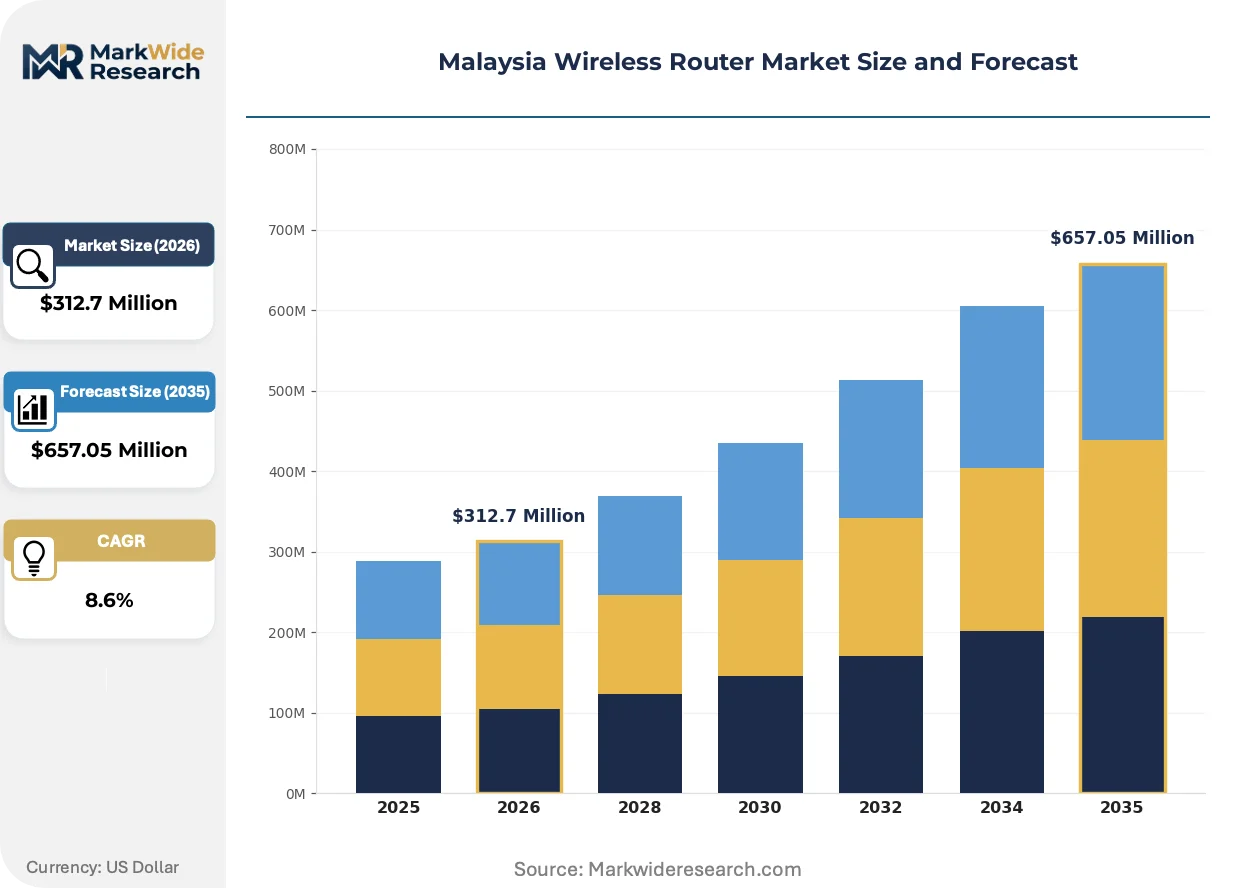
| Market Size in 2026 | $312.7 Million |
| Market Size in 2035 | $657.05 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual-Band, Tri-Band, 4G LTE, 5G Technology: Wi-Fi 5, Wi-Fi 6, Mesh Networking, Point-to-Point End User: Residential, Small Business, Large Enterprise, Educational Institution Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Huawei Technologies, Xiaomi, TP-Link, Buffalo Americas, Edimax Technology, D-Link, ASUSTeK Computer, Netgear, Cisco Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Wireless Router Market Shifts & Advancements
Malaysian network infrastructure is undergoing simultaneous transitions across protocol generations, spectrum allocation, and service delivery models, compressing typical equipment refresh cycles and elevating technical complexity for procurement decisions.
Wi-Fi 6E with 6 GHz spectrum access is unifying previously separate enterprise and premium residential feature sets into single hardware platforms. Property developers in Mont Kiara and Bangsar are specifying tri-band mesh systems as standard condominium fit-outs. This convergence is compressing price premiums that historically separated commercial and consumer tiers.
MCMC's 2024 technical code amendment mandating IPv6-ready equipment certification is forcing firmware architecture overhauls across the vendor base. The regulation eliminates grandfathering for legacy IPv4-only designs in public-sector tenders. Enterprise procurement teams are accelerating RFP timelines to lock in compliant suppliers before certification bottlenecks intensify.
Direct-to-installer distribution is displacing traditional retail channel dominance for multi-node residential mesh systems. Wiring contractors and smart-home integrators in Selangor are capturing margin previously held by electronics chains. This channel shift is most pronounced in landed property developments where pre-wiring specifications are set during construction phase.
Malaysia Wireless Router Market Segmentation
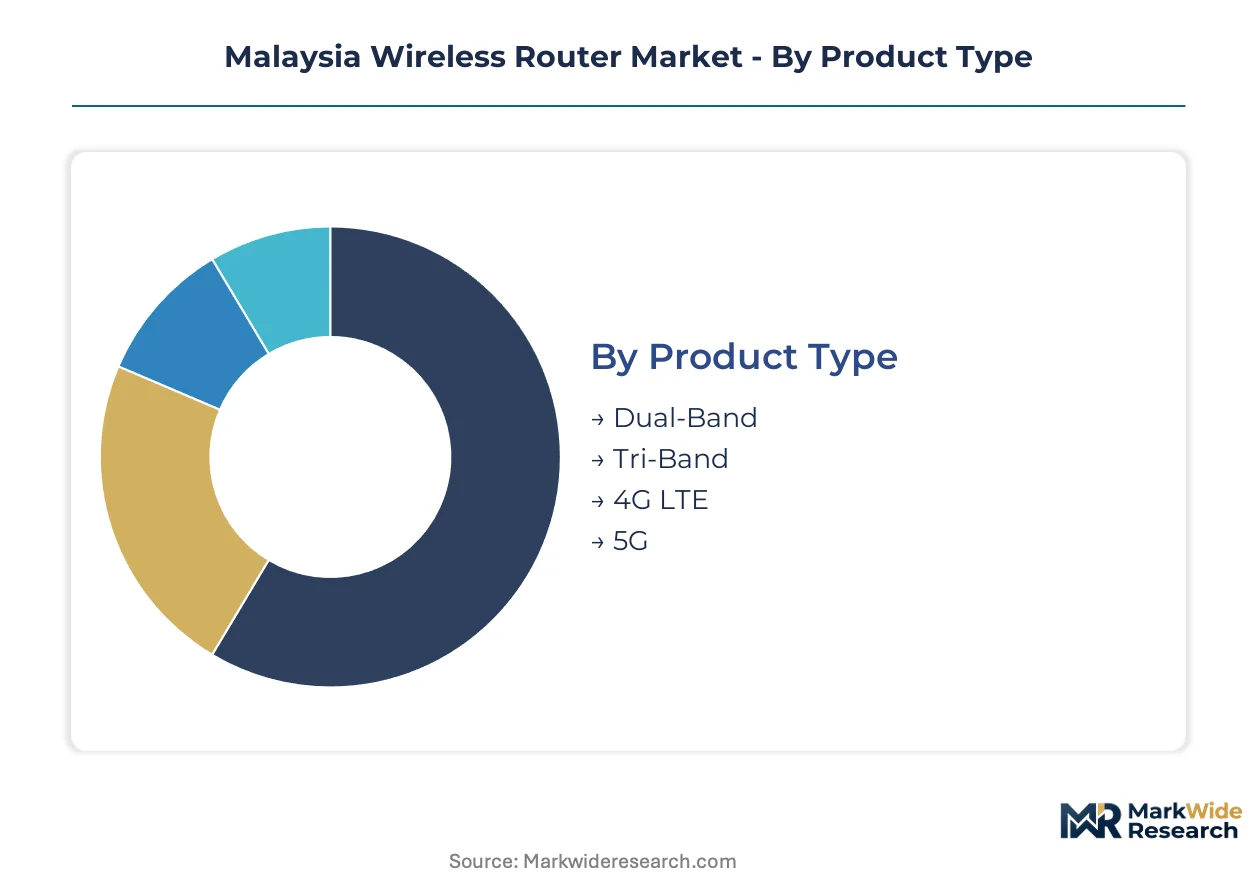
Equipment refresh cycles across Malaysian households and enterprises create distinct demand profiles by specification tier and procurement channel. Segmentation reveals where IPv6 compliance, spectrum allocation, and installation complexity reshape purchasing behavior.
Product Type:
Replacement cycles accelerate where fiber-to-home penetration deepens, pushing households toward higher-capacity hardware even when legacy devices remain functional.
- Dual-Band:AC1200 to AX3000 specifications dominate mass-market retail in Selangor electronics chains. Klang Valley residential subscribers upgrading from 100 Mbps copper connections drive concentrated volume through bundled ISP promotions.
- Tri-Band:Dedicated backhaul channels eliminate bandwidth contention in multi-device environments. Mont Kiara and Bangsar condominium developers specify these as standard fit-outs for units above 1,500 square feet.
- 4G LTE:Portable routing solutions address connectivity gaps in East Malaysia where fixed-line infrastructure remains sparse. Sarawak construction sites and Sabah plantation operations generate B2B procurement.
- 5G:Enterprise edge deployments leverage higher throughput for manufacturing IoT backhaul. DNB network densification in Penang industrial zones accelerates pilot installations.
Volume placements concentrate in Dual-Band; the faster expansion belongs to Tri-Band.
Technology:
Protocol generation determines certification urgency under MCMC's IPv6 mandate, with compliance timelines compressing procurement decisions.
- Wi-Fi 5:Legacy AC standards persist in price-sensitive rural markets where sub-gigabit broadband limits performance differentiation. Perak and Kedah retail channels clear remaining inventory through aggressive discounting.
- Wi-Fi 6:OFDMA and MU-MIMO architectures reduce latency in high-density environments. Kuala Lumpur enterprise campuses undergoing simultaneous 5G and fiber upgrades specify these for access layer refreshes.
- Mesh Networking:Self-healing topologies address coverage gaps in multi-story dwellings without structured cabling. Direct-to-installer channels in Selangor landed property developments capture premium margin through pre-wiring specifications.
- Point-to-Point:Directional antenna systems bridge connectivity across industrial compounds and campus environments. Johor manufacturing facilities deploy these for warehouse-to-office links bypassing trenching costs.
Wi-Fi 5 retains the largest installed base; Mesh Networking climbs the fastest as condominium stock expands.
End User:
Procurement sophistication varies sharply by organizational scale, with subsidy eligibility and technical staff availability shaping specification ceilings.
- Residential:Subscriber-owned equipment dominates where unbundled fiber tariffs allow hardware choice. JENDELA voucher programs accelerate Wi-Fi 6 adoption among first-time fiber households in urban corridors.
- Small Business:MDEC technology grants subsidize enterprise-grade features previously unattainable at this tier. Cyberjaya and Penang startup clusters drive demand for cloud-managed platforms with zero-touch provisioning.
- Large Enterprise:Centralized policy enforcement and captive portal requirements mandate controller-based architectures. Banking and telecommunications verticals in Kuala Lumpur central business district lead refresh cycles.
- Educational Institution:Campus-wide density planning for 1:1 device programs requires high-capacity infrastructure. Public university hostel renovations in Selangor generate concentrated RFP activity.
Residential accounts for the greatest unit volume; Small Business shows the steepest expansion trajectory as digitalization incentives take effect.
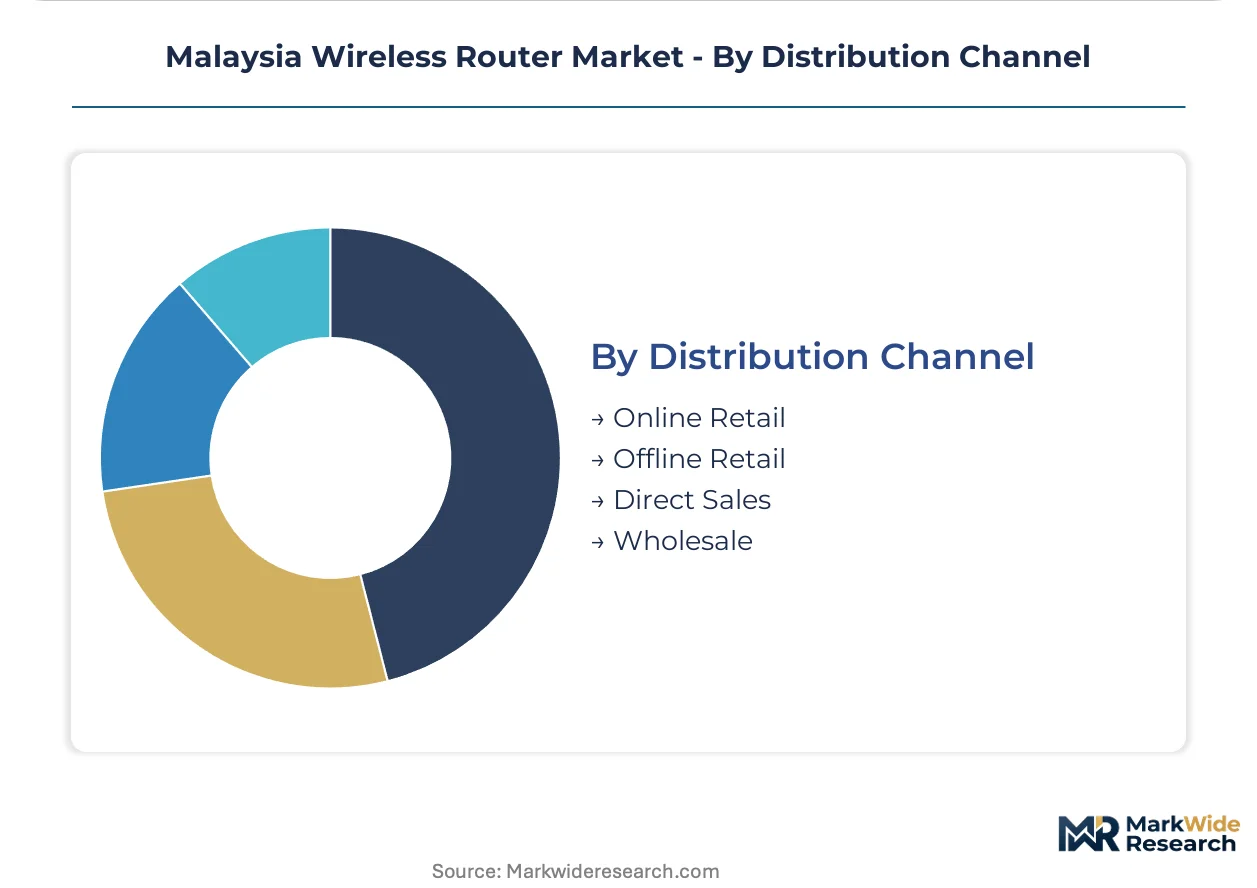
Distribution Channel:
Channel selection tracks installation complexity, with professional integration displacing self-installation for multi-node residential systems.
- Online Retail:E-commerce platforms capture price-comparison shoppers seeking unbundled hardware. Lazada and Shopee promotional calendars synchronize with ISP marketing campaigns.
- Offline Retail:Electronics chains retain relevance for immediate replacement needs and technical consultation. Low Yat Plaza and Mid Valley Megamall outlets serve Klang Valley walk-in demand.
- Direct Sales:Manufacturer field teams engage enterprise procurement with customized site surveys. Huawei and Cisco maintain dedicated Malaysian enterprise sales organizations.
- Wholesale:Bulk procurement for property development and ISP bundling flows through distributor networks. Selangor wiring contractors source mesh systems through specialized B2B channels.
Offline Retail still handles the most transactions; Direct Sales is gaining share fastest as enterprise edge deployments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for wireless routers in Malaysia concentrates in the Klang Valley corridor, where fiber-to-home penetration and condominium densification create synchronized procurement waves across residential and enterprise segments.
Kuala Lumpur
Mont Kiara and Bangsar property developers specify tri-band mesh systems as standard condominium fit-outs. MCMC's IPv6-ready equipment certification mandates accelerate hardware refresh cycles in government and banking verticals. Enterprise campuses in the central business district deploy Wi-Fi 6 access layers to support simultaneous 5G and fiber upgrades.
Selangor
Cyberjaya startup clusters drive demand for cloud-managed routing platforms with zero-touch provisioning. JENDELA voucher programs accelerate Wi-Fi 6 adoption among first-time fiber households in Shah Alam and Petaling Jaya. Wiring contractors capture margin through direct-to-installer distribution channels for landed property developments.
Penang
Industrial zones in Bayan Lepas generate enterprise edge-router replacements to support DNB 5G network densification. Manufacturing facilities deploy point-to-point directional systems for warehouse-to-office connectivity. Sub-gigabit broadband in rural northern districts limits addressable market for premium router tiers.
Sarawak
Construction sites and plantation operations generate B2B procurement for portable 4G LTE routing solutions. Submarine cable investments reaching completion create first-mover potential in underserved fixed-broadband markets. Kuching urban corridors show early fiber adoption patterns similar to peninsular Malaysia five years prior.
Sabah
Eastern connectivity gaps persist despite infrastructure investments, with rural broadband remaining sub-gigabit outside Kota Kinabalu. Plantation and logistics operations drive demand for ruggedized edge equipment. State-level digitalization initiatives lag peninsular counterparts by 18-24 months in equipment refresh cycles.
Malaysia Wireless Router Market Competitive Landscape
Chinese producers anchor the mass-market tier; Taiwanese specialists hold the small-business segment. The vendor base organizes around three strategic archetypes: integrated chipset-to-system designers, channel-controlled retail brands, and regulatory-compliance specialists. Competitive moves concentrate on SIRIM certification pre-positioning and direct-to-installer channel capture.
Within the integrated-system tier, Huawei Technologies occupies a position exemplifying captive supply advantages in carrier-grade deployments. TP-Link represents the channel-controlled archetype through electronics retail chain presence. Edimax Technology sits within the compliance-specialist category, navigating certification requirements for small-business segments.
| Leading Market Players |
|---|
| Huawei Technologies |
| Xiaomi |
| TP-Link |
| Buffalo Americas |
| Edimax Technology |
| D-Link |
| ASUSTeK Computer |
| Netgear |
| Cisco Systems |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap distributors in Selangor and Kuala Lumpur anchor procurement channels for Malaysian router vendors, tightening payment terms and compressing working-capital cycles for manufacturers seeking retail shelf presence. This ownership concentration feeds back into supply behavior through volume-commitment demands and exclusive distribution arrangements that reshape pricing discipline across tiered product lines.
Pricing Analysis
Premium pricing for short lead-time delivery applies to SIRIM-certified inventory held in Penang bonded warehouses, while spot-market units face discount pressure from clearance activity in Perak electronics retail chains. Pricing stratifies across Wi-Fi 6 enterprise-grade, Wi-Fi 5 mass-market, and legacy IPv4 clearance tiers, with certification-grade differentiation commanding margin expansion. Cost compression in the dual-band residential segment is intensifying due to ISP bundling requirements. Small-business procurement teams show highest price sensitivity; government and banking verticals demonstrate lowest sensitivity given compliance mandates.
Supply Chain Analysis
Dual-sourcing requirements from Telekom Malaysia and DNB procurement teams mandate multi-supplier qualification for Wi-Fi 6/6E chipsets, forcing vendors to maintain relationships with both MediaTek and Qualcomm chipset platforms. Manufacturing draws from Taiwan for foundry services, China for PCB assembly and component sourcing, and Malaysia for final SIRIM certification and localization. Single-source vulnerability centers on Taiwan-based foundry allocation decisions for advanced node production. Distribution runs through Selangor-based electronics distributors serving retail chains, with direct-to-installer channels gaining share in landed property developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's wireless router market is consolidating around regulatory compliance capabilities, with MCMC's IPv6 mandate and SIRIM certification backlog forcing capital-constrained vendors toward exit or acquisition. This consolidation pressure favors established players with dedicated Malaysian regulatory affairs teams and pre-certified product pipelines.
For Market Incumbents: Acquire SIRIM-certified product portfolios from distressed local assemblers to compress certification timelines and block new entrant access to carrier procurement channels. Expand Cyberjaya-based technical support capacity to capture SME digitalization grant flows. Threat: Embedded systems engineering scarcity constrains firmware differentiation timelines. Lever: Channel control through exclusive wiring-contractor relationships in Selangor landed developments. For New Entrants and Emerging Players: MCMC's mandatory IPv6 transition in Malaysia opens a window for regulatory-specialist entrants targeting the small-business segment with cloud-managed platforms. White-space targets include East Malaysia's underserved fixed-broadband corridors and Cyberjaya startup clusters seeking zero-touch provisioning. Go-to-market: Direct-to-installer partnerships with Mont Kiara and Bangsar smart-home integrators specifying pre-wired mesh systems. For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-specialist assemblers with existing SIRIM relationships and localized firmware capabilities in the Klang Valley corridor. Long-term viability hinges on Wi-Fi 7 pre-positioning ahead of spectrum allocation decisions. Signal to watch: DNB 5G densification pace in Penang industrial zones as enterprise edge-router replacement trigger.| Strategic Initiative | Industry Significance |
|---|---|
| SIRIM Certification Pre-Positioning | Compresses market entry timelines for MCMC IPv6-mandated public-sector tenders. |
| Direct-to-Installer Channel Capture | Wiring contractors in Selangor displace retail margin through pre-wiring specifications. |
| Wi-Fi 7 Early Certification | Captures upgrade cycles from gaming and early-adopter residential segments ahead of spectrum decisions. |
| East Malaysia Distribution Buildout | Submarine cable investments in Sarawak create first-mover advantage in underserved fixed-broadband markets. |
| SME Cloud-Managed Platform Launch | MDEC technology grants subsidize enterprise-grade features previously unattainable at small-business tier. |
Research Methodology
MCMC regulatory filings, SIRIM certification databases, and JENDELA program disbursement records formed the secondary backbone for market sizing and compliance timeline analysis. Primary interviews with ISP procurement managers, electronics retail category buyers, and smart-home integrators in Kuala Lumpur and Selangor validated demand assumptions and channel dynamics. Bottom-up triangulation across product-type segmentation and top-down validation against national broadband penetration statistics produced volume and value estimates. Secondary sources included customs import records for networking equipment, Telekom Malaysia infrastructure capex disclosures, and DNB 5G rollout progress reports.
Historical trendline analysis of equipment refresh cycles, fiber-to-home penetration rates, and condominium construction permits established baseline growth patterns across the projection horizon. The analytical framework modeled segmentation dimensions including product type, technology generation, end-user tier, and distribution channel, with regional variation across Klang Valley, Penang, and East Malaysia corridors. CAGRs derived from equipment replacement velocity, protocol transition timelines, and subsidy program scaling curves. Industry-specific inputs included MCMC spectrum allocation decisions, SIRIM testing capacity expansion, and DNB network densification milestones.
The model assumes a particular technology adoption path; alternative pathways for Wi-Fi 6E and Wi-Fi 7 would alter the outlook if spectrum allocation delays or chipset supply constraints materialize. Forecasts incorporate assumptions regarding JENDELA voucher program continuation, DNB 5G enterprise uptake, and SIRIM certification processing capacity. A model refresh is warranted upon material change in MCMC regulatory timelines or DNB infrastructure deployment pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
North America Structured Cabling Market
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
Network Equipment Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
Intelligent Network Management Market
Network Technology
Cloud Gateway Module Market
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Asia Pacific Structured Cabling Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
UK B2B Fixed Connectivity Market
Network Technology
Indoor Distributed Antenna Systems Market
Network Technology
Small Cell Networks Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Protocol Analyzer Market