
 Global Data Loss Prevention Software Market | 2026-2036
Global Data Loss Prevention Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Loss Prevention Software Market Foresight
ISO 27001 certification is bifurcating the competitive landscape into qualified and non-qualified vendors. Microsoft leverages its cloud-native architecture to dominate enterprise deployments. Broadcom sustains its position through in-house production of integrated security stacks. Forcepoint specializes in insider threat detection for government agencies and defense contractors.
Data loss prevention software monitors, detects, and blocks sensitive data exfiltration across endpoints, networks, and cloud repositories using content inspection, contextual analysis, and policy enforcement engines. Cloud-based deployment leads solution architecture as hybrid workforces expand distributed data footprints. Endpoint protection captures the largest margin pool due to agent complexity and persistent licensing models. Network protection grows fastest as zero-trust architectures mandate deep packet inspection at perimeter and core layers.
FDA 21 CFR Part 11, SEC cybersecurity rules, and GDPR enforcement by EU data protection authorities shape product standards and procurement timelines across regulated industries. HIPAA drives demand in US healthcare where patient data monitoring carries statutory penalties. Stakeholders must weigh cloud migration velocity against sovereignty requirements as national data localization laws proliferate.
Market Dynamics
Cloud-native architecture is bifurcating vendor viability as enterprises abandon on-premise data centers for distributed SaaS deployments, forcing legacy providers to rewrite core inspection engines or exit the market entirely.
Growth Catalysts
- SEC Cybersecurity Disclosure Rules:US financial services firms must deploy real-time data monitoring systems to satisfy public reporting mandates, compressing procurement cycles from twelve months to under ninety days.
- EU AI Act Compliance Deadlines:European enterprises face statutory penalties for ungoverned AI systems processing personal data, creating immediate demand for policy enforcement engines with automated risk scoring.
- Hybrid Workforce Expansion:Distributed endpoints accessing cloud repositories multiply data exfiltration vectors, requiring agent-based protection that travels with employee devices regardless of network perimeter.
Market Restraints
- Agent Complexity Costs:Endpoint protection requires kernel-level software installation that degrades system performance, creating user resistance and helpdesk burden that slows enterprise rollouts.
- Cloud Provider Concentration:Three hyperscalers control the infrastructure layer where DLP policy engines must integrate, extracting margin through API access fees and data egress charges.
- False Positive Fatigue:Content inspection algorithms generate excessive alert volume that security operations centers cannot triage, eroding trust in automated blocking decisions.
Strategic Opportunities
- India Digital Personal Data Protection Act:Cross-border data transfer restrictions create localized deployment requirements for multinational corporations operating captive centers in Bangalore and Hyderabad.
- Generative AI Content Scanning:Large language model outputs require real-time classification before corporate dissemination, opening adjacent product categories for data loss prevention vendors.
- Outcome-Based Licensing Models:Enterprises prefer consumption-based pricing tied to actual data events monitored rather than perpetual seat licenses, rewarding vendors with superior cloud metering infrastructure.
Industry Challenges
- ISO 27001 Certification Timeline:Vendor qualification processes extend eighteen to twenty-four months, delaying market entry for new entrants regardless of technical capability.
- Legacy SIEM Integration Complexity:Enterprises demand seamless correlation between DLP alerts and security information platforms, requiring expensive professional services engagements that compress software margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Loss Prevention Software Market |
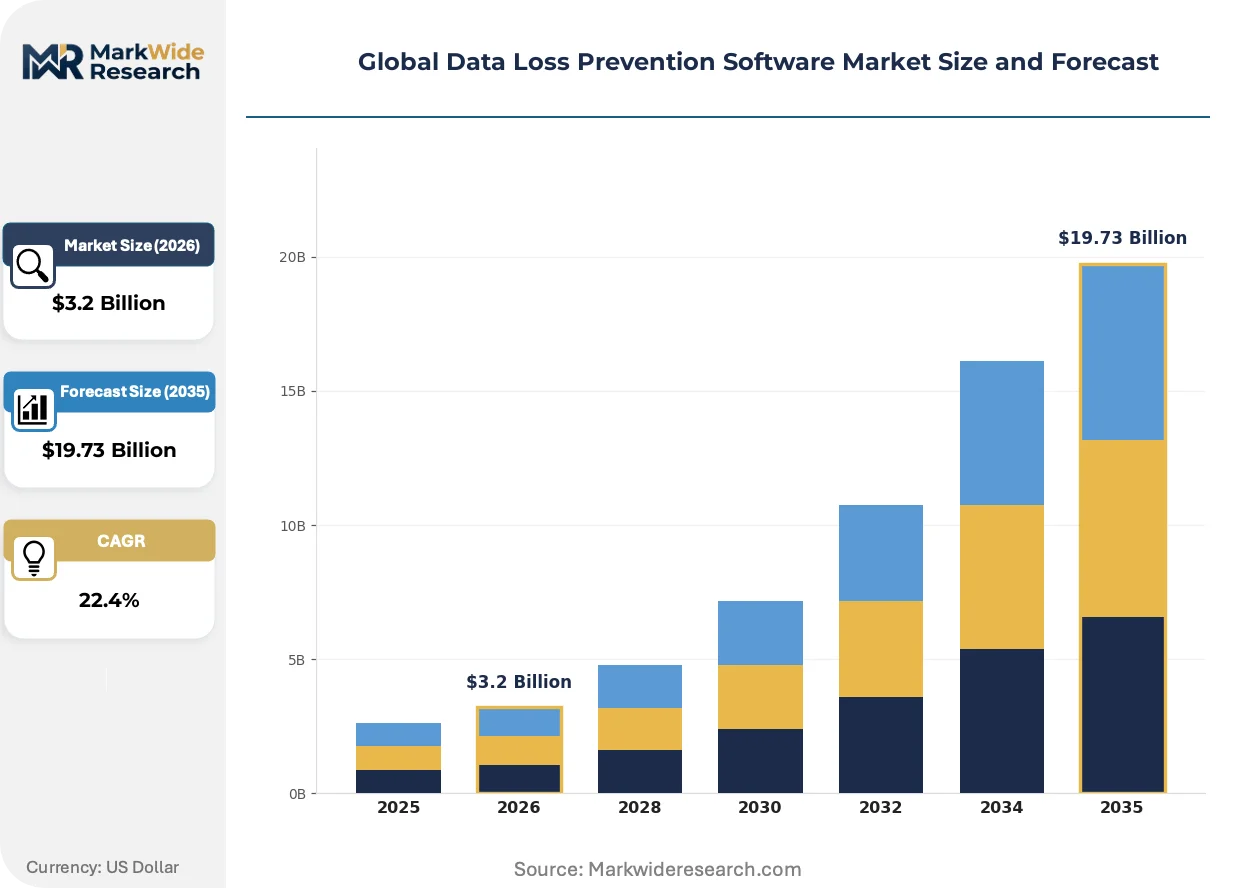
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $19.73 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Virtual Appliance Solution Type: Endpoint Protection, Network Protection, Cloud Security, Email Security, Storage Security Application: Data Monitoring, Compliance Management, Insider Threat Detection, Intellectual Property Protection, Regulatory Reporting End User Industry: Financial Services, Telecommunications, Energy & Utilities, Government Agencies, Educational Institutions |
| Companies Covered | Microsoft, Broadcom, Forcepoint, Proofpoint, Fortra, McAfee, Trend Micro, Check Point Software Technologies, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Loss Prevention Software Market Shifts & Advancements
Behavioral analytics engines are displacing signature-based detection as insider threat sophistication outpaces static rule definitions, forcing architectural pivots across the vendor ecosystem.
Machine learning classification is bifurcating deployment strategies between cloud-native and hybrid architectures. Financial services institutions in New York and London are adopting federated learning models that train on local data without centralizing sensitive information. This approach is bifurcating vendor roadmaps into edge-computing specialists versus centralized SaaS providers.
GDPR enforcement by EU data protection authorities is hardening cross-border data governance requirements. German automotive manufacturers and French pharmaceutical firms now mandate EU-sovereign cloud instances with cryptographic key localization. French CNIL penalties against non-compliant data processors have accelerated procurement of region-specific deployment options.
Security procurement committees are consolidating vendor relationships to reduce integration overhead. Healthcare systems in the United States now require DLP solutions bundled with identity management and endpoint detection platforms. This preference shift favors integrated security stacks over standalone point solutions, compressing addressable market space for specialized vendors.
Global Data Loss Prevention Software Market Segmentation
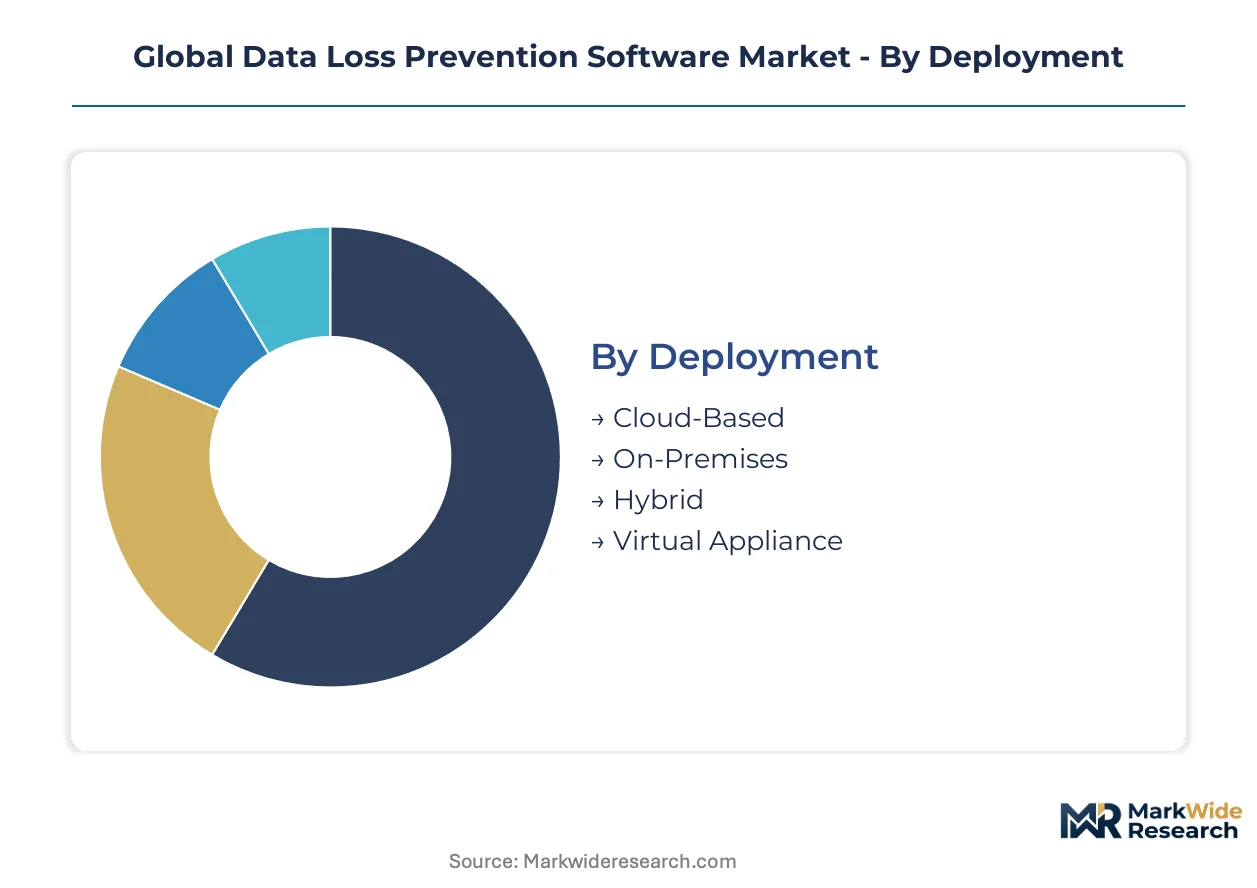
Deployment architecture determines margin capture in data loss prevention software, with cloud-native implementations commanding premium pricing against legacy on-premise installations. Solution packaging and application focus further stratify vendor positioning across regulated industries with distinct compliance burdens.
Deployment:
Margin pools concentrate in recurring SaaS arrangements that eliminate capital expenditure friction for enterprise procurement committees.
- Cloud-Based:Multi-tenant architectures with API-first policy engines enable instantaneous scaling across distributed workforces. Financial services firms in New York and London prioritize these deployments to satisfy SEC and FCA real-time monitoring mandates without infrastructure latency.
- On-Premises:Air-gapped installations with localized data residency satisfy national sovereignty requirements in Germany, France, and Saudi Arabia. German automotive manufacturers and French pharmaceutical firms mandate these configurations under CNIL and BSI guidance for cryptographic key control.
- Hybrid:Split architectures route sensitive data through on-premise inspection while cloud-native components handle routine traffic.
- Virtual Appliance:Containerized deployments bridge legacy data centers and cloud migration trajectories.
The dominant share belongs to Cloud-Based deployments, while Hybrid configurations are closing the gap fastest as enterprises navigate sovereignty requirements.
Solution Type:
Application complexity drives pricing tiers, with endpoint agents requiring kernel-level engineering that standalone network appliances cannot match.
- Endpoint Protection:Persistent agents residing at operating system kernels inspect data at creation and rest across laptops, mobile devices, and virtual desktops. Healthcare systems deploying these solutions face HIPAA audit scrutiny for patient data monitoring, compressing vendor qualification timelines.
- Network Protection:Deep packet inspection engines operating at perimeter and core layers enforce policies without endpoint installation. Zero-trust architecture mandates in US federal agencies and Japanese financial institutions accelerate procurement of these solutions.
- Cloud Security:API-native scanners integrated with SaaS repositories inspect data in motion across Microsoft 365, Salesforce, and Google Workspace.
- Email Security:Gateway and inline inspection tools prevent exfiltration through corporate messaging channels.
- Storage Security:At-rest encryption and access logging for data lakes and object stores.
Endpoint Protection retains the largest revenue pool, though Cloud Security solutions are expanding most quickly alongside SaaS migration.
Application:
Functional specialization determines addressable market breadth, with integrated compliance suites capturing wider procurement budgets than point solutions.
- Data Monitoring:Real-time visibility engines tracking data movement across endpoints, networks, and cloud repositories. Telecommunications operators in India deploy these tools under Digital Personal Data Protection Act requirements for cross-border transfer logging.
- Insider Threat Detection:Behavioral analytics correlating user activity patterns with data access anomalies. US defense contractors and intelligence agencies mandate these capabilities under CMMC and NIST frameworks.
- Compliance Management:Automated policy mapping to regulatory requirements with audit trail generation.
- Intellectual Property Protection:Source code and design document classification for manufacturing and technology sectors.
- Regulatory Reporting:Structured disclosure outputs for SEC, EBA, and PRA submission deadlines.
Data Monitoring commands the broadest deployment base, while Insider Threat Detection is climbing the fastest as board-level risk committees elevate personnel security.
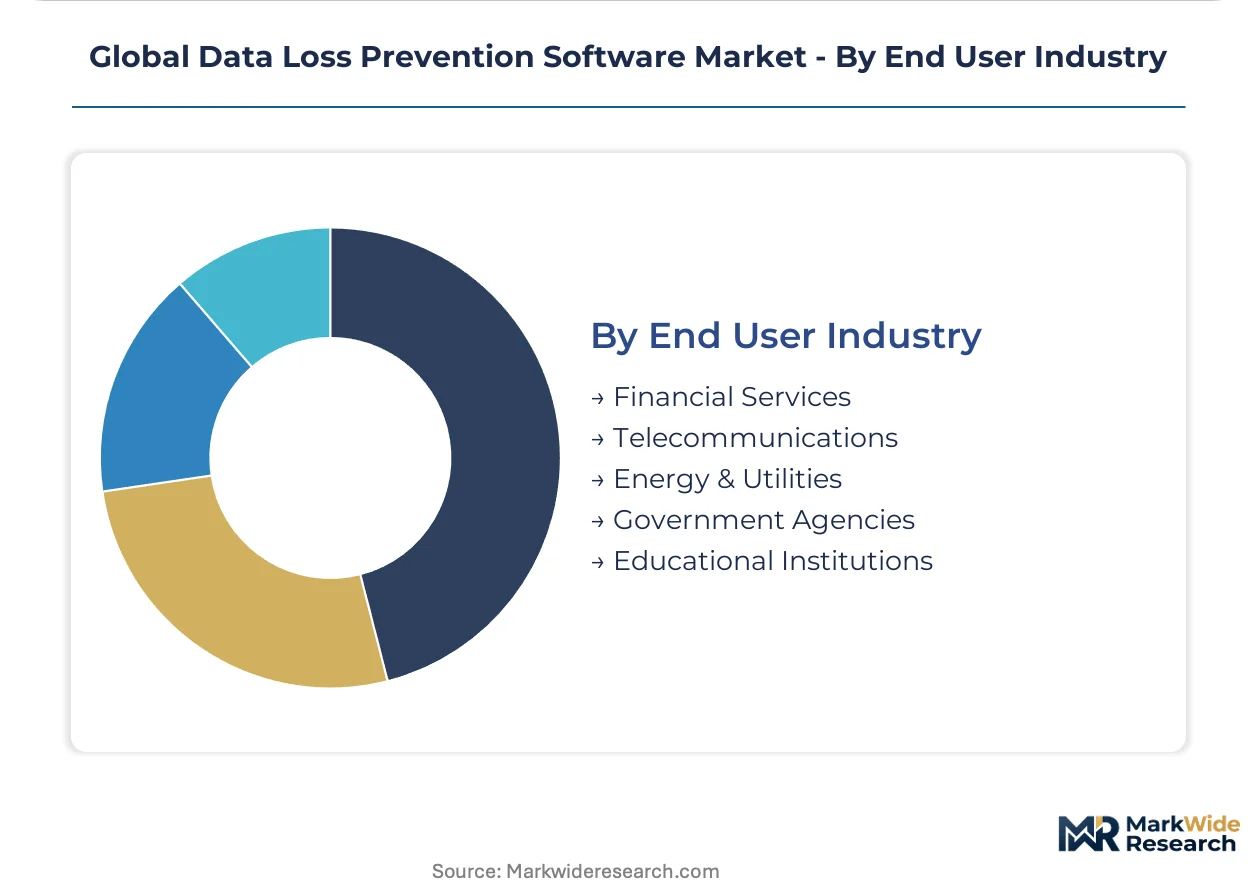
End User Industry:
Regulatory intensity shapes customer lifetime value, with financial services procurement cycles compressing dramatically under statutory deadlines.
- Financial Services:Banks, insurers, and asset managers face overlapping SEC cybersecurity disclosure rules, GDPR Article 33 breach notification, and PCI-DSS cardholder data requirements. Singaporean and Swiss private banks prioritize DLP investments following MAS and FINMA enforcement actions.
- Government Agencies:Classified information handling mandates drive specialized deployments with FedRAMP and NATO certification requirements. Australian federal departments and Canadian provincial authorities specify these standards in tender documents.
- Telecommunications:Subscriber data protection under sector-specific privacy frameworks.
- Energy & Utilities:Critical infrastructure protection aligned with NERC CIP and EU NIS2 directives.
- Educational Institutions:Student records management under FERPA and analogous national frameworks.
Financial Services holds the dominant procurement volume, with Government Agencies gaining share fastest through classified data protection mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC cybersecurity disclosure rules compress procurement cycles to ninety days for US financial services firms. GDPR enforcement by EU data protection authorities hardens cross-border data governance requirements. India's Digital Personal Data Protection Act mandates localized deployment for multinational captive centers.
United States
New York and London financial institutions prioritize cloud-native deployments to satisfy SEC real-time monitoring mandates. HIPAA drives demand in healthcare systems where patient data monitoring carries statutory penalties. Silicon Valley technology firms and Washington DC defense contractors anchor the largest procurement volumes for insider threat detection.
Germany
BSI guidance and national data sovereignty requirements mandate air-gapped installations with cryptographic key control. Automotive manufacturers in Stuttgart and Munich specify EU-sovereign cloud instances under CNIL-aligned procurement policies. Frankfurt financial centers drive hybrid architecture adoption balancing latency against residency compliance.
United Kingdom
FCA operational resilience requirements accelerate procurement of endpoint protection for distributed workforces. London-based asset managers and insurers face overlapping GDPR Article 33 breach notification obligations. Edinburgh and Manchester technology clusters concentrate cloud security solution deployments for SaaS migration.
India
Cross-border data transfer restrictions under the Digital Personal Data Protection Act create localized deployment requirements for multinational corporations. Bangalore and Hyderabad captive centers drive demand for data monitoring solutions with regional sovereignty compliance. Mumbai financial institutions align with RBI cybersecurity guidelines for real-time transaction surveillance.
Japan
METI guidelines for critical infrastructure protection shape procurement standards for energy and telecommunications operators. Tokyo financial institutions under FSA oversight adopt federated learning models for sensitive data classification. Osaka manufacturing clusters implement endpoint protection for intellectual property safeguarding.
Global Data Loss Prevention Software Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with cloud infrastructure assets. The vendor ecosystem exhibits tiered concentration where ISO 27001 certification bifurcates qualified from non-qualified participants. Strategic archetypes include cloud-native platform providers, integrated security stack vendors, and specialized insider threat detection firms. Dominant competitive moves encompass API-first policy engine development and outcome-based licensing model transitions.
Within the cloud-native tier, Microsoft leverages multi-tenant architectures for enterprise dominance. Broadcom sustains positioning through in-house production of integrated security components. Forcepoint occupies a specialized position serving government agencies and defense contractors with behavioral analytics capabilities.
| Leading Market Players |
|---|
| Microsoft |
| Broadcom |
| Forcepoint |
| Proofpoint |
| Fortra |
| McAfee |
| Trend Micro |
| Check Point Software Technologies |
| IBM |
| Others |
Supply & Pricing Matrix
Perpetual-to-subscription conversion contracts lock in multi-year SaaS commitments for enterprise buyers while giving vendors predictable revenue visibility against cloud infrastructure costs. This structure concentrates pricing power with ISO 27001-certified providers who can command premium tiers under SEC and GDPR procurement mandates.
Pricing Analysis
Certification level creates the primary spread between qualified and non-qualified vendor tiers in this market. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 27001 status, FedRAMP authorization, and API integration depth. Cost compression in the standard tier is intensifying because hyperscaler API fees erode margins for non-integrated providers. Healthcare systems and mid-market financial firms exhibit highest price sensitivity due to budget constraints, while defense contractors and intelligence agencies show lowest sensitivity given statutory security mandates.
Supply Chain Analysis
Inventory lead times for kernel-level endpoint agents extend deployment cycles, forcing vendors to maintain pre-certified software builds across multiple operating system versions. Engineering talent concentrates in the United States, Israel, and Ireland where cybersecurity specialization clusters around military and intelligence ecosystem spillovers. Component dependencies include cryptographic libraries, machine learning inference engines, and cloud-native container orchestration platforms. Single-source vulnerability runs through hyperscaler API access agreements that gate policy engine functionality. Distribution runs through direct enterprise sales teams supplemented by systems integrators for SIEM correlation deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positions. Certification requirements and switching costs lock customers into qualified vendor relationships.
For Market Incumbents: Consolidate adjacent security categories through in-house development of identity management and endpoint detection capabilities. Acquire behavioral analytics specialists before federated learning architectures fragment the insider threat detection segment. Anchor cloud-native roadmaps to hyperscaler partnership tiers that extract favorable API economics.
For New Entrants and Emerging Players: Anchor in India's captive center market where Digital Personal Data Protection Act localization requirements outpace incumbent deployment capacity. Target generative AI content scanning as the most penetrable adjacent category with minimal qualified competition. Pursue outcome-based licensing models that reward superior cloud metering infrastructure against legacy seat-license incumbents.
For Investors and Strategic Acquirers: Cloud-native specialists with FedRAMP authorization and behavioral analytics IP represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory compliance automation rather than point-solution feature depth. Watch for hyperscaler API fee restructuring as the inflection signal that compresses non-integrated vendor margins.
| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Architecture Development | Enables German automotive and French pharmaceutical firms to train models without centralizing sensitive EU data. |
| API-First Policy Engine Integration | Reduces deployment friction for Microsoft 365 and Salesforce environments dominating financial services procurement. |
| Outcome-Based Licensing Transition | Aligns vendor economics with actual data events monitored under SEC real-time disclosure mandates. |
| Regional Sovereign Cloud Deployment | Satisfies BSI and CNIL cryptographic key localization requirements for German and French enterprise buyers. |
| Behavioral Analytics Acquisition | Addresses CMMC and NIST insider threat mandates displacing signature-based detection in defense contractor accounts. |
Research Methodology
Desk research of vendor certification databases, hyperscaler API documentation, and regulatory filing precedents preceded structured interviews with CISOs, IT procurement officers, compliance directors, and systems integration specialists. Secondary validation drew from SEC cybersecurity disclosure filings, EU data protection authority enforcement actions, and cloud infrastructure capex disclosures. Bottom-up deployment estimates triangulated against top-down addressable market calculations across deployment architectures and solution types.
Variance decomposition across the projection horizon isolates growth contributions from cloud migration velocity, regulatory deadline clustering, and hybrid workforce expansion. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs were derived from fitted growth curves calibrated to procurement cycle compression observed under SEC and GDPR enforcement timelines. Forecast inputs incorporate API access fee trajectories and ISO 27001 certification pipeline data.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and hyperscaler market concentration; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Enterprise Key Management Market
Security Software
Digital Credential Management Software Market
Security Software
Cloud Intrusion Protection Software Market
Security Software
Saudi Arabia Managed Security Services Market
Security Software
Global Security Orchestration Automation and Response (SOAR) Market
Security Software
User Provisioning Software Market
Security Software
Encryption As A Service Market
Security Software
Global Digital Vehicle Forensics Market
Security Software
Global Cloud IAM Market
Security Software
GDPR Software and Tools Market
Security Software
Global Anti-Spam Software Market
Security Software
Endpoint Detection and Response [EDR] Market
Security Software
Devsecops Market
Security Software
Information Rights Management Market
Security Software
Cloud Encryption Software Market
Security Software
Online Background Check Market