
 Router and Switch Market | 2026-2036
Router and Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Router and Switch Market Outlook
The EU Cybersecurity Act is consolidating the cost-of-entry calculus for network hardware vendors seeking CE marking under the EN 303 645 baseline. Cisco Systems leverages its established certification pipeline to sustain market position across European telecom deployments. Huawei Technologies anchors its competitive stance through vertical integration into semiconductor fabrication and optical component manufacturing. Juniper Networks differentiates via specialized routing silicon optimized for AI training cluster interconnects.
Routers and switches are packet-forwarding devices that operate at Layer 2 through Layer 3 of the OSI model, with switching capacities ranging from sub-terabit chassis for enterprise access to multi-terabit spine architectures in hyperscale facilities. Their primary commercial purpose is to direct data traffic across local area networks, wide area networks, and internet backbones with deterministic latency and failover redundancy. Managed switches command premium positioning due to embedded telemetry and zero-touch provisioning capabilities demanded by cloud-native operations teams. SDN-enabled deployments represent the fastest-expanding technology segment as disaggregated control planes enable programmable traffic engineering across multi-vendor fabrics.
FCC equipment authorization rules in the United States, ETSI standards under EU regulation, and MIIT network access licensing in China collectively shape product compliance roadmaps and regional market access timelines. These frameworks mandate electromagnetic compatibility testing, security vulnerability disclosure, and supply chain provenance documentation that extend engineering cycles by quarters. Stakeholders must monitor evolving encryption export controls and data sovereignty mandates that threaten to fragment previously unified product platforms into geography-specific SKUs.
Market Dynamics
AI training cluster interconnects are forcing a generational refresh of spine-leaf architectures as hyperscale operators demand sub-microsecond latency at multi-terabit scale. This workload shift is compressing refresh cycles from five years to three while elevating silicon specialization as the primary competitive moat.
Growth Catalysts
- EN 303 645 certification mandate:The EU Cybersecurity Act's baseline requirements are accelerating replacement cycles among European telecom operators seeking CE marking for critical network infrastructure.
- Hyperscale data center construction:Facility buildouts across the United States, China, and Germany are driving concentrated procurement of 400G and 800G switching platforms.
- 5G backhaul densification:Mobile network operators are deploying cell site routers with enhanced timing synchronization to support millimeter-wave radio access networks.
Market Restraints
- Advanced node silicon scarcity:Foundry capacity constraints at 7nm and below are extending lead times for merchant switch silicon by six to nine months.
- Export control fragmentation:Encryption and semiconductor licensing restrictions are forcing product platform bifurcation into geography-specific SKUs with non-interchangeable firmware.
- Copper and rare earth price volatility:Raw material input swings are compressing gross margins on chassis-based systems with extensive backplane and connector content.
Strategic Opportunities
- India digital infrastructure buildout:TRAI's BharatNet expansion and domestic manufacturing incentives under the PLI scheme are opening captive demand for cost-optimized switching platforms.
- Convergence of optical and packet layers:Co-packaged optics integration with switch ASICs is eliminating discrete transponder shelves in metro aggregation networks.
- Edge computing micro-data centers:Distributed AI inference nodes are creating demand for fanless, extended-temperature switches with cellular backhaul integration.
Industry Challenges
- Embedded systems security engineering talent:Firmware vulnerability assessment and secure boot implementation expertise remains concentrated among a small pool of specialists.
- Multi-vendor SDN controller integration:Disaggregated control plane deployments are exposing API incompatibility and telemetry format fragmentation that stalls production cutovers.
- Common Criteria EAL4+ certification timelines:Government and defense network deployments face eighteen-month evaluation cycles that misalign with commercial product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Router and Switch Market |
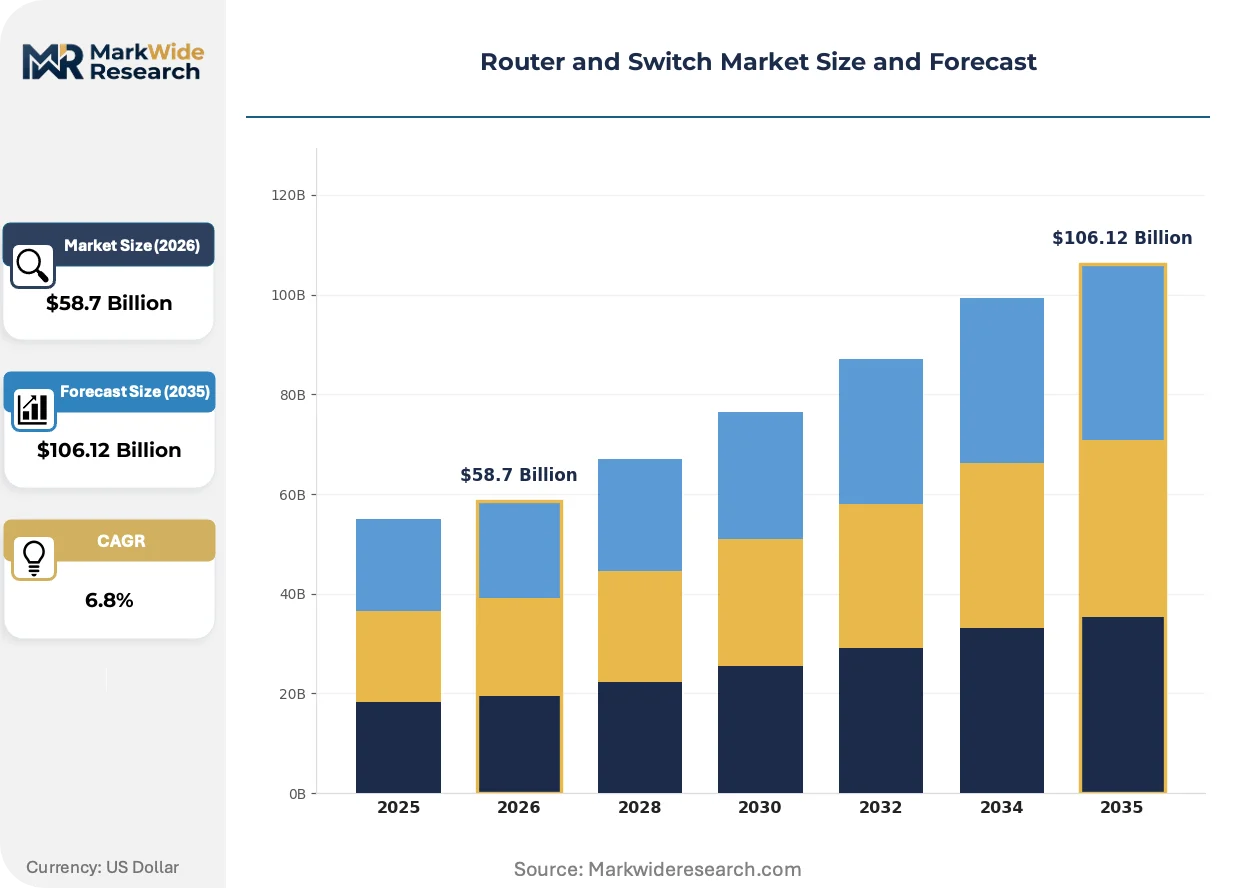
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Managed Switches, Unmanaged Switches, Layer 3 Switches, Routers Deployment Model: On-Premises, Cloud-Based, Hybrid, Virtual End User: SMEs, Large Enterprises, Data Centers, Telecom Providers Technology: Ethernet, MPLS, SDN, Wi-Fi 6 |
| Companies Covered | Cisco Systems, Huawei Technologies, Juniper Networks, Hewlett Packard Enterprise, Extreme Networks, Dell Technologies, Ericsson, Arista Networks, ZTE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Router and Switch Market Strategic Shifts
Silicon photonics co-packaging and disaggregated software stacks are dissolving traditional boundaries between optical transport and packet switching. These shifts are compressing equipment footprints while elevating programmable forwarding as the dominant architectural paradigm.
Merchant silicon switch ASICs with integrated CPO engines are decentralizing optical-electrical conversion from standalone transponder shelves into the switch fabric itself. Hyperscale operators are deploying these platforms in training clusters exceeding ten thousand nodes. This integration is decentralizing supply chain leverage away from discrete optical module vendors toward captive silicon design teams.
ETSI's forthcoming quantum-safe cryptography standards under the EU Cybersecurity Act are mandating algorithmic agility in network equipment firmware. Hardware vendors must预留 cryptographic accelerator capacity for post-quantum key exchange without performance degradation. European telecom operators are front-loading procurement specifications to ensure compliance readiness ahead of enforcement deadlines.
Hyperscale cloud operators are consolidating network equipment purchasing through direct-to-fab silicon partnerships that bypass traditional OEM channels. This disintermediation is compressing gross margins for branded hardware vendors while elevating contract manufacturing and ODM design services. The United States and China exhibit the most pronounced channel restructuring as buyer concentration accelerates.
Router and Switch Market Segmentation
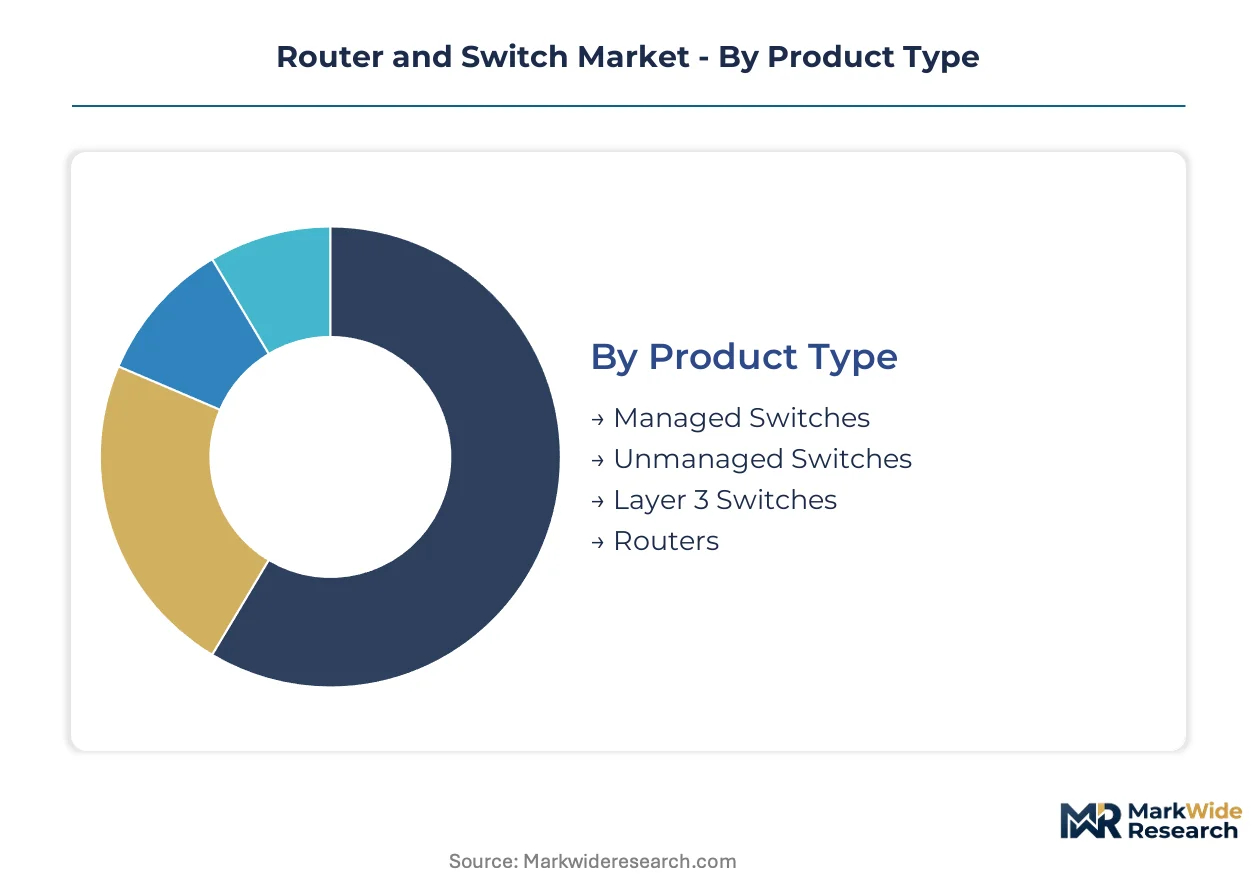
Segmentation in the router and switch market reveals divergent margin structures across hardware form factors and control plane architectures. Procurement patterns split between capex-intensive chassis deployments and opex-driven subscription models, with each quadrant demanding distinct channel strategies and certification roadmaps.
Product Type:
Volume concentrates in access-layer switches while premium margins accrue to programmable spine platforms with embedded telemetry.
- Managed Switches:These platforms embed SNMP agents, VLAN provisioning, and zero-touch configuration for cloud-native operations teams. Data center operators in the United States and Germany specify these for spine-leaf fabrics requiring real-time flow visibility. FCC equipment authorization and CE marking under EN 303 645 extend engineering cycles but sustain pricing power.
- Routers:Packet-forwarding systems operating at Layer 3 with hardware-accelerated forwarding tables and deep buffer architectures. Telecom providers across China and India deploy these for 5G backhaul and BharatNet rural aggregation where timing synchronization and deterministic latency prove critical.
- Unmanaged Switches:Fixed-configuration Layer 2 devices with plug-and-play operation for small office deployments and price-sensitive edge locations.
- Layer 3 Switches:Hybrid platforms combining wire-speed switching with inter-VLAN routing and policy-based forwarding for enterprise campus cores.
Today's leader: Managed Switches. Tomorrow's challenger: Routers.
Deployment Model:
Customer preference is bifurcating between physical appliance ownership and disaggregated control plane subscriptions.
- On-Premises:Dedicated hardware appliances with captive power and cooling, favored by financial services and defense networks requiring air-gapped operation. Common Criteria EAL4+ certification timelines in Germany and France stretch procurement cycles but lock in multi-year maintenance contracts.
- Cloud-Based:Controller-as-a-service platforms abstracting forwarding plane management across distributed sites. These configurations are climbing the fastest among retail chains and healthcare networks in the United States seeking rapid branch provisioning without truck rolls.
- Hybrid:Split control planes with local forwarding and centralized policy orchestration for regulatory compliance in data-sovereign jurisdictions.
- Virtual:Software instances running on commodity compute for NFV deployments and lab environments.
On-Premises retains the installed base. Cloud-Based is capturing greenfield expansion.
End User:
Procurement scale and technical specification authority vary dramatically across buyer archetypes.
- Data Centers:Hyperscale operators with direct-to-fab silicon partnerships and custom ASIC requirements. These buyers in the United States and China are consolidating purchasing through ODM channels that bypass traditional OEM markups.
- Telecom Providers:Incumbent carriers and mobile network operators with stringent timing synchronization and five-nines availability mandates. EU Cybersecurity Act compliance is front-loaded into RFP specifications across Germany, France, and Italy.
- Large Enterprises:Fortune 500 corporations with multi-site campus networks and SD-WAN integration requirements.
- SMEs:Mid-market organizations with standardized SKUs and value-added reseller channel dependence.
Data Centers command pricing power. Telecom Providers drive certification complexity.
Technology:
Physical layer standards and control plane protocols are converging toward programmable forwarding with optical integration.
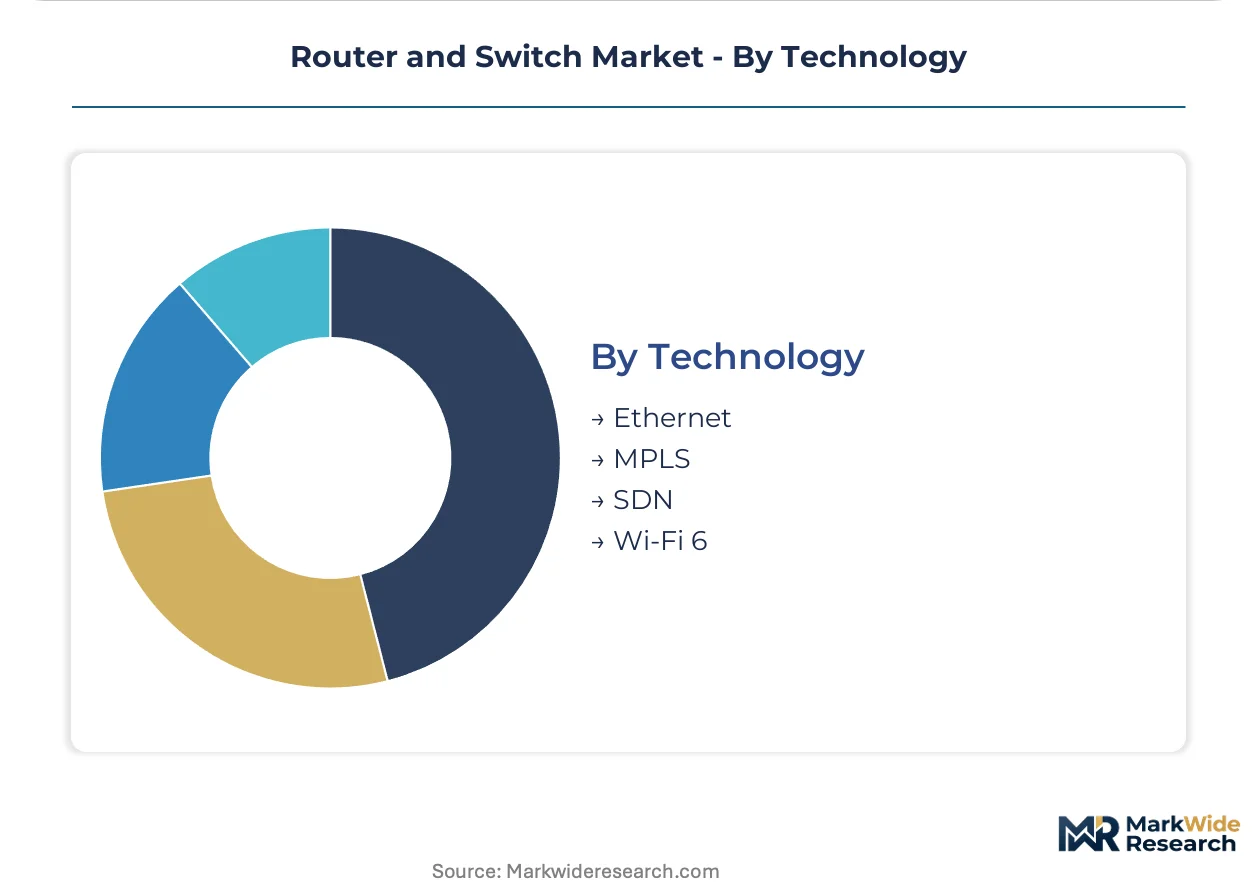
- SDN:Disaggregated control planes enabling centralized traffic engineering and intent-based networking. Hyperscale facilities in the United States and China are deploying these fabrics for AI training cluster interconnects demanding sub-microsecond latency at multi-terabit scale.
- Ethernet:Dominant Layer 2 technology with 400G and 800G SerDes now standard for spine architectures. IEEE 802.3 standards and ETSI interoperability testing shape product roadmaps across European deployments.
- MPLS:Label-switched paths for traffic engineering in carrier backbones and VPN services.
- Wi-Fi 6:Wireless access integration driving unified campus switching platforms with PoE++ power budgets.
Ethernet owns volume. SDN owns growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The router and switch industry traces its commercial origins to Silicon Valley's networking pioneers of the 1980s, with subsequent scaling through Cisco Systems' campus dominance and China's state-backed telecommunications buildouts. Infrastructure investment patterns now concentrate in five national markets where hyperscale facility construction and regulatory mandates intersect.
United States
Hyperscale data center construction in Northern Virginia, Dallas-Fort Worth, and Phoenix is driving concentrated procurement of 400G and 800G switching platforms. FCC equipment authorization rules mandate electromagnetic compatibility testing and security vulnerability disclosure that extend engineering cycles. Cloud operators in Ashburn, Virginia operate training clusters exceeding ten thousand nodes, compressing hardware refresh cycles from five years to three.
China
MIIT network access licensing governs domestic equipment deployment while state-directed AI infrastructure investment accelerates spine-leaf architecture upgrades. Dual carbon goals are reshaping facility power budgets and thermal design specifications for network hardware. The Yangtze River Delta and Pearl River Delta clusters host the majority of domestic hyperscale construction, with operators demanding sub-microsecond latency at multi-terabit scale.
Germany
EN 303 645 certification under the EU Cybersecurity Act is accelerating replacement cycles among Deutsche Telekom and Vodafone infrastructure teams. Common Criteria EAL4+ evaluation timelines stretch eighteen months, misaligning commercial product roadmaps with defense network requirements. Frankfurt's concentration of data centers and Munich's industrial automation clusters generate divergent demand profiles for enterprise versus carrier-grade equipment.
India
TRAI's BharatNet rural broadband expansion and PLI scheme manufacturing incentives are opening captive demand for cost-optimized switching platforms. CEA grid reliability standards intersect with telecom equipment deployment in heat-stressed environments. Bengaluru's software-defined networking talent pool and Hyderabad's electronics manufacturing corridor are emerging as dual poles for domestic production and engineering services.
Japan
METI's digital infrastructure investment programs support 5G backhaul densification and private 5G industrial network deployment. JIS standards and NTT procurement specifications favor equipment with enhanced timing synchronization for millimeter-wave radio access. Tokyo-Osaka corridor data centers and Nagoya's automotive manufacturing belt represent distinct buyer archetypes with divergent latency and availability requirements.
Router and Switch Market Competitive Environment
The competitive structure tilts toward integrated platform vendors with captive silicon design capabilities. Market concentration is pronounced at the hyperscale procurement tier where direct-to-fab partnerships bypass traditional OEM channels, while mid-market segments retain fragmentation across regional value-added resellers. Two strategic archetypes dominate: vertically integrated semiconductor-to-systems vendors and merchant silicon specialists with disaggregated software stacks. Competitive moves center on optical-electrical integration through co-packaged optics and geographic manufacturing diversification to mitigate export control exposure.
Among integrated platform vendors, Cisco Systems exemplifies the certification-heavy European telecom deployment archetype, while Huawei Technologies occupies a position shaped by backward integration into component manufacturing. Juniper Networks sits within the specialized routing silicon segment targeting AI training cluster interconnects. These three anchors illustrate the divergence between compliance-driven incumbent positioning and workload-optimized challenger strategies.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Juniper Networks |
| Hewlett Packard Enterprise |
| Extreme Networks |
| Dell Technologies |
| Ericsson |
| Arista Networks |
| ZTE Corporation |
| Others |
Value Chain & Pricing Dynamics
Hyperscale cloud operators with direct-to-fab silicon partnerships command pricing leverage that compresses OEM margins while elevating contract manufacturing premiums. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, performance tier, and after-sales bundling rather than raw hardware cost.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by EN 303 645 certification grade and 400G/800G port density. Cost compression in economy-tier chassis systems is intensifying because copper and rare earth price volatility squeezes backplane manufacturing margins. Telecom providers in Germany exhibit lowest price sensitivity due to eighteen-month Common Criteria EAL4+ procurement cycles, while India's BharatNet rural aggregators prioritize cost-optimized SKUs above telemetry features.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Los Angeles anchor hub-and-spoke patterns for optical module and switch ASIC fulfillment. Merchant silicon fabrication concentrates in Taiwan, South Korea, and the United States, drawing from 7nm and below foundry capacity. Copper connector backplanes and rare earth magnet components feed from Chinese and Australian mining operations. Single-source vulnerability at advanced process nodes threatens supply continuity. Distribution runs through ODM direct-ship channels for hyperscale buyers and value-added reseller networks for enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU Cybersecurity Act compliance investments and India's PLI scheme manufacturing incentives creates divergent cost structures for identical hardware platforms. Regulatory divergence rewards dual-track product strategies.
For Market Incumbents: Cement certification pipeline advantages by accelerating EN 303 645 pre-certification for next-generation spine platforms before enforcement deadlines tighten. Deepen backward integration into co-packaged optics design to offset merchant silicon margin compression from hyperscale direct-to-fab partnerships. Channel control through zero-touch provisioning ecosystems locks in telecom provider switching costs.
For New Entrants and Emerging Players: India's cost-optimized switching demand from TRAI's BharatNet expansion offers the most penetrable entry vector for fanless extended-temperature platforms. Edge computing micro-data centers with cellular backhaul integration represent adjacent white-space with lower certification barriers than hyperscale spine markets. Go-to-market execution through Hyderabad's electronics manufacturing corridor leverages domestic PLI incentives and avoids import duty exposure.
For Investors and Strategic Acquirers: Hyperscale cloud operators are the most active acquirer in this space, consolidating network equipment purchasing through captive silicon design teams and ODM equity stakes. Long-term viability hinges on optical-electrical integration capabilities rather than discrete hardware assembly. Watch for co-packaged optics adoption inflection in AI training cluster deployments exceeding ten thousand nodes as signal of merchant silicon displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-Packaged Optics Integration | Eliminates discrete transponder shelves in Deutsche Telekom metro aggregation networks. |
| EN 303 645 Pre-Certification | Accelerates Vodafone infrastructure replacement cycles ahead of EU enforcement deadlines. |
| Direct-to-Fab Silicon Partnership | Bypasses Cisco and Juniper OEM markups for Ashburn hyperscale training clusters. |
| PLI Scheme Manufacturing Localization | Captures BharatNet rural broadband procurement preferences under TRAI domestic content rules. |
| Quantum-Safe Cryptographic Agility | Reserves hardware accelerator capacity for ETSI post-quantum standards in European telecom firmware. |
Study Parameters
Bottom-up data center and telecom operator modeling reconciled against top-down semiconductor foundry and optical component tracking forms the analytical core of this study. Primary interviews with hyperscale network architects, carrier infrastructure procurement leads, ODM program managers, and firmware security engineering specialists combined with secondary validation from MIIT network access filings, FCC equipment authorization databases, ETSI interoperability test reports, and hyperscaler capex disclosures. Triangulation between deployment volume estimates and silicon wafer allocation data ensures segment-level consistency.
Historical trendline analysis of spine-leaf architecture refresh cycles and merchant switch ASIC shipment patterns anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, deployment model, end user archetype, and technology protocol. CAGRs derived from logistic diffusion curves fitted to 400G and 800G port adoption rates, adjusted for EU Cybersecurity Act compliance-driven replacement acceleration and India PLI scheme capacity buildout timelines.
Underlying measurement precision varies by segment; hyperscale data center and cloud-based deployment categories carry tighter precision than SME virtual switching estimates due to disclosure granularity differences. Forecasts reflect assumptions about foundry capacity expansion, regulatory enforcement timing, and raw material price stabilization that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global 5G Smart Antenna Market
Network Technology
Cloud Gateway Module Market
Network Technology
Optical Networking Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Industrial Wireline Networking Market
Network Technology
Global Active Network Management Market
Network Technology
Intelligent Network Management Market
Network Technology
Mobile Backhaul Market
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
MENA Wireless Routers Market
Network Technology
Mobile Accelerator Market
Network Technology
ISP Management Systems Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Sand Lane Systems Market
Network Technology
Mobile Hotspot Router Market
Network Technology
Global Carrier Wi-Fi Equipment Market