
 Global Network Management Market | 2026-2036
Global Network Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Network Management Market Foresight
Subscription-based software-defined network analytics is rebalancing what enterprises purchase, shifting capital expenditure toward recurring operational models. Cisco Systems Inc. anchors its position through deep channel control across enterprise routing infrastructure. Huawei Technologies Co Ltd competes aggressively on manufacturing scale in telecommunications-grade equipment. Nokia Corporation specializes in optical and IP portfolio breadth for service provider transformations.
Network management encompasses the systematic administration, monitoring, and optimization of data transmission infrastructure through protocols, telemetry, and policy-driven automation, typically operating across Layer 2 through Layer 7 of the OSI model with sub-50-millisecond failover requirements for carrier-grade deployments. Its primary purpose is ensuring service continuity, security posture, and resource efficiency across distributed computing environments. Cloud-based deployment is capturing the fastest expansion as enterprises abandon rigid on-premises architectures for elastic consumption. Security management applications command premium positioning due to escalating breach remediation costs and mandatory disclosure regimes.
The FCC in the United States mandates network reliability reporting for critical infrastructure operators, while GDPR and the EU AI Act impose algorithmic transparency requirements on automated network decision systems in Europe. Japan's METI promotes 5G Open RAN interoperability standards that reshape vendor qualification pathways. Stakeholders must weigh sovereign cloud mandates against interoperability costs when architecting multi-territory network operations.
Market Dynamics
Automated network orchestration platforms are compressing operational decision cycles from hours to milliseconds, forcing vendors to rearchitect software stacks around intent-based policy engines rather than manual configuration workflows.
Growth Catalysts
- EU AI Act compliance mandates:European telecommunications operators must deploy algorithmic transparency tools for autonomous network decisions, creating immediate procurement pull for explainable AI modules in orchestration software.
- 5G Open RAN interoperability standards:Japan's METI certification requirements are accelerating multi-vendor radio access network deployments that demand unified management planes across disaggregated hardware.
- Critical infrastructure reliability reporting:The FCC's mandatory outage disclosure regime for US operators is driving investment in predictive analytics platforms that preempt service degradation before threshold violations trigger regulatory filings.
Market Restraints
- Semiconductor supply concentration:Custom ASICs for telemetry processing face single-source dependency on Taiwan-based foundries, creating 18-24 month lead time volatility for high-throughput network probes.
- GDPR algorithmic audit friction:European data protection authorities require documented human oversight of automated network remediation actions, adding procedural latency to sub-50-millisecond failover requirements.
- Legacy protocol entrenchment:SNMPv2c persists in 60% of installed enterprise infrastructure, blocking native adoption of streaming telemetry standards that enable real-time analytics.
Strategic Opportunities
- India smart city network mandates:The country's urban infrastructure programs require integrated operations centers that consolidate traffic, energy, and public safety networks under unified management platforms.
- Convergence of AIOps with zero-trust architecture:Security posture verification is integrating with performance optimization engines, enabling single-pane enforcement of access policies and traffic engineering.
- Germany industrial edge certification:The country's IT security labeling framework for critical infrastructure creates preferential procurement pathways for network management vendors meeting BSI baseline protection standards.
Industry Challenges
- Intent-based networking skill scarcity:Network engineering teams lack proficiency in declarative policy languages and YAML-based infrastructure-as-code workflows, creating implementation bottlenecks for advanced orchestration deployments.
- Multi-cloud topology fragmentation:Enterprises operating across AWS, Azure, and private Kubernetes clusters face inconsistent API implementations that complicate unified visibility and cost attribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Network Management Market |
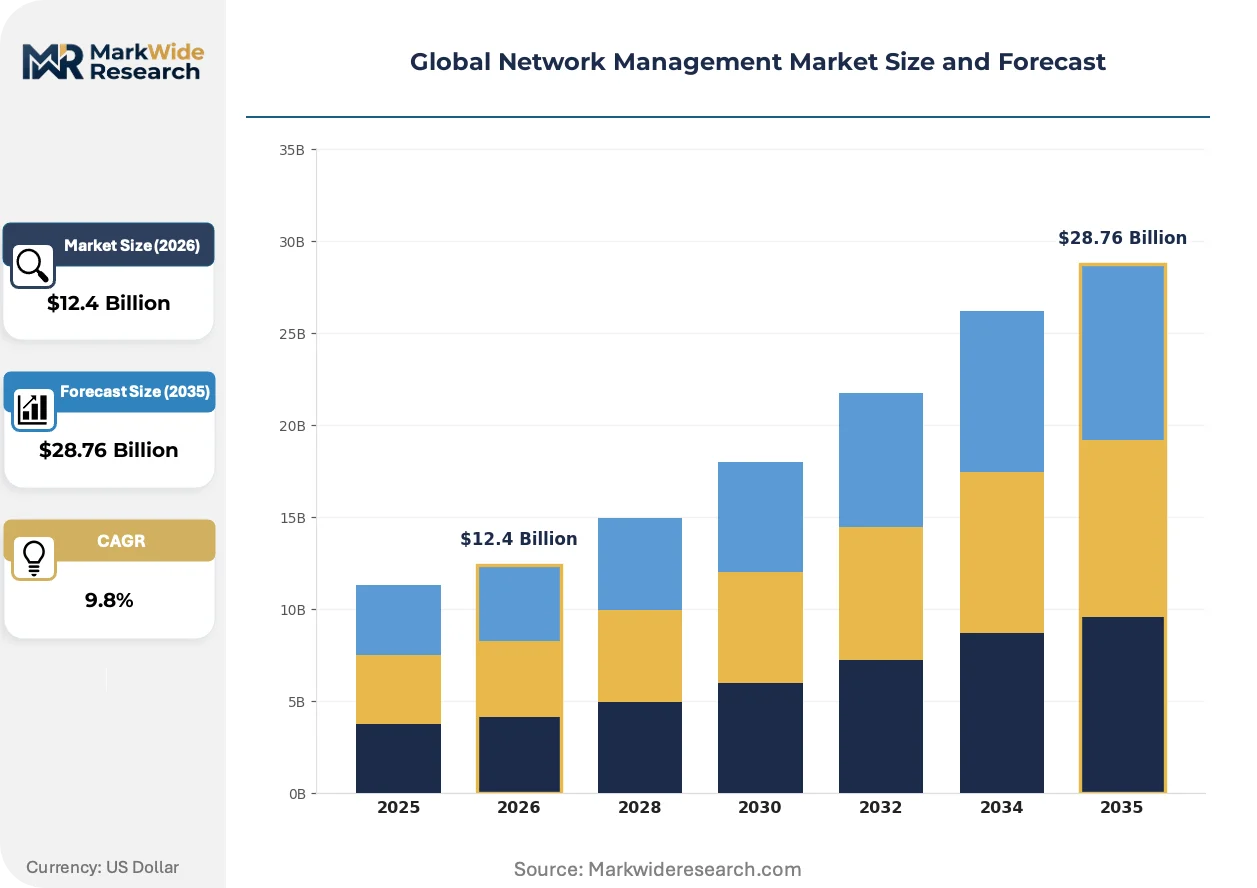
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.76 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
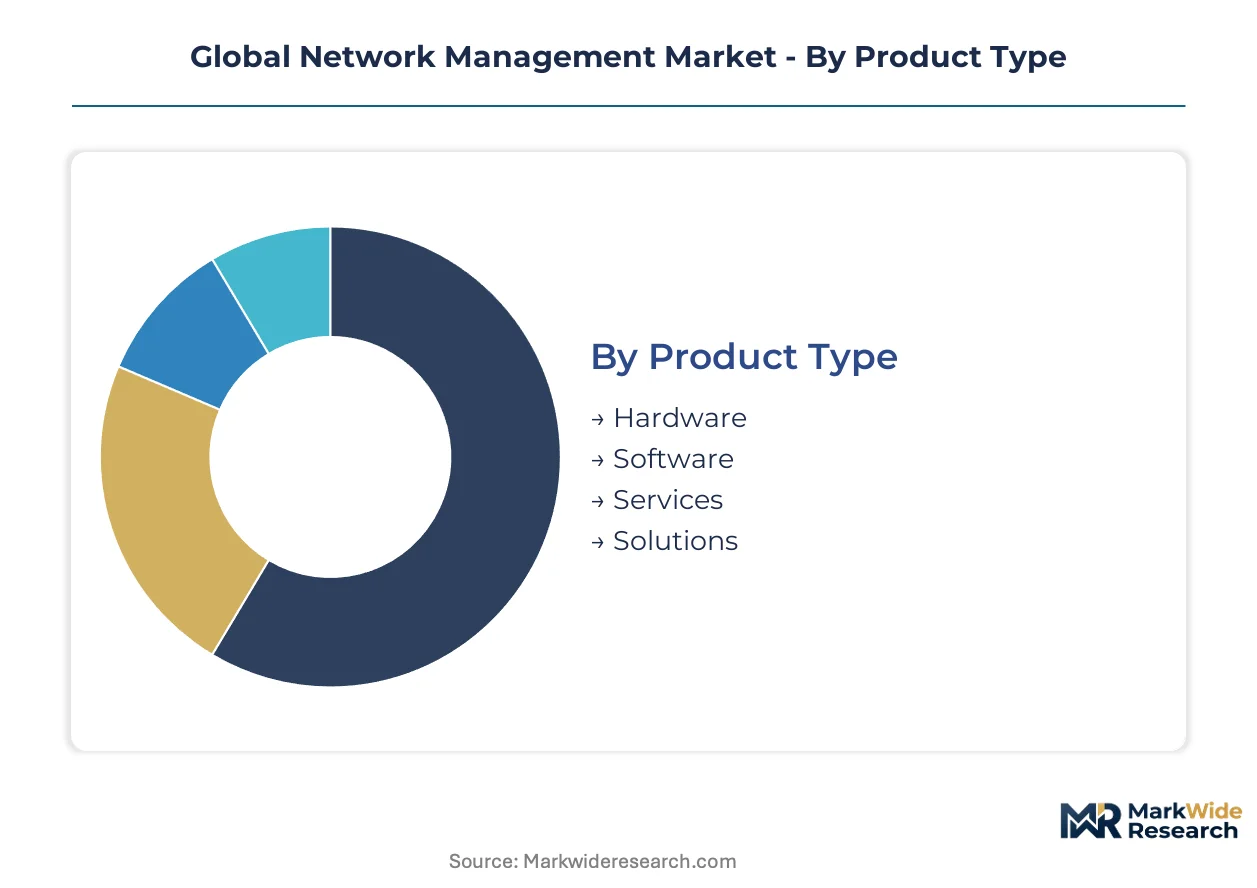
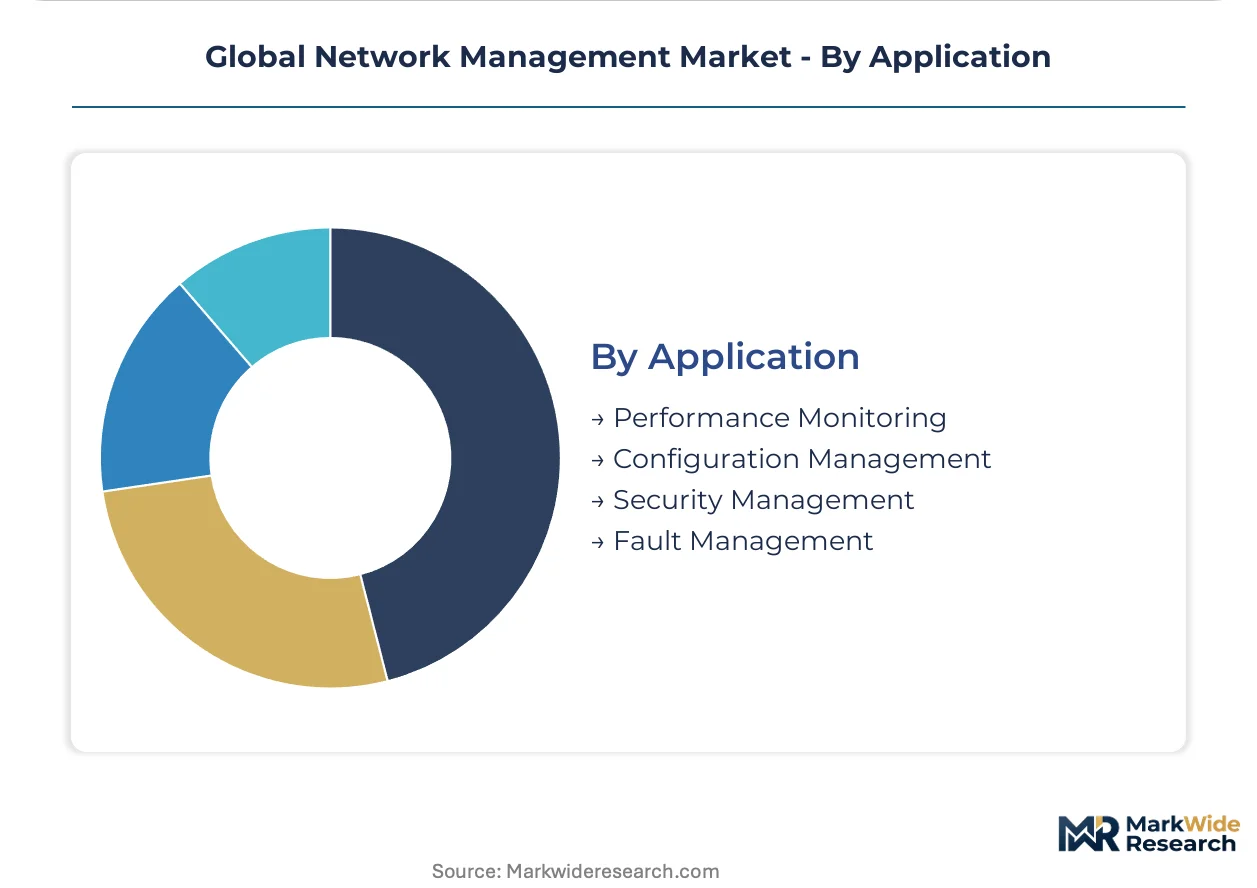
| Segmentation | Product Type: Hardware, Software, Services, Solutions Deployment: On-Premises, Cloud-Based, Hybrid, Virtual End User: Telecommunications, BFSI, Government, Education Application: Performance Monitoring, Configuration Management, Security Management, Fault Management |
| Companies Covered | International Business Machines Corporation, SolarWinds Inc., Cisco Systems Inc., Ericsson AB, NETSCOUT Systems Inc., Huawei Technologies Co Ltd, Juniper Networks Inc., Nokia Corporation, Hewlett Packard Enterprise Development LP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Network Management Market Shifts & Advancements
Streaming telemetry architectures are displacing polling-based monitoring, enabling continuous data ingestion that supports predictive models rather than reactive alerting. This shift demands new database designs and compression algorithms optimized for time-series cardinality.
Streaming telemetry using gRPC and Protocol Buffers is integrating with cloud-native observability stacks to replace SNMP polling in carrier-grade environments. Tier-1 telecommunications operators in Japan and Germany are deploying these protocols at scale for 400G backbone links. The technology is integrating network state visibility directly into CI/CD pipelines, collapsing the boundary between infrastructure operations and application deployment.
The EU AI Act's risk classification framework is mandating human-in-the-loop oversight for automated network remediation in high-availability systems. Operators must maintain audit trails of algorithmic decisions affecting service continuity. Financial services and healthcare verticals in France and Germany face the most stringent documentation requirements, driving demand for integrated compliance reporting modules.
Subscription consumption models are displacing perpetual license procurement for network analytics software. Enterprise buyers in the United States are consolidating vendor relationships through multi-year enterprise agreements that bundle hardware, software, and managed services. Manufacturing and logistics verticals show the fastest behavioral transition, motivated by balance sheet preferences for operational expenditure classification.
Global Network Management Market Segmentation
Network management procurement varies sharply by infrastructure maturity and operational risk tolerance. Enterprises replace legacy monitoring stacks on 3-5 year cycles, while telecommunications operators compress refresh windows to 18-24 months under 5G rollout pressure.
Product Type:
Replacement cycles diverge materially across product categories, with hardware refresh outpacing software adoption in established installations.
- Hardware:Telemetry probes, packet brokers, and out-of-band management appliances process 400G backbone traffic with custom ASIC architectures. Telecommunications operators in Japan and Germany dominate procurement volumes as METI and BSI certification requirements mandate carrier-grade reliability specifications.
- Software:Orchestration platforms, analytics engines, and policy controllers deploy as containerized microservices or virtual appliances. Cloud-native observability stacks in the United States absorb the steepest expansion trajectory as enterprises abandon perpetual licenses for subscription consumption.
- Services:Managed network operations, professional implementation, and training engagements address skill scarcity in intent-based networking.
- Solutions:Integrated bundles combining hardware, software, and services for specific vertical compliance requirements.
Volume placements concentrate in Hardware; the faster expansion belongs to Software.
Deployment:
Cost tier stratification separates capital-intensive on-premises builds from operational expenditure models favored by balance-sheet-conscious buyers.
- Cloud-Based:Elastic consumption models provision monitoring capacity via SaaS platforms with API-driven configuration. Financial services verticals in the United States and Germany drive premium-tier procurement under SEC and BaFin audit requirements for outsourced infrastructure visibility.
- Hybrid:Split architectures retain sensitive telemetry processing on-premises while pushing analytics to cloud substrates. Manufacturing enterprises across Japan and Germany adopt this pattern to satisfy sovereign data mandates without sacrificing scalability.
- On-Premises:Dedicated appliance deployments persist in classified government networks and air-gapped industrial control systems.
- Virtual:Software-only implementations on commodity compute eliminate hardware dependency for mid-market buyers.
Hybrid deployments capture the largest committed volumes; cloud-native adoption climbs the fastest among new implementations.
End User:
Application criticality determines procurement sophistication, with regulated verticals demanding integrated compliance modules.
- Telecommunications:Tier-1 and Tier-2 operators manage multi-vendor radio access networks, transport layers, and subscriber-facing services. Japanese operators under METI Open RAN mandates and German carriers facing EU AI Act algorithmic transparency rules drive the most complex procurement specifications.
- BFSI:Banking, financial services, and insurance institutions require sub-50-millisecond failover with immutable audit trails for transaction integrity. French and German institutions face the strictest documentation burdens under national financial regulators.
- Government:Federal, state, and municipal networks prioritize sovereign cloud compliance and supply chain attestation.
- Education:University and research networks balance open-access requirements against research data protection protocols.
Telecommunications commands the deepest volume commitments; BFSI procurement expands most quickly under mandatory disclosure regimes.
Application:
Maturity gradients separate established fault management from emerging security-performance convergence use cases.
- Security Management:Zero-trust posture verification integrates with traffic engineering for unified policy enforcement. Healthcare and financial verticals in the United States and Germany absorb premium pricing as breach remediation costs escalate and HIPAA, GDPR, and EU AI Act mandates harden.
- Performance Monitoring:Streaming telemetry architectures displace SNMP polling with gRPC and Protocol Buffers for real-time state visibility. Tier-1 telecommunications operators in Japan deploy these protocols at scale for 400G backbone instrumentation.
- Configuration Management:Infrastructure-as-code workflows and intent-based policy engines compress provisioning cycles from hours to minutes.
- Fault Management:Predictive analytics platforms preempt service degradation before threshold violations trigger regulatory filings under FCC reliability mandates.
Fault management retains the largest installed base; security management gains share fastest through zero-trust convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Network management solution production concentrates in the United States, Germany, and Japan, while consumption spreads across telecommunications operators and enterprises modernizing legacy infrastructure in these markets.
United States
FCC-mandated reliability reporting drives predictive analytics procurement among critical infrastructure operators. SEC audit requirements for financial services push cloud-native observability adoption. Silicon Valley and Northern Virginia data center clusters absorb premium-tier security management deployments under zero-trust mandates.
Germany
Industrial edge certification under BSI baseline protection standards creates preferential procurement pathways for network management vendors. EU AI Act algorithmic transparency rules reshape autonomous network decision systems. Bavaria's automotive manufacturing corridor and Frankfurt's financial hub lead 5G Open RAN management platform deployments.
Japan
METI-promoted 5G Open RAN interoperability standards accelerate multi-vendor radio access network deployments. Tier-1 telecommunications operators compress refresh windows to 18-24 months under rollout pressure. Tokyo-Osaka metropolitan clusters and Nagoya's industrial belt drive 400G backbone instrumentation with streaming telemetry protocols.
India
Smart city network mandates require integrated operations centers consolidating traffic, energy, and public safety networks. TRAI regulations shape telecommunications infrastructure modernization timelines. Bangalore's technology corridor and Mumbai's financial district anchor enterprise network transformation projects.
United Kingdom
Financial services regulators mandate immutable audit trails for transaction integrity across banking networks. GDPR compliance requirements add procedural oversight to automated remediation workflows. London's fintech cluster and Edinburgh's banking hub drive security-performance convergence procurement.
Global Network Management Market Competitive Landscape
Top-tier vendors anchor enterprise routing and telecommunications infrastructure, while specialized analytics providers and regional systems integrators fill mid-market and vertical-specific gaps. The vendor base stratifies across three layers: full-stack infrastructure platforms, cloud-native observability specialists, and managed services operators. Two strategic archetypes dominate: hardware-centric telecommunications equipment manufacturers and software-defined orchestration platforms. Competitive moves concentrate on strategic partnerships for multi-cloud visibility and portfolio diversification into zero-trust security modules.
Within the full-stack infrastructure tier, Cisco Systems Inc. and Nokia Corporation exemplify divergent geographic positioning strategies, with the former leveraging deep channel control across enterprise markets and the latter specializing in optical and IP portfolio breadth for service provider transformations. Huawei Technologies Co Ltd occupies a position shaped by manufacturing scale advantages in telecommunications-grade equipment, though regulatory friction in Western markets constrains certain deployment pathways. These three entities collectively represent the competitive tension between integrated hardware-software stacks and disaggregated, cloud-native alternatives reshaping procurement patterns.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| SolarWinds Inc. |
| Cisco Systems Inc. |
| Ericsson AB |
| NETSCOUT Systems Inc. |
| Huawei Technologies Co Ltd |
| Juniper Networks Inc. |
| Nokia Corporation |
| Hewlett Packard Enterprise Development LP |
| Others |
Supply & Pricing Matrix
Intent-based networking engineering talent concentration in Northern California and Bangalore widens pricing-tier spreads between premium-certified orchestration platforms and commodity monitoring tools, as labor-cost differentials compound with ASIC foundry access fees to stratify procurement budgets.
Pricing Analysis
Margin tightening in standard-tier software subscriptions traces to hyperscaler cloud-observability bundling and aggressive SaaS pricing from venture-backed entrants. Three-tier pricing structure across premium, standard, and economy levels separates carriers with METI certification requirements from mid-market enterprises and cost-sensitive municipal buyers. Cost-down pressure on hardware appliances accelerates because Taiwan-based foundry allocation constraints extend lead times for 400G telemetry probes. Municipal smart-city buyers in India exhibit highest price sensitivity; Tier-1 Japanese telecommunications operators absorb premium positioning with minimal negotiation leverage.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for custom ASIC telemetry processors, while value-added distributors serve mid-market enterprises with bundled professional services. Manufacturing concentrates in Taiwan for semiconductor fabrication, China for commodity appliance assembly, and Germany for BSI-certified edge equipment. Custom ASICs for 400G backbone instrumentation draw from single-source foundry relationships with TSMC and Samsung. Single-source vulnerability in Taiwan-based semiconductor fabrication creates procurement risk for carriers requiring carrier-grade reliability specifications. Distribution runs through systems integrators with METI certification credentials in Japan and BSI baseline protection accreditation in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Custom ASIC foundry capacity constraints prop pricing power for vendors with secured wafer allocation, making supply-constrained execution the defining competitive variable.
For Market Incumbents: Lock in multi-year enterprise agreements with United States financial services institutions before venture-backed observability platforms achieve SOC 2 Type II certification. Deepen backward integration into semiconductor design to reduce dependency on Taiwan-based foundry allocation cycles. Channel control through certified systems integrators remains the priority defensive lever against cloud-native disaggregators.
For New Entrants and Emerging Players: Cloud-native API-first distribution routes bypass incumbent channel gatekeeping and enable direct procurement relationships with DevOps teams at mid-market manufacturers. Target India's smart-city integrated operations centers as the most penetrable geography given fragmented incumbent presence and aggressive procurement timelines. Pursue zero-trust security convergence positioning as the differentiated go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native observability specialists given EU AI Act compliance module attach-rate expansion. Long-term viability hinges on recurring revenue concentration above hardware-refresh dependency. Watch METI Open RAN certification completion rates as the inflection signal for Japanese telecommunications procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Module Development | Algorithmic transparency tooling becomes mandatory procurement criterion for European telecommunications operators under risk-classification mandates. |
| Streaming Telemetry Protocol Integration | gRPC and Protocol Buffers deployment at Tier-1 Japanese carriers displaces SNMP polling and collapses infrastructure-application deployment boundaries. |
| Zero-Trust Security Convergence | Single-pane enforcement of access policies and traffic engineering addresses healthcare and financial vertical breach-cost escalation. |
| 5G Open RAN Management Platform Certification | METI interoperability standards in Japan and BSI baseline protection in Germany create preferential vendor qualification pathways. |
| Subscription Consumption Model Transition | Operational expenditure classification preference among United States manufacturing and logistics verticals accelerates recurring revenue capture. |
Research Methodology
Independent corroboration across network operations executives at Tier-1 telecommunications operators, chief information security officers at BFSI institutions, procurement leads at smart-city authorities, and platform engineering directors at cloud-native enterprises underwrites the qualitative findings. Secondary validation drew from FCC reliability reporting databases, METI Open RAN certification registries, EU AI Act implementation guidance documents, and SEC filings of publicly traded network infrastructure vendors. Bottom-up demand modeling and top-down market sizing triangulate volume and value estimates.
Historical reference periods spanning pre-pandemic baseline through post-5G rollout acceleration anchor the projection horizon. The analytical framework models deployment mode, organization scale, vertical compliance requirements, integration complexity, and regional regulatory cluster as segmentation dimensions. CAGRs derive from fitted growth curves against adoption-rate benchmarks and infrastructure refresh-cycle compression patterns. Forecast inputs include telecommunications operator capex disclosure trends and enterprise cloud-migration velocity indicators.
The model holds under sustained semiconductor foundry capacity expansion and stable regulatory enforcement timelines; deviation in Taiwan-based fabrication disruption or EU AI Act audit intensity escalation would shift trajectory assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Network Probe Market
Network Technology
Unified Network Management Market
Network Technology
Application Delivery Controller (ADC) Market
Network Technology
Industrial Ethernet Market
Network Technology
Global Routing Market
Network Technology
Optical Networking Market
Network Technology
Router and Switch Market
Network Technology
Mobile Hotspot Router Market
Network Technology
Optical Network Equipment Market
Network Technology
Malaysia Wireless Router Market
Network Technology
Network Devices Market
Network Technology
Global Network Monitoring Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
Global Internet Transit Market
Network Technology
Intelligent Network Management Market
Network Technology
Low-Power WAN Market