
 Wi-Fi 6E Router Market | 2026-2036
Wi-Fi 6E Router Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi 6E Router Market Insights
Taiwanese semiconductor foundries is rebalancing wafer allocation toward Wi-Fi 6E chipsets as router OEMs secure die capacity for tri-band platforms. Cisco Systems Inc. leverages its enterprise switching installed base to bundle cloud-managed Wi-Fi 6E access points. Netgear Inc. anchors the premium consumer segment through retail channel dominance in North America. TP-Link Technologies Co. Ltd. competes on manufacturing scale, sustaining cost leadership across mesh system configurations.
A Wi-Fi 6E router is a wireless networking device that operates across the 2.4 GHz, 5 GHz, and newly allocated 6 GHz spectrum bands, utilizing 160 MHz channel widths and 1024-QAM modulation to deliver multi-gigabit throughput with sub-10 millisecond latency for high-density environments. Its primary purpose is to relieve spectrum congestion in enterprise, educational, and residential settings where legacy 802.11ac infrastructure cannot support concurrent 4K video, AR/VR, and IoT device loads. Enterprise routers command the deepest margin pools as CIOs prioritize WPA3-Enterprise security and SD-WAN integration over unit cost. Mesh systems represent the fastest-growing product architecture, displacing standalone range extenders in residential deployments where whole-home coverage has become the baseline expectation.
The FCC governs 6 GHz unlicensed access through its Part 15 rules, while the EU's Radio Equipment Directive mandates CE marking for harmonized spectrum use across member states. Japan's MIC has allocated portions of the 6 GHz band, with METI coordinating industrial IoT pilot programs that specify Wi-Fi 6E for factory automation backhaul. Stakeholders must monitor whether India's WPC extends 6 GHz liberalization beyond trial licenses, as that determination will unlock or delay one of the largest remaining addressable populations.
Market Dynamics
Tri-band silicon allocation decisions at Taiwanese foundries are compressing lead times for router OEMs while simultaneously concentrating supply risk in a single manufacturing geography. This supply-side concentration shapes competitive positioning more than demand variability.
Growth Catalysts
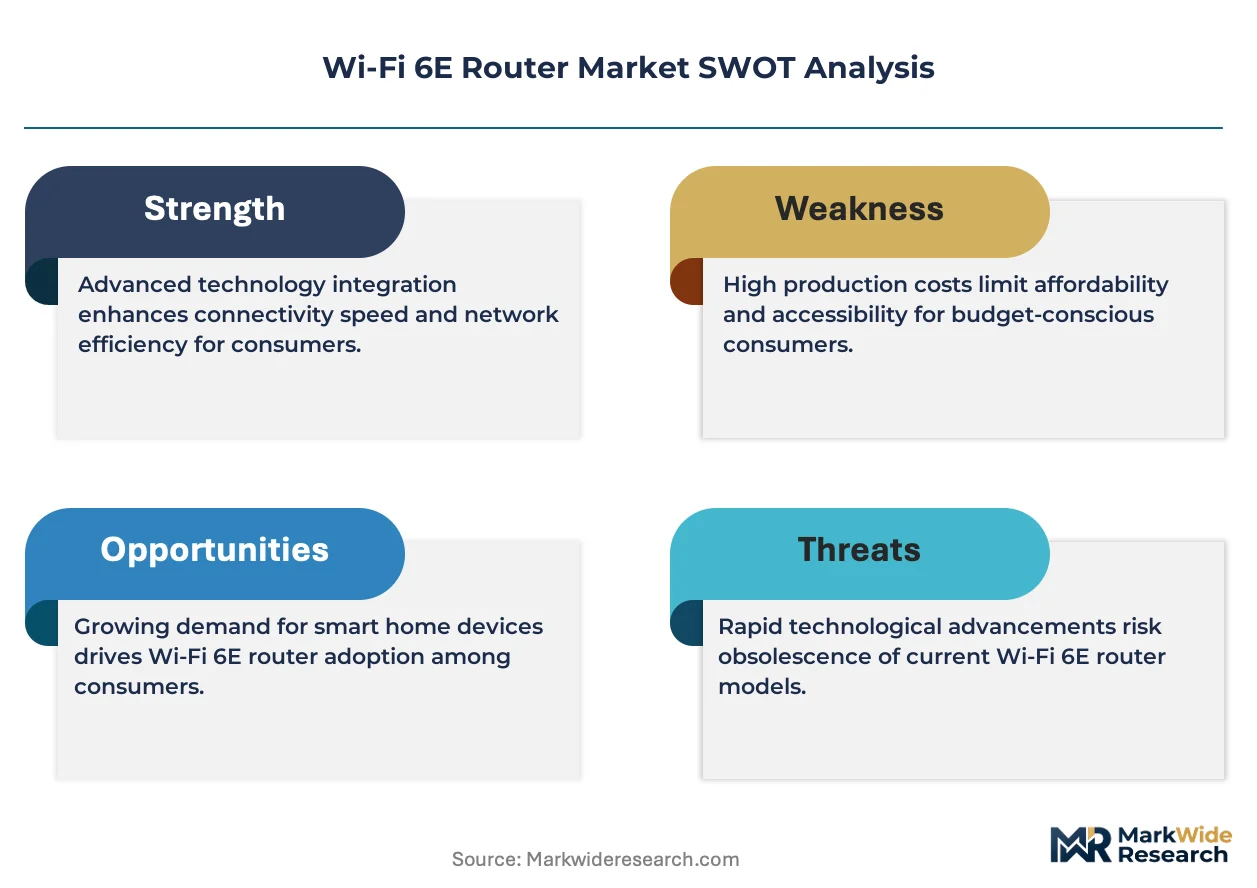
- 6 GHz spectrum liberalization:The FCC's Part 15 rules unlicensed the 6 GHz band, triggering regulatory emulation across developed economies and expanding addressable spectrum for high-density deployments.
- Enterprise IoT density:Factory automation backhaul requirements in Japan's METI-coordinated pilot programs specify Wi-Fi 6E for sub-10 millisecond latency in industrial settings.
- Mesh architecture preference:Residential buyers are displacing standalone range extenders with whole-home coverage systems, elevating average selling prices and attachment rates for tri-band configurations.
Market Restraints
- Wafer allocation concentration:Foundry capacity for Wi-Fi 6E chipsets concentrates at TSMC and Samsung, creating single-source vulnerability for router OEMs during supply shocks.
- Legacy infrastructure substitution:Enterprise CIOs face switching costs from embedded 802.11ac access points, delaying refresh cycles despite performance gaps.
- Regulatory fragmentation:India's WPC maintains trial-license restrictions on 6 GHz commercial use, withholding one of the largest remaining subscriber populations from full market access.
Strategic Opportunities
- Educational campus modernization:K-12 and university IT departments in the United States are consolidating networking budgets toward cloud-managed tri-band infrastructure for hybrid learning environments.
- EU harmonization tailwind:The Radio Equipment Directive's CE marking framework is reducing cross-border certification friction for mesh system vendors targeting pan-European retail distribution.
- AR/VR throughput requirements:Meta's enterprise VR deployments and Apple's spatial computing initiatives are creating specification pull for 160 MHz channel widths in commercial real estate.
Industry Challenges
- RF engineering talent scarcity:Tri-band antenna design and thermal management for 6 GHz operation require specialized skills that outpace university pipeline output.
- Interoperability certification delays:Wi-Fi Alliance certification queues for WPA3-Enterprise and EasyMesh compliance extend product launch timelines by fiscal quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi 6E Router Market |
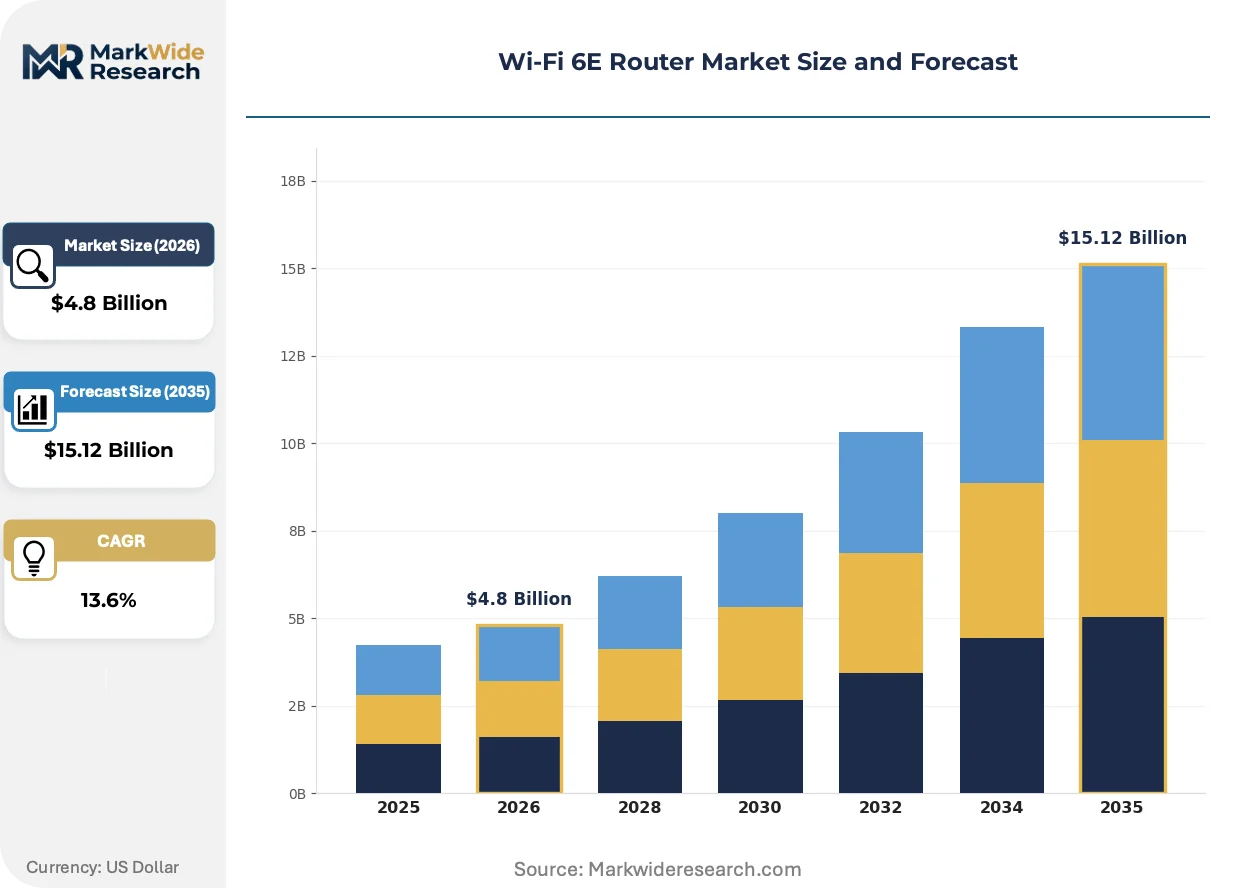
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.12 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Routers, Enterprise Routers, Mesh Systems, Range Extenders End User: Residential Users, Small Offices, Large Enterprises, Educational Institutions Technology: Multi-User MIMO, OFDMA, Beamforming, Security Protocols Deployment: Indoor, Outdoor, Hybrid, Cloud-Managed |
| Companies Covered | Cisco Systems Inc., TP-Link Technologies Co. Ltd., Netgear Inc., Huawei Technologies Co. Ltd., Broadcom Inc., Intel Corporation, AsusTek Computer Inc., Hewlett Packard Enterprise, Linksys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi 6E Router Market Trends and Innovations
Cloud-native network management is absorbing operational responsibilities previously held by on-premises controllers, compressing enterprise IT headcount requirements while elevating recurring revenue attachment rates for infrastructure vendors.
Multi-user MIMO with 16 spatial streams is absorbing backhaul capacity demands in high-density venues. Convention centers and sports stadiums in the United States are deploying these configurations during 2024-2025 renovation cycles. The technology is absorbing what would otherwise require fiber pulls to every access point, reducing capital intensity for brownfield deployments.
The EU's Radio Equipment Directive is mandating cybersecurity baseline requirements for wireless equipment placed on the single market. Manufacturers must demonstrate secure boot processes and firmware update mechanisms to obtain CE marking. German and French enterprise distributors are prioritizing compliant SKUs in procurement frameworks, compressing shelf space for legacy-certified inventory.
Enterprise buyers are consolidating vendor relationships around switching-access point bundles, displacing best-of-breed procurement for standalone wireless hardware. Value-added distributors in North America are responding with managed service wrappers that unbundle hardware margin from deployment labor. This pattern is most visible in healthcare verticals where HIPAA compliance documentation requirements favor single-vendor accountability structures.
Wi-Fi 6E Router Market Segmentation
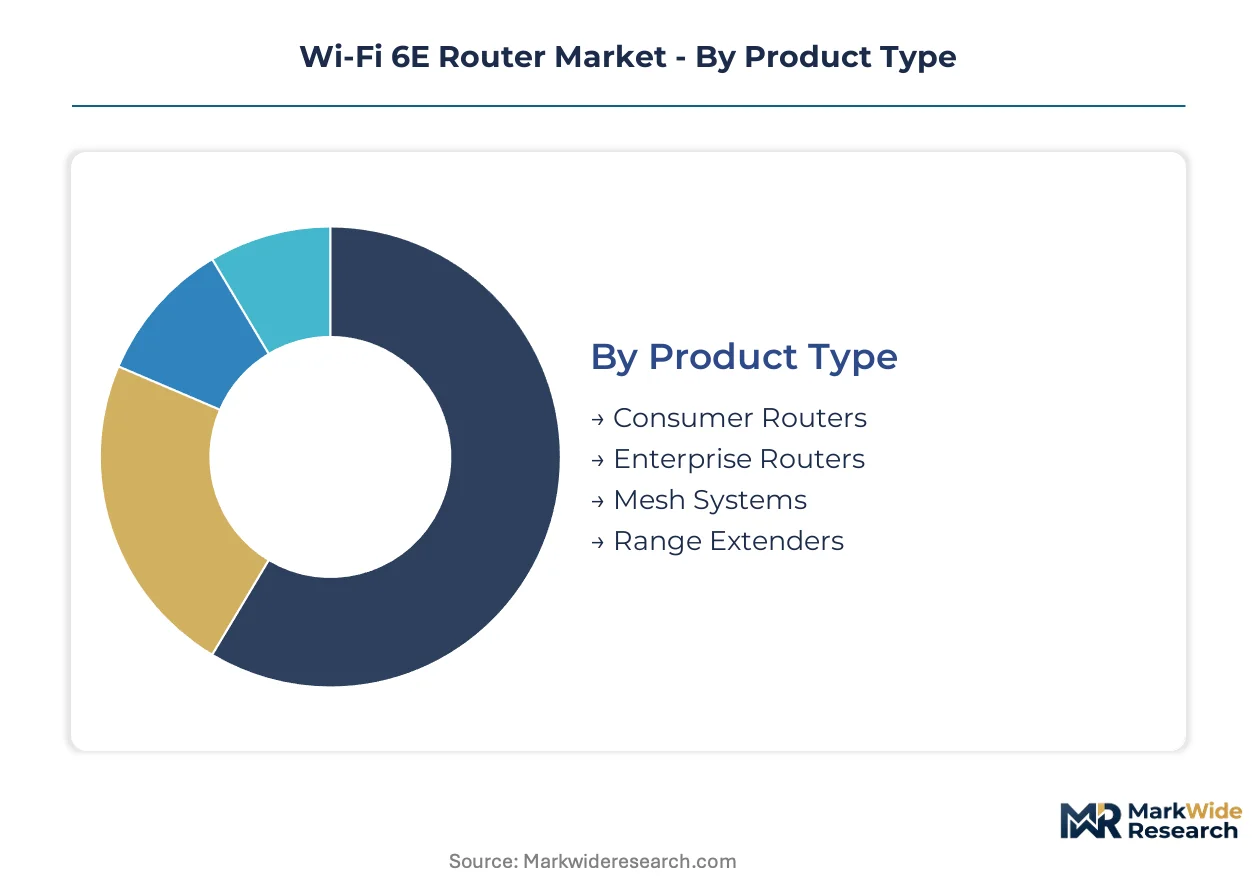
Wi-Fi 6E router segmentation reveals how certification requirements, spectrum licensing, and deployment complexity fragment procurement patterns across buyer types. Each dimension carries distinct regulatory burdens that shape vendor go-to-market strategies and pricing architecture.
Product Type:
Certification pathways diverge sharply across product categories, with enterprise-grade hardware requiring WPA3-Enterprise validation and FCC Part 15 testing that consumer SKUs bypass entirely.
- Consumer Routers:Standalone tri-band units targeting residential throughput demands carry CE marking for EU retail and FCC authorization for North American distribution. Demand concentrates in US suburban markets where 6 GHz spectrum availability preceded commercial rollout elsewhere.
- Enterprise Routers:Rack-mounted or ceiling-deployed access points integrate SD-WAN controllers and captive portal authentication, requiring Common Criteria certification for federal deployments and PCI-DSS validation for retail environments. CIO procurement frameworks prioritize these units for campus refresh cycles despite switching costs from embedded 802.11ac infrastructure.
- Mesh Systems:Multi-node configurations with dedicated backhaul radios are displacing standalone range extenders in whole-home coverage scenarios. These systems require coordinated FCC certification across node clusters, elevating compliance costs that concentrate in premium retail channels.
- Range Extenders:Single-band or dual-band repeaters lacking native 6 GHz support face shrinking addressable markets as mesh architectures absorb residential expansion demand.
Enterprise Routers sits at the top of the volume ranking, with Mesh Systems climbing the fastest.
End User:
Cost tier stratification separates residential self-installation from enterprise managed services, with educational institutions occupying a hybrid procurement zone between capital budgets and operating leases.
- Residential Users:Retail-purchased units dominate this segment, with buyers prioritizing ease of setup over advanced security features. North American households lead adoption curves where 6 GHz device penetration supports tri-band utilization.
- Small Offices:Professional services firms and medical practices require HIPAA-compliant configurations with guest network isolation. These buyers favor cloud-managed SKUs that reduce on-site IT headcount.
- Large Enterprises:Campus-scale deployments with thousands of access points command the deepest margin pools. Factory automation backhaul in Japan's METI-coordinated programs specifies Wi-Fi 6E for sub-10 millisecond latency, pulling specification requirements from industrial IoT density.
- Educational Institutions:K-12 and university IT departments in the United States consolidate networking budgets toward cloud-managed tri-band infrastructure for hybrid learning environments, with E-Rate funding eligibility shaping vendor selection.
Large Enterprises captures the largest revenue concentration, with Educational Institutions expanding most quickly.
Technology:
Implementation maturity varies across technical foundations, with silicon availability and RF engineering talent scarcity constraining deployment of advanced spatial stream configurations.
- Multi-User MIMO:16 spatial stream configurations absorb backhaul capacity demands in high-density venues. Convention centers and sports stadiums in the United States deploy these during renovation cycles, reducing fiber pull requirements for brownfield access point placement.
- OFDMA:Sub-channel resource allocation enables concurrent low-latency and high-throughput traffic on identical spectrum. This technology supports IoT sensor density in smart building deployments without degrading video conferencing quality.
- Beamforming:Explicit beamforming with sounding frames improves signal-to-noise ratios at range, particularly valuable for outdoor deployments and warehouse environments with obstructed line-of-sight.
- Security Protocols:WPA3-Enterprise with 192-bit cryptographic suites and Wi-Fi Enhanced Open for public networks represent baseline requirements for regulated verticals. Certification queues for these protocols extend product launch timelines.
Multi-User MIMO dominates current shipment volumes, with OFDMA gaining share fastest among new infrastructure deployments.
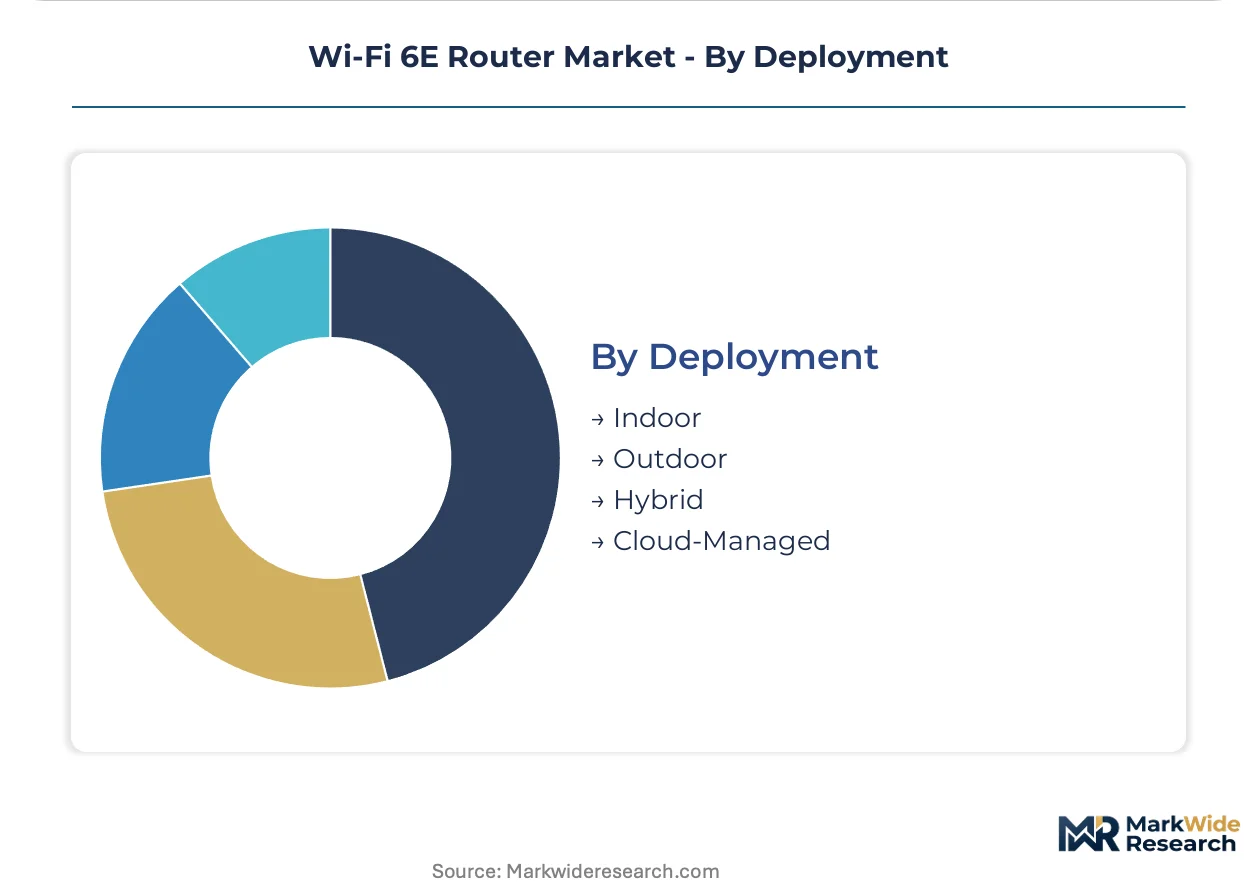
Deployment:
Geographic deployment patterns reflect climate resilience requirements and spectrum propagation characteristics that vary between indoor drywall penetration and outdoor weather exposure.
- Indoor:Enterprise ceiling-mounted and residential desktop configurations constitute the installed base majority. These deployments prioritize thermal management for continuous 6 GHz operation in climate-controlled environments.
- Outdoor:IP67-rated enclosures with directional antennas serve stadium concourses, parking structures, and campus quads. These units require additional FCC certification for maximum permissible exposure compliance.
- Hybrid:Mixed indoor-outdoor architectures with unified management planes support distributed enterprise footprints. Retail chains and healthcare systems favor this approach for consistent policy enforcement across property boundaries.
- Cloud-Managed:Controller-less architectures with zero-touch provisioning absorb operational responsibilities previously held by on-premises hardware. This deployment model elevates recurring revenue attachment rates for infrastructure vendors while compressing enterprise IT headcount requirements.
Indoor deployment maintains volume leadership, with Cloud-Managed configurations showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are concentrating Wi-Fi 6E router assembly in jurisdictions where FCC Part 15 alignment reduces certification friction for North American export. Taiwanese foundries exploit this compliance-cost gap while OEMs site final integration in Mexico and Vietnam to preserve margin.
United States
Enterprise campus refreshes and stadium renovation cycles absorb tri-band access point volumes. The FCC's Part 15 rules govern 6 GHz unlicensed access, with recent equipment authorization database expansions accelerating commercial deployment. Dallas-Fort Worth metroplex hosts multiple cloud-managed networking headquarters where vendor engineering teams coordinate federal procurement frameworks.
China
Domestic smart building deployments and industrial IoT backhaul specifications pull silicon demand despite export control complexities. MIIT spectrum allocations for 6 GHz remain in trial phase, constraining native market scale. Shenzhen manufacturing clusters concentrate PCB assembly and antenna calibration for global OEM supply chains.
Germany
Industrial automation requirements in automotive and precision manufacturing specify low-latency wireless backhaul. The EU Radio Equipment Directive mandates CE marking with cybersecurity baseline requirements, elevating compliance costs for non-EU suppliers. Bavaria's Munich-Stuttgart corridor hosts systems integrators bundling Wi-Fi 6E with factory digitalization contracts.
Japan
METI-coordinated pilot programs for factory automation explicitly specify Wi-Fi 6E for sub-10 millisecond latency applications. MIC spectrum allocations cover designated 6 GHz portions, with commercial rollout trailing US timing by 18-24 months. Nagoya industrial clusters anchor equipment qualification programs for robotics and semiconductor fabrication facilities.
India
Educational institution networking budgets and hybrid learning infrastructure create procurement pull for cloud-managed tri-band systems. WPC maintains trial-license restrictions on 6 GHz commercial use, withholding full market access pending spectrum liberalization determination. Bengaluru IT corridors host vendor technical support centers serving South Asian deployment requirements.
Wi-Fi 6E Router Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native management overlays and vertical-specific certification bundles. The vendor base stratifies across three tiers: semiconductor foundries supplying tri-band chipsets, systems OEMs integrating radio modules, and cloud-managed service platforms abstracting hardware operations. Strategic archetypes include foundry-dependent integrators, switching-access point bundlers, and subscription-revenue platform operators. Competitive moves concentrate on M&A for SD-WAN integration capabilities and strategic partnerships with educational procurement frameworks.
Within the enterprise networking tier, Cisco Systems Inc. and Hewlett Packard Enterprise exemplify switching-access point bundlers leveraging installed base relationships. TP-Link Technologies Co. Ltd. occupies a scale-driven position across consumer and small-office mesh configurations. Netgear Inc. anchors premium residential positioning through retail channel presence in North American markets.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| TP-Link Technologies Co. Ltd. |
| Netgear Inc. |
| Huawei Technologies Co. Ltd. |
| Broadcom Inc. |
| Intel Corporation |
| AsusTek Computer Inc. |
| Hewlett Packard Enterprise |
| Linksys |
| Others |
Pricing and Supply Chain Analysis
Enterprise CIO consolidation around switching-access point bundles is forcing router OEMs to absorb channel margin compression while maintaining die allocation commitments at Taiwanese foundries. This procurement pattern concentrates pricing power with systems integrators bundling cloud-managed infrastructure, squeezing standalone hardware margins across tri-band configurations.
Pricing Analysis
Distributor margin layers in North American enterprise channels absorb 15-25 point markups before federal procurement frameworks apply volume discounts. Three-tier pricing structure across premium, standard, and economy levels separates WPA3-Enterprise certified units from retail consumer SKUs and trial-license inventory for restricted markets. Pricing pressure stems from educational institution E-Rate funding eligibility requirements that prioritize cost-per-port metrics over performance specifications. Small offices and residential buyers exhibit highest price sensitivity, while federal and healthcare verticals prioritize security certification over unit cost.
Supply Chain Analysis
Returns and refurbishment flows for enterprise access points create secondary market supply that competes with new unit sales in cost-constrained educational segments. Tri-band chipset fabrication concentrates in Taiwan and South Korea, with final assembly migrating to Mexico and Vietnam for FCC-aligned export efficiency. Raw material dependencies span GaAs RF components, high-layer-count PCBs, and thermal interface materials for 6 GHz operation. Single-source vulnerability at TSMC and Samsung foundries represents the dominant structural risk. Distribution runs through value-added distributors in North America and pan-European retail channels for consumer mesh systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wi-Fi 6E router market functions as a stable compounder anchored by spectrum liberalization waves that refresh infrastructure on predictable regulatory cycles rather than discretionary technology adoption.
For Market Incumbents: Acquire cloud-native network management platforms to bundle subscription revenue with hardware refresh cycles. Cisco Systems Inc. and Hewlett Packard Enterprise should deepen SD-WAN integration capabilities to defend switching-access point bundling relationships against best-of-breed wireless specialists. Certification investment in WPA3-Enterprise and EasyMesh compliance creates switching costs that delay enterprise churn. For New Entrants and Emerging Players: Educational procurement frameworks offer the most penetrable entry vector for cloud-managed tri-band systems, with E-Rate funding eligibility reducing customer acquisition friction. India's WPC trial-license environment presents white-space opportunity for vendors pre-positioning technical support infrastructure ahead of spectrum liberalization. Channel partnerships with value-added distributors bundling managed service wrappers accelerate enterprise footprint without direct sales force investment. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor foundries capturing wafer allocation premiums during supply-constrained periods. The five-to-ten year viability window favors subscription-revenue platform operators over hardware-centric integrators due to recurring revenue attachment rates and compressed customer acquisition costs. Monitor India's WPC spectrum liberalization determination and EU Radio Equipment Directive cybersecurity enforcement as inflection indicators for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Management Platform Acquisition | Absorbs operational responsibilities previously held by on-premises controllers, elevating recurring revenue at Cisco and HPE. |
| WPA3-Enterprise Certification Investment | Creates procurement switching costs in federal and healthcare verticals requiring Common Criteria validation. |
| Educational Procurement Framework Partnership | E-Rate funding eligibility shapes vendor selection for K-12 and university IT departments consolidating networking budgets. |
| Taiwanese Foundry Die Allocation Commitment | Secures tri-band chipset supply during periods of wafer capacity constraint at TSMC and Samsung. |
| EU Cybersecurity Baseline Compliance | Mandatory secure boot and firmware update mechanisms for CE marking compress shelf space for legacy-certified inventory. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with router OEM product managers, enterprise IT procurement officers, value-added distributor channel leads, and Taiwanese foundry supply planners with secondary validation against FCC equipment authorization databases, Wi-Fi Alliance certification records, SEC 10-K infrastructure disclosures, and EU Radio Equipment Directive implementation guidance. Bottom-up shipment estimates by product category and end-use segment triangulated against top-down addressable spectrum deployment models.
Segment-weighting approaches distributed volume and value across consumer, enterprise, mesh system, and range extender product types, further stratified by residential, small office, large enterprise, and educational institution end-users. Technology dimensions including Multi-User MIMO, OFDMA, beamforming, and security protocol implementations were modeled across indoor, outdoor, hybrid, and cloud-managed deployment architectures. CAGRs derived from infrastructure refresh cycle analysis and spectrum availability timelines across the projection horizon, with inputs from semiconductor wafer allocation forecasts and regulatory determination schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to foundry capacity allocation decisions, India's WPC spectrum liberalization timing, and EU cybersecurity enforcement intensity. Practitioners should monitor FCC Part 15 equipment authorization database expansion rates, TSMC and Samsung capex disclosures for Wi-Fi 6E die capacity, and educational institution E-Rate funding appropriations for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Network Management Solutions Market
Network Technology
Global Cloud Managed Wi-Fi Market
Network Technology
5G Enterprise Private Network Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
Managed MPLS Market
Network Technology
Global Deep Packet Inspection and Processing Market
Network Technology
Passive Optical LAN (POL) Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
MENA Wireless Routers Market
Network Technology
Global Network Monitoring Market
Network Technology
Open RAN Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Self-Healing Networks Market
Network Technology
IT Connector Market
Network Technology
Microduct Market
Network Technology
Global Network Switches Market