
 Hong Kong Data Center Rack Market | 2026-2036
Hong Kong Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Data Center Rack Market Insights
Data center infrastructure engineering talent scarcity is reorganizing vendor priorities across Hong Kong. Schneider Electric SE anchors its position through deep manufacturing scale in thermal-integrated enclosures. Rittal GmbH & Co. KG differentiates via precision-modular steel framing systems designed for high-density GPU clusters. Vertiv Group Corp. competes on power-distribution integration within rack units.
Hong Kong data center racks are standardized metal enclosure systems, typically fabricated from cold-rolled steel with static load ratings exceeding 1,500 kg, designed to house servers, switches, and power distribution units in controlled environments. Their primary purpose is spatial organization, thermal management facilitation, and physical security for IT hardware in facilities where floor space commands premium lease rates. Enclosed rack configurations dominate current procurement as hyperscale tenants prioritize aisle containment and fire suppression integration. Edge data center deployment models represent the fastest-expanding segment as latency-sensitive financial trading and content delivery networks push compute closer to urban demand nodes.
Hong Kong's Office of the Communications Authority enforces telecommunications facility standards that directly specify rack-level electromagnetic compatibility and structural loading certifications for licensed operators. The Electrical and Mechanical Services Department mandates IEC 61439 compliance for low-voltage switchgear assemblies housed within rack enclosures, elevating product qualification barriers for imported equipment. Building Energy Codes administered by the Electrical and Mechanical Services Department increasingly reference rack-level power usage effectiveness metrics, pressuring operators to specify higher-efficiency containment architectures. Stakeholders must weigh whether to prioritize modular factory-integrated rack-and-power systems against site-built custom configurations as land scarcity intensifies and vertical build costs escalate.
Market Dynamics
Data residency mandates under Hong Kong's Personal Data Privacy Ordinance are forcing financial institutions to expand captive colocation capacity, compressing procurement timelines for certified rack systems while concentrating demand in Kwai Chung and Tseung Kwan O cable landing zones.
Growth Catalysts
- PDPO Compliance Pressure:Hong Kong's data localization rules compel banks and insurers to maintain onshore infrastructure, driving rack procurement for compliant colocation builds.
- Submarine Cable Density:Eleven active subsea cable systems land in Tseung Kwan O, creating latency arbitrage opportunities that reward rack deployment in adjacent facilities.
- GPU Cluster Density:AI training workloads in financial modeling and algorithmic trading now demand 30-50 kW per rack, forcing enclosure upgrades with enhanced thermal management.
Market Restraints
- Land Scarcity Premium:Industrial zoned land in Hong Kong commands lease rates exceeding Singapore and Tokyo, elevating total cost of ownership for rack deployments.
- Steel Input Volatility:Cold-rolled steel prices fluctuate with mainland Chinese supply disruptions, compressing margin predictability for enclosure fabricators serving the territory.
- Import Certification Friction:Electrical and Mechanical Services Department mandates IEC 61439 compliance for switchgear assemblies, extending qualification timelines for non-local suppliers.
Strategic Opportunities
- Edge Micro-Sites:Latency-sensitive securities trading and content delivery networks are creating demand for sub-1MW facilities in Central and Kowloon commercial districts.
- Modular Factory Integration:Pre-integrated rack-and-power systems shipped from regional manufacturing hubs reduce on-site labor requirements and accelerate deployment in vertical builds.
- Building Energy Code Alignment:Rack-level power usage effectiveness metrics now factor into EMSD compliance pathways, creating specification advantages for high-efficiency containment architectures.
Industry Challenges
- Thermal Engineering Talent Gap:Hong Kong produces fewer than 200 mechanical engineering graduates annually with data center specialization, forcing operators to recruit from Singapore and Australia.
- Vertical Build Complexity:High-rise data center construction requires structural reinforcement for 1,500+ kg static rack loads, extending project timelines and coordination with Buildings Department.
Report Scope
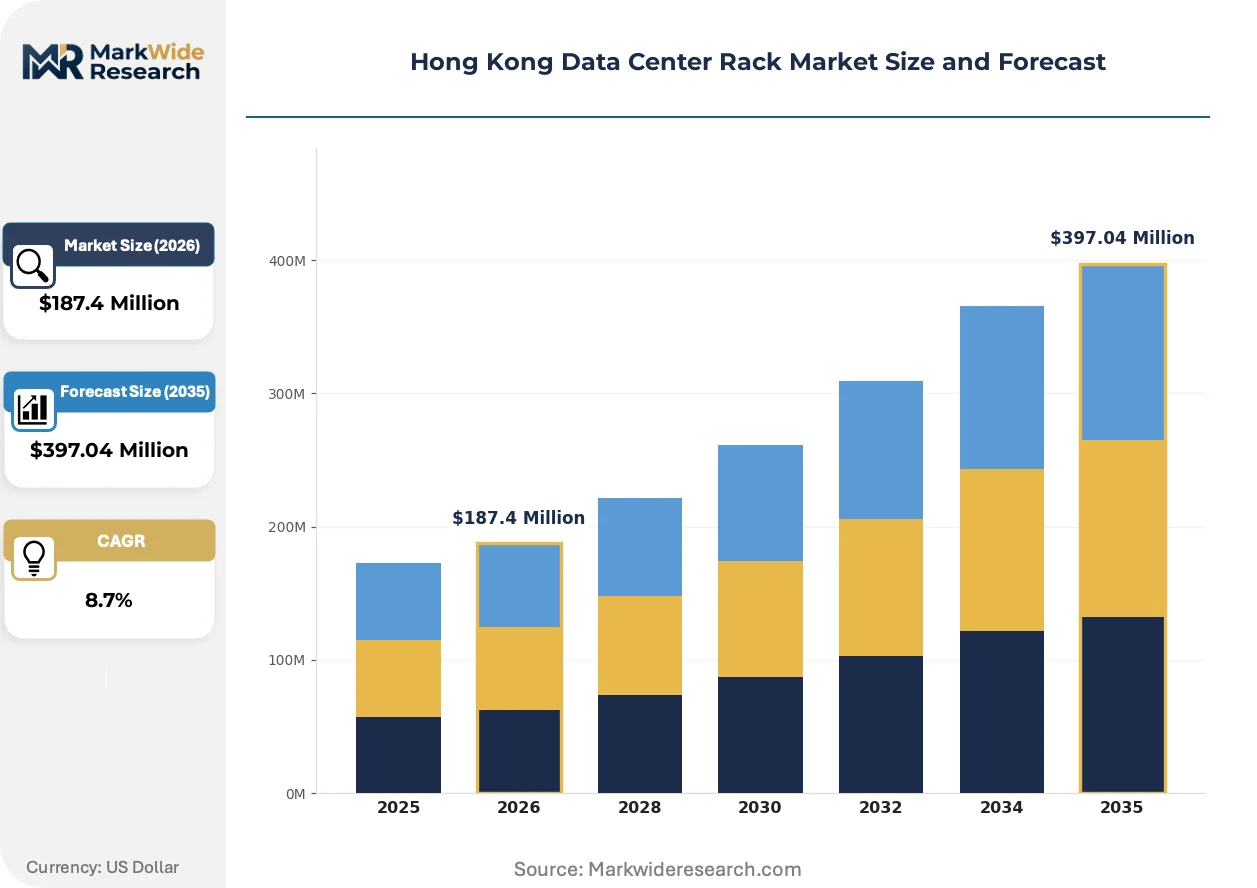
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Data Center Rack Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Rack, Wall-Mounted Rack, Heavy-Duty Rack Deployment Model: On-Premise, Colocation, Edge Data Centers, Hybrid Cloud End User: Telecommunication, IT Service Providers, BFSI, Healthcare Power Rating: 1U, 2U, 4U, 8U |
| Companies Covered | Rittal GmbH & Co. KG, Chatsworth Products, Vertiv Group Corp., Legrand Group, ABB Ltd, Schneider Electric SE, Delta Electronics Inc., Fujitsu Limited, Eaton Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Data Center Rack Market Trends and Innovations
Liquid cooling integration and intelligent power distribution are restructuring rack architecture specifications as density thresholds breach air-cooling limits. Procurement patterns favor factory-integrated systems over site-built configurations.
Direct-to-chip liquid cooling is displacing traditional perimeter CRAC architectures in Hong Kong facilities hosting NVIDIA H100 clusters. Hyperscale tenants now specify cold-plate manifolds and rear-door heat exchangers as standard rack features. This technology shift is compressing the addressable market for air-side containment specialists while elevating thermal engineering capabilities to primary vendor selection criteria.
EMSD Building Energy Codes now reference rack-level PUE measurement as a compliance pathway for licensed telecommunications facilities. Operators must demonstrate sub-1.4 PUE at the rack row or face penalties under progressive efficiency standards. Financial services colocation providers are responding by specifying sealed aisle containment with automated airflow modulation.
Buying patterns among Hong Kong enterprises are consolidating toward single-source rack-power-thermal contracts rather than fragmented component procurement. Systems integrators with regional manufacturing footprints capture preference over pure-play enclosure vendors. This concentration is most visible among securities firms building algorithmic trading infrastructure in Tseung Kwan O.
Hong Kong Data Center Rack Market Segmentation
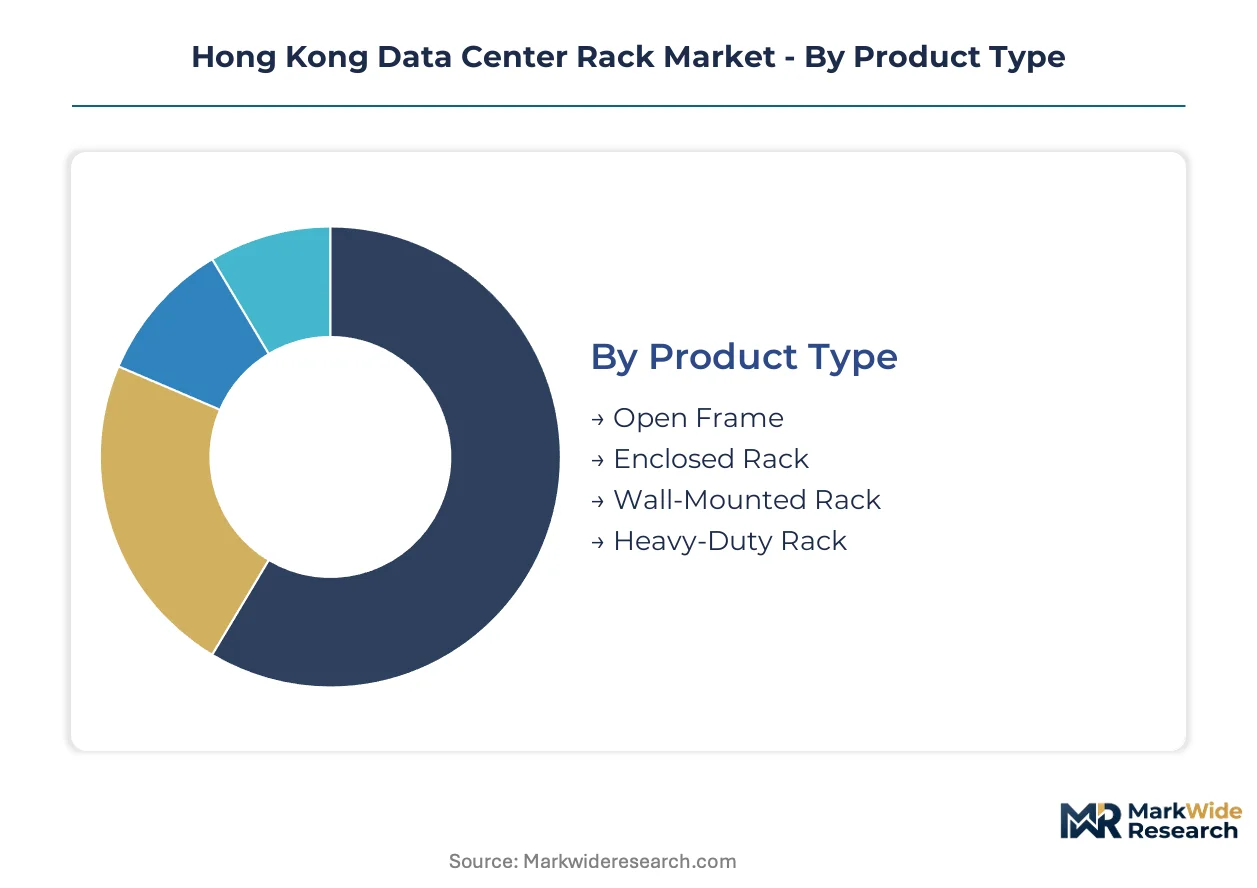
Segmentation in Hong Kong's data center rack market reveals how regulatory mandates and infrastructure constraints reshape procurement patterns across enclosure types and deployment models. The Electrical and Mechanical Services Department's certification requirements create divergent qualification pathways that favor certain product configurations over others.
Product Type:
The Electrical and Mechanical Services Department's IEC 61439 compliance mandates for low-voltage switchgear assemblies create structural differentiation between open and enclosed rack systems.
- Enclosed Rack:Factory-sealed metal cabinets with integrated fire suppression and electromagnetic shielding meet EMSD telecommunications facility standards for licensed operators. Demand concentrates in Tseung Kwan O cable landing zones where hyperscale tenants prioritize aisle containment and thermal isolation for GPU clusters running algorithmic trading workloads.
- Open Frame:Unenclosed four-post structures with static load ratings exceeding 1,500 kg offer superior airflow for air-cooled legacy infrastructure. Procurement dominates Kwai Chung industrial facilities serving enterprise colocation providers facing compressed deployment timelines under Personal Data Privacy Ordinance compliance pressure.
- Wall-Mounted Rack:Compact swing-out enclosures designed for constrained mechanical rooms in Central commercial towers.
- Heavy-Duty Rack:Reinforced steel framing engineered for vertical data center builds requiring structural coordination with Hong Kong's Buildings Department.
Established volume favors Enclosed Rack; emerging adoption favors Heavy-Duty Rack.
Deployment Model:
Cost tier differentiation separates capex-intensive on-premise builds from operational expenditure models favored by financial services institutions managing regulatory uncertainty.
- Colocation:Third-party facility tenancy allows banks and insurers to satisfy Personal Data Privacy Ordinance data residency mandates without direct real estate exposure. Demand clusters in Kwai Chung and Tseung Kwan O where submarine cable density creates latency arbitrage for securities trading infrastructure.
- Edge Data Centers:Sub-1MW facilities positioned in Central and Kowloon commercial districts address latency-sensitive content delivery and financial applications. This segment is expanding most quickly as proximity requirements override traditional hub-and-spoke architecture economics.
- On-Premise:Captive facility ownership retains control over security architecture for defense-sensitive government and enterprise workloads.
- Hybrid Cloud:Architectures blending private rack infrastructure with public cloud burst capacity optimize capital efficiency for variable demand patterns.
Revenue concentration sits with Colocation; steepest expansion trajectory belongs to Edge Data Centers.
End User:
Application-specific requirements drive specification divergence between latency-sensitive trading infrastructure and compliance-bound healthcare archives.
- BFSI:Banks, insurers, and securities firms generate concentrated demand for high-density GPU-ready racks with liquid cooling manifolds. Procurement timelines compress under Personal Data Privacy Ordinance enforcement while algorithmic trading requirements specify sub-millisecond connectivity to Tseung Kwan O cable landing stations.
- Telecommunication:Licensed operators face Office of the Communications Authority rack-level electromagnetic compatibility and structural loading certifications that elevate product qualification barriers. Network equipment demands standardized 19-inch mounting with integrated power distribution for 5G edge node deployment.
- IT Service Providers:Multi-tenant infrastructure operators balance customization flexibility against factory integration economies.
- Healthcare:Patient data archiving under Hong Kong's privacy framework requires air-gapped physical security with biometric rack access controls.
Specification leadership originates from BFSI; procurement volume scales through Telecommunication.
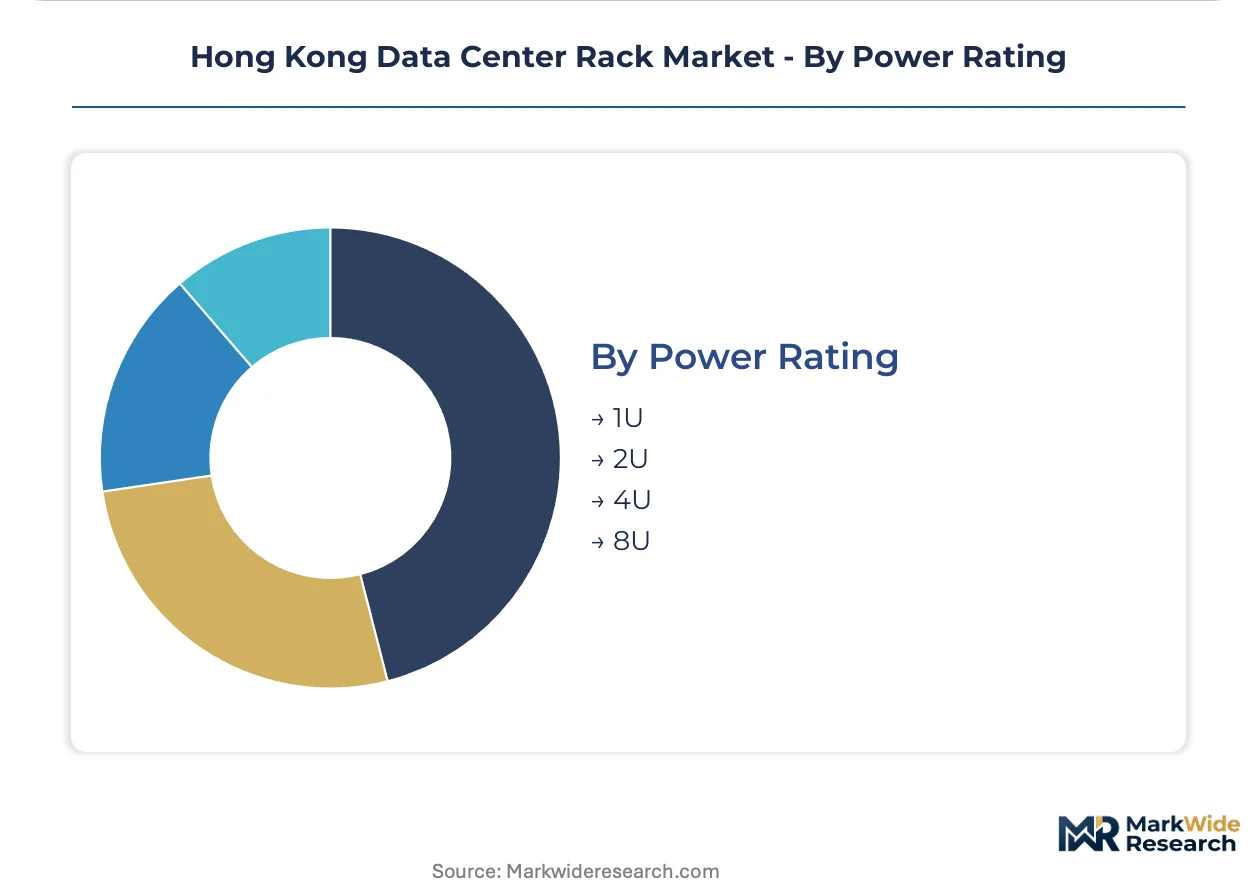
Power Rating:
Customer type segmentation separates hyperscale density requirements from enterprise standardization preferences.
- 4U:Mid-density enclosures accommodate dual-processor servers with discrete GPUs for financial modeling workloads. Demand concentrates among securities firms in Tseung Kwan O balancing thermal load against floor loading constraints in high-rise facilities.
- 8U:Extended-height racks support multi-node GPU clusters and integrated liquid cooling manifolds for AI training infrastructure. Adoption accelerates among hedge funds and proprietary trading desks deploying NVIDIA H100 architectures.
- 1U:Minimal-profile mounting for high-density switching and storage controllers in space-constrained Central district facilities.
- 2U:Standard enterprise server form factor dominating legacy infrastructure refresh cycles.
Current procurement volume clusters at 4U; specification momentum shifts toward 8U.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Electrical and Mechanical Services Department anchors Hong Kong's data center rack regulatory framework through IEC 61439 compliance mandates and Building Energy Code enforcement. These standards create qualification barriers that reshape procurement patterns across the territory's industrial zones.
Tseung Kwan O
Eleven active submarine cable systems land in this eastern New Territories district, creating latency arbitrage opportunities for securities trading infrastructure. The Office of the Communications Authority enforces rack-level electromagnetic compatibility certifications for licensed operators in cable landing stations. Hyperscale tenants concentrate GPU cluster deployments here to exploit sub-millisecond connectivity to global financial markets.
Kwai Chung
Legacy industrial zoning and utility corridor density attract enterprise colocation providers serving Personal Data Privacy Ordinance compliance timelines. The Buildings Department coordinates structural loading approvals for high-rise data center facilities with 1,500+ kg static rack requirements. Financial institutions expand captive footprints here to satisfy data residency mandates without direct real estate exposure.
Central District
Commercial tower mechanical rooms drive demand for compact wall-mounted rack configurations in space-constrained environments. The Electrical and Mechanical Services Department mandates integrated fire suppression systems for telecommunications facilities in dense urban cores. Edge micro-sites for latency-sensitive content delivery networks proliferate in this traditional financial district.
Kowloon Bay
Rezoned industrial land supports vertical data center construction with reinforced steel framing for heavy-duty rack loads. The Buildings Department extends project timelines through structural coordination requirements for high-rise builds. Trading firms and IT service providers cluster here seeking proximity to both submarine cable landings and urban demand nodes.
Sha Tin
University and research institution presence generates specialized demand for AI training infrastructure with liquid cooling integration. The Office of the Communications Authority references rack-level PUE metrics in telecommunications facility licensing for research networks. Technology parks in this new town attract modular factory-integrated rack deployments from regional manufacturing hubs.
Hong Kong Data Center Rack Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Hong Kong's data center rack market. The upper tier commands preference through factory-integrated rack-power-thermal systems that reduce on-site labor requirements in vertical builds. Specialist fabricators compete on precision-modular steel framing and thermal management customization for high-density GPU clusters. Dominant competitive moves include strategic partnerships with regional manufacturing hubs and portfolio diversification into liquid cooling manifolds.
Among Germany-based integrated manufacturers, Rittal GmbH & Co. KG exemplifies the precision-modular archetype for high-density enclosures. Vertiv Group Corp. and Schneider Electric SE represent North American and French-origin leaders respectively, anchoring positions through power distribution integration and thermal-integrated manufacturing scale. These three companies occupy the premium specification tier where procurement patterns consolidate toward single-source contracts.
| Leading Market Players |
|---|
| Rittal GmbH & Co. KG |
| Chatsworth Products |
| Vertiv Group Corp. |
| Legrand Group |
| ABB Ltd |
| Schneider Electric SE |
| Delta Electronics Inc. |
| Fujitsu Limited |
| Eaton Corporation |
| Others |
Pricing and Supply Chain Analysis
IEC 61439 compliance mandates from Hong Kong's Electrical and Mechanical Services Department simultaneously gate supply qualification and stratify price tiers, as non-local vendors absorb extended certification timelines while integrated manufacturers capture premium positioning through factory-certified rack-power-thermal systems.
Pricing Analysis
Hong Kong data center racks command 15-25% premiums over Singapore and Tokyo equivalents due to land scarcity and vertical build complexity. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by IEC 61439 certification grade and liquid cooling integration depth. Cost compression in the standard tier is intensifying as mainland Chinese fabricators achieve EMSD qualification, though hyperscale tenants show low price sensitivity for GPU-ready enclosures with direct-to-chip thermal management.
Supply Chain Analysis
Container availability constraints across the Shenzhen-Hong Kong trade lane elevate inbound logistics costs for cold-rolled steel and precision-manufactured power distribution components. Manufacturing concentrates in mainland China, Taiwan, and South Korea, with raw material dependencies spanning cold-rolled steel, copper busbars, and aluminum extrusions for thermal management. Single-source vulnerability runs through mainland Chinese steel supply, which feeds from regional mills with pricing volatility exposure. Distribution runs through direct OEM relationships with colocation operators and systems integrators serving Tseung Kwan O cable landing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hong Kong's data center rack market is accelerating through a regulatory inflection as EMSD Building Energy Codes enforce rack-level PUE metrics, compressing procurement timelines and elevating factory-integrated thermal solutions above site-built alternatives.
For Market Incumbents: Compound manufacturing scale advantages in liquid cooling manifolds and rear-door heat exchangers to defend against modular systems integrators encroaching from regional hubs. Prioritize certification maintenance with the Electrical and Mechanical Services Department as qualification timelines become a competitive moat. Deepen backward integration into precision steel fabrication to offset cold-rolled steel price volatility from mainland supply disruptions. For New Entrants and Emerging Players: Lead with edge micro-site deployments in Central and Kowloon commercial districts, where sub-1MW facility demand outpaces incumbent coverage and latency requirements override scale economies. Target securities trading infrastructure in Tseung Kwan O with sub-millisecond connectivity specifications as the most penetrable high-value segment. Pursue partnerships with regional manufacturing hubs for pre-integrated rack-and-power systems that reduce on-site labor requirements in vertical builds. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid-cooled GPU-ready rack segments as thermal engineering capabilities displace commodity enclosure fabrication. The 5-10 year viability window favors acquisitions of precision-modular steel framing specialists with EMSD certification pathways and regional manufacturing footprints. Monitor EMSD enforcement patterns on rack-level PUE compliance as the signal indicating when specification premiums will widen versus standard-tier commoditization.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Integration Partnership | Positions vendors for NVIDIA H100 cluster specifications in Tseung Kwan O trading facilities. |
| EMSD Certification Fast-Track Investment | Compresses qualification timelines for IEC 61439 compliance against mainland competitors. |
| Regional Manufacturing Hub Expansion | Reduces landed costs for pre-integrated systems serving Hong Kong's vertical build constraints. |
| Edge Micro-Site Distribution Agreement | Captures latency-sensitive demand in Central and Kowloon commercial districts. |
| Thermal Engineering Talent Acquisition | Addresses Hong Kong's sub-200 annual mechanical engineering graduate pipeline for data center specialization. |
Research Methodology
Desk research of customs trade records, EMSD regulatory filings, and submarine cable landing station disclosures preceded structured interviews with data center operators, thermal engineering specialists, colocation procurement directors, and regional manufacturing executives. Primary fieldwork combined facility site assessments in Kwai Chung and Tseung Kwan O with technical validation from enclosure fabricators and power distribution OEMs. Secondary sources included IEC certification databases, Buildings Department structural approval records, and hyperscale tenant capex disclosures. Bottom-up unit economics triangulated against top-down market sizing across enclosure types and deployment models.
Variance decomposition across product type, deployment model, end user, and power rating segmentation anchored the analytical framework throughout the projection horizon. CAGRs derived from installed base growth, replacement cycle compression, and density upgrade trajectories in financial services colocation. Industry-specific inputs incorporated GPU cluster adoption curves, PDPO enforcement timelines, and vertical build completion rates from the Buildings Department.
The analysis sits within stated boundaries; outcomes outside sustained PDPO compliance pressure, stable mainland Chinese steel supply, and EMSD regulatory continuity would require recalibration. Forecasts reflect assumptions on hyperscale tenant concentration in Tseung Kwan O, edge deployment economics in urban commercial districts, and liquid cooling technology cost curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
Netherlands Data Center Power Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
Asia-Pacific Virtual Desktop Infrastructure Market
Data Center Infrastructure
Global Data Center Accelerator Market
Data Center Infrastructure
Norway Data Center Physical Security Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
Denmark Data Center Power Market
Data Center Infrastructure
Europe Green Data Center Market