
 Dark Fiber Network Market | 2026-2036
Dark Fiber Network Market Size, Share, and Industry Trends Forecast 2026-2036
Dark Fiber Network Market Intelligence
Modular leasing of individual fiber strands and wavelength-division multiplexing (WDM) bundles is hardening as the dominant procurement pattern for enterprise buyers. Zayo Group Holdings leverages its dense metro footprint across North America and Europe to compete on route diversity and low-latency paths. Lumen Technologies anchors its position through deep long-haul conduit ownership and integrated network operations centers. Crown Castle specializes in fiber-to-the-tower and small-cell backhaul, extending its infrastructure model into dark fiber leasing for wireless carriers and edge computing deployments.
Dark fiber networks consist of installed optical fiber infrastructure that remains unlit by transmission equipment, enabling lessees to deploy their own transceivers, amplifiers, and routing gear across single-mode fiber strands typically rated for C-band and L-band wavelengths up to 100 kilometers before regeneration. The primary commercial purpose is to grant end users full control over bandwidth, protocol, and latency without recurring transport charges from lit-service carriers. Wholesale services and dark fiber leasing dominate value capture, as these segments attract hyperscalers and financial exchanges seeking dedicated, non-shared physical paths with predictable cost structures. Enterprise connectivity applications are expanding fastest among educational institutions and healthcare facilities building private research networks, though telecom infrastructure retains the largest installed base of underutilized conduit and strand count.
The FCC's infrastructure programs and state public utility commissions shape deployment economics through right-of-way rules and interconnection mandates, while the EU's GDPR and national telecom regulators such as Ofcom in the United Kingdom impose data sovereignty and cross-border fiber security standards that influence route planning. In the United States, the NTIA's BEAD program and state broadband offices are directing subsidy flows toward middle-mile fiber builds that expand addressable dark fiber inventory. Stakeholders must monitor how municipal open-access fiber ordinances and utility pole attachment reforms alter the competitive balance between incumbent carriers, independent infrastructure operators, and hyperscale self-build programs.
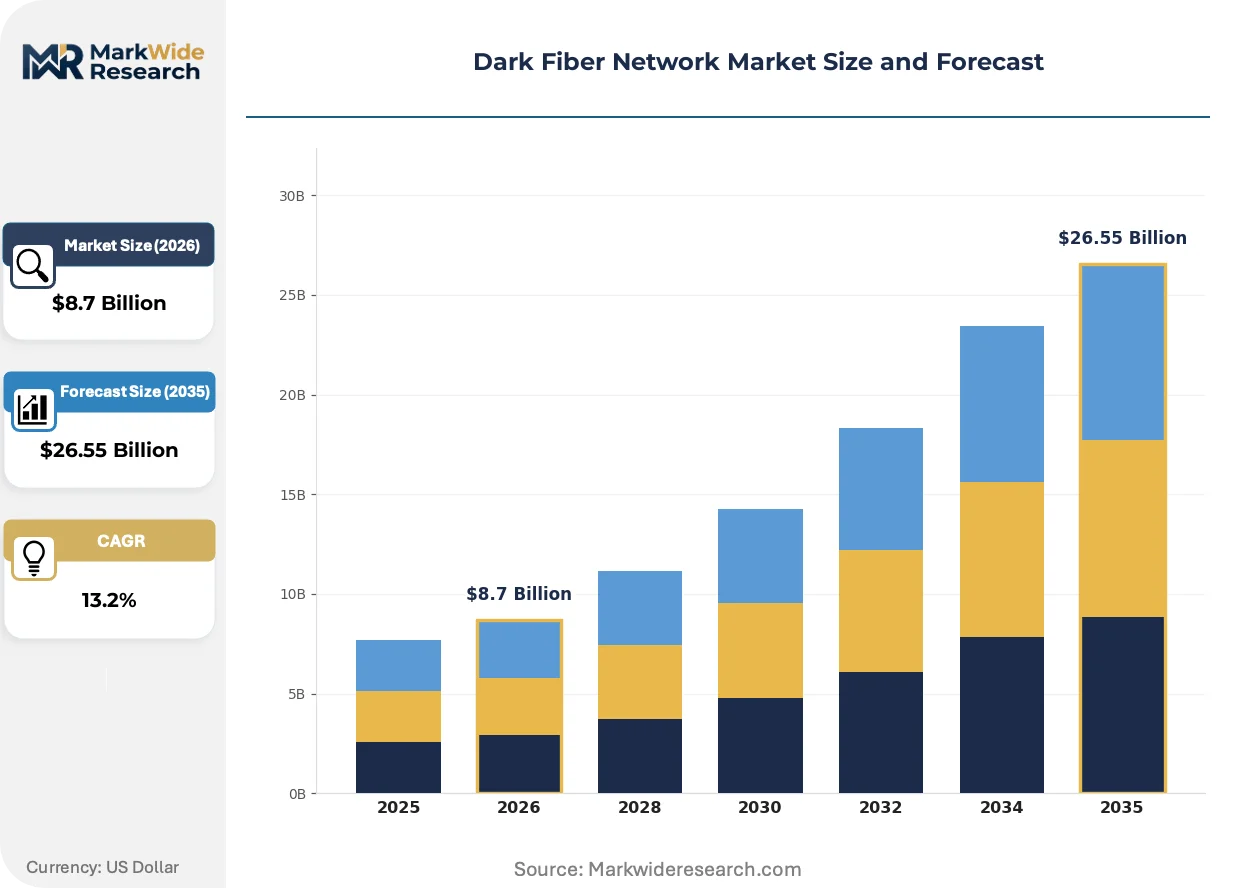
Market Dynamics
Hyperscale data center operators are bypassing traditional carrier networks by leasing unlit fiber pairs, creating direct control over latency and routing while compressing margins for legacy lit-service providers.
Growth Catalysts
- NTIA BEAD Program:Federal subsidies for middle-mile fiber builds are expanding addressable dark fiber inventory across underserved U.S. counties, lowering entry barriers for regional operators.
- Edge Computing Clusters:Distributed AI inference workloads require dedicated low-latency paths that shared networks cannot guarantee, pulling fiber demand toward secondary markets.
- Quantum Key Distribution:Financial exchanges and defense contractors are provisioning physical fiber pairs for quantum-secured transmission, creating premium lease tiers.
Market Restraints
- Right-of-Way Access:Municipal ordinances and railroad crossing permits create 18-24 month deployment timelines in dense urban cores, freezing capital in permitting limbo.
- Optical Amplifier Supply:Erbium-doped fiber amplifier manufacturing concentrates in three East Asian facilities, exposing lessees to component lead time volatility.
- Wireless Substitution:5G fixed wireless access and low-earth orbit satellite constellations are capturing price-sensitive enterprise connectivity demand in rural fringe zones.
Strategic Opportunities
- Submarine Cable Landing Stations:Coastal dark fiber rings connecting transatlantic and transpacific cable termini in Virginia Beach and Los Angeles remain underbuilt relative to traffic volumes.
- Smart Grid Fiber:Electric utilities are leasing excess optical ground wire capacity to telecom operators, creating hybrid infrastructure revenue streams.
- Open RAN Fronthaul:Disaggregated radio access network architectures require dedicated fiber between distributed units and radio units, expanding addressable strand demand.
Industry Challenges
- Fusion Splicing Technician Shortage:Precision fiber termination skills are aging out of the workforce faster than training programs replenish qualified installers, extending service activation windows.
- Interoperability Testing Burden:Each lessee-deployed transceiver brand requires validation across amplifier chains and dispersion compensation modules, multiplying pre-activation engineering cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dark Fiber Network Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.55 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Private Networks, Wholesale Services, Dark Fiber Leasing, Managed Services Application: Data Centers, Telecom Infrastructure, Enterprise Connectivity, Government Applications End User: Telecommunications Providers, Enterprises, Educational Institutions, Healthcare Facilities Deployment: On-Premises, Off-Site, Hybrid, Colocation |
| Companies Covered | Zayo Group Holdings, Lumen Technologies, AT&T, Verizon Communications, Crown Castle, Colt Technology Services, Comcast Corporation, GTT Communications, FiberLight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dark Fiber Network Market Strategic Shifts & Innovations
Optical transport economics are compressing as coherent DSP technology enables higher spectral efficiency, while regulatory subsidy flows are reshaping competitive entry patterns across fiber-rich and fiber-poor geographies.
Coherent pluggable optics operating at 400G and 800G per wavelength is absorbing capital expenditure that previously funded discrete transponder shelves and separate line system equipment. Cloud operators are deploying these modules directly into switch routers, collapsing network layers and shrinking data center interconnect footprints. This integration is absorbing margin from traditional optical transport system vendors while accelerating wavelength turn-up velocity.
The FCC's infrastructure investment programs are mandating open-access middle-mile fiber for grant recipients, prohibiting exclusive leasing arrangements that locked out competitive providers. State broadband offices are enforcing this condition through clawback provisions, altering how network operators structure wholesale agreements. Rural electric cooperatives receiving these funds are responding by creating separate fiber leasing subsidiaries to maintain compliance while capturing retail upside.
Enterprise buyers are consolidating fiber procurement under infrastructure-as-code frameworks, replacing multi-year IRU contracts with API-driven wavelength provisioning that scales monthly. Systems integrators and cloud brokers are displacing traditional carrier account teams as the primary vendor relationship. This transition is most visible among SaaS providers in Northern Virginia and financial services firms in Chicago, where network engineering teams have merged with software operations functions.
Dark Fiber Network Market Segmentation
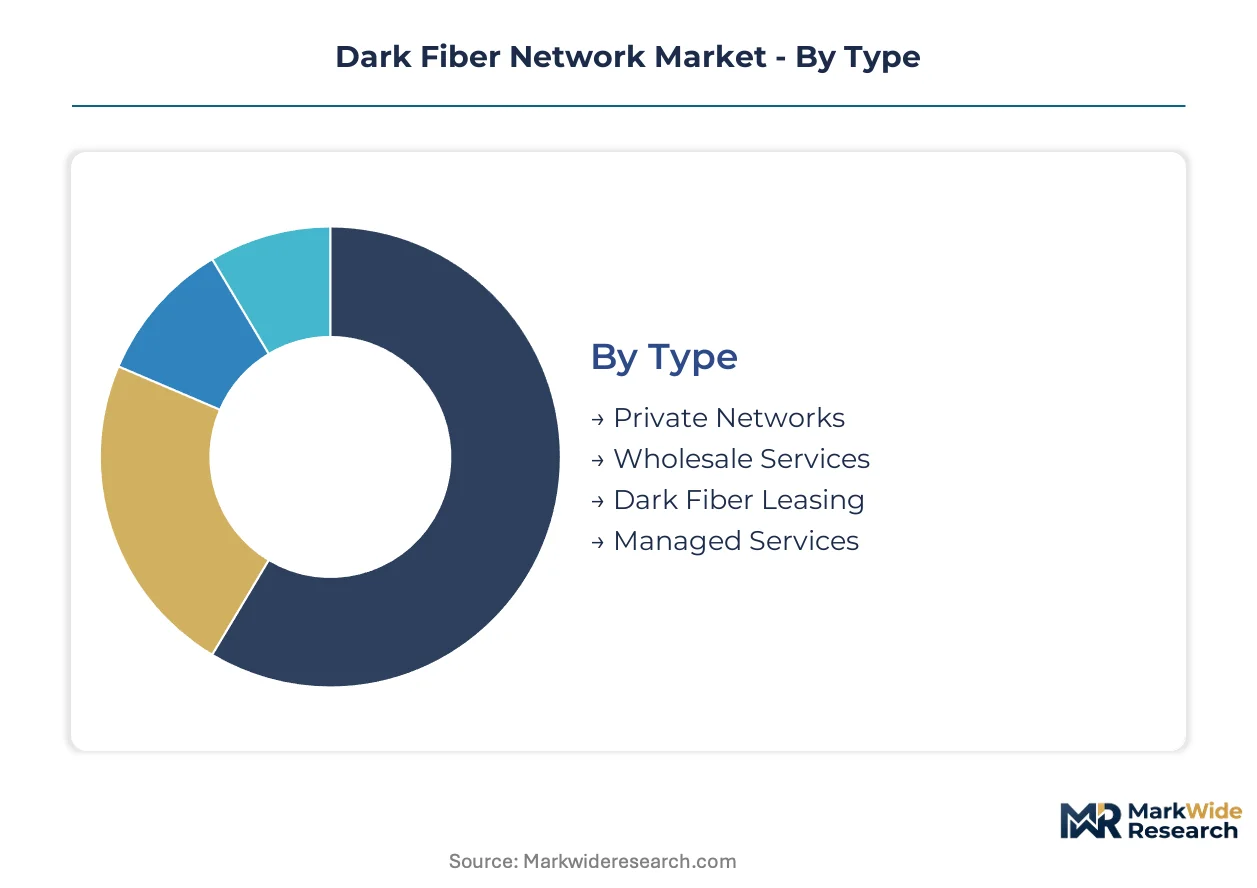
Dark fiber procurement patterns diverge sharply across customer types and deployment models, with regulatory compliance burdens varying by application context. Understanding these segment boundaries enables suppliers to calibrate pricing structures and service level agreements to actual buyer capabilities and constraints.
Type:
FCC open-access mandates for BEAD-funded middle-mile builds impose uniform leasing conditions on wholesale services, while private network deployments face lighter regulatory scrutiny but heavier capital requirements for self-operated line systems.
- Wholesale Services:Aggregated fiber capacity sold to downstream carriers and resellers, typically structured as indefeasible rights of use with 10-20 year terms. Demand concentrates among regional telecom operators in Texas and Florida seeking to bypass incumbent last-mile bottlenecks, constrained by NTIA clawback provisions requiring non-discriminatory access.
- Dark Fiber Leasing:Physical strand or fiber pair rentals where lessees supply all active transmission equipment. Hyperscalers in Northern Virginia and Phoenix dominate procurement, drawn by the ability to tune coherent optics for specific latency targets without carrier intermediation.
- Private Networks:Captive fiber installations owned and operated by single entities for exclusive use. Financial exchanges in Chicago and defense contractors near Washington DC favor this model for physical path control.
- Managed Services:Fully operational wavelength or Ethernet services delivered over dark fiber infrastructure. Healthcare systems in secondary Midwest markets prefer this option to avoid optical engineering staffing requirements.
Wholesale services sit at the top of the volume ranking, with dark fiber leasing climbing the fastest.
Application:
Cost tiering separates mission-critical low-latency deployments from cost-optimized backup connectivity, with data center interconnect commanding premium pricing against government-mandated lowest-cost-technically-acceptable procurement.
- Data Centers:Inter-facility connectivity and cloud region meshing requiring sub-millisecond latency guarantees. Operators in Columbus and Salt Lake City are expanding strand counts to support AI training cluster distribution, though amplifier supply constraints limit turn-up velocity.
- Enterprise Connectivity:Campus networks and private WAN infrastructure for large organizations. Research universities in North Carolina and Pennsylvania are driving demand for 400G-ready single-mode pairs to interconnect distributed compute nodes.
- Telecom Infrastructure:Mobile backhaul, carrier-neutral exchange points, and intercity transport. 5G densification in Atlanta and Dallas is pulling fiber toward cell towers and distributed antenna systems.
- Government Applications:Secure networks for federal, state, and municipal agencies. NTIA BEAD program compliance requirements are reshaping procurement toward open-access middle-mile specifications.
Data centers command the highest revenue per strand, with enterprise connectivity expanding most quickly among educational buyers.
End User:
Customer type determines technical sophistication thresholds, with telecommunications providers bringing in-house optical engineering capabilities that healthcare and education buyers typically lack.
- Telecommunications Providers:Incumbent and competitive carriers with established network operations centers. These buyers self-provision amplifiers and dispersion compensation across leased pairs, particularly for long-haul routes between Denver and Seattle.
- Enterprises:Financial services, manufacturing, and technology firms building private infrastructure. SaaS providers in Northern Virginia are consolidating procurement under infrastructure-as-code frameworks with API-driven provisioning.
- Healthcare Facilities:Hospital systems and regional health networks requiring HIPAA-compliant dedicated paths. Systems in Tennessee and Ohio are leasing dark fiber for medical imaging network isolation.
- Educational Institutions:Universities and K-12 districts constructing research and administrative networks. State university systems in California and New York are pooling procurement to achieve scale.
Telecommunications providers represent the largest installed base, with educational institutions gaining share fastest through consortium purchasing.
Deployment:
Physical location of termination equipment creates divergent operational risk profiles, with on-premises deployments bearing full environmental control burdens against colocation models shifting facility management to specialized operators.
- Colocation:Fiber termination within third-party data center facilities where cross-connects and meet-me rooms simplify interconnection. This model dominates in Ashburn and Los Angeles where carrier density supports rapid peering.
- Hybrid:Split architectures with critical paths on-premises and backup connectivity colocated. Financial exchanges in Chicago and New Jersey favor this approach for operational resilience.
- On-Premises:Customer-controlled facilities with dedicated equipment rooms and power infrastructure. Defense contractors and classified government installations require this deployment mode.
- Off-Site:Remote termination points such as carrier hotels or network access points without customer presence. Smaller enterprises in Portland and Austin use this to reduce capital exposure.
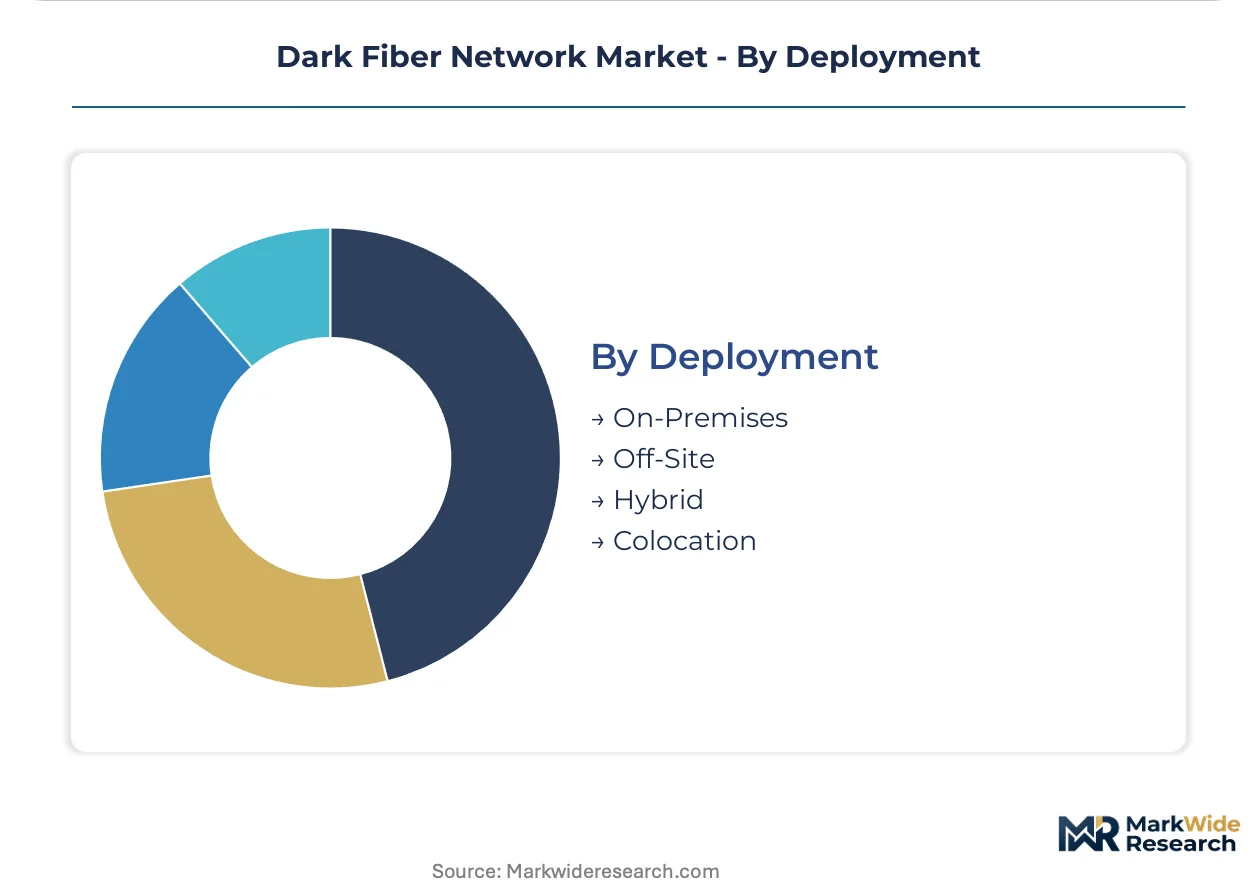
Colocation leads in port count deployed, with hybrid configurations seeing the steepest expansion trajectory among risk-sensitive buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dark fiber infrastructure first achieved commercial scale across North American long-haul routes during the 1990s telecommunications deregulation era, with dense metro builds subsequently spreading to European financial centers and Asia-Pacific cloud hubs.
United States
Hyperscale data center construction in Northern Virginia and Phoenix drives strand demand for AI cluster interconnects. The FCC's BEAD program mandates open-access middle-mile fiber for subsidy recipients, prohibiting exclusive lease arrangements. Zayo Group Holdings and Lumen Technologies compete for route diversity across Dallas-Fort Worth and Chicago financial exchange corridors.
Germany
Industrial automation and automotive R&D facilities in Bavaria and Baden-Württemberg require deterministic latency for private 5G backhaul. Germany's national telecom regulator enforces unbundling obligations on Deutsche Telekom's fiber infrastructure. Frankfurt's concentration of trading venues and cloud regions anchors dark fiber demand for cross-border connectivity into France and the Netherlands.
United Kingdom
Financial services firms in the City of London and Canary Wharf lease dedicated fiber pairs for microwave backup and primary trading infrastructure. Ofcom's wholesale fiber access remedies shape competitive entry conditions for alternative network operators. Slough and Docklands data center clusters concentrate interconnection demand for transatlantic cable terminations.
Japan
Tokyo-Osaka corridor traffic growth from cloud gaming and distributed AI inference pulls fiber investment toward secondary metro rings. METI's digital infrastructure investment tax incentives accelerate conduit builds in regional cities. Osaka's emergence as a submarine cable landing hub creates coastal ring demand connecting Kansai International Airport facilities.
Australia
Research universities in New South Wales and Victoria construct private optical networks linking distributed high-performance computing nodes. The Australian Competition and Consumer Commission's special access undertakings regulate NBN Co's wholesale fiber pricing. Sydney's growth as an Asia-Pacific cloud region drives inter-capital dark fiber procurement for Melbourne and Brisbane connectivity.
Dark Fiber Network Market Key Industry Players
The competitive structure tilts toward infrastructure-heavy incumbents with deep conduit ownership and long-dated indefeasible rights of use. Tier-one carriers and independent fiber operators coexist in a bifurcated landscape where scale economies in route density separate sustainable competitors from marginal players. Strategic archetypes include national long-haul backbone specialists, metro-focused density operators, and hyperscale-captive infrastructure developers. Capacity expansion through organic fiber builds and strategic conduit acquisitions represent the dominant competitive moves, with M&A activity concentrating on regional fiber depth rather than geographic breadth.
Among North American infrastructure operators, Zayo Group Holdings exemplifies the metro-density archetype through its extensive strand inventory in secondary data center markets. Lumen Technologies occupies a position representing legacy long-haul consolidation with deep conduit ownership across intercity corridors. Crown Castle anchors the fiber-to-the-tower specialization, extending infrastructure models into edge computing and small-cell backhaul applications. These three entities collectively illustrate how competitive positioning derives from route-specific asset depth rather than service-layer differentiation.
| Leading Market Players |
|---|
| Zayo Group Holdings |
| Lumen Technologies |
| AT&T |
| Verizon Communications |
| Crown Castle |
| Colt Technology Services |
| Comcast Corporation |
| GTT Communications |
| FiberLight |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up infrastructure specialists anchor supply concentration across North American metro fiber markets, translating conduit scarcity into pricing discipline while compressing margins for lit-service intermediaries. Their aggregated strand portfolios in Northern Virginia and Phoenix feed directly into long-term indefeasible rights of use contracts that hyperscalers negotiate to lock in route-specific latency guarantees.
Pricing Analysis
Indefeasible rights of use with 10-20 year terms dominate commercial structures, separating premium metro-density routes from standard long-haul corridors and economy rural fringe builds. Price differentiation rests on route diversity metrics and amplifier spacing requirements, with sub-50-kilometer regeneration intervals commanding substantial premiums. Cost compression in long-haul wholesale tiers is intensifying as hyperscalers self-provision coherent optics and bypass traditional carrier markups. Financial exchanges in Chicago exhibit the least price sensitivity, while rural electric cooperatives in secondary Midwest markets drive hardest bargain on middle-mile strand rates.
Supply Chain Analysis
Direct-to-hyperscale channels handle demand from cloud operators in Northern Virginia and Phoenix, while carrier-neutral meet-me rooms in Los Angeles and Ashburn aggregate smaller enterprise procurement. Manufacturing concentrates in the United States for fusion splicing equipment, Japan for erbium-doped fiber amplifiers, and China for passive optical components. Raw material dependencies include high-purity silica glass, specialized coating polymers, and rare-earth doping elements for signal amplification. Single-source vulnerability in East Asian amplifier fabrication exposes deployment timelines to component lead time volatility. Distribution runs through specialized fiber infrastructure brokers and direct carrier sales teams serving tier-one data center operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
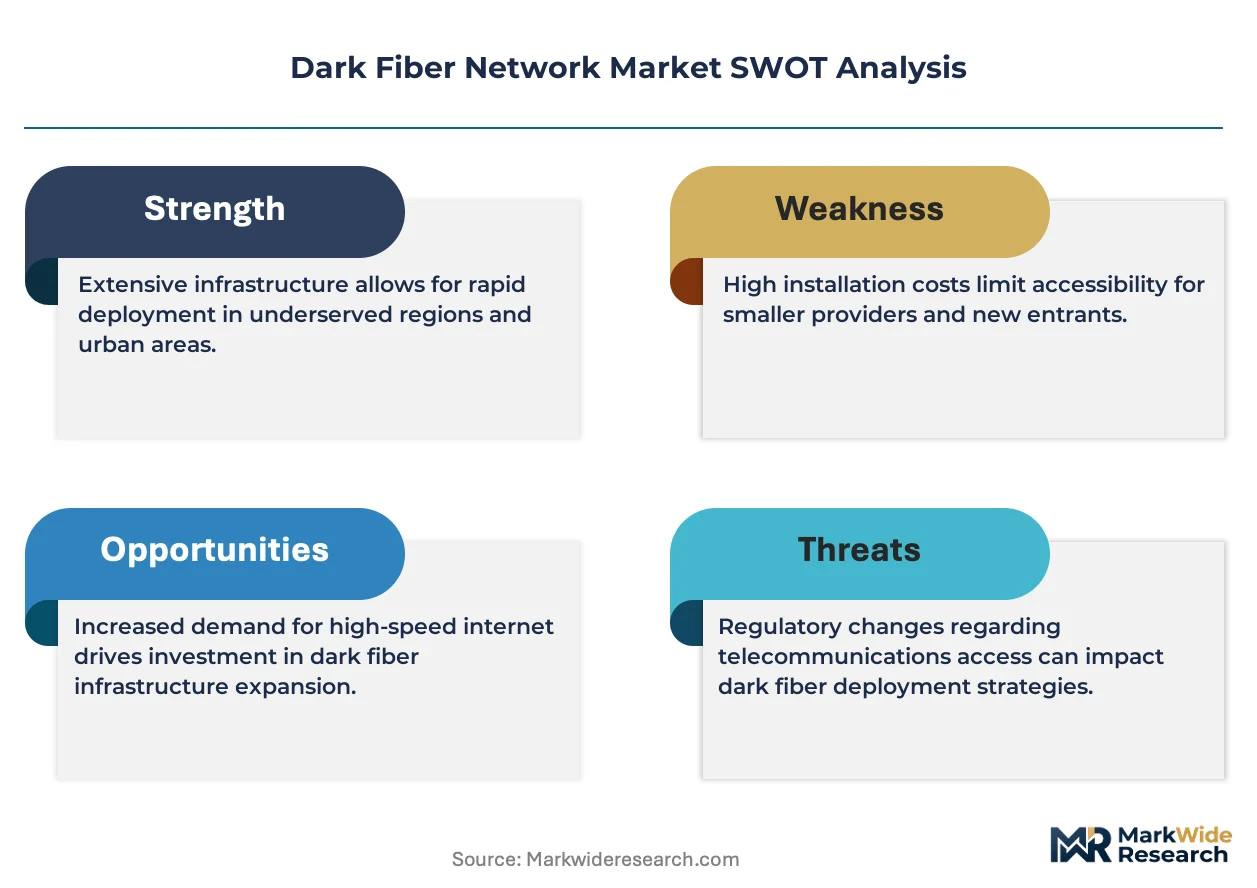
The Dark Fiber Network Market functions as a stable compounder, with data center construction cycles generating predictable strand demand across decade-long lease horizons.
For Market Incumbents: Deepen metro route density in Columbus and Salt Lake City before hyperscale construction commitments solidify. Expand conduit ownership through municipal joint ventures to preempt open-access regulatory mandates. Defensive consolidation should target regional fiber operators in Texas and Florida where NTIA BEAD subsidies are expanding addressable inventory. Priority investment in automated fusion splicing training programs addresses technician shortage risks that extend service activation windows. For New Entrants and Emerging Players: Rural electric cooperatives receiving federal broadband subsidies represent the most penetrable channel partner type for middle-mile fiber builds. Target secondary markets including Portland and Austin where carrier-neutral colocation density remains underdeveloped relative to hyperscale demand growth. White-space opportunities concentrate in submarine cable landing station rings connecting Virginia Beach and Los Angeles termini. Go-to-market positioning should emphasize API-driven wavelength provisioning that displaces traditional carrier account relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among metro-focused density operators with stranded assets in secondary markets awaiting hyperscale construction waves. Long-term viability frames around 5-10 year infrastructure replacement cycles and irreplaceable right-of-way portfolios. Acquisition targets should display deep conduit ownership in data center corridor geographies with proven lease-up velocity. The signal to watch is hyperscaler direct-build announcements that bypass traditional leasing channels and compress wholesale pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Conduit Acquisition in Secondary Markets | Preemptive right-of-way capture in Columbus and Salt Lake City secures hyperscale anchor tenants before competitors. |
| Open-Access Infrastructure Subsidiary Formation | Rural electric cooperatives creating separate leasing entities maintain NTIA BEAD compliance while capturing retail upside. |
| Automated Service Provisioning Platform | API-driven wavelength turn-up displaces traditional carrier sales cycles for SaaS providers in Northern Virginia. |
| Submarine Cable Landing Station Ring Build | Coastal fiber rings connecting Virginia Beach and Los Angeles termini address underbuilt capacity relative to transatlantic traffic volumes. |
| Precision Technician Training Program | Accelerated fusion splicing certification replenishes aging workforce and compresses service activation timelines. |
Research Approach
Multiple input streams — structured interviews with network engineering directors, discussions with data center development leads, and regulatory filing analysis — were reconciled against secondary validation from FCC infrastructure program disclosures and state broadband office procurement records. Primary fieldwork captured perspectives from hyperscale cloud operators, regional fiber infrastructure owners, and enterprise network procurement officers across North American and European markets. Secondary sources included SEC 10-K infrastructure disclosures, NTIA BEAD program funding announcements, and submarine cable landing station development permits. Bottom-up strand inventory counts were triangulated against top-down capital expenditure flows from major data center developers.
Data-stream reconciliation across supply-side conduit inventories and demand-side lease commitments anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include service type, application context, end-user sophistication tier, and deployment physical location. CAGRs were derived from lease commencement velocity and hyperscale construction pipeline tracking. Industry-specific forecast inputs incorporated coherent optics deployment rates and FCC subsidy program execution timelines.
Revisions become necessary when hyperscaler self-build announcements, municipal open-access ordinance adoptions, or optical amplifier supply disruptions materialize at scale. Forecasts reflect assumptions regarding sustained data center construction activity and continued federal infrastructure subsidy flows. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Mobile Data Offload Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
Voice Over Internet Protocol (Voip) Market
Data Center and Networking
Global Data Warehouse As a Service (Dwaas) Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Saudi Arabia Data Center Networking Market
Data Center and Networking
Chile Data Center Networking Market
Data Center and Networking
Software Defined Video Networking Market
Data Center and Networking
Nosql Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Belgium Data Center Networking Market
Data Center and Networking
Cache Server Market
Data Center and Networking
Network Function Virtualization (NFV) Market