
 Network Telemetry Market | 2026-2036
Network Telemetry Market Size, Share, and Industry Trends Forecast 2026-2036
Network Telemetry Market Intelligence
Cloud service providers is reorganizing procurement patterns across the network telemetry landscape, displacing traditional enterprise IT as the dominant buyer archetype. Cisco Systems leverages its installed base of switching infrastructure to embed telemetry agents at the silicon layer. Juniper Networks competes through programmable forwarding-plane architectures that expose granular flow metadata. Arista Networks specializes in low-latency visibility fabrics purpose-built for hyperscale environments.
Network telemetry encompasses the automated collection, transmission, and analysis of operational data from network devices, typically using protocols such as gRPC, IPFIX, and SNMP to stream state information at sub-second intervals for real-time decisioning. Its primary commercial purpose is to replace polling-based monitoring with continuous, event-driven visibility that enables predictive fault remediation and dynamic traffic engineering. Flow analytics and packet capture represent the most mature solution categories, while edge-based deployment modes capture the fastest expansion as 5G and IoT workloads push intelligence toward distributed points of presence. Security monitoring applications command premium pricing relative to bandwidth management, reflecting the higher operational cost of breach incidents versus throughput optimization.
The Federal Communications Commission shapes US carrier obligations around outage reporting and data integrity, while the European Union's Cybersecurity Act and NIS2 Directive establish baseline visibility requirements for critical infrastructure operators across member states. Japan's Ministry of Internal Affairs and Communications drives similar technical standards for telecommunications resilience through JIS-aligned certification programs. Stakeholders must weigh cloud-native telemetry architectures against sovereign data-localization mandates when designing multi-region deployment strategies.
Market Dynamics
Zero-trust security mandates from NIST and equivalent bodies in Germany and Japan are forcing network operators to deploy deeper visibility layers, compressing procurement cycles and reshaping vendor selection criteria across enterprise and carrier segments.
Growth Catalysts
- Hyperscale data center buildouts:Cloud service providers in the United States are expanding telemetry deployments to manage distributed infrastructure, creating concentrated procurement pull for real-time visibility fabrics.
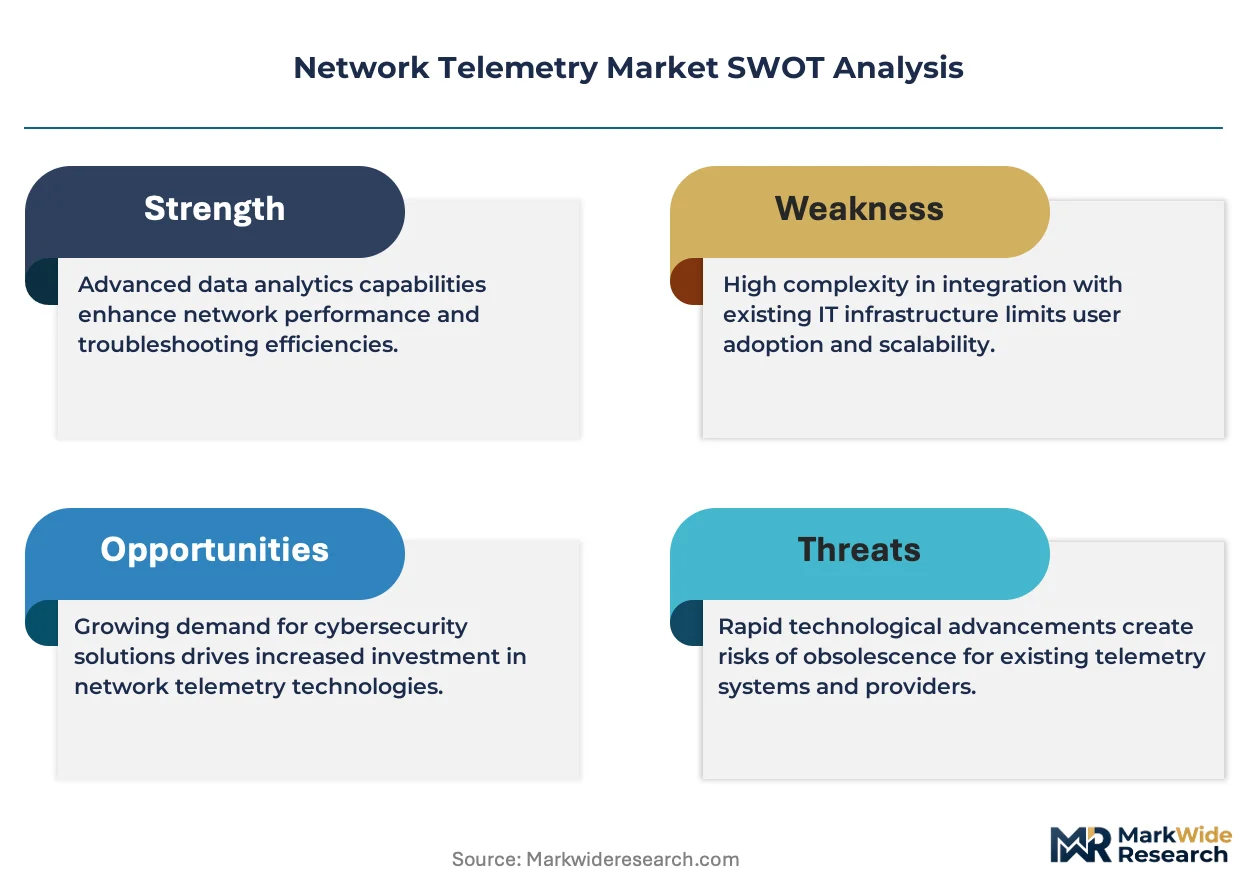
- EU NIS2 Directive:The European Union's baseline visibility requirements for critical infrastructure operators are mandating continuous network monitoring across energy, transport, and digital services sectors.
- gRPC streaming protocols:Sub-second state transmission is replacing SNMP polling architectures, enabling predictive fault remediation in high-velocity traffic environments.
Market Restraints
- Silicon-layer vendor concentration:Telemetry agent deployment depends on switching ASIC architectures controlled by a narrow supplier base in Taiwan and South Korea.
- Data-localization compliance costs:Sovereign mandates in Germany, Japan, and India require region-locked telemetry storage, fragmenting cloud-native architectures.
- Specialized engineering scarcity:Flow analytics and programmable forwarding-plane configuration demand skills concentrated among veteran routing protocol engineers.
Strategic Opportunities
- Edge-based deployment expansion:5G and IoT workloads in Brazil and Saudi Arabia are pushing intelligence toward distributed points of presence with minimal incumbent competition.
- Security monitoring premium capture:Breach-incident cost differentials enable pricing power for telemetry solutions targeting financial services and healthcare verticals.
- Japan MIC resilience standards:JIS-aligned certification programs for telecommunications operators create a regulated demand pool for compliant visibility platforms.
Industry Challenges
- Legacy SNMP integration friction:Brownfield environments with embedded polling architectures resist event-driven telemetry overlays without forklift upgrades.
- Cross-border data governance complexity:Multi-region enterprises must reconcile FCC outage-reporting obligations with GDPR data-minimization principles.
- Real-time pipeline engineering talent gap:Streaming analytics infrastructure requires expertise in Apache Kafka and Flink that outpaces supply from university programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Telemetry Market |
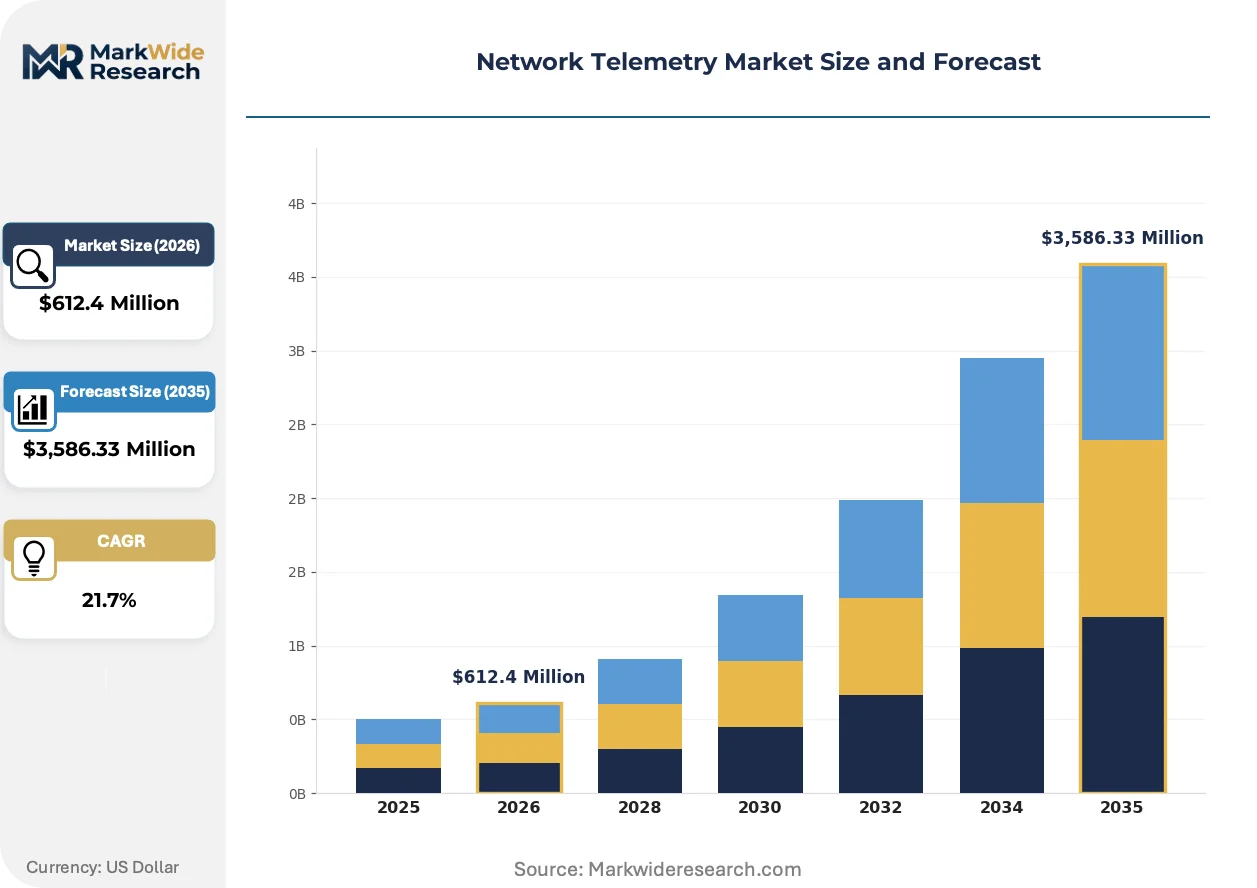
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $3,586.33 Million |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Flow Analytics, Packet Capture, Network Performance Monitoring, Traffic Analysis, Fault Detection Deployment Mode: On-Premises, Cloud-Based, Hybrid, Edge-Based, Virtualized Application: Bandwidth Management, Anomaly Detection, Capacity Planning, Security Monitoring, QoS Optimization End User Industry: Telecommunication Providers, Data Centers, Managed Service Providers, Enterprises, Content Delivery Networks |
| Companies Covered | Cisco Systems, Juniper Networks, Arista Networks, Hewlett Packard Enterprise Development LP, IBM, NVIDIA Corporation, Gigamon, Palo Alto Networks, NetScout Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Telemetry Market Strategic Shifts & Innovations
Telemetry collection architectures are pivoting from centralized aggregation to distributed edge processing, compressing decision latency and altering where intelligence resides in the network stack.
Programmable data-plane silicon is fragmenting traditional switching hierarchies by embedding flow metadata extraction directly at the forwarding layer. Hyperscale operators in the United States are deploying these architectures at scale, displacing standalone probe appliances. This compression is fragmenting the visibility vendor landscape into silicon-integrated versus software-overlay specialists.
Germany's implementation of NIS2 through national cybersecurity legislation is mandating continuous monitoring for critical infrastructure operators. The industrial consequence is a surge in certified telemetry deployments across energy distribution and railway signaling networks. German carriers are responding by procuring sovereign-cloud-hosted visibility platforms that satisfy data-residency requirements.
Buying patterns among enterprise IT departments are compressing from multi-year capital cycles to consumption-based telemetry-as-a-service arrangements. Systems integrators and managed security providers are capturing this shift through subscription visibility offerings. This transformation is most visible in United States federal contractor segments, where budget predictability requirements favor operational expenditure models.
Network Telemetry Market Segmentation
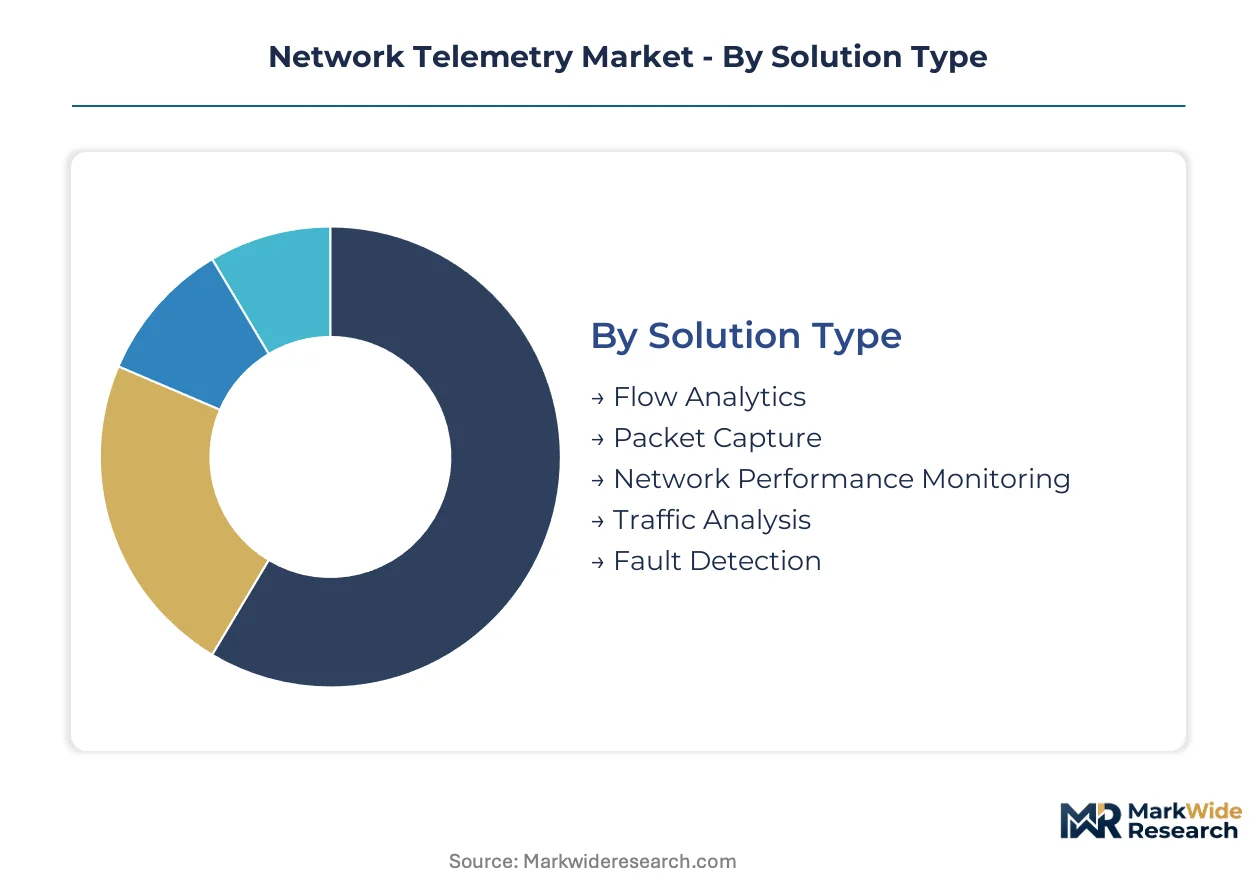
Telemetry vendors configure product portfolios around distinct operational workflows, with solution architecture and deployment topology determining channel strategy and customer acquisition costs. Segmentation clarity reveals where pricing power concentrates and which buyer archetypes drive expansion.
Solution Type:
Flow analytics and packet capture solutions reach enterprise buyers through direct sales teams, while network performance monitoring and fault detection increasingly route through cloud marketplaces and managed service provider channels.
- Flow Analytics:Collects IPFIX and NetFlow records to reconstruct traffic patterns and identify east-west lateral movement within data center fabrics. Financial services institutions in the United States deploy these systems to satisfy SEC audit trail requirements for transaction network visibility.
- Packet Capture:Performs full-payload recording at line rate for forensic reconstruction and compliance documentation. Healthcare providers prioritize this segment for HIPAA-mandated breach investigation capabilities, accepting higher storage costs for complete evidentiary chains.
- Network Performance Monitoring:Synthetic transaction testing and path analysis for application-layer SLA enforcement.
- Traffic Analysis:Behavioral profiling and baseline deviation detection for DDoS mitigation and congestion forecasting.
- Fault Detection:Correlation of syslog, SNMP traps, and streaming telemetry for root-cause isolation.
Flow analytics dominates installed base. Packet capture is where expansion concentrates for regulated verticals.
Deployment Mode:
Cost tiering separates perpetual-license on-premises deployments from consumption-metered cloud offerings, with hybrid and edge configurations commanding premium professional services attach rates.
- On-Premises:Dedicated appliance or software deployment within customer-controlled data centers with full administrative sovereignty. German energy utilities and railway operators mandate this mode to satisfy BSI compliance for critical infrastructure protection.
- Cloud-Based:SaaS-delivered visibility with elastic compute scaling and vendor-managed infrastructure updates. Mid-market enterprises in the United States favor this tier for opex predictability and rapid time-to-value without capital committee approval cycles.
- Hybrid:Split architecture with sensitive flow metadata retained on-premises while analytics processing leverages cloud elasticity.
- Edge-Based:Lightweight agent deployment at 5G base stations and IoT aggregation points with local inference and filtered upstream transmission.
- Virtualized:Containerized telemetry functions orchestrated through Kubernetes for cloud-native network functions.
On-premises retains the largest revenue base among regulated industries. Edge-based deployment is climbing the fastest as telecommunications providers modernize radio access networks.
Application:
Volume concentration varies by buyer sophistication, with bandwidth management and QoS optimization standardizing into commodity features while security monitoring and anomaly detection sustain differentiation premiums.
- Bandwidth Management:Traffic shaping and congestion control for cost-optimized transit and peering relationships. Content delivery networks deploy these capabilities at scale to minimize egress charges from cloud origin servers.
- Anomaly Detection:Machine learning-driven baseline deviation identification for zero-day threat discovery. Managed security providers in Japan bundle this application with SOC services to meet MIC resilience certification requirements.
- Capacity Planning:Trend extrapolation and forecasting models for infrastructure investment timing.
- Security Monitoring:Correlation of telemetry streams with threat intelligence feeds for incident response orchestration.
- QoS Optimization:Real-time policy enforcement for latency-sensitive voice and video traffic.
Bandwidth management saturates enterprise accounts. Security monitoring is gaining share fastest as breach cost escalation reshapes procurement priorities.
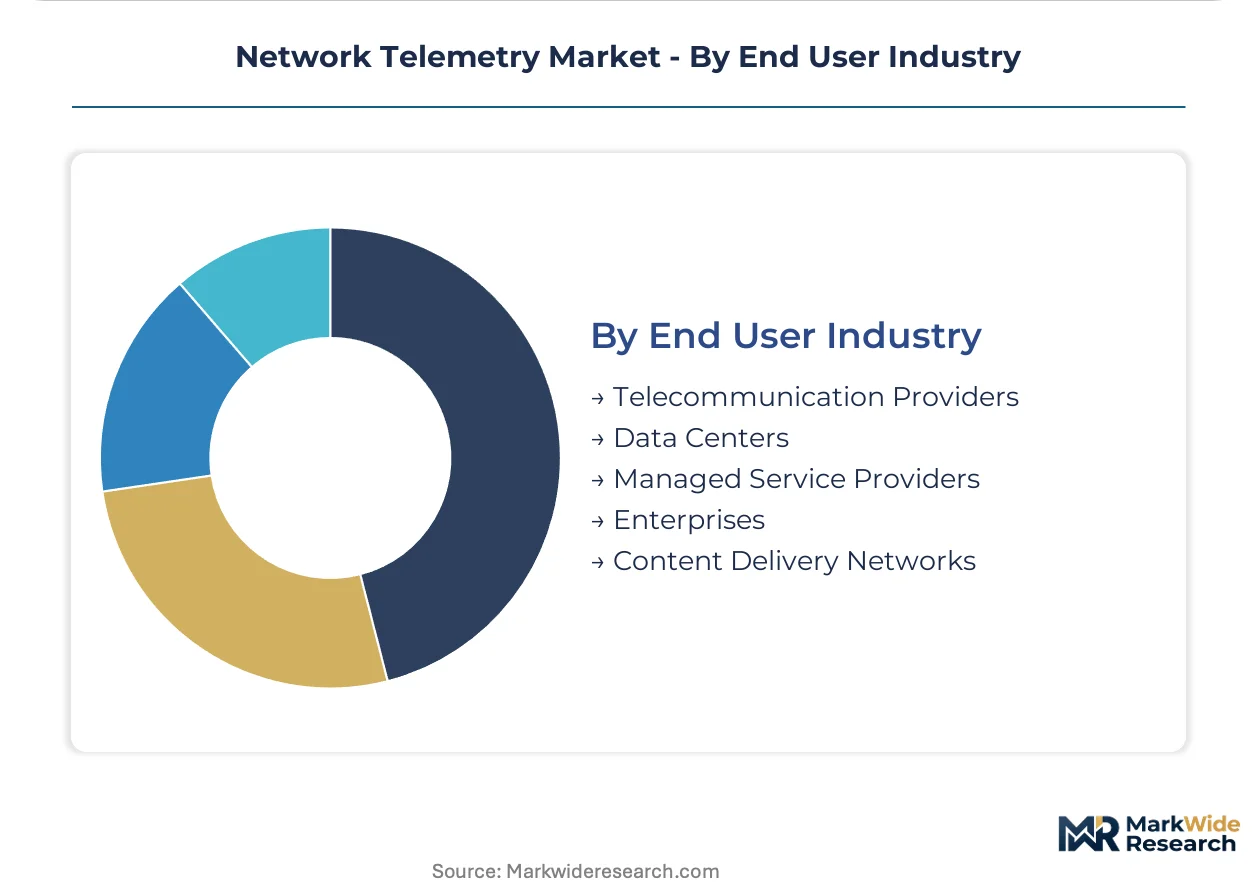
End User Industry:
Customer type determines contract structure, with telecommunications providers and data centers negotiating volume commitments while enterprises and managed service providers favor flexible consumption terms.
- Telecommunication Providers:Nationwide backbone and access network visibility for regulatory reporting and service assurance. Japanese carriers procure JIS-aligned platforms to satisfy MIC certification for telecommunications resilience.
- Data Centers:Hyperscale and colocation facility monitoring for cross-tenant traffic visibility and thermal optimization. United States cloud service providers drive concentrated demand for low-latency fabrics supporting sub-second fault detection.
- Managed Service Providers:Multi-tenant telemetry aggregation with customer-segregated dashboards and alerting.
- Enterprises:Campus and branch office visibility for digital transformation and hybrid workforce enablement.
- Content Delivery Networks:Edge PoP performance monitoring and origin shield optimization.
Telecommunication providers anchor recurring revenue through long-term infrastructure refresh cycles. Data centers represent the steepest expansion trajectory as hyperscale buildouts accelerate across multiple geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based hyperscale operators export telemetry architectures to European and Asian data center operators, establishing technical standards that cascade through procurement specifications worldwide.
United States
Federal cybersecurity directives and hyperscale data center buildouts drive concentrated procurement for real-time visibility fabrics. FCC outage-reporting obligations mandate carrier-grade telemetry deployment across backbone networks. Northern Virginia's data center corridor hosts the densest concentration of cloud-native telemetry implementations, with sub-second fault detection now standard.
Germany
Critical infrastructure operators in energy and railway sectors deploy certified telemetry under BSI-mandated NIS2 implementation. National cybersecurity legislation requires continuous monitoring with sovereign-cloud data residency. Bavaria's industrial automation clusters anchor demand for on-premises visibility platforms that satisfy operational technology isolation requirements.
Japan
Telecommunications resilience standards from the Ministry of Internal Affairs and Communications create regulated demand pools for JIS-aligned certification. 5G radio access network modernization pushes edge-based telemetry toward distributed base stations. Tokyo-Osaka corridor carriers procure integrated visibility platforms to satisfy MIC-mandated service assurance benchmarks.
United Kingdom
Financial services institutions deploy flow analytics to satisfy regulatory audit trail requirements for transaction network visibility. The national cybersecurity center's guidance shapes procurement criteria for critical national infrastructure operators. London's fintech concentration drives premium pricing for security monitoring applications with breach investigation capabilities.
South Korea
Semiconductor and electronics manufacturing clusters demand low-latency visibility for automated production line monitoring. National standards alignment with JIS and ISO frameworks enables technology transfer from Japanese telecommunications markets. Seoul-Incheon metropolitan area hosts the densest deployment of programmable forwarding-plane architectures in the Asia-Pacific region.
Network Telemetry Market Key Industry Players
Listed leaders compete with private specialists across capital structure and customer access dimensions. The vendor base stratifies into three tiers: silicon-integrated incumbents with switching infrastructure control, programmable forwarding-plane specialists, and software-overlay challengers. Strategic differentiation concentrates on embedding telemetry agents at the ASIC layer versus deploying probe-based overlays. Competitive moves center on M&A for programmable silicon capabilities and strategic partnerships with cloud service providers for consumption-based distribution.
Within the silicon-integrated tier, Cisco Systems and Juniper Networks exemplify architectures that leverage installed switching bases for embedded agent deployment. Arista Networks occupies a distinct position specializing in hyperscale-optimized visibility fabrics. These three entities anchor the competitive structure, with each representing divergent technical bets on where intelligence resides in the network stack.
| Leading Market Players |
|---|
| Cisco Systems |
| Juniper Networks |
| Arista Networks |
| Hewlett Packard Enterprise Development LP |
| IBM |
| NVIDIA Corporation |
| Gigamon |
| Palo Alto Networks |
| NetScout Systems |
| Others |
Cost & Logistics Intelligence
Hyperscale infrastructure scale economies compress unit costs for telemetry fabrics deployed across multi-tenant data centers, concentrating supply leverage among cloud service providers while establishing price floors for on-premises alternatives. Taiwan-based switching ASIC fabrication and South Korean memory module production anchor hardware cost structures, with NIST zero-trust mandates and EU NIS2 compliance requirements adding certification premiums that fragment pricing tiers across regulated and unregulated buyer segments.
Pricing Analysis
Current-generation silicon-embedded telemetry agents command substantial premiums over prior-generation SNMP polling architectures and next-generation quantum-encrypted streaming protocols still in pilot. Three-tier pricing structure across premium, standard, and economy levels stratifies by ASIC integration depth and JIS certification status, with German energy utilities and Japanese telecommunications carriers absorbing premium tiers for sovereign-cloud data residency. Pricing pressure stems from cloud service provider procurement consolidation favoring consumption-based SaaS models over perpetual licenses. Mid-market enterprises in the United States exhibit highest price sensitivity due to capital committee approval friction, while financial services institutions demonstrate lowest sensitivity given SEC-mandated audit trail requirements.
Supply Chain Analysis
Strategic stockpiling of programmable forwarding-plane silicon dominates inventory strategy among tier-one networking vendors, contrasting with just-in-time component flows for commodity probe appliances. Supply concentrates in Taiwan for switching ASICs, South Korea for high-bandwidth memory modules, and the United States for cloud-native software stacks. Raw material dependencies include rare earth elements for magnetics in high-speed interconnects, specialized photonics substrates for optical telemetry taps, and advanced packaging resins for thermal management. Single-source vulnerability around Taiwan Semiconductor Manufacturing capacity represents the dominant structural risk. Distribution runs through direct enterprise sales teams for on-premises deployments and cloud marketplaces for SaaS-tiered offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching infrastructure incumbents benefit from regulatory entrenchment—NIST, BSI, and MIC mandates create compliance-driven switching costs that lock in telemetry agent deployments at the silicon layer.
For Market Incumbents: Secure programmable silicon capabilities through targeted acquisitions of forwarding-plane specialists before next-generation ASIC tape-outs, and deepen certification investments for JIS-aligned and BSI-mandated platforms to forestall software-overlay challengers. The emerging threat of cloud-native telemetry startups unbundling visibility from hardware demands preemptive channel control through managed service provider partnerships. For New Entrants and Emerging Players: Edge-based deployment gaps at 5G base stations in Brazil and Saudi Arabia offer the most penetrable white-space, where incumbent switching vendors lack localized presence and telecommunications providers prioritize rapid radio access network modernization. A telemetry-as-a-service go-to-market angle bypasses capital committee friction among mid-market enterprises while capturing recurring revenue streams. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors programmable forwarding-plane specialists with existing cloud service provider relationships and JIS certification pathways. Long-term viability over the next decade hinges on embedding agents at the ASIC layer rather than deploying probe-based overlays. The signal to watch is hyperscale capital expenditure inflection for distributed edge infrastructure buildouts.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Layer Agent Integration | Embedding telemetry at ASIC layer locks in switching infrastructure incumbents against software-overlay challengers. |
| JIS Certification Pathway Investment | Japanese MIC resilience standards create regulated demand pools with premium pricing power for compliant vendors. |
| Edge-Based Deployment Expansion | 5G radio access network modernization in Brazil and Saudi Arabia opens white-space with minimal incumbent competition. |
| Consumption-Based SaaS Transition | Telemetry-as-a-service models capture mid-market enterprise demand while bypassing capital committee approval cycles. |
| Strategic Partnership with Hyperscalers | Cloud service provider procurement consolidation favors vendors integrated into distributed infrastructure buildouts. |
Research Approach
A standing panel of network operations executives at cloud service providers, telecommunications carrier engineering leads, critical infrastructure CISOs, and hyperscale data center architects provided ongoing calibration across the study period. Primary interview findings combined with secondary validation from FCC outage reporting databases, NIST cybersecurity framework documentation, EU NIS2 implementation guidance, and JIS certification registry records. Bottom-up telemetry deployment counts triangulated against top-down infrastructure capital expenditure disclosures from major cloud providers.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler capex trajectory filings and telecommunications equipment trade data. The analytical framework modeled segmentation dimensions across solution type, deployment mode, application, and end-user industry across the analysis window. CAGRs derived from curve-fitting historical deployment velocity against projected infrastructure buildout schedules, with gRPC protocol adoption curves and zero-trust mandate implementation timelines serving as industry-specific forecast inputs.
Forecasts assume regulatory continuity in NIST, BSI, and MIC compliance regimes; material policy shifts would require re-modeling. Forecasts reflect assumptions around Taiwan semiconductor fabrication capacity stability and rare earth element supply chain integrity. Revision becomes warranted when hyperscale capital expenditure inflection or sovereign data-localization mandate expansion crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
North America Network Management Solutions Market
Network Technology
Mobile Accelerator Market
Network Technology
Gigabit Ethernet Market
Network Technology
Lit Fiber Market
Network Technology
Global Network Probe Market
Network Technology
Mobile Backhaul Market
Network Technology
5G Enterprise Private Network Market
Network Technology
Private Network Services Market
Network Technology
Global Network Monitoring Market
Network Technology
Europe Video Conferencing Hardware Market
Network Technology
ISP Management Systems Market
Network Technology
5G CPE Device Market
Network Technology
GCC Set-Top Box Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
Global Industrial Ethernet Switch Market
Network Technology
GPON WIFI6 Home Gateway Market