
 5G CPE Device Market | 2026-2036
5G CPE Device Market Size, Share, and Industry Trends Forecast 2026-2036
5G CPE Device Market Insights
The EU Green Deal is realigning procurement criteria for 5G CPE hardware across European telecom operators, pushing vendors toward energy-efficient designs and recyclable materials. Samsung Electronics leverages its semiconductor foundry capacity to control modem supply chains for premium indoor units. Nokia Corporation anchors its position through carrier aggregation intellectual property that spans sub-6 GHz and mmWave configurations. Huawei Technologies competes aggressively on outdoor CPE pricing, though its access narrows in markets with national security screening requirements.
A 5G CPE device is a customer premises equipment unit that bridges 5G cellular signals to local wired or Wi-Fi networks, typically incorporating 4x4 MIMO antenna arrays and supporting throughput above 1 Gbps for residential and enterprise backhaul. The fixed wireless access segment commands the deepest carrier investment cycles as operators bypass fiber trenching in suburban and rural footprints. Sub-6 GHz technology dominates volume shipments due to propagation advantages, while mmWave configurations concentrate in dense urban enterprise zones where bandwidth density justifies infrastructure cost. Carrier aggregation capabilities differentiate premium tiers, enabling simultaneous bonding of multiple spectrum bands to sustain peak rates.
The FCC governs device certification and spectrum allocation in the United States, while ETSI and CE marking frameworks shape European market access and electromagnetic compatibility standards. Japan's MIC and South Korea's MSIT enforce national 5G spectrum roadmaps that directly determine CPE frequency support requirements and import eligibility. Stakeholders must monitor spectrum auction timelines and national security review expansions, as these mechanisms increasingly determine which vendors qualify for operator tenders before technical merit enters the equation.
Market Dynamics
Carrier aggregation intellectual property is consolidating competitive advantage among modem suppliers as sub-6 GHz and mmWave bonding becomes mandatory for operator certification. Spectrum reallocation timelines in the United States and EU F-Gas Regulation compliance deadlines are compressing vendor qualification windows.
Growth Catalysts
- Enterprise fixed wireless access:Telecom operators in Germany and the United States are bypassing fiber trenching in suburban corridors. Manufacturing clusters demand ultra-reliable low-latency connectivity for industrial automation backhaul.
- FCC spectrum reallocation:Mid-band auction releases are expanding addressable spectrum for CPE manufacturers. Device certification pathways now prioritize sub-6 GHz and mmWave dual-mode configurations.
- EU Green Deal procurement mandates:Energy-efficient designs and recyclable materials are becoming mandatory evaluation criteria. European operators are rewriting tender specifications to exclude non-compliant hardware.
Market Restraints
- Modem supply concentration:Advanced node semiconductor foundry capacity is bottlenecked among three suppliers. CPE vendors face allocation uncertainty for premium indoor units.
- National security screening:Markets with expanded vendor review requirements are excluding qualified low-cost manufacturers. Outdoor CPE pricing pressure narrows as competitive supply contracts.
- mmWave propagation limitations:Line-of-sight requirements restrict deployment to dense urban enterprise zones. Suburban and rural fixed wireless access relies on lower-margin sub-6 GHz configurations.
Strategic Opportunities
- Industrial automation corridors:Dense manufacturing zones in Germany require ultra-reliable low-latency connectivity. Premium CPE tiers with carrier aggregation command pricing premiums in these deployments.
- EU F-Gas Regulation retrofit cycles:Equipment replacement mandates are accelerating refresh timelines. Vendors with pre-certified compliant designs capture tender advantages.
- Convergence of Wi-Fi 7 and 5G:Local network bridging is integrating cellular backhaul with next-generation wireless LAN. Enterprise buyers are consolidating premises equipment procurement around unified platforms.
Industry Challenges
- RF engineering talent scarcity:4x4 MIMO antenna array design expertise concentrates among legacy base station specialists. CPE vendors compete for limited electromagnetic simulation and field testing capacity.
- Multi-regional certification timelines:FCC, CE marking, and Japan MIC approvals require parallel testing tracks. Product launches slip by quarters when electromagnetic compatibility failures trigger redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G CPE Device Market |
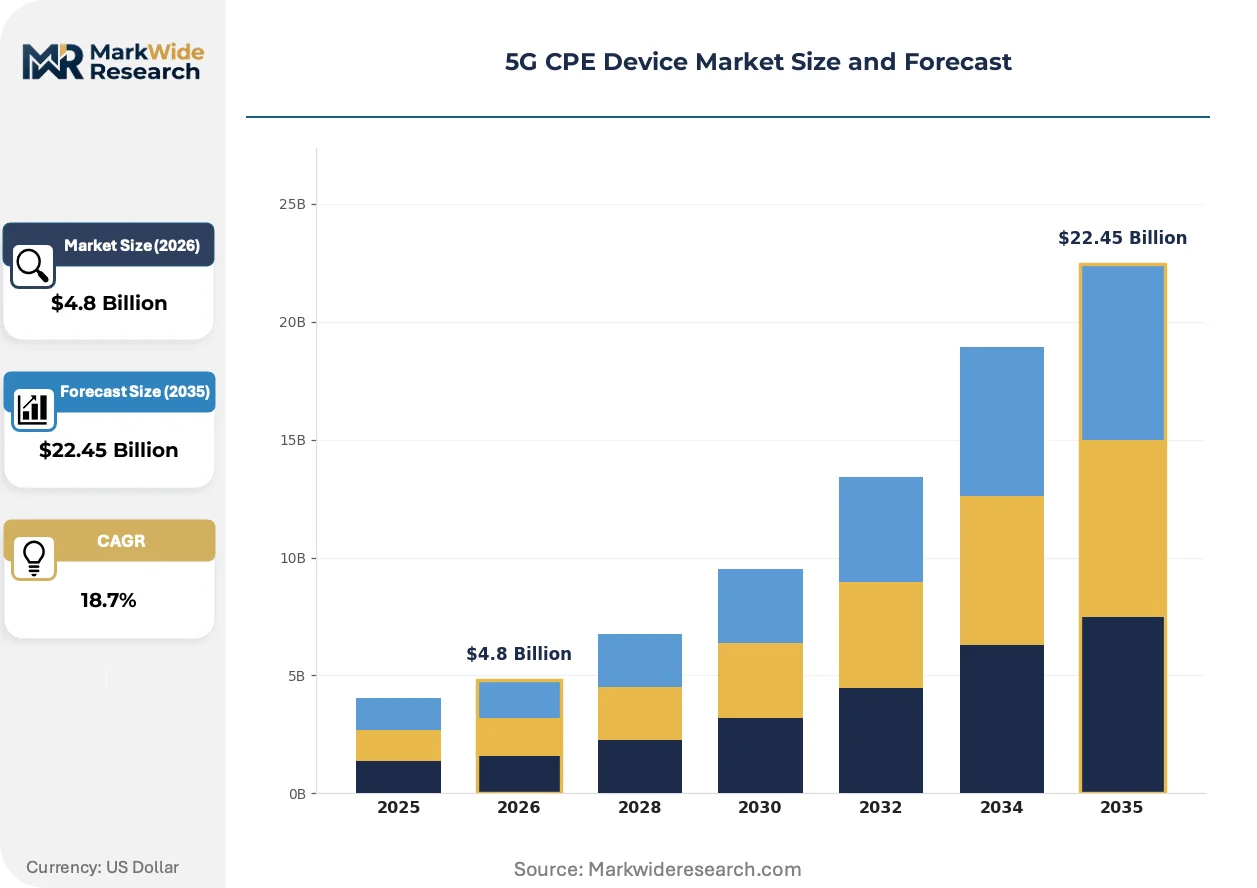
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor CPE, Outdoor CPE, Wi-Fi Gateway, Fixed Wireless Access Technology: Sub-6 GHz, mmWave, Dual-Band, Carrier Aggregation End User: Residential, Commercial, Industrial, Enterprise Installation Type: Wall-Mount, Pole-Mount, Desktop, Embedded |
| Companies Covered | Samsung Electronics, CommScope, Huawei Technologies, Qualcomm Incorporated, Sagemcom Broadband, Nokia Corporation, ZTE Corporation, TP-Link, Ericsson AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G CPE Device Market Trends and Innovations
Open RAN interface standards are decoupling modem and radio hardware from baseband software, enabling new vendor entry and compressing incumbent integration advantages. Certification complexity is rising as operators demand multi-vendor interoperability.
Carrier aggregation firmware is integrating sub-6 GHz and mmWave bands into unified throughput management. Enterprise fixed wireless access buyers in Germany and the United States are mandating simultaneous bonding capabilities in premium tenders. This integration is compressing single-band CPE into commodity positioning while elevating multi-band units.
The EU F-Gas Regulation is banning fluorinated greenhouse gases in cooling systems for outdoor CPE enclosures. Equipment suppliers are redesigning thermal management around phase-change materials and passive heat dissipation. Outdoor unit manufacturers serving European operators face 2027 compliance deadlines that favor early redesign investments.
Buying committees are consolidating premises equipment procurement across IT and facilities functions. Telecom operators in the United States are unbundling CPE from service contracts, shifting capital expenditure risk to enterprise customers. This pattern is most visible in suburban manufacturing zones where fixed wireless access displaces leased line commitments.
5G CPE Device Market Segmentation
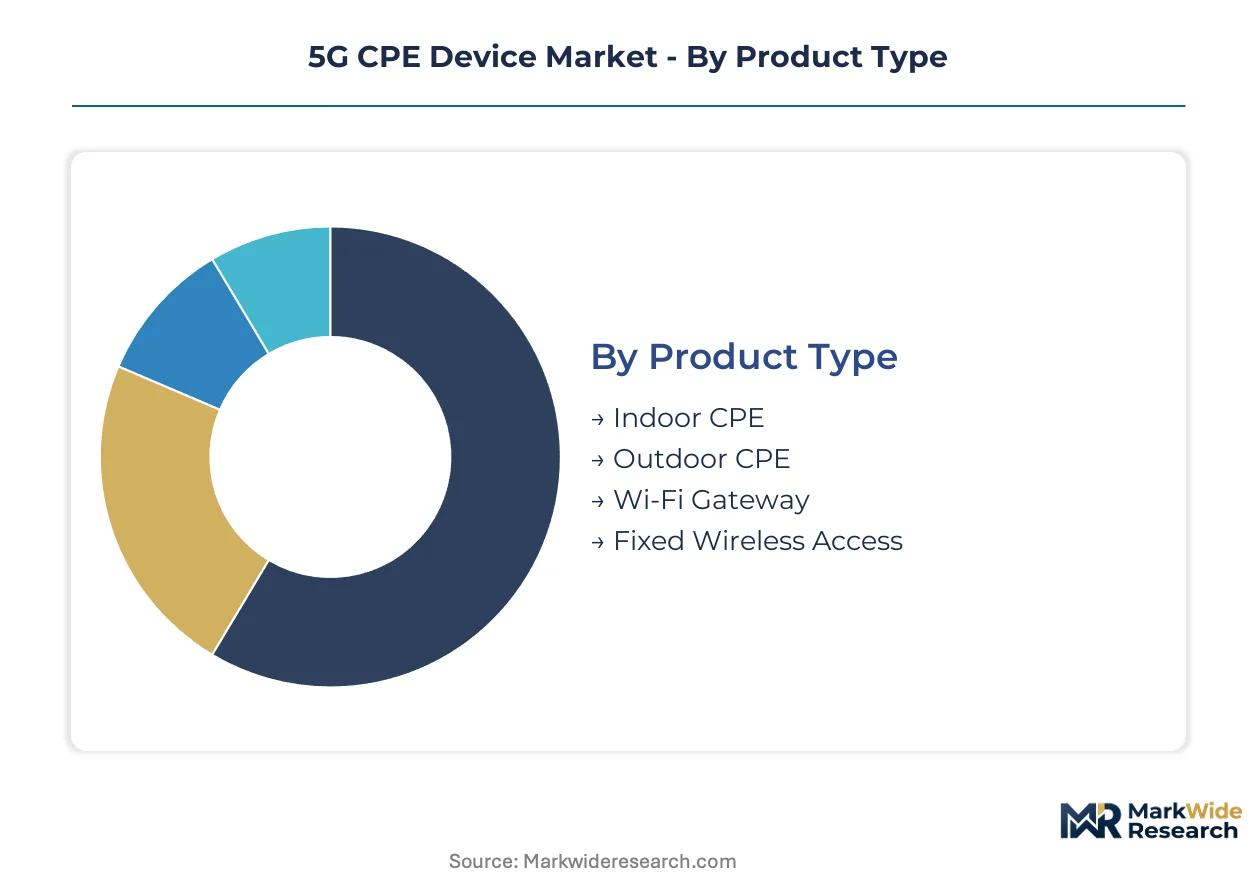
5G CPE segmentation reflects divergent engineering requirements across propagation environments, thermal constraints, and spectrum licensing patterns. Procurement specifications from German industrial automation clusters and U.S. suburban fixed wireless access deployments are compressing single-band configurations into commodity positioning while elevating multi-band, carrier-aggregation-capable tiers.
Product Type:
Antenna configuration and thermal envelope specifications differentiate hardware categories, with enclosure IP ratings and MIMO array sizing determining addressable deployment scenarios.
- Indoor CPE:Compact units integrate 4x4 MIMO arrays within temperature-controlled residential and office environments. Demand concentrates in U.S. suburban corridors where Verizon and T-Mobile deploy self-install customer premises equipment for fixed wireless access services constrained by FCC device certification timelines.
- Outdoor CPE:Ruggedized enclosures with IP67 ratings and active thermal management sustain operation across -40°C to +60°C temperature swings. German manufacturing clusters in Bavaria and Baden-Württemberg specify these units for industrial automation backhaul where EU F-Gas Regulation compliance mandates phase out fluorinated greenhouse gas cooling systems.
- Wi-Fi Gateway:Converged platforms bridge 5G cellular backhaul with Wi-Fi 6E/7 local distribution, reducing premises equipment count for enterprise buyers.
- Fixed Wireless Access:Purpose-built subscriber units optimized for carrier-managed service models with remote diagnostics and zero-touch provisioning capabilities.
Indoor CPE leads on scale; outdoor CPE leads on momentum.
Technology:
Spectrum band selection directly determines propagation range, penetration capability, and achievable throughput density for operator network planners.
- Sub-6 GHz:Frequencies below 6 GHz deliver superior building penetration and non-line-of-sight coverage, making this the default configuration for rural and suburban fixed wireless access. Volume shipments dominate as carriers prioritize coverage economics over peak rate marketing.
- mmWave:Millimeter-wave configurations concentrate in dense urban enterprise zones across Seoul, Tokyo, and Manhattan where bandwidth density justifies infrastructure cost and line-of-sight constraints are manageable. These units command pricing premiums but face propagation limitations that restrict addressable market scope.
- Dual-Band:Simultaneous sub-6 GHz and mmWave radio chains enable dynamic spectrum selection based on real-time link quality.
- Carrier Aggregation:Firmware-defined bonding of multiple spectrum blocks sustains peak throughput during congestion events, now mandatory for premium enterprise tenders.
Sub-6 GHz configurations anchor volume; carrier aggregation capabilities are gaining share fastest.
End User:
Latency requirements, reliability specifications, and procurement authority structures fragment demand across consumer and institutional buyer categories.
- Residential:Price-sensitive consumers prioritize self-installation simplicity and Wi-Fi coverage extension over peak cellular throughput. U.S. cable displacement campaigns by T-Mobile and Verizon are accelerating subscriber acquisition in suburban markets where fiber trenching costs prove prohibitive.
- Enterprise:IT procurement committees mandate carrier aggregation, dual-band support, and unified Wi-Fi 7 bridging for premises consolidation. German automotive suppliers and U.S. logistics hubs specify ultra-reliable low-latency connectivity tiers with service-level agreements below 10ms.
- Commercial:Small and medium businesses with limited IT staffing favor managed service bundles over capital equipment ownership.
- Industrial:Hardened specifications for electromagnetic interference immunity and extended temperature operation serve manufacturing floor deployments.
Residential segments dominate shipment volume; enterprise segments command steepest expansion trajectory.
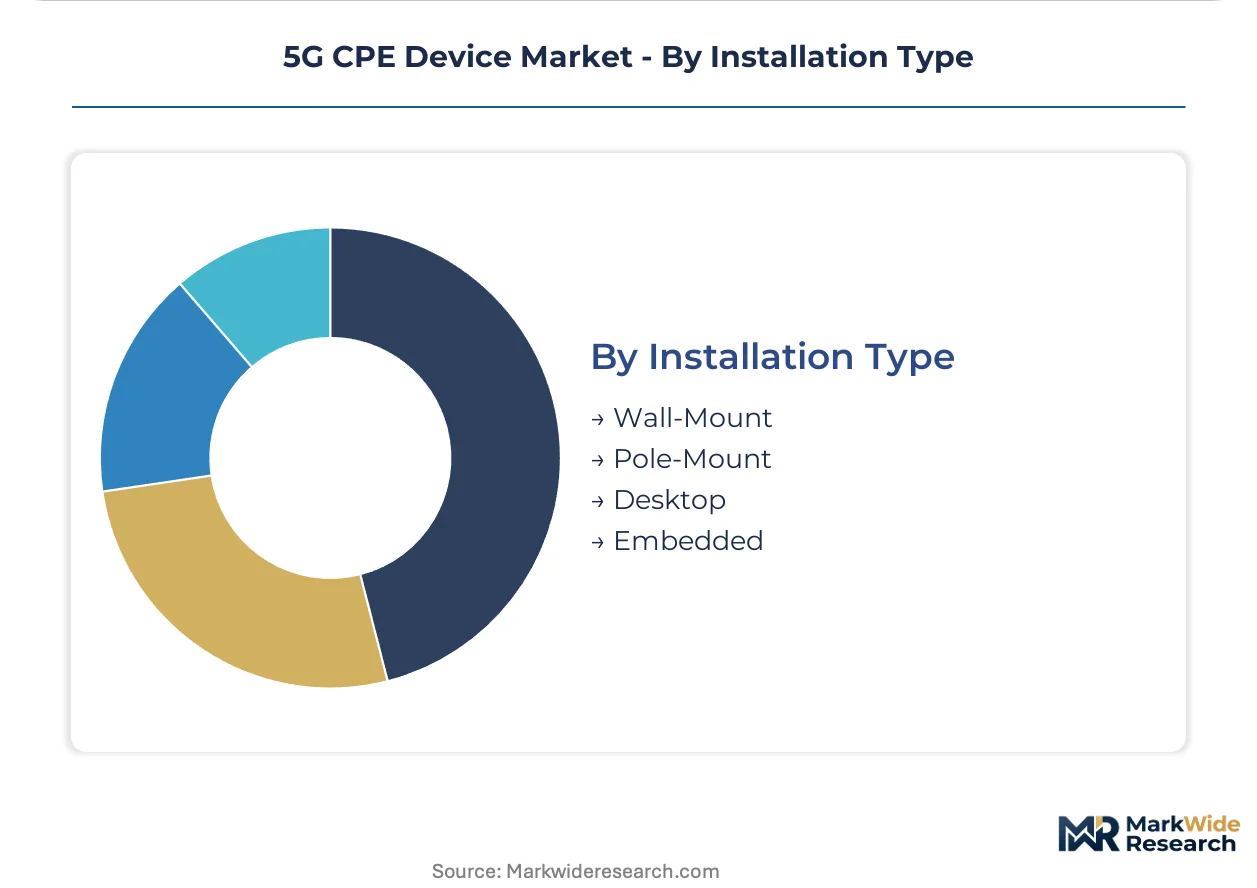
Installation Type:
Mounting methodology determines antenna positioning flexibility, technician dispatch requirements, and total cost of ownership for operator deployment economics.
- Wall-Mount:Bracket-based installation on building exteriors optimizes signal reception while protecting equipment from ground-level interference. Korean operators deploy these extensively in apartment-dense districts where rooftop access is restricted.
- Pole-Mount:Street furniture and utility pole attachment enables line-of-sight optimization for mmWave links in urban corridors. Japanese MIC certification requirements specify wind load and seismic resilience standards that filter vendor qualification pools.
- Desktop:Plug-and-play positioning near windows suits consumer self-installation scenarios with minimal technical support burden.
- Embedded:Integration into third-party equipment such as industrial gateways and vehicle telematics units enables OEM supply relationships.
Wall-mount configurations sustain highest deployment velocity; pole-mount installations are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 5G CPE device industry traces its commercial scaling to South Korea's 2019 national 5G launch, with subsequent infrastructure buildouts in the United States and Germany establishing the three dominant demand centers that now shape equipment certification requirements and spectrum band priorities.
United States
Verizon and T-Mobile deploy self-install indoor units across suburban corridors to displace cable broadband, with fixed wireless access subscriber growth exceeding fiber trenching economics. FCC mid-band auction releases and refreshed device certification pathways prioritize sub-6 GHz and mmWave dual-mode configurations. Manufacturing zones in Michigan and Ohio specify ultra-reliable low-latency connectivity for industrial automation backhaul.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg mandate carrier aggregation capabilities with service-level agreements below 10ms for factory floor connectivity. EU F-Gas Regulation compliance deadlines accelerate outdoor CPE refresh cycles, favoring vendors with pre-certified thermal management redesigns. Dense manufacturing corridors around Stuttgart and Munich concentrate premium-tier procurement for industrial automation.
South Korea
SK Telecom and KT Corporation anchor mmWave deployment velocity in Seoul's apartment-dense districts, with wall-mount configurations optimizing signal reception where rooftop access faces restrictions. MSIT national spectrum roadmaps determine CPE frequency support requirements and import eligibility thresholds. The Seoul Capital Area generates concentrated demand for converged Wi-Fi 7 and 5G gateway platforms.
Japan
NTT Docomo and KDDI drive enterprise fixed wireless access in Tokyo and Osaka enterprise zones, with MIC certification requirements specifying wind load and seismic resilience standards for pole-mount installations. JIS standards and electromagnetic compatibility frameworks filter vendor qualification pools. Chubu manufacturing clusters around Nagoya specify hardened outdoor units for extended temperature operation.
China
MIIT spectrum allocation frameworks and GB standards shape domestic CPE frequency support and electromagnetic compatibility requirements. Yangtze River Delta industrial zones in Shanghai and Jiangsu province deploy outdoor subscriber units for smart factory backhaul. National security screening mechanisms increasingly determine vendor qualification for operator tenders before technical evaluation.
5G CPE Device Market Competitive Landscape
Capital-heavy producers with captive semiconductor foundry capacity compete with asset-light designers dependent on external modem supply allocations. The vendor base concentrates around three modem suppliers whose advanced node capacity determines allocation certainty for premium indoor units. Strategic archetypes span vertically integrated electronics conglomerates, telecom infrastructure specialists with carrier aggregation intellectual property, and cost-optimized equipment fabricators. Competitive moves center on strategic partnerships for spectrum band certification and portfolio diversification into converged Wi-Fi gateway platforms.
Among vertically integrated electronics conglomerates, Samsung Electronics occupies a position representing captive semiconductor supply chain control, while Nokia Corporation exemplifies the infrastructure specialist archetype anchored in carrier aggregation intellectual property. Huawei Technologies sits within the cost-optimized equipment fabricator tier, though its market access narrows in jurisdictions with expanded national security review requirements. These three anchors illustrate how competitive positioning fragments across supply chain control, standards-essential patent holdings, and pricing flexibility vectors.
| Leading Market Players |
|---|
| Samsung Electronics |
| CommScope |
| Huawei Technologies |
| Qualcomm Incorporated |
| Sagemcom Broadband |
| Nokia Corporation |
| ZTE Corporation |
| TP-Link |
| Ericsson AB |
| Others |
Pricing and Supply Chain Analysis
Carrier aggregation firmware integration is compressing single-band 5G CPE into commodity positioning while elevating multi-band premium tiers, simultaneously concentrating cost advantages among modem suppliers with captive foundry capacity and fragmenting pricing power across downstream equipment vendors dependent on external semiconductor allocations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with carrier aggregation certification and EU F-Gas Regulation compliance serving as the primary price differentiation drivers. Cost compression in economy sub-6 GHz units is intensifying because modem supply concentration limits vendor bargaining power. Residential fixed wireless access subscribers exhibit highest price sensitivity, while German automotive suppliers purchasing ultra-reliable low-latency enterprise tiers demonstrate minimal elasticity.
Supply Chain Analysis
Reverse-logistics flows for outdoor CPE refurbishment are emerging as operators in Germany and South Korea extend equipment lifecycles to manage F-Gas Regulation compliance costs. Manufacturing concentrates in China, South Korea, and Taiwan, with advanced node semiconductor foundry capacity serving as the critical bottleneck. Raw material dependencies include gallium nitride substrates, high-frequency laminates, and rare-earth magnet components. Single-source vulnerability in 5G modem supply creates systemic exposure. Distribution runs through carrier-managed procurement channels and enterprise IT integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
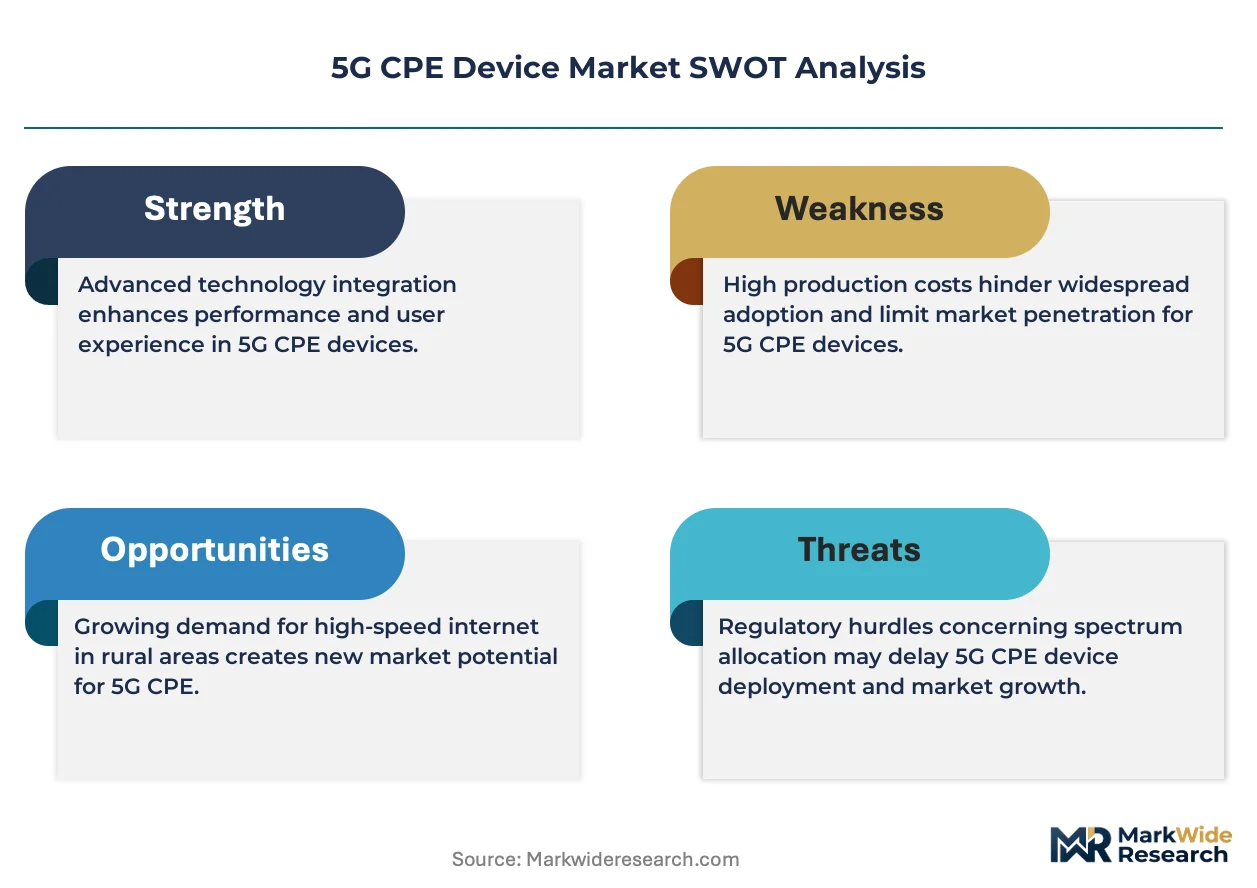
The 5G CPE device market functions as a stable compounder anchored by infrastructure replacement cycles, with FCC spectrum reallocation and EU F-Gas Regulation mandates ensuring sustained equipment refresh demand regardless of macroeconomic volatility.
For Market Incumbents: Lock in carrier aggregation intellectual property advantages through accelerated sub-6 GHz and mmWave dual-mode certification investments. Secure captive foundry allocations for premium indoor units to defend against modem supply concentration risks. Deepen channel control over German industrial automation corridors where ultra-reliable low-latency specifications command durable pricing premiums. For New Entrants and Emerging Players: Open RAN interface compatibility offers a technology-first wedge into operator procurement committees seeking multi-vendor interoperability. Target U.S. suburban fixed wireless access deployments where Verizon and T-Mobile unbundle CPE from service contracts, shifting capital expenditure risk to enterprise buyers. Pursue white-label manufacturing partnerships with established modem suppliers to bypass allocation bottlenecks. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light CPE designers lacking captive semiconductor capacity but possessing strong regional certification track records. Long-term viability over the projection horizon rests on convergence plays bridging 5G cellular backhaul with Wi-Fi 7 local distribution. Monitor FCC mid-band auction timelines and EU F-Gas Regulation enforcement intensity as inflection indicators for equipment refresh velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Aggregation Certification Investment | Dual-mode sub-6 GHz and mmWave qualification unlocks premium enterprise tenders in German manufacturing corridors. |
| F-Gas Regulation Pre-Compliance Redesign | Phase-change thermal management certification captures outdoor CPE replacement cycles ahead of 2027 deadlines. |
| Converged Wi-Fi 7 Gateway Development | Unified premises equipment consolidation addresses enterprise buyer demand for reduced hardware count. |
| Open RAN Interface Partnership | Multi-vendor interoperability commitments satisfy operator procurement committees seeking supply diversification. |
| Industrial Automation Corridor Targeting | Ultra-reliable low-latency specifications for Bavarian automotive suppliers sustain pricing premiums. |
Research Methodology
Multiple input streams — executive interviews with carrier procurement officers, technical discussions with RF engineering specialists, and validation sessions with semiconductor supply chain managers — were reconciled against secondary sources including FCC equipment authorization databases, ETSI technical specifications, and operator capex disclosure filings. Bottom-up shipment estimates by product tier and technology configuration were triangulated against top-down market value reconstructions.
Data-stream reconciliation across the analysis window employed a segmented growth model incorporating product type, spectrum band, end-user category, and regional regulatory cluster as primary dimensions. CAGRs were derived from fitted growth curves applied to carrier deployment timelines and equipment replacement cycles. Forecast inputs included spectrum auction schedules, F-Gas Regulation compliance deadlines, and fixed wireless access subscriber penetration trajectories.
The model holds under stable regulatory enforcement and continued carrier capital commitment to fixed wireless access; deviation in spectrum reallocation timing or modem supply disruption would shift equipment availability and pricing trajectories. Practitioners should monitor FCC certification queue lengths and foundry capacity allocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Open RAN Market
Network Technology
DNS DHCP and IPAM Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
ISP Management Systems Market
Network Technology
Network Emulator Market
Network Technology
Network Equipment Market
Network Technology
Global GPS Market
Network Technology
Data Center Switches Market
Network Technology
Gigabit Ethernet Market
Network Technology
United States and European Fiber Optic Cable Market
Network Technology
Global Carrier Ethernet Equipment Market
Network Technology
Structured Cabling Market
Network Technology
MENA Wireless Routers Market
Network Technology
Global Internet Transit Market
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
Mobile Accelerator Market