
 Network Devices Market | 2026-2036
Network Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Network Devices Market Outlook
Enterprise buyers are collapsing their historical preference for on-premises-only network stacks as hybrid work models force cloud-first procurement. Cisco Systems leverages its installed base of enterprise routers to sustain recurring software subscription revenue. Huawei Technologies anchors its position through in-house semiconductor fabrication for carrier-grade switching gear. Arista Networks differentiates in hyperscale data center deployments where low-latency spine architectures dominate rack-level traffic.
Network devices are electronic hardware systems that forward, filter, and route data packets across local and wide area networks using protocols such as TCP/IP, MPLS, and BGP, with throughput ratings commonly measured in terabits per second for backbone-class routers. These systems enable enterprise connectivity, cloud service delivery, and telecommunications infrastructure by maintaining deterministic packet delivery across heterogeneous physical media. Router deployments command the highest capital allocation among device types due to their role at network boundaries where security policy enforcement and WAN optimization converge. Cloud-based deployment models are expanding fastest as organizations repatriate management overhead to managed service providers. Fiber optic connectivity technology captures premium pricing relative to copper Ethernet because single-mode installations support 100G+ wavelengths over distances exceeding eighty kilometers without signal regeneration.
The Federal Communications Commission in the United States mandates equipment authorization under Part 15 rules for radio-frequency emitting network hardware, while the European Union's Radio Equipment Directive and Cybersecurity Act impose conformity assessment and vulnerability disclosure obligations on devices sold within member states. China's Ministry of Industry and Information Technology enforces GB standards for domestic network equipment certification, creating divergent testing requirements for multinational vendors. India's Telecom Engineering Centre issues technical approvals that gate market entry for imported routing and switching platforms. Stakeholders must monitor how divergent national cybersecurity certification schemes fragment product development roadmaps and compliance budgets across major sales territories.
Market Dynamics
Cloud-ready switching platforms are collapsing enterprise procurement timelines as IT departments abandon three-year hardware refresh cycles in favor of subscription-based network-as-a-service models.
Growth Catalysts
- EU NIS2 Directive:The directive mandates vulnerability disclosure and incident reporting for critical network infrastructure, forcing replacement of legacy routing hardware and accelerating compliance-driven procurement across European utilities and transport operators.
- Hyperscale data center buildouts:Cloud service providers in India are deploying spine-leaf architectures at unprecedented density, driving demand for 400G-capable switching platforms in Mumbai and Hyderabad facilities.
- Silicon photonics integration:Co-packaged optics technology is reducing power consumption per bit by eliminating pluggable transceivers, enabling rack-scale deployment of AI training clusters without thermal constraints.
Market Restraints
- Advanced semiconductor fabrication concentration:Production of merchant silicon for programmable switching ASICs concentrates in Taiwan-based foundries, exposing supply continuity to geopolitical friction and export control volatility.
- Fiber optic component shortages:Single-mode transceivers and coherent DSPs face allocation constraints due to limited indium phosphide substrate supply, extending lead times for 100G+ wavelength deployments.
- Copper Ethernet substitution ceiling:Twisted-pair cabling cannot sustain signal integrity beyond 10Gbps at standard distances, forcing premature infrastructure replacement in campus environments where fiber trenching costs prove prohibitive.
Strategic Opportunities
- India's BharatNet expansion:The government's rural broadband initiative targets 600,000 village-level network access points, creating demand for ruggedized, low-cost routing platforms with integrated power-over-Ethernet capabilities.
- Convergence of SD-WAN and SASE frameworks:Enterprises are collapsing separate security and connectivity procurement into unified cloud-delivered edge stacks, opening white space for vendors with integrated zero-trust network access.
- EU Cybersecurity Act certification:The Common Criteria-based assurance framework creates premium positioning for hardware vendors achieving EAL4+ ratings, particularly in European defense and financial infrastructure tenders.
Industry Challenges
- Embedded systems firmware expertise scarcity:Vendors struggle to recruit engineers proficient in real-time operating systems and hardware security module integration, delaying secure boot implementation timelines.
- Multi-vendor interoperability certification:Enterprise buyers demand seamless operation across switching platforms from different suppliers, forcing extensive protocol conformance testing that compresses margin on mid-range product lines.
- Legacy MPLS backbone migration complexity:Carriers face decade-long transition timelines to segment routing and EVPN architectures, straining engineering resources and deferring new platform revenue recognition.
Report Scope
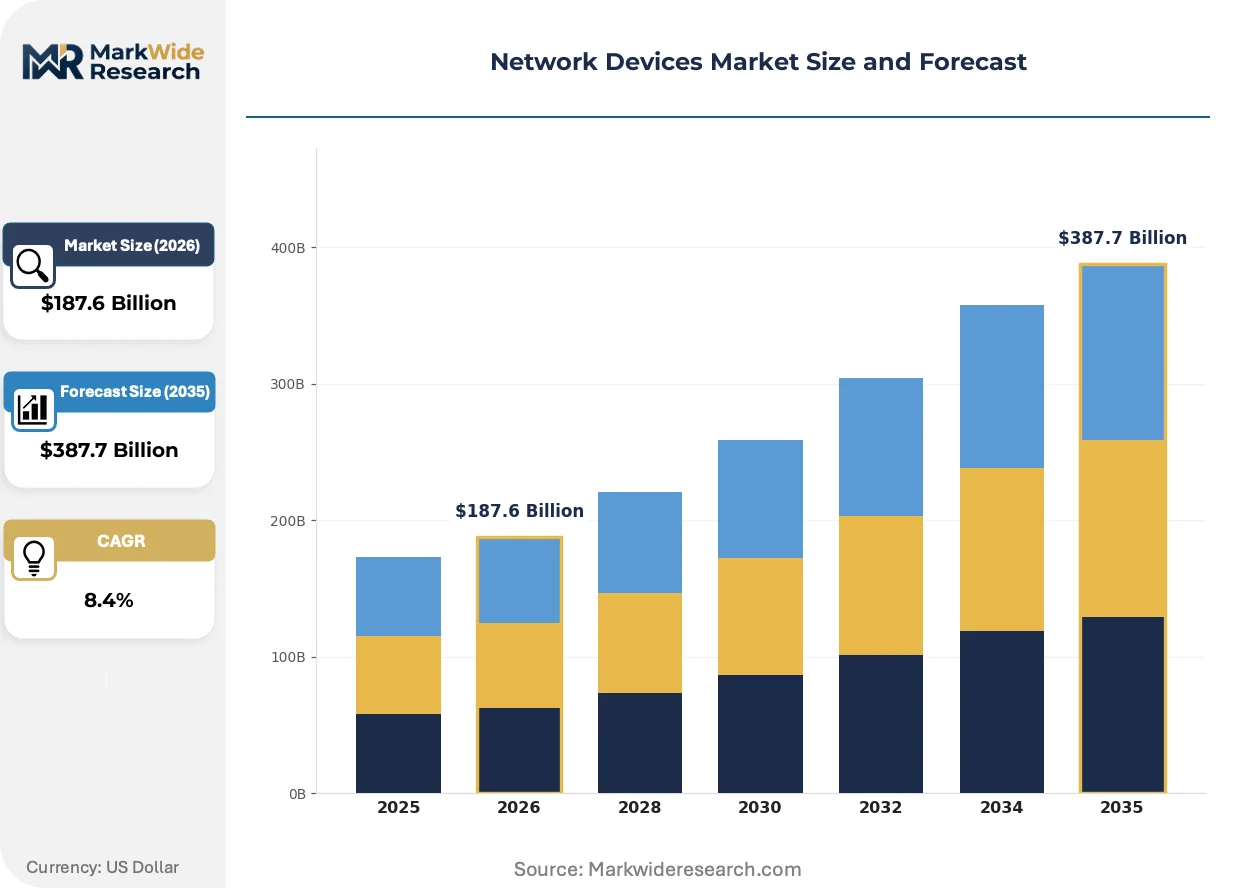
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Devices Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $387.7 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Router, Switch, Hub, Bridge Deployment Model: On-Premises, Cloud-Based, Hybrid, Virtual End User: Enterprise, SMB, Educational Institution, Government Connectivity Technology: Wired, Wireless, Fiber Optic, Microwave |
| Companies Covered | Cisco Systems, Huawei Technologies, Hewlett Packard Enterprise, Juniper Networks, Arista Networks, Broadcom, Nokia, Samsung Electronics, ZTE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Devices Market Strategic Shifts
Disaggregation of hardware and software control planes is rewriting vendor competitive boundaries, while regulatory mandates and procurement model evolution reshape how network infrastructure reaches end users.
White-box switching hardware paired with independent network operating systems is decomposing the traditional integrated-router market. Hyperscale operators and large financial institutions are adopting merchant silicon-based platforms at accelerating velocity. This decomposition enables buyers to unbundle software licensing from chassis procurement, compressing incumbent vendor maintenance revenue streams and shifting value capture toward software-defined networking stacks.
The EU AI Act imposes risk-based conformity assessment obligations on network equipment deployed in high-stakes AI infrastructure. Hardware vendors must document training data provenance and algorithmic transparency for management plane automation tools. European data center operators are responding by demanding hardware bill-of-materials disclosure and firmware signing key escrow arrangements in procurement contracts.
Enterprise buyers are consolidating network infrastructure spend under managed service contracts with telecom carriers and systems integrators. Channel disintermediation is displacing traditional value-added reseller relationships, particularly in mid-market manufacturing verticals. This pattern concentrates most visibly in Germany, where Mittelstand firms prefer OpEx-based network subscriptions over capital-intensive ownership models.
Network Devices Market Segmentation
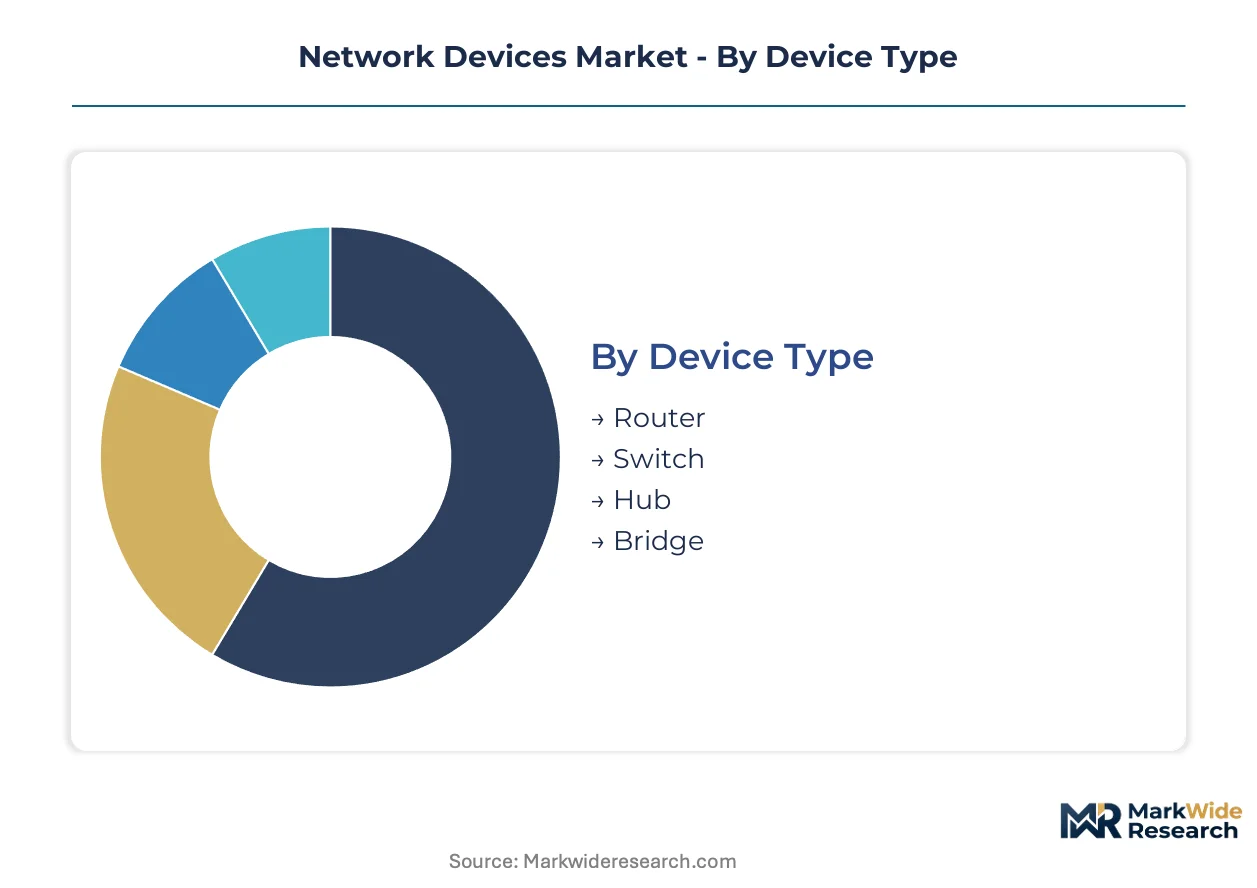
Network device procurement patterns diverge sharply across deployment contexts, with regulatory compliance timelines and infrastructure lifecycle stages dictating hardware selection. Buyers segment their spending based on where control plane intelligence resides and which connectivity medium matches their physical plant constraints.
Device Type:
Regulatory differentiation separates carrier-grade routing platforms from campus switching gear, with critical infrastructure mandates in the EU and India forcing hardened firmware architectures at network boundaries.
- Router:Backbone-class systems execute BGP and MPLS protocols at terabit-scale throughput, anchoring WAN boundaries where the EU NIS2 Directive mandates vulnerability disclosure and incident reporting capabilities. European utilities and Indian telecom operators are replacing legacy hardware to meet these compliance deadlines.
- Switch:Layer 2/3 forwarding platforms dominate data center rack-level traffic, with spine-leaf architectures in Mumbai and Hyderabad hyperscale facilities driving demand for 400G-capable merchant silicon. Thermal constraints from AI training clusters are accelerating co-packaged optics adoption.
- Hub:Simple broadcast repeaters persist in legacy industrial environments where protocol compatibility outweighs performance requirements. Replacement cycles extend to decade-plus horizons in manufacturing verticals with frozen infrastructure budgets.
- Bridge:Protocol translation devices connect heterogeneous network segments in campus environments undergoing gradual fiber retrofit. Demand concentrates where copper Ethernet distance limitations force media conversion at building demarcation points.
Established volume favors Router; emerging adoption favors Switch.
Deployment Model:
Cost tier stratification separates capital-intensive ownership from operational expenditure models, with mid-market manufacturers in Germany preferring subscription-based network-as-a-service contracts over chassis procurement.
- On-Premises:Physical hardware ownership maintains control plane autonomy for defense and financial infrastructure subject to data residency requirements. EAL4+ certification under the EU Cybersecurity Act commands premium positioning in these deployments.
- Cloud-Based:Managed service providers absorb management overhead as enterprises repatriate operational burden, expanding fastest among organizations abandoning three-year hardware refresh cycles. Channel disintermediation displaces traditional reseller relationships in this segment.
- Hybrid:Split control plane architectures preserve on-premises forwarding while centralizing policy management in cloud orchestration layers. Complexity from multi-vendor interoperability certification compresses margins for mid-range product lines.
- Virtual:Software-defined network functions running on commodity compute enable rapid scaling without physical hardware procurement. NFV adoption concentrates in service provider core networks undergoing MPLS-to-segment-routing transitions.
Capital retention favors On-Premises; OpEx migration favors Cloud-Based.
End User:
Application urgency varies across organizational scale, with government digitalization programs in India and rural broadband initiatives creating demand for ruggedized, low-cost platforms with integrated power-over-Ethernet.
- Enterprise:Large organizations consolidate security and connectivity procurement into unified SASE frameworks, collapsing separate WAN edge and zero-trust network access spending. Hyperscale cloud providers anchor demand for spine-leaf switching density.
- SMB:Mid-market firms lack dedicated network engineering staff, driving preference for carrier-managed service contracts. Procurement concentrates through telecom channels rather than value-added resellers.
- Educational Institution:Campus environments face copper Ethernet substitution ceilings where fiber trenching costs prove prohibitive. 10Gbps twisted-pair limitations force premature infrastructure replacement decisions.
- Government:Critical infrastructure operators face tightened cybersecurity compliance timelines from the EU NIS2 Directive and India's Telecom Engineering Centre technical approvals. Procurement prioritizes firmware signing key escrow and hardware bill-of-materials disclosure.
Compliance-driven replacement favors Government; subscription migration favors SMB.
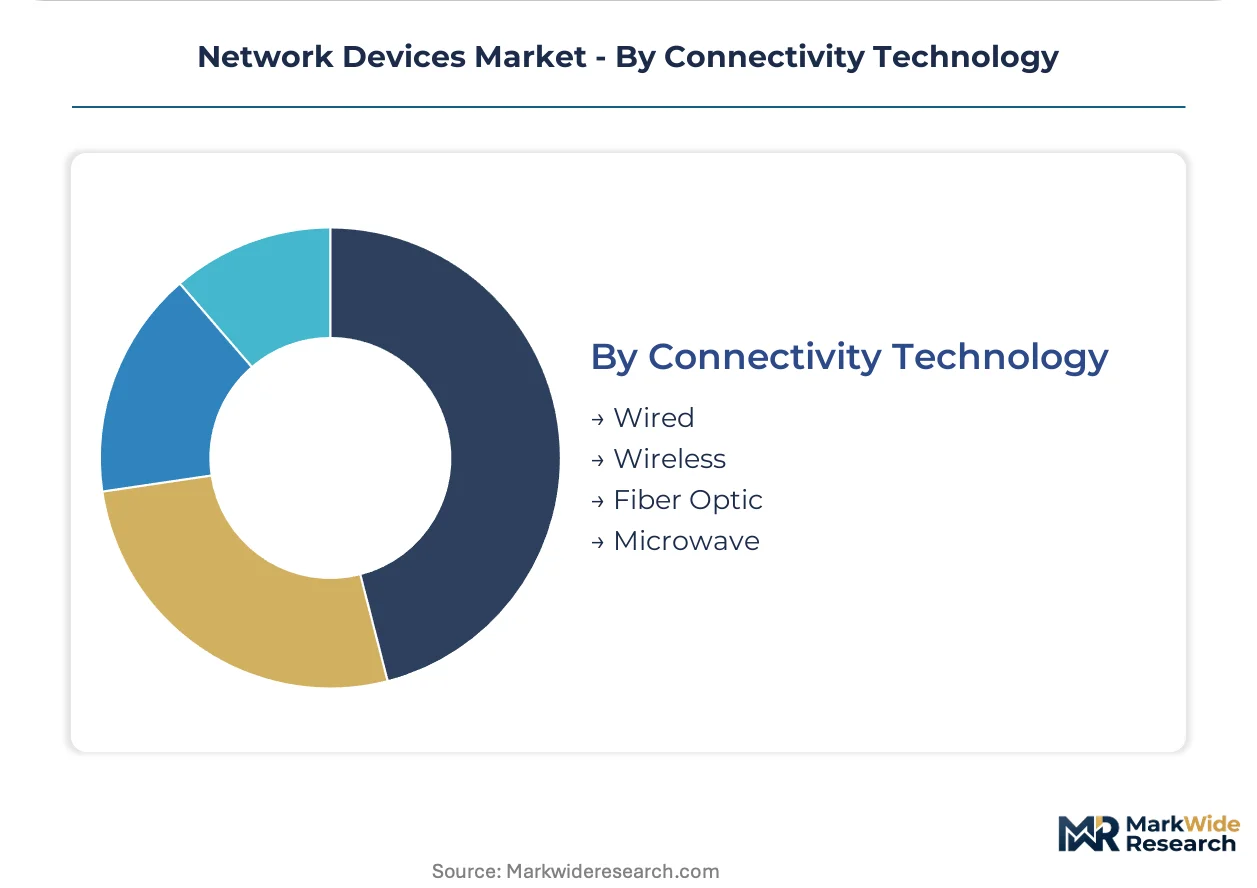
Connectivity Technology:
Supply concentration in Taiwan-based foundries for coherent DSPs and indium phosphide substrate constraints on single-mode transceivers fragment availability across wavelength and distance requirements.
- Wired:Copper Ethernet maintains installed base in campus environments where distance runs stay within 100-meter specifications. Category 8 cabling supports 25Gbps for emerging high-density access layer requirements.
- Wireless:Wi-Fi 6E and emerging 7 GHz spectrum expansion address density requirements in hybrid work environments. FCC Part 15 equipment authorization gates market entry for radio-frequency emitting hardware in the United States.
- Fiber Optic:Single-mode installations capture premium pricing for 100G+ wavelengths exceeding eighty kilometers without regeneration. Allocation constraints on coherent DSPs extend lead times for carrier backbone upgrades.
- Microwave:Point-to-point radio links serve terrain-blocked fiber routes and rapid disaster recovery deployment. Spectrum licensing requirements vary across national regulatory regimes.
Distance economics favor Fiber Optic; deployment velocity favors Wireless.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan-based foundries export merchant silicon to hyperscale operators in India and Germany, while Chinese equipment manufacturers supply carrier-grade platforms across Southeast Asian infrastructure buildouts.
United States
FCC Part 15 equipment authorization governs radio-frequency emitting hardware, with hyperscale data center operators in Northern Virginia and Dallas-Fort Worth deploying 400G spine-leaf architectures. Cloud service providers are collapsing three-year hardware refresh cycles in favor of subscription-based procurement models.
Germany
Mittelstand manufacturing firms prefer OpEx-based network subscriptions over capital-intensive ownership, with the EU NIS2 Directive mandating vulnerability disclosure for critical infrastructure operators. Frankfurt and Munich data center clusters anchor demand for EAL4+ certified switching platforms.
India
The Telecom Engineering Centre issues technical approvals gating market entry for imported routing platforms, while the BharatNet rural broadband initiative targets 600,000 village-level access points. Mumbai and Hyderabad hyperscale facilities drive 400G-capable merchant silicon procurement.
China
MIIT enforces GB standards for domestic network equipment certification, creating divergent testing requirements for multinational vendors. Beijing and Shanghai carrier networks are undergoing MPLS-to-segment-routing transitions that strain engineering resources.
Japan
METI standards shape procurement specifications for telecommunications infrastructure, with Tokyo and Osaka financial institutions demanding hardware bill-of-materials disclosure. Real-time operating systems expertise scarcity delays secure boot implementation timelines for domestic vendors.
Network Devices Market Competitive Environment
Listed leaders compete with private specialists across capital structure and customer segment coverage. The vendor base spans integrated chassis manufacturers, merchant silicon suppliers, and software-defined networking stacks. Three archetypes dominate: vertically integrated incumbents with captive semiconductor fabrication, disaggregated white-box assemblers leveraging third-party silicon, and cloud-native specialists targeting hyperscale data center density. Competitive moves concentrate on strategic partnerships for interoperability certification and backward integration into coherent DSP design.
Within the integrated incumbent tier, Cisco Systems and Huawei Technologies occupy positions defined by installed base scale and in-house semiconductor capabilities. Arista Networks exemplifies the cloud-native specialist archetype, with its focus on low-latency spine architectures for rack-level traffic. These three companies represent contrasting strategic postures: recurring software subscription revenue, captive supply chain control, and hyperscale deployment specialization respectively.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Hewlett Packard Enterprise |
| Juniper Networks |
| Arista Networks |
| Broadcom |
| Nokia |
| Samsung Electronics |
| ZTE |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Taiwan-based foundries lock in merchant silicon supply while anchoring price visibility for hyperscale buyers negotiating three-year switching platform deployments. These arrangements concentrate procurement leverage among cloud service providers in India and Germany, compressing margin flexibility for mid-range vendors locked into spot-market component sourcing.
Pricing Analysis
400G-capable switching platforms command substantial premiums over 100G prior-generation hardware, while 800G next-generation coherent optics remain priced at prototype tiers pending volume ramp. Three-tier pricing structure across EAL4+ certified premium, standard enterprise, and economy white-box levels separates compliance-driven defense procurement from cost-optimized hyperscale deployments. Pricing pressure stems from merchant silicon commoditization as Broadcom and Marvell disaggregate switching ASICs from vendor-integrated chassis. Government buyers in India and the EU exhibit lowest price sensitivity due to regulatory compliance mandates, while German Mittelstand SMBs drive hardest subscription economics negotiation.
Supply Chain Analysis
Strategic stockpiling of coherent DSPs and single-mode transceivers dominates inventory strategy as lead time volatility from indium phosphide substrate constraints forces buffer accumulation. Merchant silicon fabrication concentrates in Taiwan, South Korea, and the United States, while optical component assembly clusters in China and Malaysia. Supply chain risk hinges on single-source vulnerability for advanced node switching ASICs at TSMC. Distribution runs through direct hyperscale procurement teams, carrier systems integrators, and residual value-added reseller channels serving legacy campus retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems firmware engineering proficiency anchors competitive differentiation as secure boot implementation timelines stretch across vendor roadmaps. The scarcity of engineers proficient in real-time operating systems and hardware security module integration constrains product development velocity for new platform introductions.
For Market Incumbents: Compound recurring software subscription revenue by collapsing maintenance contracts into cloud-delivered network-as-a-service offerings, defending against white-box disaggregation. Deepen backward integration into coherent DSP design to offset indium phosphide substrate allocation constraints. Prioritize EAL4+ certification investment under the EU Cybersecurity Act to capture premium positioning in European defense and financial infrastructure tenders. For New Entrants and Emerging Players: Differentiate on integrated zero-trust network access by collapsing SD-WAN and SASE procurement into unified edge stacks, targeting white space vacated by separate security and connectivity vendors. Penetrate India's BharatNet rural broadband initiative with ruggedized, low-cost routing platforms featuring integrated power-over-Ethernet capabilities. Pursue carrier-managed service channel partnerships rather than direct enterprise sales to bypass incumbent reseller relationships. For Investors and Strategic Acquirers: Merchant silicon-based white-box assemblers with independent network operating system partnerships represent the most defensible acquisition archetype as disaggregation accelerates. Long-term viability favors vendors controlling software-defined networking stacks rather than chassis-dependent integrated incumbents. Watch hyperscale capex disclosure patterns as the inflection signal for 800G switching platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Silicon Partnership | Broadcom and Marvell ASIC supply agreements enable white-box switching cost structures competitive with integrated vendors. |
| Co-Packaged Optics Integration | Eliminating pluggable transceivers reduces thermal constraints for AI training cluster rack-scale deployments. |
| EAL4+ Certification Investment | EU Cybersecurity Act compliance creates premium positioning in European defense and financial infrastructure tenders. |
| Rural Broadband Platform Development | BharatNet's 600,000 village access point target demands ruggedized, low-cost routing with integrated power-over-Ethernet. |
| Network-as-a-Service Transition | Subscription revenue models displace three-year hardware refresh cycles among German Mittelstand manufacturing firms. |
Study Parameters
Operator-level perspectives from data center infrastructure directors, carrier network planning officers, enterprise IT procurement managers, and hyperscale platform engineers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FCC equipment authorization filings, EU NIS2 Directive implementation guidance, Telecom Engineering Centre technical approval records, and hyperscaler capex disclosure analysis. Bottom-up merchant silicon shipment tracking and top-down enterprise networking spend estimates were triangulated to anchor market sizing.
Sensitivity analysis across deployment model adoption curves, regulatory compliance timeline acceleration, and semiconductor foundry capacity allocation stress-tested forecast robustness. Segmentation dimensions modeled include device type, deployment model, end user organization scale, connectivity technology, and regional regulatory cluster. CAGRs were derived from iterative reconciliation of historical procurement pattern analysis with forward-looking infrastructure buildout pipelines. AI training cluster density requirements and MPLS-to-segment-routing transition velocity served as industry-specific forecast inputs.
Material uncertainties — export control volatility, indium phosphide substrate supply disruption, and divergent national cybersecurity certification scheme fragmentation — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding hyperscale data center buildout continuity and EU NIS2 Directive enforcement rigor. Revision becomes warranted when merchant silicon foundry utilization rates cross thresholds indicating sustained allocation constraint or abrupt demand destruction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Europe Structured Cabling Market
Network Technology
Managed MPLS Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Network Packet Broker Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Radio Modem Market
Network Technology
Global Self-Organizing Network Market
Network Technology
5G CPE Device Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
Wimax Solutions Market
Network Technology
Gigabit Ethernet Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Global Carrier Wi-Fi Equipment Market
Network Technology
Digital Repeater Market
Network Technology
Global Network Switches Market