
 Global Ethernet Switch and Routers Market | 2026-2036
Global Ethernet Switch and Routers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ethernet Switch and Routers Market Foresight
India is rewriting supply assumptions for Ethernet switching hardware as domestic electronics manufacturing zones scale capacity for export-bound production. Cisco Systems leverages deep channel partnerships across enterprise and service provider verticals to sustain installed-base renewal cycles. Huawei Technologies anchors its position through captive silicon development and integrated optical-electrical platforms. Arista Networks differentiates in cloud-grade data center fabrics where latency thresholds define procurement decisions.
Ethernet switches and routers are packet-forwarding devices built around ASIC-based switching fabrics that process Layer 2 through Layer 3 traffic at port densities reaching 800G per slot in flagship chassis. Their commercial purpose centers on deterministic traffic engineering across enterprise LANs, WAN backbones, and hyperscale data center interconnects. Managed switches command the largest revenue pool among product types as IT administrators prioritize telemetry, automation, and policy enforcement. SDN-enabled segments are expanding fastest as controller-based architectures displace CLI-centric provisioning in campus and cloud environments. Service provider applications retain concentrated margin pools due to carrier-grade reliability requirements and long replacement cycles.
FCC equipment authorization rules in the United States, CE marking under the EU Radio Equipment Directive, and China's GB standards administered by MIIT collectively shape product compliance roadmaps and time-to-market schedules. The EU AI Act and NIS2 Directive introduce new cybersecurity baseline requirements for critical network infrastructure procurement. Stakeholders must monitor how open-source routing software and merchant silicon commoditization reshape vendor lock-in economics across enterprise buying centers.
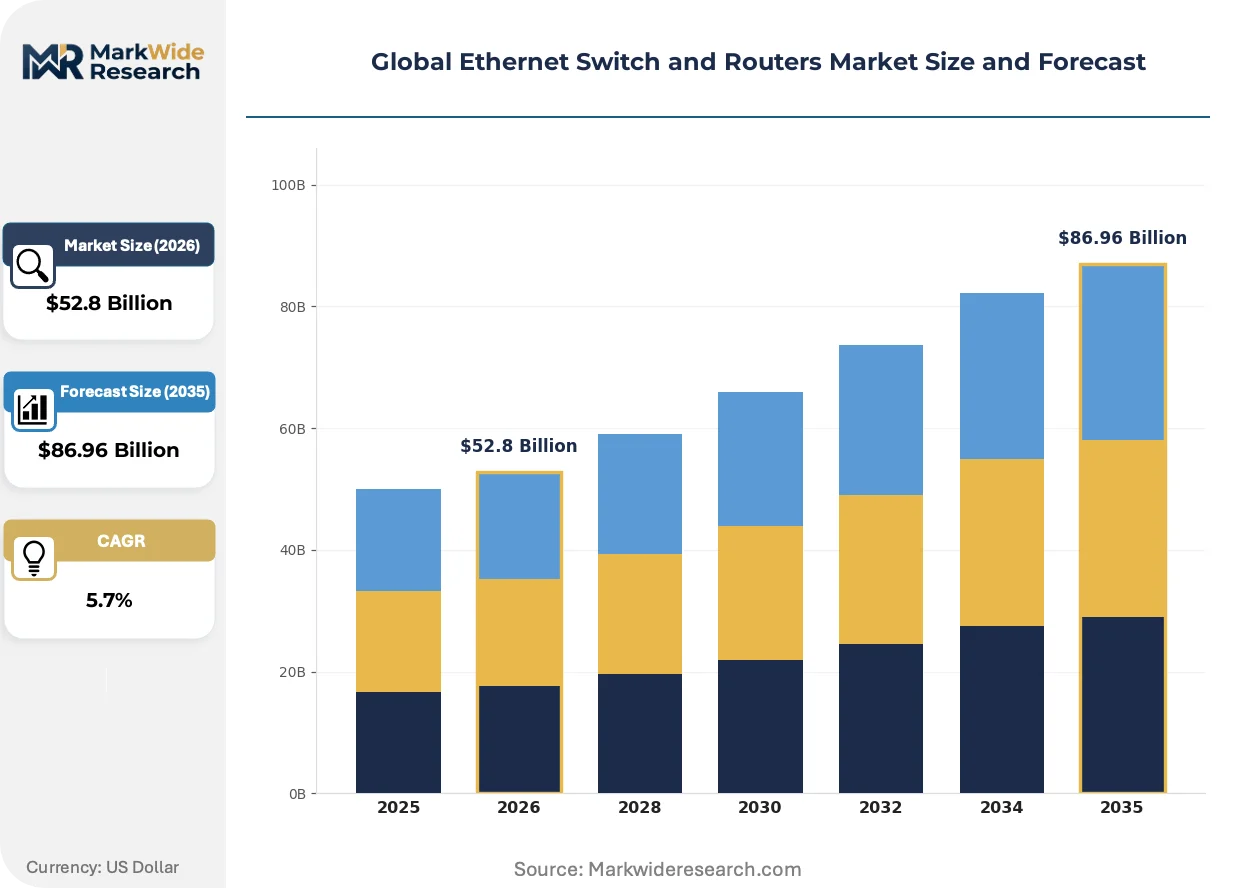
Market Dynamics
Merchant silicon commoditization is collapsing vendor lock-in economics across enterprise buying centers, forcing incumbent hardware suppliers to defend margin pools through software-defined differentiation and captive ASIC roadmaps.
Growth Catalysts
- EU AI Act and NIS2 Directive:The EU AI Act and NIS2 Directive impose mandatory cybersecurity baselines for critical network infrastructure, compelling financial institutions and energy utilities to accelerate refresh cycles.
- Hyperscale data center interconnects:Cloud service providers in the United States are expanding campus networks at scale, driving port density requirements toward 800G per slot in flagship chassis.
- India's digitalization wave:Banking and telecom sectors across India are modernizing core networks, creating concentrated demand for managed switches with telemetry and automation capabilities.
Market Restraints
- ASIC design cost escalation:Custom silicon development for switching fabrics requires nine-figure capital commitments, concentrating advanced capability among vertically integrated suppliers.
- Optical component supply concentration:Coherent DSP and laser suppliers cluster in Taiwan and Japan, exposing lead times to geopolitical friction and foundry allocation constraints.
- FCC equipment authorization timelines:The FCC's certification backlog for 60 GHz and 6 GHz Wi-Fi 6E implementations stretches time-to-market by three to six months for unlicensed spectrum products.
Strategic Opportunities
- Sub-Saharan Africa underpenetration:Fiber backhaul deployment across Nigeria and Kenya lags population growth, creating white space for cost-optimized Layer 3 switches in mobile operator networks.
- Convergence of silicon photonics and switching:Integrated optical-electrical platforms are compressing power-per-bit economics, enabling new entrants to bypass discrete transceiver supply chains.
- India PLI scheme incentives:Production-linked incentives for electronics manufacturing zones in Tamil Nadu and Karnataka are attracting contract assembly for export-bound switching hardware.
Industry Challenges
- Embedded systems security certification:Common Criteria EAL4+ evaluation timelines extend eighteen to twenty-four months, delaying government and defense procurement decisions.
- Legacy CLI-to-API migration friction:Enterprise IT operations teams face skill gaps in Python-based automation frameworks, slowing SDN controller adoption despite capex savings.
- Supply chain reconfiguration costs:Diversifying PCB and connector sourcing away from concentrated Asian suppliers requires qualification cycles that compress gross margins during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ethernet Switch and Routers Market |
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $86.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Managed Switches, Unmanaged Switches, Routers, Layer 3 Switches, Modular Switches Technology: Ethernet, MPLS, SDN, IP Routing, GRE Tunneling Application: Data Centers, Telecommunications, Cloud Computing, Enterprise Networks, Service Providers End User: Telecom Operators, Internet Service Providers, Educational Institutions, Financial Services Firms, Government Agencies |
| Companies Covered | Cisco Systems, Huawei Technologies, Juniper Networks, Arista Networks, Hewlett Packard Enterprise, Extreme Networks, Dell Technologies, H3C, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ethernet Switch and Routers Market Shifts & Advancements
Three simultaneous vectors are compressing hardware differentiation cycles while expanding software attach rates: merchant silicon maturation, security mandate proliferation, and procurement model fragmentation across buyer segments.
Co-packaged optics is collapsing the physical separation between switch ASICs and optical engines, integrating lasers and modulators directly onto the substrate. Hyperscale operators in the United States and China are piloting 51.2 Tbps switches with co-packaged optics to halve power consumption per gigabit. This integration is collapsing the standalone transceiver market for intra-data center links below two kilometers.
The EU AI Act introduces mandatory conformity assessments for AI systems embedded in network management platforms, requiring documentation of training data provenance and risk mitigation protocols. European telecommunications operators must now embed these assessments into vendor qualification workflows, extending procurement cycles by four to six months. Managed service providers serving EU critical infrastructure are responding by pre-certifying hardware-software bundles to accelerate deployment.
Consumption-based network-as-a-service contracts are displacing perpetual license purchases in mid-market enterprise segments, unbundling hardware ownership from operational management. Systems integrators and managed service providers are capturing this shift through multi-year subscriptions that include refresh guarantees. This pattern is most visible in Germany and the United Kingdom, where CFO preference for opex treatment aligns with IT staff consolidation trends.
Global Ethernet Switch and Routers Market Segmentation
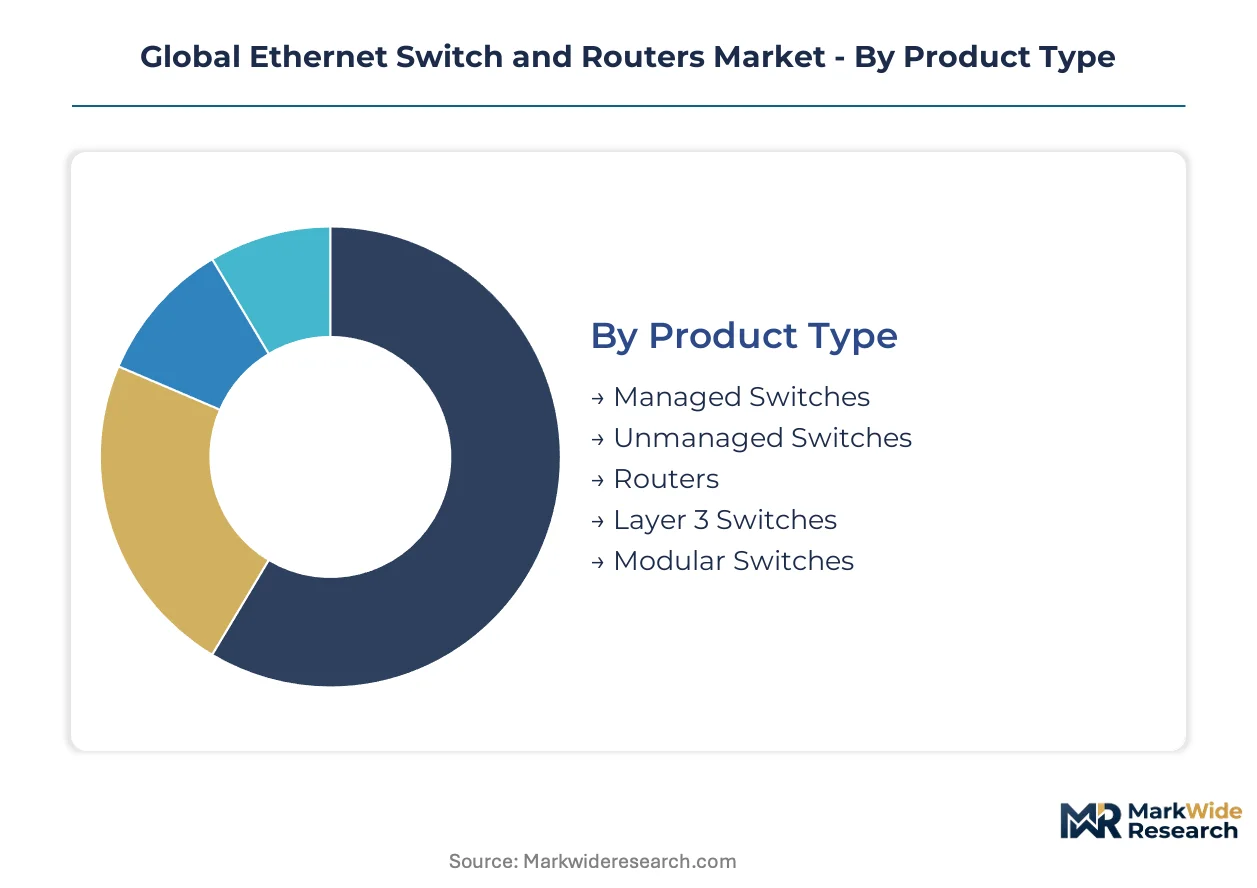
Ethernet switching hardware segments diverge sharply in procurement cadence, with cloud-facing equipment refreshing every 18-24 months while carrier infrastructure endures 7-10 year replacement cycles. Understanding these temporal patterns reveals where margin pools concentrate and which technology transitions offer entry points for new suppliers.
Product Type:
Replacement velocity varies from annual hyperscale refreshes to decade-long carrier deployments, creating distinct competitive arenas with opposing margin structures.
- Managed Switches:ASIC-based platforms with embedded telemetry, automation APIs, and policy enforcement engines. Demand concentrates in Indian banking and telecom sectors where RBI-mandated uptime requirements and TRAI quality-of-service rules drive procurement of fault-tolerant chassis with hot-swappable components.
- Routers:Packet-forwarding systems optimized for WAN aggregation and BGP path selection at multi-terabit scale. Cloud service providers across the United States are expanding campus interconnects, compressing procurement cycles for 800G-capable platforms with programmable forwarding pipelines.
- Unmanaged Switches:Fixed-configuration Layer 2 devices serving cost-sensitive SMB deployments in price-driven markets.
- Layer 3 Switches:Hybrid platforms combining switching fabric density with routing protocol support for collapsed core-distribution architectures.
- Modular Switches:Chassis-based systems with slot-expandable capacity serving long-horizon enterprise and government installations.
Managed switches anchor the volume base while routers gain share at the steepest rate.
Technology:
Control plane architectures separate legacy hardware-bound implementations from software-defined abstractions with diverging capex-to-opex profiles.
- SDN:Controller-based architectures displacing CLI-centric provisioning through centralized policy orchestration. European telecommunications operators subject to EU AI Act conformity assessments are extending procurement cycles by four to six months, favoring pre-certified hardware-software bundles from managed service providers.
- Ethernet:IEEE 802.3-based Layer 2 switching with deterministic MAC address learning and VLAN segmentation. Hyperscale data centers in the United States and China are piloting co-packaged optics integration to halve power consumption per gigabit, collapsing standalone transceiver demand for intra-facility links.
- MPLS:Label-switched path technology for traffic-engineered carrier backbones with guaranteed QoS.
- IP Routing:Destination-based forwarding using OSPF, IS-IS, and BGP for internet-scale reachability.
- GRE Tunneling:Encapsulation protocol for overlay network construction across heterogeneous transport.
Ethernet dominates installed capacity while SDN climbs the fastest as controller adoption accelerates.
Application:
Workload characteristics dictate port density requirements, with latency-sensitive traffic commanding premium pricing over bulk transport.
- Data Centers:High-radix switching fabrics optimized for east-west traffic patterns and microsecond latency budgets. Cloud computing expansion across United States hyperscale campuses is driving 800G per slot density requirements in flagship chassis.
- Telecommunications:Carrier-grade platforms with five-nines reliability and redundant control plane architectures. India's banking and telecom digitalization wave is concentrating demand for managed switches with telemetry and automation capabilities in Mumbai and Bangalore metro clusters.
- Cloud Computing:Software-defined infrastructure with API-driven provisioning and consumption-based billing models.
- Enterprise Networks:Campus and branch architectures balancing performance with operational simplicity.
- Service Providers:Multi-tenant edge platforms with hierarchical QoS and lawful intercept capabilities.
Telecommunications provides the revenue foundation while data center applications expand most quickly.
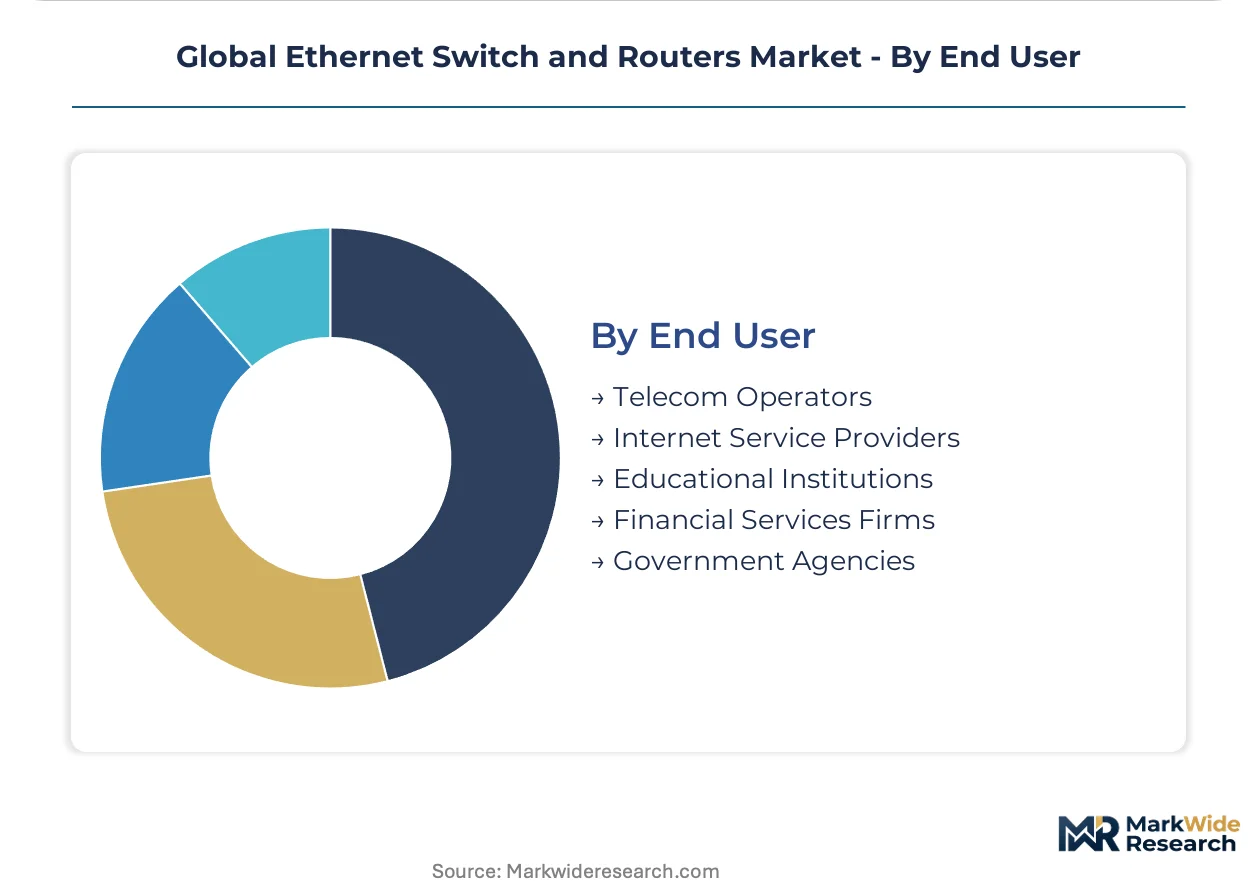
End User:
Procurement sophistication ranges from centralized carrier sourcing to fragmented institutional purchasing with diverging technical evaluation criteria.
- Telecom Operators:Tier-1 carriers with dedicated network engineering teams and multi-year capital planning cycles. FCC equipment authorization timelines for 60 GHz and 6 GHz implementations are stretching time-to-market by three to six months for unlicensed spectrum products targeting these buyers.
- Financial Services Firms:Institutions with regulatory-mandated resilience requirements and sub-millisecond latency thresholds for algorithmic trading. EU AI Act and NIS2 Directive cybersecurity baselines are compelling European banks and energy utilities to accelerate refresh cycles for critical network infrastructure.
- Internet Service Providers:Regional and national broadband operators with cost-optimized Layer 3 switching requirements.
- Government Agencies:Public sector entities with Common Criteria EAL4+ certification requirements extending procurement timelines.
- Educational Institutions:Universities and research networks with high-bandwidth research computing interconnect needs.
Telecom operators represent the largest committed volume while financial services firms show the steepest adoption trajectory for security-hardened platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC equipment authorization rules in the United States anchor the regulatory framework that shapes global product compliance roadmaps and time-to-market schedules for Ethernet switching hardware.
United States
Cloud service providers are expanding hyperscale campus networks, driving port density requirements toward 800G per slot in flagship chassis. FCC certification backlogs for 60 GHz and 6 GHz Wi-Fi 6E implementations stretch time-to-market by three to six months. Silicon Valley clusters and Dallas-Fort Worth metro areas concentrate pilot deployments of co-packaged optics integration.
China
Hyperscale operators are piloting 51.2 Tbps switches with integrated optical-electrical platforms to halve power consumption per gigabit. MIIT-administered GB standards govern product compliance and domestic market access requirements. Beijing and Shenzhen industrial zones anchor captive silicon development and switching fabric manufacturing.
Germany
Financial services firms and energy utilities are accelerating refresh cycles for critical network infrastructure under EU AI Act and NIS2 Directive cybersecurity baselines. CE marking under the EU Radio Equipment Directive shapes procurement qualification workflows. Frankfurt and Munich metro clusters concentrate managed service provider activity for pre-certified hardware-software bundles.
India
Banking and telecom sectors are modernizing core networks, creating concentrated demand for managed switches with telemetry and automation capabilities. RBI-mandated uptime requirements and TRAI quality-of-service rules drive procurement of fault-tolerant chassis. Production-linked incentives for electronics manufacturing zones in Tamil Nadu and Karnataka are attracting contract assembly for export-bound switching hardware.
Japan
Coherent DSP and laser suppliers cluster in domestic foundries, exposing lead times to foundry allocation constraints but maintaining optical component supply chain integrity. METI standards coordination influences regional procurement specifications. Tokyo and Osaka industrial corridors concentrate advanced optical-electrical platform integration for intra-data center interconnects.
Global Ethernet Switch and Routers Market Competitive Landscape
Vertically integrated platform suppliers and merchant silicon-dependent challengers split the market into opposing margin structures with divergent R&D intensity profiles. The vendor base concentrates among five to eight dominant suppliers with tiered positioning across enterprise, service provider, and hyperscale segments. Incumbents defend position through captive ASIC roadmaps and deep channel partnerships while challengers exploit software-defined differentiation and consumption-based procurement models. Strategic moves center on co-packaged optics integration partnerships and multi-year network-as-a-service subscription constructs.
Within the vertically integrated tier, Cisco Systems and Huawei Technologies exemplify archetypes combining captive silicon development with integrated optical-electrical platforms. Arista Networks occupies a position representing cloud-grade data center fabric specialization where latency thresholds define procurement decisions. These three anchors illustrate how vendor lock-in economics collapse under merchant silicon commoditization pressure, forcing divergent responses across software-defined differentiation and hardware integration vectors.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Juniper Networks |
| Arista Networks |
| Hewlett Packard Enterprise |
| Extreme Networks |
| Dell Technologies |
| H3C |
| NEC Corporation |
| Others |
Supply & Pricing Matrix
Trans-Pacific container freight corridors linking Shenzhen and Long Beach transmit cost volatility directly into landed equipment costs, amplifying price spreads between merchant silicon-dependent challengers and vertically integrated incumbents while compressing margins for contract manufacturers serving hyperscale buyers.
Pricing Analysis
Price spreads between Taiwan-sourced merchant silicon platforms and captive ASIC architectures exceed three-to-one at equivalent port densities. Pricing stratifies across chassis-based carrier systems, cloud-grade spine switches, and cost-optimized campus edge hardware. Cost compression in unmanaged SMB tiers is intensifying because white-label manufacturers from China's Pearl River Delta are flooding distribution channels. Hyperscale cloud operators exhibit the lowest price sensitivity due to total-cost-of-ownership procurement frameworks, while educational institutions and regional ISPs anchor the economy tier.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for Ethernet switching hardware, forcing qualification of alternative PCB and connector sourcing from Vietnam and Mexico. Switching fabric production concentrates in Taiwan, South Korea, and the People's Republic of China. Coherent DSPs, lasers, and advanced packaging substrates feed from Japanese and Taiwanese foundries. Single-source vulnerability in 800G optical engine supply is amplifying lead time uncertainty. Distribution runs through tier-one channel partners for enterprise accounts and direct fulfillment for hyperscale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Merchant silicon commoditization threatens incumbent margin structures by collapsing the proprietary ASIC differentiation that historically sustained vendor lock-in economics across enterprise procurement.
For Market Incumbents: Entrench software-defined differentiation through controller-based orchestration platforms that embed telemetry and automation APIs beyond hardware reach. Deepen captive silicon roadmaps for 51.2 Tbps co-packaged optics integration to defend hyperscale relationships against merchant silicon challengers. Channel control in Indian banking and telecom verticals remains a critical lever as RBI-mandated uptime requirements sustain premium positioning. For New Entrants and Emerging Players: Sub-Saharan Africa fiber backhaul deployment gaps in Nigeria and Kenya represent the most penetrable entry point for cost-optimized Layer 3 switches in mobile operator networks. India's PLI-backed electronics manufacturing zones in Tamil Nadu offer contract assembly partnerships for export-bound production without captive fab investment. Consumption-based network-as-a-service contracts in German and British mid-market segments provide a channel bypass around entrenched direct sales organizations. For Investors and Strategic Acquirers: Cloud-grade data center fabric specialists with proven 800G deployment credentials and established hyperscale relationships command scarcity premia in a consolidating vendor landscape. SDN controller software assets with pre-certified EU AI Act compliance bundles carry defensive value as European procurement cycles extend. The signal to watch is co-packaged optics pilot conversion rates at United States and Chinese hyperscale campuses.| Strategic Initiative | Industry Significance |
|---|---|
| Co-packaged Optics Integration | 51.2 Tbps switches with integrated optical-electrical platforms halve power consumption per gigabit at hyperscale facilities. |
| EU AI Act Pre-certification | Hardware-software bundles with embedded conformity assessments compress European telecommunications procurement cycles by four to six months. |
| India PLI Contract Assembly | Tamil Nadu and Karnataka manufacturing zones attract export-bound switching hardware production for global channel fulfillment. |
| SDN Controller Platform Development | Centralized policy orchestration displaces CLI-centric provisioning and sustains recurring revenue streams in campus environments. |
| Sub-Saharan Distribution Partnership | Cost-optimized Layer 3 switches address fiber backhaul gaps in Nigerian and Kenyan mobile operator networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC equipment supplier filings, hyperscaler capital expenditure disclosures, and FCC equipment authorization databases. Network engineering directors at cloud service providers, carrier procurement officers at tier-one telecom operators, and channel sales executives at systems integrators contributed structured interviews. Trade data from customs authorities, MIIT-administered GB standards documentation, and EU regulatory filings provided triangulation anchors. Bottom-up port shipment estimates and top-down infrastructure spending analysis were cross-validated.
Forecast inputs include switching fabric port densities, merchant silicon availability cycles, and regulatory compliance timeline shifts across the projection horizon. Segmentation dimensions span product architecture, control plane technology, workload application, and end-user procurement sophistication. CAGRs were derived from fitted growth curves against historical refresh cycle patterns and forward infrastructure investment intentions. Optical component supply constraints and co-packaged optics adoption curves were modeled as scenario-dependent variables.
Macroeconomic conditions sit as an overlay; deviation in hyperscaler capital allocation priorities or carrier infrastructure spending would shift the trajectory. Forecasts reflect documented assumptions about merchant silicon maturation rates and regulatory implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Radio Modem Market
Network Technology
Global Carrier Ethernet Equipment Market
Network Technology
Enterprise Routers Market
Network Technology
Passive Optical Network Market
Network Technology
Wi-Fi Network Equipment Market
Network Technology
Carrier Routing Equipment Market
Network Technology
Indoor Distributed Antenna Systems Market
Network Technology
Cloud Gateway Module Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
United States and European Fiber Optic Cable Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Global Carrier Wi-Fi Equipment Market
Network Technology
Global Active Network Management Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market