
 Europe Home Energy Management System Market | 2026-2036
Europe Home Energy Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Home Energy Management System Market Foresight
Energy efficiency certification tiers is collapsing the gap between premium and mass-market home energy management offerings. Schneider Electric leverages its building automation heritage to anchor whole-home integration portfolios. tado GmbH specializes in thermostat-centric energy optimization for European residential heating systems. Sonnen GmbH competes through its battery-software convergence for solar self-consumption households.
A home energy management system orchestrates distributed residential assets—HVAC, solar inverters, battery storage, and smart appliances—through centralized control platforms that typically operate on sub-15-minute data sampling intervals to optimize consumption against dynamic electricity pricing signals. Smart Thermostats currently dominate product-level revenue as the most accessible retrofit entry point, while Solar Management Systems represent the fastest-expanding category tied to rooftop PV deployment rates. IoT Solutions underpin most platform architectures, though Machine Learning integration is deepening as utilities roll out time-of-use tariffs requiring predictive load shifting.
The EU Green Deal, CE marking requirements under the Radio Equipment Directive, and national transpositions of the Energy Performance of Buildings Directive collectively mandate interoperable, cybersecurity-hardened platforms for new construction and major renovations. EMA and national regulators in Germany and France are tightening data governance standards for cloud-connected energy devices, reshaping vendor compliance roadmaps. Stakeholders must weigh whether to build proprietary ecosystems or pursue certified interoperability as utility partnerships become the decisive channel for scale.
Market Dynamics
The EU Green Deal and national building renovation mandates are compressing deployment timelines for interoperable home energy management platforms, forcing vendors to choose between proprietary ecosystems and certified utility partnerships as the primary scaling channel.
Growth Catalysts
- Energy Performance of Buildings Directive transpositions:National mandates across Germany, France, and the Nordic markets require interoperable, cybersecurity-hardened platforms for new construction and major renovations, creating regulatory pull-through.
- Smart grid infrastructure investment:Deep capital deployment in German, French, and Nordic distribution networks enables sub-15-minute data sampling intervals that optimize consumption against dynamic electricity pricing signals.
- Residential electricity tariff escalation:Climbing rates across the continent are accelerating homeowner adoption of retrofit entry points, particularly thermostat-centric optimization systems.
Market Restraints
- CE marking compliance under Radio Equipment Directive:Certification timelines and testing costs create friction for smaller platform vendors seeking European market access.
- Cloud data governance standard divergence:EMA and German and French national regulators are tightening divergent requirements for connected energy devices, fragmenting vendor compliance roadmaps.
- Legacy HVAC system incompatibility:Substantial installed base of non-communicating heating and cooling equipment limits addressable market for whole-home integration portfolios without costly hardware retrofits.
Strategic Opportunities
- Machine Learning predictive load shifting:Convergence of IoT platform architectures with utility time-of-use tariff rollouts creates white space for algorithmic consumption optimization in solar self-consumption households.
- Polish and Romanian building stock renovation:Underpenetrated Central and Eastern European markets present expansion targets as EU cohesion funds flow toward energy efficiency upgrades.
- Utility partnership channel development:Certified interoperability pathways with European distribution system operators offer scale advantages over direct-to-consumer hardware sales for battery-software convergence providers.
Industry Challenges
- Cybersecurity certification complexity:ETSI EN 303 645 and evolving national implementations demand specialized engineering talent scarce among mid-cap platform developers.
- Multi-protocol integration execution:Synchronous orchestration of HVAC, solar inverters, battery storage, and smart appliances across Modbus, Zigbee, and proprietary stacks strains technical implementation teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Home Energy Management System Market |
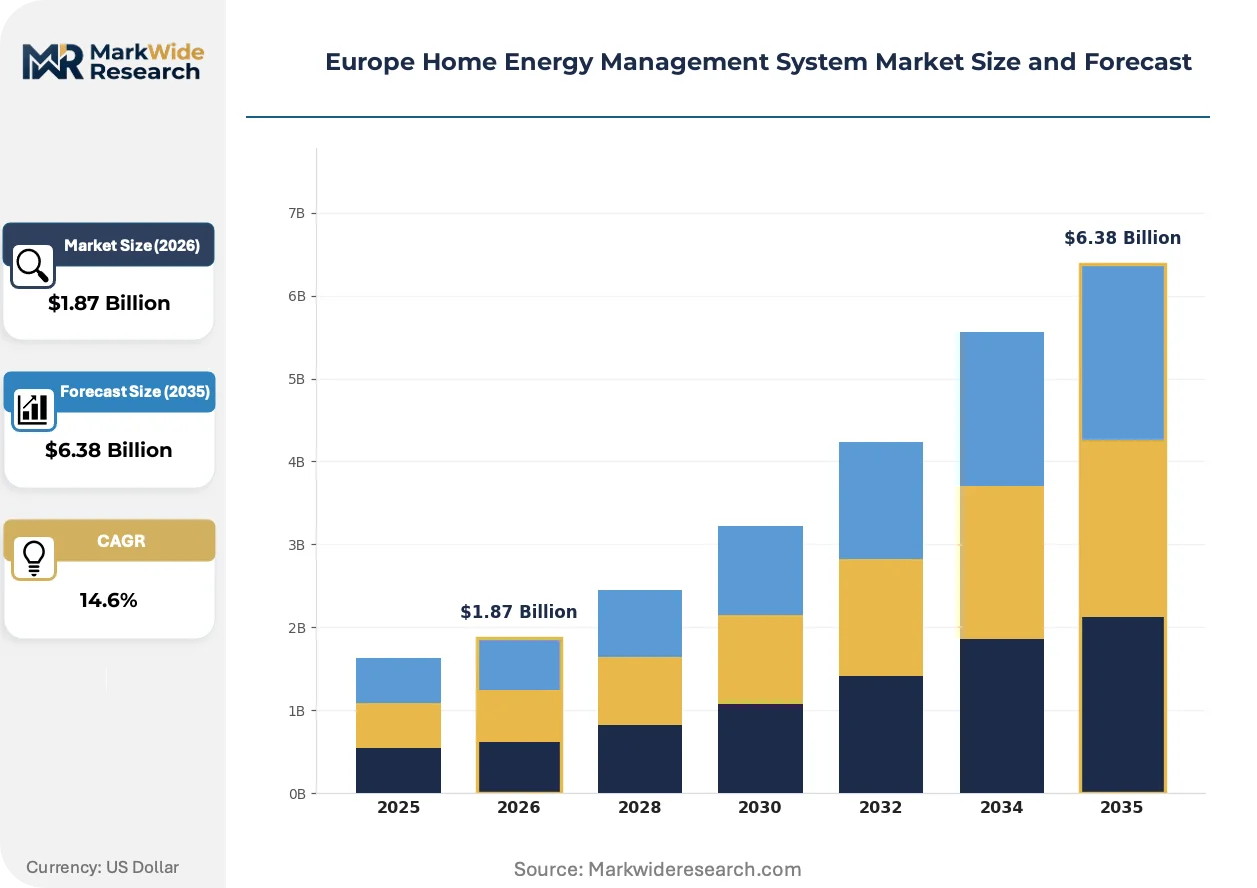
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $6.38 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Thermostats, Energy Monitors, Solar Management Systems, Home Automation Hubs End User: Residential, Multifamily Buildings, Single Family Homes, Smart Communities Technology: IoT Solutions, Cloud Computing, Machine Learning, Data Analytics Distribution Channel: Retail, Online Sales, Direct Sales, Distributors |
| Companies Covered | Eaton Corporation, tado GmbH, Schneider Electric, Sonnen GmbH, Netatmo, ABB Group, Johnson Controls, Legrand Group, Honeywell International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Home Energy Management System Market Shifts & Advancements
Machine Learning integration is deepening across European home energy management platforms as utilities accelerate time-of-use tariff deployment, compressing the competitive window for predictive optimization capabilities.
Edge computing architectures are fragmenting the traditional cloud-centric platform model. Residential battery storage systems with onboard processing now execute load-shifting decisions locally, reducing latency for price signal response. German and French solar self-consumption households are adopting these distributed intelligence configurations fastest, compressing margins for pure-software cloud platform vendors dependent on recurring subscription revenue.
The EU AI Act and national transpositions of the Cybersecurity Act are mandating conformity assessment procedures for algorithmic energy optimization systems. Industrial consequence includes mandatory risk management systems and transparency requirements for automated decision-making in residential load control. Battery-software convergence providers face the steepest compliance burden as their systems directly influence grid-interactive power flows.
Homeowner procurement of energy management capabilities is fragmenting across bundled and unbundled acquisition models. Traditional hardware-plus-subscription packages face displacement from utility-embedded platform offerings where equipment costs are socialized across rate bases. This channel rotation is most visible in Denmark and the Netherlands, where distribution system operators have secured regulatory approval for cost recovery of customer-sited flexibility assets.
Europe Home Energy Management System Market Segmentation
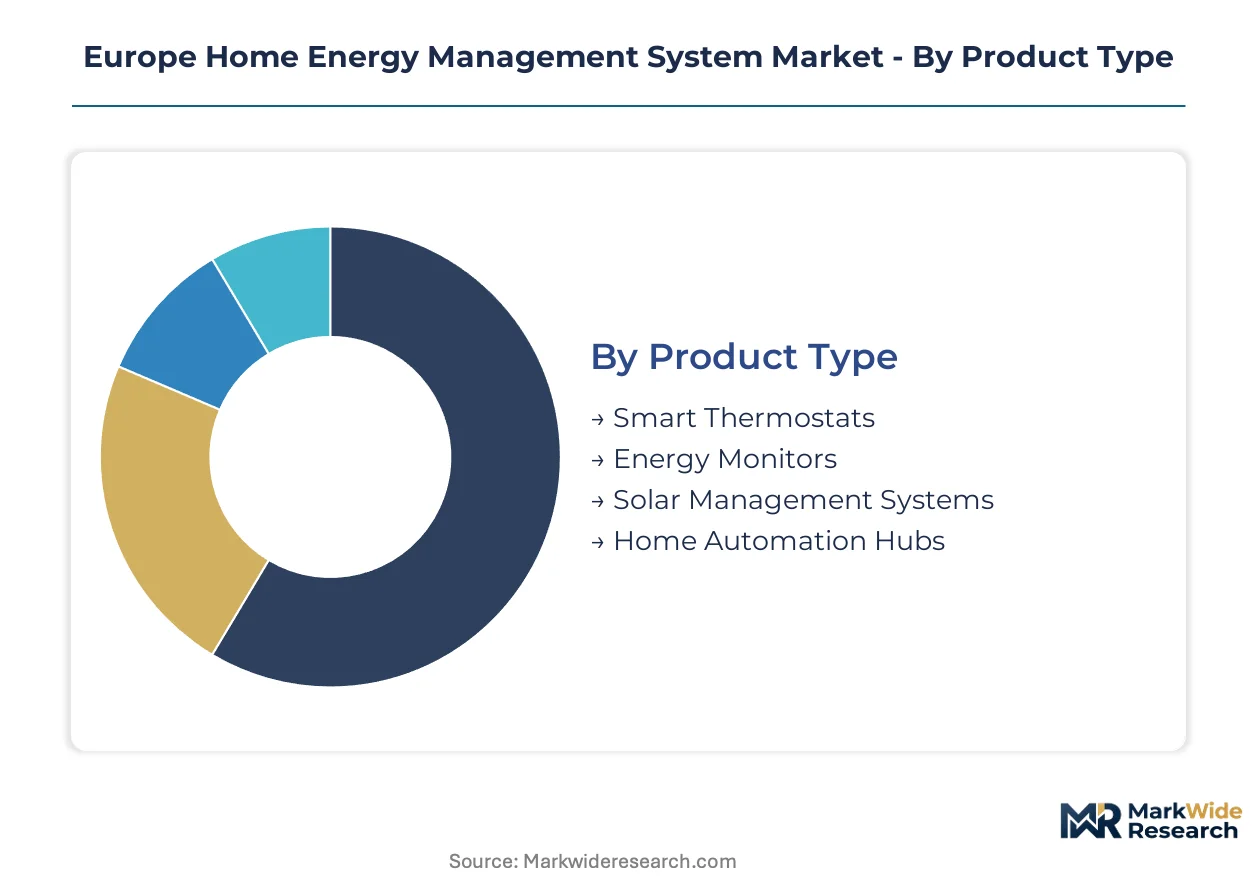
Segmentation in the Europe Home Energy Management System Market reveals how substitution pressure from adjacent building automation technologies reshapes competitive boundaries across product tiers. Vendors must align portfolio depth with the specific integration requirements of each end-use configuration.
Product Type:
Substitution pressure runs highest for standalone hardware categories facing convergence with whole-home platforms, while integrated systems build defensive moats through ecosystem lock-in.
- Smart Thermostats:Retrofit-friendly devices with sub-15-minute data sampling capabilities that optimize residential heating against dynamic electricity pricing. Demand concentrates in Germany and France where legacy gas boiler installations dominate renovation activity and homeowners seek accessible entry points without full system replacement.
- Solar Management Systems:Platforms synchronizing rooftop PV inverters with battery storage and grid export controls to maximize self-consumption economics. German and Nordic solar households drive adoption fastest as net metering regimes tighten and time-of-use spreads widen, compressing payback periods for software-enabled load shifting.
- Energy Monitors:Circuit-level consumption tracking hardware feeding real-time feedback to homeowner dashboards.
- Home Automation Hubs:Centralized controllers orchestrating multi-protocol device networks across HVAC, lighting, and security endpoints.
Smart Thermostats retain volume leadership; Solar Management Systems hold the steepest expansion curve.
End User:
Cost tier differentiation separates premium integrated deployments from mass-market retrofit solutions, with procurement authority fragmenting across owner-occupied and rental housing stock.
- Residential:Individual homeowner deployments spanning single-unit dwellings with varying levels of technical sophistication and renovation appetite. French and German owner-occupiers concentrate demand for thermostat-centric solutions as electricity tariff escalation accelerates payback-conscious purchasing decisions.
- Smart Communities:Master-planned developments with centralized energy management infrastructure serving aggregated household fleets. Danish and Dutch distribution system operator partnerships drive fastest adoption as regulatory frameworks permit cost recovery of customer-sited flexibility assets across rate bases.
- Multifamily Buildings:Shared infrastructure serving tenant populations with split incentive challenges between landlords and occupants.
- Single Family Homes:Detached dwellings with unconstrained rooftop solar potential and full homeowner control over renovation scope.
Residential captures the broadest installed base; Smart Communities demonstrate the most rapid contract velocity.
Technology:
Application maturity varies sharply across the technology stack, with foundational connectivity layers commoditizing while algorithmic optimization layers build differentiation.
- IoT Solutions:Device networking architectures employing Zigbee, Modbus, and proprietary protocols to connect distributed residential assets. German and French cybersecurity certification requirements under ETSI EN 303 645 concentrate vendor engineering investment as national implementations diverge.
- Machine Learning:Predictive algorithms forecasting consumption patterns and price signals to automate load-shifting decisions. Utility time-of-use tariff rollouts in Germany and the Nordics create immediate deployment pull for algorithmic optimization capabilities.
- Cloud Computing:Centralized data processing and platform management infrastructure.
- Data Analytics:Historical consumption pattern analysis and efficiency benchmarking tools.
IoT Solutions underpins current platform economics; Machine Learning commands the steepest R&D allocation trajectory.
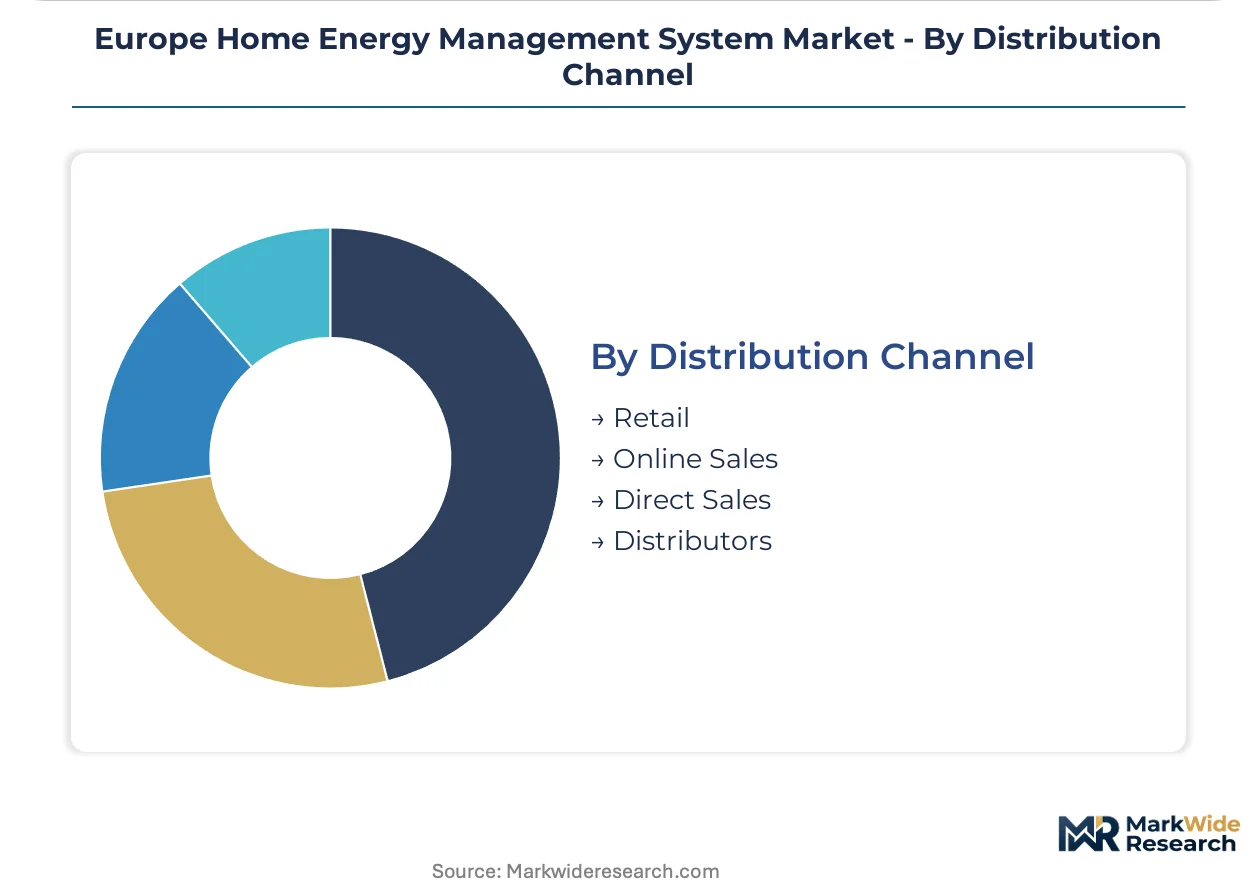
Distribution Channel:
Channel concentration reflects the shift from direct hardware sales toward utility-embedded service models, with margin structures compressing accordingly.
- Retail:Big-box and specialty electronics stores serving homeowner self-selection with standardized thermostat and monitor SKUs. French and German retail networks retain significance for entry-level retrofit purchases despite utility channel encroachment.
- Direct Sales:Manufacturer-owned channels capturing full margin on integrated whole-home systems. Nordic markets sustain direct sales viability for battery-software convergence providers targeting solar self-consumption households with complex configuration requirements.
- Online Sales:E-commerce platforms with price transparency and installation service bundling.
- Distributors:Wholesale intermediaries serving electrical contractor and system integrator trade channels.
Retail maintains transaction volume leadership; Direct Sales secures the highest average contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's home energy management system trade flows reflect a net import position for platform software and a net export orientation for hardware components, with German and French manufacturers capturing cross-border demand across Central and Eastern European renovation markets.
Germany
Residential electricity tariffs have climbed faster than EU averages, accelerating thermostat-centric retrofits in owner-occupied single-family housing. The national transposition of the Energy Performance of Buildings Directive mandates interoperable platforms for renovations exceeding 75 square meters. The Rhine-Ruhr metropolitan corridor concentrates battery-software convergence providers serving solar self-consumption households with time-of-use optimization capabilities.
France
Legacy gas boiler installations dominate the renovation pipeline, creating accessible entry points for smart thermostat deployment without full system replacement. ANSM and CNIL have tightened cloud data governance standards for connected energy devices beyond baseline GDPR requirements. The Île-de-France region anchors utility partnership channels where distribution system operators embed platform costs across rate bases.
Netherlands
Smart community developments with centralized energy infrastructure demonstrate the fastest contract velocity as regulatory frameworks permit cost recovery of customer-sited flexibility assets. The national building renovation mandate under the EU Green Deal compresses deployment timelines for interoperable platforms in multifamily stock. The Randstad urban agglomeration hosts distribution system operator innovation labs testing machine learning predictive load shifting at fleet scale.
Denmark
Distribution system operators have secured regulatory approval for rate-base financing of residential flexibility assets, displacing direct-to-consumer hardware procurement models. The country's district heating legacy creates hybrid integration opportunities for home energy management platforms coordinating both electric and thermal loads. The Copenhagen metropolitan area concentrates master-planned smart community developments with aggregated household fleet management.
Poland
EU cohesion fund flows toward building stock renovation are activating underpenetrated demand for entry-level energy monitoring and thermostat solutions. CE marking compliance timelines under the Radio Equipment Directive create friction for smaller platform vendors relative to established Western European suppliers. The Warsaw-Łódź corridor is emerging as a deployment target for German and French hardware manufacturers seeking volume expansion beyond saturated core markets.
Europe Home Energy Management System Market Competitive Landscape
Listed leaders compete with private specialists across capital access and speed of utility partnership formation. The market structure shows moderate concentration with tiered differentiation between whole-home integration portfolios and standalone device manufacturers. Three archetypes dominate: diversified industrial conglomerates with building automation heritage, pure-play thermostat and battery-software specialists, and utility-embedded platform providers. Competitive moves center on certified interoperability pathways with distribution system operators and edge computing capability acquisition.
Within the private specialist tier, tado GmbH and Sonnen GmbH exemplify focused business models built around European residential heating and solar self-consumption respectively. Schneider Electric occupies a position representing diversified industrial scale with whole-home integration capabilities spanning HVAC, storage, and grid-interactive controls. Among listed entities, Eaton Corporation and ABB Group sit within the industrial automation conglomerate archetype competing through building management system convergence into residential applications.
| Leading Market Players |
|---|
| Eaton Corporation |
| tado GmbH |
| Schneider Electric |
| Sonnen GmbH |
| Netatmo |
| ABB Group |
| Johnson Controls |
| Legrand Group |
| Honeywell International |
| Others |
Supply & Pricing Matrix
CE marking requirements under the Radio Equipment Directive gate both vendor qualification timelines and price differentiation across European home energy management platforms, compressing margins for uncertified entrants while rewarding incumbents with compliance infrastructure already deployed.
Pricing Analysis
Residential homeowners anchor pricing stratification across premium, standard, and economy tiers differentiated by cybersecurity certification grade and after-sales service bundling. Cost compression in the economy tier intensifies as utility-embedded platform offerings socialise equipment costs across rate bases in Denmark and the Netherlands. Smart community procurement demonstrates the lowest price sensitivity due to regulatory cost recovery mechanisms, while retail-direct thermostat sales face the highest sensitivity.
Supply Chain Analysis
Semiconductor fabrication chokepoints in Taiwan, South Korea, and Germany underpin component availability for Zigbee and Modbus communication modules. Platform assembly draws from Chinese PCB manufacturing, German enclosure production, and Nordic sensor suppliers. Single-source vulnerability concentrates in application-specific integrated circuits for grid-interactive controls. Distribution runs through electrical contractor networks and utility partnership channels rather than pure retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates switching costs that lock in utility partnerships and certified interoperability pathways.
For Market Incumbents: Secure distribution system operator certification pathways in Germany and France before tightening ETSI EN 303 645 implementations fragment compliance roadmaps further. Deepen backward integration into edge computing silicon to defend against battery-software convergence providers displacing pure-cloud platform margins. Reinforce machine learning talent density as algorithmic optimization becomes the primary differentiation layer. For New Entrants and Emerging Players: Lead with Polish and Romanian building stock renovation markets where EU cohesion fund flows activate underpenetrated demand for entry-level thermostat and energy monitor solutions. Target utility partnership channels in the Netherlands and Denmark where regulatory frameworks permit cost recovery of customer-sited flexibility assets. Anchor go-to-market strategy around certified interoperability rather than proprietary ecosystem builds. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed thermostat specialists facing convergence pressure from whole-home integration portfolios. Five-to-ten year viability hinges on machine learning capability depth and edge computing architecture ownership. Watch utility time-of-use tariff deployment velocity as the inflection signal for algorithmic optimization demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Utility Partnership Formation | Certified interoperability with German and French distribution system operators unlocks rate-base financing and fleet-scale deployment. |
| Edge Computing Architecture Acquisition | Onboard processing capabilities in battery storage systems reduce latency for price signal response and displace cloud-centric competitors. |
| Machine Learning R&D Expansion | Predictive load shifting algorithms capture value from time-of-use tariff spreads widening across German and Nordic markets. |
| Cybersecurity Certification Investment | ETSI EN 303 645 compliance creates regulatory moats as national implementations diverge and testing timelines extend. |
| Central and Eastern European Market Entry | Polish and Romanian renovation activity activated by EU cohesion funds offers volume expansion beyond saturated Western European core markets. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, smart thermostat product managers, distribution system operator innovation leads, and residential solar installation contractors, then refined against secondary validation from EIA electricity pricing data, IEA building efficiency reports, national transpositions of the Energy Performance of Buildings Directive, and CE marking registration databases. Bottom-up sizing of installed base and top-down cross-check against utility capex disclosures ensured triangulation integrity.
Variance decomposition across product type, end user configuration, technology layer, and distribution channel structured the analytical framework over the projection horizon. CAGRs were derived from segment-level adoption curves calibrated against regulatory mandate timelines and tariff escalation patterns. Forecast inputs incorporated smart grid infrastructure investment trajectories in Germany, France, and the Nordics alongside rooftop PV deployment rates driving solar management system demand.
Underlying assumptions cover regulatory enforcement consistency, semiconductor supply normalisation, and utility tariff reform implementation, with deviation risk concentrated in cybersecurity standard divergence and legacy HVAC retrofit compatibility constraints. Practitioners should keep alternative scenarios live as EMA and national data governance frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
District Cooling Market
Energy Management Systems
Asia-Pacific Home Energy Management System Market
Energy Management Systems
India Home Ventilation System Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Energy Management Systems (EMS) Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
Africa Digital Showers Market
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
Smart Thermostat Market
Energy Management Systems
Grid Operations Management Software Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
Peltier Chillers Market