
 CPE Router Market | 2026-2036
CPE Router Market Size, Share, and Industry Trends Forecast 2026-2036
CPE Router Market Insights
Leasing-based procurement for ISP infrastructure is tilting capital allocation toward vendors with flexible financing structures. Nokia Corporation leverages its asset-light managed-services portfolio to secure multi-year operator contracts. Huawei Technologies anchors production scale in Shenzhen to compete on cost for emerging-market deployments. TP-Link Technologies differentiates through channel control in the residential segment across Southeast Asia.
A CPE router is a customer-premises device that terminates broadband access connections and distributes local network traffic through integrated Wi-Fi radios, Gigabit Ethernet switch fabrics, and embedded LTE or 5G modems. These devices perform NAT, firewall, and QoS functions to enable residential and enterprise connectivity over fiber, DSL, or cable backhauls. Wireless routers lead volume shipments as ISPs bundle Wi-Fi 6 and Wi-Fi 7 units with service subscriptions. Rack-mounted installations in data center edge locations represent the fastest-growing configuration as enterprises disaggregate routing from core infrastructure.
The FCC enforces broadband labeling rules that mandate CPE equipment disclosures for speed and latency performance. ETSI harmonizes radio equipment directives across Europe, while China's MIIT certifies domestic 5G CPE models before market entry. Stakeholders must monitor spectrum reallocation decisions and energy-efficiency mandates that will determine next-generation hardware qualification requirements.
Market Dynamics
Wi-Fi 7 certification mandates from the FCC and ETSI are compressing hardware refresh cycles and forcing complete radio redesigns across the installed base of CPE equipment.
Growth Catalysts
- Fiber-to-the-Home Mandates:Government broadband expansion programs in Germany and India are accelerating ISP equipment procurement timelines and shortening replacement intervals for legacy DSL hardware.
- 5G Fixed Wireless Access:Mobile operators are deploying 5G CPE units as primary broadband alternatives in areas lacking fiber trenching economics, opening new subscriber acquisition channels.
- REACH and RoHS Directives:European material compliance requirements are standardizing component sourcing and eliminating hazardous substances from PCB manufacturing processes.
Market Restraints
- Semiconductor Concentration Risk:Advanced Wi-Fi 7 baseband silicon production concentrates among three foundry operators in Taiwan, creating supply vulnerability during geopolitical tensions.
- Radio Spectrum Licensing Costs:6 GHz band access fees in multiple jurisdictions inflate BOM costs for tri-band router platforms and compress margin structures.
- Copper Network Sunset Complexity:Incumbent operators in legacy DSL markets face stranded asset write-downs that delay full-fiber migration and equipment replacement decisions.
Strategic Opportunities
- Rural Broadband Subsidies:USDA ReConnect and similar programs in Canada and Australia fund CPE deployment for underserved populations, creating price-insensitive demand pockets.
- Enterprise Edge Disaggregation:Rack-mounted CPE installations in distributed office locations are replacing branch routers, converging security and switching functions at the network edge.
- Energy Efficiency Labeling:EU Ecodesign requirements for standby power consumption are differentiating efficient designs and creating premium positioning for compliant hardware.
Industry Challenges
- RF Engineering Talent Scarcity:Wi-Fi 7 beamforming and 6 GHz coexistence algorithms require specialized expertise that remains concentrated among veteran design teams.
- Multi-Standard Certification Overlap:Simultaneous FCC, ETSI, and MIIT approval processes extend time-to-market by eight to fourteen months for global product launches.
- Legacy IPv4 Address Exhaustion:CGNAT implementation complexity increases firmware development overhead and complicates peer-to-peer application support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CPE Router Market |
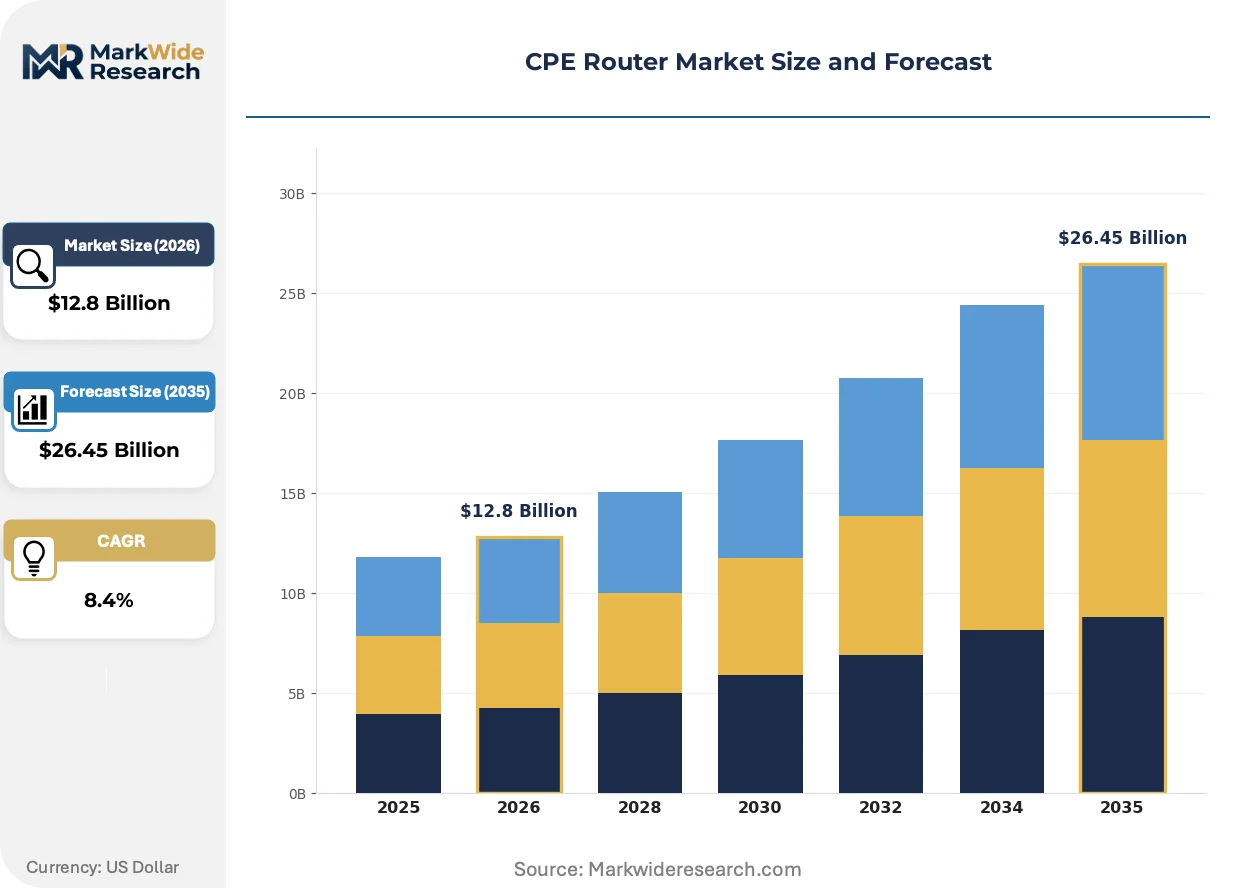
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Routers, Wireless Routers, 4G Routers, 5G Routers End User: Residential, Small Business, Large Enterprise, ISP Technology: Gigabit Ethernet, Fiber Optic, DSL, LTE Installation Type: Standalone, Wall-mounted, Rack-mounted, Embedded |
| Companies Covered | Netgear Inc., Nokia Corporation, Huawei Technologies, ARRIS International, Fiberhome, ZTE Corporation, Cisco Systems, Inc., Sagemcom, TP-Link Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CPE Router Market Trends and Innovations
Multi-gigabit broadband penetration is collapsing the distinction between residential and enterprise CPE feature requirements, while software-defined management overlays are displacing proprietary hardware stacks.
Wi-Fi 7's 320 MHz channel bonding and 4K-QAM modulation are rendering obsolete prior-generation mesh systems that relied on 5 GHz backhaul links with limited spectral efficiency. ISPs in South Korea and the United States are bundling Wi-Fi 7 gateways with gigabit service tiers to reduce churn and support premium pricing. The technology is rendering obsolete standalone range extenders by embedding coordinated multi-user MIMO directly into operator-provided hardware.
The FCC's broadband nutrition labels now mandate latency and speed disclosures for all CPE equipment sold with internet service plans, forcing hardware vendors to publish standardized performance metrics. ETSI harmonization of radio equipment directives across member states is consolidating previously fragmented national approval processes into single-market access. Equipment manufacturers serving Europe are redesigning thermal management systems to meet combined RF exposure and energy efficiency thresholds.
Leasing-based procurement models are replacing direct equipment purchases among tier-one operators, transferring ownership risk to vendors with financing capabilities. Managed service contracts now bundle hardware refresh cycles with remote monitoring and firmware update obligations, compressing traditional sales cycles. This shift is most visible in the United States and Germany where capital-light balance sheet preferences align with multi-year service agreements.
CPE Router Market Segmentation
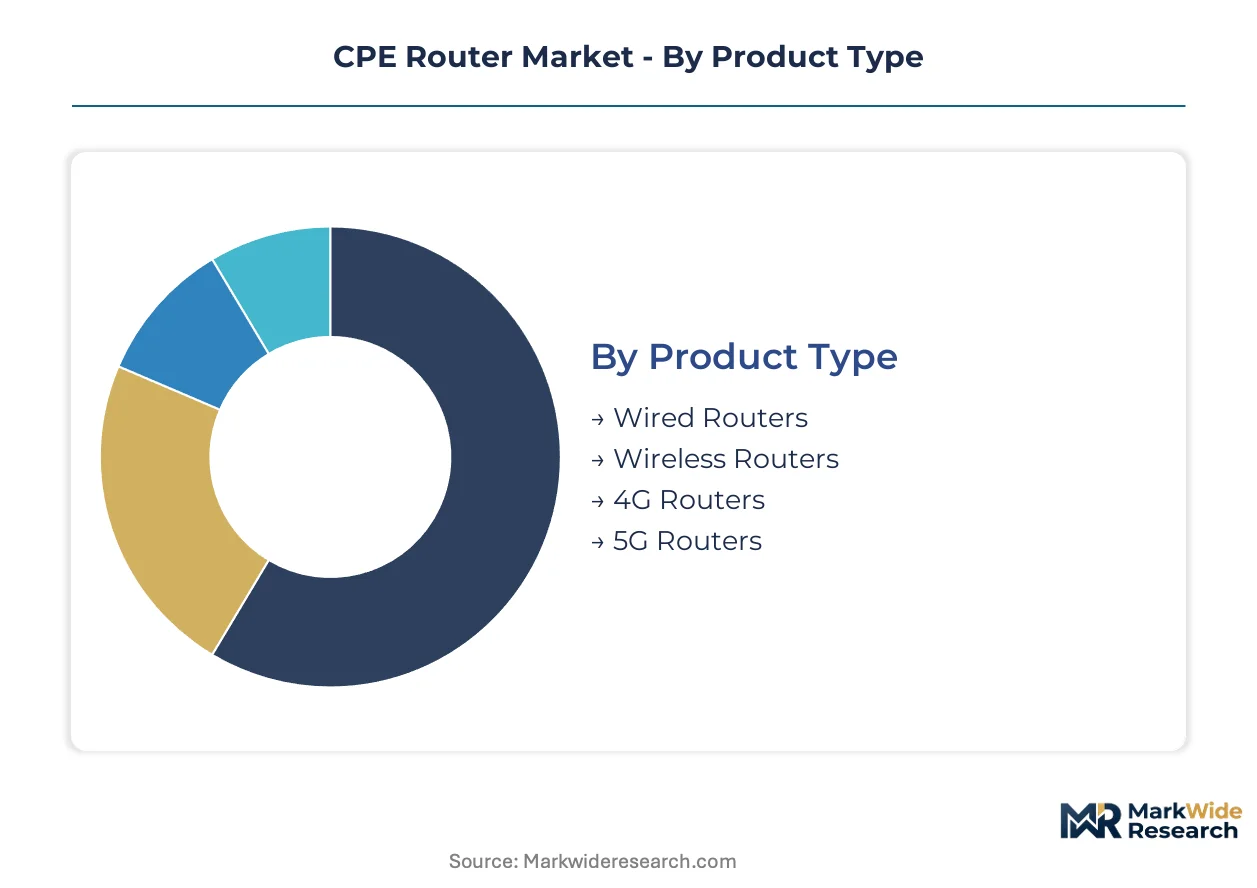
CPE router segmentation reveals divergent service intensity requirements across product architectures. Wireless and 5G variants demand continuous firmware management and spectrum optimization support that wired alternatives rarely require. Installation complexity and end-user technical sophistication further stratify aftermarket service obligations.
Product Type:
After-sales service intensity varies dramatically across router architectures, with cellular and wireless platforms requiring sustained RF optimization support that wired products seldom demand.
- Wireless Routers:These units integrate dual-band or tri-band Wi-Fi radios with beamforming capabilities and mesh coordination protocols. ISPs in the United States and Germany bundle these with gigabit fiber subscriptions to reduce subscriber churn through whole-home coverage guarantees. Firmware updates for Wi-Fi 6E and Wi-Fi 7 compatibility extend active vendor support timelines significantly.
- 5G Routers:Fixed wireless access CPE units embed 5G NR modems with carrier aggregation and network slicing capabilities. Mobile operators in India deploy these where fiber trenching economics fail, requiring ongoing modem configuration tuning as spectrum allocations evolve. Remote diagnostic capabilities become critical for subscriber retention in rural deployment scenarios.
- Wired Routers:Ethernet-only devices serving enterprise edge locations with deterministic latency requirements.
- 4G Routers:LTE-based CPE units bridging connectivity gaps in transitional broadband markets.
By volume, Wireless Routers lead. By growth pace, 5G Routers are climbing the fastest.
End User:
Customer type determines procurement channel structure and support escalation pathways, with ISPs and large enterprises demanding dedicated technical account management that residential segments rarely justify.
- ISP:Service providers procure CPE at scale for subscriber equipment programs, requiring vendor-managed inventory and logistics integration. Operators in China negotiate multi-year supply agreements with embedded refresh cycles and remote monitoring obligations. Leasing-based financing structures transfer ownership risk while locking in recurring service revenue streams.
- Large Enterprise:Distributed organizations deploy rack-mounted CPE at branch locations to disaggregate routing from core infrastructure. Financial services firms in Germany specify SD-WAN integration and zero-touch provisioning capabilities. Security policy enforcement at the network edge drives premium positioning for hardware with embedded firewall and segmentation functions.
- Residential:Individual consumers acquiring routers through retail channels or ISP subsidy programs.
- Small Business:Commercial establishments with limited IT staff requiring simplified management interfaces.
ISPs capture the highest shipment volumes. Large Enterprise segments show the steepest expansion trajectory as edge disaggregation accelerates.
Technology:
Physical layer architecture dictates component sourcing geography and certification burden, with fiber and cellular platforms facing distinct regulatory approval pathways across jurisdictions.
- Fiber Optic:GPON and XGS-PON termination equipment handles symmetrical multi-gigabit speeds for fiber-to-the-home deployments. German operators refresh these units to meet government-mandated broadband coverage targets. Optical transceiver compatibility with varied OLT vendor implementations complicates multi-source procurement strategies.
- Gigabit Ethernet:Copper-based gigabit ports serve enterprise edge and high-end residential applications with deterministic performance. Chinese manufacturers achieve cost optimization through switch fabric integration at the chipset level. Power-over-Ethernet variants support connected camera and access point deployments without separate electrical infrastructure.
- DSL:Legacy copper-line termination equipment facing sunset pressure in developed markets.
- LTE:4G cellular backhaul for portable and backup connectivity scenarios.
Gigabit Ethernet dominates current volume. Fiber Optic platforms are gaining share fastest as FTTH penetration deepens.
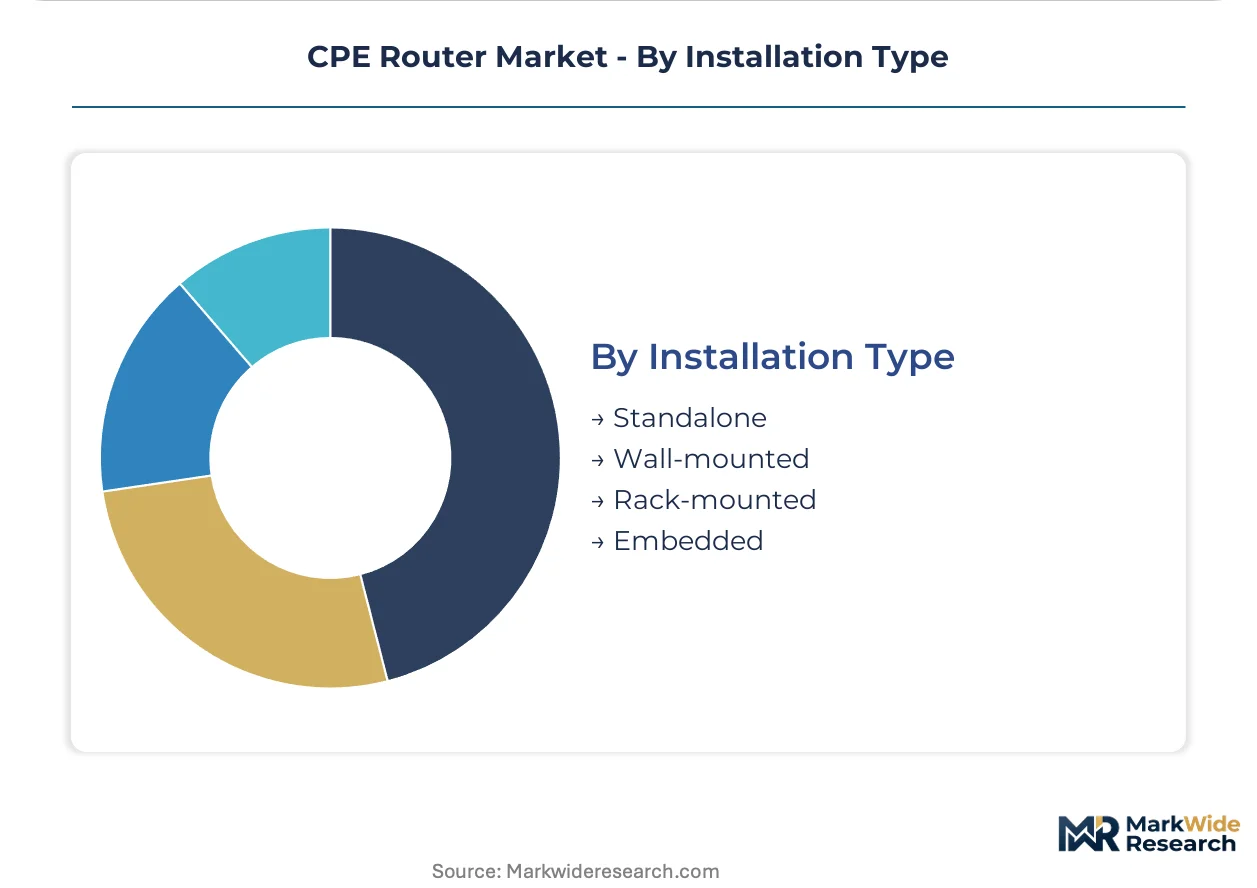
Installation Type:
Physical mounting configuration correlates with thermal design complexity and service accessibility, with rack-mounted units demanding redundant cooling and hot-swap capabilities absent in residential form factors.
- Rack-mounted:19-inch chassis installations in data center edge and telecommunications facilities accommodate modular interface cards and redundant power supplies. Enterprise deployments in the United States favor these for centralized management and standardized cooling infrastructure. Front-panel serviceability reduces mean-time-to-repair in mission-critical locations.
- Standalone:Desktop or shelf-positioned units for residential and small office environments.
- Wall-mounted:Space-constrained installations requiring integrated antenna positioning.
- Embedded:System-on-module implementations for industrial gateway and IoT aggregation applications.
Standalone units lead by volume. Rack-mounted configurations are expanding most quickly as enterprise edge infrastructure consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese manufacturing clusters dominate CPE router trade balances, while import demand concentrates in fiber-intensive Western European markets and subsidy-driven North American deployments.
United States
US operators deploy Wi-Fi 7 gateways through USDA ReConnect-funded rural broadband programs. FCC broadband nutrition labels mandate standardized latency disclosures for all subscriber equipment. Dallas-Fort Worth logistics hubs coordinate nationwide CPE distribution for tier-one ISPs.
Germany
German operators refresh GPON termination hardware to meet government-mandated gigabit coverage targets by 2025. ETSI harmonization streamlines radio equipment approvals across EU member states. Bavaria's industrial corridor hosts testing facilities for energy-efficient router designs.
China
MIIT certification requirements gate domestic 5G CPE market entry for global vendors. Shenzhen production clusters achieve cost optimization through integrated switch fabric manufacturing. Yangtze River Delta fabs concentrate advanced Wi-Fi 7 baseband silicon output.
India
TRAI fiber-to-the-home mandates accelerate DSL-to-fiber migration timelines for incumbent operators. PLI scheme incentives attract CPE assembly investments for export-oriented manufacturing. Bengaluru's electronics corridor anchors firmware development for carrier aggregation algorithms.
South Korea
Korean operators bundle Wi-Fi 7 equipment with multi-gigabit service tiers to reduce subscriber churn. MFDS radio equipment directives align with ETSI standards for streamlined regional launches. Seoul Capital Area data centers drive rack-mounted edge router demand from financial services firms.
CPE Router Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on baseband silicon and optical transceivers. The vendor base stratifies across three tiers: multinational network equipment providers with managed service portfolios, regional champions competing on cost, and specialized mesh system vendors. Consolidation pressure intensifies as leasing-based procurement transfers ownership risk to vendors with financing capabilities. Dominant competitive moves include strategic partnerships for spectrum licensing and vertical integration into firmware development.
Among multinational platform providers, Nokia Corporation and Cisco Systems occupy positions emphasizing enterprise edge disaggregation and SD-WAN integration. Huawei Technologies anchors the scale-driven tier with Shenzhen-based production advantages for emerging-market deployments. TP-Link Technologies exemplifies channel-control specialists targeting residential segments through retail and ISP subsidy programs.
| Leading Market Players |
|---|
| Netgear Inc. |
| Nokia Corporation |
| Huawei Technologies |
| ARRIS International |
| Fiberhome |
| ZTE Corporation |
| Cisco Systems, Inc. |
| Sagemcom |
| TP-Link Technologies |
| Others |
Pricing and Supply Chain Analysis
Undercapacity at Taiwan's advanced Wi-Fi 7 baseband foundries is compressing supplier margins while amplifying pricing power for contract manufacturers with secured allocation. Equipment vendors absorb higher silicon costs through leasing-based procurement structures that transfer ownership risk to financing-capable integrators.
Pricing Analysis
ISP procurement teams anchor contract-based long-term offtake structures that lock in multi-year equipment refresh cycles. Pricing stratifies across Wi-Fi 7 premium tiers, mid-range Wi-Fi 6E standard offerings, and legacy DSL economy units based on certification complexity and firmware support duration. Cost compression in the economy tier is intensifying because copper network sunset delays strand replacement revenue. Residential retail channels exhibit highest price sensitivity, while large enterprise edge deployments show lowest sensitivity due to SD-WAN integration requirements.
Supply Chain Analysis
Foxconn, Jabil, and Pegatron hold dominant contract-manufacturing capacity for CPE router assembly across Shenzhen, Dongguan, and Ho Chi Minh City facilities. Production draws from Taiwan-sourced Wi-Fi 7 baseband silicon, Chinese switch fabric chipsets, and Malaysian PCB substrates. Single-source vulnerability concentrates in advanced 6 GHz RF front-end components from three Taiwan foundry operators. Distribution runs through tier-one ISP logistics hubs in Dallas-Fort Worth, Frankfurt, and Singapore before last-mile subscriber deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as leasing-based procurement fragments vendor relationships and creates service-attachment niches for specialized firmware and remote monitoring providers.
For Market Incumbents: Pre-empt margin erosion by securing captive supply of Wi-Fi 7 baseband silicon through foundry partnership structures rather than spot-market allocation. Consolidate position through backward integration into optical transceiver manufacturing for GPON termination equipment, neutralizing ZTE and Fiberhome cost advantages in Chinese ISP tenders. For New Entrants and Emerging Players: Rural broadband subsidy programs in the United States, Canada, and Australia present white-space demand with price-insensitive procurement characteristics. Target USDA ReConnect-funded deployments with fixed-wireless 5G CPE units that bypass fiber trenching economics. Pursue managed-service bundling with regional ISPs lacking in-house firmware development capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated firmware specialists with Wi-Fi 7 beamforming algorithm expertise and existing FCC certification track records. Long-term viability hinges on regulatory compliance velocity rather than hardware cost position alone. Monitor ETSI spectrum reallocation decisions for 6 GHz band access expansion as inflection signal for tri-band platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Wi-Fi 7 Certification Fast-Track | FCC and ETSI pre-approval investments compress time-to-market by eight to fourteen months for global launches. |
| Foundry Partnership Structuring | Secured allocation agreements with Taiwan baseband manufacturers neutralize semiconductor concentration risk exposure. |
| Leasing-Platform Financing Capability | Asset-light balance sheet structures align with tier-one operator capital-light procurement preferences in Germany and the United States. |
| Firmware-as-a-Service Integration | Remote monitoring and over-the-air update obligations create recurring revenue attachment to hardware refresh cycles. |
| Rural Subsidy Program Alignment | USDA ReConnect and similar Canadian and Australian programs fund price-insensitive CPE deployment for underserved populations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, ETSI harmonized standards publications, MIIT certification filings, and ISP procurement disclosure documents. Interviews with network equipment vendor product managers, tier-one ISP procurement directors, contract manufacturing operations executives, and semiconductor foundry account managers informed demand and supply-side validation. Bottom-up shipment modeling triangulates against top-down service provider capex analysis.
Forecast inputs include Wi-Fi 7 adoption curves, fiber-to-the-home penetration rates, 5G fixed wireless access subscriber acquisition, and enterprise edge disaggregation intensity across the analysis window. Segmentation dimensions span product architecture, end-user type, physical layer technology, and installation configuration. CAGRs derive from installed base replacement interval compression and gigabit broadband penetration elasticity.
Practitioners should monitor FCC spectrum reallocation proceedings, ETSI energy-efficiency mandate timelines, and Taiwan foundry utilization reports for early signals requiring forecast revision. Cross-checking against operator-reported CPE shipment volumes and semiconductor foundry revenue disclosures by product category is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
Germany Residential Gateway Market
Network Technology
Network Telemetry Market
Network Technology
2.4GHz Router Market
Network Technology
United States and European Fiber Optic Cable Market
Network Technology
SP Routing and Ethernet Switching Market
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Lit Fiber Market
Network Technology
Fiber to the Premises Market
Network Technology
Digital Repeater Market
Network Technology
Hyperconnectivity Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
RTP Market
Network Technology
Mobile Network Optimization Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
Enterprise Network Equipment Market