
 Global Optical Transport Network (OTN) Market | 2026-2036
Global Optical Transport Network (OTN) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Transport Network (OTN) Market Foresight
Premium coherent transponder performance is decoupling from commodity optical amplifier pricing as hyperscalers demand 800G+ wavelengths while regional carriers optimize 100G legacy routes. Huawei Technologies Co. Ltd leverages captive silicon photonics R&D to sustain cost advantages in Asia-Pacific deployments. Ciena Corporation differentiates through programmable line systems that anchor North American cloud interconnect contracts. Nokia Corporation competes on subsea cable integration, controlling a narrow but high-margin niche in transoceanic routes.
Optical Transport Network (OTN) refers to the ITU-T standardized digital wrapper protocol that maps client signals into optical channels using G.709 framing with forward error correction, enabling transparent multi-vendor interoperability across fiber infrastructure. Its primary purpose is to guarantee service-level agreements for latency, jitter, and availability across carrier-grade backbone networks. Transponder modules command the largest value share as baud-rate escalation drives module refresh cycles. DWDM technology leads volume deployment though Flexgrid adoption accelerates in research networks requiring elastic spectrum allocation. Data Center Interconnect application segments attract the fastest investment as cloud operators build dedicated fiber meshes between metro facilities.
ITU-T G.709 standards, FCC Part 68 terminal equipment rules, and EU RoHS substance restrictions collectively shape product compliance costs and interoperability testing burdens for equipment vendors. ETSI EN 300 019 environmental specifications further constrain outdoor optical line terminal designs for European railway and utility deployments. Stakeholders must monitor silicon photonics foundry capacity allocation as coherent DSP chip supply tightens against 800G port demand.
Market Dynamics
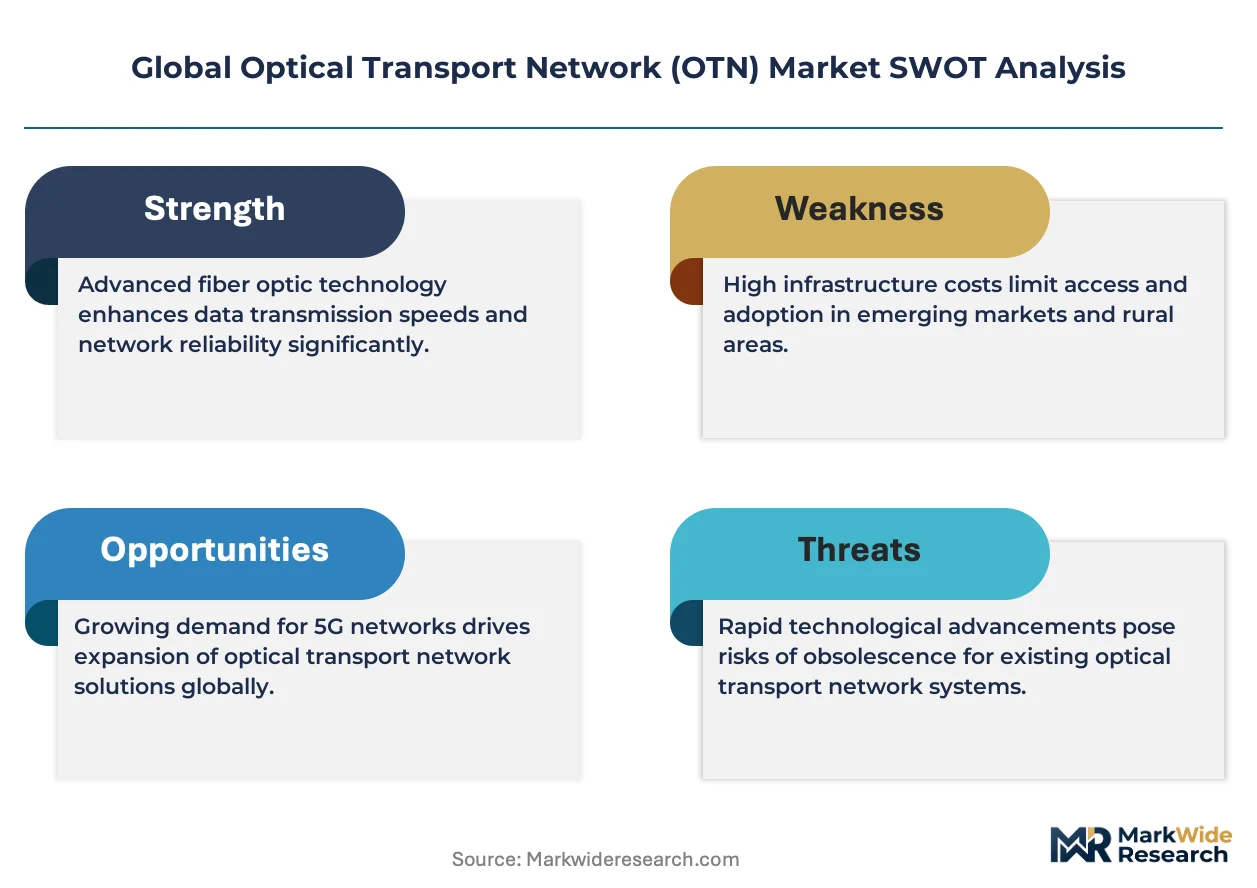
Coherent DSP silicon supply concentration is forcing equipment vendors into multi-year foundry commitments while hyperscalers accelerate 800G wavelength deployment, creating a structural squeeze between component availability and customer refresh cycles.
Growth Catalysts
- ITU-T G.709 standardization:The protocol enables transparent multi-vendor interoperability, reducing integration friction for carriers operating heterogeneous fiber infrastructure across national boundaries.
- Hyperscale data center construction:Cloud operators in the United States, China, and Germany are deploying dedicated fiber meshes between metro facilities, driving concentrated demand for high-capacity transponder modules.
- Flexgrid spectrum allocation:Research networks requiring elastic optical channels are accelerating adoption of reconfigurable add-drop multiplexers with variable channel spacing.
Market Restraints
- Silicon photonics foundry concentration:Coherent DSP chip production concentrates among a handful of advanced semiconductor fabs, creating supply vulnerability against 800G port demand.
- EU RoHS substance restrictions:Compliance testing for restricted materials in optical line terminals adds certification burden and extends product qualification timelines for European railway deployments.
- Legacy 100G route optimization:Regional carriers extending depreciation cycles on installed base delay refresh investments, compressing near-term addressable market for next-generation equipment.
Strategic Opportunities
- Subsea cable integration:Transoceanic route expansion creates demand for specialized wet-plant terminal equipment with ultra-long-haul coherent transmission capabilities.
- India's BharatNet rural fiber program:Government-backed optical backbone construction opens procurement volume for cost-optimized 100G-400G transport platforms.
- ETSI EN 300 019 environmental specifications:Railway and utility network mandates for outdoor optical line terminals create certified-product premiums in European infrastructure markets.
Industry Challenges
- Coherent optical engineering talent scarcity:Specialized skills in high-baud-rate DSP algorithm development concentrate among experienced design teams, constraining vendor R&D scaling.
- Interoperability certification timelines:Multi-vendor testing against ITU-T G.709 implementations extends product launch schedules and defers revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Transport Network (OTN) Market |
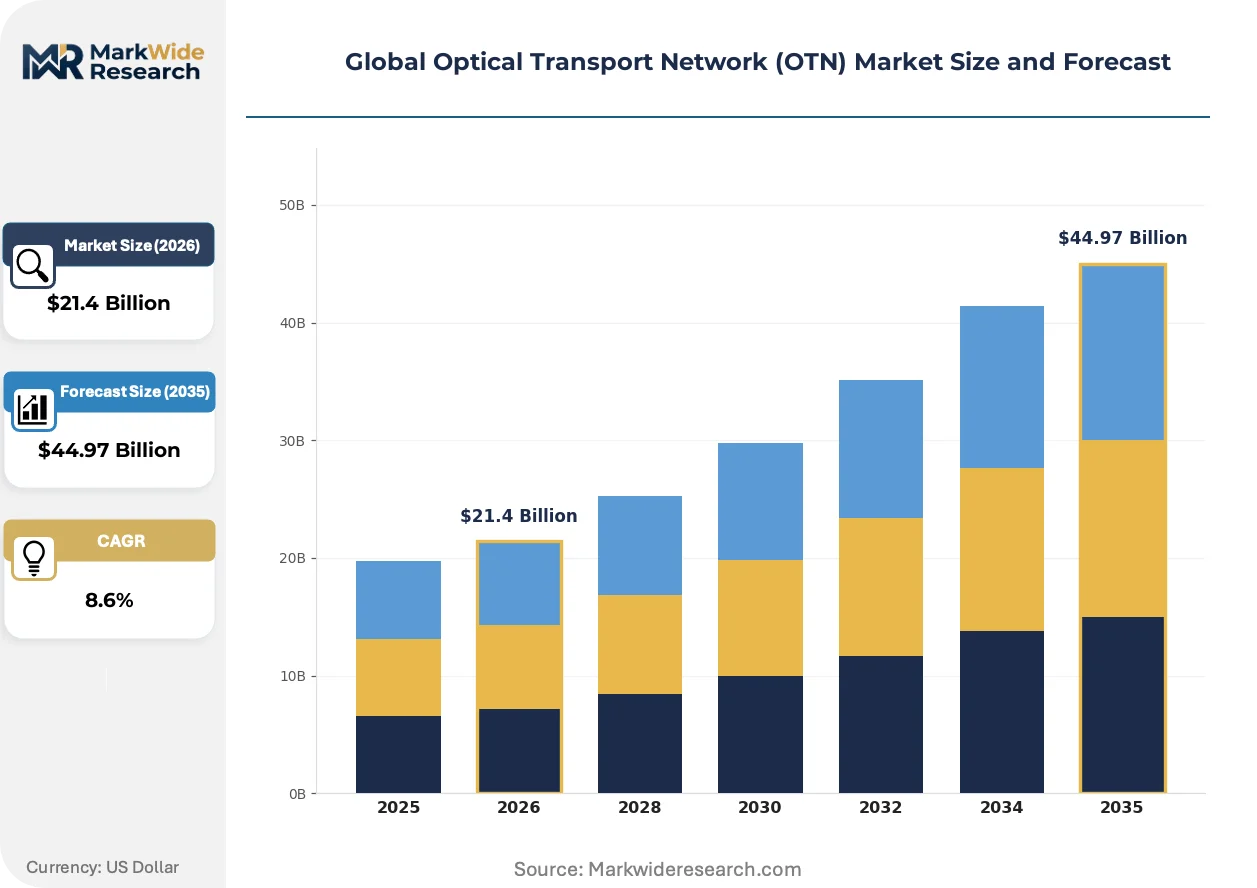
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $44.97 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
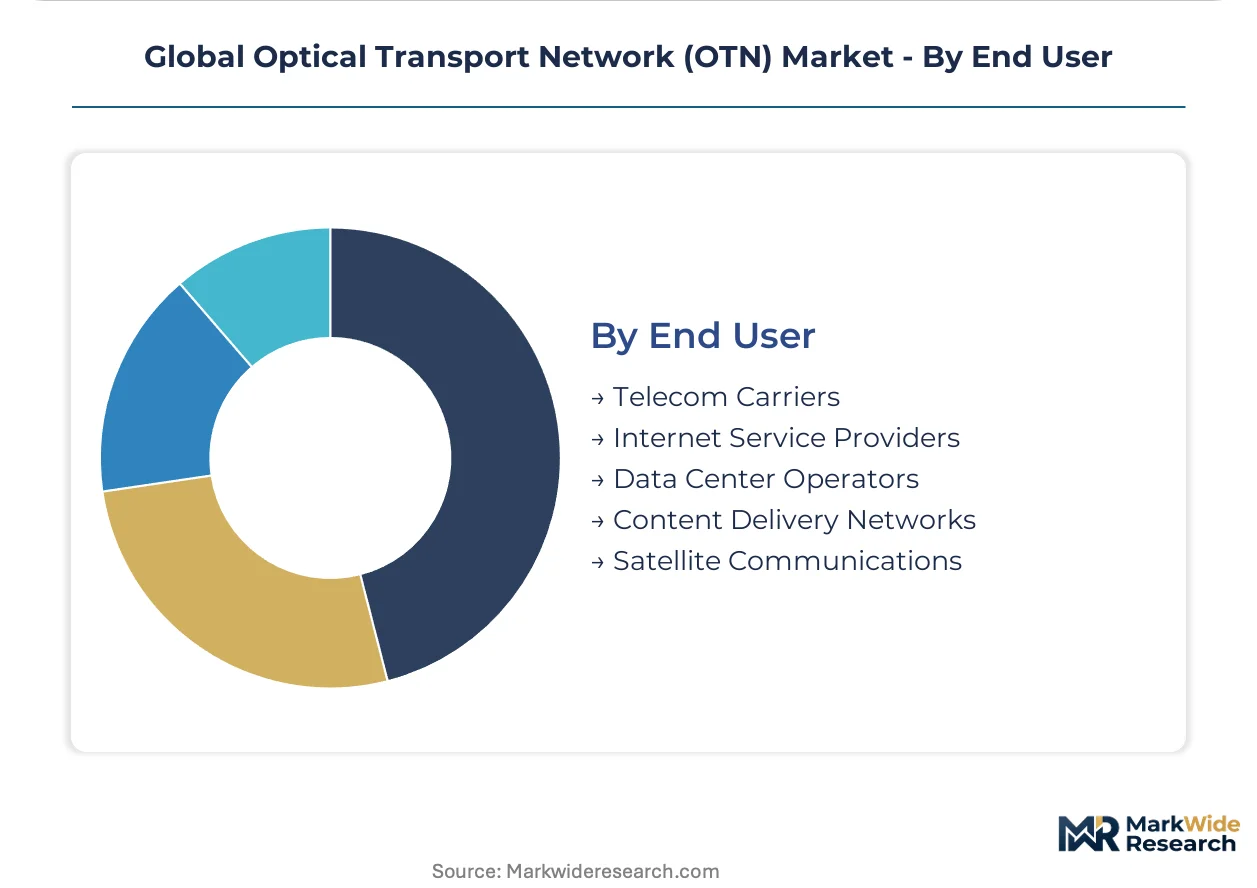
| Segmentation | Product Type: Transponders, Optical Amplifiers, Multiplexers, Network Management Systems, Switches Technology: WDM, DWDM, ROADM, MPLS-TP, Flexgrid Application: Data Center Interconnect, Long-Haul Transmission, Metro Networks, Submarine Cable Systems, Cloud Services End User: Telecom Carriers, Internet Service Providers, Data Center Operators, Content Delivery Networks, Satellite Communications |
| Companies Covered | ZTE Corporation, Cisco Systems Inc., Huawei Technologies Co. Ltd, ADVA Optical Networking SE, Fujitsu Limited, Ciena Corporation, Infinera Corporation, NEC Corporation, Nokia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Transport Network (OTN) Market Shifts & Advancements
Open optical line systems are decoupling transponder procurement from amplifier shelf decisions, enabling hyperscalers to mix vendor components within unified fiber infrastructure.
Pluggable coherent optics is modularizing transport architecture by embedding DSP and optical engine within QSFP-DD form factors, collapsing traditional transponder shelf requirements. Cloud operators are deploying these modules directly into switch routers, eliminating separate transport layers. This compression is modularizing vendor value capture from chassis-based systems toward component-level suppliers.
FCC Part 68 terminal equipment rules are tightening electromagnetic compatibility requirements for optical transport gear deployed in US carrier central offices. Equipment vendors must demonstrate compliance with conducted emissions limits across extended temperature ranges. North American cloud interconnect contracts now specify pre-certified modules to accelerate deployment timelines.
Buying committees are consolidating optical transport procurement decisions within hyperscale network engineering teams, displacing traditional carrier supply chain intermediaries. Equipment vendors are establishing direct technical relationships with cloud operators, bypassing systems integrators. This channel compression is most visible in United States and China metro markets where cloud operators self-build fiber infrastructure.
Global Optical Transport Network (OTN) Market Segmentation
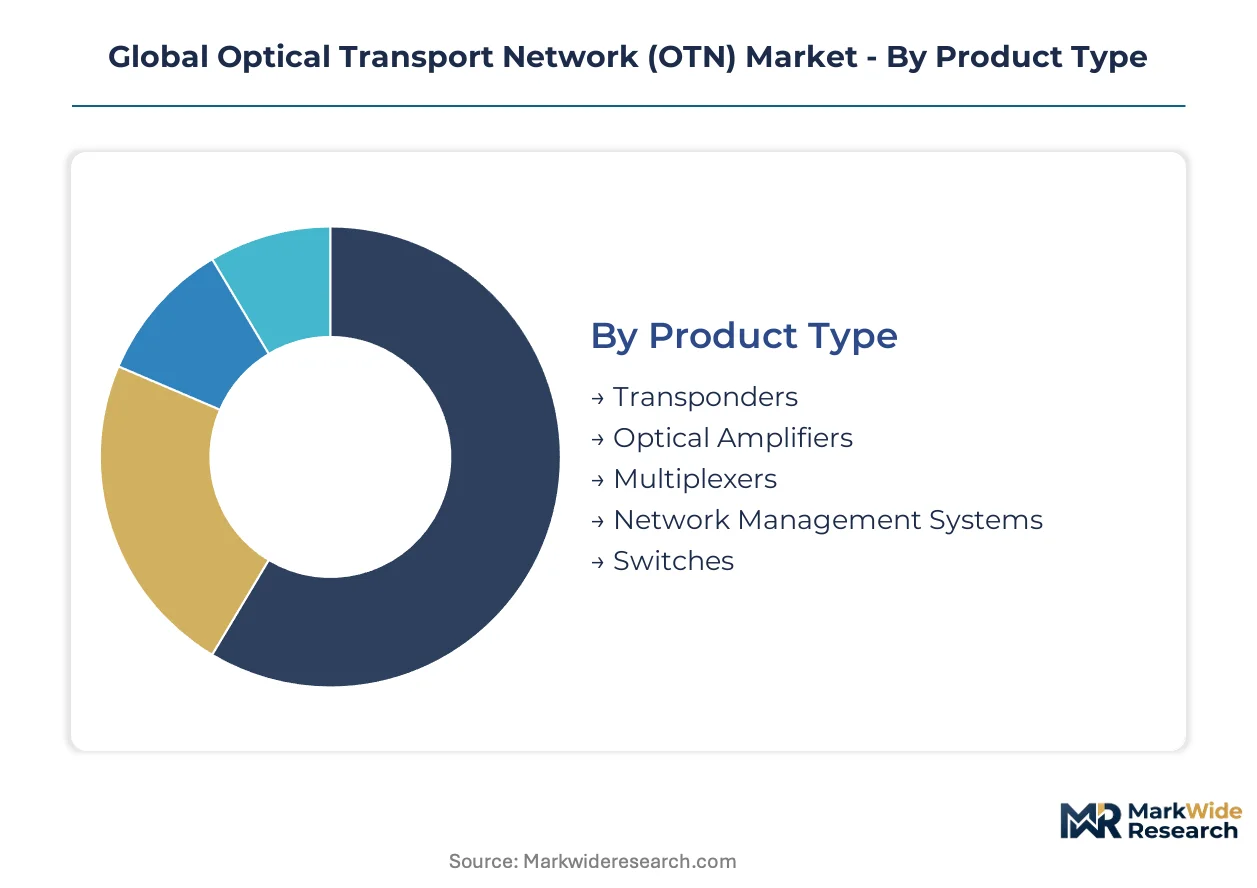
OTN procurement decisions hinge on certification requirements that vary sharply across product types and deployment environments. Equipment vendors must align engineering roadmaps with ITU-T G.709 interoperability mandates, FCC Part 68 electromagnetic rules, and ETSI EN 300 019 environmental specifications to unlock addressable demand in carrier and hyperscale channels.
Product Type:
Certification burdens cluster around coherent DSP integration and outdoor environmental tolerance, with FCC Part 68 and ETSI EN 300 019 creating divergent approval pathways for central office versus railway deployments.
- Transponders:These modules integrate high-baud-rate coherent DSP with silicon photonics engines to map client signals onto optical wavelengths. Hyperscale data center operators in the United States and Germany are refreshing 400G-800G transponder shelves at accelerated cadences to support cloud interconnect bandwidth scaling. ITU-T G.709 interoperability testing extends vendor qualification timelines.
- Optical Amplifiers:Erbium-doped fiber amplifiers and Raman amplification stages boost signal power across long-haul spans. Regional carriers in China optimize legacy 100G routes using cost-sensitive amplifier upgrades rather than full transponder replacement, compressing near-term premium product demand. FCC Part 68 conducted emissions compliance adds certification overhead for US central office deployments.
- Multiplexers:ROADM-based wavelength aggregation devices from Ciena and Huawei dominate metro core builds.
- Network Management Systems:Software-defined control planes orchestrate multi-vendor optical layers per ITU-T standards.
- Switches:Packet-optical hybrid platforms serve enterprise edge connectivity in German utility networks.
Leading the category by volume: Optical Amplifiers. Growing fastest: Transponders.
Technology:
Cost tier differentiation separates mature WDM deployments from premium Flexgrid installations requiring specialized foundry capacity and extended R&D amortization.
- DWDM:Dense wavelength division multiplexing packs 80+ channels onto single fiber pairs using 50GHz or 100GHz spacing. Telecom carriers across India and Germany anchor volume demand for 100G-400G DWDM systems as BharatNet rural fiber programs and utility backbone expansions drive procurement. Legacy route optimization limits premium pricing power.
- Flexgrid:Variable channel spacing enables elastic spectrum allocation for research and cloud operator networks. Hyperscale facilities in the United States deploy Flexgrid ROADMs to support 800G+ superchannels with non-standard bandwidth granularity, though coherent DSP supply concentration constrains deployment velocity. ITU-T G.694.1 flexible grid extensions guide interoperability testing.
- WDM:Coarse wavelength systems serve cost-optimized access layer builds in emerging markets.
- ROADM:Reconfigurable add-drop nodes enable wavelength routing without optical-electrical conversion.
- MPLS-TP:Transport profile packet switching supports carrier Ethernet service delivery.
Highest deployment maturity: WDM. Steepest expansion trajectory: Flexgrid.
Application:
Customer type concentration shapes procurement patterns, with hyperscale self-build programs displacing traditional carrier intermediaries in fastest-growing segments.
- Data Center Interconnect:Dedicated fiber meshes linking metro cloud facilities demand low-latency, high-capacity optical transport. Operators in the United States and China are constructing private fiber infrastructures between availability zones, bypassing traditional telecom carrier services and compressing channel margins. FCC Part 68 pre-certification requirements accelerate deployment timelines.
- Cloud Services:Hyperscale backbone extensions require programmable line systems with software-defined provisioning. Cloud engineering teams in Germany consolidate optical procurement decisions internally, establishing direct vendor relationships that displace systems integrators from traditional carrier supply chains. EU RoHS substance restrictions extend qualification cycles.
- Long-Haul Transmission:Inter-city fiber routes anchor 400G coherent deployments for national carriers.
- Metro Networks:Urban aggregation rings concentrate ROADM volume for regional telecom operators.
- Submarine Cable Systems:Transoceanic wet-plant terminals command ultra-long-haul coherent premiums.
Largest installed base: Metro Networks. Gaining share fastest: Data Center Interconnect.
End User:
Supply concentration among coherent DSP foundries creates allocation tension between telecom carrier refresh cycles and hyperscale data center operator expansion timelines.
- Data Center Operators:Hyperscale engineering organizations self-procure optical transport equipment for private fiber meshes. Cloud operators in the United States and China negotiate multi-year foundry commitments alongside equipment vendors to secure 800G coherent DSP allocation, bypassing traditional carrier supply chain intermediaries. Direct technical relationships compress vendor sales cycles.
- Telecom Carriers:Incumbent operators manage heterogeneous multi-vendor optical infrastructures requiring ITU-T G.709 interoperability certification. Carriers in Germany and India extend depreciation cycles on 100G legacy routes, delaying refresh investments and constraining near-term addressable market for next-generation platforms. ETSI EN 300 019 environmental specifications govern outdoor railway deployments.
- Internet Service Providers:Competitive broadband operators deploy cost-optimized 100G-400G transport.
- Content Delivery Networks:Edge caching networks require metro optical capacity for origin server connectivity.
- Satellite Communications:Ground station fiber backhaul demands low-latency transport for LEO constellation gateways.
Dominant procurement volume: Telecom Carriers. Expanding most quickly: Data Center Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the densest concentration of optical transport manufacturing and hyperscale data center deployment worldwide. Cloud operators across the Pearl River Delta are constructing private fiber meshes between metro facilities at unprecedented scale. Foundry commitments for coherent DSP silicon flow disproportionately through Chinese semiconductor fabs.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are self-building dedicated fiber infrastructure between availability zones. FCC Part 68 terminal equipment rules tighten electromagnetic compatibility requirements for central office deployments. Ashburn's Data Center Alley commands the largest transponder procurement volume for cloud interconnect applications.
China
Cloud service providers in Beijing and Shanghai are scaling 800G wavelength deployment for metro backbone expansion. MIIT spectrum allocation policies govern 5G and optical transport coexistence in dense urban corridors. Hangzhou's cloud computing cluster drives concentrated demand for programmable line systems.
Germany
Utility network operators in North Rhine-Westphalia are deploying outdoor optical line terminals for railway backbone modernization. ETSI EN 300 019 environmental specifications mandate extended temperature range certification for infrastructure deployments. Frankfurt's financial services corridor anchors premium coherent transponder demand for low-latency trading networks.
India
Government-backed BharatNet rural fiber programs are opening procurement volume for cost-optimized 100G-400G transport platforms. TRAI infrastructure sharing guidelines accelerate passive optical network deployment in underserved districts. Karnataka's technology corridor concentrates systems integration expertise for national backbone projects.
Japan
Submarine cable landing stations in Chiba and Kanagawa are upgrading wet-plant terminal equipment for trans-Pacific capacity expansion. METI green transformation initiatives incentivize energy-efficient coherent transmission technologies. Tokyo's financial district demands ultra-low-latency optical transport for high-frequency trading infrastructure.
Global Optical Transport Network (OTN) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coherent DSP integration depth and foundry access tiering. The vendor base stratifies between captive silicon photonics developers, programmable line system architects, and subsea cable integration specialists. Three archetypes dominate: integrated platform vendors with captive semiconductor capacity, disaggregated optical system specialists, and component-level coherent module suppliers. Competitive moves concentrate on multi-year foundry commitment negotiations and direct hyperscale technical relationship cultivation.
Within the integrated platform tier, Huawei Technologies Co. Ltd and ZTE Corporation represent the Asia-Pacific captive R&D archetype, while Ciena Corporation exemplifies the North American programmable systems specialist. Nokia Corporation occupies a position in subsea cable integration. These three anchors demonstrate how geographic clustering around foundry partnerships and hyperscale customer proximity is reshaping vendor competitive positioning.
| Leading Market Players |
|---|
| ZTE Corporation |
| Cisco Systems Inc. |
| Huawei Technologies Co. Ltd |
| ADVA Optical Networking SE |
| Fujitsu Limited |
| Ciena Corporation |
| Infinera Corporation |
| NEC Corporation |
| Nokia Corporation |
| Others |
Supply & Pricing Matrix
Coherent DSP silicon foundry costs cascade through optical transport equipment tiers, with 800G-capable wafer allocation premiums translating into transponder shelf pricing stratification across hyperscale and regional carrier buyer segments.
Pricing Analysis
Throughput-per-watt benchmarks anchor value-based pricing for coherent transponder modules, with hyperscale data center operators in the United States and Germany commanding volume discounts on 400G-800G wavelengths while regional carriers absorb certification premiums for ITU-T G.709 interoperability. Price differentiation separates Flexgrid-enabled programmable line systems from fixed-grid DWDM commodity platforms. Pricing pressure stems from coherent DSP supply concentration constraining module availability against cloud operator refresh timelines. Regional carriers optimizing legacy 100G routes exhibit highest price sensitivity; hyperscale self-build programs demonstrate lowest sensitivity due to total cost of ownership optimization.
Supply Chain Analysis
Direct-to-hyperscale technical engagement channels handle cloud operator procurement, displacing traditional systems integrator intermediaries in United States and China metro markets. Coherent DSP silicon concentrates in Taiwan, South Korea, and United States advanced semiconductor fabs. Supply chains draw from germanium substrates, indium phosphide wafers, and specialized packaging materials. Single-source vulnerability in 800G-capable foundry capacity creates allocation tension between telecom carrier and hyperscale demand cycles. Distribution runs through equipment vendor direct sales organizations with embedded field application engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optical transport market sits in an 800G wavelength transition phase, with pluggable coherent optics in QSFP-DD form factors displacing traditional chassis-based transponder architectures.
For Market Incumbents: Deploy captive silicon photonics R&D to secure coherent DSP allocation commitments against hyperscale demand surges. Incumbents must consolidate programmable line system differentiation through software-defined control plane integration while defending against disaggregated optical component suppliers eroding chassis-based value capture. Foundry partnership depth serves as the critical lever for sustaining margin position. For New Entrants and Emerging Players: Capture BharatNet rural fiber procurement volume in India through cost-optimized 100G-400G transport platforms with ETSI EN 300 019 environmental pre-certification. Railway and utility network mandates across Germany present secondary white-space opportunity. Component-level coherent module supply to hyperscale switch router vendors offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Multi-year foundry commitment announcements from cloud operators are the leading indicator that coherent DSP supply scarcity will persist, favoring vendors with captive semiconductor capacity or secured allocation agreements. Long-term viability hinges on positioning upstream of pluggable optics modularization. Acquisition targets should demonstrate silicon photonics design capability or established hyperscale technical relationships. Watch for FCC Part 68 pre-certification requirements accelerating as signal of North American cloud interconnect procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Foundry Commitment | Secures coherent DSP silicon allocation against 800G hyperscale demand surges from United States and China cloud operators. |
| Pluggable Optics Integration | Embeds transport functionality within QSFP-DD modules for direct switch router deployment, collapsing traditional chassis layers. |
| ETSI EN 300 019 Certification | Unlocks outdoor optical line terminal premiums in German railway and European utility infrastructure markets. |
| Direct Hyperscale Engagement | Bypasses systems integrators to establish technical relationships with cloud engineering teams in Ashburn and Shanghai. |
| Flexgrid ROADM Development | Enables elastic spectrum allocation for 800G+ superchannels in research and cloud operator networks per ITU-T G.694.1. |
Research Methodology
Independent corroboration across primary interviews with optical transport equipment executives, hyperscale network engineering directors, and coherent DSP semiconductor specialists underwrites the qualitative findings. Secondary validation draws from ITU-T standards documentation, FCC Part 68 regulatory filings, and hyperscaler capital expenditure disclosures. Bottom-up segment sizing triangulates against top-down infrastructure deployment tracking across United States, China, and Germany metro markets.
Rate-of-change decomposition separates volume drivers from value migration across the analysis window. Segmentation dimensions span product type, technology tier, application use case, and end-user procurement archetype. CAGRs derive from installed base refresh cycle modeling against hyperscale construction pipelines. Forecast inputs incorporate coherent DSP foundry capacity allocation schedules and ITU-T G.709 interoperability certification timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silicon photonics foundry expansion decisions and hyperscale self-build program continuity. Forecasts reflect documented assumptions regarding cloud operator capex trajectories and regulatory certification stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Private 5G Network Market
Network Technology
Gigabit Passive Optical Network (GPON) Market
Network Technology
Wi-Fi Network Equipment Market
Network Technology
United States and European Fiber Optic Cable Market
Network Technology
WAN Optimization Controllers Market
Network Technology
North America Network Management Solutions Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
Lit Fiber Market
Network Technology
Europe Structured Cabling Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Wi-Fi Extender Market
Network Technology
DNS DHCP and IPAM Market
Network Technology
Global Network Monitoring Market
Network Technology
Service Provider Network Infrastructure Market
Network Technology
Network Management Systems (NMS) Market
Network Technology
Data Center Switches Market