
 Ethernet Backhaul Equipment Market | 2026-2036
Ethernet Backhaul Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ethernet Backhaul Equipment Market Foresight
Mobile operator infrastructure spend is consolidating around 5G transport upgrades as carriers phase out legacy TDM circuits. Huawei Technologies dominates integrated microwave and fiber backhaul portfolios across Asia, while Ericsson anchors European deployments with its Router 6000 series and microwave transport platforms. Cisco Systems competes in the enterprise and service provider edge router segment, leveraging its ASIC silicon program to sustain pricing power in high-density 100G aggregation nodes.
Ethernet backhaul equipment comprises routers, switches, optical transceivers, and Ethernet adapters engineered to aggregate and transport cellular traffic from cell sites to core networks at speeds from Fast Ethernet through 100 Gigabit Ethernet. These systems employ MPLS, Segment Routing, and timing synchronization protocols such as IEEE 1588v2 and SyncE to meet sub-microsecond latency requirements for 5G fronthaul and midhaul. Optical transceivers represent the fastest-expanding product category as coherent optics displace direct-detect modules in metro aggregation, while Gigabit Ethernet and 10 Gigabit Ethernet technology tiers remain the volume backbone for rural and small-cell deployments where cost-per-bit dominates procurement.
The FCC in the United States enforces network reliability and cybersecurity standards for critical communications infrastructure, while the EU AI Act and GDPR impose data governance requirements on automated network management systems deployed in European backhaul networks. China's MIIT mandates domestic encryption and GB standards compliance for equipment operating within national 5G transport layers. Stakeholders must monitor divergence between open RAN transport specifications and proprietary vendor implementations, as interoperability certifications will determine supplier eligibility in next-generation public network tenders.
Market Dynamics
5G fronthaul timing synchronization requirements are compressing equipment refresh cycles as operators replace legacy TDM-based backhaul with packet-switched Ethernet platforms capable of sub-microsecond latency performance.
Growth Catalysts
- BharatNet rural broadband initiative:India's government-mandated fiber-to-the-village program is mandating Ethernet aggregation equipment for 250,000+ gram panchayat connections.
- Open RAN transport specifications:The O-RAN Alliance's fronthaul interface definitions are creating procurement pull for disaggregated routers and switches in European and North American carrier tenders.
- Coherent optical modules:400G ZR and ZR+ pluggable optics are collapsing metro aggregation cost-per-bit economics for cloud interconnect and 5G midhaul applications.
Market Restraints
- ASIC silicon supply concentration:Advanced 7nm and 5nm fabrication capacity for high-density router chips remains captive to Taiwan-based foundry constraints.
- GB standards compliance:China's MIIT mandates domestic encryption certification for equipment deployed in national 5G transport layers, creating technical friction for non-domestic suppliers.
- Copper and rare earth input costs:Optical transceiver manufacturing depends on gallium arsenide and indium phosphide substrates subject to export control volatility.
Strategic Opportunities
- Private 5G enterprise networks:Manufacturing campuses and logistics hubs in Germany and Japan are deploying dedicated Ethernet backhaul for ultra-reliable low-latency communication.
- EU AI Act network governance:Automated fault prediction systems in European backhaul networks must demonstrate algorithmic transparency, creating demand for explainable AIOps platforms.
- Segment Routing IPv6 convergence:The combination of SRv6 traffic engineering and IPv6-only core networks is enabling simplified provisioning for multi-access edge computing sites.
Industry Challenges
- IEEE 1588v2 timing engineer scarcity:Sub-nanosecond clock synchronization deployment requires specialized expertise in boundary clock and transparent clock configuration that outstrips available talent pools.
- Multi-vendor interoperability certification:Open RAN fronthaul gateways must pass O-RAN WG4 conformance testing, extending product qualification timelines by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethernet Backhaul Equipment Market |
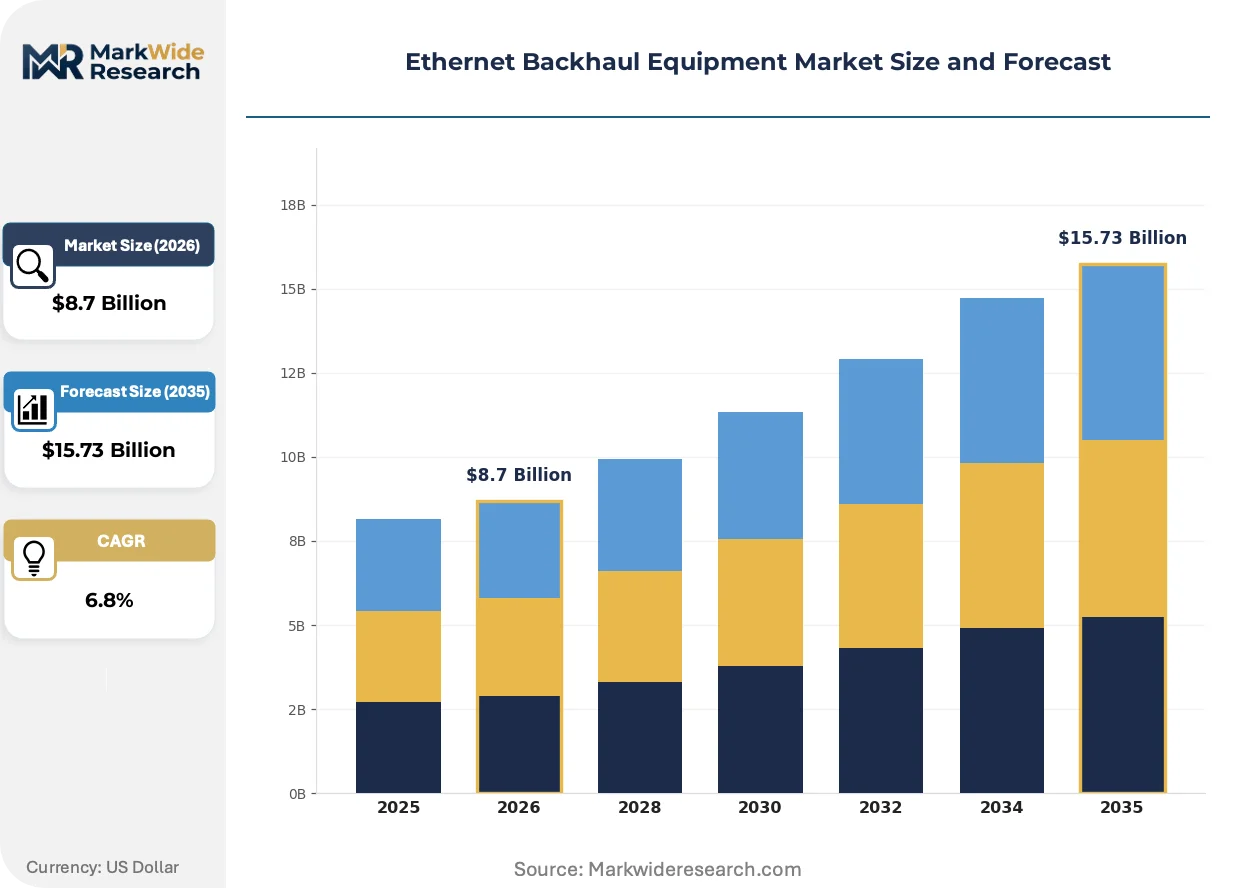
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Routers, Switches, Optical Transceivers, Ethernet Adapters Technology: Fast Ethernet, Gigabit Ethernet, 10 Gigabit Ethernet, 100 Gigabit Ethernet End User: Telecom Operators, Internet Service Providers, Enterprises, Government Agencies Application: Mobile Backhaul, Business Continuity, Cloud Services, Data Transmission |
| Companies Covered | Huawei Technologies, Ericsson, NEC Corporation, Cisco Systems, Nokia, Juniper Networks, Ceragon Networks, ZTE, ADVA Optical Networking, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethernet Backhaul Equipment Market Shifts & Advancements
Intent-based networking software is automating configuration management across heterogeneous backhaul estates, reducing manual provisioning errors while compressing service activation intervals for 5G site deployments.
Artificial intelligence for IT operations is automating fault correlation and root-cause analysis in multi-layer transport networks. Tier-1 operators in South Korea and the United States are deploying machine learning models that predict optical link degradation before service impact occurs. This capability is automating preventive maintenance scheduling and reducing mean-time-to-repair for critical 5G fronthaul connections.
The FCC's supply chain security rules for communications infrastructure are mandating component provenance documentation for equipment receiving federal funding support. Router and switch vendors must now certify silicon sourcing and manufacturing location for each hardware revision. This policy is forcing procurement teams to maintain alternative qualified suppliers for ASIC and optical component streams.
Outcome-based network availability contracts are displacing traditional equipment purchase models in European operator tenders. Vendors now guarantee specific latency and packet-loss thresholds rather than selling hardware with standard warranty terms. This shift concentrates risk with equipment suppliers while aligning payment schedules to measured service performance in German and French metro network expansions.
Ethernet Backhaul Equipment Market Segmentation
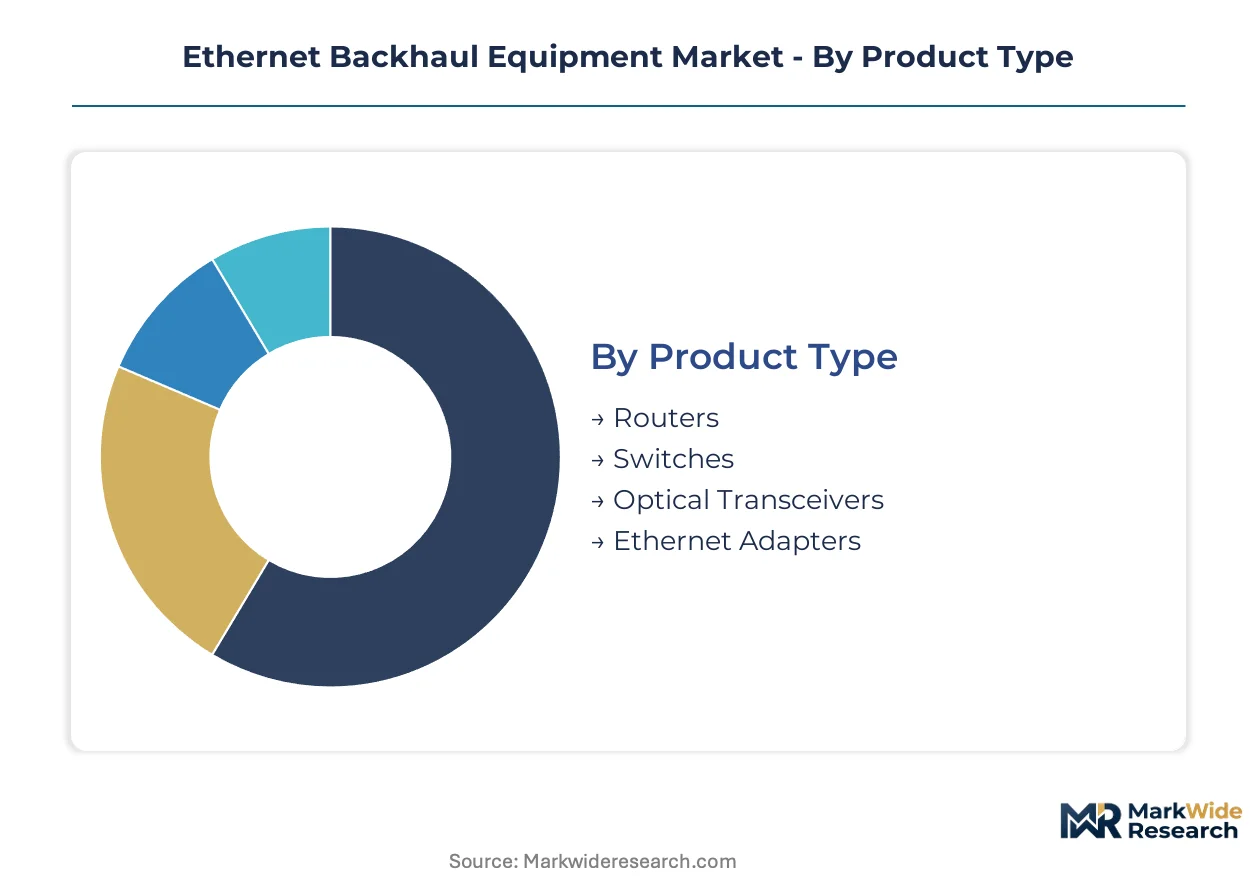
Ethernet backhaul equipment segmentation reveals how procurement patterns concentrate around specific performance tiers and deployment contexts. Equipment vendors calibrate product portfolios across these dimensions to capture operator refresh cycles and emerging application requirements.
Product Type:
Supply concentration in ASIC fabrication and optical component manufacturing shapes competitive positioning across hardware categories.
- Routers:High-capacity aggregation platforms integrate MPLS, Segment Routing, and timing synchronization for 5G midhaul. Indian telecom operators under BharatNet specifications are deploying these systems for rural fiber aggregation nodes.
- Switches:Layer 2 and Layer 3 switching platforms handle cell site traffic aggregation at access and aggregation tiers. Cost-per-port economics dominate procurement for small-cell densification projects in Germany and Japan where private 5G networks require simplified provisioning.
- Optical Transceivers:Pluggable coherent optics including 400G ZR and ZR+ variants are collapsing metro aggregation economics.
- Ethernet Adapters:NICs and smartNICs enable server connectivity for edge computing deployments.
Routers absorb the bulk of installed capacity; optical transceivers are expanding most quickly.
Technology:
Cost tier differentiation separates legacy infrastructure preservation from next-generation transport investments.
- Fast Ethernet:100 Mbps interfaces persist in legacy TDM replacement scenarios and cost-constrained rural deployments. India's gram panchayat connections under BharatNet specifications specify Fast Ethernet for basic village-level aggregation where fiber penetration remains incomplete.
- Gigabit Ethernet:1 Gbps technology constitutes the volume backbone for small-cell backhaul and enterprise edge connectivity. Telecom operators in South Korea deploy Gigabit Ethernet for urban microcell aggregation where density requirements outstrip fiber availability.
- 10 Gigabit Ethernet:10 Gbps interfaces serve macrocell aggregation and enterprise campus interconnect.
- 100 Gigabit Ethernet:100 Gbps platforms anchor core aggregation and cloud interconnect applications.
Gigabit Ethernet absorbs the bulk of installed capacity; 100 Gigabit Ethernet is climbing the fastest.
End User:
Customer type determines procurement sophistication, with tier-1 telecom operators driving specification standards that cascade to smaller deployers.
- Telecom Operators:Mobile network operators specify carrier-grade timing, redundancy, and five-nines availability. Reliance Jio and Bharti Airtel in India are driving massive fiber and microwave backhaul procurement for nationwide 5G coverage expansion.
- Internet Service Providers:Fixed-line broadband providers deploy Ethernet aggregation for residential and business service delivery. ISPs in the United States leverage FCC rural broadband funding to upgrade legacy copper infrastructure with fiber-to-the-premises backhaul.
- Enterprises:Manufacturing and logistics campuses deploy private 5G with dedicated Ethernet transport.
- Government Agencies:Public sector networks prioritize cybersecurity certification and domestic sourcing compliance.
Telecom operators absorb the bulk of installed capacity; enterprises are gaining share fastest.
Application:
Application context dictates latency budgets, synchronization requirements, and equipment lifecycle expectations.
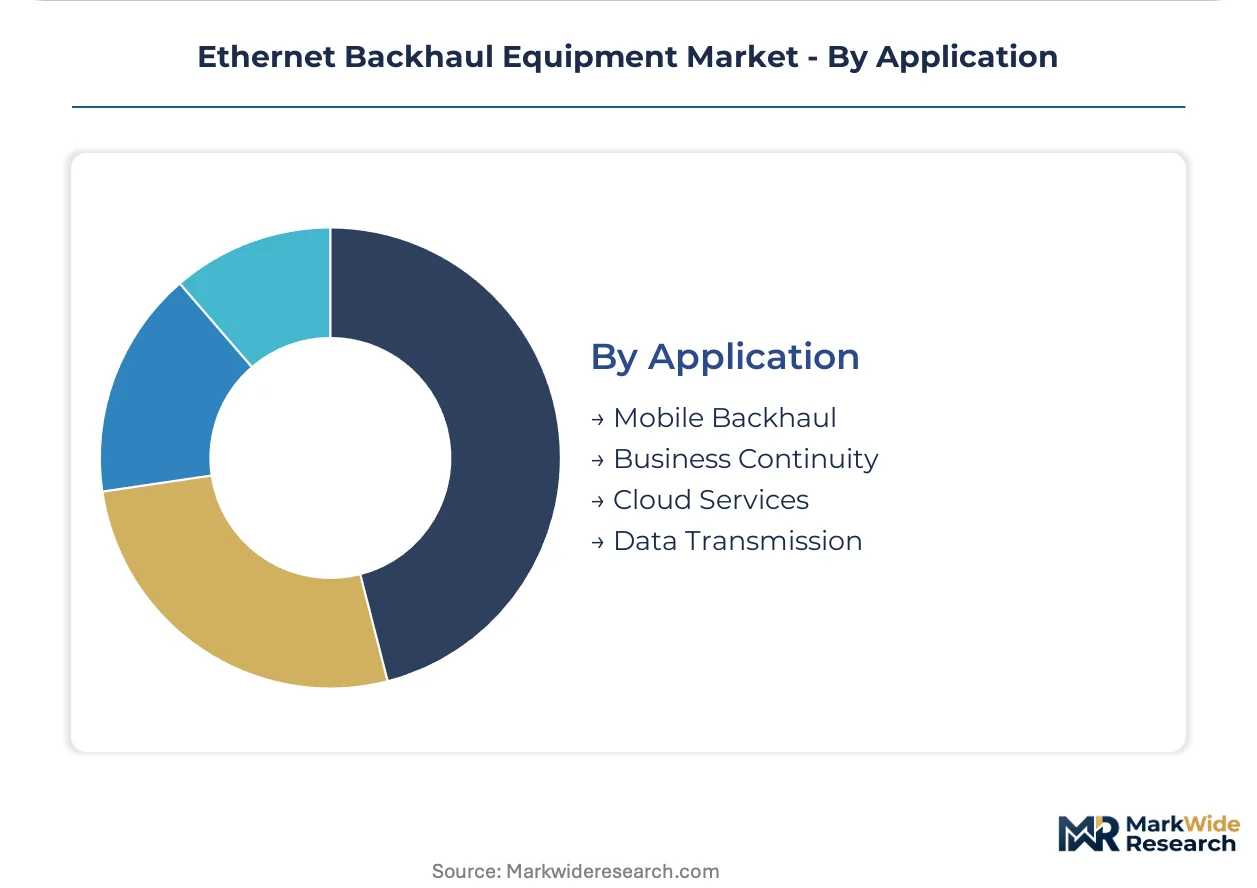
- Mobile Backhaul:Cell site-to-core transport requires sub-microsecond timing for 5G fronthaul and strict latency bounds for midhaul. South Korean operators deploy IEEE 1588v2-capable platforms nationwide to support advanced 5G services.
- Business Continuity:Disaster recovery and redundant path provisioning demand rapid failover capabilities. Financial institutions in Singapore specify dual-homed Ethernet backhaul for trading floor connectivity resilience.
- Cloud Services:Hyperscale data center interconnect drives coherent optical module adoption.
- Data Transmission:General-purpose enterprise and carrier data transport applications prioritize cost-optimized port density.
Mobile backhaul absorbs the bulk of installed capacity; cloud services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of optical transceiver components and ASIC silicon, while India and the United States drive equipment consumption through 5G deployment mandates. This production-consumption asymmetry shapes procurement timelines and compliance requirements across major demand centers.
United States
Verizon and AT&T are accelerating 100G router deployments for midhaul aggregation in urban 5G networks. The FCC enforces supply chain security documentation for equipment receiving federal rural broadband funding. Dallas-Fort Worth and Seattle host major cloud interconnect facilities where 400G ZR optics are displacing legacy coherent modules.
China
MIIT mandates GB standards compliance and domestic encryption certification for 5G transport equipment deployed nationwide. Huawei Technologies and ZTE anchor integrated microwave and fiber backhaul portfolios for domestic carrier tenders. Shenzhen and Beijing concentrate R&D facilities for 400G optical module development serving both domestic and export markets.
India
Reliance Jio and Bharti Airtel are driving massive fiber and microwave backhaul procurement for nationwide 5G coverage under TRAI spectrum allocation rules. The BharatNet rural broadband initiative mandates Ethernet aggregation equipment for 250,000 gram panchayat connections. Mumbai and Bangalore cluster telecom equipment integration facilities supporting both public and private network deployments.
Germany
Deutsche Telekom and Vodafone specify carrier-grade timing synchronization for 5G fronthaul under BNetzA spectrum license conditions. The EU AI Act imposes algorithmic transparency requirements on automated network management systems in backhaul networks. Munich and Stuttgart host manufacturing campuses deploying private 5G with dedicated Ethernet transport for ultra-reliable low-latency communication.
Japan
NTT Docomo and KDDI deploy IEEE 1588v2-capable platforms nationwide to support advanced 5G services under MIC spectrum policy. METI promotes open RAN interoperability standards that reshape equipment procurement criteria for domestic carriers. Tokyo and Osaka concentrate edge computing facilities where Segment Routing IPv6 convergence enables simplified provisioning for multi-access edge computing sites.
Ethernet Backhaul Equipment Market Competitive Landscape
Top-tier vendors anchor integrated platform supply, while specialized optical component suppliers occupy niche positions in pluggable coherent optics. The market structures around three tiers: full-stack telecom infrastructure providers, disaggregated routing specialists, and optical component pure-plays. Strategic archetypes include timing-synchronization specialists, silicon-integrated platform vendors, and open RAN transport disaggregators. Competitive moves concentrate on ASIC silicon sourcing security and multi-vendor interoperability certification.
Among Asian infrastructure providers, Huawei Technologies and ZTE occupy positions exemplifying integrated microwave and fiber portfolio breadth. Cisco Systems represents the enterprise and service provider edge router segment, leveraging silicon development programs for high-density aggregation nodes. These three companies anchor distinct competitive vectors—integrated telecom infrastructure, disaggregated enterprise routing, and optical transport specialization—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Huawei Technologies |
| Ericsson |
| NEC Corporation |
| Cisco Systems |
| Nokia |
| Juniper Networks |
| Ceragon Networks |
| ZTE |
| ADVA Optical Networking |
| Others |
Supply & Pricing Matrix
China's MIIT domestic encryption mandates gate qualified supply for 5G transport equipment, restricting premium-tier pricing access to vendors with GB standards certification while forcing non-compliant suppliers toward discounted secondary markets.
Pricing Analysis
Cost-down pressure on 100G aggregation nodes accelerates because coherent optical module commoditization collapses metro economics. Equipment procurement operates on three-tier pricing structure across premium, standard, and economy levels, with IEEE 1588v2 timing certification and ASIC silicon sourcing security as primary price differentiation drivers. Pricing pressure stems from BharatNet cost-per-bit specifications in India. Rural gram panchayat deployments exhibit highest price sensitivity; hyperscale cloud interconnect buyers prioritize performance over unit cost.
Supply Chain Analysis
Refurbishment flows for legacy TDM-to-Ethernet migration equipment create secondary supply channels extending asset lifecycles. Manufacturing concentrates in China, Taiwan, and South Korea, with advanced 7nm and 5nm router ASIC fabrication captive to Taiwan-based foundry capacity. Optical transceiver production draws from gallium arsenide and indium phosphide substrate supply anchored in Chinese and Japanese chemical processing. Single-source vulnerability in coherent DSP silicon poses structural risk. Distribution runs through carrier-direct procurement teams and systems integrators serving BharatNet and FCC rural broadband programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FCC supply chain security rules and MIIT encryption mandates erect barrier-to-entry moats favoring vendors with documented component provenance and domestic certification investment.
For Market Incumbents: Deploy timing synchronization IP as a defensive moat against open RAN disaggregation threats. Incumbents should deepen captive supply of 400G ZR optical modules to secure ASIC silicon allocation priority. Carrier-direct relationships in India and Germany provide channel control leverage against emerging transport disaggregators. For New Entrants and Emerging Players: Enter via private 5G enterprise networks in Japan and Germany where timing expertise scarcity creates penetrable whitespace. Manufacturing campus deployments offer lowest certification friction compared to carrier-grade public networks. AIOps platform bundling with Ethernet hardware provides differentiated go-to-market positioning against router incumbents. For Investors and Strategic Acquirers: O-RAN WG4 interoperability certification completion is the leading indicator that transport disaggregators have cleared qualification barriers for tier-1 carrier tenders. Long-term viability centers on vendors bridging open RAN specifications with proprietary timing performance. Acquisition targets should exhibit coherent optics integration capability and established relationships with Taiwan-based foundry capacity. Monitor IEEE 1588v2 deployment engineer availability as talent scarcity signal.| Strategic Initiative | Industry Significance |
|---|---|
| ASIC Silicon Sourcing Security Program | Taiwan foundry allocation agreements secure 7nm router chip supply for Indian 5G deployments. |
| Open RAN Transport Certification | O-RAN WG4 conformance testing unlocks Deutsche Telekom and Vodafone procurement eligibility. |
| Coherent Optics Vertical Integration | In-house 400G ZR module production collapses cost-per-bit for cloud interconnect applications. |
| Timing Synchronization IP Development | Sub-nanosecond IEEE 1588v2 expertise commands premium pricing in South Korean fronthaul tenders. |
| AIOps Platform Integration | EU AI Act algorithmic transparency compliance creates explainable fault prediction demand in German networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Ethernet backhaul equipment analysis. Primary interviews with carrier transport planners, optical component procurement leads, and network timing engineers combined with TRAI spectrum allocation documents, FCC equipment authorization databases, and MIIT GB standards publications. Bottom-up equipment shipment triangulation against top-down carrier capex analysis validated market sizing across router, switch, and optical transceiver categories.
Reconciliation of vendor shipment disclosures, carrier procurement announcements, and foundry capacity allocation reports shaped the analytical framework. Segmentation modeling spanned product type, technology tier, end-user category, and application context alongside regional regulatory cluster differentiation. CAGRs derived from equipment refresh cycle analysis and 5G deployment timeline correlation with BharatNet and FCC rural broadband funding disbursement patterns. Coherent optical module cost curves and ASIC node transition schedules provided industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control expansion for gallium arsenide substrates or foundry capacity disruption. Projections reflect assumptions regarding open RAN interoperability certification timelines and O-RAN Alliance specification maturation. Practitioners should monitor Taiwan semiconductor equipment licensing developments and India PLI scheme disbursement velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Network Fault Monitoring Tools Market
Network Technology
Router and Switch Market
Network Technology
Lit Fiber Market
Network Technology
Digital Repeater Market
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
Cloud Gateway Module Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
Germany Residential Gateway Market
Network Technology
Global Carrier Wi-Fi Equipment Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Internet Protocol Address Management (IPAM) Market
Network Technology
Passive Optical LAN (POL) Market
Network Technology
Virtual Router Market
Network Technology
Mobile Hotspot Router Market
Network Technology
Europe Structured Cabling Market