
 Industrial Ethernet Market | 2026-2036
Industrial Ethernet Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Ethernet Market Analysis
Copper cabling is expanding its presence in high-vibration factory floors as fiber-optic alternatives face cost barriers in legacy retrofit scenarios. Cisco Systems Inc. leverages its enterprise routing heritage to anchor industrial switching portfolios. Siemens AG sustains deep ties to German automation OEMs through native PROFINET integration. Rockwell Automation Inc. dominates North American automotive line deployments with EtherCAT-compatible programmable controllers.
Industrial Ethernet denotes hardened network infrastructure built to IEC 61000 electromagnetic immunity standards, operating across -40°C to +75°C temperature ranges while delivering sub-millisecond deterministic latency for motion control and safety systems. Switches command the largest product revenue pool due to port-density requirements in converged IT/OT architectures. TSN technology leads growth trajectory as IEEE 802.1 time-synchronization protocols displace proprietary fieldbus layers in precision manufacturing.
IEC 62443 cybersecurity standards, EU Cyber Resilience Act device certification, and FCC Part 15 emissions rules collectively shape hardware design cycles and market access timelines for connected industrial equipment. IEEE 802.1 TSN working groups and ODVA conformance testing further constrain interoperability claims among vendors. Stakeholders must weigh proprietary protocol loyalty against TSN migration costs as end-users demand single-cable consolidation of control, safety, and diagnostic traffic.
Market Dynamics
TSN protocol migration is compressing proprietary fieldbus timelines as automotive OEMs demand single-cable architectures for motion control, safety, and diagnostic convergence. This technology shift is forcing incumbent vendors to recertify hardware stacks while opening sockets for new entrants.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory device certification for connected industrial equipment is accelerating hardware refresh cycles across European manufacturing bases.
- Automotive assembly automation:Precision manufacturing lines in Germany's Ruhr corridor are deploying TSN-enabled networks for sub-millisecond deterministic control.
- IEEE 802.1 time-synchronization:Open standards are displacing vendor-locked fieldbus layers in converged IT/OT architectures.
Market Restraints
- Copper commodity volatility:Shielded twisted-pair cabling remains cost-advantaged for legacy retrofits but faces input price swings affecting project margins.
- German automation OEM concentration:Deep protocol loyalty among incumbent system integrators creates switching friction for alternative suppliers.
- Fiber-optic cost barriers:Glass fiber deployment in high-vibration environments requires specialized termination labor and protective conduit.
Strategic Opportunities
- Indian PLI scheme for manufacturing:Production-linked incentives for electronics and automotive sectors are creating greenfield TSN deployment opportunities.
- Edge-to-cloud convergence:Time-sensitive networking combined with OPC UA pub-sub is enabling unified data models for predictive maintenance.
- Japan METI digital transformation:Smart factory subsidies are accelerating EtherCAT and PROFINET adoption in precision machinery sectors.
Industry Challenges
- IEC 62443 certification timelines:Multi-stage security assessments for industrial components are extending product launch windows by 8-14 months.
- OT-IT skill convergence:Network engineering teams lack cross-training in deterministic protocols and enterprise cybersecurity frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Ethernet Market |
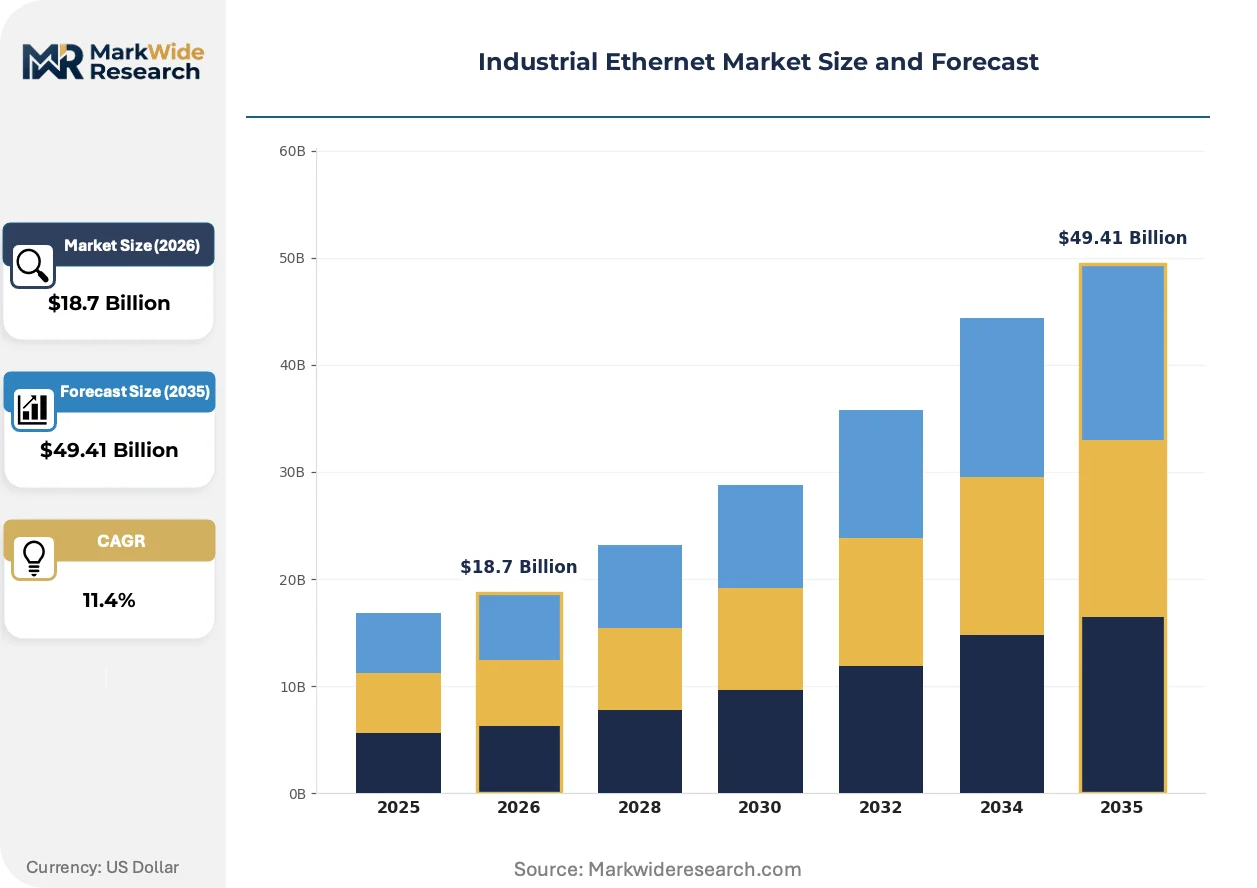
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Gateways, Cables Technology: Ethernet/IP, PROFINET, EtherCAT, TSN End User: Manufacturing, Oil & Gas, Automotive, Energy Deployment: On-premise, Cloud, Hybrid, Remote |
| Companies Covered | Cisco Systems Inc., Siemens AG, Rockwell Automation Inc., Schneider Electric SE, Belden Inc., ABB Ltd., Moxa Inc., OMRON Corp., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Ethernet Market Emerging Trajectories
Deterministic networking protocols are rewriting competitive boundaries as hardware vendors race to unify control-plane and data-plane silicon. This convergence is compressing proprietary moats while elevating certification and interoperability testing as strategic differentiators.
Time-Sensitive Networking is expanding into precision manufacturing environments through IEEE 802.1Qbv time-aware shapers and 802.1AS clock synchronization. Automotive OEMs in Stuttgart and Wolfsburg are piloting TSN backbones for powertrain assembly lines. This expansion is collapsing the historical separation between machine control traffic and enterprise data flows onto shared Ethernet infrastructure.
The EU Cyber Resilience Act is mandating vulnerability disclosure and automatic update capabilities for all network-connected industrial devices placed on the European market. Hardware manufacturers must redesign firmware architectures to support over-the-air patching without disrupting deterministic cycle times. Switch vendors serving German automotive and French aerospace end-users are prioritizing secure boot and hardware root-of-trust implementations.
Buying committees are consolidating vendor relationships around single-source TSN stack providers capable of certifying end-to-end latency guarantees. System integrators in Michigan and Bavaria are replacing multi-vendor fieldbus patchworks with unified Cisco or Siemens switching fabrics. This concentration is marginalizing specialist protocol gateway suppliers who cannot demonstrate IEEE 802.1 conformance across temperature-hardened product lines.
Industrial Ethernet Market Segmentation
Industrial Ethernet segmentation reveals how capital allocation, protocol migration, and deployment complexity fragment purchasing decisions across hardened infrastructure buyers. Understanding these divides exposes where vendor consolidation and specialist survival intersect.
Product Type:
Switches command the steepest upfront capital outlays due to port-density requirements and temperature-hardened component sourcing.
- Switches:Multi-port devices built to IEC 61000 electromagnetic immunity standards with -40°C to +75°C operating ranges. German automotive assembly plants in Stuttgart and Wolfsburg are absorbing the bulk of managed TSN-enabled switching capacity to collapse control, safety, and diagnostic traffic onto single-cable architectures.
- Routers:Layer-3 devices bridging deterministic OT subnets with enterprise IT backbones. Demand concentrates in converged IT/OT deployments where Cisco's enterprise routing heritage anchors industrial switching portfolios.
- Gateways:Protocol translation hardware linking legacy fieldbus segments to Ethernet infrastructures. Oil & Gas operators in the US Permian Basin deploy these for brownfield modernization without ripping and replacing installed sensor networks.
- Cables:Shielded twisted-pair copper and fiber-optic transmission media. Copper dominates legacy retrofit scenarios where fiber termination labor and protective conduit costs prove prohibitive.
Switches absorb the bulk of installed capacity; cables are expanding most quickly as TSN single-cable architectures displace multi-layer fieldbus deployments.
Technology:
Protocol selection dictates recurring engineering costs through certification cycles, interoperability testing, and vendor lock-in exposure.
- Ethernet/IP:ODVA-managed open standard natively integrated with Rockwell Automation controller portfolios. North American automotive lines in Michigan favor this stack for EtherCAT-compatible programmable controller deployments.
- PROFINET:Siemens-backed deterministic protocol with deep German automation OEM integration. The Ruhr industrial corridor sustains concentrated demand for native PROFINET switching fabrics.
- EtherCAT:Beckhoff-origin high-speed fieldbus with sub-microsecond cycle times. Japan METI smart factory subsidies are accelerating adoption in precision machinery sectors.
- TSN:IEEE 802.1 time-synchronization protocols displacing proprietary layers. IEEE 802.1Qbv time-aware shapers and 802.1AS clock synchronization are gaining share fastest as automotive OEMs pilot unified backbones for powertrain assembly.
PROFINET and Ethernet/IP retain the largest installed bases; TSN shows the steepest expansion trajectory as IEEE 802.1 conformance testing becomes a procurement gate.
End User:
Vertical application requirements split procurement between safety-critical certification burdens and throughput-maximizing performance specifications.
- Manufacturing:Discrete and process automation environments requiring deterministic latency for motion control. EU Cyber Resilience Act device certification is accelerating hardware refresh cycles across European manufacturing bases.
- Oil & Gas:Hazardous-location deployments demanding explosion-proof enclosures and extended temperature ratings. Remote monitoring of upstream assets drives hybrid deployment architectures.
- Automotive:Precision assembly lines with sub-millisecond synchronization requirements for robotic welding and paint systems. TSN-enabled networks are collapsing historical traffic separation in Stuttgart and Wolfsburg pilot programs.
- Energy:Grid modernization and renewable integration projects requiring IEC 62443 cybersecurity compliance. Multi-stage security assessments are extending product launch windows by 8-14 months for this risk-averse buyer segment.
Manufacturing commands the largest revenue pool; automotive is climbing the fastest as single-cable TSN architectures rewrite line deployment economics.
Deployment:
Infrastructure location determines capital split between edge hardware, connectivity services, and ongoing operational technology staffing.
- On-premise:Fully captive switching and routing infrastructure with direct OT team management. German automation OEM concentration creates switching friction for alternative suppliers in this conservative deployment mode.
- Cloud:Managed network services with centralized policy orchestration. Edge-to-cloud convergence through OPC UA pub-sub is enabling unified data models for predictive maintenance in this segment.
- Hybrid:Split architectures retaining deterministic control on-premise while pushing analytics to cloud substrates. Indian PLI scheme production-linked incentives are creating greenfield hybrid deployment opportunities in electronics and automotive sectors.
- Remote:Satellite-connected or cellular-backhauled infrastructure for geographically dispersed assets. Fiber-optic cost barriers in high-vibration environments favor copper-based remote terminal units in legacy retrofit scenarios.
On-premise retains dominant share; hybrid is gaining share fastest as end-users balance deterministic control requirements against cloud analytics economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive assembly plants absorb the steepest share of TSN-enabled switching capacity, while US and Chinese manufacturing bases are accelerating hardware refresh cycles under divergent regulatory pressures. National industrial policies and certification timelines are fragmenting procurement patterns across major economies.
Germany
Stuttgart and Wolfsburg automotive OEMs pilot unified TSN backbones for powertrain assembly, collapsing historical traffic separation onto single-cable architectures. The EU Cyber Resilience Act mandates vulnerability disclosure and automatic update capabilities for all network-connected industrial devices placed on the European market. The Ruhr industrial corridor sustains concentrated demand for native PROFINET switching fabrics among deep-rooted automation OEMs.
United States
Michigan automotive lines favor EtherCAT-compatible programmable controller deployments for precision manufacturing synchronization. FCC Part 15 emissions rules constrain hardware design cycles and market access timelines for connected industrial equipment. The Permian Basin drives hybrid deployment architectures where oil and gas operators deploy protocol translation hardware for brownfield modernization without replacing installed sensor networks.
China
Electronics and automotive sectors are creating greenfield TSN deployment opportunities through production-linked incentive structures. GB standards and MIIT industrial policy frameworks shape local certification requirements for hardened network infrastructure. Yangtze River Delta manufacturing clusters are absorbing managed switching capacity for converged IT/OT architectures in smart factory deployments.
Japan
Precision machinery sectors are accelerating EtherCAT and PROFINET adoption through targeted subsidy programs. METI digital transformation initiatives fund smart factory retrofits requiring deterministic latency for motion control applications. The Nagoya industrial corridor anchors concentrated demand for high-speed fieldbus with sub-microsecond cycle times in automotive component manufacturing.
India
Electronics and automotive production-linked incentives are creating greenfield deployment opportunities for converged network architectures. The PLI scheme is attracting contract manufacturers requiring hardened infrastructure built to IEC 61000 electromagnetic immunity standards. Karnataka and Tamil Nadu industrial corridors are absorbing temperature-hardened switching capacity for new electronics assembly facilities.
Industrial Ethernet Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with incumbent automation OEMs commanding loyalty through protocol integration while open-standard challengers erode proprietary moats. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with native protocol stacks, enterprise networking incumbents extending into hardened infrastructure, and specialist connectivity vendors focused on temperature-hardened component sourcing. Competitive intensity centers on IEEE 802.1 conformance certification and end-to-end latency guarantee capabilities rather than pure price positioning.
Within the diversified industrial tier, Siemens AG and Rockwell Automation Inc. exemplify archetypes built on deep automation OEM relationships and native fieldbus integration. Cisco Systems Inc. occupies a distinct position bridging enterprise routing heritage with industrial switching portfolios. These three anchors demonstrate how competitive positioning increasingly depends on certification breadth across converged IT/OT architectures rather than single-protocol dominance.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Siemens AG |
| Rockwell Automation Inc. |
| Schneider Electric SE |
| Belden Inc. |
| ABB Ltd. |
| Moxa Inc. |
| OMRON Corp. |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between IEC 62443-compliant hardware and uncertified commodity switches splits both pricing power and sourcing strategies across vendor tiers. Premium-grade TSN-enabled switches command substantial markups through guaranteed latency performance, while commodity copper cabling draws from spot-market raw material exposure that compresses margins on legacy retrofit projects.
Pricing Analysis
High-volume switch deployments run on thinner margins than low-volume router configurations due to port-density standardization. Three-tier pricing structure across premium TSN-certified, standard managed, and economy unmanaged levels tracks directly to IEC 61000 immunity grade and temperature-hardening specifications. Cost compression in copper cabling is intensifying because shielded twisted-pair commodity volatility feeds directly into project bids. Small system integrators in India's PLI corridor show the sharpest price sensitivity, whereas German automotive OEMs prioritize deterministic performance guarantees over unit economics.
Supply Chain Analysis
Freight cost escalation from Asia-Pacific component hubs to European assembly plants is reshaping regional inventory positioning for temperature-hardened semiconductors. Manufacturing concentrates in China, Taiwan, and Germany for switching silicon, magnetic components, and precision mechanical housings. Production draws from copper cathode, FR-4 substrate, and FPGA chip supply streams. Single-source vulnerability in IEEE 802.1AS clock synchronization chipsets creates bottleneck exposure for TSN-enabled product lines. Distribution runs through authorized industrial distributors with field application engineering support rather than commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is accelerating into a vertical-integration race as players pursue captive control over IEEE 802.1 conformance testing capabilities to compress certification timelines and lock in procurement relationships.
For Market Incumbents: Anchor switching portfolio loyalty through native protocol stack integration with German automation OEMs while building in-house TSN certification labs to bypass third-party testing delays. Threat from open-standard challengers eroding proprietary PROFINET and EtherCAT moats demands accelerated R&D in unified silicon converging control-plane and data-plane functions. Capacity addition in India's Karnataka corridor captures PLI-driven greenfield demand before local competitors establish field service networks. For New Entrants and Emerging Players: Mid-sized US oil and gas operators deploying hybrid cloud-edge architectures represent the most penetrable buyer archetype underserved by incumbent fieldbus specialists. White-space concentrates in protocol translation hardware for brownfield Permian Basin modernization and managed TSN services for electronics contract manufacturers in Tamil Nadu. Go-to-market positioning through OPC UA pub-sub integration partnerships bypasses direct competition with Cisco and Siemens switching fabric dominance. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified industrial conglomerates seeking IEEE 802.1 conformance capabilities and temperature-hardened product line extensions. Long-term viability hinges on certification breadth across converged IT/OT architectures rather than single-protocol specialization. Watch for inflection when Indian PLI scheme disbursement volumes cross thresholds triggering accelerated TSN deployment in electronics assembly facilities.| Strategic Initiative | Industry Significance |
|---|---|
| TSN Certification Lab Investment | In-house IEEE 802.1 conformance testing compresses product launch windows by 8-14 months. |
| Native Protocol Stack Integration | Deep PROFINET and EtherCAT embedding locks in German Ruhr corridor OEM procurement relationships. |
| Edge-to-Cloud Platform Partnership | OPC UA pub-sub integration enables predictive maintenance revenue streams beyond hardware sales. |
| Temperature-Hardening Capacity Expansion | -40°C to +75°C rated production lines capture automotive and energy sector safety-critical demand. |
| Cybersecurity Firmware Architecture Redesign | Secure boot and hardware root-of-trust implementations satisfy EU Cyber Resilience Act mandatory requirements. |
Methodological Framework
Document review covered IEEE 802.1 standards documentation, IEC 62443 certification registries, and EU Cyber Resilience Act implementation guidance, complemented by interviews with plant engineers at German automotive assembly facilities, procurement leads at US oil and gas operators, and field application engineers at industrial distributors. Secondary validation drew from SEC filings of listed automation vendors, customs data on copper and fiber-optic cable trade flows, and ODVA conformance testing records. Bottom-up unit economics triangulated against top-down market sizing across switching, routing, gateway, and cable product categories.
Cross-referencing historical shipment patterns against expert panel input on TSN migration timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, protocol technology, end-user vertical, and deployment architecture, with regional regulatory cluster as an additional industrial Ethernet-specific dimension. CAGRs were derived through iterative convergence of demand-side adoption curves and supply-side capacity constraints, incorporating automotive OEM TSN pilot program disclosures and METI smart factory subsidy disbursement trajectories as industry-specific forecast inputs.
Revisions become necessary when IEC 62443 certification timeline extensions, copper commodity price spikes, or geopolitical restrictions on semiconductor fabrication equipment materialize beyond baseline assumptions. Forecasts reflect documented adoption drivers and regulatory mandates rather than speculative technology disruptions. Stakeholders should weight assumptions against their own operating context in deterministic control and enterprise cybersecurity convergence planning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
DNS DHCP and IPAM Market
Network Technology
RTP Market
Network Technology
Dark Fiber Market
Network Technology
Enterprise Network Equipment Market
Network Technology
Protocol Analyzer Market
Network Technology
United States and European Fiber Optic Cable Market
Network Technology
Global Intelligent Network Market
Network Technology
Network Telemetry Market
Network Technology
BYOD Market
Network Technology
Optical Networking Market
Network Technology
Global Network Management Market
Network Technology
MENA Wireless Routers Market
Network Technology
Global Active Network Management Market
Network Technology
Indoor Distributed Antenna Systems Market
Network Technology
North America Network Management Solutions Market
Network Technology
Global Wireless Router Market