
 Dark Fiber Market | 2026-2036
Dark Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Dark Fiber Market Intelligence
The unbundling of raw fiber capacity from managed network services is repositioning buyer choice toward greater network control and scalability. Zayo Group Holdings, Inc. specializes in providing extensive fiber infrastructure to large enterprises and wholesale carriers. Lumen Technologies, Inc. leverages its vast continental long-haul network to offer a range of dark and lit fiber solutions across diverse industries. Crown Castle Fiber LLC focuses on dense metropolitan and small cell connectivity, anchoring its position in key US urban corridors.
Dark fiber refers to unused optical fiber infrastructure, typically single-mode fiber pairs, laid but not yet activated by carrier equipment. It provides organizations full control over their network architecture, allowing them to deploy their own transmission technology. While long-haul network applications form a mature base, metropolitan network deployments show significant growth. Telecom operators and data center providers are the dominant end users, leasing fiber for cloud interconnects and 5G backhaul.
Regulatory frameworks from bodies like the US Federal Communications Commission (FCC) and European Union directives on telecommunications influence right-of-way access and wholesale competition. Standards from the International Telecommunication Union (ITU) govern the technical specifications for optical fiber, ensuring interoperability. Stakeholder decisions will hinge on balancing the capital expenditure of new fiber builds against the operational flexibility gained from leasing existing dark fiber assets.
Market Dynamics
The central dynamic shaping the dark fiber market is the unbundling of raw network capacity from managed services. This shift grants enterprises and carriers unprecedented control over their network architecture, directly fueling demand for latent fiber assets to support custom deployments.
Growth Catalysts
- 5G Infrastructure Rollout:The deployment of 5G networks requires a dense, high-capacity fiber backbone to connect thousands of new small cells and macro towers, creating substantial demand for dark fiber pairs for fronthaul and backhaul applications.
- Hyperscale Data Center Expansion:Proliferation of data centers by cloud providers, particularly in major clusters like Frankfurt, drives the need for high-bandwidth, low-latency interconnects between facilities, which is most efficiently met by leasing dark fiber.
- Financial Services Demand:Key financial hubs in Asia and other regions require dedicated, ultra-low latency routes for algorithmic trading and secure data transmission, making dark fiber a preferred solution for maintaining a competitive edge.
Market Restraints
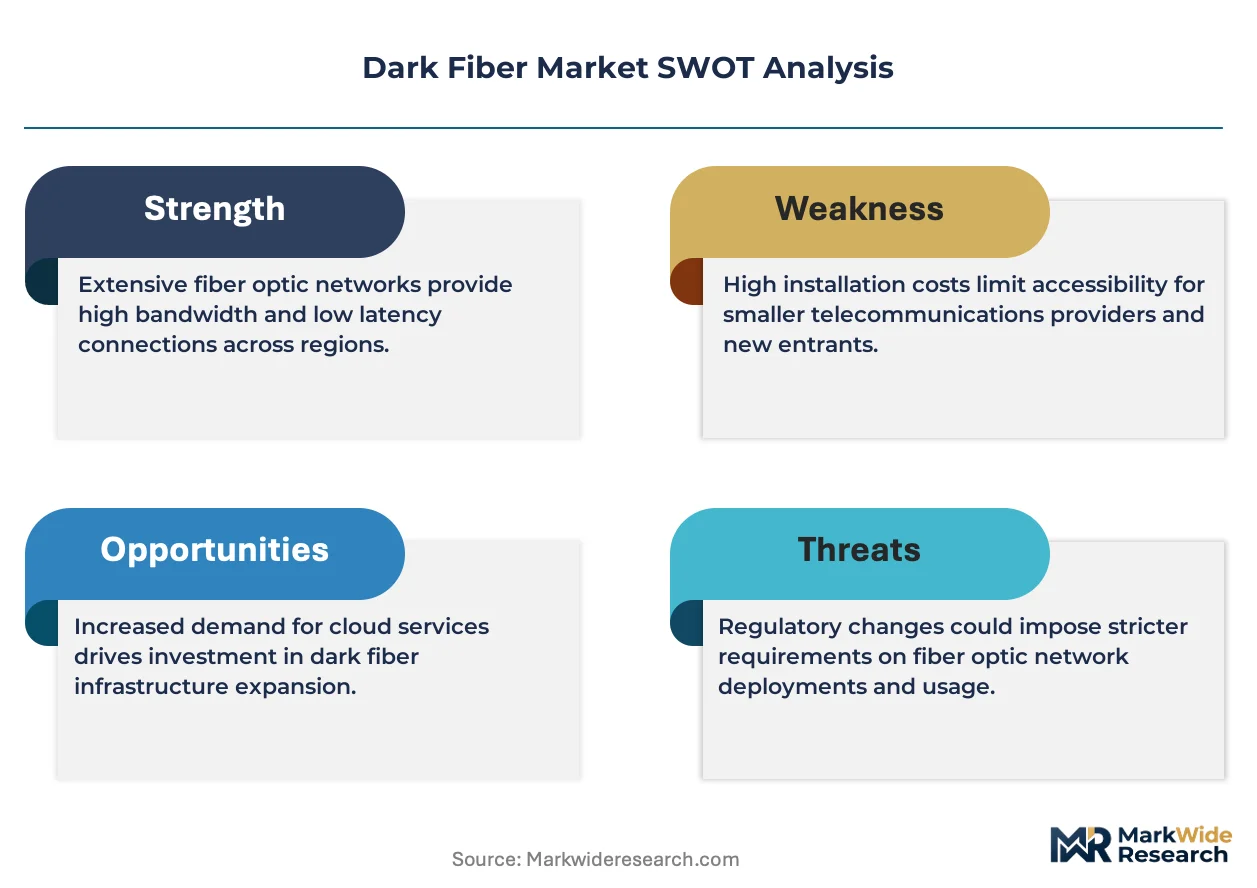
- High Capital Expenditure:The significant upfront investment required to lay new fiber optic cable, including costs for trenching and civil works, acts as a major barrier to entry for new providers and limits network expansion.
- Right-of-Way Complexities:Securing permits and navigating regulations from bodies like the US Federal Communications Commission (FCC) for access to public and private land can introduce significant delays and costs to new fiber construction projects.
- Limited Geographic Availability:While dense in urban cores, dark fiber infrastructure remains scarce in many suburban and rural areas, limiting options for organizations outside of major metropolitan corridors and concentrating supply with incumbents.
Strategic Opportunities
- Edge Computing Networks:The rise of edge computing creates a need for new fiber routes to connect distributed compute nodes located closer to end-users, opening opportunities for providers to build out networks in previously underserved secondary markets.
- Quantum Network Infrastructure:Leasing dark fiber to support the development of Quantum Key Distribution (QKD) networks offers a new, high-value application targeting government, defense, and financial sectors that require provably secure communication channels.
- Monetizing Utility Corridors:Electric utilities and railway companies can lease excess dark fiber capacity running along their existing right-of-way, creating new revenue streams from an underutilized asset with minimal additional construction cost.
Industry Challenges
- Skilled Labor Shortages:A deficit of qualified technicians with expertise in optical fiber splicing, testing, and maintenance can create bottlenecks in deployment schedules and increase operational costs for network operators.
- Network Integration Hurdles:Organizations face significant technical challenges when integrating leased dark fiber with their existing network equipment and operational support systems, often requiring specialized engineering expertise.
- Interoperability Assurance:While ITU standards provide a baseline, ensuring seamless interoperability between different vendors' optical transmission equipment deployed over a dark fiber link remains a persistent operational concern for network managers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dark Fiber Market |
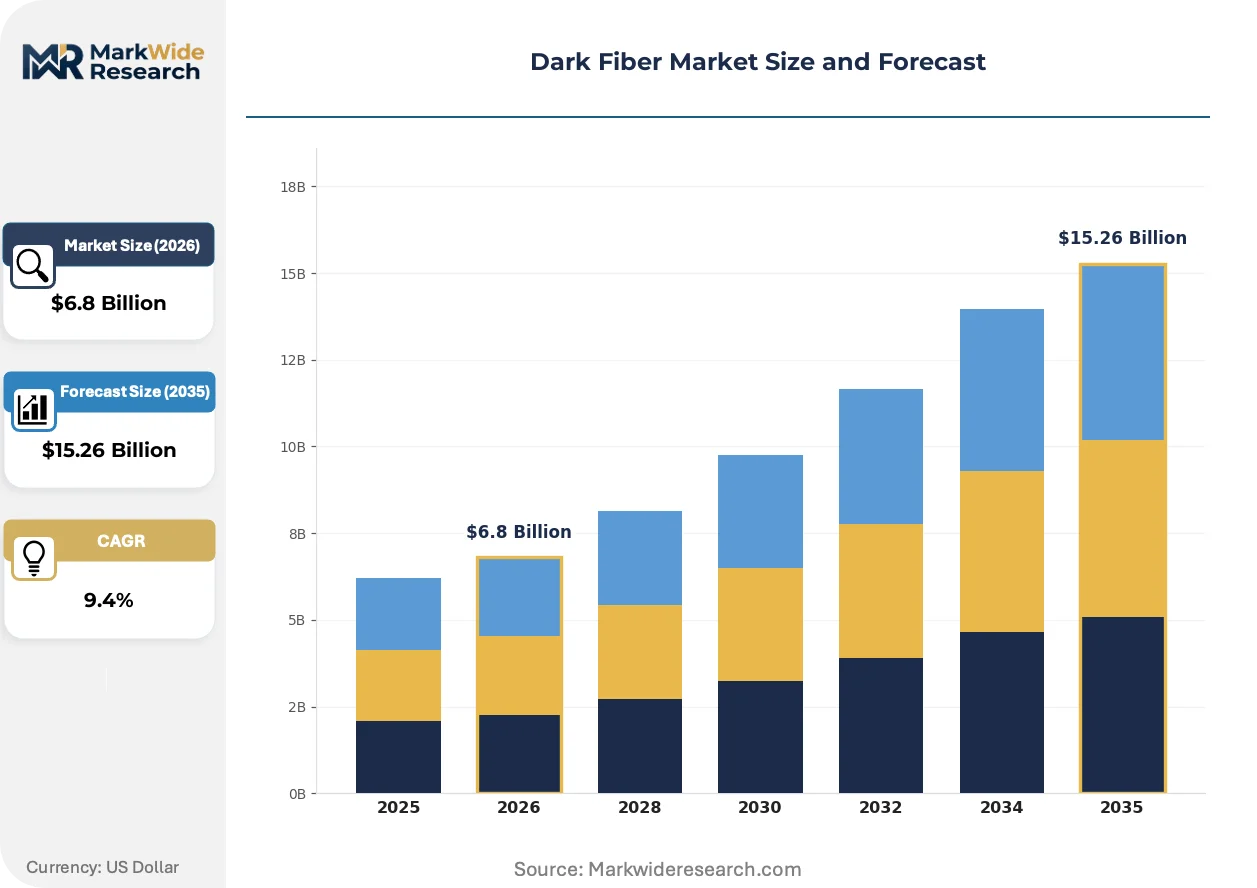
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unlit Fiber, Lit Fiber Services, Wavelength Services, Ethernet Services, MPLS Services End User: Telecom Operators, Data Center Providers, Internet Service Providers, Colocation Facilities Application: Long-Haul Networks, Metropolitan Networks, Enterprise Connectivity, Cloud Interconnects, Government Networks Deployment Model: Point-to-Point, Ring Network, Mesh Network, Passive Optical Network, Customized Architecture |
| Companies Covered | Zayo Group Holdings, Inc., Lumen Technologies, Inc., Crown Castle Fiber LLC, AT&T, Verizon Communications, Inc., FiberLight, LLC, Colt Technology Services, euNetworks Group Limited, Uniti Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dark Fiber Market Strategic Shifts & Innovations
The market is evolving from providing simple point-to-point connectivity toward enabling software-defined, highly customized network fabrics. This transformation is driven by technological advancements in fiber itself and new regulatory frameworks promoting open access to physical infrastructure.
Hollow-core fiber is an emerging technology that guides light through an air-filled channel, offering significantly lower latency than conventional solid-glass fiber. High-frequency trading firms and national research labs are among the earliest adopters, where nanoseconds of latency advantage are critical. This advanced physical medium is converging with sophisticated coherent optical transmission systems, creating specialized, ultra-high-performance network pathways for niche, latency-sensitive applications.
European Union directives promoting wholesale competition and open access to telecommunications infrastructure are a significant policy driver. These regulations compel incumbent carriers to offer access to their physical assets, including dark fiber ducts and strands, to alternative service providers. The impact is most visible in competitive data center hubs, where it fosters price competition and encourages the entry of new players focused on specialized connectivity services.
A notable behavioral shift involves enterprises moving from static, long-term capacity leases to more flexible consumption models for network infrastructure. This change challenges the traditional multi-year contract structure, prompting the emergence of platforms that facilitate shorter-term or on-demand acquisition of fiber routes. This trend is most prominent among large enterprises and content providers in North America seeking to align network expenditures more closely with fluctuating project demands and data traffic patterns.
Dark Fiber Market Segmentation
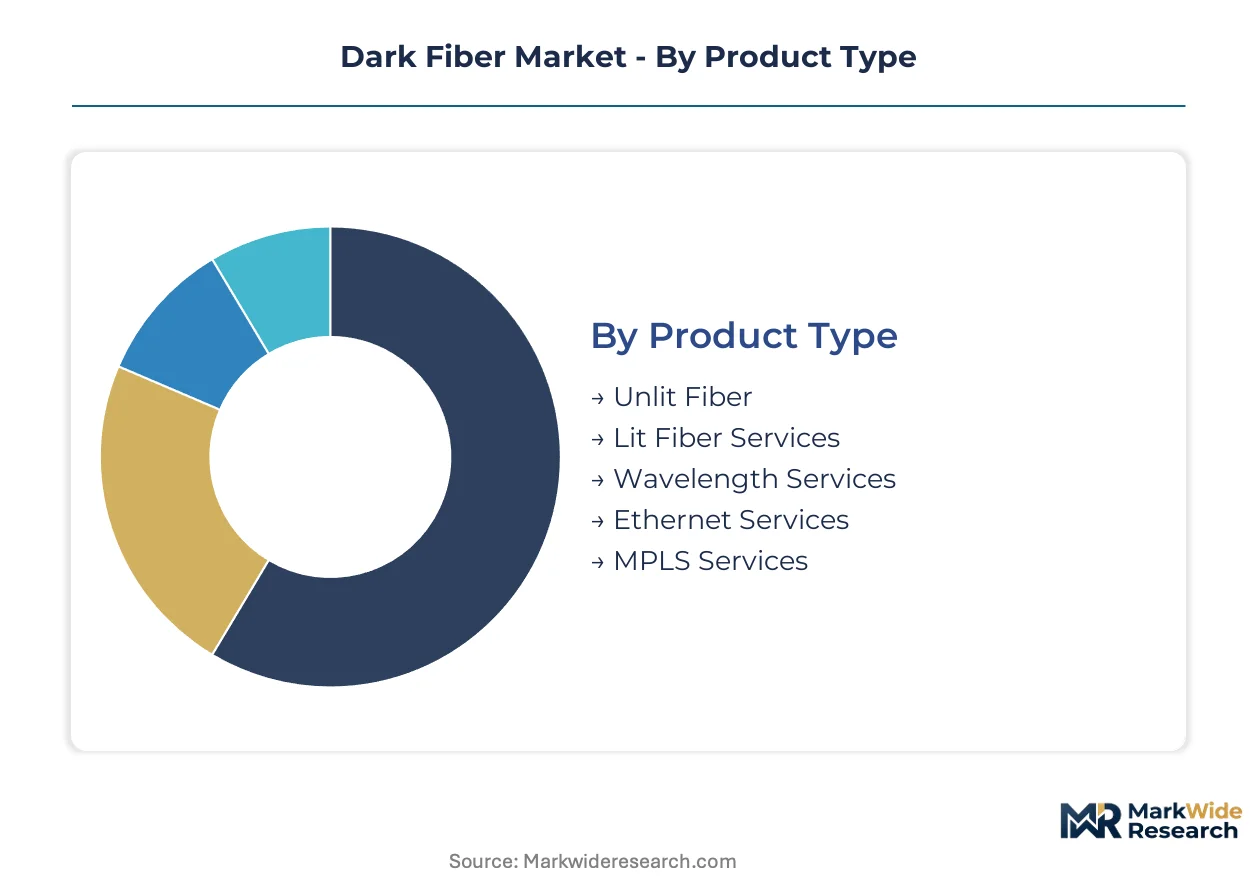
The dark fiber market categorizes its offerings to meet diverse enterprise and carrier requirements for network control and capacity. Segmentation highlights the specialized infrastructure and service models that enable high-bandwidth connectivity across various industries. Understanding these distinctions clarifies how different solutions address specific operational demands.
Product Type:
The range of product types reflects the technical specifications and level of network management provided to end-users. These offerings span from raw physical infrastructure to managed optical services, each serving distinct operational needs.
- Unlit Fiber:This foundational product provides raw, unactivated optical fiber strands, allowing customers complete autonomy over their network equipment and transmission protocols. Demand concentrates in data center clusters like Frankfurt, where hyperscalers require dedicated, low-latency interconnects for massive data volumes.
- Lit Fiber Services:These services offer activated fiber links with the provider's equipment already transmitting data, often used when customers prefer a managed solution without the capital expenditure of their own optics. Financial institutions in Asia frequently leverage lit fiber for secure, high-speed data exchange, prioritizing reliability and managed performance.
- Wavelength Services:Customers lease specific wavelengths over a provider's existing fiber, enabling high-capacity data transmission without managing the underlying optical layer.
- Ethernet Services:These provide high-speed, point-to-point or multipoint Ethernet connectivity over a fiber network, commonly used for enterprise data center interconnections.
- MPLS Services:Multi-Protocol Label Switching services offer advanced traffic engineering and VPN capabilities over a provider's network, optimizing data flow for complex enterprise architectures.
Mature deployment sits with Unlit Fiber. Newer deployment is concentrated in Lit Fiber Services.
End User:
The customer types acquiring dark fiber vary significantly in their network scale and operational requirements. Each end-user group leverages fiber infrastructure to support distinct business models and service offerings.
- Telecom Operators:These companies lease dark fiber to expand their backbone networks, support 5G infrastructure rollouts, and enhance backhaul capacity to cell towers. Their demand is driven by the need for dense, high-capacity fiber to connect new small cells and macro towers across urban and suburban areas.
- Data Center Providers:These entities utilize dark fiber for high-bandwidth, low-latency interconnects between their facilities and to cloud on-ramps, especially within major data center clusters. Proliferation of hyperscale data centers fuels their requirement for dedicated fiber links to handle massive inter-facility traffic.
- Internet Service Providers:ISPs procure dark fiber to extend their network reach, improve last-mile connectivity, and enhance peering capabilities with content providers.
- Colocation Facilities:These facilities lease dark fiber to offer enhanced connectivity options to their tenants, facilitating direct connections to carriers and cloud providers.
Data Center Providers represent the fastest-growing trajectory for dark fiber procurement.
Application:
The specific applications of dark fiber determine the required network topology, latency characteristics, and overall capacity. Each application addresses a distinct set of communication and data transport challenges.
- Metropolitan Networks:These applications focus on dense urban areas, supporting last-mile connectivity, intra-city data center links, and 5G small cell backhaul. The widespread rollout of 5G infrastructure necessitates robust metropolitan fiber deployments to ensure high-speed, low-latency services for urban populations.
- Cloud Interconnects:This application involves dedicated fiber links connecting enterprises and data centers directly to cloud service providers, bypassing the public internet for enhanced security and performance. Hyperscale data center expansion specifically drives demand for these high-bandwidth, low-latency connections to facilitate cloud adoption.
- Long-Haul Networks:These networks span significant geographical distances, forming the backbone for national and international data transmission.
- Enterprise Connectivity:Businesses lease dark fiber for secure, high-capacity links between their various offices, data centers, and remote facilities.
- Government Networks:Public sector entities utilize dark fiber for secure and resilient communication infrastructure, supporting critical services and defense applications.
Demand for dark fiber is heavily distributed across Metropolitan Networks and Cloud Interconnects.
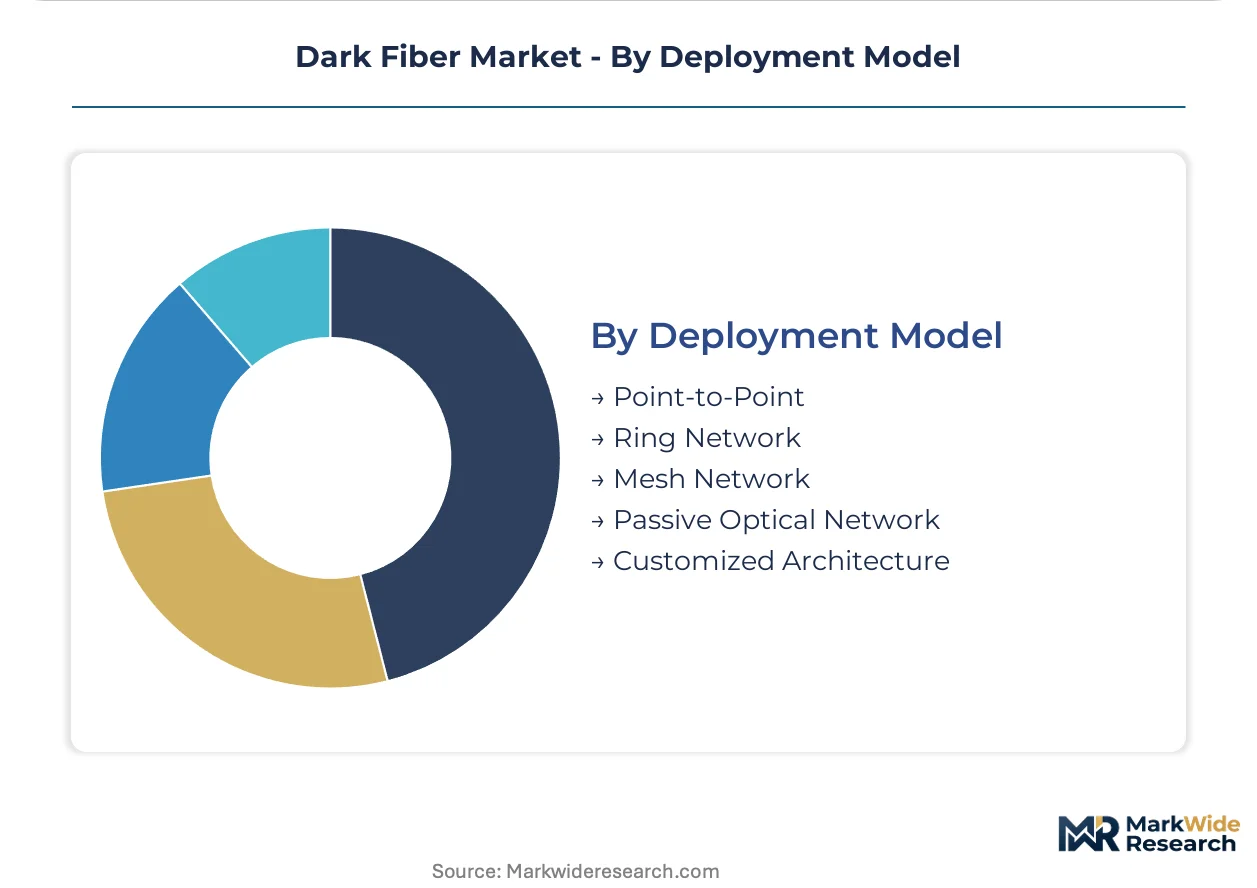
Deployment Model:
The deployment model for dark fiber dictates the network's physical layout, resilience, and scalability characteristics. Each configuration offers distinct advantages for different operational environments and performance requirements.
- Point-to-Point:This direct fiber connection between two specific locations offers simplicity and dedicated bandwidth, commonly used for high-capacity links between data centers or enterprise campuses. Organizations requiring guaranteed, low-latency routes for critical data transmission frequently opt for this straightforward and reliable model.
- Mesh Network:This highly resilient topology features multiple redundant paths between nodes, ensuring continuous service even if one link fails, making it ideal for mission-critical applications. Financial services firms in major hubs often deploy mesh networks to achieve ultra-low latency and fault tolerance for algorithmic trading operations.
- Ring Network:A closed loop of fiber connects multiple nodes, providing redundancy by allowing data to travel in both directions if a segment is cut.
- Passive Optical Network:PON architectures use unpowered optical splitters to serve multiple endpoints from a single fiber strand, efficient for last-mile residential or small business connectivity.
- Customized Architecture:This model involves designing bespoke fiber networks tailored to unique client requirements, integrating various topologies and technologies for specialized use cases.
Point-to-Point models prioritize simplicity, while Customized Architecture offers maximum flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The dark fiber market demonstrates a clear divide between robust consumption centers and regions requiring significant infrastructure build-out. Demand for high-capacity network solutions is heavily concentrated in major data center hubs and financial centers. This dynamic shapes investment priorities and regulatory approaches across different geographies.
United States
Demand in the United States is driven by hyperscale data center expansion and 5G infrastructure deployment. The US Federal Communications Commission (FCC) influences right-of-way access and wholesale competition for fiber. Major data center clusters in Northern Virginia and Silicon Valley show intense dark fiber procurement for cloud interconnects.
Germany
German dark fiber demand stems from its central European data center role and industrial digitalization initiatives. European Union directives on telecommunications foster open access to physical infrastructure, impacting pricing. Frankfurt, as a leading financial and data hub, experiences high demand for low-latency dark fiber links.
Japan
Japanese financial services firms require ultra-low latency dark fiber for algorithmic trading and secure data transmission. The Ministry of Internal Affairs and Communications (MIC) regulates telecommunications infrastructure and competition. Tokyo's financial district and major data center zones exhibit strong demand for dedicated fiber routes.
Singapore
Singapore's position as a regional data center and financial hub fuels its dark fiber market, supporting cloud interconnects. The Infocomm Media Development Authority (IMDA) promotes fiber infrastructure deployment and digital connectivity. Data center parks in Jurong and Tai Seng are critical nodes for high-bandwidth fiber backbone requirements.
Dark Fiber Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the dark fiber market, creating a varied competitive landscape. The market structure exhibits a tiered consolidation, with large incumbent carriers and dedicated fiber infrastructure providers occupying different segments. Strategic archetypes include national long-haul network operators, metropolitan fiber specialists, and those focused on specific industry verticals. Geographic expansion into underserved areas and strategic partnerships for last-mile access remain dominant competitive moves.
Scale-driven providers like AT&T and Lumen Technologies, Inc. leverage extensive existing network assets, offering diverse dark and lit fiber solutions across broad geographies. Zayo Group Holdings, Inc. represents a pure-play infrastructure specialist, focusing on dense fiber networks for large enterprises and wholesale carriers. These companies exemplify the market's segmentation, ranging from incumbent telecom operators with vast reach to specialized fiber infrastructure owners catering to specific high-bandwidth demands. Their strategies often involve balancing legacy network optimization with new fiber build-outs for emerging applications.
| Leading Market Players |
|---|
| Zayo Group Holdings, Inc. |
| Lumen Technologies, Inc. |
| Crown Castle Fiber LLC |
| AT&T |
| Verizon Communications, Inc. |
| FiberLight, LLC |
| Colt Technology Services |
| euNetworks Group Limited |
| Uniti Group Inc. |
Cost & Logistics Intelligence
The unbundling of raw fiber capacity from managed services reshapes cost economics for network operators and shifts supply concentration towards infrastructure owners. This market evolution allows enterprises greater control over their network architecture, impacting both capital and operational expenditures.
Pricing Analysis
Pricing pressure intensifies for unlit fiber due to increased competition from new infrastructure builds and open-access mandates. The dominant pricing model involves contract-based long-term leasing agreements, providing stability for both providers and customers. Price differentiation drivers include geographic availability, specific latency requirements for applications like algorithmic trading, and the count or type of fiber strands. Telecom operators and data center providers exhibit lower price sensitivity for mission-critical, high-bandwidth routes, while smaller enterprises prioritize cost-effectiveness for general connectivity.
Supply Chain Analysis
Optical fiber supply chains are anchored in key manufacturing regions such as the United States, Germany, and Japan, which produce specialized cables and components. Raw material dependencies include high-purity silica for fiber optics and heavy equipment for trenching and civil works. A significant supply chain risk stems from right-of-way complexities and a persistent shortage of skilled technicians for fiber deployment and maintenance. Distribution runs through direct leasing from large infrastructure owners and wholesale carriers, who manage the physical assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dark fiber market is undergoing a technology-transition phase, as unbundled fiber capacity replaces traditional managed network services. This shift empowers end-users with unprecedented control over their network infrastructure.
For Market Incumbents:To counter emerging specialized connectivity providers, incumbents must invest in new fiber builds within underserved secondary markets. Acquiring metropolitan fiber specialists can also bolster their dense urban network footprint. Leveraging existing right-of-way assets and established regulatory relationships provides a significant competitive advantage. Focus on operational efficiency in large-scale network management remains critical for margin defense.
For New Entrants and Emerging Players:Enter via strategic white-space opportunities in edge computing networks and previously unaddressed secondary markets. Focus on niche, high-value applications like Quantum Key Distribution (QKD) networks requiring specialized, ultra-secure connectivity. A compelling go-to-market angle involves offering flexible, on-demand acquisition models for fiber routes, catering to project-based demands from large enterprises and content providers.
For Investors and Strategic Acquirers:Exit pathways concentrate in pure-play fiber infrastructure providers with extensive, well-maintained networks. The long-term viability of this market is strong, driven by foundational demand for digital infrastructure across a 5-10 year window. Acquisition targets should possess robust right-of-way portfolios or unique access to utility corridors. Increased M&A activity among utility companies monetizing their existing fiber assets is a key signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Enables hyperscale data centers to meet growing demand for cloud interconnects in key clusters. |
| Strategic Partnerships | Allows incumbent carriers to extend last-mile reach and leverage new fiber builds in underserved areas. |
| Technology Licensing | Facilitates the deployment of advanced optical transmission systems, reducing latency for financial services firms. |
| Geographic Expansion | Targets new data center hubs and 5G deployment zones, increasing network density for telecom operators. |
| Monetizing Utility Corridors | Creates new revenue streams for railway and electric utility companies from underutilized fiber assets. |
Research Approach
Independent corroboration across primary interviews, SEC filings, and regulatory reports underwrites the qualitative findings of this study. The analysis incorporates insights from telecom operators, data center providers, financial services firms, and regulatory bodies. Bottom-up and top-down triangulation methods ensure comprehensive market sizing and validation.
Rate-of-change decomposition framing informs the analytical framework, projecting market evolution over the projection horizon. This approach quantifies growth across product type, end user, application, deployment model, and geographic region. Compound annual growth rates are derived from historical data and projected shifts in technology adoption and infrastructure investment. Key industry-specific forecast inputs include global 5G rollout schedules and hyperscale data center capacity additions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant regulatory shifts or unforeseen technological disruptions. The forecasts reflect assumptions regarding infrastructure investment patterns and evolving data traffic demands. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Cloud Gateway Module Market
Network Technology
Wi-Fi Router Market
Network Technology
CPE Router Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Mobile Accelerator Market
Network Technology
Global Internet Transit Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Middle East & Africa Video Conferencing Hardware Market
Network Technology
Global Cloud Managed Wi-Fi Market
Network Technology
GCC Set-Top Box Market
Network Technology
Europe Video Conferencing Hardware Market
Network Technology
Netops Market
Network Technology
Europe Structured Cabling Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
Malaysia Wireless Router Market
Network Technology
ISP Management Systems Market