
 Wireless Infrastructure Monitoring Market | 2026-2036
Wireless Infrastructure Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Infrastructure Monitoring Market Outlook
Market Context
Wireless sensor engineering talent is rotating from telecom hardware into civil infrastructure monitoring, unlocking deployment capacity that structural engineering firms previously lacked. Nova Metrix leverages its geotechnical heritage to dominate vibration sensing for dams and tunnels across North America. Campbell Scientific sustains leadership in ruggedized dataloggers purpose-built for extreme weather telemetry networks. Geokon anchors its position through deep specialization in vibrating wire technology for concrete dam instrumentation.
Technical Definition and Structural Segments
Wireless infrastructure monitoring encompasses distributed sensor networks that measure strain, tilt, vibration, corrosion, and displacement in bridges, dams, tunnels, and buildings, transmitting data via cellular, satellite, Wi-Fi, or LPWAN protocols to centralized analytics platforms for predictive maintenance decisions. LPWAN technology leads deployment economics for remote, low-bandwidth installations where battery life spans multiple years without infrastructure power. Smart Cities application demand is accelerating fastest as municipalities integrate structural health data with traffic management and emergency response systems. Cloud-Based deployment captures expanding margin pools as operators shift from capital-intensive on-premises servers to subscription telemetry platforms.
Regulatory Framework
Federal Highway Administration guidelines and ISO 18649 structural vibration standards shape product certification requirements and procurement specifications across United States infrastructure projects. The EU Green Deal and CSRD reporting mandates in Europe are forcing asset owners to document structural condition transparency, directly expanding monitoring system demand. Stakeholders must weigh LPWAN against cellular technology commitments based on regional spectrum allocation decisions and long-term carrier infrastructure plans.
Market Dynamics
LPWAN protocol adoption is compressing deployment economics for remote civil infrastructure, enabling battery-powered sensor networks to operate for decade-long lifecycles without grid connectivity. Bridge operators now face Federal Highway Administration mandates requiring real-time structural transparency, forcing capital allocation toward distributed telemetry systems.
Growth Catalysts
- Federal Highway Administration mandates:Bridge operators in the United States must install continuous monitoring systems under structural health transparency requirements, creating procurement pull for vibration and strain sensor networks.
- EU Green Deal CSRD reporting:European asset owners must document structural condition data, expanding demand for cloud-based telemetry platforms that automate compliance documentation.
- Smart Cities integration:Municipalities are fusing structural health data with traffic management and emergency response systems, creating multi-department budget pools for unified sensor deployments.
Market Restraints
- Lithium battery supply concentration:Remote sensor networks depend on Chinese-processed lithium cells, exposing deployment timelines to raw material export restrictions and price volatility.
- Spectrum allocation uncertainty:Regional carrier infrastructure plans for LPWAN and cellular protocols remain unsettled, forcing operators to delay multi-year technology commitments.
- ISO 18649 certification friction:Structural vibration sensor vendors face extended testing timelines for product approval, compressing margins on standardized hardware.
Strategic Opportunities
- Japan tunnel modernization:Aging mountain tunnel networks lack instrumentation, creating first-mover advantage for vendors offering LoRaWAN-based displacement monitoring.
- AI-driven predictive analytics:Machine learning models trained on historical failure data are converging with edge computing hardware, enabling on-sensor anomaly detection without cloud latency.
- Germany dam safety upgrades:Federal water infrastructure regulations are tightening inspection frequencies, opening subscription revenue models for continuous monitoring services.
Industry Challenges
- RF engineering talent scarcity:Wireless protocol optimization for concrete and steel penetration requires specialized expertise that structural engineering firms rarely retain in-house.
- Legacy SCADA integration complexity:Decades-old dam control systems use proprietary data formats, forcing costly middleware development for unified telemetry dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Infrastructure Monitoring Market |
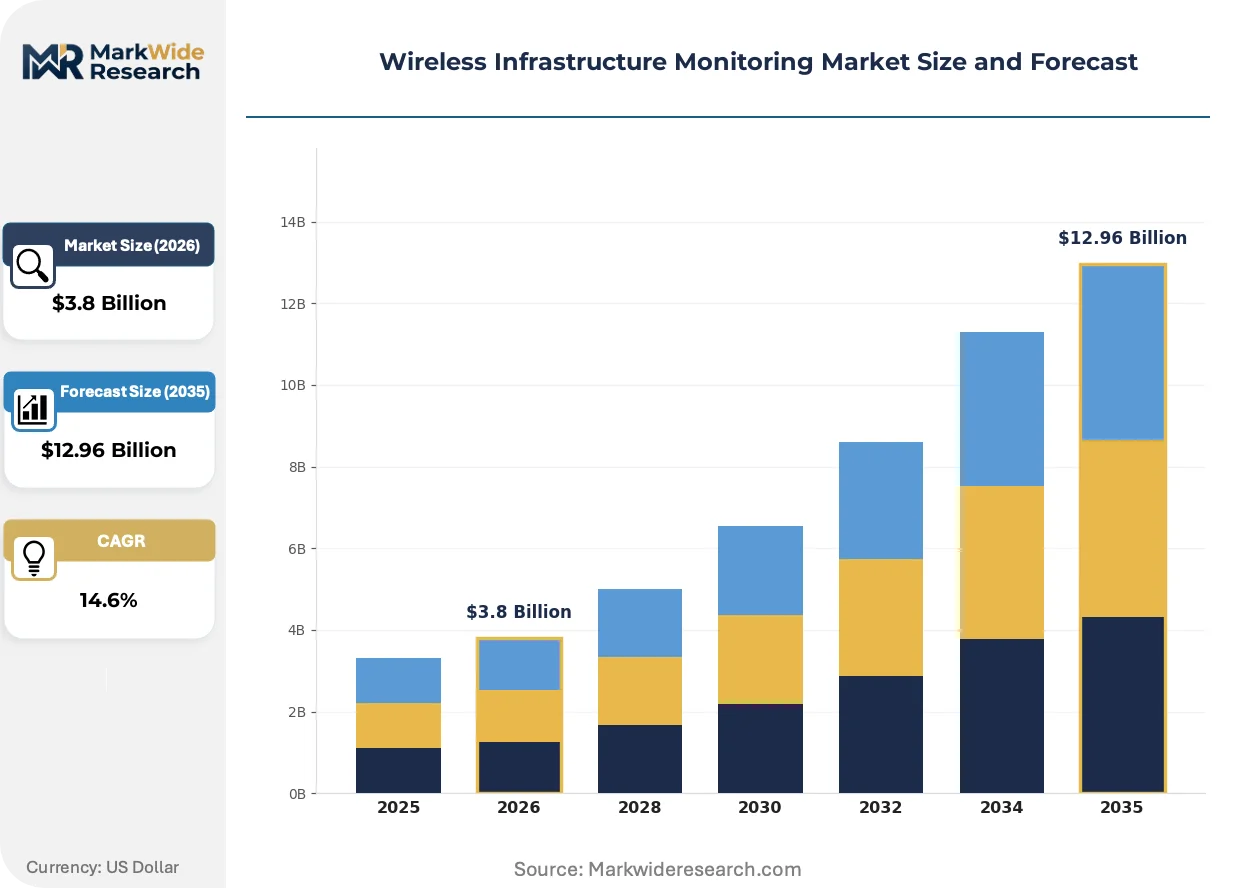
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cellular, Satellite, Wi-Fi, LPWAN Application: Smart Cities, Industrial Automation, Transportation, Public Safety End User: Telecom Operators, Government Agencies, Utility Companies, Transportation Providers Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Nova Metrix, Geokon, Campbell Scientific, RST Instruments, Sisgeo, Trimble, COWI, Geocomp, Acellent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Infrastructure Monitoring Market Strategic Shifts
Edge computing architectures are migrating analytical workloads from centralized cloud platforms to battery-powered field devices, reshaping how civil infrastructure generates actionable intelligence. This shift compresses response latency for critical safety alerts while extending network resilience during connectivity outages.
LoRaWAN is supplanting cellular telemetry for remote dam and tunnel installations where bandwidth requirements remain minimal and power infrastructure is absent. German water authorities are deploying these networks across Rhine basin flood control structures, eliminating recurring carrier subscription costs. The technology is supplanting legacy GSM modems by delivering comparable range at one-tenth the operational expenditure, forcing cellular IoT providers toward higher-data applications.
The EU CSRD mandates are compelling asset owners to publish machine-readable structural condition disclosures, transforming monitoring data from operational tool to regulatory asset. Engineering firms must now architect telemetry systems with audit-trail capabilities and third-party verification hooks. Bridge operators in France and the Netherlands are responding by consolidating fragmented sensor vendors under single-platform contracts that guarantee data lineage compliance.
Municipal procurement departments are unbundling hardware acquisition from analytics subscriptions, treating sensor networks as separable capital expenditures. This pattern disrupts traditional bundled offerings from integrated vendors. United States transportation departments are most visible in this shift, issuing distinct RFPs for installation contractors and software platform operators to optimize competitive bidding.
Wireless Infrastructure Monitoring Market Segmentation
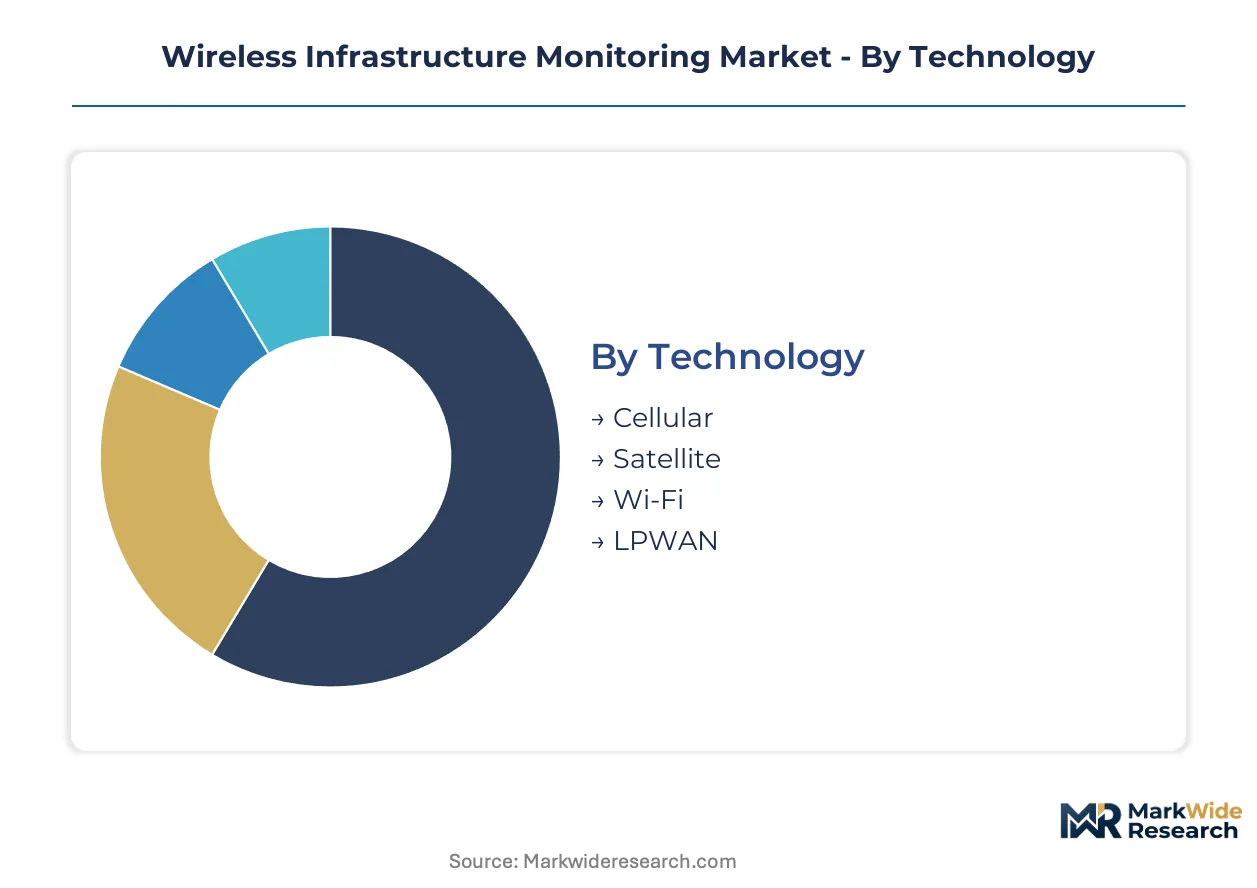
Technology selection determines power budgets, transmission range, and lifecycle economics for civil infrastructure deployments. Application context shapes sensor density requirements and integration complexity with legacy control systems.
Technology:
LPWAN protocols dominate export-led deployments across remote dams and mountain tunnels where cellular infrastructure is absent; cellular and Wi-Fi concentrate in domestic urban bridge networks with reliable grid connectivity.
- LPWAN:LoRaWAN and NB-IoT protocols enable decade-long battery operation without maintenance access. Rhine basin flood control structures in Germany deploy these networks to eliminate recurring carrier subscriptions.
- Cellular:LTE-M and 5G modules deliver high-bandwidth telemetry for vibration-intensive applications. United States bridge operators under Federal Highway Administration mandates favor cellular for real-time structural transparency requirements.
- Satellite:Iridium and Starlink terminals serve Arctic and offshore installations beyond terrestrial coverage. Norwegian hydroelectric reservoirs deploy satellite backhaul for seismic monitoring in fjord regions.
- Wi-Fi:Mesh networks power dense urban sensor grids with existing power infrastructure. Japanese smart city districts integrate Wi-Fi telemetry with traffic management command centers.
LPWAN holds the largest share; momentum sits with cellular as 5G coverage expands into secondary bridge corridors.
Application:
Smart Cities applications command premium pricing through multi-department budget consolidation; Transportation and Public Safety segments operate on constrained municipal capital cycles with extended procurement timelines.
- Smart Cities:Integrated platforms fuse structural health data with emergency response and traffic optimization systems. Amsterdam and Rotterdam consolidate sensor vendors under single-platform contracts to satisfy CSRD audit-trail requirements.
- Transportation:Bridge and tunnel networks require continuous strain, tilt, and displacement measurement. California Department of Transportation specifications mandate ISO 18649-certified vibration sensors for seismic zone structures.
- Industrial Automation:Factory and warehouse structural monitoring integrates with SCADA control loops. German automotive manufacturing clusters deploy wireless tilt sensors for automated guided vehicle pathway validation.
- Public Safety:Dam failure early warning systems and landslide detection networks serve population protection mandates. Swiss federal water authorities mandate redundant telemetry for alpine reservoir spillway monitoring.
Transportation holds the largest share; Smart Cities is climbing the fastest as municipalities unify departmental data platforms.
End User:
Government Agencies drive standardization through procurement specifications; Telecom Operators and Utility Companies favor managed service models to transfer operational risk.
- Government Agencies:Federal, state, and municipal infrastructure departments specify certified hardware with documented data lineage. French bridge operators respond to CSRD mandates by consolidating fragmented vendor relationships.
- Utility Companies:Electric, water, and gas network operators monitor substation foundations and pipeline corridors. German dam operators subscribe to continuous monitoring services as federal inspection frequencies tighten.
- Telecom Operators:Tower and data center structural health monitoring protects capital-intensive network assets. NTT Docomo deploys vibration sensors across Japan's mountain tunnel mobile coverage infrastructure.
- Transportation Providers:Railway and port authorities track trackbed settlement and quay wall displacement. Netherlands rail infrastructure managers integrate structural telemetry with traffic control signaling systems.
Government Agencies hold the largest share; Utility Companies are gaining share fastest through subscription revenue conversion.
Deployment:
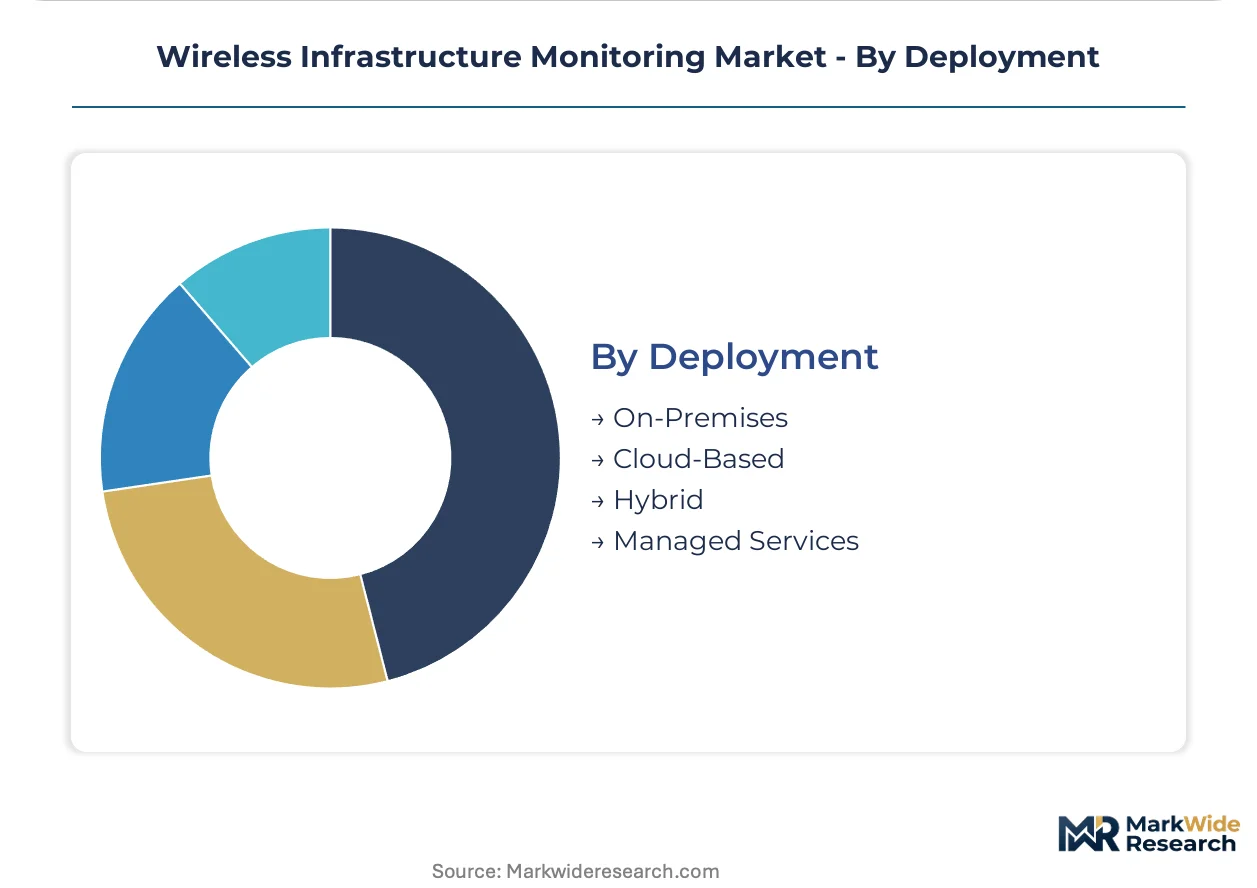
Cloud-Based and Managed Services models displace capital-intensive On-Premises installations as asset owners prioritize operational expenditure predictability.
- Cloud-Based:Subscription telemetry platforms automate compliance documentation and predictive analytics. European asset owners publish machine-readable structural condition disclosures through centralized dashboards.
- Managed Services:Vendors assume sensor maintenance, data validation, and platform operation responsibilities. United States transportation departments unbundle hardware from analytics to optimize competitive bidding.
- On-Premises:Air-gapped servers serve classified or critical infrastructure with cybersecurity isolation requirements. Swiss nuclear facility perimeter monitoring maintains local data sovereignty.
- Hybrid:Edge processing with cloud aggregation balances latency-sensitive alerts with long-term analytics. Japanese tunnel networks deploy on-sensor anomaly detection with periodic cloud model retraining.
Cloud-Based holds the largest share; Managed Services is expanding most quickly as procurement departments seek risk transfer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal Highway Administration mandates for structural health transparency anchor demand in the United States, while EU CSRD reporting requirements and Japan's aging tunnel networks create parallel expansion corridors across three continents.
United States
Bridge operators under Federal Highway Administration mandates must install continuous vibration and strain monitoring systems, creating procurement pull for certified sensor networks. California Department of Transportation specifications require ISO 18649-certified hardware for seismic zone structures. The San Francisco Bay Area corridor concentrates deployment activity as metropolitan transportation agencies consolidate vendor relationships.
Germany
Rhine basin flood control structures deploy LPWAN networks to eliminate recurring carrier subscriptions, while federal water infrastructure regulations tighten dam inspection frequencies. EU Green Deal CSRD reporting mandates force asset owners to document structural condition transparency through machine-readable disclosures. Munich and Stuttgart engineering clusters anchor telemetry platform development for European export markets.
Japan
Aging mountain tunnel networks lack instrumentation, creating first-mover opportunities for LoRaWAN-based displacement monitoring vendors. METI infrastructure modernization programs prioritize seismic resilience for civil structures across the archipelago. The Kanto region around Tokyo concentrates smart city integration projects fusing structural health data with emergency response systems.
Switzerland
Federal water authorities mandate redundant telemetry for alpine reservoir spillway monitoring, protecting downstream population centers from dam failure risks. Swissmedic-equivalent civil engineering standards require documented data lineage for critical infrastructure instrumentation. The Alpine Rhine corridor hosts concentrated deployment of satellite backhaul systems for fjord-region hydroelectric seismic monitoring.
France
Bridge operators respond to CSRD mandates by consolidating fragmented sensor vendors under single-platform contracts guaranteeing audit-trail compliance. ANSM-aligned procurement specifications shape certification requirements for structural vibration sensors in public infrastructure. The Paris metropolitan region drives smart city platform integration linking structural health data with traffic management command centers.
Wireless Infrastructure Monitoring Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, creating a two-tier structure where scale advantages in cloud telemetry platforms contrast with deep domain expertise in geotechnical sensing. The upper tier commands subscription revenue pools through managed service offerings, while specialists capture premium pricing on certified hardware for extreme environment installations. Three archetypes dominate: geotechnical heritage firms with vibrating wire specialization, ruggedized datalogger manufacturers with extreme weather telemetry focus, and cloud-native platform operators unbundling analytics from hardware acquisition. Competitive moves concentrate on M&A to absorb LPWAN protocol engineering talent and strategic partnerships to penetrate Japan's tunnel modernization wave.
Within the geotechnical specialist tier, Nova Metrix and Geokon occupy positions anchored by deep instrumentation heritage, while Campbell Scientific exemplifies the ruggedized telemetry archetype through its extreme environment datalogger focus. These three firms represent contrasting strategic postures: Nova Metrix leverages North American dam and tunnel deployment experience, Geokon anchors concrete dam instrumentation through vibrating wire technology specialization, and Campbell Scientific sustains leadership in weather-hardened field equipment for distributed networks.
| Leading Market Players |
|---|
| Nova Metrix |
| Geokon |
| Campbell Scientific |
| RST Instruments |
| Sisgeo |
| Trimble |
| COWI |
| Geocomp |
| Acellent |
| Others |
Value Chain & Pricing Dynamics
LoRaWAN module substitution for legacy GSM telemetry simultaneously relocates manufacturing gravity toward Taiwan and South Korea while collapsing operational expenditure benchmarks for remote dam operators, compressing pricing premiums that cellular IoT vendors previously commanded for decade-long battery deployments.
Pricing Analysis
Geographic price spreads of 40-60 percent separate German-engineered vibrating wire sensors from Asian-manufactured LPWAN nodes, with ISO 18649 certification tiers and extreme weather hardening as the primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels stratifies by data lineage compliance depth and after-sales calibration bundling. Pricing pressure stems from municipal procurement departments unbundling hardware from analytics subscriptions, forcing margin compression on integrated vendors. Government agencies exhibit highest price sensitivity due to competitive bidding mandates, while utility companies accept premium positioning for managed service risk transfer.
Supply Chain Analysis
Lithium cell processing concentration in China creates a single-source vulnerability for decade-long battery deployments across North American bridge networks. Sensor manufacturing draws from Taiwan for semiconductor components, Germany for precision strain gauges, and Japan for MEMS accelerometers. Raw material dependencies center on rare earth magnets, lithium carbonate, and high-purity copper for antenna systems. Tariff exposure runs through Chinese-processed battery supply chains. Distribution runs through engineering firm channel partners who specify certified hardware for federal infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF engineering talent scarcity for concrete penetration optimization creates competitive moats that structural engineering firms cannot replicate without external acquisition, reshaping how vendors defend positioning across Federal Highway Administration procurement cycles.
For Market Incumbents: Compound cloud telemetry platform scale through LPWAN protocol engineering acquisitions that absorb scarce RF optimization talent before cellular IoT vendors pivot downward. Defend margin position by anchoring ISO 18649 certification pipelines against emerging Asian sensor manufacturers. Prioritize backward integration into lithium battery pack assembly to offset Chinese supply concentration risks. For New Entrants and Emerging Players: Lead with LoRaWAN-based displacement monitoring for Japan's aging mountain tunnel networks, where first-mover advantage remains unclaimed and METI infrastructure programs prioritize seismic resilience. Target German dam operators through subscription revenue models aligned with federal inspection frequency tightening. Deploy direct sales teams through Munich engineering clusters rather than fragmented distributor relationships. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors geotechnical heritage firms with vibrating wire specialization over cloud-native platform operators lacking field calibration expertise. Long-term viability across the analysis window favors vendors with captive LPWAN protocol engineering and documented CSRD audit-trail capabilities. Watch for carrier spectrum allocation decisions as the inflection signal that reshapes technology commitment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of LPWAN Protocol Engineering Talent | Absorbs scarce RF optimization expertise that cellular IoT vendors cannot replicate for concrete penetration applications. |
| CSRD-Compliant Audit-Trail Platform Development | Captures European asset owner procurement as EU Green Deal mandates force machine-readable structural condition disclosures. |
| Subscription Revenue Model Conversion | Aligns with German federal dam inspection frequency tightening and United States transportation department unbundling trends. |
| Strategic Partnership with Japanese Tunnel Operators | Secures first-mover positioning in METI infrastructure modernization programs for seismic resilience instrumentation. |
| Backward Integration into Battery Pack Assembly | Reduces Chinese lithium cell supply concentration exposure for decade-long remote deployment lifecycles. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bridge engineering directors, dam safety officers, LPWAN network architects, and municipal procurement managers. Secondary validation drew from Federal Highway Administration guideline publications, EU CSRD regulatory texts, ISO 18649 certification documentation, and customs records for sensor component trade flows. Bottom-up deployment volume estimates triangulated against top-down infrastructure spending allocations across the analysis window.
Across the projection horizon, the analytical framework modeled technology protocol selection, application segment integration complexity, end-user procurement structure, and deployment model migration patterns. CAGRs were derived from infrastructure age profiles, regulatory mandate implementation schedules, and technology substitution elasticity estimates. Forecast inputs included Federal Highway Administration mandate compliance timelines, EU Green Deal CSRD reporting phase-ins, and Japan METI tunnel modernization program allocations.
Forecasts assume regulatory continuity in United States federal infrastructure guidelines and EU corporate sustainability reporting regimes; material policy shifts would require re-modeling deployment elasticity assumptions. Practitioners should keep alternative scenarios live as carrier spectrum allocation decisions and lithium export restriction risks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Home Networking Device Market
Network Technology
Network Performance Monitoring Market
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
Zero-Touch Provisioning Market
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
Lit Fiber Market
Network Technology
RTP Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Internet Protocol Address Management (IPAM) Market
Network Technology
Global Private 5G Network Market
Network Technology
Residential Routers Market
Network Technology
Global Network Probe Market
Network Technology
Europe Private 5G Network Market
Network Technology
Network Equipment Market
Network Technology
Europe Structured Cabling Market
Network Technology
Virtual Customer Premises Equipment Market