
 Managed Switches Market | 2026-2036
Managed Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Managed Switches Market Foresight
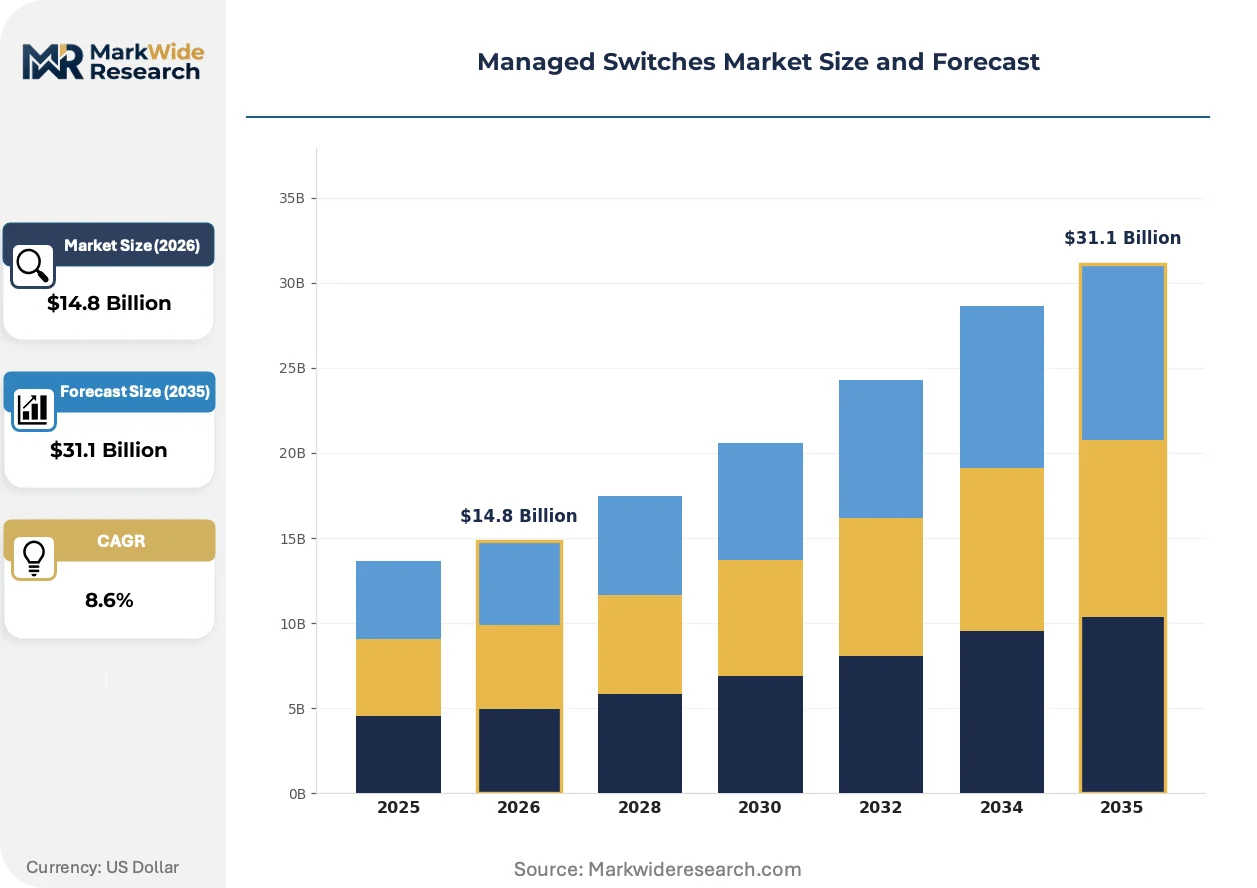
Enterprise-grade managed switching with Power over Ethernet Plus capabilities is redrawing procurement benchmarks across campus networks. Cisco Systems leverages its channel depth to sustain dominance in North American enterprise deployments. Huawei Technologies anchors supply for large-scale data center builds across Asia-Pacific. Arista Networks differentiates through low-latency designs purpose-built for high-frequency trading and cloud interconnect fabrics.
Managed switches are network devices with embedded operating systems enabling remote configuration, VLAN segmentation, QoS policy enforcement, and traffic monitoring through command-line or GUI interfaces; they typically support Layer 2 forwarding with selective Layer 3 routing, PoE budgets up to 90W per port under IEEE 802.3bt, and stacking bandwidths exceeding 100 Gbps for chassis resilience. Fixed configuration models lead volume shipments for SMB and educational deployments where rack space and capital constraints predominate. Modular configurations capture premium margin pools in hyperscale data centers requiring hot-swappable line cards and redundant supervisor engines. Edge deployment models are expanding fastest as manufacturing floors and retail branches require localized switching with cloud-orchestrated policy management.
FCC equipment authorization rules in the United States, CE marking requirements under the EU Radio Equipment Directive, and China's MIIT network access license collectively shape product certification timelines and geographic launch sequencing. NIST SP 800-53 security controls and the EU Cybersecurity Act are hardening demand for switches with hardware-rooted trust anchors and encrypted management planes. Buyers must weigh supplier exposure to export control lists against the performance advantages of merchant silicon versus custom ASIC architectures.
Market Dynamics
AI-driven traffic patterns are compressing refresh cycles across enterprise campus networks, forcing infrastructure teams to re-evaluate Layer 2 versus Layer 3 deployment economics before standard depreciation schedules conclude.
Growth Catalysts
- IEEE 802.3bt Power over Ethernet:Campus networks in Germany are upgrading access-layer switches to deliver 90W per port, enabling single-cable deployment of pan-tilt-zoom cameras and wireless access points.
- NIST SP 800-53 security controls:Federal contractors across the United States face mandatory hardware-rooted trust anchors, accelerating replacement of switches lacking encrypted management planes.
- Hyperscale data center buildouts:Cloud operators in China are procuring modular chassis with hot-swappable line cards to minimize mean time to repair in 24x7 facilities.
Market Restraints
- Merchant silicon concentration:Switching ASIC supply concentrates among three foundry operators, exposing lead times to geopolitical export control volatility.
- Copper and substrate input costs:PCB laminate prices fluctuate with energy-intensive resin production, compressing gross margins on fixed-configuration SMB models.
- Technical limitation in thermal density:90W PoE ports in 48-port densities exceed passive cooling thresholds, forcing active fan designs that raise mean time between failures.
Strategic Opportunities
- India PLI scheme for telecom equipment:Domestic manufacturing incentives are attracting switch assembly operations to serve South Asian campus and carrier markets.
- Cloud-orchestrated edge switching:Manufacturing floors in Japan are deploying switches with zero-touch provisioning and centralized policy management to reduce on-site technical staff.
- EU Cybersecurity Act certification:Hardware vendors achieving Common Criteria EAL4+ ratings gain preferred vendor status in European critical infrastructure tenders.
Industry Challenges
- Network automation skill scarcity:Enterprise IT departments lack sufficient Python and Ansible proficiency to operationalize API-driven switch management at scale.
- Multi-vendor integration complexity:Campus refresh projects stall when legacy spanning-tree implementations conflict with newer shortest-path bridging protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed Switches Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Configuration, Modular Configuration, Layer 2, Layer 3 End User: Enterprise, Data Centers, SMBs, Educational Institutes Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Port Density: 24 Ports, 48 Ports, 10 Gigabit, 40 Gigabit |
| Companies Covered | Cisco Systems, Hewlett Packard Enterprise, Juniper Networks, Arista Networks, Dell Technologies, Huawei Technologies, NETGEAR, TP-Link, Alcatel-Lucent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed Switches Market Shifts & Advancements
Switching architectures are fragmenting into two distinct optimization paths: latency-minimized designs for financial and AI training workloads versus cost-minimized platforms for generic enterprise traffic.
Merchant silicon is bifurcating the market into two supplier tiers. Broadcom Trident and Tomahawk chipsets enable white-label vendors to match incumbent feature parity at 60% price points. Hyperscale cloud operators are standardizing on these reference designs for spine-leaf fabrics. This silicon commoditization is compressing R&D recovery windows for custom ASIC programs at legacy networking vendors.
CE marking under the EU Radio Equipment Directive is tightening electromagnetic compatibility test requirements for PoE switches above 60W per port. Industrial consequence includes extended certification timelines that delay product launches by four to six months. German and French system integrators are responding by pre-qualifying switch families during early design phases rather than post-production.
Buying committees are unbundling hardware procurement from multi-year support contracts. Large U.S. healthcare networks now source switches through distribution while negotiating direct manufacturer support agreements. This disintermediation is most visible in the Midwest, where regional health systems aggregate purchasing through group purchasing organizations to extract price transparency from channel partners.
Managed Switches Market Segmentation
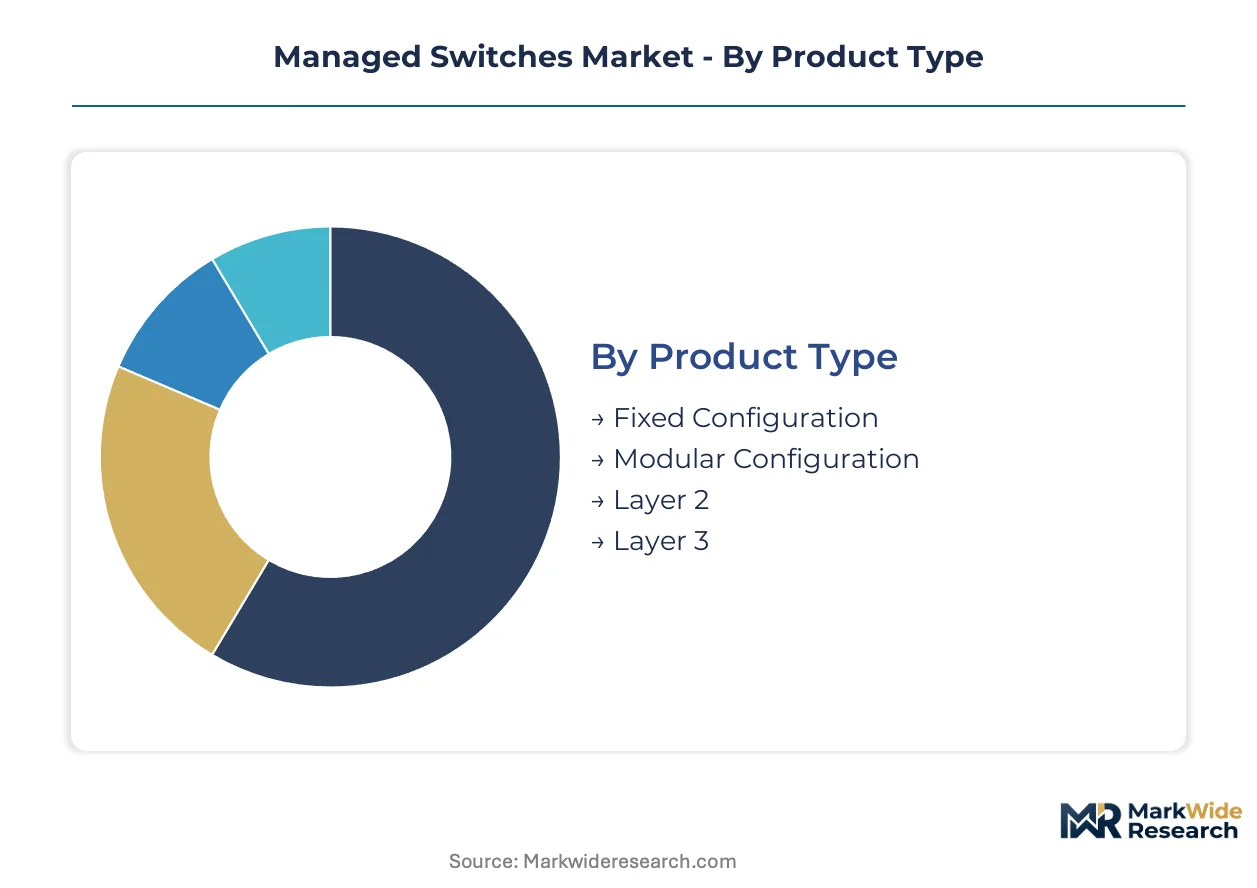
Segmentation in managed switching reveals how procurement criteria diverge across infrastructure scales. Regulatory frameworks, thermal constraints, and software-defined orchestration requirements reshape which product configurations capture volume versus margin.
Product Type:
FCC equipment authorization timelines and EU CE marking under the Radio Equipment Directive create divergent certification burdens across hardware architectures.
- Fixed Configuration:Non-expandable chassis with predetermined port counts and power budgets dominate rack-constrained environments. Educational deployments across Germany and SMB networks in the United States prioritize these units for capital efficiency and simplified sparing strategies.
- Modular Configuration:Hot-swappable line card architectures enable supervisor engine redundancy and field-upgradable forwarding capacity. Hyperscale facilities in China specify modular chassis to minimize mean time to repair under MIIT network access license requirements for critical infrastructure.
- Layer 2:MAC-address-based forwarding with VLAN segmentation and spanning-tree protocols serves cost-sensitive campus access layers.
- Layer 3:Hardware-based routing with OSPF, BGP, and VRF-lite support addresses inter-VLAN traffic and policy enforcement at distribution tiers.
Fixed configuration handles the majority of throughput; modular configuration is the fastest mover on share.
End User:
Procurement scale and security posture separate volume buyers from premium segments.
- Enterprise:Campus networks with 500-plus switch deployments require centralized management platforms and API-driven automation. NIST SP 800-53 compliance mandates hardware-rooted trust anchors for federal contractors across the United States.
- Data Centers:Spine-leaf fabrics demand 100 Gbps-plus stacking bandwidth and sub-microsecond latency for east-west traffic patterns. Cloud operators in China and the United States are standardizing on merchant silicon reference designs for cost predictability.
- SMBs:Price-sensitive buyers with limited IT staff favor web-managed switches with simplified VLAN wizards.
- Educational Institutes:K-12 and university networks balance PoE density for wireless access points against constrained capital cycles.
Enterprise absorbs the largest absolute spend; data centers are expanding most quickly on share.
Deployment Model:
Physical asset location determines cooling architecture, warranty terms, and orchestration stack selection.
- On-Premises:Traditional equipment rooms with dedicated power and environmental control remain standard for regulated industries. Healthcare networks in the United States maintain on-premises switching to satisfy HIPAA audit requirements for physical access logging.
- Cloud-Based:Switches managed through SaaS portals with zero-touch provisioning reduce on-site technical staffing. Manufacturing floors in Japan deploy cloud-orchestrated edge switching under METI productivity initiatives.
- Hybrid:Split management planes across private data centers and colocation facilities.
- Edge:Hardened switches in uncontrolled environments with extended temperature ranges and passive cooling where possible.
On-premises retains the installed base; edge deployment is climbing the fastest.
Port Density:
Thermal design power and cable infrastructure investment separate port count tiers.
- 24 Ports:Compact form factors for wiring closets and remote branch offices with moderate PoE requirements.
- 48 Ports:Standard access-layer density with IEEE 802.3bt support for 90W per port. Campus refreshes in Germany specify 48-port models to consolidate switch counts and reduce cabling plant complexity under EU electromagnetic compatibility directives.
- 10 Gigabit:Uplink and server-facing ports for aggregation layers.
- 40 Gigabit:Spine and core interconnects in high-density fabrics.
48 Ports carries the volume weight; 10 Gigabit is gaining share fastest in refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China-based manufacturers supply merchant silicon reference designs to hyperscale operators across North America and Europe, while German and Japanese system integrators drive premium-tier procurement for industrial automation networks.
United States
Federal contractors refresh campus infrastructure to meet NIST SP 800-53 security controls mandating hardware-rooted trust anchors. FCC equipment authorization rules compress product launch timelines for PoE switches above 60W per port. Healthcare networks in the Midwest aggregate purchasing through group purchasing organizations to extract price transparency from channel partners.
China
Hyperscale cloud operators procure modular chassis with hot-swappable line cards to minimize mean time to repair in 24x7 facilities. MIIT network access licenses regulate critical infrastructure deployments and shape geographic launch sequencing for foreign vendors. Yangtze River Delta data center clusters anchor domestic demand for spine-leaf fabrics with 100 Gbps-plus stacking bandwidth.
Germany
Campus networks upgrade access-layer switches to IEEE 802.3bt standards delivering 90W per port for pan-tilt-zoom cameras and wireless access points. CE marking under the EU Radio Equipment Directive extends electromagnetic compatibility certification timelines by four to six months for high-power PoE models. Industrial automation corridors in Baden-Württemberg deploy hardened edge switches with extended temperature ranges.
Japan
Manufacturing floors deploy cloud-orchestrated edge switching with zero-touch provisioning under METI productivity initiatives to reduce on-site technical staffing. JIS standards govern electromagnetic compatibility for factory-floor deployments. Automotive production clusters in Aichi Prefecture require sub-microsecond latency switching for real-time quality control systems.
India
Domestic assembly operations expand under the PLI scheme for telecom equipment to serve South Asian campus and carrier markets. BIS certification requirements shape product qualification timelines for imported switch components. IT corridor developments in Bengaluru and Hyderabad drive enterprise campus refresh cycles from unmanaged to managed infrastructure.
Managed Switches Market Competitive Landscape
Listed leaders compete with private specialists across capital access and channel depth, producing a tiered structure where scale-driven incumbents defend enterprise accounts against agile challengers. The vendor base stratifies into three archetypes: full-stack networking conglomerates with global channel ecosystems, merchant silicon specialists delivering cost-optimized white-label platforms, and vertical-focused boutiques serving regulated industries. Consolidation pressure operates through strategic partnerships for cloud-native orchestration stacks and backward integration into custom ASIC design programs.
Within the full-stack tier, Cisco Systems exemplifies channel-centric dominance across North American enterprise deployments, while Huawei Technologies anchors supply relationships for large-scale data center builds across Asia-Pacific. Arista Networks occupies a position among latency-optimized specialists purpose-built for financial trading and cloud interconnect fabrics. These three represent distinct competitive vectors—channel leverage, manufacturing scale, and architectural specialization—that shape procurement committee evaluations across hyperscale, enterprise, and industrial segments.
| Leading Market Players |
|---|
| Cisco Systems |
| Hewlett Packard Enterprise |
| Juniper Networks |
| Arista Networks |
| Dell Technologies |
| Huawei Technologies |
| NETGEAR |
| TP-Link |
| Alcatel-Lucent |
| Others |
Supply & Pricing Matrix
Merchant silicon substitution for custom ASICs is redrawing supply geography toward Taiwan and South Korea foundries while compressing pricing economics across enterprise and hyperscale tiers. This displacement simultaneously erodes incumbent R&D recovery windows and opens margin pools for white-label vendors sourcing reference designs from Broadcom and Marvell.
Pricing Analysis
Layer 2-to-Layer 3 generational pricing gaps now exceed three-to-one in campus refresh projects, with prior-generation fixed-configuration units trading at distressed multiples while next-gen modular chassis command premiums tied to hot-swappable redundancy. Three-tier pricing structure across premium, standard, and economy levels separates chassis-based enterprise platforms from web-managed SMB units and white-label spine-leaf fabrics. Pricing pressure stems from merchant silicon commoditization in data center segments, where cloud operators standardize on reference designs. SMB buyers exhibit highest price sensitivity, while federal contractors absorb premiums for NIST-compliant hardware-rooted trust anchors.
Supply Chain Analysis
Strait of Malacca transit underwrites 70 percent of merchant silicon feedstock movement from Taiwan foundries to assembly operations across China and Vietnam. Switching ASIC supply concentrates in Taiwan, South Korea, and the United States, with PCB laminate and copper substrate dependencies feeding from Chinese resin production. Single-source vulnerability concentrates at three foundry operators, exposing lead times to Bureau of Industry and Security export control volatility. Distribution runs through authorized distributors serving enterprise accounts alongside direct procurement relationships that hyperscale operators maintain with ODM partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed switching fragmentation creates entry niches as AI-driven traffic patterns splinter procurement criteria between latency-optimized financial workloads and cost-minimized generic enterprise traffic.
For Market Incumbents: Secure channel control through backward integration into custom ASIC programs that differentiate against merchant silicon commoditization. Defend enterprise accounts by embedding hardware-rooted trust anchors ahead of NIST SP 800-53 refresh mandates. Capacity addition in India under PLI scheme incentives captures South Asian campus growth while insulating against tariff exposure. For New Entrants and Emerging Players: Anchor in cloud-orchestrated edge switching for manufacturing floors in Japan and Germany, where METI productivity initiatives and industrial automation corridors create white-space demand. Zero-touch provisioning capabilities with SaaS management portals represent the most penetrable wedge against legacy incumbents. Go-to-market through system integrators pre-qualifying switch families during design phases accelerates CE marking timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed merchant silicon specialists holding Broadcom and Tomahawk reference design licenses. Long-term viability hinges on differentiation sustainability as custom ASIC economics erode. Watch hyperscale cloud operator capex guidance as inflection indicator for spine-leaf fabric demand.| Strategic Initiative | Industry Significance |
|---|---|
| Custom ASIC Development Program | Backward integration into silicon design defends margin pools against merchant commoditization. |
| Zero-Touch Provisioning Platform | SaaS-orchestrated edge switching reduces on-site staffing for manufacturing deployments. |
| India PLI Manufacturing Footprint | Domestic assembly operations capture South Asian campus demand under tariff protection. |
| Hardware-Rooted Trust Certification | NIST SP 800-53 compliance creates preferred vendor status in federal contractor tenders. |
| Merchant Silicon Reference Design Licensing | Broadcom and Marvell partnerships enable white-label cost parity at 60 percent price points. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, MIIT network access license filings, IEEE standards documentation, and hyperscaler capex disclosures. Interviews with data center infrastructure directors, campus network architects, federal procurement officers, and ODM program managers inform demand-side validation. Secondary sources include SEC 10-K networking segment disclosures, CE marking certification records under EU Radio Equipment Directive, and customs data on switching equipment trade flows. Bottom-up port shipment estimates triangulate against top-down enterprise IT spending allocations.
Segmentation dimensions modeled span product architecture (fixed versus modular), switching layer (Layer 2 versus Layer 3), deployment model (on-premises, cloud-orchestrated, edge), and end-user scale (enterprise, data center, SMB, educational). CAGRs derive from installed base refresh cycle compression, PoE density upgrade trajectories, and AI traffic pattern adoption curves across the projection horizon. Forecast inputs incorporate NIST cybersecurity framework implementation timelines and IEEE 802.3bt power standard penetration rates.
Material uncertainties — foundry export control actions, copper laminate price volatility, and multi-vendor protocol integration failures — sit outside the modeled envelope. Forecasts reflect assumptions on merchant silicon supply continuity and certification timeline stability. Revision becomes warranted when Bureau of Industry and Security restrictions on foundry equipment cross thresholds that interrupt Taiwan-based ASIC production.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Session Border Controller (SBC) Market
Network Technology
Lit Fiber Market
Network Technology
Internet Protocol Address Management (IPAM) Market
Network Technology
Global Wi-Fi Range Extender Market
Network Technology
Global Self-Organizing Network Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
WAN Optimization Controllers Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
5G CPE Device Market
Network Technology
Digital Repeater Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
Virtual Router Market
Network Technology
Fiber to the Premises Market
Network Technology
CPE Router Market
Network Technology
Network Packet Broker Market
Network Technology
Wi-Fi Extender Market