
 Fiber to the Premises Market | 2026-2036
Fiber to the Premises Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber to the Premises Market Intelligence
The Fiber to the Premises industry is pivoting around a widening performance gap between gigabit-capable deployments and legacy DSL upgrades that cap out below 100 Mbps. Corning Inc. leverages its vertical integration from preform manufacturing to finished cable to sustain pricing power in North American markets. Prysmian Group anchors European supply through dense distribution networks and marine cable synergies. CommScope competes aggressively on active equipment bundles that pair fiber plant with centralized management software.
Fiber to the Premises denotes the direct installation of optical fiber cabling from a central office or access node to individual buildings, typically employing single-mode fiber with wavelengths of 1310 nm or 1550 nm to deliver symmetric gigabit throughput over distances exceeding 20 kilometers. Its primary purpose is eliminating electrical signal degradation and bandwidth bottlenecks inherent in copper twisted-pair or coaxial last-mile architectures. Gigabit Passive Optical Network technology dominates installed volume due to its split-ratio economics and passive splitter simplicity, while Wavelength Division Multiplexing commands premium positioning in data center interconnects where spectral efficiency determines lease pricing. Residential Broadband application generates the largest absolute revenue pool, though Business Connectivity carries wider margin spreads from service-level guarantees and managed router provisioning.
The Federal Communications Commission in the United States sets minimum broadband benchmarks that effectively disqualify non-fiber technologies from subsidy eligibility, while the EU Green Deal and national digital agendas in France and Germany mandate fiber-first public procurement. India's Department of Telecommunications enforces BharatNet milestones that compel state-owned and private carriers to prioritize rural optical builds. Stakeholders must track how subsidy clawback provisions and open-access mandates reshape returns on deployed fiber plant.
Market Dynamics
The Fiber to the Premises market pivots on the collision between subsidy-driven deployment mandates and the physical constraints of last-mile construction economics. Government broadband programs in the United States, the European Union, and India are compressing deployment timelines while labor shortages and material costs strain execution capacity.
Growth Catalysts
- BharatNet Phase III:India's Department of Telecommunications mandates optical fiber connectivity to 600,000 village councils, creating concentrated demand for drop cables and passive splitters.
- FCC Broadband Equity Access and Deployment Program:The United States conditions $42.45 billion in funding on minimum 100 Mbps symmetrical speeds, effectively disqualifying copper and fixed wireless alternatives.
- XGS-PON Technology Migration:Internet service providers are upgrading from GPON to XGS-PON to deliver 10 Gbps symmetrical service without replacing fiber plant.
Market Restraints
- Optical Fiber Preform Supply Concentration:Four manufacturers control over 80% of global preform production, creating input cost volatility and allocation risk during demand surges.
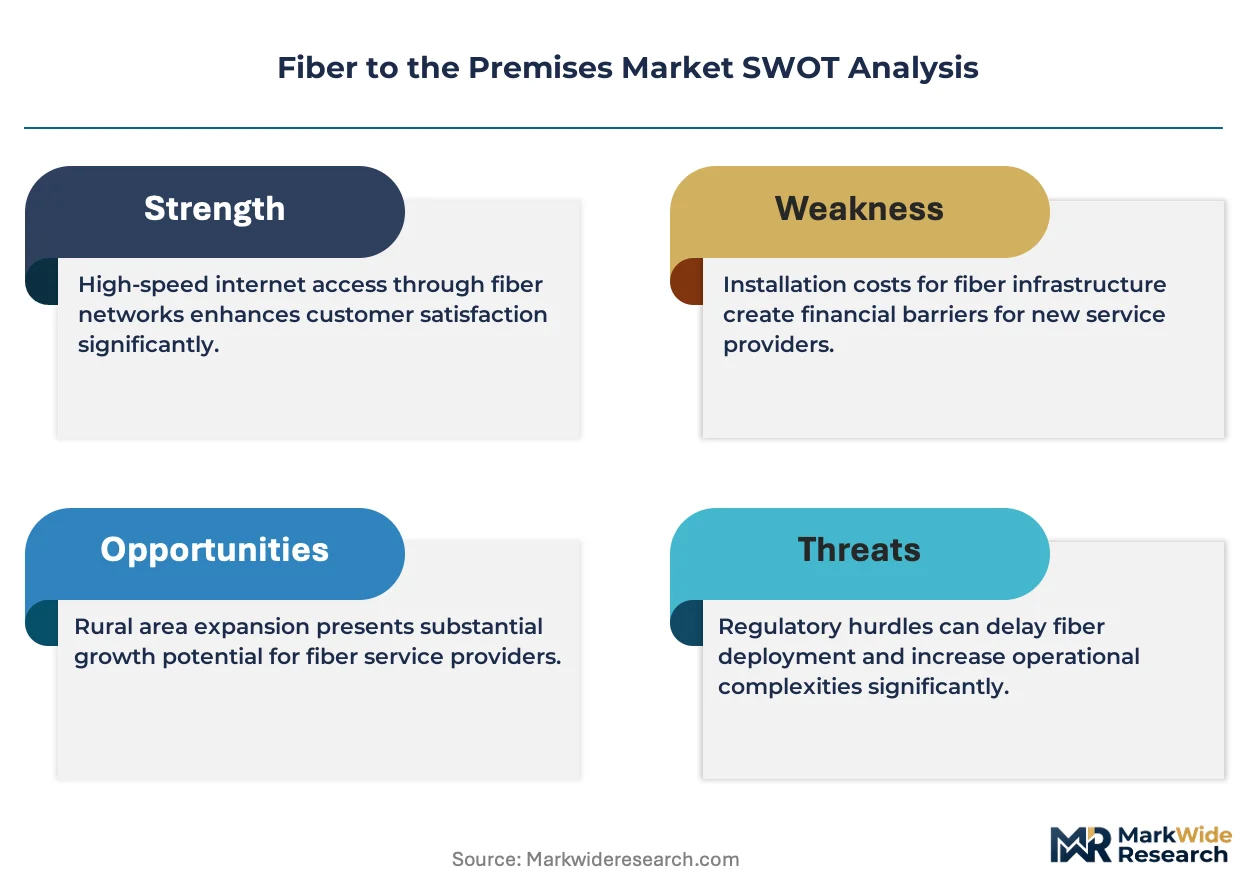
- Right-of-Way Acquisition Friction:Municipal permitting timelines in dense urban cores stretch 18-24 months, delaying revenue recognition on committed capital.
- Fixed Wireless Access Substitution:Millimeter-wave and sub-6 GHz wireless technologies are capturing price-sensitive subscribers in suburban markets where fiber overbuild economics remain marginal.
Strategic Opportunities
- Rural India Penetration Gap:Less than 15% of Indian rural households have fixed broadband access, creating a decade-long deployment runway under government subsidy programs.
- Smart City Convergence:Fiber infrastructure is converging with intelligent traffic management and public safety networks, enabling bundled service contracts with municipal governments.
- Open-Access Mandate Arbitrage:France and Germany are requiring infrastructure unbundling, creating wholesale revenue streams for neutral host operators.
Industry Challenges
- Fusion Splicing Technician Scarcity:Deployment targets exceed the trained workforce supply in North America and Western Europe, inflating labor costs and extending project timelines.
- Legacy Copper Integration Complexity:Hybrid networks require simultaneous maintenance of DSL, coaxial, and fiber plant, fragmenting operational focus and capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber to the Premises Market |
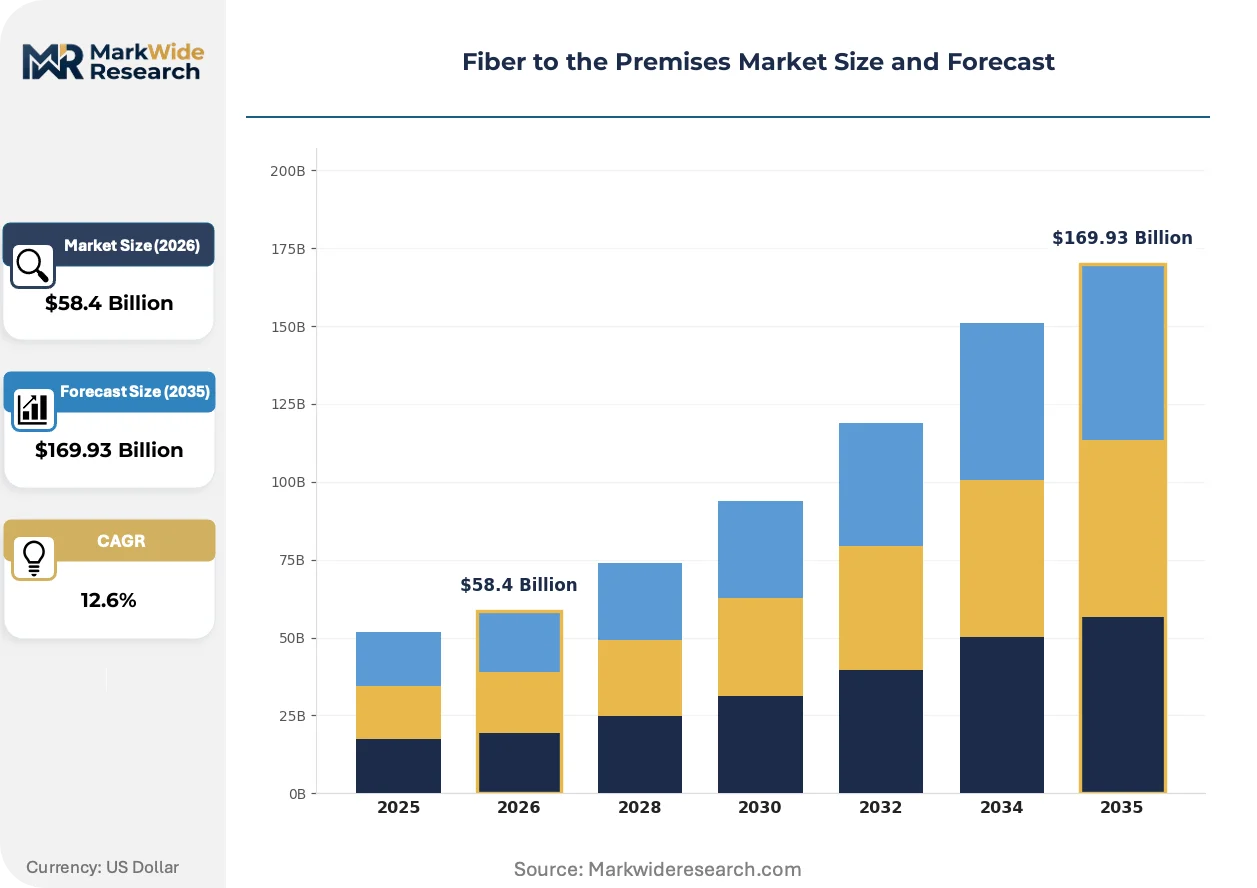
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $169.93 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gigabit Passive Optical Network, Ethernet Passive Optical Network, Active Optical Network, Wavelength Division Multiplexing, Time Division Multiplexing Product Type: Optical Network Terminal, Optical Line Terminal, Optical Distribution Frame, Fiber Optic Cable, Fiber Access Terminal Application: Residential Broadband, Business Connectivity, Government Networks, Educational Institutions, Data Center Interconnects End User: Internet Service Providers, Telecommunication Carriers, Managed Service Providers, Enterprise Corporations, Housing Associations |
| Companies Covered | OFS, Superior Essex Communications, Corning Inc., Belden Inc., Sterlite Technologies, Prysmian Group, AFL, Panduit, CommScope, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber to the Premises Market Strategic Shifts & Innovations
Three forces are compressing deployment timelines and reshaping procurement patterns across the Fiber to the Premises value chain. Technology migration, subsidy conditionality, and buyer behavior shifts are intersecting to accelerate infrastructure replacement cycles.
Passive optical network architecture is converging with software-defined access control to enable real-time bandwidth provisioning and automated fault detection. Tier-one carriers in South Korea and Japan are deploying these converged systems to reduce truck rolls and accelerate service activation. The structural consequence is a compression in operational expenditure per subscriber, shifting competitive advantage toward integrated hardware-software vendors.
The EU Green Deal's digital component is mandating energy efficiency disclosures for network equipment, favoring low-power optical line terminals over legacy active Ethernet switches. Equipment manufacturers must now certify power consumption per port under standardized test conditions. Data center interconnect and enterprise verticals are responding by specifying 400G ZR coherent optics with programmable power modes.
Procurement patterns among United States rural electric cooperatives are shifting from equipment purchases to design-build-operate contracts with 15-20 year terms. These arrangements transfer construction risk to engineering firms while locking in subscriber revenue streams. The shift is most visible in Appalachia and the Midwest, where electric utilities are leveraging existing pole attachments and customer relationships to challenge incumbent telephone cooperatives.
Fiber to the Premises Market Segmentation
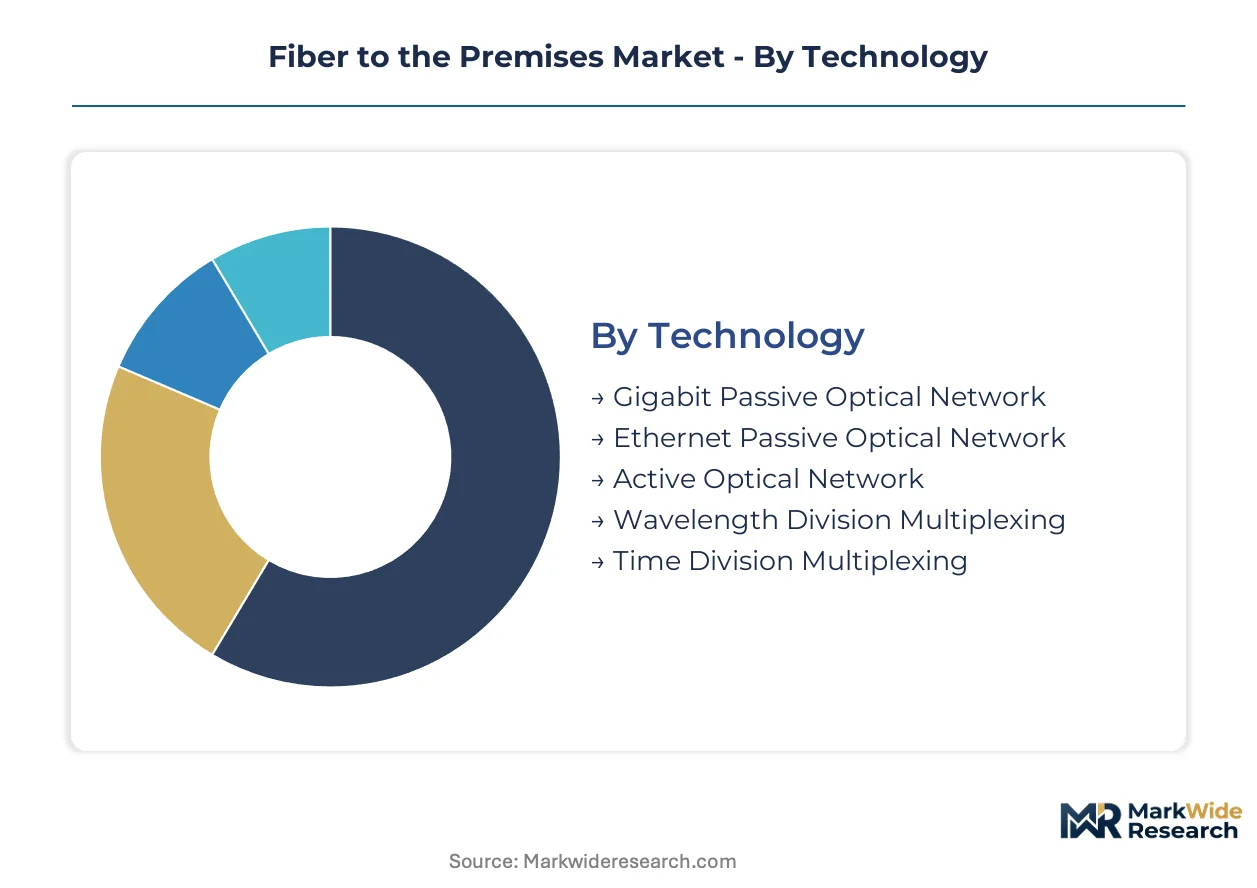
Segmentation in the Fiber to the Premises market reveals how deployment economics and performance requirements fragment procurement patterns across network architectures. Technology choices determine passive versus active infrastructure investments, while application tiers separate mass-market residential builds from high-margin enterprise and government contracts.
Technology:
Standalone optical transport systems dominate metro and long-haul interconnects, while embedded PON architectures integrate directly into last-mile distribution networks with splitters deployed in field enclosures.
- Gigabit Passive Optical Network:Employs passive optical splitters to serve 32-64 subscribers from a single optical line terminal port, eliminating powered intermediate nodes. Indian operators under BharatNet Phase III specifications source GPON equipment for rural village council deployments where electrical grid reliability remains intermittent.
- Ethernet Passive Optical Network:Delivers dedicated bandwidth per subscriber through point-to-multipoint architecture with active switching at the distribution point. Japanese carriers in Tokyo and Osaka metropolitan areas specify EPON for business park deployments requiring deterministic latency below 5 milliseconds.
- Active Optical Network:Dedicated fiber strands run directly from central office to each premises without splitting, maximizing bandwidth and security. Financial institutions in Frankfurt and Singapore specify active Ethernet for trading floor connectivity where jitter tolerance approaches zero.
- Wavelength Division Multiplexing:Multiple optical carrier signals multiplex onto a single fiber using different wavelengths. Data center operators in Northern Virginia and Amsterdam deploy coarse WDM for inter-facility links exceeding 40 kilometers.
- Time Division Multiplexing:Allocates discrete time slots to multiple data streams across shared fiber infrastructure. Legacy cable operators in the United States Midwest utilize TDM overlays during hybrid fiber-coaxial migration phases.
Volume placements concentrate in Gigabit Passive Optical Network; the faster expansion belongs to Wavelength Division Multiplexing.
Product Type:
Cost tiering separates customer-premises equipment absorbing retail price pressure from central office gear capturing multi-year depreciation schedules.
- Optical Network Terminal:Subscriber-side device terminating fiber and converting optical signals to electrical Ethernet or POTS interfaces. Housing associations across France and Germany procure ONTs in thousand-unit volumes for multi-dwelling unit retrofits under open-access mandates.
- Optical Line Terminal:Central office aggregation equipment managing upstream traffic from hundreds of subscriber endpoints. Indian state-owned carriers deploy OLT chassis in district headquarters to aggregate BharatNet rural connectivity.
- Optical Distribution Frame:Physical termination and cross-connect infrastructure for fiber management in central offices and field cabinets. United States rural electric cooperatives specify weatherized ODF enclosures for pole-mounted installations in Appalachian terrain.
- Fiber Optic Cable:Single-mode and bend-insensitive fiber assemblies spanning aerial, underground, and submarine deployment environments. Prysmian and Corning supply loose-tube cables for United States BEAD program recipients requiring 20-year operational lifespans.
- Fiber Access Terminal:Outdoor enclosure housing splitters, splice trays, and patch panels at network distribution points. Municipal utilities in Germany specify FAT units with IP68 ratings for sidewalk vault installations.
Shipments cluster in Fiber Optic Cable; Optical Network Terminal climbs the fastest as subscriber activation accelerates.
Application:
Margin structure separates residential mass-market deployments from contractual service-level guarantees commanding premium pricing.
- Residential Broadband:Mass-market fiber-to-the-home deployments delivering symmetric gigabit service to single-family and multi-dwelling units. United States internet service providers prioritize residential overbuilds in suburban markets where FCC BEAD subsidies de-risk capital deployment.
- Business Connectivity:Dedicated fiber links with contractual uptime guarantees and managed router provisioning. Enterprise customers in London's Square Mile specify diverse-path fiber rings with sub-50 millisecond failover.
- Government Networks:Secure fiber infrastructure for administrative, defense, and emergency communications. India's National Informatics Centre mandates dedicated fiber for district magistrate offices under e-Governance expansion.
- Educational Institutions:Campus-wide fiber backbones connecting academic buildings, research facilities, and dormitories. Research universities in the United States specify 100 Gbps fiber links between supercomputing centers and storage arrays.
- Data Center Interconnects:High-capacity fiber spans linking hyperscale facilities within metro regions or across continental distances. Cloud operators in Dublin and Frankfurt deploy 400G ZR coherent optics for inter-campus replication.
Revenue concentrates in Residential Broadband; Data Center Interconnects gains share fastest on hyperscale expansion.
End User:
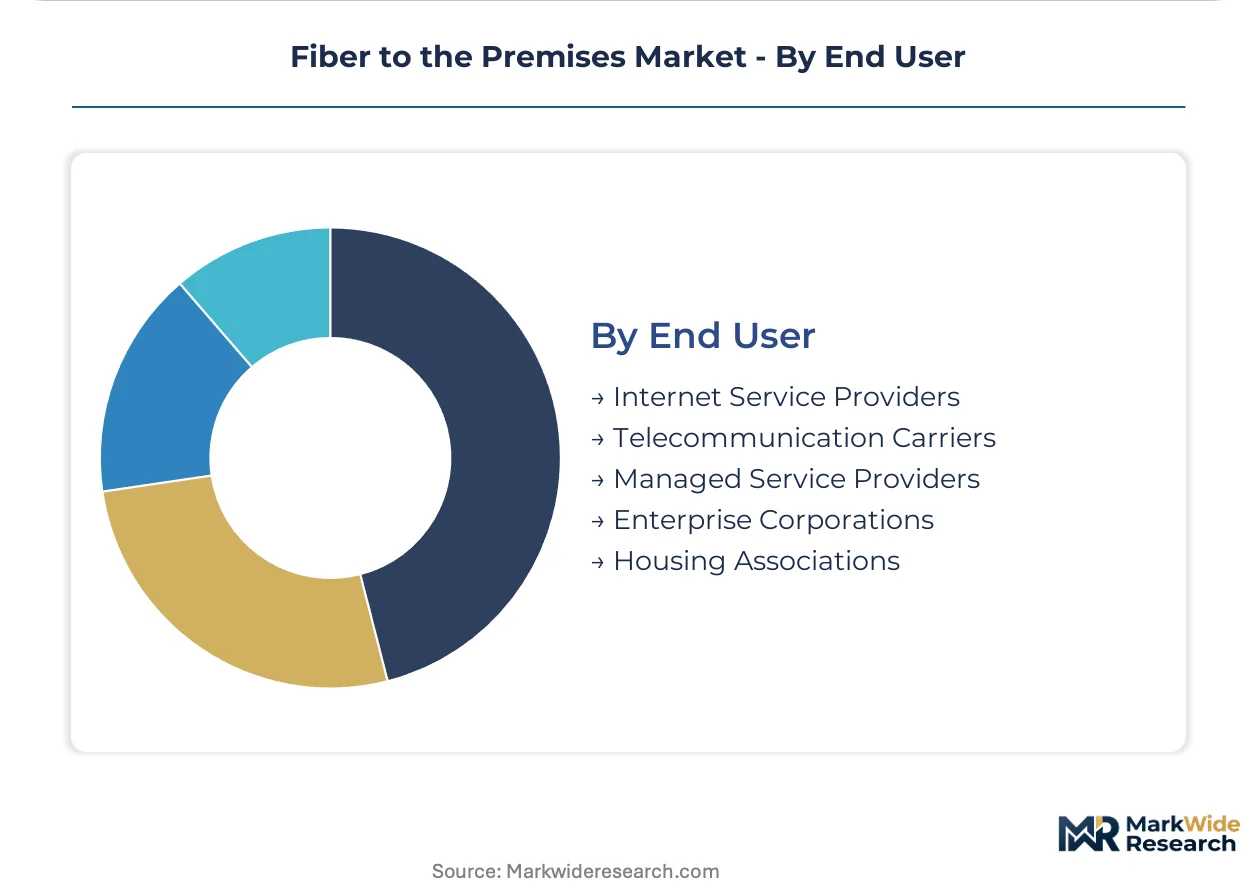
Procurement sophistication separates capital-rich carriers from price-sensitive housing associations managing constrained infrastructure budgets.
- Internet Service Providers:Competitive retail operators building fiber plant to capture subscriber market share from incumbents. Regional ISPs in the United States Southeast negotiate design-build-operate contracts with 15-year terms to transfer construction risk.
- Telecommunication Carriers:Incumbent operators with legacy copper estates upgrading infrastructure to retain subscriber bases. Deutsche Telekom and Orange specify XGS-PON overlays to extend fiber capacity without trenching replacement.
- Managed Service Providers:Third-party operators delivering fiber-based connectivity as bundled service offerings. United Kingdom MSPs procure wholesale dark fiber from Openreach to resell under white-label arrangements.
- Enterprise Corporations:Large organizations procuring dedicated fiber for campus networks and cloud connectivity. Automotive manufacturers in Stuttgart and Wolfsburg deploy private fiber rings linking engineering centers to production facilities.
- Housing Associations:Non-profit and cooperative entities retrofitting multi-tenant buildings with fiber infrastructure. Dutch housing corporations utilize EU recovery fund grants for social housing fiberization in Rotterdam and The Hague.
Capital deployment concentrates with Telecommunication Carriers; Housing Associations expand most quickly on subsidy program eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors fiber deployment velocity in India, where BharatNet Phase III mandates optical connectivity to 600,000 village councils. The United States, Germany, Japan, and South Korea concentrate distinct regulatory frameworks and infrastructure investment patterns.
United States
Rural electric cooperatives in Appalachia and the Midwest are leveraging existing pole attachments for fiber overbuilds. The FCC's Broadband Equity Access and Deployment program conditions $42.45 billion in funding on minimum 100 Mbps symmetrical speeds. Municipal utilities in Tennessee and Kentucky are executing design-build-operate contracts with 15-20 year terms.
Germany
Deutsche Telekom and Orange specify XGS-PON overlays to extend fiber capacity without trenching replacement infrastructure. The EU Green Deal's digital component mandates energy efficiency disclosures for network equipment. Industrial clusters in Frankfurt and Stuttgart deploy active Ethernet for financial trading floors requiring sub-millisecond latency.
India
State-owned carriers deploy OLT chassis in district headquarters to aggregate BharatNet rural connectivity. The Department of Telecommunications enforces milestones that compel carriers to prioritize optical builds. Sterlite Technologies and regional suppliers concentrate manufacturing in Pune and Chennai to serve village council deployments.
Japan
NTT and KDDI are converging passive optical networks with software-defined access control for automated fault detection. METI guidelines favor low-power optical line terminals over legacy active Ethernet switches. Tokyo and Osaka metropolitan areas specify EPON for business park deployments requiring deterministic latency.
South Korea
SK Broadband and KT Corporation are deploying converged hardware-software systems to reduce operational expenditure per subscriber. The national broadband plan mandates gigabit connectivity as a baseline utility. Seoul's dense urban fabric supports split-ratio economics that maximize passive optical network efficiency.
Fiber to the Premises Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology integration depth and geographic coverage breadth. The vendor base stratifies into three tiers: integrated preform-to-cable manufacturers, active equipment specialists bundling software management layers, and regional cable fabricators competing on logistics proximity. Strategic archetypes include vertical integrators controlling optical fiber preform supply, neutral host operators capturing wholesale revenue under open-access mandates, and design-build-operate contractors transferring construction risk from capital-constrained utilities. Dominant competitive moves encompass strategic partnerships between cable manufacturers and rural electric cooperatives, plus technology licensing arrangements for XGS-PON migration without plant replacement.
Among North American integrated manufacturers, Corning Inc. and CommScope occupy positions spanning preform production through subscriber premises equipment. Prysmian Group anchors European supply architecture through dense distribution networks. Sterlite Technologies represents the India-centric archetype, positioned to capture concentrated demand from BharatNet rural deployments. These three entities exemplify how geographic alignment with subsidy program jurisdictions determines competitive positioning.
| Leading Market Players |
|---|
| OFS |
| Superior Essex Communications |
| Corning Inc. |
| Belden Inc. |
| Sterlite Technologies |
| Prysmian Group |
| AFL |
| Panduit |
| CommScope |
| Others |
Cost & Logistics Intelligence
Optical fiber preform costs cascade through the value chain from four dominant suppliers into tiered equipment pricing, with BharatNet subsidy eligibility compressing margins at the rural deployment tier while data center interconnects sustain premium positioning.
Pricing Analysis
Throughput-based pricing anchors fiber infrastructure procurement, with service-level guarantees commanding substantial premiums over best-effort residential tiers. Three-tier pricing structure across premium, standard, and economy levels separates active Ethernet with deterministic latency from GPON mass-market deployments and legacy copper transition bundles. Pricing pressure stems from fixed wireless access substitution in suburban fringe markets where millimeter-wave alternatives undercut trenching economics. Rural electric cooperatives exhibit highest price sensitivity due to capital constraints, while hyperscale cloud operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
CE marking and FCC equipment authorization gate entry for optical line terminals and network terminals destined for regulated markets. Manufacturing concentrates in China, the United States, and India, with Corning and Prysmian controlling preform supply that feeds cable fabrication. The supply chain draws from silica sand, specialty gases, and rare-earth dopants for fiber amplification. Single-source vulnerability in optical preform production exposes deployers to allocation risk during subsidy-driven demand surges. Distribution runs through carrier-direct procurement for central office gear and distributor networks for customer-premises equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Fiber to the Premises market functions as a cost-of-compliance arena where FCC BEAD program eligibility requirements and EU Green Deal energy efficiency mandates erect regulatory moats that disadvantage non-compliant suppliers.
For Market Incumbents: Deploy XGS-PON overlay technology to extend existing fiber plant capacity without civil works replacement, preserving capital efficiency against greenfield overbuilders. Consolidate technician training pipelines through community college partnerships to address fusion splicing workforce scarcity. Neutralize fixed wireless substitution threats by accelerating suburban deployment timelines through design-build-operate contracting structures. For New Entrants and Emerging Players: Rural electric cooperatives represent the most penetrable channel archetype, given their existing pole attachments and customer billing relationships in Appalachian and Midwestern territories. Target housing association retrofit segments in France and Germany where open-access mandates create wholesale revenue streams without retail subscriber acquisition costs. Pursue software-defined access control bundling as a differentiated go-to-market angle against hardware-centric incumbents. For Investors and Strategic Acquirers: XGS-PON equipment certification announcements from tier-one carriers are the leading indicator that upgrade cycles are accelerating and replacement demand is firming. Five-to-ten year viability favors neutral host operators with open-access infrastructure positions in regulated European markets. Acquisition focus should center on regional cable fabricators with logistics proximity to BharatNet Phase III deployment zones.| Strategic Initiative | Industry Significance |
|---|---|
| XGS-PON Technology Migration | Enables 10 Gbps symmetrical service without fiber plant replacement, preserving capital deployed under prior subsidy rounds. |
| Open-Access Infrastructure Positioning | Captures wholesale revenue streams under France and Germany unbundling mandates, decoupling returns from retail subscriber economics. |
| Design-Build-Operate Contracting | Transfers construction risk to engineering firms while locking in 15-20 year revenue streams for rural electric cooperatives. |
| Fusion Splicing Workforce Development | Addresses technician scarcity inflating labor costs and extending project timelines across North American and Western European markets. |
| Software-Defined Access Integration | Reduces operational expenditure per subscriber through automated fault detection and real-time bandwidth provisioning. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with network planning executives at telecommunication carriers, procurement leads at rural electric cooperatives, and deployment managers at design-build-operate contractors. FCC BEAD program documentation, EU Green Deal implementation guidance, and BharatNet Phase III milestone reports provided policy-side validation. Bottom-up subscriber activation models and top-down infrastructure spend estimates were triangulated to converge volume and value figures.
Granularity-level modeling operated at technology-architecture, product-type, and application-tier dimensions, with geographic splits calibrated to subsidy program jurisdictions rather than continental aggregates. CAGRs were derived from fitted trend analysis across the projection horizon, incorporating XGS-PON migration curves, fixed wireless substitution elasticities, and labor cost inflation assumptions specific to fusion splicing technician markets.
Caveats apply where subsidy clawback provisions, open-access mandate enforcement intensity, or optical preform supply allocation decisions could materially shift the outlook. Forecasts embed assumptions regarding right-of-way permitting timelines and workforce training pipeline throughput. A model refresh is warranted upon material change in FCC BEAD disbursement schedules or BharatNet Phase III milestone acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Network Management Solutions Market
Network Technology
Global Active Network Management Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
Network Emulator Market
Network Technology
Carrier Routing Equipment Market
Network Technology
Enterprise Routers Market
Network Technology
GCC Set-Top Box Market
Network Technology
Microduct Market
Network Technology
ISP Management Systems Market
Network Technology
Wi-Fi Router Market
Network Technology
Wimax Solutions Market
Network Technology
Global Cloud Managed Wi-Fi Market
Network Technology
Self-Healing Networks Market
Network Technology
Mobile Network Optimization Market
Network Technology
Router and Switch Market