
 Advanced Gas Generators Sales Market | 2026-2036
Advanced Gas Generators Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Gas Generators Sales Market Insights
The shift from diesel-dominant backup architectures toward natural gas and dual-fuel systems is tilting procurement specifications across critical infrastructure sectors. General Electric leverages its aeroderivative turbine heritage to anchor utility-scale contracts in markets prioritizing rapid ramp rates. Siemens competes through integrated power island solutions that bundle generators with grid stabilization software. Mitsubishi Power specializes in hydrogen-ready gas turbine frames that extend product lifecycles amid fuel-transition planning.
Advanced gas generators are reciprocating or turbine-based prime movers engineered to convert gaseous fuels into electrical output with thermal efficiencies typically ranging from 35% to 45% in modern combined-cycle configurations, serving industrial, commercial, and emergency power applications where grid reliability is insufficient. Standby generators dominate revenue contribution due to mandatory backup requirements for healthcare and data center facilities, while portable generators represent the fastest-expanding category as construction and remote mining operations decentralize power procurement. Natural gas holds the largest fuel-type share where pipeline infrastructure exists, though biofuel compatibility is gaining specification traction in markets with renewable portfolio obligations.
The US EPA enforces Tier 4 final emissions standards for non-road and stationary engines, while the EU F-Gas Regulation and CE marking frameworks constrain refrigerant-based cooling integrations in packaged generator sets. China's MEE implements GB standards for stationary gas engine emissions that affect import eligibility and local manufacturing compliance. Stakeholders must monitor hydrogen blending mandates and carbon border adjustment mechanisms as these frameworks redefine generator fuel specifications and cross-border equipment certification requirements.
Market Dynamics
Data center operators are forcing generator specifications toward sub-15-minute startup times and nitrogen oxide emissions below 0.5 grams per brake horsepower-hour as utility interconnection queues stretch to 36 months in key markets. This operational pressure is compressing procurement cycles and disqualifying legacy diesel architectures from new-build specifications.
Growth Catalysts
- EPA Tier 4 Final compliance deadlines:Stationary engine operators in the United States face mandated retrofit timelines that accelerate natural gas generator replacements across healthcare and municipal infrastructure.
- Data center load volatility:Hyperscale facilities in Northern Virginia, Frankfurt, and Singapore are expanding on-site generation fleets to manage 40% year-over-year compute demand swings independent of grid stability.
- Hydrogen blending pilot programs:Germany's H2Global initiative and California's SB 100 directives are creating certified demand for turbine frames engineered to 30% hydrogen co-firing by 2030.
Market Restraints
- Stainless steel and superalloy input volatility:Inconel 718 and 347H stainless price swings of 18-24% annually compress generator OEM margins and extend quoting validity periods to 45 days.
- Pipeline infrastructure gaps:Remote mining operations in Western Australia and the Canadian Arctic cannot access natural gas distribution, forcing continued diesel dependence despite emissions penalties.
- Grid interconnection queue paralysis:ERCOT and PJM interconnection study timelines exceeding 24 months are freezing commercial-industrial generator deployment decisions in Texas and Mid-Atlantic load zones.
Strategic Opportunities
- India's CEA grid code revisions:Mandatory spinning reserve requirements for renewable-rich states are creating procurement mandates for fast-ramp gas turbines in Gujarat, Rajasthan, and Tamil Nadu.
- Modular containerized architectures:Skid-mounted 2-10 MW units are penetrating construction and disaster response applications where permanent installation is economically unviable.
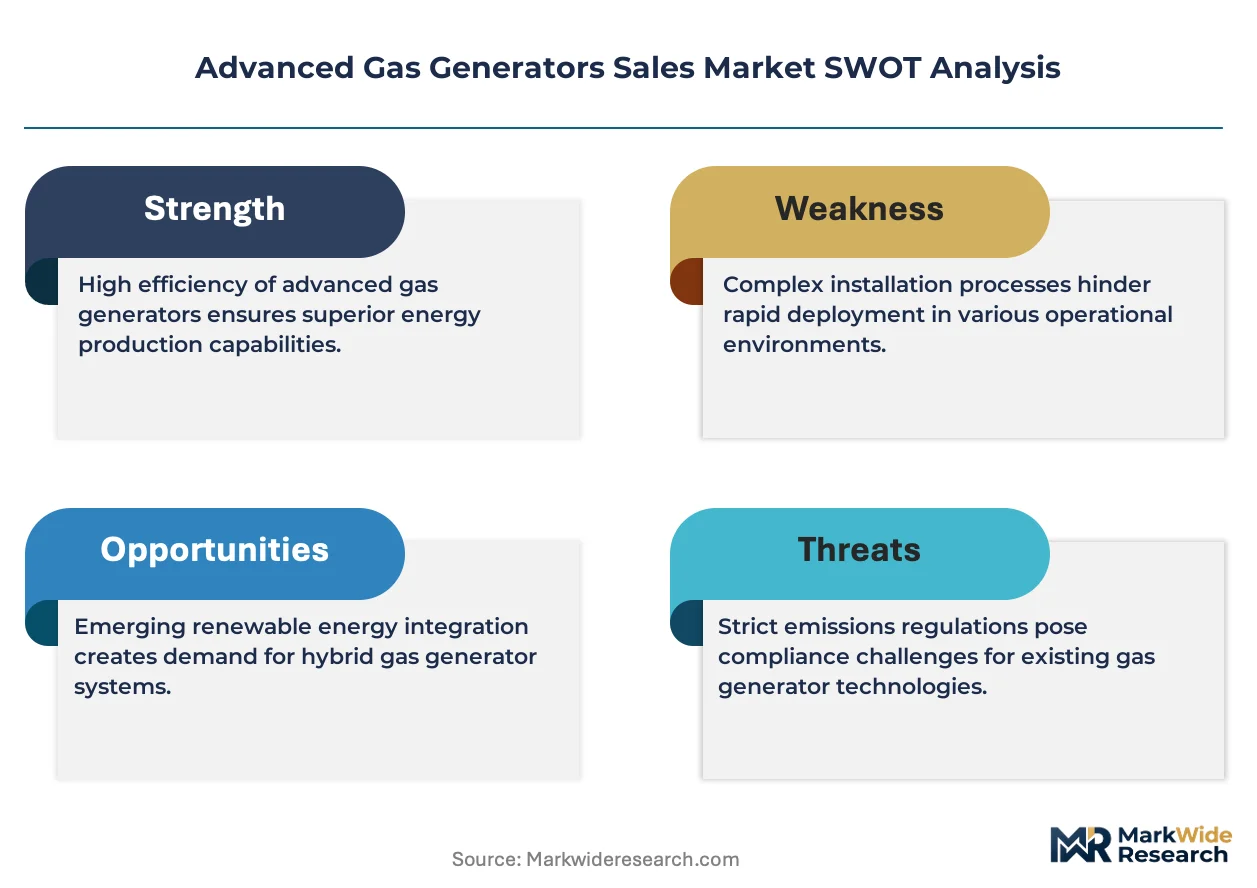
- EU F-Gas Regulation phase-down:Refrigerant-based cooling system constraints are accelerating demand for air-cooled generator packages with alternative thermal management.
Industry Challenges
- Combustion engineer scarcity:Specialized expertise in lean-premixed burner design and dynamic modeling commands 35% salary premiums, constraining OEM expansion timelines.
- Multi-fuel certification complexity:Dual-fuel engines require separate EPA, MEE, and CE marking test cycles that extend product launch timelines by 14-18 months.
- Legacy SCADA integration friction:New digital turbine control systems face protocol incompatibilities with 1990s-era plant distributed control systems, forcing middleware expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Gas Generators Sales Market |
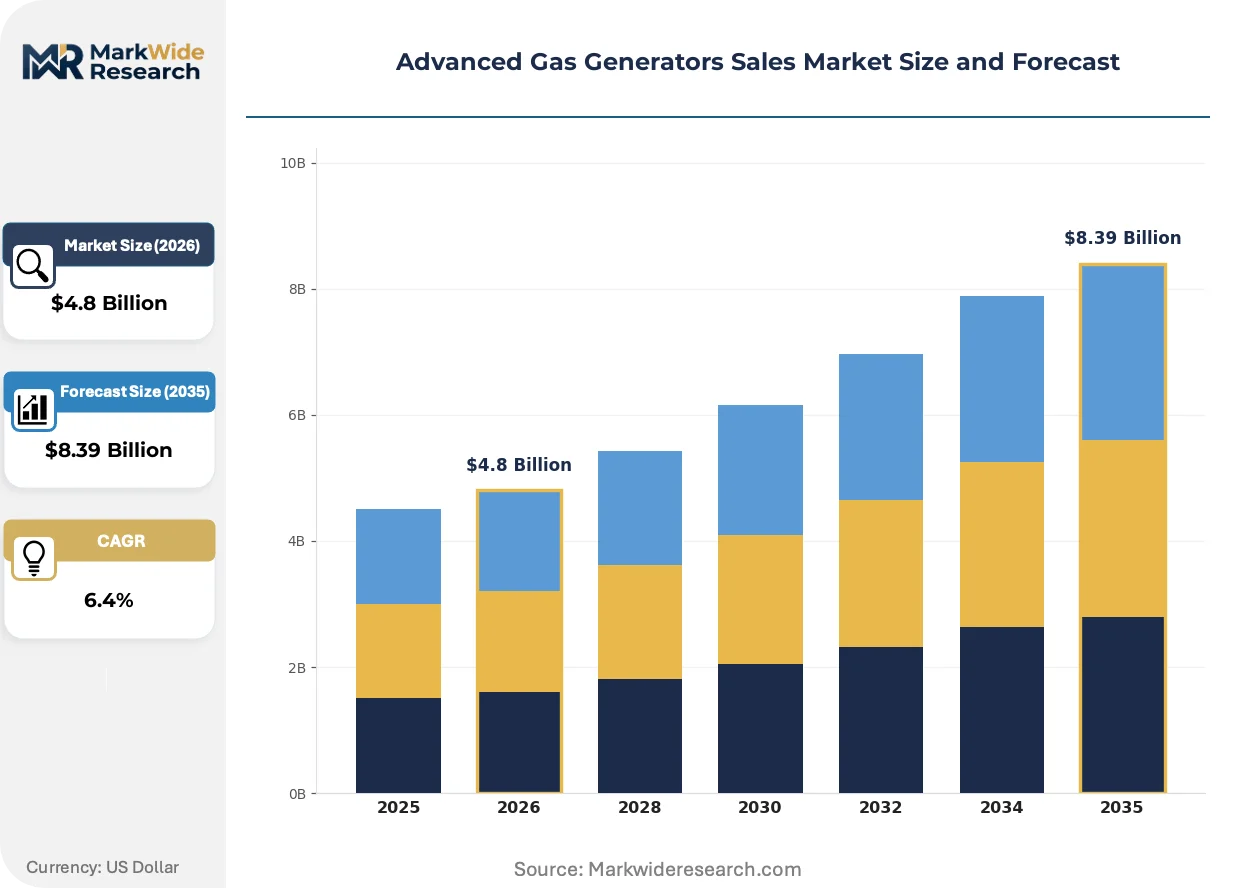
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Industrial Generators, Marine Generators End User: Construction, Mining, Residential, Power Plants Fuel Type: Natural Gas, Propane, Diesel, Biofuel Application: Emergency Power, On-Site Energy, Backup Power, Primary Power |
| Companies Covered | General Electric, Siemens, Rolls-Royce, Caterpillar, Cummins, Mitsubishi Power, Kawasaki Heavy Industries, Wartsila, Generac Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Gas Generators Sales Market Trends and Innovations
Aeroderivative turbine architectures and additive manufacturing are compressing development cycles while hydrogen combustion research rewrites fuel flexibility specifications across utility and industrial procurement.
Additive manufacturing of turbine blades through direct metal laser sintering is reducing cooling channel complexity constraints that previously limited thermal efficiency gains. Siemens Energy and Mitsubishi Power are qualifying nickel superalloy components with internal geometries impossible through conventional casting. This capability is rendering obsolete the traditional five-year development cycles for incremental efficiency improvements in heavy-frame turbines.
China's MEE is enforcing GB 36886-2018 emissions standards for stationary gas engines that tighten particulate matter and hydrocarbon thresholds effective 2024. Domestic OEMs including Harbin Electric and Dongfang Electric are accelerating indigenous combustion system development to avoid import dependency. Foreign manufacturers are establishing localized testing facilities in Shanghai and Xi'an to maintain market access under the evolving certification regime.
Power purchase agreement structures are unbundling generator hardware from long-term service contracts that previously locked operators into OEM maintenance networks. Industrial buyers in Texas, Alberta, and Queensland are negotiating separate procurement for major overhauls and parts supply, compressing OEM service margins by 12-18%. This disintermediation is most visible in the Permian Basin oilfield power sector, where independent service providers now capture 40% of maintenance expenditure on gas turbine assets.
Advanced Gas Generators Sales Market Segmentation
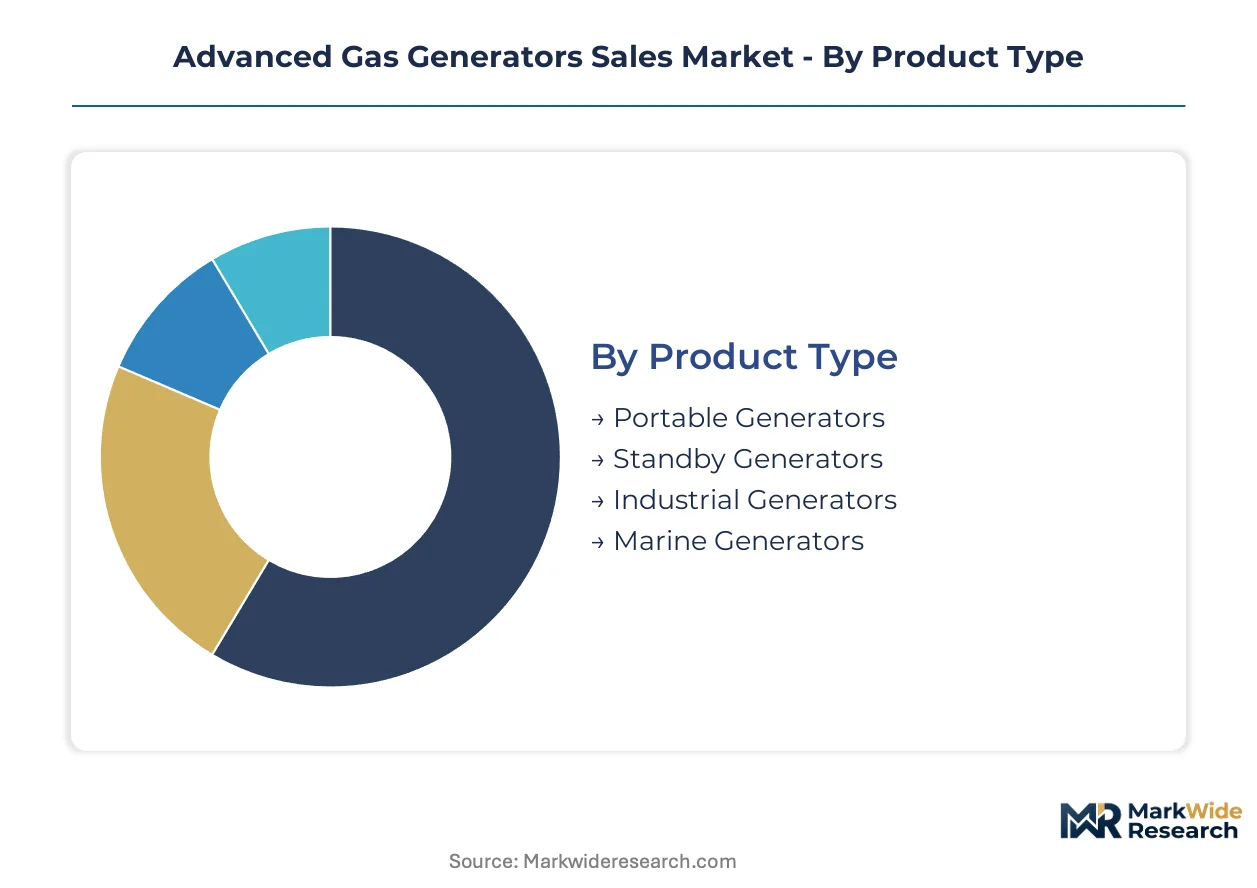
Advanced gas generator procurement specifications diverge sharply across deployment contexts, from emergency healthcare backup to continuous industrial baseload. Fuel infrastructure availability, emissions compliance thresholds, and load profile volatility collectively determine segment-level demand concentration.
Product Type:
Mature standby architectures dominate revenue contribution while portable formats emerge fastest from decentralized construction and remote resource extraction.
- Portable Generators:Compact, towable or skid-mounted units ranging from 10 kW to 500 kW designed for temporary deployment without fixed installation. Mining contractors in Western Australia and construction firms across Texas shale plays are expanding rental fleets to bypass 24-month grid interconnection delays. This segment is gaining share fastest.
- Standby Generators:Fixed-installation systems engineered for automatic transfer switching within 10 seconds of grid failure, typically 100 kW to 2 MW capacity. Hospital systems in Germany and data center campuses in Northern Virginia face mandatory backup requirements under NFPA 110 and EU data center efficiency directives. This segment handles the majority of throughput.
- Industrial Generators:Heavy-frame reciprocating engines and aeroderivative turbines exceeding 5 MW for continuous or prime power applications.
- Marine Generators:Seaworthy enclosures with vibration isolation and corrosion-resistant coatings for offshore platforms and vessel propulsion.
Standby generators anchor procurement volumes in regulated critical infrastructure; portable formats climb fastest on mobile workforce expansion.
End User:
Cost tier separation between capital-intensive permanent installations and operational-expense-driven rental models shapes customer procurement behavior.
- Construction:Project-based demand for temporary power during grid extension lags, with contractors favoring rental agreements over ownership to match 6-18 month build cycles. German and UAE infrastructure stimulus programs are accelerating fleet turnover.
- Mining:Continuous operations in isolated geographies requiring 1-10 MW prime power where pipeline infrastructure is absent. Canadian Arctic and Pilbara Basin operators face diesel dependence despite carbon penalties, constraining fuel switching timelines. This segment maintains the steepest expansion trajectory.
- Residential:Single-family and multi-unit standby systems triggered by outage frequency in storm-prone US Gulf Coast and wildfire-vulnerable California markets.
- Power Plants:Utility-scale combined-cycle and peaking turbine installations for grid stabilization and renewable firming.
Power plants command the largest unit values; mining applications expand most quickly on resource extraction decentralization.
Fuel Type:
Application context determines fuel specification, with pipeline access dictating natural gas feasibility and emissions mandates accelerating biofuel qualification.
- Natural Gas:Pipeline-delivered methane with lower carbon intensity than liquid hydrocarbons, dominating where distribution infrastructure exists. US EPA Tier 4 Final compliance deadlines are accelerating displacement of diesel standby fleets in healthcare and municipal buildings.
- Biofuel:Renewable natural gas and hydrogen-blended methane compatible with modified combustion systems. California SB 100 mandates and Germany's H2Global initiative are certifying 30% hydrogen co-firing specifications for turbine frames. This fuel category is ascending fastest on portfolio obligation pressures.
- Propane:Liquefied petroleum gas stored on-site for locations beyond pipeline networks, common in rural residential and remote commercial settings.
- Diesel:Liquid fuel for portable and marine applications where gaseous fuel storage is impractical, facing regulatory compression in stationary applications.
Natural gas captures the dominant share where infrastructure permits; biofuel climbs fastest on decarbonization procurement mandates.
Application:
Customer type stratification separates life-safety critical loads from economic optimization opportunities.
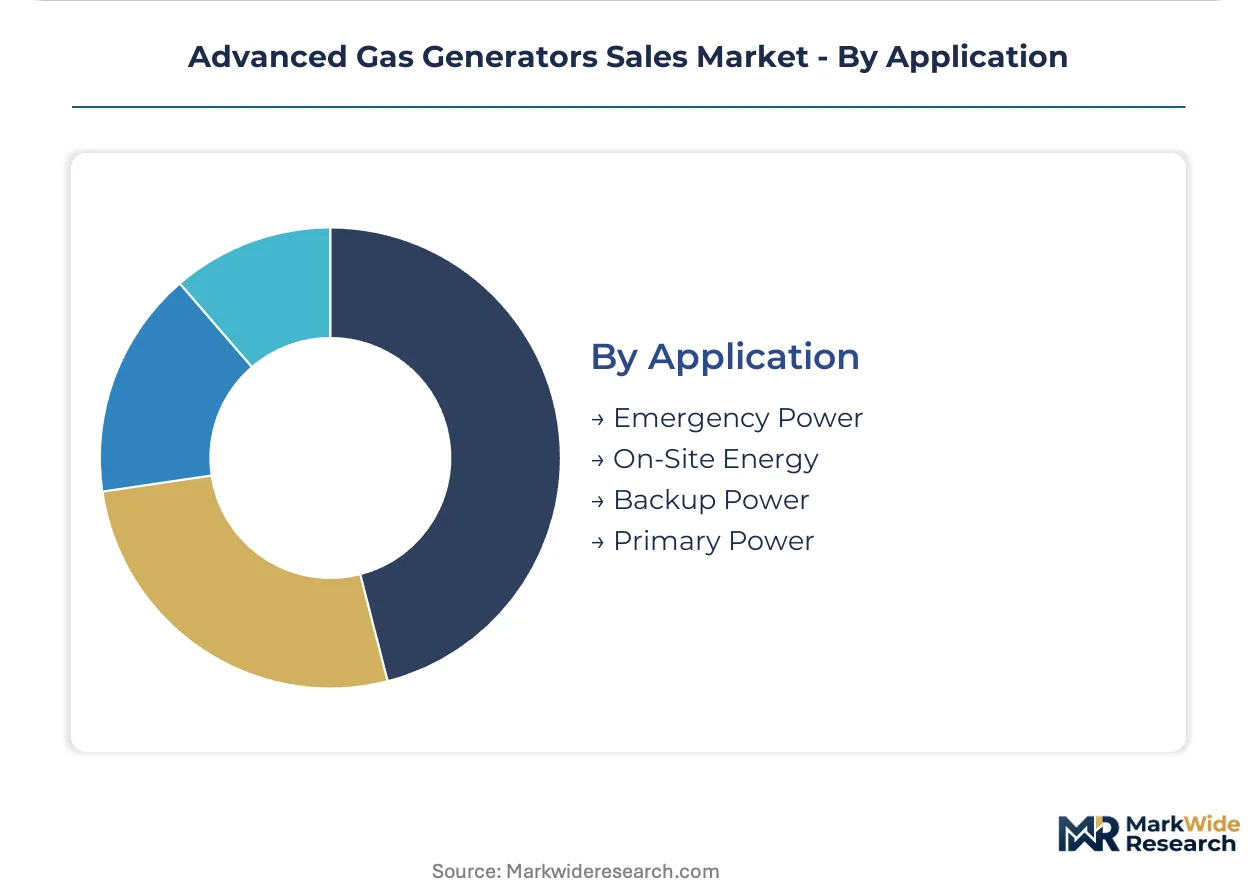
- Emergency Power:Life-safety systems requiring automatic startup within 10 seconds for healthcare, aviation, and telecommunications infrastructure. US hospital accreditation standards and EU critical infrastructure directives enforce minimum 96-hour fuel autonomy. This application commands the largest procurement volumes.
- Backup Power:Commercial and industrial load protection against revenue loss from outages, with less stringent startup windows than emergency classifications. Data center operators in Singapore and Frankfurt are expanding on-site generation to manage 40% year-over-year compute demand swings. This application is expanding most rapidly.
- On-Site Energy:Distributed generation for industrial facilities seeking energy cost arbitrage or combined heat and power efficiency.
- Primary Power:Continuous prime mover operation where grid connection is unavailable or economically unviable.
Emergency power specifications drive the majority of regulatory-mandated procurement; backup power applications gain share fastest on data center load volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center operators and industrial facilities in the United States, China, and Germany account for the majority of procurement volume, with each market shaped by distinct regulatory deadlines and infrastructure constraints.
United States
Hyperscale data center campuses in Northern Virginia and Texas are expanding on-site generation fleets to manage 36-month utility interconnection queues. EPA Tier 4 Final compliance deadlines are accelerating natural gas generator replacements across healthcare and municipal infrastructure. ERCOT load zones in Texas face deployment freezes as interconnection study timelines exceed 24 months.
Germany
Industrial facilities in Bavaria and North Rhine-Westphalia are procuring hydrogen-ready turbine frames under the H2Global initiative's 30% co-firing certification pathway. The EU F-Gas Regulation is constraining refrigerant-based cooling integrations in packaged generator sets. Frankfurt's data center cluster is mandating sub-15-minute startup specifications for backup power systems.
China
Grid modernization investments in Guangdong and Jiangsu provinces are driving demand for fast-ramp gas turbines to firm renewable output. MEE enforcement of GB 36886-2018 emissions standards is tightening particulate matter thresholds for stationary gas engines. Shanghai and Xi'an are hosting localized testing facilities established by foreign manufacturers to maintain market access.
India
CEA grid code revisions are mandating spinning reserve requirements for renewable-rich states including Gujarat, Rajasthan, and Tamil Nadu. Domestic OEMs Harbin Electric and Dongfang Electric are accelerating indigenous combustion system development. Mumbai-Pune industrial corridor operators are evaluating dual-fuel architectures to manage natural gas supply intermittency.
Australia
Remote mining operations in Western Australia's Pilbara Basin cannot access pipeline infrastructure, forcing continued diesel dependence despite carbon penalties. Modular containerized generators are penetrating construction applications in Queensland's infrastructure stimulus zones. Perth-based contractors are expanding rental fleets to bypass grid extension delays in the country's northwest.
Advanced Gas Generators Sales Market Competitive Landscape
Channel-controlling players compete with product-specialist players across utility-scale, industrial, and portable generator segments. The market structure tilts toward consolidated positions among aeroderivative turbine manufacturers and fragmented competition in reciprocating engine categories. Two strategic archetypes dominate: integrated power island providers bundling hardware with grid software, and combustion-system specialists focused on fuel-flexible architectures. Competitive moves center on hydrogen combustion research partnerships and additive manufacturing qualifications for nickel superalloy components.
Among diversified industrial conglomerates, General Electric, Siemens, and Mitsubishi Power occupy positions spanning aeroderivative heritage, integrated solutions, and hydrogen-ready frame development respectively. General Electric exemplifies the rapid-ramp utility-scale archetype through its turbine lineage. Siemens represents bundled power island offerings combining generation assets with stabilization software. Mitsubishi Power anchors the fuel-transition planning segment with hydrogen co-firing specifications. These three entities collectively illustrate the competitive vectors reshaping procurement specifications across data center, utility, and industrial buyer segments.
| Leading Market Players |
|---|
| General Electric |
| Siemens |
| Rolls-Royce |
| Caterpillar |
| Cummins |
| Mitsubishi Power |
| Kawasaki Heavy Industries |
| Wartsila |
| Generac Power Systems |
| Others |
Pricing and Supply Chain Analysis
Harbin and Shanghai manufacturing clusters anchor turbine component capacity, with localized production dynamics translating directly into OEM quoting leverage over foreign competitors facing import certification delays. Price formation in this market tracks nickel superalloy input volatility alongside hydrogen-ready engineering premiums.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange nickel and Inconel 718 spot prices dominate utility-scale procurement, with 45-day validity windows reflecting raw material uncertainty. Three-tier pricing structure across aeroderivative, industrial frame, and portable skid-mounted tiers separates rapid-ramp specifications from standard backup configurations. Cost compression in the portable segment is intensifying because rental fleet operators are consolidating procurement volumes. Data center buyers show lowest price sensitivity due to 36-month interconnection queue penalties, while construction contractors negotiate aggressively on 6-18 month project cycles.
Supply Chain Analysis
Contract manufacturing concentrates among Mitsubishi Heavy Industries' Nagasaki turbine works, Siemens Energy's Berlin gas turbine plant, and GE's Greenville aeroderivative facility, with each anchoring distinct technology lineages. Nickel superalloy forgings draw from Japanese and German specialty steel mills, while precision casting for cooled turbine blades rests on single-source suppliers in Aichi Prefecture. Single-source vulnerability around additive manufacturing-qualified nickel components creates qualification bottlenecks for new entrants. Distribution runs through OEM-direct channels for utility contracts and rental fleet aggregators for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as hydrogen-ready turbine specifications create interoperability lock-in across utility and data center procurement. The shift from hardware-only sales to bundled service contracts redefines margin capture for incumbents and entry barriers for challengers.
For Market Incumbents: Insulate service contract attach rates by embedding predictive maintenance software into turbine control architectures, countering independent service provider encroachment in the Permian Basin and Queensland oilfield power segments. Accelerate additive manufacturing qualification for nickel superalloy components to compress development cycles below the 14-18 month multi-fuel certification timeline that constrains competitor product launches. For New Entrants and Emerging Players: Build out modular containerized architectures in the 2-10 MW range for Western Australian mining and Canadian Arctic construction, where pipeline infrastructure gaps force diesel dependence and create white-space for fuel-flexible displacement. Target India's CEA-mandated spinning reserve procurement in Gujarat and Rajasthan, where fast-ramp gas turbine demand outpaces domestic OEM combustion system development. For Investors and Strategic Acquirers: Long-term, this sits as a hydrogen infrastructure play because turbine frame certification for 30% co-firing creates stranded asset risk for non-compliant manufacturers and acquisition premiums for hydrogen-ready portfolios. Watch Germany's H2Global auction clearing prices and California SB 100 implementation velocity as signals of certified demand materialization.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Co-firing Certification | Positions turbine frames for Germany's H2Global and California SB 100 procurement mandates. |
| Additive Manufacturing Qualification | Unlocks internal cooling geometries in nickel superalloy blades impossible through conventional casting methods. |
| Modular Containerized Deployment | Addresses Western Australian mining and Queensland construction applications lacking pipeline infrastructure. |
| Independent Service Network Buildout | Captures maintenance expenditure disintermediated from OEM service contracts in Texas and Alberta. |
| Localized Testing Facility Investment | Maintains China market access under MEE GB 36886-2018 emissions enforcement in Shanghai and Xi'an. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, data center infrastructure directors, EPC contractors, and gas turbine maintenance heads, and refined through secondary validation against EIA power plant databases, IEA generation technology reports, FERC interconnection queue filings, and EPA Tier 4 Final compliance records. Bottom-up segmentation modeling across fuel type, capacity tier, and application was triangulated with top-down macro demand projections.
Demand-supply balance modeling anchored forecasts across the projection horizon, with capacity additions tracked by technology segment including aeroderivative turbines, industrial gas engines, and portable skid-mounted units. CAGRs were derived from regression analysis of historical procurement volumes against grid interconnection delays, emissions compliance deadlines, and data center load growth patterns.
Sensitivities concentrate around hydrogen blending mandate implementation timelines, nickel superalloy price volatility, and grid interconnection queue resolution speeds. Quarterly review of EPA enforcement patterns, MEE certification regime updates, and ERCOT/PJM study timeline progression is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Wind Tunnel Fans Market
Power Equipment
Power Recovery Winches Market
Power Equipment
India Nuclear Power Plant Equipment Market
Power Equipment
Cogeneration Equipment Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Variable Frequency Drive (VFD) Market
Power Equipment
Global Power System Simulator Market
Power Equipment
Power Engineering, Procurement, and Construction (EPC) Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
India Power EPC Market
Power Equipment
Australia Power EPC Market
Power Equipment
Global Power Supply Market
Power Equipment
Thailand Power EPC Market
Power Equipment
Nigeria Power EPC Market