
 Gas Turbine Compressor Market | 2026-2036
Gas Turbine Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Turbine Compressor Market Analytics
Direct procurement channels between original equipment manufacturers and utility operators is reshaping how gas turbine compressor contracts are negotiated and fulfilled. General Electric leverages its integrated power plant portfolio to bundle compressor service with long-term maintenance agreements. Siemens Energy anchors its position through regional manufacturing hubs that shorten delivery timelines for European and Middle Eastern buyers. Mitsubishi Heavy Industries competes on advanced aerodynamic designs that extend mean time between overhauls for baseload operators.
A gas turbine compressor is a rotating machine that pressurizes incoming air before combustion, typically achieving pressure ratios between 15:1 and 40:1 in modern heavy-duty frames through multi-stage axial or centrifugal arrangements. Its primary purpose is to deliver sufficient compressed air mass flow to sustain efficient combustion and drive the turbine section for electricity generation or mechanical work. Axial technology dominates the large-frame power generation segment where efficiency and throughput requirements are most stringent. Centrifugal designs occupy niche positions in offshore oil and gas applications where compact footprint and resistance to salt-laden intake air provide operational advantages. Variable geometry systems represent the fastest-growing technology category as operators seek turndown flexibility to balance renewable intermittency.
EPA emissions rules under the Clean Air Act constrain allowable nitrogen oxide and carbon monoxide outputs from gas turbine installations, directly influencing compressor stage design and combustion staging requirements. EU F-Gas Regulation and REACH compliance obligations affect sealing technologies and lubricant formulations used in compressor maintenance protocols. ISO 3977 and IEC standards govern mechanical integrity and grid connection specifications across international project finance requirements. Stakeholders must monitor evolving carbon border adjustment mechanisms and hydrogen blending mandates that will redefine compressor material specifications and performance warranties.
Market Dynamics
Variable geometry compressor systems are forcing a recalibration of maintenance schedules and spare parts forecasting across utility fleets, as operators trade mechanical simplicity for operational flexibility in renewable-heavy grids.
Growth Catalysts
- Combined-cycle capacity expansion:Power generation utilities in the United States are commissioning new peaking plants to bridge intermittency gaps left by solar and wind assets.
- EU F-Gas Regulation compliance:Sealing technology upgrades mandated by tightening leakage-rate thresholds are accelerating compressor refurbishment cycles across European installations.
- Hydrogen blending pilots:Material specification changes for hydrogen-adapted compressor stages are creating incremental demand for retrofit engineering services.
Market Restraints
- Specialized alloy supply concentration:Superalloy forging capacity for high-temperature compressor blades concentrates among a limited supplier base in Germany and Japan.
- EPA New Source Review thresholds:Stringent pre-construction permitting for gas turbine installations in non-attainment zones extends project timelines by 18-36 months.
- Long-haul transport cost structure:Compressor rotor assemblies exceed dimensional limits for standard container shipping, requiring project-specific logistics arrangements.
Strategic Opportunities
- India grid stabilization mandate:Central Electricity Authority directives for flexible generation capacity are opening procurement channels for advanced compressor configurations.
- Digital twin integration:Convergence of physics-based modeling with operational data streams enables predictive maintenance contracts that capture recurring revenue.
- Offshore platform electrification:North Sea oil and gas operators are replacing gas-driven compression with electrically driven units to reduce platform emissions profiles.
Industry Challenges
- Aerodynamicist talent scarcity:Specialized computational fluid dynamics expertise for multi-stage axial design resides with a shrinking cohort of experienced engineers.
- ISO 3977 certification timelines:Mechanical integrity validation protocols for new compressor frame sizes require extended test cell availability at accredited facilities.
- Legacy control system integration:Variable geometry actuator retrofits must interface with decades-old turbine governor architectures without triggering warranty voids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Turbine Compressor Market |
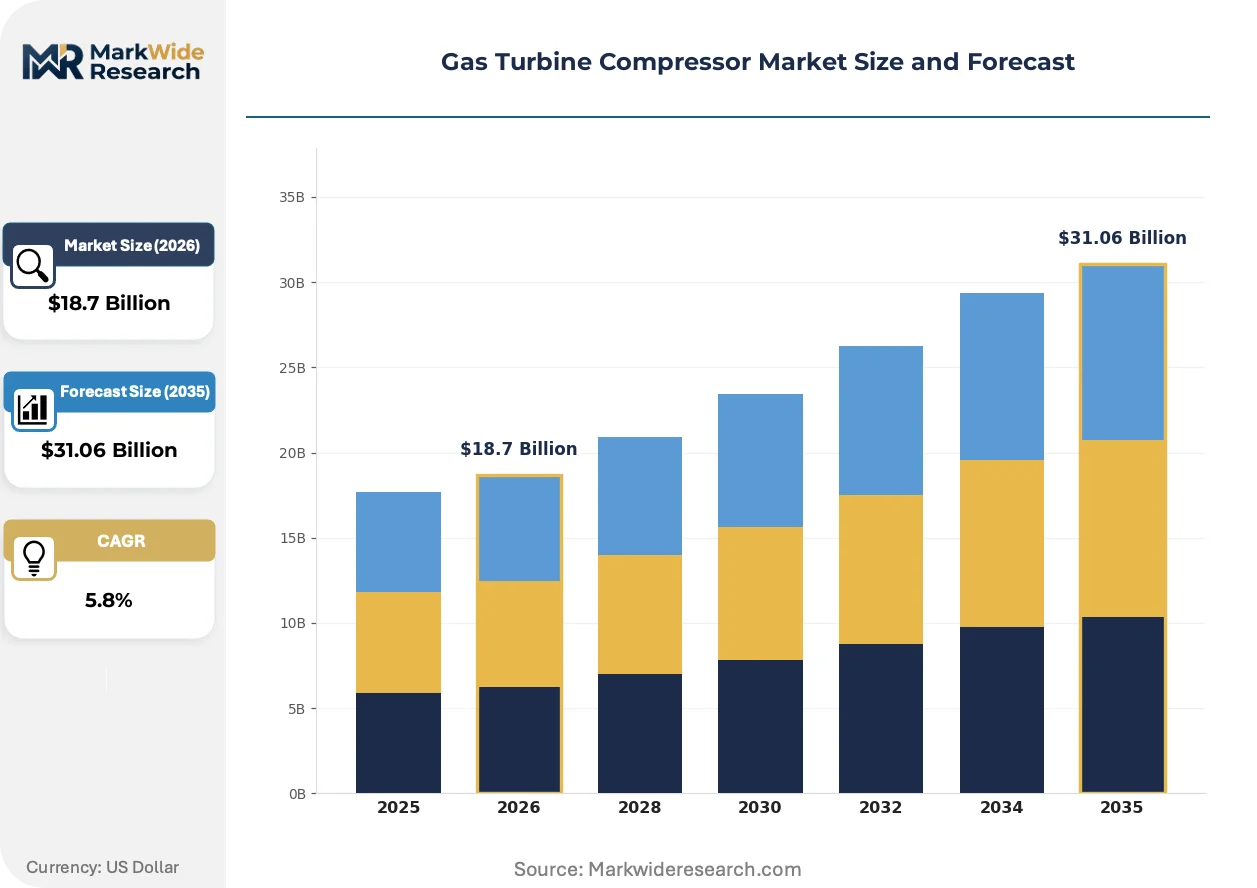
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Inlet Filter, Compressor Stage, Control System, Nozzle End User: Power Generation, Oil & Gas, Marine, Aviation Deployment: Onshore, Offshore, Industrial Facility, Power Plant Technology: Axial, Centrifugal, Hybrid, Variable Geometry |
| Companies Covered | General Electric, Siemens Energy, Mitsubishi Heavy Industries, MAN Energy Solutions, Rolls-Royce Holdings, Solar Turbines Incorporated, Ansaldo Energia, Kawasaki Heavy Industries, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Turbine Compressor Market Evolving Landscape
Additive manufacturing is penetrating critical compressor component production, reshaping supply economics for blade and vane geometries that were previously machined from solid forgings.
Advanced ceramic matrix composites are hybridizing traditional metallic airfoil construction in the hottest forward stages of heavy-duty compressors. Mitsubishi Heavy Industries and Siemens Energy have validated silicon carbide fiber-reinforced designs for temperatures exceeding metallic creep limits. This material transition is compressing cooling airflow requirements and enabling higher pressure ratios without efficiency penalties.
EPA emissions enforcement under the Clean Air Act is tightening continuous monitoring obligations for nitrogen oxide output from gas turbine installations. Compressor stage matching and combustion staging must now accommodate real-time adjustment protocols rather than fixed tuning maps. Combined-cycle operators in California and Texas are retrofitting variable inlet guide vane systems to maintain compliance across load-following duty cycles.
Long-term service agreements are displacing transactional spare parts purchasing among baseload power generators. Original equipment manufacturers are capturing fifteen-to-twenty-year maintenance contracts that bundle compressor overhauls with hot gas path inspections. This contractual shift is most pronounced in the United States, where utility procurement departments prioritize budget predictability over capital expenditure minimization.
Gas Turbine Compressor Market Segmentation
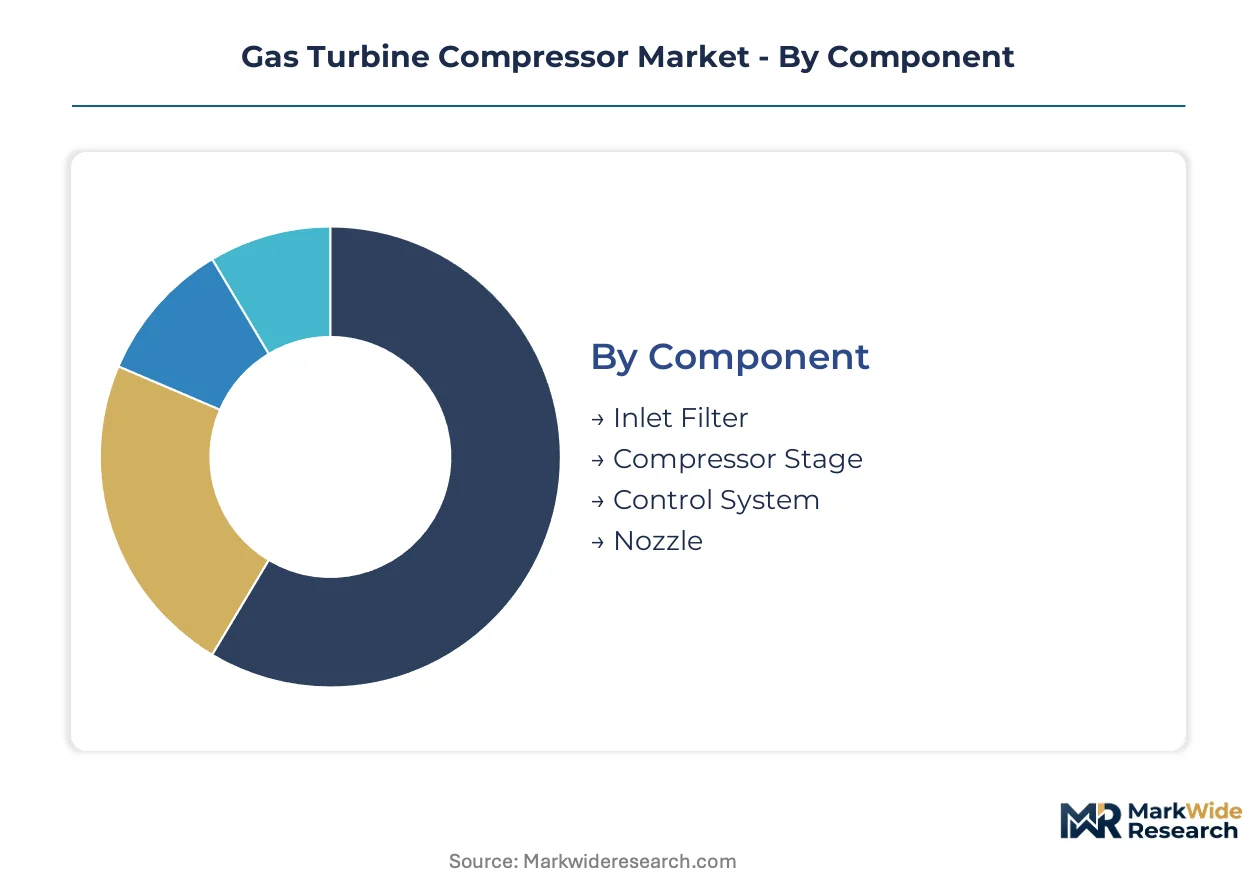
Gas turbine compressor procurement patterns diverge sharply across operational contexts, with component lifecycle requirements and deployment environment constraints dictating specification priorities. Understanding these segment boundaries clarifies why identical compressor frames command vastly different pricing and service terms across power generation versus oil and gas applications.
Component:
Mature hardware categories dominate installed base maintenance spend while emerging subsystems capture incremental technology investment.
- Compressor Stage:Multi-stage axial arrangements with titanium or nickel-alloy airfoils constitute the core value concentration, absorbing the majority of capital expenditure and aftermarket service revenue. Demand clusters in combined-cycle power plants across the United States and Germany as operators pursue pressure ratio improvements to offset fuel cost volatility.
- Control System:Digital governor architectures with integrated variable geometry actuation represent the fastest-advancing technology frontier, enabling real-time surge margin optimization and grid-following response. Procurement accelerates in California and Texas where EPA emissions enforcement mandates continuous combustion tuning.
- Inlet Filter:High-efficiency filtration cartridges with pulse-cleaning mechanisms protect compressor aerodynamic surfaces from fouling in desert and coastal environments. Specifications tighten in Middle Eastern installations confronting dust loading and salt aerosol intrusion.
- Nozzle:Adjustable geometry inlet and interstage nozzles modulate mass flow distribution across operating envelopes. Adoption concentrates in peaking plants requiring rapid turndown capability to balance renewable intermittency.
Compressor Stage retains volume leadership; Control System holds the steepest expansion curve.
End User:
Application-specific duty cycles and regulatory exposure create distinct procurement behaviors across customer verticals.
- Power Generation:Baseload and peaking electricity producers constitute the dominant demand pool, with combined-cycle operators specifying heavy-duty frames for 50,000+ hour maintenance intervals. Investment concentrates in the United States, China, and Germany as utilities retrofit aging infrastructure and commission flexible capacity.
- Oil & Gas:Pipeline compression and gas processing facilities require robust designs tolerant of contaminated intake streams and remote maintenance access. North Sea platform electrification drives substitution of gas-driven units with electrically driven compressors to satisfy emissions reduction mandates.
- Marine:Naval and commercial vessel propulsion systems prioritize compact packaging and shock-resistant mounting configurations. Procurement channels flow through specialized marine engineering integrators rather than direct OEM relationships.
- Aviation:Aero-derivative gas turbines for mechanical drive and power generation applications leverage flight-proven compressor architectures with accelerated certification timelines. Demand originates in emergency power and mobile generation contexts.
Power Generation commands installed base dominance; Oil & Gas presents the most volatile replacement cycle profile.
Deployment:
Environmental exposure severity and logistics accessibility shape specification divergence across installation contexts.
- Power Plant:Grid-connected utility installations with controlled intake environments and scheduled maintenance access enable optimized aerodynamic designs with minimal corrosion allowances. Procurement volumes concentrate in the United States and China as the largest commissioning markets.
- Industrial Facility:Cogeneration and process steam applications in chemical and refining complexes demand compressor configurations tolerant of thermal cycling and partial-load operation. Site-specific engineering requirements extend delivery timelines.
- Offshore:Platform and subsea installations impose severe space constraints and salt-laden atmospheric exposure, favoring compact centrifugal designs with enhanced corrosion protection. North Sea operators lead electrification-driven replacement demand.
- Onshore:Pipeline compressor stations and remote power generation sites balance accessibility against environmental protection requirements. Modular packaging standards facilitate rapid field assembly in frontier basins.
Power Plant deployment anchors revenue scale; Offshore commands the highest unit value premium.
Technology:
Aerodynamic architecture selection reflects the trade-off between peak efficiency and operational flexibility requirements.
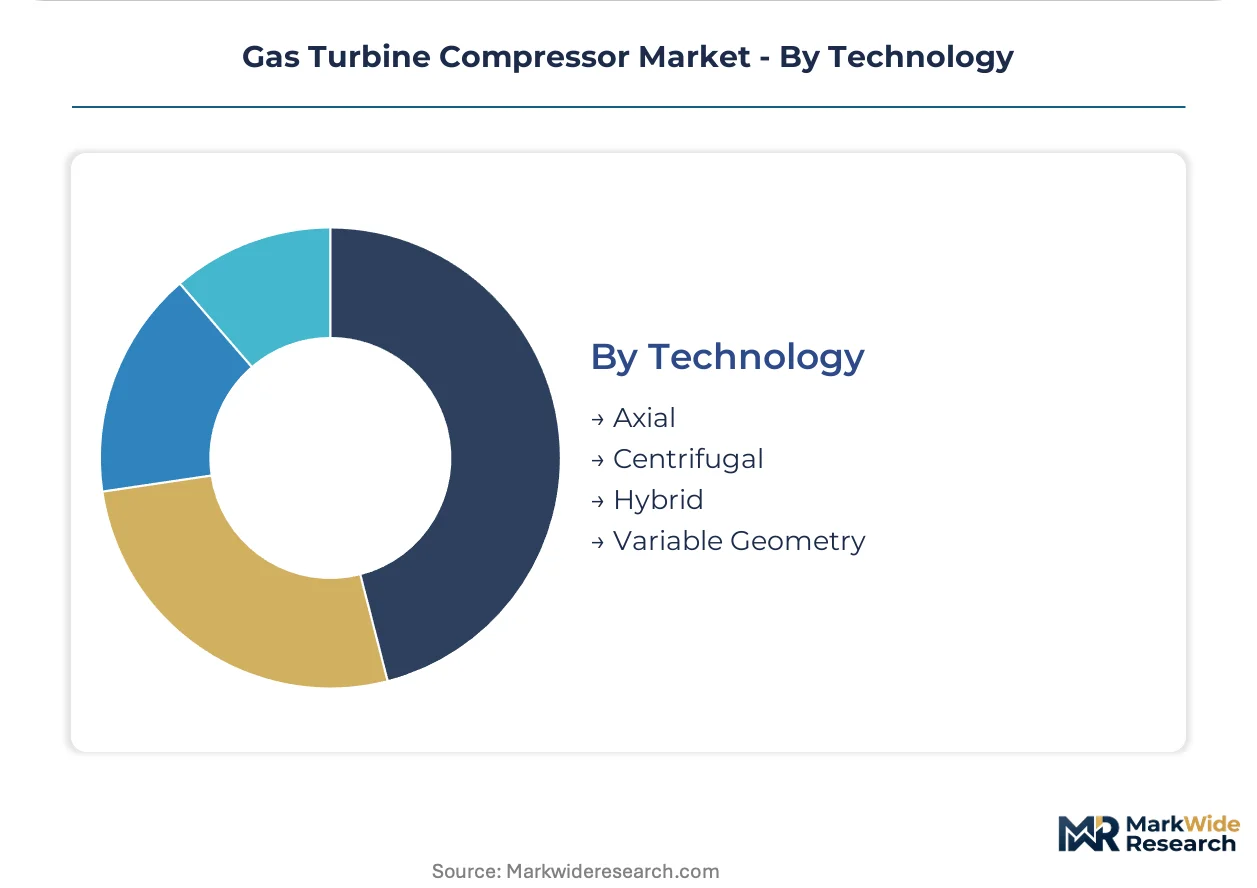
- Axial:Multi-stage configurations achieving pressure ratios exceeding 30:1 dominate heavy-duty power generation where efficiency maximization justifies mechanical complexity. Manufacturing concentration in Germany and Japan limits supplier diversity.
- Variable Geometry:Inlet guide vane and stator vane adjustment systems enable stable operation across 50-100% load ranges without surge margin compromise. Adoption accelerates in renewable-heavy grids requiring rapid ramping capability.
- Centrifugal:Single or two-stage designs with overhung rotor construction occupy compact footprint applications in offshore oil and gas and small-scale power generation. Pressure ratio limitations constrain use to lower-efficiency tolerance segments.
- Hybrid:Axial-centrifugal combinations merge the efficiency advantages of axial front stages with the robustness and pressure rise of centrifugal rear stages. Niche positioning in aeroderivative and mechanical drive applications.
Axial technology maintains installed base leadership; Variable Geometry exhibits the most aggressive penetration trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean energy mandates and grid stabilization requirements are redirecting capital toward flexible gas turbine capacity across major industrial economies. Government incentives for combined-cycle retrofits and hydrogen-ready infrastructure are accelerating procurement timelines in established markets.
United States
Utility procurement for peaking capacity dominates demand as California and Texas utilities commission flexible generation to balance renewable intermittency. EPA emissions enforcement under the Clean Air Act tightens continuous monitoring obligations for nitrogen oxide output. The Permian Basin and Gulf Coast corridor concentrate new combined-cycle installations serving industrial load centers.
China
Provincial grid operators in Jiangsu and Guangdong are expanding gas-fired capacity to manage peak demand surges amid coal-to-gas transitions. National dual carbon goals under MEE directives constrain new coal approvals and redirect investment toward lower-carbon thermal alternatives. Yangtze River Delta manufacturing clusters supply domestic compressor component forging capacity.
Germany
Utility Uniper and RWE are retrofitting existing gas turbine fleets for hydrogen blending compatibility under EU Green Deal timelines. EU F-Gas Regulation mandates sealing technology upgrades that accelerate refurbishment cycles across Bavarian and North Rhine-Westphalian power plants. Industrial cogeneration sites in Baden-Württemberg specify advanced compressor configurations for process steam reliability.
India
Central Electricity Authority directives for flexible generation capacity are opening procurement channels for advanced compressor systems as Gujarat and Maharashtra utilities address renewable integration challenges. PLI scheme incentives for domestic manufacturing support component localization efforts. Hazira and Mundra industrial corridors anchor demand for captive power and grid-connected peaking assets.
Saudi Arabia
Vision 2030 diversification programs are expanding gas turbine deployment for power generation and desalination integration across the Eastern Province. The national regulator mandates efficiency benchmarks that favor high-pressure-ratio compressor configurations. Jubail Industrial City and Ras Al-Khair concentrate new combined-cycle capacity serving petrochemical load centers.
Gas Turbine Compressor Market Competitive Landscape
On the supply side, the industry is consolidated around integrated power plant OEMs with captive compressor design capabilities and long-term service agreement portfolios. Three strategic archetypes dominate: full-system integrators bundling compression with generation assets, component specialists supplying aftermarket airfoils and sealing systems, and aeroderivative licensors leveraging aviation heritage for mechanical drive applications. Competitive positioning hinges on fifteen-to-twenty-year maintenance contract capture and regional manufacturing hub proximity to shorten delivery timelines.
Among the integrated-system tier, General Electric and Siemens Energy occupy positions defined by power plant portfolio breadth and service agreement penetration. Mitsubishi Heavy Industries exemplifies the advanced aerodynamics archetype through its validated ceramic matrix composite applications. MAN Energy Solutions anchors the mechanical drive and process compression segment with centrifugal expertise.
| Leading Market Players |
|---|
| General Electric |
| Siemens Energy |
| Mitsubishi Heavy Industries |
| MAN Energy Solutions |
| Rolls-Royce Holdings |
| Solar Turbines Incorporated |
| Ansaldo Energia |
| Kawasaki Heavy Industries |
| Baker Hughes Company |
| Others |
Value Network & Pricing Analysis
Superalloy forging capacity in Germany and Japan concentrates upstream control over high-temperature compressor blade supply, anchoring margin capture among integrated OEMs with captive metallurgy partnerships while tier-two aftermarket suppliers face cost pass-through pressure.
Pricing Analysis
Volume-discount tiering structures separate integrated power plant OEMs from component aftermarket suppliers, with General Electric and Siemens Energy commanding premium pricing through bundled long-term service agreements while independent airfoil vendors compete on spot-market transactional terms. Price differentiation hinges on ISO 3977 certification grade and regional manufacturing proximity to project sites. Cost compression in standard-grade replacement blades intensifies as Chinese forging capacity expands into mid-pressure ratio segments. Utility procurement departments exhibit lowest price sensitivity for baseload combined-cycle contracts, whereas peaking plant operators and oil and gas midstream buyers prioritize capital expenditure minimization over lifecycle cost optimization.
Supply Chain Analysis
Titanium and nickel-based superalloy feedstock draws from concentrated mining and refining operations in Australia, Russia, and Canada before downstream processing into aerospace-grade forgings. Critical component dependencies span single-crystal casting capacity for high-pressure turbine blades, precision grinding equipment for axial compressor airfoils, and specialized coatings for corrosion resistance. Single-source vulnerability concentrates in silicon carbide fiber supply for ceramic matrix composite transitions. Distribution runs through direct OEM channels for new unit procurement and authorized service networks for aftermarket spares, with project-specific logistics arrangements required for oversized rotor assemblies exceeding standard shipping dimensional limits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized aerodynamicist expertise for multi-stage axial compressor design resides with a shrinking cohort of experienced engineers, creating structural bottlenecks that favor incumbents with established talent retention programs and complicate scaling for challengers.
For Market Incumbents: Entrench market position through backward integration into superalloy forging capacity in Germany or Japan to secure blade supply against emerging Chinese competition, while simultaneously expanding digital twin predictive maintenance contracts to capture recurring revenue streams that lock out independent service providers. Priority investment in variable geometry actuator R&D addresses the renewable intermittency flexibility mandate threatening fixed-geometry installed base retention. For New Entrants and Emerging Players: Pursue white-space opportunities in hydrogen-adapted compressor stage retrofit engineering services for European utilities facing EU Green Deal compliance deadlines, and target India's Gujarat and Maharashtra industrial corridors where PLI scheme incentives reduce localization cost barriers. Go-to-market positioning as a digital-native predictive maintenance platform bypasses the capital intensity of manufacturing competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aeroderivative compressor specialists holding aviation heritage licensing agreements but lacking integrated power plant service scale. Long-term viability over a 5-10 year horizon rests on hydrogen blending retrofit order flow and carbon border adjustment mechanism implementation pace. Watch EPA New Source Review permitting velocity in Texas and California as the signal for North American capacity expansion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Matrix Composite Scale-Up | Mitsubishi Heavy Industries validation enables pressure ratio gains beyond metallic creep limits for next-generation heavy-duty frames. |
| Digital Twin Platform Deployment | Physics-based modeling convergence with operational data streams captures fifteen-to-twenty-year maintenance contract recurring revenue. |
| Hydrogen-Ready Retrofit Engineering | Material specification changes for hydrogen-adapted stages address EU Green Deal timelines and German utility fleet refurbishment demand. |
| Regional Manufacturing Hub Expansion | Siemens Energy's proximity to European and Middle Eastern buyers shortens delivery timelines against Asian competitors. |
| Variable Geometry System Integration | Real-time surge margin optimization enables California and Texas utilities to satisfy EPA emissions enforcement across load-following duty cycles. |
Research Methodology
Desk research of EIA power generation databases, FERC interconnection filings, and IEA gas turbine deployment statistics preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads. Primary fieldwork captured procurement decision criteria, maintenance interval expectations, and technology adoption timelines across United States, German, Chinese, and Indian installations. Secondary validation drew from OEM annual disclosures, trade association technical papers, and customs records of compressor component imports. Bottom-up unit deployment counts triangulated against top-down market value estimates derived from disclosed contract values.
Assumptions regarding EPA emissions enforcement stringency, EU F-Gas Regulation leakage rate thresholds, and hydrogen blending mandate timelines were held fixed across baseline scenarios while fuel price volatility and carbon border adjustment mechanism implementation pace were stress-tested through sensitivity analysis. Segmentation modeling spanned component category, end-user vertical, deployment environment, and aerodynamic technology architecture. CAGRs were derived from logistic growth curve fitting to historical commissioning data, with inflection points calibrated to regulatory deadline schedules and utility capital expenditure cycle phasing. Forecast inputs incorporated superalloy forging capacity expansion announcements and accredited test cell availability for ISO 3977 certification.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories affecting utility capital budgeting or natural gas price volatility impacting combined-cycle dispatch economics would shift the trajectory. Forecasts reflect these documented assumptions and the inherent uncertainty of hydrogen infrastructure buildout pace. Cross-checking against IEA World Energy Outlook gas-fired capacity projections is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
United Arab Emirates Power Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
North America Exhaust Heat Recovery System Market
Power Equipment
Submarine Power Cable Market
Power Equipment
Portable Power Station Market
Power Equipment
Magnetic Bearing Market
Power Equipment
Power Conditioning Services Market
Power Equipment
Cogeneration Equipment Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Industrial Gas Turbine Sales Market
Power Equipment
Wind Turbine Components Market
Power Equipment
Air Preheater Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Russian Federation Power EPC Market