
 Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market | 2026-2036
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market Size, Share, and Industry Trends Forecast 2026-2036
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market Insights
The EU Green Deal's carbon neutrality mandates for heavy industry is recalibrating investment priorities across turbomachinery operators. General Electric Company leverages its digital twin platform to anchor aftermarket service contracts for legacy turbine fleets. Siemens Energy AG competes through specialized hydrogen-ready control retrofits that extend unit compatibility with low-carbon fuels. Emerson Electric Co. dominates the North American calibration and optimization segment through channel control over OEM-authorized service networks.
Turbomachinery control systems, retrofitting, and ancillary services encompass the engineered hardware, software, and field services that govern rotational energy conversion equipment operating at speeds from 3,000 to 30,000 RPM, with retrofitting specifically addressing the replacement of analog governors and relay logic with digital distributed control architectures to restore precision within 0.1% of setpoint. The primary industrial purpose centers on sustaining safe operating margins, preventing surge and stall conditions, and maximizing thermodynamic efficiency across compressors, turbines, and pumps in continuous-process environments. The technology dimension shows DCS and AI-Based Control as the fastest-expanding categories, with AI-Based Control capturing margin pools through predictive anomaly detection that reduces unplanned outage frequency. The application dimension reveals Oil & Gas as the mature revenue base while Power Generation generates the fastest retrofit inquiry growth as utilities confront cycling duty demands from renewable intermittency.
The EPA enforces stationary source emission limits that compel turbomachinery operators to upgrade combustion control logic and add continuous emissions monitoring integration. The EU F-Gas Regulation restricts fluorinated greenhouse gas use in cooling circuits, forcing control system updates to manage alternative refrigerant thermodynamics. OSHA process safety management standards mandate functional safety verification for turbomachinery trip systems, sustaining demand for third-party ancillary certification services. Stakeholders must monitor how hydrogen blending mandates in multiple jurisdictions reshape fuel control algorithm requirements and retrofit scope definitions.
Market Dynamics
The EPA's greenhouse gas standards for power plants are forcing utilities to modernize aging combustion control architectures, compressing upgrade timelines and expanding the addressable market for digital retrofit services across North American gas turbine fleets.
Growth Catalysts
- EPA Emission Thresholds:Tightening standards for existing turbines mandate continuous emissions monitoring integration, driving control system replacement cycles at coal and gas-fired facilities.
- AI-Based Predictive Control:Machine learning algorithms for anomaly detection reduce unplanned outage frequency, creating pull from power generators facing renewable intermittency cycling demands.
- United States Fleet Age:Decades-old gas turbine installations require governor modernization, concentrating retrofit demand in the country's utility sector.
Market Restraints
- Specialized Labor Scarcity:Field technicians capable of calibrating digital distributed control systems within 0.1% setpoint precision command premium wages, elevating service delivery costs.
- Legacy Protocol Fragmentation:Proprietary communication standards from analog-era OEMs create integration friction, extending project timelines and technical risk.
- Capital Allocation Competition:Utilities prioritize renewable generation investments over turbomachinery retrofits, constraining budget availability for control modernization.
Strategic Opportunities
- Hydrogen-Ready Fuel Control:Blending mandates in multiple jurisdictions reshape algorithm requirements, opening retrofit scope for low-carbon fuel compatibility upgrades.
- EU Green Deal Alignment:Carbon neutrality mandates for heavy industry recalibrate investment priorities, positioning control system vendors for industrial decarbonization contracts.
- Digital Twin Convergence:Integration of physics-based modeling with real-time sensor data enables remote optimization services, expanding recurring revenue beyond hardware sales.
Industry Challenges
- Functional Safety Certification:OSHA process safety management standards mandate third-party verification for turbomachinery trip systems, creating documentation bottlenecks and extending project completion timelines.
- Legacy System Integration:Relay logic replacement in continuous-process environments requires hot-cutover execution without production interruption, demanding specialized commissioning expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market |
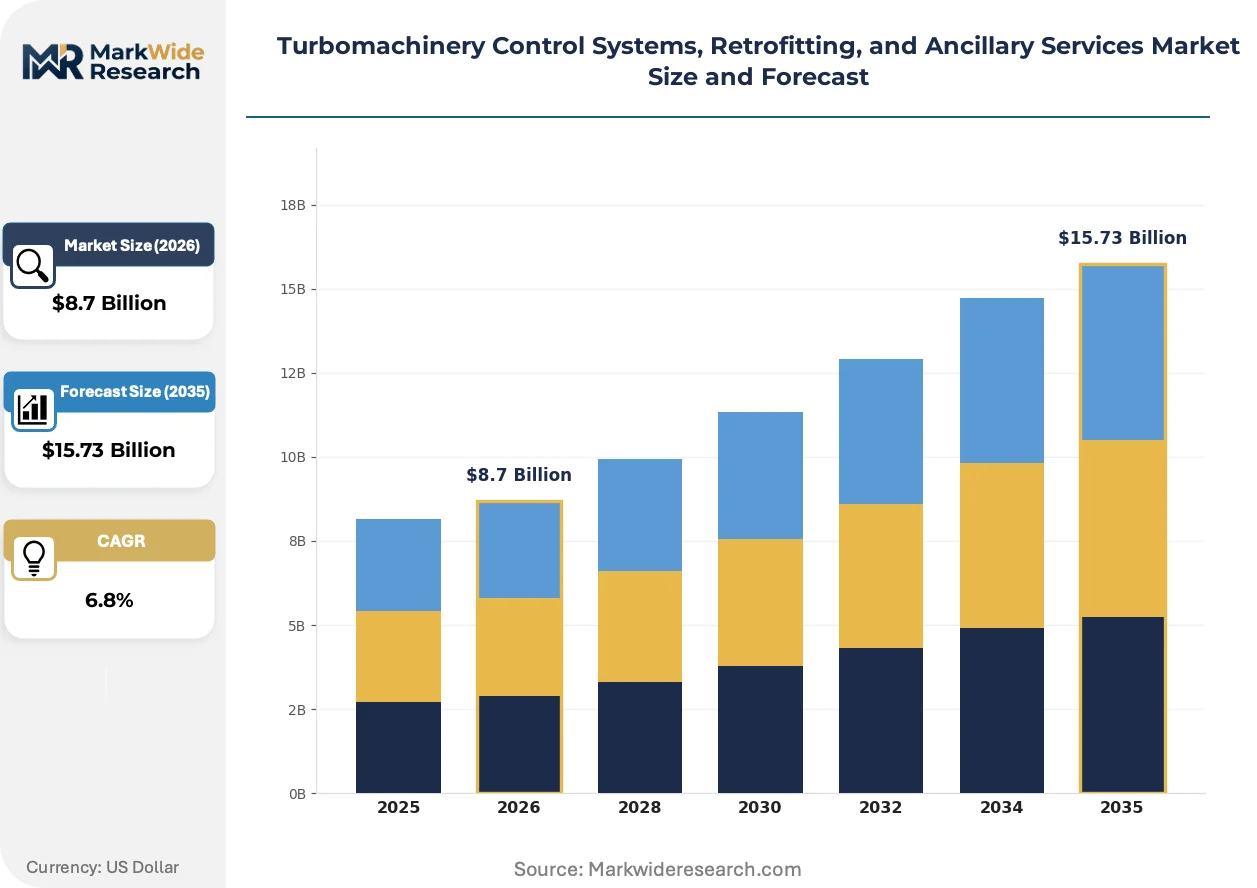
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Upgrades, Calibration, Optimization Technology: DCS, PLC, SCADA, AI-Based Control Application: Power Generation, Oil & Gas, Aerospace, Water Treatment End User: Utilities, Manufacturers, Operators, Contractors |
| Companies Covered | General Electric Company, Siemens Energy AG, Emerson Electric Co., ABB Ltd, Rockwell Automation Inc., Honeywell International Inc., Schneider Electric SE, Compressor Controls Corporation, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market Trends and Innovations
Control architectures are fragmenting into interoperable subsystems, enabling staged modernization without full replacement. This shift reduces capital barriers while accelerating technology refresh cycles across industrial turbomachinery assets.
Digital distributed control platforms are modularizing hardware configurations, allowing utilities to upgrade specific control loops incrementally. Power generators in the United States adopt this approach to spread capital expenditure across fiscal years. The technology is modularizing the traditional monolithic retrofit project into discrete, budget-manageable work packages.
The EU F-Gas Regulation restricts fluorinated greenhouse gas use in cooling circuits, forcing updates to manage alternative refrigerant thermodynamics. Turbomachinery operators must recalibrate thermal management control logic to accommodate new fluid properties. Compressor segments in European process industries face the steepest compliance-driven retrofit requirements.
Service unbundling is separating hardware procurement from ongoing optimization contracts. Industrial buyers now source control system hardware through capital budgets while purchasing predictive maintenance through operational expenditure channels. Oil and gas operators in North America lead this bifurcation, pressuring OEMs to decouple software subscriptions from initial equipment sales.
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market Segmentation
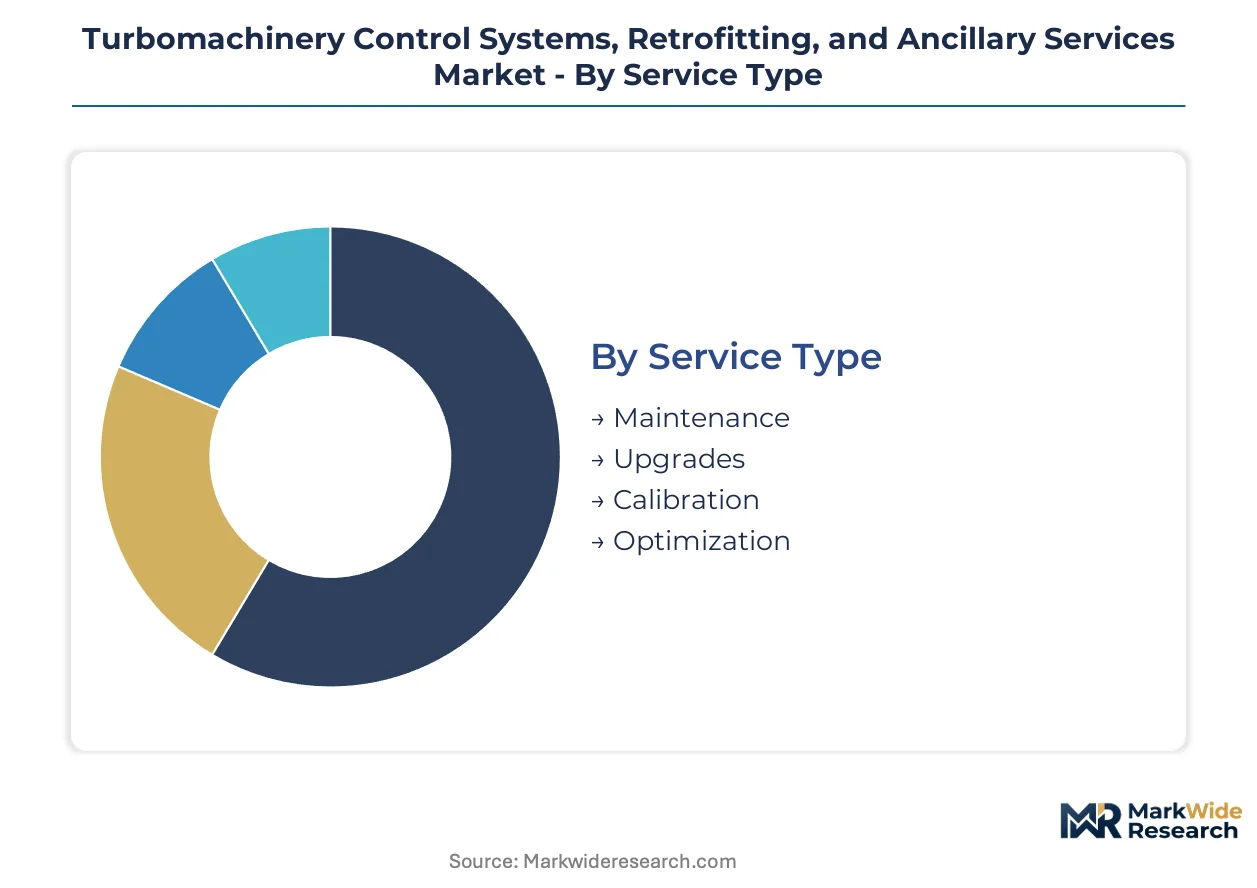
Turbomachinery control services fragment across service intensity layers, control architectures, industrial applications, and procurement authority structures. Each dimension shapes vendor engagement models and margin capture differently.
Service Type:
Standalone service contracts operate independently of equipment sales, while embedded services bundle with original hardware procurement or long-term service agreements.
- Maintenance:Scheduled inspection, parts replacement, and lubrication services preserve mechanical integrity across bearing systems, seals, and rotor assemblies. Power generators in the United States favor multi-year maintenance contracts to manage cycling duty wear from renewable intermittency.
- Upgrades:Hardware and software modernization replaces analog governors with digital distributed control architectures, restoring precision within 0.1% of setpoint. EPA emission threshold tightening accelerates upgrade timelines at coal and gas-fired facilities.
- Calibration:Precision adjustment of sensor feedback loops and actuator response curves ensures control accuracy. Specialized technicians command premium wages, elevating service delivery costs for this labor-intensive segment.
- Optimization:Performance tuning of combustion control logic and thermal management algorithms maximizes thermodynamic efficiency. Industrial process operators purchase optimization through operational expenditure channels separate from capital hardware budgets.
Maintenance leads volumes today; upgrades are gaining share fastest.
Technology:
Cost tiers separate legacy architectures from premium intelligent systems, with integration complexity escalating across the spectrum.
- DCS:Distributed control systems coordinate multiple turbomachinery units through networked controllers and centralized operator interfaces. Oil and gas process plants deploy DCS for integrated compressor and pump station management.
- PLC:Programmable logic controllers execute discrete control functions for smaller turbomachinery assets or safety-critical trip systems. Manufacturers favor PLCs for standalone machine protection where full DCS integration proves uneconomical.
- SCADA:Supervisory control and data acquisition layers provide remote monitoring across geographically dispersed assets. Pipeline operators leverage SCADA for centrifugal compressor stations spanning interstate networks.
- AI-Based Control:Machine learning algorithms analyze vibration signatures, thermal profiles, and process variables to predict anomaly conditions before failure. Predictive anomaly detection reduces unplanned outage frequency for utilities facing renewable intermittency cycling demands.
DCS anchors installed base value; AI-Based Control expands most quickly.
Application:
Maturity gradients separate established industrial verticals from emerging retrofit opportunities, with regulatory pressure intensity varying by sector.
- Power Generation:Gas turbine and steam turbine control modernization addresses cycling duty demands from grid-scale renewable integration. EPA greenhouse gas standards for power plants mandate combustion control logic upgrades and continuous emissions monitoring integration.
- Oil & Gas:Upstream, midstream, and downstream turbomachinery—including compressors, pumps, and expanders—requires control system sustainment across harsh operating environments. This vertical constitutes the mature revenue base with predictable maintenance cycles.
- Aerospace:Aircraft engine test cell control systems and ground support equipment demand high-reliability architectures with rapid response characteristics. Specialized functional safety certification requirements constrain vendor participation.
- Water Treatment:Pump stations and aeration blowers in municipal and industrial water facilities adopt turbomachinery control for energy efficiency optimization. Smaller unit sizes limit individual project value despite volume potential.
Oil & Gas dominates current revenue; Power Generation shows the steepest retrofit inquiry expansion.
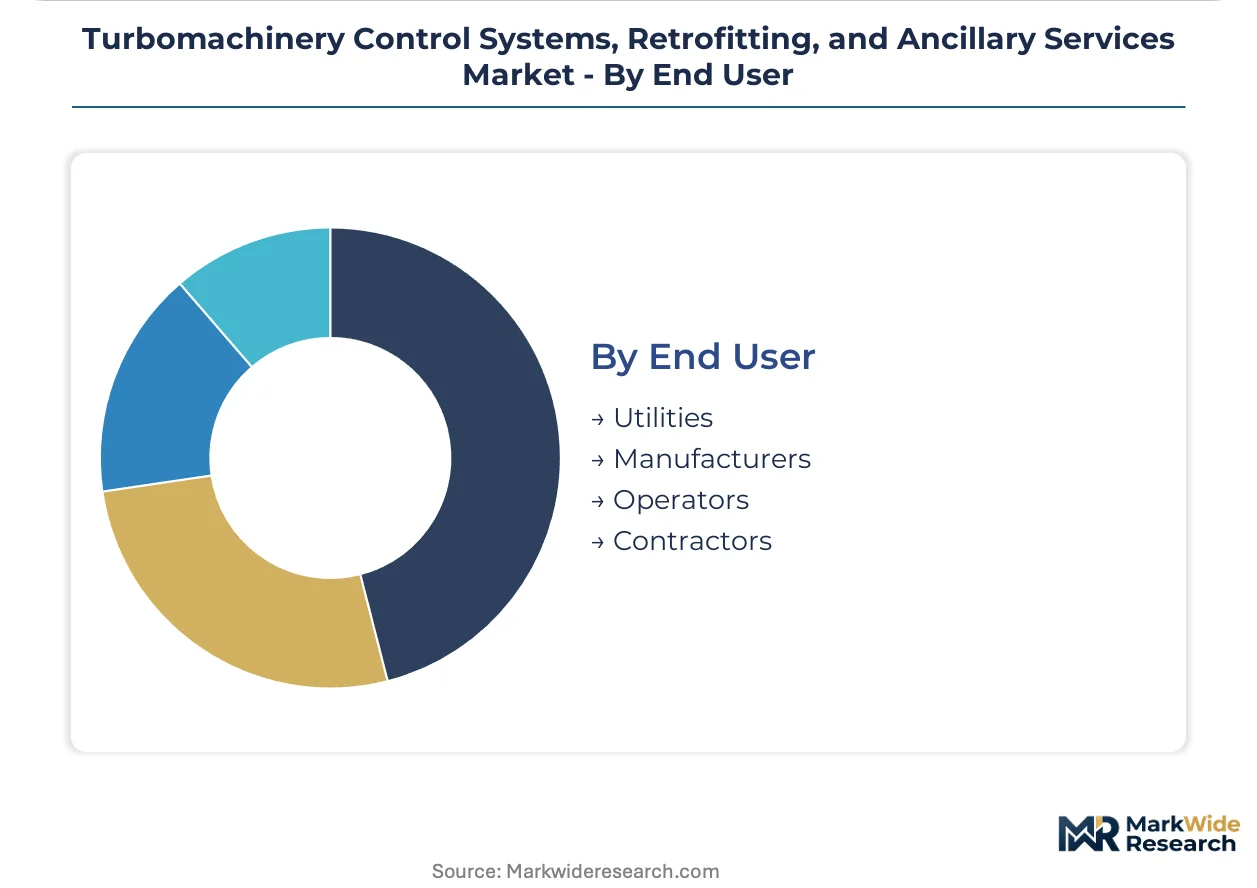
End User:
Procurement authority structures determine contract terms, with capital budget holders negotiating differently than operational expenditure decision-makers.
- Utilities:Investor-owned and public power utilities manage aging gas turbine fleets requiring governor modernization. Capital allocation competition with renewable generation investments constrains control modernization budgets.
- Manufacturers:Industrial process companies with captive turbomachinery assets prioritize uptime assurance over technology refresh. These buyers increasingly unbundle hardware procurement from ongoing optimization contracts.
- Operators:Third-party asset management firms and independent power producers seek performance-based service agreements. Outcome-based contracting shifts technical risk to service vendors.
- Contractors:Engineering, procurement, and construction firms specify control systems for new build and major retrofit projects. Contractor specifications influence long-term aftermarket service capture.
Utilities command the largest individual contract values; manufacturers represent the broadest addressable population.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turbomachinery control systems originated in the United States during the post-war industrial expansion, with early analog governor technologies scaling through the 1960s-70s oil and gas boom. This historical foundation established North American technical standards that continue shaping global retrofit specifications.
United States
Aging gas turbine fleets across the Midwest and Southeast drive governor modernization demand. EPA greenhouse gas standards for power plants mandate continuous emissions monitoring integration, compressing upgrade timelines. Houston and the Gulf Coast industrial corridor concentrate compressor control retrofit activity for petrochemical operations.
Germany
Industrial decarbonization mandates under the EU Green Deal recalibrate investment priorities for heavy process industries. The F-Gas Regulation restricts fluorinated greenhouse gas use in cooling circuits, forcing thermal management control updates. The Ruhr industrial region and Bavarian chemical clusters lead hydrogen-ready fuel control retrofit adoption.
China
Dual carbon goals accelerate digital distributed control adoption across coal and gas-fired power plants. National emission standards tighten combustion control requirements for existing turbine assets. The Yangtze River Delta manufacturing belt and Shandong Peninsula energy corridor concentrate domestic control system procurement.
Saudi Arabia
Gas turbine fleet expansion for power and desalination sustains long-term control system demand. National industrial diversification programs under Vision 2030 prioritize local service capability development. The Eastern Province oil and gas infrastructure cluster anchors aftermarket service contract volumes.
Japan
Precision manufacturing standards elevate functional safety certification requirements for turbomachinery trip systems. METI energy efficiency directives drive optimization service adoption. The Chubu industrial region around Nagoya and Keihin manufacturing belt concentrate high-reliability control architecture demand.
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market Competitive Landscape
Capital-heavy original equipment manufacturers compete with asset-light control system integrators across service delivery models. The market structure consolidates around diversified industrial conglomerates with captive turbomachinery portfolios, while specialized retrofit contractors fragment the mid-tier upgrade segment. Three archetypes dominate: full-stack OEMs anchoring long-term service agreements, automation specialists capturing digital transformation contracts, and regional system integrators executing field commissioning. Competitive dynamics center on technology licensing partnerships and geographic service network expansion.
Within the full-stack OEM tier, General Electric Company and Siemens Energy AG exemplify platform-centric strategies that bind hardware sales to recurring optimization contracts. Emerson Electric Co. occupies a distinct position through channel control over authorized service networks. These three companies represent contrasting approaches to capturing value across the retrofit lifecycle, from initial digital architecture deployment through ongoing predictive maintenance subscriptions.
| Leading Market Players |
|---|
| General Electric Company |
| Siemens Energy AG |
| Emerson Electric Co. |
| ABB Ltd |
| Rockwell Automation Inc. |
| Honeywell International Inc. |
| Schneider Electric SE |
| Compressor Controls Corporation |
| Mitsubishi Heavy Industries |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation's fluorinated greenhouse gas restrictions gate qualified supply for thermal management control modules and command premium-tier pricing for compliant retrofit architectures. Buyers seeking EPA-certified continuous emissions monitoring integration face parallel supply bottlenecks that compress procurement timelines and elevate service delivery rates.
Pricing Analysis
Project-based contracting with outcome-based performance guarantees dominates turbomachinery control retrofits, separating hardware procurement from ongoing optimization subscriptions. Price differentiation hinges on functional safety certification tier (SIL-rated trip systems command substantial premiums) and geographic delivery complexity (remote site mobilization escalates field service costs). Cost compression in standard-tier digital governor replacements is intensifying because utilities unbundle hardware from software subscriptions. Independent power producers exhibit highest price sensitivity, while integrated oil majors prioritize uptime assurance over unit economics.
Supply Chain Analysis
Direct-to-OEM authorized service networks handle utility-scale retrofit demand, while regional system integrators serve mid-tier industrial process operators. Manufacturing concentrates in Germany, the United States, and Japan for precision control hardware, with China expanding domestic distributed control platform production. Semiconductor content for AI-based control modules and specialized sensor arrays draws from Taiwan and South Korea. Single-source vulnerability around legacy protocol translation chips creates procurement risk for analog-to-digital migration projects. Distribution runs through OEM-captive service organizations and independent automation distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through predictive maintenance subscription scaling, as AI-based anomaly detection shifts vendor revenue from transactional hardware to recurring software tiers.
For Market Incumbents: Anchor long-term service agreements through digital twin platform deployment, locking in aftermarket capture across aging gas turbine fleets. Deepen backward integration into sensor manufacturing to reduce procurement exposure and accelerate hot-cutover commissioning timelines. Hydrogen-ready fuel control algorithm development represents the critical capability gap for defending against automation specialists entering from adjacent industrial software markets. For New Entrants and Emerging Players: Regional system integrators with functional safety certification expertise offer the most penetrable channel partnership for accessing utility retrofit pipelines. Target water treatment municipalities and independent power producers, segments where OEM service networks maintain weaker presence and price sensitivity runs lower than utilities. Lead with modular DCS upgrades that spread capital expenditure across fiscal years, matching procurement authority structures of budget-constrained buyers. For Investors and Strategic Acquirers: Roll-up economics work for specialized retrofit contractors because project fragmentation across thousands of aging turbomachinery assets prevents any single vendor from achieving scale dominance. Focus acquisition screening on firms with OSHA process safety management certification credentials and established relationships with EPC contractors. Watch hydrogen blending mandate implementation timelines as the inflection signal for fuel control retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Control Retrofit | EU Green Deal alignment positions vendors for industrial decarbonization contracts in German chemical clusters. |
| Digital Twin Platform Integration | Physics-based modeling with real-time sensor data expands recurring revenue beyond hardware sales for GE and Siemens. |
| Functional Safety Certification Investment | SIL-rated trip system capabilities unlock utility sector contracts requiring OSHA process safety management compliance. |
| Authorized Service Network Expansion | Channel control over OEM-authorized calibration services anchors North American market position for Emerson. |
| AI-Based Predictive Control Development | Machine learning algorithms for anomaly detection reduce unplanned outages for renewable-cycling power generators. |
Research Methodology
Bottom-up power generation utility modeling reconciled against top-down turbomachinery OEM service contract tracking forms the analytical core of this study. Primary interviews with plant maintenance directors, control system engineers, EPC procurement leads, and aftermarket service heads were validated against secondary sources including EPA emission standard filings, FERC generator databases, EU ETS compliance records, and industrial automation trade association statistics. This dual approach ensures demand-side consumption patterns align with supply-side capacity and pricing disclosures.
The input-output matrix links installed base aging curves, regulatory compliance timelines, and technology substitution rates to project retrofit inquiry volumes across the analysis window. Segmentation dimensions include service type intensity, control architecture tier, industrial application vertical, and procurement authority structure. CAGRs were derived from regression analysis of historical upgrade cycle data against emission threshold tightening schedules. Forecast inputs incorporate hydrogen blending mandate progression and renewable intermittency cycling duty projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA rulemaking delays, EU F-Gas Regulation enforcement intensity, and hydrogen infrastructure buildout pace. Periodic stress-testing of base assumptions against actual retrofit project announcement flows is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
Japan Power EPC Market
Power Equipment
Portable Power Station Market
Power Equipment
Wind Turbine Bolts Market
Power Equipment
Australia Power EPC Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
United Kingdom Power EPC Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Europe Power Rental Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Global Transformerless UPS Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Chad Power EPC Market