
 Steam Safety Valve Market | 2026-2036
Steam Safety Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Safety Valve Market Analytics
The divergence between premium and commodity tiers is shifting toward certification depth and material traceability rather than price alone. Emerson Electric Co. leverages its global service network to anchor long-term maintenance contracts with utility operators. Spirax Sarco Limited specializes in steam system optimization, competing on application engineering rather than unit volume.
A steam safety valve is a pressure-relief device engineered to open automatically when system pressure exceeds a predetermined set point, typically constructed with stainless steel or carbon steel bodies rated for temperatures exceeding 500°F. Its primary industrial purpose is protecting boilers, pressure vessels, and steam distribution networks from catastrophic overpressure events. Spring-loaded designs dominate installed bases across mature markets, while pilot-operated configurations capture expanding share in high-pressure chemical processing where precise blowdown control protects batch integrity. Stainless steel material grades command premium positioning in food production and pharmaceutical end uses where corrosion resistance intersects with sanitary compliance requirements.
ASME Boiler and Pressure Vessel Code Section I and API Standard 526 govern product certification and set pressure-temperature ratings that determine market access across North American jurisdictions. EMA-equivalent pressure equipment directives in Europe enforce conformity assessment procedures that favor established manufacturers with notified body relationships. China's SAMR implements GB standards that increasingly align with international codes while retaining domestic testing requirements. Stakeholders must monitor how diverging national certification timelines affect inventory planning and regional manufacturing footprint decisions.
Market Dynamics
Power generation utilities are extending replacement cycles for aging boiler infrastructure while ASME and API certification requirements tighten qualification thresholds, compressing vendor margins and favoring manufacturers with established notified body relationships.
Growth Catalysts
- China's thermal power modernization:State-owned energy groups are retrofitting coal-fired plants with higher-capacity safety valves to meet efficiency mandates under SAMR oversight.
- API Standard 526 alignment:North American refineries and petrochemical complexes are upgrading to certified valves to satisfy pressure-temperature rating requirements.
- Stainless steel adoption:Food processing and pharmaceutical facilities are specifying corrosion-resistant grades to meet sanitary compliance under FDA and EMA frameworks.
Market Restraints
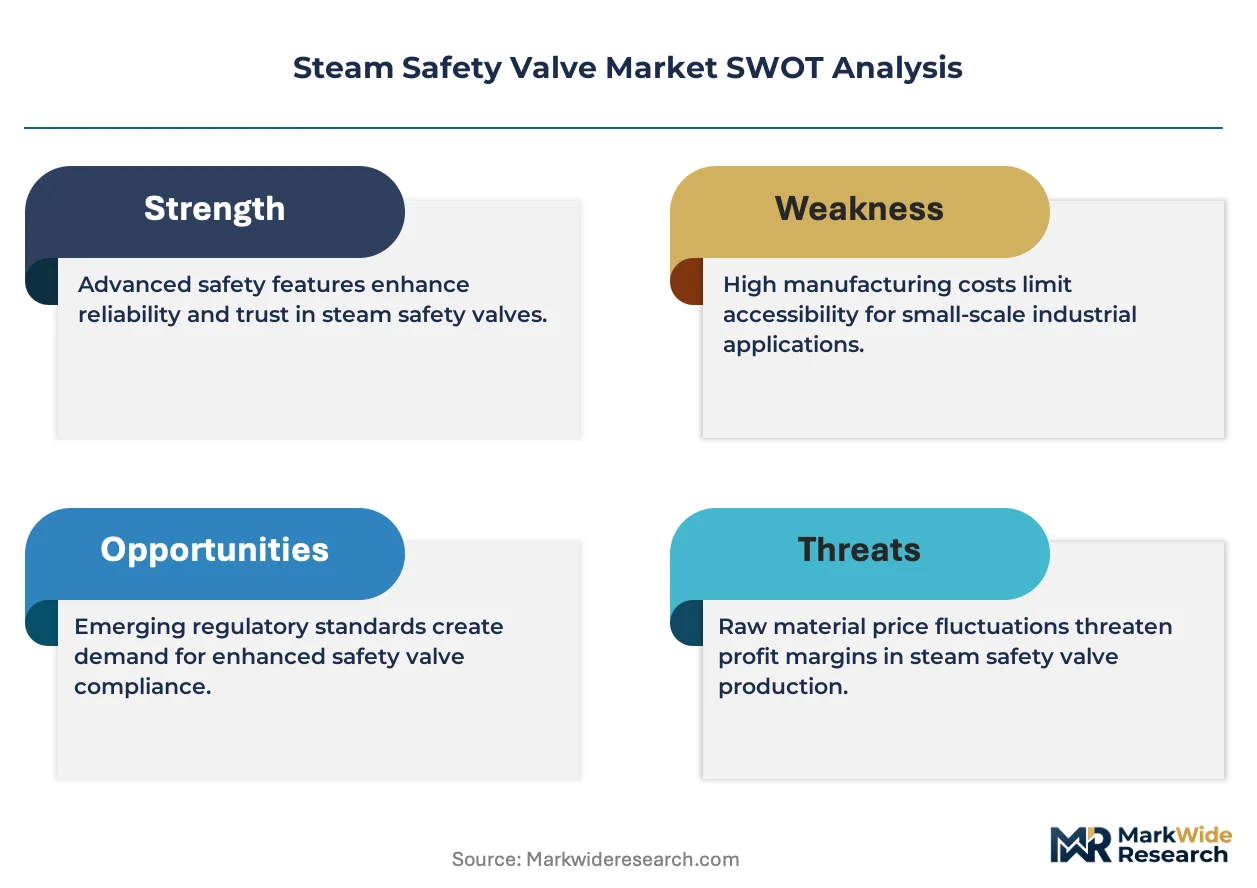
- Alloy steel price volatility:Nickel and chromium input costs fluctuate with mining supply disruptions, squeezing foundry margins on high-pressure valve castings.
- Foundry concentration in China:Roughly two-thirds of global stainless steel valve body production clusters in Jiangsu and Zhejiang provinces, creating geographic supply risk.
- Pilot-operated valve complexity:Precision blowdown control mechanisms require specialized machining tolerances that limit qualified supplier pools.
Strategic Opportunities
- India's power sector expansion:Central Electricity Authority mandates for supercritical boiler installations create demand for high-pressure safety systems in thermal plants.
- Digital valve monitoring:Integration of pressure sensors and IoT connectivity enables predictive maintenance contracts with utility operators.
- EU F-Gas Regulation compliance:Industrial refrigeration system retrofits require compatible safety valves, opening replacement cycles across cold chain facilities.
Industry Challenges
- ASME Section I certification timelines:Third-party inspection backlogs at accredited bodies extend product qualification periods by six to twelve months.
- Weld procedure qualification:Specialized joining techniques for dissimilar metals demand certified technicians that foundries struggle to recruit and retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Safety Valve Market |
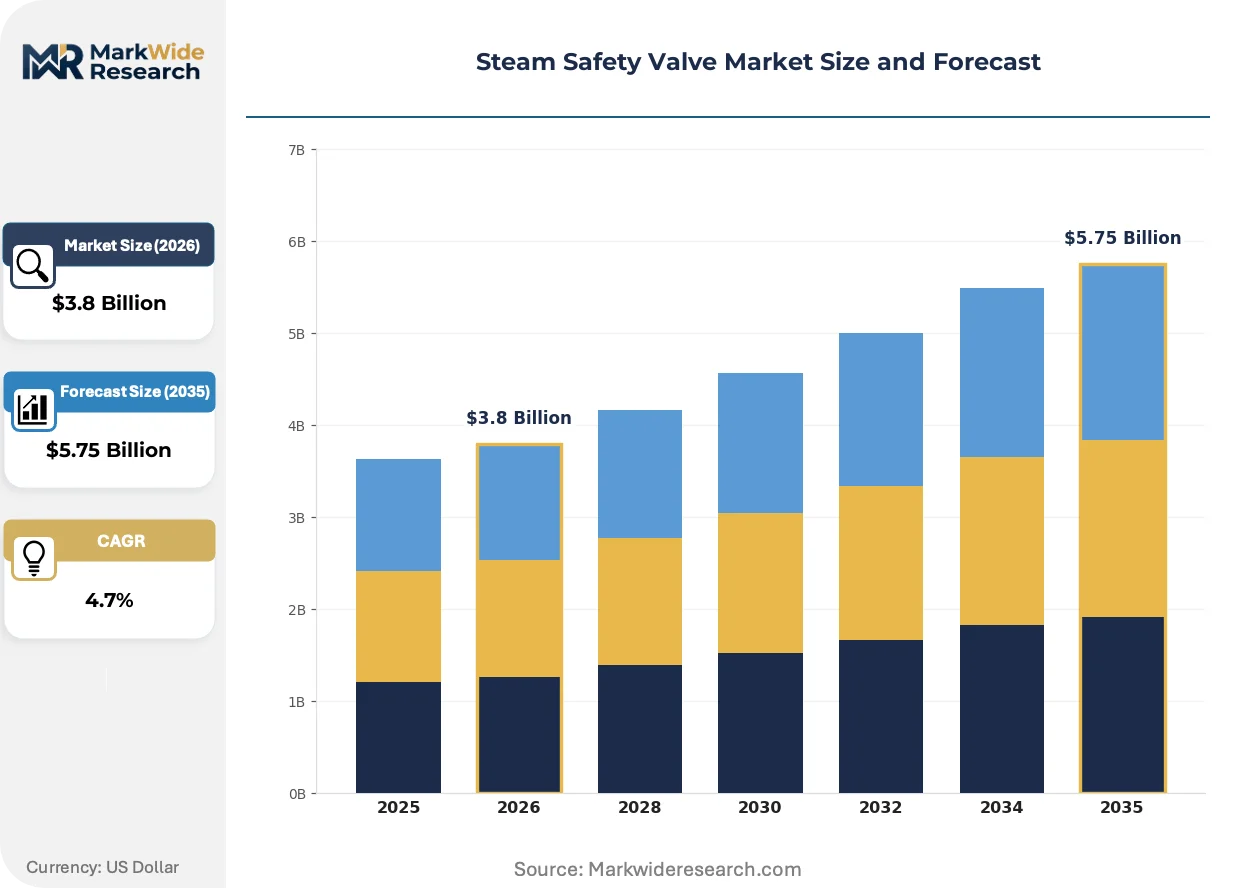
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Spring-Loaded, Pilot-Operated, Balanced Bellows, Excess Pressure Application: Power Generation, Chemical Processing, Oil Refining, Food Production Material: Stainless Steel, Carbon Steel, Bronze, Plastic End User: Energy Sector, Manufacturing Industry, Food & Beverage, Pharmaceuticals |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, Honeywell International Inc., Parker Hannifin Corporation, Spirax Sarco Limited, Pentair plc, Velan Inc., LESER GmbH & Co. KG, IMI Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Safety Valve Market Evolving Landscape
Wireless sensor integration and additive manufacturing are reshaping how safety valves are produced, monitored, and serviced across heavy industrial installations.
Additive manufacturing of valve components is decentralizing production economics for complex geometries. Oil and gas operators in the Permian Basin and North Sea clusters are qualifying laser-sintered seat rings for critical service applications. Distributed printing networks reduce lead times for obsolete replacement parts that traditional foundries no longer stock.
REACH substance restrictions on chromium compounds are forcing material substitutions in European valve coatings. Manufacturers serving German chemical parks and Rotterdam refining complexes are transitioning to tungsten-carbide alternatives. This regulatory pressure compresses product development cycles as notified bodies assess new surface treatment qualifications.
Service contract unbundling is fragmenting traditional vendor-customer relationships. Power utilities in Texas and Alberta are separating valve supply from inspection and recertification, awarding multi-year maintenance agreements to independent service providers. This procurement pattern shift pressures original equipment manufacturers to defend aftermarket revenue through proprietary diagnostic tools.
Steam Safety Valve Market Segmentation
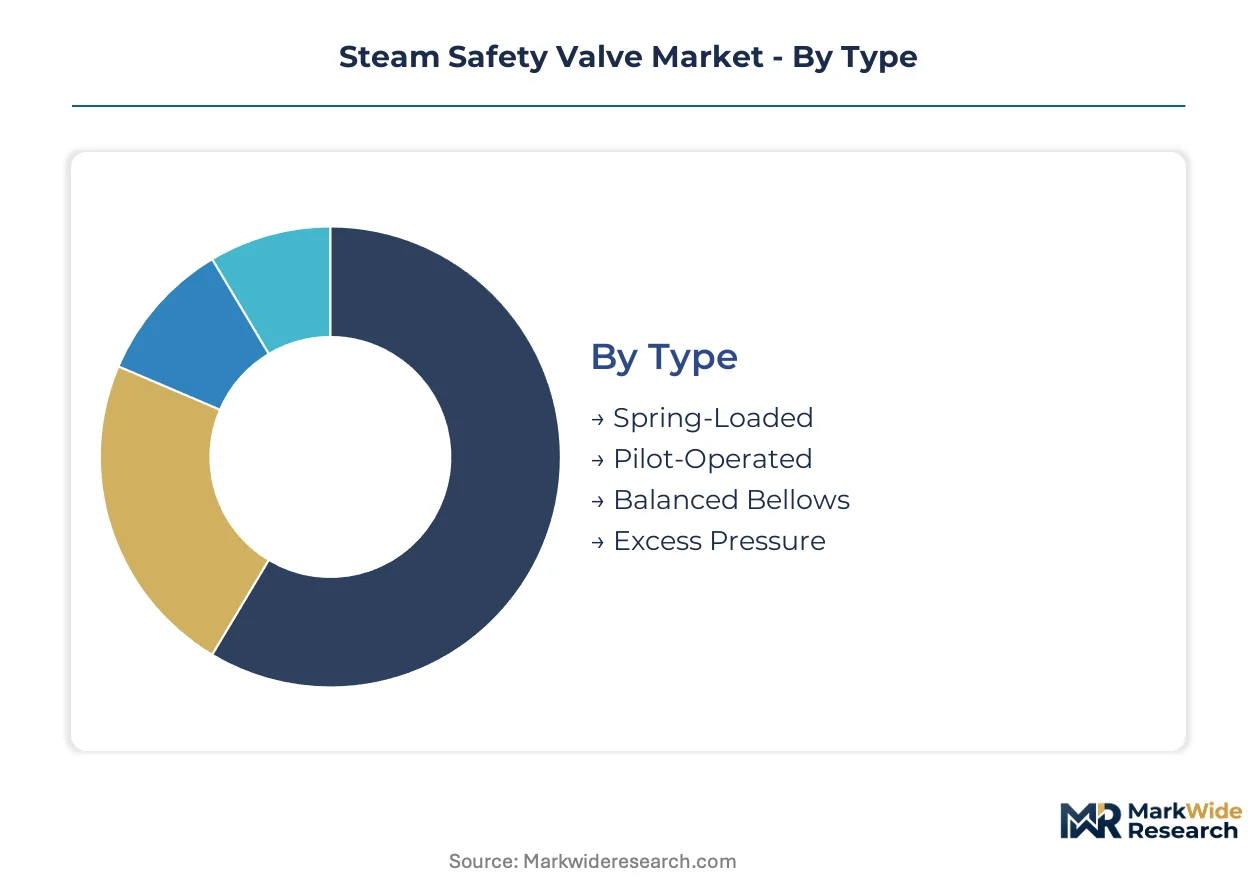
Segmentation in steam safety valves reveals how capital intensity and certification requirements stratify procurement decisions. Utility operators prioritize ASME-certified spring-loaded designs for baseload reliability, while specialty chemical processors accept premium pilot-operated systems for precise blowdown control.
Type:
Capital intensity varies sharply by actuation mechanism, with pilot-operated configurations demanding the most sophisticated machining and testing infrastructure.
- Spring-Loaded:Mechanical simplicity using helical compression springs to maintain set pressure against system load. Coal-fired utilities in China and India specify these for supercritical boiler protection where maintenance crews maintain in-house rebuild capability.
- Pilot-Operated:A main valve modulated by a smaller pilot stage enabling tight blowdown control. High-pressure polyethylene reactors and ammonia synthesis loops in the US Gulf Coast and German chemical parks pay premiums for this precision.
- Balanced Bellows:Bellows element isolates spring from process fluid, suited for corrosive steam conditions in geothermal plants.
- Excess Pressure:Rapid-opening designs for emergency relief scenarios in batch chemical vessels.
Spring-Loaded absorbs the bulk of installed capacity; Pilot-Operated is expanding most quickly.
Application:
Application segmentation tracks how pressure-temperature ratings and batch continuity requirements shape specification priorities.
- Power Generation:Continuous-duty boilers demand valves rated for 650°F superheated steam with minimal leakage. China's state-owned thermal operators are retrofitting aging 300MW units with higher-capacity replacements under SAMR efficiency mandates.
- Chemical Processing:Batch integrity protection requires precise reseating after relief events. BASF and Dow complexes along the US Gulf Coast specify API 526-certified valves with tight blowdown for ethylene cracker service.
- Oil Refining:Hydrocracker and coker units expose valves to hydrogen sulfide and particulate carryover.
- Food Production:Sanitary-grade stainless steel construction with FDA-compliant surface finishes for clean-in-place protocols.
Power Generation dominates current procurement volume; Chemical Processing is climbing the fastest as capacity expansions accelerate in India and the Middle East.
Material:
Material selection reflects the intersection of corrosion resistance, pressure containment, and traceability requirements across end-use environments.
- Stainless Steel:Austenitic and duplex grades resist chloride stress cracking in marine and chemical exposures. Pharmaceutical facilities in Switzerland and Singapore specify 316L with full material certification under EMA and FDA frameworks.
- Carbon Steel:Cost-effective for dry saturated steam in standard industrial service. Foundries in Jiangsu province produce the majority of global valve bodies in this grade.
- Bronze:Naval and desalination applications favor copper alloys for seawater compatibility.
- Plastic:PTFE and PEEK linings handle aggressive chemical vapors in semiconductor wet processing.
Carbon Steel underpins the largest installed base; Stainless Steel is gaining share fastest on regulatory tightening in food and pharmaceutical end uses.
End User:
End user segmentation captures how procurement centralization and maintenance outsourcing reshape vendor relationships.
- Energy Sector:Vertically integrated utilities with captive engineering staffs negotiate long-term service agreements. Saudi Aramco and NTPC India bundle valve supply with inspection contracts spanning 10-year replacement cycles.
- Manufacturing Industry:Fragmented ownership across process plants favors distributor channels and rapid-turn replacement sourcing.
- Food & Beverage:Hygienic design standards and 3-A sanitary certifications drive specification toward specialized suppliers.
- Pharmaceuticals:Validation documentation and change-control protocols extend qualification timelines but lock in premium pricing.
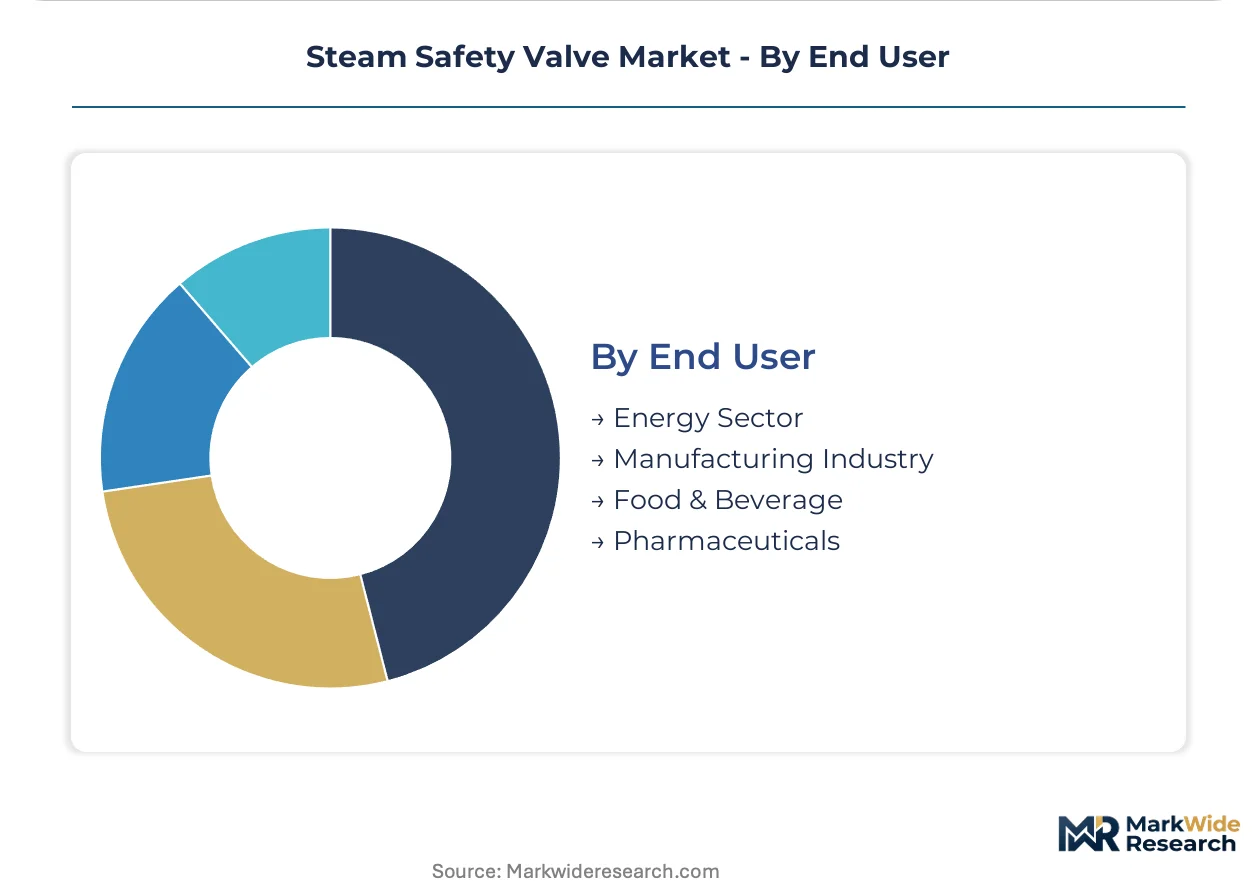
Energy Sector accounts for the greatest valve population; Pharmaceuticals shows the steepest expansion trajectory on biologics manufacturing capacity growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor global valve body foundry capacity, with over two-thirds of stainless steel casting output concentrated in this eastern China corridor. State-owned energy groups in Beijing and Shanghai are retrofitting aging thermal infrastructure under SAMR efficiency mandates. German chemical parks along the Rhine and Ruhr valleys drive premium pilot-operated valve demand for precise blowdown control.
China
State-owned energy groups including China Energy and Huaneng Power are retrofitting 300MW coal-fired units with higher-capacity safety valves. SAMR enforces GB standards alignment with international codes while retaining domestic testing protocols for pressure equipment. Foundry clusters in Jiangsu and Zhejiang provinces supply the majority of global stainless steel valve bodies.
United States
Refineries and petrochemical complexes along the US Gulf Coast are upgrading to API 526-certified valves for hydrocracker and coker unit protection. EPA and OSHA regulations intersect with ASME Section I certification requirements for boiler safety systems. The Permian Basin oilfield operators are qualifying additively manufactured seat rings for critical service applications.
Germany
BASF and Dow complexes in Ludwigshafen and the Rhine-Ruhr chemical corridor specify pilot-operated valves with tight blowdown for ethylene cracker service. REACH substance restrictions on chromium compounds are forcing tungsten-carbide coating substitutions in valve surface treatments. Notified bodies in Berlin and Munich assess new material qualifications under EMA-equivalent pressure equipment directives.
India
NTPC and other central utilities are installing supercritical boiler safety systems under Central Electricity Authority mandates for thermal capacity expansion. BIS certification requirements are tightening for imported pressure relief equipment. Manufacturing clusters in Maharashtra and Gujarat are developing domestic foundry capability for high-pressure valve castings.
Saudi Arabia
Saudi Aramco bundles valve supply with ten-year inspection contracts for its refining and power generation assets. The national oil company sources ASME-certified spring-loaded designs for continuous-duty boiler protection. Industrial cities in Jubail and Yanbu concentrate petrochemical complex development requiring corrosion-resistant safety systems.
Steam Safety Valve Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and material traceability rather than unit price alone. The vendor base stratifies between diversified industrial conglomerates with global service networks and specialized valve fabricators focused on application engineering. Three archetypes dominate: full-service providers anchoring long-term maintenance contracts, precision engineering specialists competing on blowdown control technology, and scale-driven foundries supplying standardized carbon steel bodies. Consolidation pressure is mounting through strategic partnerships between notified bodies and manufacturers, while capacity expansion concentrates in Indian and Chinese foundry corridors.
Within the diversified industrial tier, Emerson Electric Co. and Honeywell International Inc. occupy positions exemplifying global service network leverage, bundling valve supply with predictive maintenance platforms. Spirax Sarco Limited sits within the application engineering specialist archetype, competing on steam system optimization rather than manufacturing scale. Among European precision fabricators, LESER GmbH & Co. KG represents the notified body relationship model that compresses competitor qualification timelines. These three companies collectively illustrate how certification infrastructure and aftermarket service architecture determine competitive positioning more than unit production volume.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| Honeywell International Inc. |
| Parker Hannifin Corporation |
| Spirax Sarco Limited |
| Pentair plc |
| Velan Inc. |
| LESER GmbH & Co. KG |
| IMI Plc |
| Others |
Value Network & Pricing Analysis
Vertically integrated utilities with captive engineering staffs anchor procurement through ten-year service bundling rather than transactional spot purchasing. This buyer concentration forces vendors to absorb certification cost inflation while defending aftermarket revenue through proprietary diagnostic lock-in.
Pricing Analysis
Value-based pricing tied to boiler uptime guarantees separates premium vendors from commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects ASME certification depth and material traceability rather than unit volume. Cost compression in carbon steel spring-loaded tiers intensifies because foundry overcapacity in eastern China squeezes export margins. Food and pharmaceutical end users show least price sensitivity due to FDA and EMA validation requirements that extend replacement cycles.
Supply Chain Analysis
India's BIS local-content mandates are reshaping sourcing for NTPC and central utility procurement, forcing multinationals to qualify domestic foundry partners. Roughly two-thirds of stainless steel valve body production rests on Jiangsu and Zhejiang province clusters, with secondary dependence on German precision machining for pilot-operated mechanisms. Single-source vulnerability runs through nickel and chromium feedstock exposure to mining supply disruptions. Distribution runs through authorized service networks that bundle inspection contracts with original equipment supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ASME Section I certification timelines stretching six to twelve months create a barrier-to-entry moat for established players with notified body relationships.
For Market Incumbents: Deepen vertical integration into Jiangsu foundry capacity to secure stainless steel body supply against BIS localization requirements in India. Lock in ten-year inspection contracts with Saudi Aramco and NTPC to defend aftermarket revenue against independent service provider fragmentation. Prioritize additive manufacturing qualification for obsolete replacement parts to reduce lead time exposure. For New Entrants and Emerging Players: Digital valve monitoring with IoT pressure sensors offers a technology-first wedge into utility predictive maintenance contracts where incumbent diagnostic tools remain proprietary. Target India's supercritical boiler expansion under Central Electricity Authority mandates as the most penetrable geography. Pursue qualification partnerships with Berlin and Munich notified bodies to compress ASME-equivalent certification timelines. For Investors and Strategic Acquirers: The window for entry favors precision fabricators with pilot-operated blowdown control technology and established EMA pressure equipment relationships. Long-term viability hinges on aftermarket service architecture rather than unit manufacturing scale. Watch for SAMR efficiency mandate acceleration in Chinese thermal power retrofits as the inflection signal for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive supply of stainless steel valve bodies insulates against Jiangsu cluster disruption and Indian BIS localization. |
| Digital Valve Monitoring Platform Launch | IoT pressure sensor integration enables predictive maintenance contracts with Texas and Alberta power utilities. |
| Notified Body Partnership Expansion | Collaboration with Berlin and Munich assessment bodies compresses competitor ASME Section I qualification timelines. |
| Additive Manufacturing Qualification | Laser-sintered seat ring certification for Permian Basin operators reduces obsolete parts lead times. |
| Long-term Service Agreement Bundling | Ten-year inspection contracts with Saudi Aramco defend aftermarket revenue against independent provider fragmentation. |
Research Methodology
Multi-period observation of ASME certification backlog durations, SAMR retrofit mandate progression, and alloy steel price volatility anchored the trend analysis, supplemented by interviews with utility maintenance directors, OEM procurement teams, foundry operations managers, and aftermarket service heads. Secondary validation drew from API Standard 526 technical committees, SEC filings of diversified industrial conglomerates, customs trade data for valve body imports, and pressure equipment directive notifications. Bottom-up unit demand estimates triangulated against top-down utility capital expenditure disclosures.
Input-output matrices mapped spring-loaded versus pilot-operated valve demand across power generation, chemical processing, and pharmaceutical end uses. Segmentation dimensions included actuation mechanism, material grade, pressure-temperature rating, and regional regulatory framework. CAGRs were derived from replacement cycle modeling and capacity expansion pipelines. Forecast inputs incorporated supercritical boiler installation mandates and REACH substance restriction timelines for coating substitutions.
Several conditions sit outside the modeled scope, including abrupt SAMR policy shifts, nickel supply disruption from mining geopolitics, and additive manufacturing qualification acceleration beyond current oilfield pilot programs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Rising Stem Ball Valve Market
Valves
Backflow Preventers Market
Valves
Valve Interlocks Market
Valves
North America Irrigation Valves Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Global Level Gauge Market
Valves
Valve Driver Market
Valves
Europe Electro Hydraulic Servo Valve Market
Valves
Global Valves Market
Valves
Fluid Transfer Solutions Market
Valves
Battery Safety Valve Market
Valves
Manual Control Valve Market
Valves
Air Jet Ejectors Market
Valves
Emergency Shut Down Valves (ESDV) Market
Valves
Insulation Flanges Market
Valves
Valve Sack Market