
 Wind Turbine Pitch and Yaw Control System Market | 2026-2036
Wind Turbine Pitch and Yaw Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Pitch and Yaw Control System Market Analytics
Electrification of pitch drives is fragmenting the traditional hydraulic-dominated technology stack across large-scale turbine platforms. Siemens AG leverages in-house converter expertise to integrate servo-electric pitch modules directly into its turbine architecture. Bonfiglioli Riduttori anchors its position through specialized planetary gearbox designs that sustain torque density requirements in 6 MW-plus rotors. Bosch Rexroth competes across both hydraulic and electric architectures, extending its motion control portfolio to capture retrofit demand from aging European fleets.
Wind turbine pitch and yaw control systems comprise electromechanical assemblies that adjust blade angle and nacelle orientation to optimize aerodynamic capture and load mitigation, typically operating within torque ranges exceeding 100 kNm and response cycles under 500 milliseconds for emergency feathering. Electric systems are displacing hydraulic architectures in new installations above 5 MW due to reduced maintenance intervals and elimination of fluid leakage risks in offshore environments. The offshore installation type commands premium component specifications as salt spray exposure and remote accessibility drive demand for sealed actuator housings and redundant sensor arrays. Control algorithms represent a concentrated margin pool as OEMs increasingly bundle proprietary firmware with hardware supply contracts to lock in long-term service revenue.
The EU Green Deal and F-Gas Regulation are tightening material and efficiency standards for components deployed across European wind zones, while IEC 61400 design certification requirements shape product development cycles for pitch safety systems. The EPA and FAA in the United States impose separate environmental and aviation lighting constraints that influence nacelle control system configurations for domestic projects. Stakeholders must monitor how divergent certification timelines between European Notified Bodies and emerging Asian test houses affect market access strategies for next-generation hybrid actuation platforms.
Market Dynamics
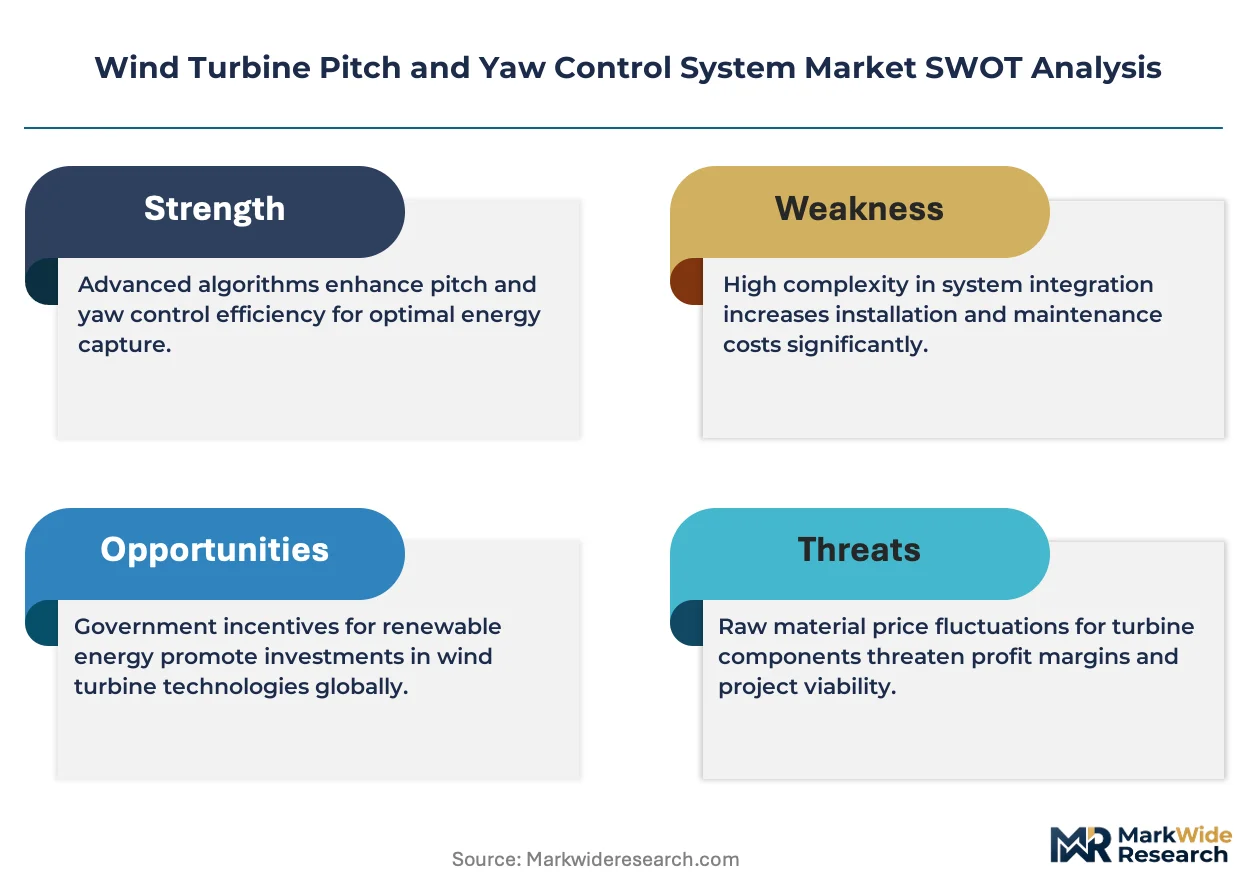
Electric pitch architecture is systematically displacing hydraulic systems across offshore turbine platforms above 5 MW, compressing supplier margins and forcing component manufacturers to requalify product portfolios under accelerated IEC 61400 certification timelines.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases is accelerating electric actuator deployment in European offshore zones, eliminating hydraulic fluid leakage risks in salt spray environments.
- Offshore wind farm operators:Procurement specifications now mandate redundant sensor arrays and sealed housing designs for remote-access turbines, expanding addressable component value per nacelle.
- 6 MW-plus rotor scaling:Torque density requirements exceeding 100 kNm are concentrating demand around specialized planetary gearbox and servo-electric module suppliers with proven load mitigation track records.
Market Restraints
- Rare earth magnet supply:Permanent magnet dependencies in high-torque servo motors expose electric pitch system costs to neodymium-dysprosium price volatility from concentrated Chinese processing capacity.
- Notified Body bottlenecks:Divergent certification timelines between European test houses and emerging Asian conformity assessment bodies are fragmenting market access for hybrid actuation platforms.
- Hydraulic retrofit inertia:Aging European onshore fleets retain installed hydraulic infrastructure, compressing replacement demand for full electric conversions through 2030.
Strategic Opportunities
- India's offshore auction pipeline:CEA coastal wind zone allocations and PLI scheme incentives for nacelle assembly are opening greenfield demand for pitch-yaw control system localization.
- Predictive maintenance convergence:Integration of edge-computing vibration sensors with cloud-based degradation models is enabling unbundled aftermarket service contracts separate from hardware supply.
- US IRA domestic content bonuses:Production tax credit adders for domestically manufactured components are incentivizing control system assembly reshoring to serve Great Lakes and Atlantic Coast projects.
Industry Challenges
- Embedded software certification:IEC 62304 medical-grade process adaptation for pitch safety firmware is extending development cycles and concentrating specialized engineering talent at OEM captive units.
- Legacy hydraulic-electric interface complexity:Hybrid retrofit architectures require reconciling disparate control bus protocols, forcing system integrators to maintain dual competency centers.
- Subsea cable routing constraints:Yaw system power and data umbilical design must accommodate dynamic platform motion in floating offshore configurations, multiplying mechanical validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Pitch and Yaw Control System Market |
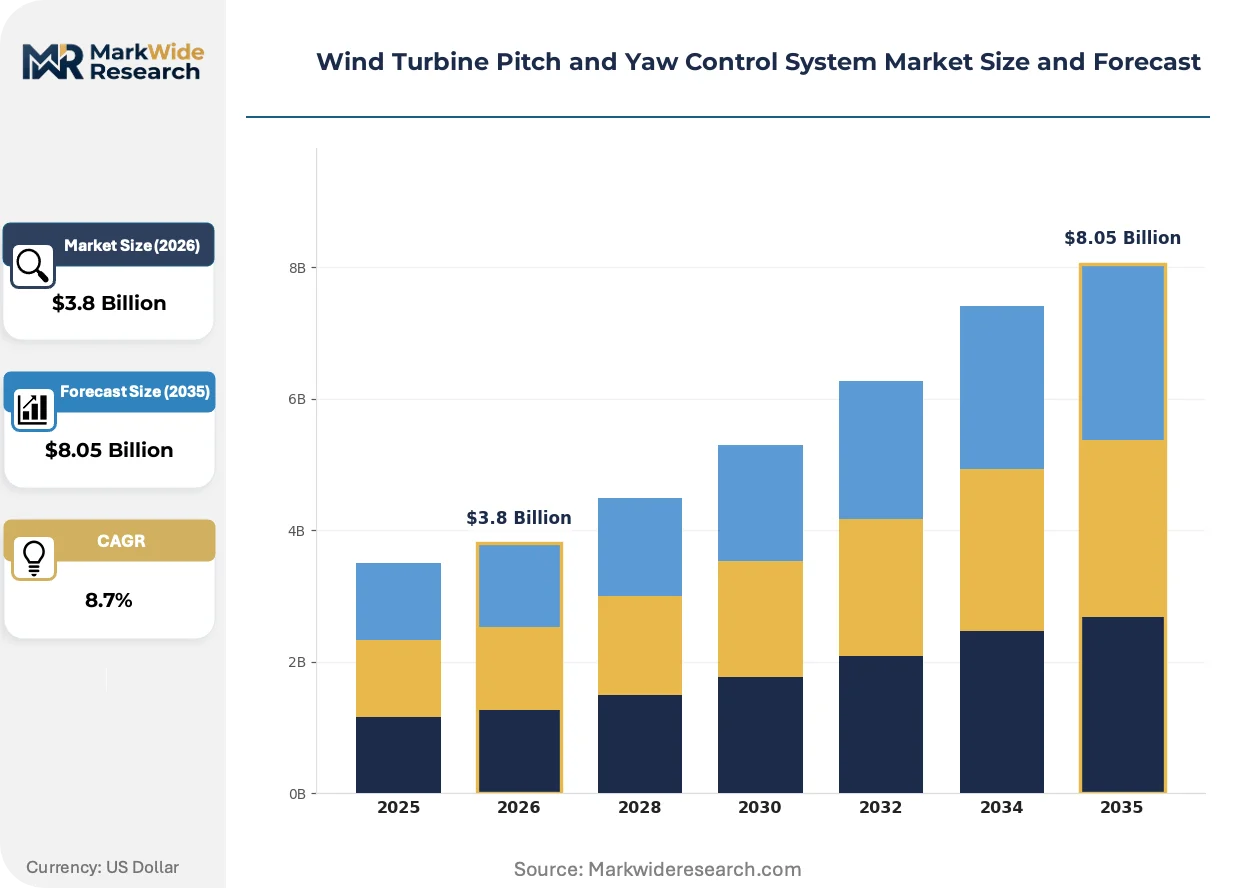
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Control Algorithms, Actuators, Sensors, Power Supply Technology: Hydraulic Systems, Electric Systems, Mechanical Systems, Hybrid Systems End User: Utility Companies, Independent Power Producers, Government, Enterprises Installation Type: Onshore, Offshore, Retrofit, New Installation |
| Companies Covered | Comer Industries, Siemens AG, Bonfiglioli Riduttori, OAT GmbH, Dana SAC UK Ltd, Liebherr, Nanjing High Speed Gear Manufacturing Co, ABM Greiffenberger Gmbh, Bosch Rexroth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Pitch and Yaw Control System Market Evolving Landscape
Control system architecture is converging around electromechanical platforms with embedded intelligence, compressing the traditional separation between hardware suppliers and algorithm developers while redrawing competitive boundaries across the value chain.
Servo-electric pitch drive technology is hybridizing hydraulic reliability with electric precision through integrated backup power architectures and multi-redundant position feedback loops. Offshore operators in the North Sea and Baltic zones are specifying these configurations for 8 MW-plus turbines to eliminate unplanned maintenance vessel dispatches. The structural consequence is compressing pure-play hydraulic component suppliers into niche onshore retrofit segments while elevating motion control specialists with converter and gearbox integration capabilities.
REACH substance restrictions and EU Green Deal embodied carbon reporting requirements are forcing material substitutions in actuator housings and cable insulation compounds. Component suppliers must now document full supply chain chemical inventories and recyclability pathways to maintain CE marking eligibility for European wind zones. Sealed housing manufacturers and sensor array vendors face the steepest compliance cost escalations as polymer formulation portfolios require systematic reformulation.
Long-term service revenue unbundling is separating hardware procurement from predictive maintenance contracts across German and Danish offshore portfolios. Independent service providers are capturing yaw bearing lubrication and pitch battery replacement cycles previously captive to OEM service arms. This channel fragmentation is most advanced in the German Bight, where KBA-certified maintenance entities now compete directly with turbine manufacturer service subsidiaries for control system overhaul contracts.
Wind Turbine Pitch and Yaw Control System Market Segmentation
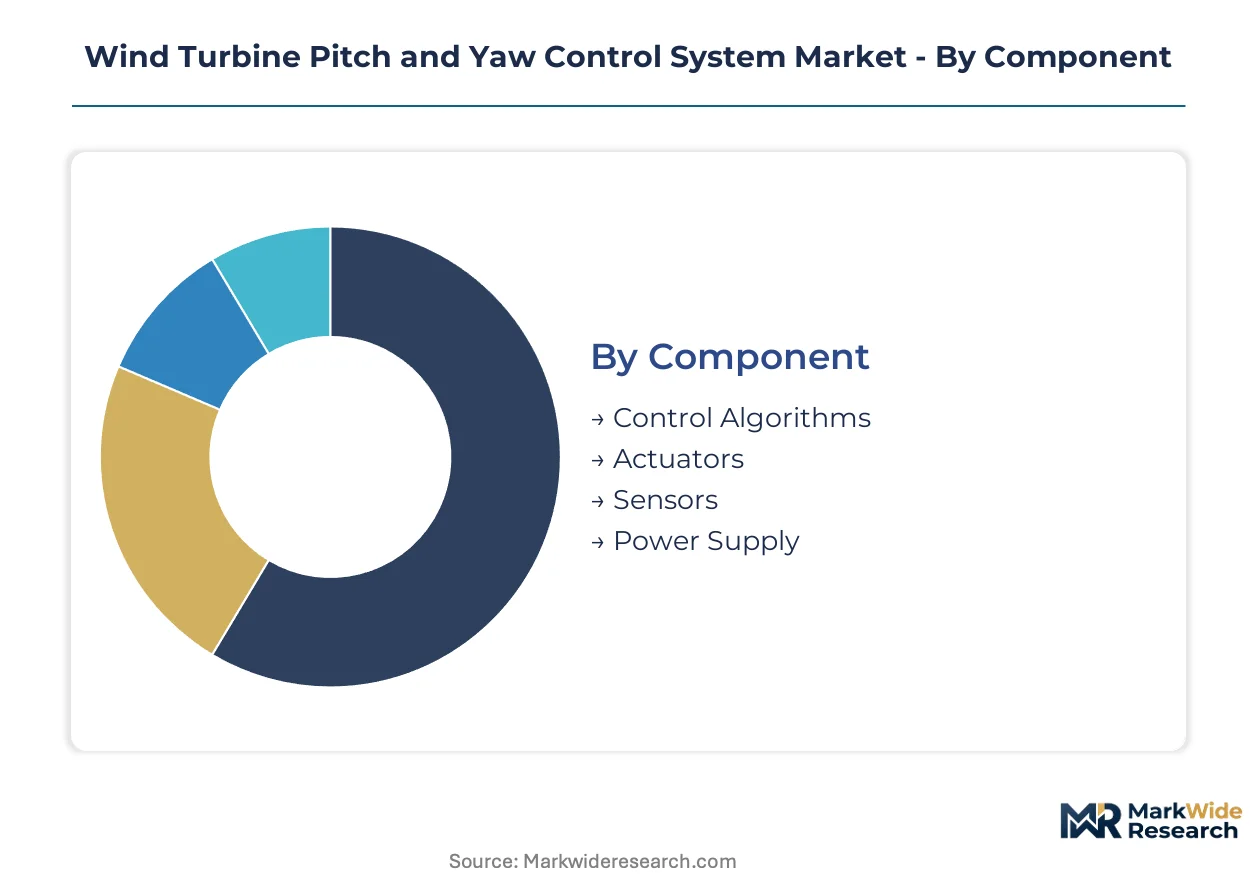
Pitch and yaw control system procurement varies sharply across turbine scale, environment, and ownership structure. Technology choices cascade through component specifications, certification requirements, and service contract structures.
Component:
Cost tier determines margin capture, with software and power electronics commanding premium pricing against commodity mechanical elements.
- Control Algorithms:Embedded firmware governs blade pitch sequencing and nacelle orientation logic with sub-500 millisecond emergency response cycles. OEMs bundle proprietary algorithm licenses with hardware supply to lock in long-term service revenue from German Bight and Danish offshore portfolios.
- Actuators:Electromechanical and hydraulic torque delivery systems exceed 100 kNm load ratings for 6 MW-plus rotors. Sealed housing designs with redundant position feedback are concentrating procurement specifications from North Sea operators eliminating unplanned maintenance vessel dispatches.
- Sensors:Multi-redundant position, vibration, and environmental monitoring arrays enable predictive maintenance convergence.
- Power Supply:Backup battery and capacitor architectures sustain emergency feathering during grid disconnection events.
Actuators hold installed capacity. Control algorithms are rotating up the share rankings.
Technology:
Application environment dictates architecture selection, with salt spray exposure and remote accessibility eliminating hydraulic dominance in offshore zones.
- Electric Systems:Servo-electric pitch drives with permanent magnet motors and integrated converters displace hydraulic architectures above 5 MW. EU F-Gas Regulation phasedown is accelerating deployment across European offshore zones where fluid leakage risks carry severe environmental penalties.
- Hydraulic Systems:Legacy fluid-power architectures retain installed base in aging European onshore fleets below 3 MW. Retrofit inertia compresses replacement demand through 2030 as operators defer full electric conversions amid capital constraints.
- Hybrid Systems:Electric precision with hydraulic backup power reconciles reliability requirements in floating offshore configurations.
- Mechanical Systems:Direct-drive linkages persist in small-scale turbines below 1 MW and emerging market cost-sensitive installations.
Hydraulic systems hold installed capacity. Electric systems are rotating up the share rankings.
End User:
Customer type shapes procurement sophistication, with utility-scale buyers driving standardization against fragmented independent producer specifications.
- Utility Companies:Vertically integrated grid operators specify certified control system packages with bundled predictive maintenance contracts. German utilities leverage KBA certification requirements to consolidate supplier panels and extract volume pricing concessions.
- Independent Power Producers:Project finance-driven developers prioritize upfront capital efficiency over lifecycle cost optimization. IPP procurement patterns fragment across regional turbine OEM preferences and local content requirements.
- Government:State-owned renewable energy corporations in India and China drive localization mandates through PLI scheme incentives and domestic assembly requirements.
- Enterprises:Corporate power purchase agreement offtakers specify control system performance guarantees aligned with contractual availability targets.
Utility companies hold installed capacity. Independent power producers are rotating up the share rankings.
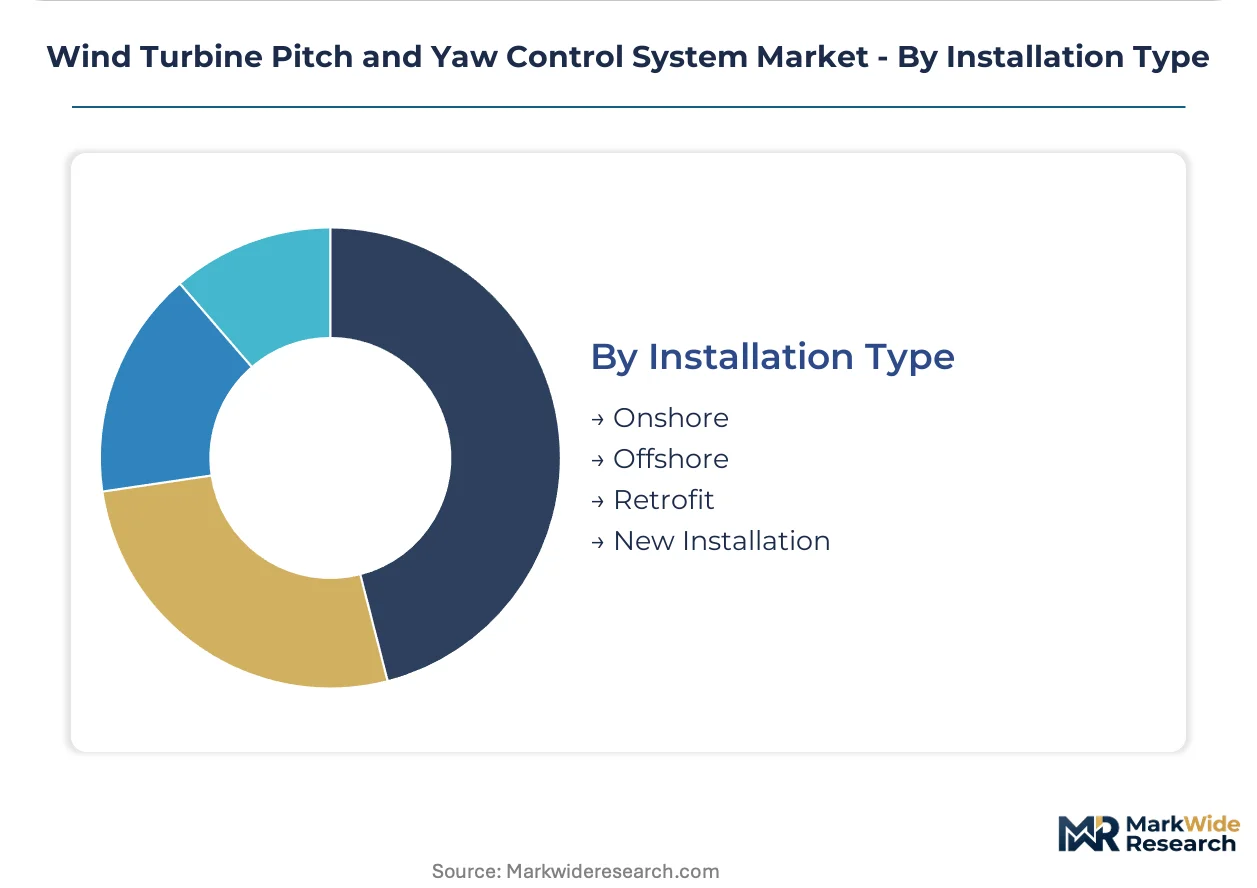
Installation Type:
Volume distribution reflects offshore buildout acceleration against saturated onshore replacement cycles.
- Offshore:Salt spray exposure and remote accessibility mandate sealed actuator housings, redundant sensor arrays, and marine-grade cable insulation. North Sea and Baltic zone specifications are concentrating premium component demand as 8 MW-plus turbine deployment accelerates.
- New Installation:Greenfield turbine assembly integrates electric pitch architecture from initial design. OEM captive converter and gearbox production is capturing margin pool previously available to independent component suppliers.
- Onshore:Mature European and North American markets shift toward replacement demand as turbine fleets age past 15-year design lifecycles.
- Retrofit:Aging hydraulic infrastructure requires hybrid interface solutions reconciling disparate control bus protocols.
Onshore holds installed capacity. Offshore is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale offshore operators in Germany concentrate procurement for 6 MW-plus turbine platforms, while independent power producers in India and corporate PPA offtakers in the United States fragment demand across regional specifications.
Germany
The KBA certifies nacelle assembly capacity for North Sea and Baltic zone deployment. EU F-Gas Regulation phasedown accelerates electric pitch system qualification timelines. Bremerhaven and Cuxhaven anchor converter and gearbox integration facilities serving 8 MW-plus rotor demand.
China
State-owned renewable corporations drive localization through dual carbon goals and domestic assembly mandates. MIIT standards shape servo-electric module certification for coastal wind zones. Yangtze River Delta clusters concentrate planetary gearbox manufacturing for export and captive turbine supply.
United States
Corporate power purchase agreement offtakers specify availability-aligned control system performance guarantees. IRA domestic content bonuses incentivize Great Lakes and Atlantic Coast assembly reshoring. Massachusetts and New York offshore lease rounds concentrate nacelle control procurement specifications.
India
CEA coastal wind zone allocations and PLI scheme incentives open greenfield demand for pitch-yaw system localization. Independent power producers prioritize upfront capital efficiency over lifecycle optimization. Gujarat and Tamil Nadu harbor infrastructure supports nacelle assembly import substitution programs.
United Kingdom
Offshore wind farm operators mandate sealed actuator housings for North Sea salt spray exposure. Health and Safety Executive requirements shape emergency feathering response certification. Scottish and English East Coast clusters concentrate 10 MW-plus turbine deployment and control system overhaul demand.
Wind Turbine Pitch and Yaw Control System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware supply and long-term service revenue capture. Siemens AG anchors the turbine OEM captive tier through in-house converter integration, while independent gearbox and motion control specialists fragment component supply. Three archetypes dominate: vertically integrated turbine manufacturers, specialized planetary gearbox fabricators, and dual-architecture motion control houses. Competitive moves concentrate on IEC 61400 certification acceleration and predictive maintenance contract unbundling.
Among European motion control specialists, Bosch Rexroth occupies a position spanning hydraulic and electric architectures to capture retrofit demand from aging fleets. Bonfiglioli Riduttori exemplifies the planetary gearbox tier through torque density specialization for 6 MW-plus rotors. Siemens AG represents the OEM captive archetype, integrating servo-electric pitch modules directly into turbine architecture to lock in service revenue.
| Leading Market Players |
|---|
| Comer Industries |
| Siemens AG |
| Bonfiglioli Riduttori |
| OAT GmbH |
| Dana SAC UK Ltd |
| Liebherr |
| Nanjing High Speed Gear Manufacturing Co |
| ABM Greiffenberger Gmbh |
| Bosch Rexroth |
| Others |
Value Network & Pricing Analysis
Rare earth magnet processing concentration in China directly shapes where margin pools accumulate across electric pitch system supply chains. Neodymium-dysprosium price volatility feeds through permanent magnet motor costs, compressing assembler margins while elevating converter and gearbox integrators with captive sourcing arrangements.
Pricing Analysis
Cost-plus contracts with rare earth indexation dominate electric pitch system procurement between European turbine OEMs and magnet-dependent suppliers. Price differentiation separates IEC 61400-certified premium tiers from standard CE-marked configurations, with offshore-rated sealed housings commanding additional premiums. Pricing pressure stems from permanent magnet cost volatility as Chinese export quotas tighten. Independent power producers exhibit highest price sensitivity, while utility-scale operators prioritize lifecycle reliability over upfront capital efficiency.
Supply Chain Analysis
Upstream rare earth feedstock draws from Chinese separation facilities, with secondary magnet alloy production concentrated in Japan and Germany. Servo motor windings, planetary gear forgings, and sealed housing polymers constitute critical component inputs. Single-source vulnerability in heavy rare earth processing creates exposure to export license disruptions. Distribution runs through nacelle assembly facilities at Bremerhaven, Cuxhaven, and Yangtze River Delta clusters before final turbine integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contract unbundling is expanding service-attach revenue faster than hardware supply across German and Danish offshore portfolios. Algorithm licensing and battery replacement cycles now generate recurring income streams independent of initial actuator sales.
For Market Incumbents: Pre-empt independent service provider encroachment by bundling edge-computing vibration sensors with proprietary firmware licenses. Capture yaw bearing lubrication contracts previously lost to KBA-certified maintenance entities. Accelerate IEC 62304 process adaptation to extend software certification lead times for emerging competitors. For New Entrants and Emerging Players: Build out localized assembly capacity in Gujarat and Tamil Nadu harbor zones to serve India's CEA coastal wind allocations. Target hybrid retrofit architectures for aging European hydraulic fleets where dual competency requirements deter established suppliers. Pursue PLI scheme qualification to access government-driven procurement channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed motion control specialists holding dual hydraulic-electric architectures but lacking predictive maintenance software stacks. Five-to-ten year viability hinges on converter integration capabilities and service revenue capture rates. Watch for IEC 61400 certification acceleration announcements as inflection indicators for market access positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Edge-computing sensor integration enables unbundled service contracts separate from hardware supply. |
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with Chinese processors hedge permanent magnet motor cost volatility. |
| IEC 61400 Certification Acceleration | Compressed safety system qualification timelines lock in supplier panel positions for 8 MW-plus turbines. |
| Converter and Gearbox Integration | In-house production of servo-electric modules captures margin pool from independent component vendors. |
| India Localization Partnership | CEA harbor zone joint ventures secure PLI scheme access for nacelle assembly import substitution. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across turbine OEM procurement teams, offshore wind farm maintenance directors, nacelle assembly plant engineers, and independent service provider technical leads. Secondary validation drew from IEC certification databases, KBA assembly capacity registers, EU F-Gas Regulation implementation reports, and customs trade records for rare earth magnet flows. Bottom-up component demand estimates were triangulated against top-down turbine deployment projections.
Calibration against historical electric pitch system adoption curves in the North Sea and Baltic zones anchored growth assumptions across the projection horizon. Segmentation modeling spanned technology architecture, installation type, turbine capacity tier, and regional regulatory framework. CAGRs were derived from weighted average of deployment pipeline visibility and replacement cycle analysis. Forecast inputs incorporated offshore auction timelines, F-Gas phasedown schedules, and PLI scheme incentive structures.
The forecast holds incumbent behavior within observed patterns; aggressive converter integration moves by captive OEM units or rapid rare earth supply diversification would shift outcomes. Cross-checking against IEA offshore wind deployment benchmarks and KBA certification issuance rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
Steel Wind Tower Market
Wind Energy Systems
Asia-Pacific Wind Power Equipment Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
Wind Turbine Rotor Blade Market
Wind Energy Systems
Wind Turbine Brakes Market