
 United Kingdom Power EPC Market | 2026-2036
United Kingdom Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Power EPC Market Analytics
Specialist turbine installation crews and high-voltage cable jointers is bifurcating the United Kingdom Power EPC Market into projects that secure labor early and those that face cost escalation. Fluor Ltd leverages its modular fabrication expertise to pre-assemble offshore substation topsides, reducing vessel-day exposure. Wood plc anchors its position through integrated project management offices that coordinate geotechnical surveys, foundation installation, and grid connection timelines. Siemens AG competes by controlling in-house manufacturing of turbine generators and power conversion systems.
Power EPC encompasses the end-to-end design, procurement, and construction of electricity generation infrastructure, typically involving steel monopile or jacket foundations, 33-66 kV array cables, and 132-400 kV export systems that interconnect with the National Grid. The primary commercial purpose is delivering operational assets under fixed-price or target-cost contracts that transfer completion risk from developers to contractors. Wind Energy dominates technology-based awards, with offshore projects commanding premium day rates due to jack-up vessel scarcity and weather windows. Engineering Services captures disproportionate margin pools early in project lifecycles, where front-end design decisions lock in sixty to seventy percent of ultimate capital expenditure. Procurement functions are consolidating under fewer EPC firms as developers seek single-point accountability for turbine supply agreements and balance-of-plant packages.
Ofgem's price control mechanisms and the UK government's Contracts for Difference regime shape developer returns and therefore EPC contract pricing structures. Health and Safety Executive regulations governing offshore construction, plus Maritime and Coastguard Agency marine licensing requirements, dictate seasonal work windows and emergency response provisioning. Stakeholders must monitor how the National Grid ESO's connection queue reforms affect project commissioning sequences and contractor cash flow profiles.
Market Dynamics
The Climate Change Act's tightening carbon budgets are forcing offshore wind developers to compress project timelines, triggering a scramble for integrated EPC packages that bundle turbine supply, foundation installation, and grid connection under single-point accountability.
Growth Catalysts
- Contracts for Difference regime:The UK government's CfD auctions guarantee strike prices for renewable generation, de-risking developer returns and accelerating procurement of turnkey construction services for offshore wind farms.
- Scotland's grid-scale battery storage pipeline:Concentrated project development in the Scottish Highlands is pulling demand for integrated EPC services covering civil works, power conversion systems, and grid synchronization.
- Jack-up vessel specialization:Purpose-built offshore installation vessels with heavy-lift capacity above 1,500 tonnes are enabling larger turbine classes and deeper water site development.
Market Restraints
- Specialist labor scarcity:High-voltage cable jointers and turbine installation crews command premium rates due to limited certification pathways through the Health and Safety Executive.
- Foundation steel price volatility:Monopile and jacket fabrication depends on European heavy plate supply chains exposed to energy-intensive production cost swings.
- Seasonal weather windows:Maritime and Coastguard Agency marine licensing restricts offshore construction to April-October periods, compressing vessel utilization rates.
Strategic Opportunities
- English East Coast cluster expansion:Norfolk and Yorkshire offshore zones offer shallow water depths suitable for fixed-bottom foundations with reduced installation complexity.
- Floating wind technology convergence:Semi-submersible platform designs combined with dynamic cable systems open deeper Celtic Sea sites previously inaccessible.
- Ofgem's connection queue reforms:Proposed changes to National Grid ESO grid access protocols could unlock stranded projects and accelerate contractor cash flow cycles.
Industry Challenges
- Geotechnical survey coordination:Seismic seabed investigations must align with foundation design iterations, creating interface risk between marine contractors and structural engineers.
- Export cable burial compliance:Post-lay trenching and protection requirements under the Crown Estate seabed licensing create unpredictable marine spread durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Power EPC Market |
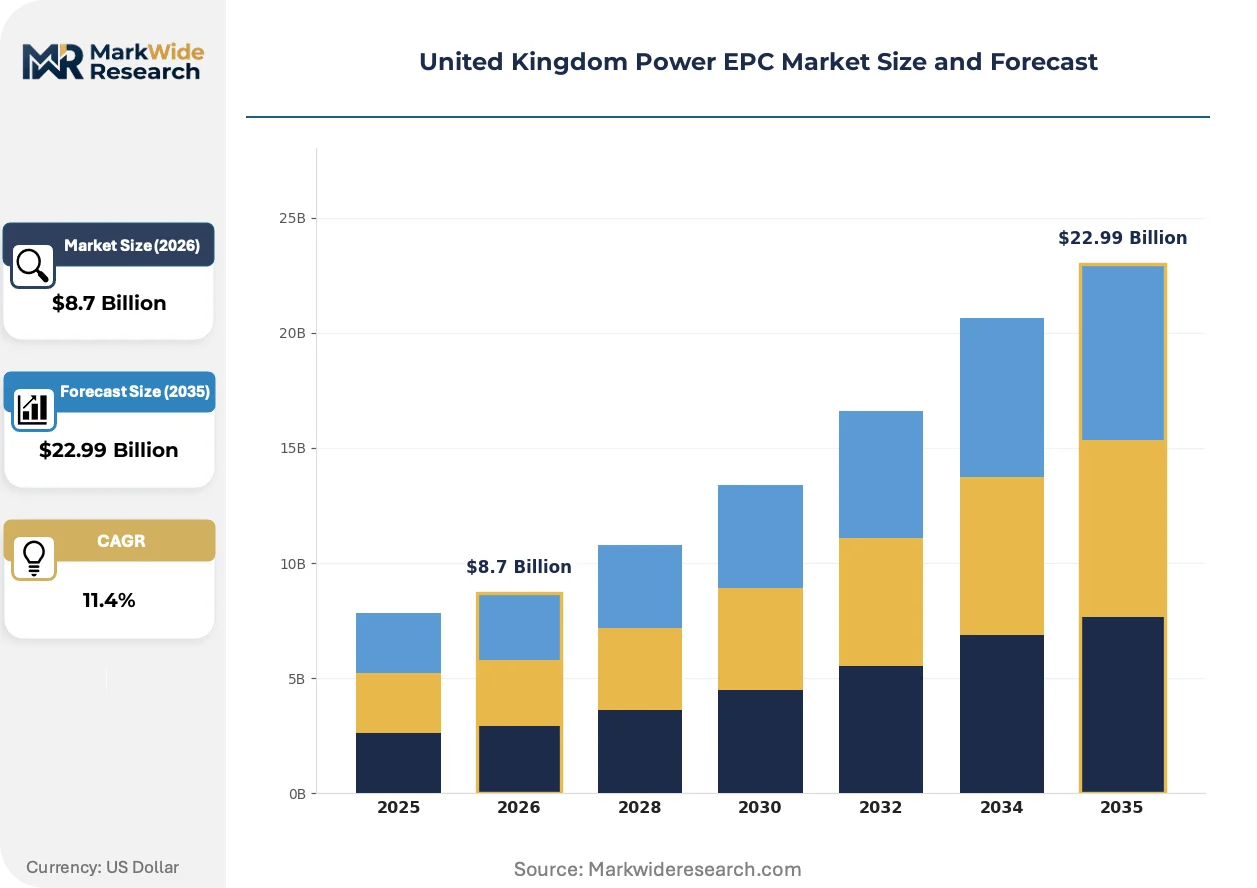
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering Services, Procurement, Construction, Project Management Technology: Wind Energy, Solar Power, Hydropower, Biomass Energy End User: Utilities, Independent Power Producers, Government Entities, Industrial Clients Project Size: Small Scale, Medium Scale, Large Scale, Utility-Scale |
| Companies Covered | Fluor Ltd, Doosan Babcock Ltd, Bechtel Corporation, Wood plc, Laing O'Rourke, Ramboll UK Limited, Siemens AG, ABB Ltd, Ørsted AS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Power EPC Market Evolving Landscape
Modular fabrication methods and digital twin integration are compressing offshore construction schedules while regulatory pressure on supply chain emissions is reshaping material sourcing decisions across the project lifecycle.
Modular offshore substation topsides are decomposing traditional stick-built construction sequences. EPC contractors now pre-assemble switchgear, transformers, and control systems at fabrication yards in Hull and Lowestoft. This shift reduces offshore vessel-day exposure by sixty percent and compresses weather window dependency. The approach is decomposing conventional marine spread contracting into shore-based assembly and single-lift installation phases.
The UK government's Carbon Budget Delivery Plan mandates supply chain emissions disclosure for infrastructure projects above £50 million capital value. Developers must now report embodied carbon in steel monopiles and array cables through the Streamlined Energy and Carbon Reporting framework. Offshore wind projects face the steepest compliance burden, with some EPC firms embedding life-cycle assessment specialists within project management offices to maintain bidding eligibility.
Integrated service contracts are displacing fragmented multi-vendor arrangements. Developers increasingly procure single EPC packages covering turbine supply agreements, balance-of-plant installation, and commissioning rather than managing tiered subcontractor interfaces. This concentration is most visible in Scotland's offshore wind pipeline, where Crown Estate Scotland leasing rounds have attracted consortia seeking turnkey execution certainty. Contractors respond by deepening in-house capability across geotechnical engineering, marine operations, and high-voltage grid connection.
United Kingdom Power EPC Market Segmentation
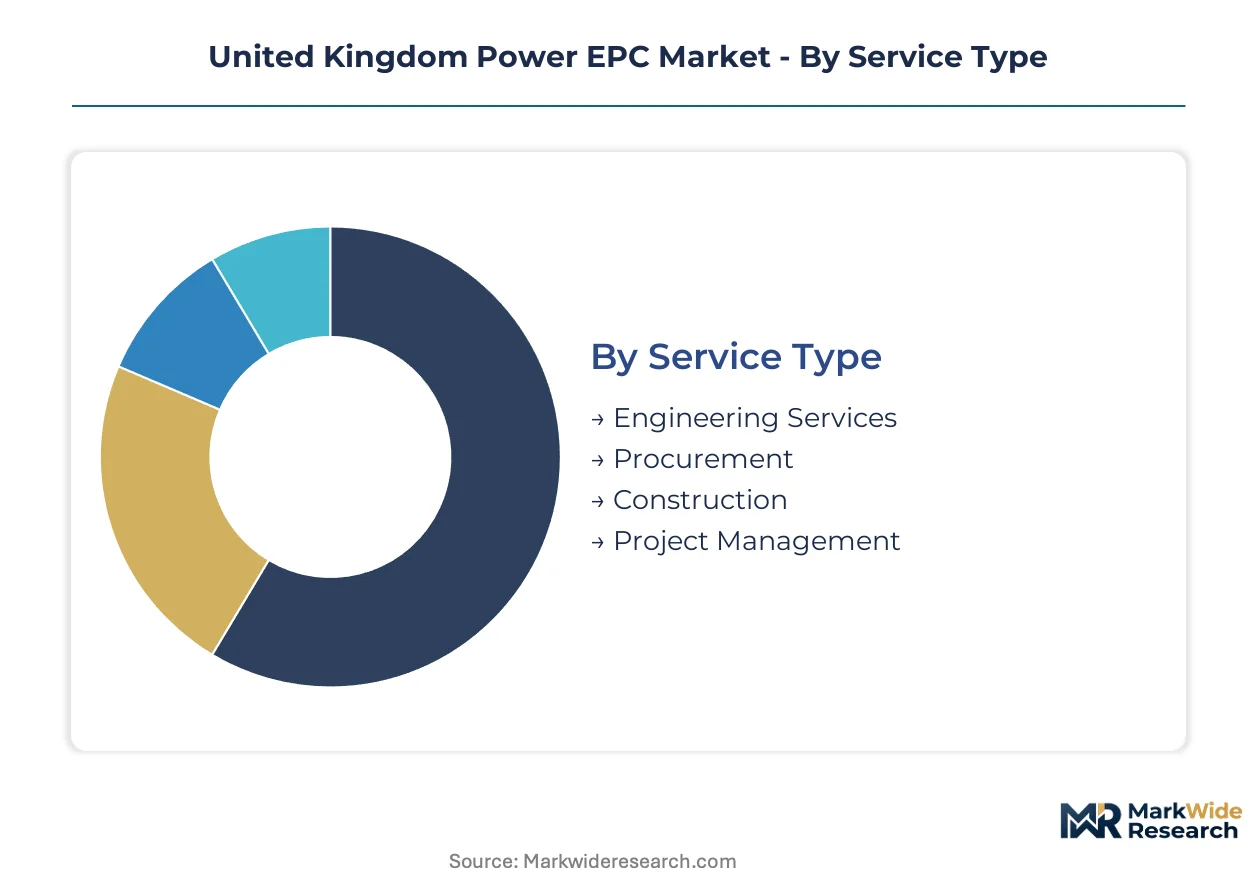
Segmentation in the United Kingdom Power EPC Market reveals how regulatory frameworks and project economics allocate contract value across distinct service bundles. Each category reflects specific interface risks between developers, contractors, and grid operators that shape procurement strategies.
Service Type:
Ofgem's price control mechanisms and the Contracts for Difference regime create divergent margin profiles across service phases, with early-stage engineering commanding premium rates due to design-lock effects on total capital expenditure.
- Engineering Services:Front-end design and feasibility studies determine sixty to seventy percent of ultimate project costs through foundation specification and grid connection routing. Demand concentrates in Scotland's offshore wind zones where Crown Estate Scotland leasing rounds require detailed geotechnical submissions before construction consent.
- Construction:Physical installation of turbines, foundations, and export cables operates under fixed-price contracts that transfer weather and vessel availability risks to EPC firms. The English East Coast cluster pulls specialized jack-up vessel fleets during compressed April-October work windows mandated by Maritime and Coastguard Agency licensing.
- Procurement:Consolidated sourcing of turbine supply agreements and balance-of-plant packages under single-point accountability reduces developer interface management.
- Project Management:Integrated coordination across marine contractors, structural engineers, and grid connection timelines anchors execution certainty for consortia bidding Crown Estate rounds.
Construction handles the majority of throughput; Engineering Services is the fastest mover on share as design decisions increasingly determine project bankability.
Technology:
Cost tier differentiation separates mature onshore technologies from capital-intensive offshore systems requiring specialized marine spreads and dynamic cable infrastructure.
- Wind Energy:Offshore projects dominate EPC contract values through steel monopile or jacket foundations, 33-66 kV array cables, and 132-400 kV export systems. Scotland's Highland and Island regions plus England's East Coast zones concentrate development activity under CfD auction pressure.
- Solar Power:Ground-mount and rooftop photovoltaic installations utilize standardized civil works and inverter procurement with shorter execution timelines. England's southern counties attract utility-scale pipeline development under streamlined planning pathways.
- Hydropower:Run-of-river and pumped storage schemes require bespoke civil engineering and tunneling expertise concentrated in Scottish hydroelectric heritage zones.
- Biomass Energy:Combined heat and power plants and dedicated biomass facilities depend on fuel supply chain integration and emissions compliance under the UK Emissions Trading Scheme.
Wind Energy captures the dominant share of EPC contract value; Solar Power is expanding most quickly on project count as distributed generation accelerates.
End User:
Customer type determines risk allocation preferences between turnkey fixed-price arrangements and target-cost contracts with shared completion exposure.
- Utilities:Vertically integrated grid operators procure integrated EPC packages covering generation assets and transmission reinforcement under regulated asset base frameworks. National Grid ESO connection queue reforms shape their commissioning sequence priorities.
- Independent Power Producers:Project finance-dependent developers demand single-point accountability to satisfy lender technical due diligence requirements on offshore wind schemes.
- Government Entities:Crown Estate and Crown Estate Scotland lessors drive standardization through leasing round requirements that mandate environmental impact assessment integration.
- Industrial Clients:Corporate power purchase agreement offtakers procure behind-the-meter generation and grid-scale battery storage for supply security and carbon reporting compliance.
Utilities anchor contract volume through regulated investment programs; Independent Power Producers are climbing the fastest on project origination as CfD auctions attract new market entrants.
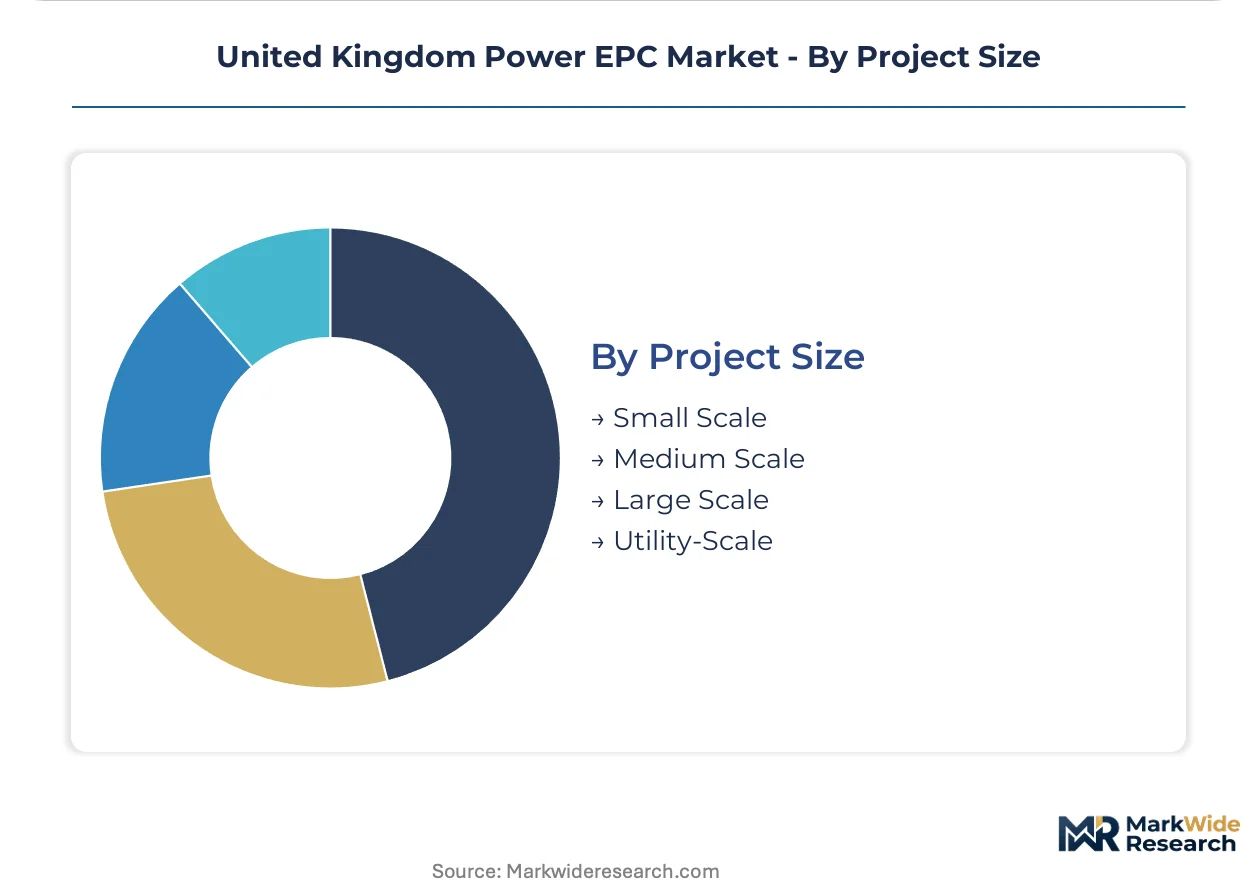
Project Size:
Scale tier determines contractor qualification thresholds and the viability of modular fabrication approaches versus stick-built execution.
- Utility-Scale:Projects exceeding 100 MW capacity justify dedicated vessel charters and yard pre-assembly of offshore substation topsides. Norfolk and Yorkshire zones offer shallow water depths that reduce installation complexity for fixed-bottom foundations.
- Large Scale:Developments between 50-100 MW balance fabrication economies against portfolio diversification needs for independent developers.
- Medium Scale:Distributed battery storage and solar arrays concentrate in Scottish Highlands where grid reinforcement constraints shape project sizing.
- Small Scale:Commercial rooftop solar and single-turbine installations operate through standardized EPC frameworks with reduced bespoke engineering content.
Utility-Scale dominates absolute contract value; Medium Scale is gaining share fastest as grid-scale battery storage proliferates across distribution network constraint zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland deploys EPC capacity toward offshore wind and grid-scale battery storage, while England concentrates procurement around East Coast offshore clusters and southern solar arrays. Wales and Northern Ireland pursue divergent pathways shaped by grid constraints and devolved planning frameworks.
Scotland
Crown Estate Scotland leasing rounds drive demand for integrated offshore wind EPC packages covering foundation installation and grid connection. Marine licensing under the Maritime and Coastguard Agency compresses construction windows to April-October periods. The Scottish Highlands concentrate battery storage development where grid reinforcement constraints shape project sizing and contractor selection.
England
Norfolk and Yorkshire offshore zones attract fixed-bottom foundation specialists due to shallow water depths and CfD auction pressure. Ofgem's price control mechanisms shape utility procurement of transmission reinforcement under regulated asset base frameworks. Southern counties host utility-scale solar pipelines benefiting from streamlined national significant infrastructure project pathways.
Wales
Grid connection queue delays under National Grid ESO protocols strand renewable generation projects in pre-construction phases. The Welsh Government's renewable energy targets contrast with limited transmission capacity west of the English border. Irish Sea offshore zones near Anglesey draw floating wind technology trials as water depths exceed fixed-bottom economic thresholds.
Northern Ireland
Single electricity market integration with the Republic of Ireland creates cross-border EPC coordination requirements for grid-scale projects. The Utility Regulator's price controls limit utility investment capacity compared to Great Britain counterparts. Onshore wind repowering dominates contractor activity as planning permission for greenfield sites faces sustained local opposition.
United Kingdom Power EPC Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the United Kingdom Power EPC Market. Tier-one contractors control end-to-end project delivery through captive vessel fleets and in-house fabrication yards. Three archetypes dominate: offshore wind specialists with marine operations expertise, integrated energy conglomerates with turbine manufacturing arms, and construction majors with modular assembly capabilities. Competitive moves concentrate on securing early labor commitments for high-voltage cable jointers and consolidating procurement functions under single-point accountability structures.
Within the integrated project management tier, Fluor Ltd and Wood plc exemplify firms that coordinate geotechnical surveys, foundation installation, and grid connection timelines through dedicated offices. Siemens AG occupies a position representing the manufacturing-integrated archetype with in-house control over turbine generators and power conversion systems. These three companies anchor the competitive structure by demonstrating how capability depth across marine operations, modular fabrication, and electrical systems integration determines bidding eligibility for Crown Estate and Crown Estate Scotland leasing rounds.
| Leading Market Players |
|---|
| Fluor Ltd |
| Doosan Babcock Ltd |
| Bechtel Corporation |
| Wood plc |
| Laing O'Rourke |
| Ramboll UK Limited |
| Siemens AG |
| ABB Ltd |
| Ørsted AS |
| Others |
Value Network & Pricing Analysis
Twelve-month vessel charter lead-times for heavy-lift jack-up units concentrate pricing power with European yard operators and compress contractor margins on fixed-price EPC contracts. This supply bottleneck feeds directly into project cost structures, as developers absorb premium day-rates or face construction window forfeiture under Maritime and Coastguard Agency licensing constraints.
Pricing Analysis
Long-term offtake contracts under the Contracts for Difference regime dominate developer procurement, with strike-price certainty enabling fixed-price EPC awards that transfer completion risk to contractors. Price differentiation rests on vessel availability windows and foundation fabrication certification tiers, with Health and Safety Executive-accredited crews commanding substantial premiums. Cost compression in turbine supply agreements is intensifying because OEMs face raw material volatility and logistics bottlenecks. Independent Power Producers exhibit highest price sensitivity due to project finance covenants, while vertically integrated utilities absorb margin pressure through regulated asset base recovery mechanisms.
Supply Chain Analysis
Strait of Dover heavy-lift vessel transit underwrites offshore construction schedules, with jack-up unit positioning from Danish, Dutch, and Belgian ports determining project sequencing feasibility. Steel monopile fabrication draws from German and Spanish heavy plate mills, while high-voltage cable manufacturing centers on Norwegian and Italian facilities. Single-source vulnerability concentrates in purpose-built installation vessels with lifting capacity above 1,500 tonnes. Distribution runs through Crown Estate seabed licensing rounds that gate project origination and contractor qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom Power EPC Market faces substitution pressure from modular fabrication approaches and digital-twin-enabled remote commissioning that reduce offshore vessel-day exposure. Incumbents must navigate this capability shift while defending integrated project management positions.
For Market Incumbents: Compound captive vessel fleet utilization through multi-project charter stacking across Crown Estate Scotland and English East Coast leasing rounds. Deepen backward integration into foundation steel sourcing via partnerships with German heavy plate mills to hedge price volatility. This defends margin position against emerging EPC consortia with modular yard assembly capabilities.
For New Entrants and Emerging Players: Lead with grid-scale battery storage EPC packages in Scottish Highland constraint zones where transmission reinforcement delays strand utility-scale wind projects. Target medium-scale distributed generation contracts below 50 MW that escape jack-up vessel dependency. Pursue go-to-market positioning through life-cycle assessment compliance services under the Streamlined Energy and Carbon Reporting framework.
For Investors and Strategic Acquirers: Carve-out targets emerge from European engineering conglomerates divesting non-core offshore construction units amid energy transition portfolio rebalancing. Long-term viability hinges on contractor ability to execute floating wind technology convergence in Celtic Sea depths. Monitor Crown Estate Scotland leasing round participation rates as inflection indicator for contractor backlog quality and pricing discipline.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Scale-Up | Pre-assembly at Hull and Lowestoft yards reduces vessel-day exposure by sixty percent under Maritime and Coastguard Agency windows. |
| Jack-Up Vessel Charter Stacking | Multi-project fleet deployment across Norfolk and Yorkshire zones maximizes utilization during compressed April-October work periods. |
| Carbon Reporting Compliance Integration | Embedded life-cycle assessment specialists maintain bidding eligibility for Contracts for Difference auction participants. |
| High-Voltage Cable Jointer Certification Pipeline | Health and Safety Executive pathway expansion addresses specialist labor scarcity constraining project commissioning timelines. |
| Floating Wind Technology Licensing | Semi-submersible platform expertise unlocks deeper Celtic Sea sites previously inaccessible to fixed-bottom foundations. |
Research Methodology
Desk research of Crown Estate leasing round documentation, Ofgem price control determinations, and Maritime and Coastguard Agency marine licensing records preceded structured interviews with EPC project directors, offshore construction managers, utility procurement leads, and independent power producer development executives. Secondary validation drew from National Grid ESO connection queue data, Health and Safety Executive certification statistics, and Contracts for Difference auction results. Bottom-up project pipeline aggregation triangulated against top-down market sizing from regulatory capacity targets.
Variance decomposition across service type, technology, end user, and project scale dimensions anchored the analytical framework over the projection horizon. CAGRs derived from regression against CfD auction capacity allocations and vessel fleet expansion schedules. Forecast inputs incorporated seasonal weather window constraints, foundation steel price indices, and grid connection queue reform implementation timelines.
Underlying assumptions cover sustained CfD auction participation, stable Health and Safety Executive regulatory frameworks, and jack-up vessel delivery schedules from European yards, with deviation risk concentrated in floating wind technology maturation rates and Crown Estate seabed licensing pace. Practitioners should keep alternative scenarios live as National Grid ESO connection queue reforms and Carbon Budget Delivery Plan enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Natural Gas Turbine Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Levant Power Cable Market
Power Equipment
Turbine Control Systems Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Industrial Gas Turbine Sales Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Ecuador Power EPC Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Asia-Pacific Steam Turbine Market
Power Equipment
Power Engineering, Procurement, and Construction (EPC) Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
AC Power Sources Market
Power Equipment
Wind Turbine Gearbox Repair and Refurbishment Market