
 Egypt Power EPC Market | 2026-2036
Egypt Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Power EPC Market Foresight
Utility procurement priorities is shifting toward hybrid renewable-thermal configurations as grid stability concerns mount. Hassan Allam Holding leverages its construction scale to dominate conventional thermal builds along the Nile corridor. Elsewedy Electric anchors Egypt's domestic supply chain through in-house cable and transformer manufacturing. Siemens AG competes on digital grid integration capabilities for complex EPC packages.
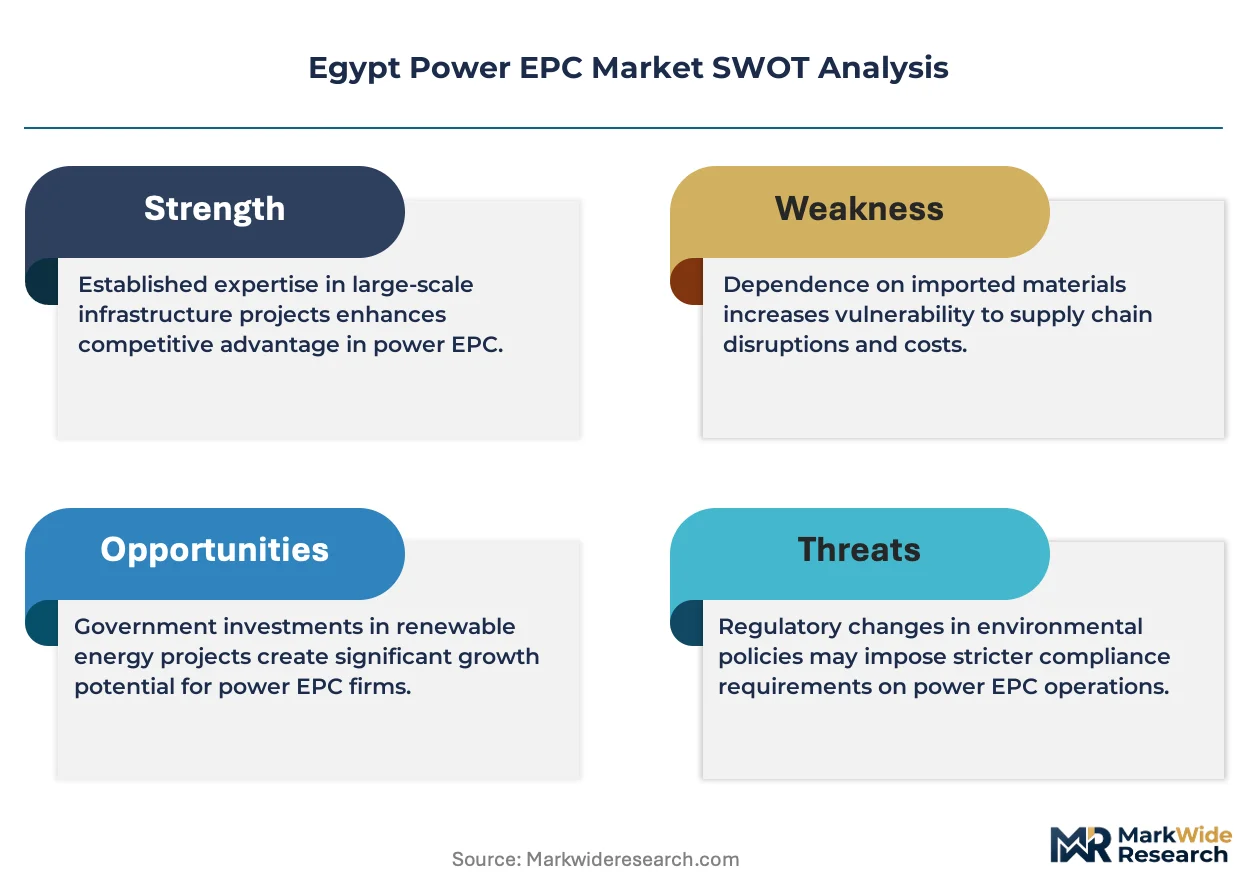
Egypt Power EPC encompasses the full-scope engineering, procurement, and construction of generation, transmission, and distribution infrastructure with rated capacities spanning 50 MW distributed plants to 4.8 GW combined-cycle facilities. Thermal technology retains the largest installed base, though renewable EPC contracts are accelerating fastest as Egyptian Electricity Holding Company tenders favor solar PV and onshore wind with local content requirements. Construction services capture the deepest margin pools due to civil works complexity and steel-intensive balance-of-plant scope, while commissioning remains concentrated among specialized international firms with grid-code certification.
Egypt's Ministry of Electricity and Renewable Energy, the Egyptian Electric Utility and Consumer Protection Regulatory Agency, and the New and Renewable Energy Authority govern licensing, tariff structures, and private participation frameworks. These bodies enforce local content thresholds and grid interconnection standards that determine EPC contractor eligibility and equipment sourcing rules. Stakeholders must monitor regulatory adjustments to renewable auction designs and gas-to-power transition timelines.
Market Dynamics
The Egyptian Electricity Holding Company's pivot toward hybrid renewable-thermal configurations is compressing traditional EPC contractor specialization and forcing capability convergence across generation technologies.
Growth Catalysts
- Feed-in Tariff Framework:Egypt's renewable energy feed-in tariff mechanism guarantees long-term power purchase agreements, de-risking private capital deployment into utility-scale solar and wind installations.
- Suez Canal Economic Zone:Industrial load centers clustering around SCZONE installations are generating concentrated demand for captive power plants and grid interconnection infrastructure.
- Local Content Mandates:Domestic manufacturing thresholds enforced by Egyptian Electric Utility and Consumer Protection Regulatory Agency are channeling EPC spend toward contractors with in-country fabrication capabilities.
Market Restraints
- Steel Input Volatility:Balance-of-plant construction depends on imported structural steel, exposing project margins to global commodity price swings and currency fluctuation against the Egyptian pound.
- Grid Interconnection Bottlenecks:Transmission capacity constraints in Upper Egypt and Western Desert renewable zones delay commercial operation dates and strain contractor working capital cycles.
- Foreign Equipment Dependence:High-voltage transformers and gas turbines remain concentrated among European and East Asian suppliers, creating procurement lead time risk and forex exposure.
Strategic Opportunities
- Green Hydrogen Integration:Electrolyzer co-location with renewable generation sites in the Red Sea corridor opens EPC scope for power-to-X infrastructure bundling.
- Digital Twin Deployment:Convergence of SCADA systems with predictive maintenance platforms enables contractors to capture recurring revenue through long-term asset management contracts.
- Distribution Network Modernization:Smart metering mandates from the Ministry of Electricity and Renewable Energy create retrofit opportunities across Egypt's aging medium-voltage infrastructure.
Industry Challenges
- Grid-Code Certification Delays:Specialized commissioning engineers with Egyptian Electricity Transmission Company certification remain scarce, extending project handover timelines.
- Legacy Asset Integration:New renewable capacity must synchronize with existing thermal fleet control systems, complicating engineering scope and interface management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Power EPC Market |
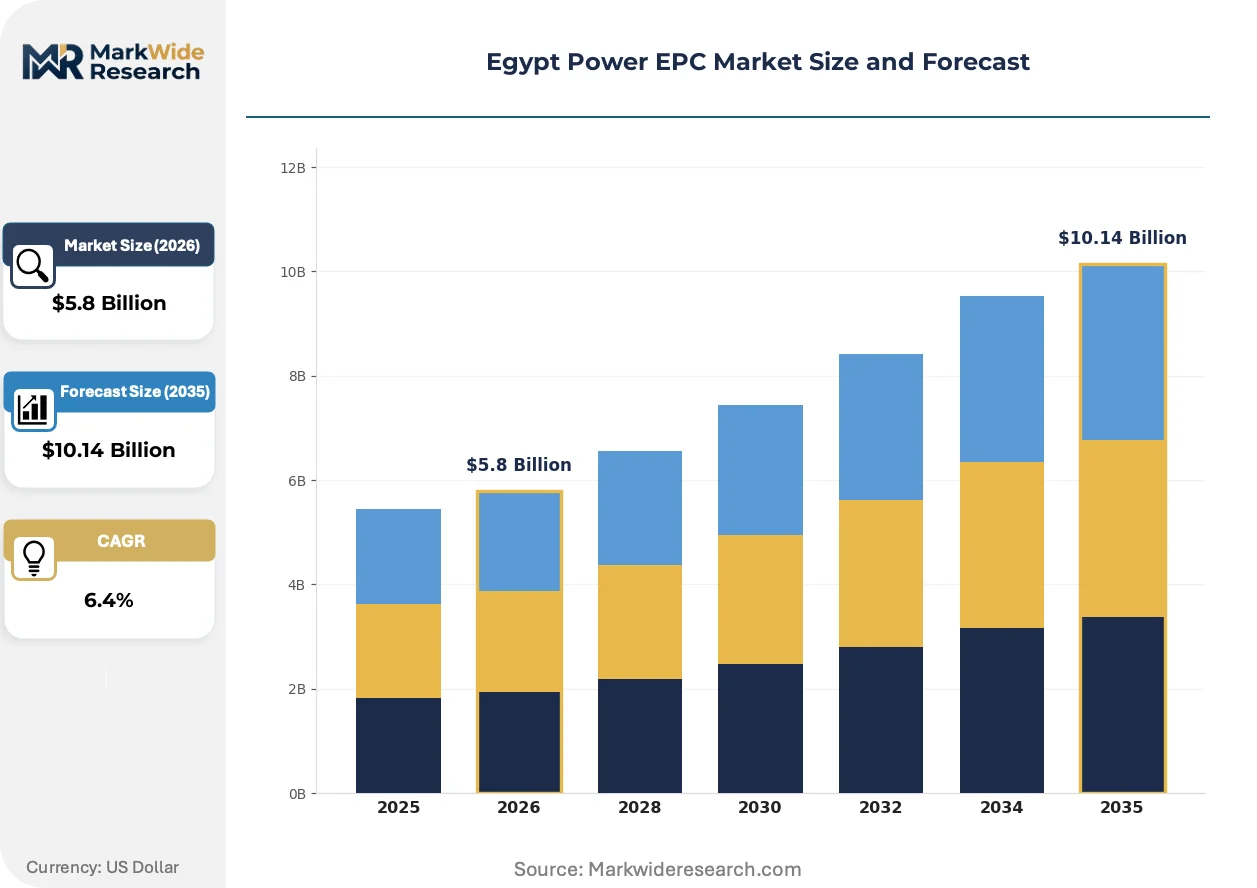
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Construction, Project Management, Commissioning, Maintenance Technology: Renewable, Thermal, Hydropower, Nuclear End User: Utilities, Independent Power Producers, Government, Industrial Installation: Onshore, Offshore, Underground, Above Ground |
| Companies Covered | Hassan Allam Holding, Scatec, Siemens AG, ACWA Power, Mitsubishi Corporation, Elsewedy Electric, General Electric Company, PowerChina, Orascom Construction, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Power EPC Market Shifts & Advancements
Digital engineering platforms and modular construction methods are compressing EPC project timelines while Egyptian regulatory pressure on local content is reshaping equipment sourcing geography.
Building Information Modeling software is automating clash detection and construction sequencing for complex balance-of-plant layouts. Egyptian Electricity Holding Company tender evaluations now weight digital deliverables alongside traditional technical compliance. The technology is automating engineering review cycles that previously consumed 15-20 percent of pre-construction schedules.
Egypt's renewable energy feed-in tariff revisions now mandate domestic content thresholds for solar module assembly and steel fabrication. The Egyptian Electric Utility and Consumer Protection Regulatory Agency audits contractor supply chain documentation during milestone payments. Foreign EPC firms are responding through joint ventures with local fabricators to preserve bidding eligibility.
Turnkey EPC contracts with integrated operations and maintenance terms are displacing traditional split procurement across Egyptian utility tenders. State-owned offtakers prefer single-point accountability that transfers operational risk to contractors for initial contract years. This pattern concentrates most visibly in the Benban Solar Park cluster and Gulf of Suez wind zones.
Egypt Power EPC Market Segmentation
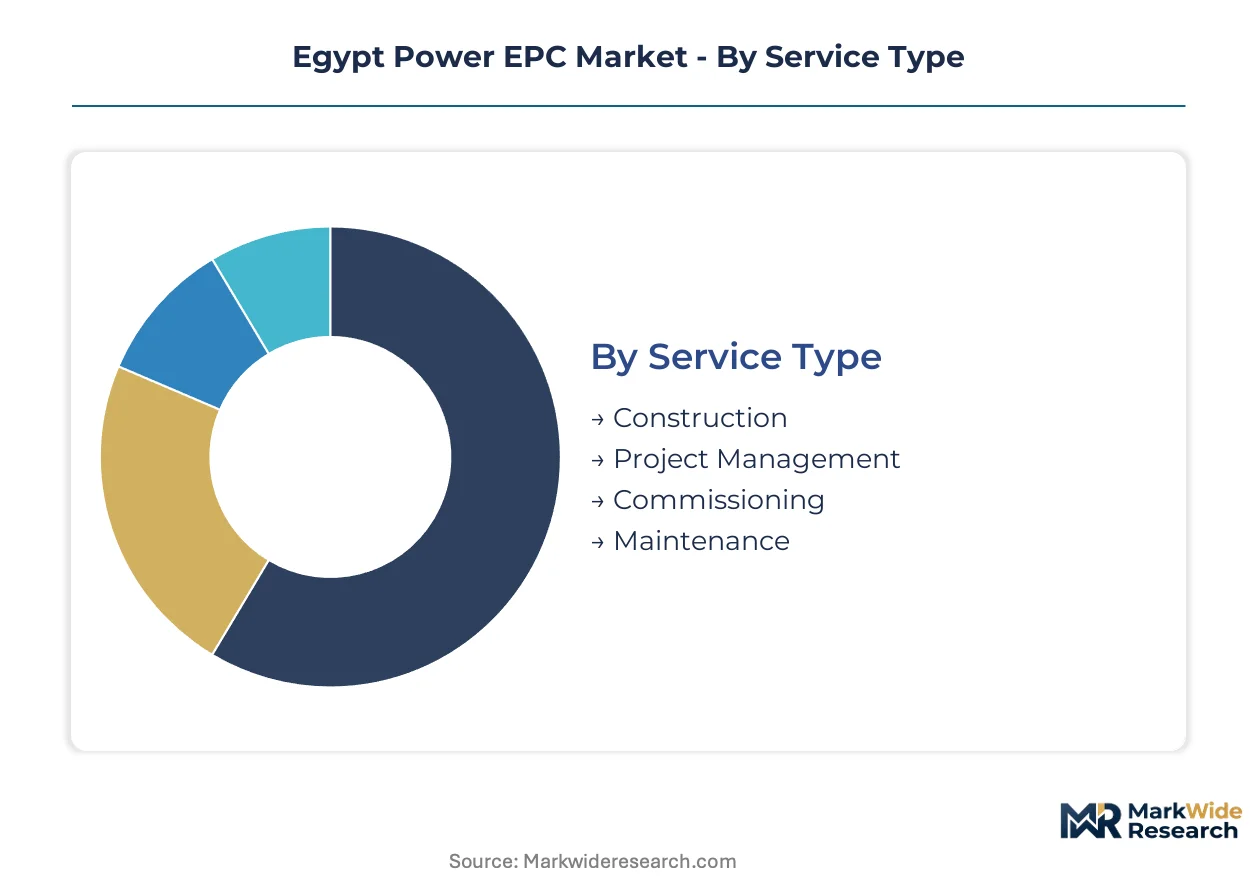
Egypt's Power EPC market exhibits distinct demand patterns across service, technology, and installation dimensions. Contractor positioning and procurement strategies diverge sharply depending on which segmentation axis Egyptian Electricity Holding Company prioritizes in tender design.
Service Type:
Technical complexity and margin capture vary by execution phase, with civil works commanding premium pricing due to steel intensity and labor mobilization requirements.
- Construction:Balance-of-plant civil works, structural steel erection, and mechanical installation constitute the deepest value pool. Suez Canal Economic Zone industrial clusters drive concentrated demand for captive power plant construction with accelerated timelines.
- Project Management:Owner's engineer and construction management services coordinate multi-contractor interfaces across hybrid renewable-thermal configurations. Egyptian regulatory milestones require dedicated local presence for permit navigation and grid authority liaison.
- Commissioning:Grid-code certification and synchronization testing with Egyptian Electricity Transmission Company standards.
- Maintenance:Long-term service agreements bundled with turnkey EPC awards.
Construction leads on scale; Project Management leads on momentum as hybrid project complexity escalates.
Technology:
Generation technology selection determines equipment sourcing geography, local content compliance thresholds, and engineering skill requirements.
- Renewable:Solar PV and onshore wind dominate new capacity awards under Egypt's feed-in tariff revisions. Benban Solar Park and Gulf of Suez wind zones concentrate procurement activity with mandatory domestic module assembly thresholds.
- Thermal:Combined-cycle gas turbines retain the largest installed base along the Nile corridor. Existing fleet modernization and efficiency upgrades sustain contractor pipelines despite renewable pivot.
- Hydropower:Rehabilitation of aging Aswan High Dam infrastructure and small-scale run-of-river development.
- Nuclear:El Dabaa project execution with Russian technology transfer requirements.
Thermal leads on installed base; Renewable leads on new award velocity.
End User:
Contracting entity type shapes risk allocation, financing structure, and local content enforcement intensity.
- Utilities:Egyptian Electricity Holding Company tenders favor single-point accountability with integrated O&M terms. State-backed offtake de-risks long-term revenue streams for contractors.
- Independent Power Producers:Private capital deployment under feed-in tariff frameworks with international financing requirements.
- Government:Ministry of Electricity and Renewable Energy direct awards for strategic transmission infrastructure.
- Industrial:Captive power demand from SCZONE manufacturing facilities seeking grid independence.
Utilities lead on contract volume; Industrial leads on growth trajectory as zone development accelerates.
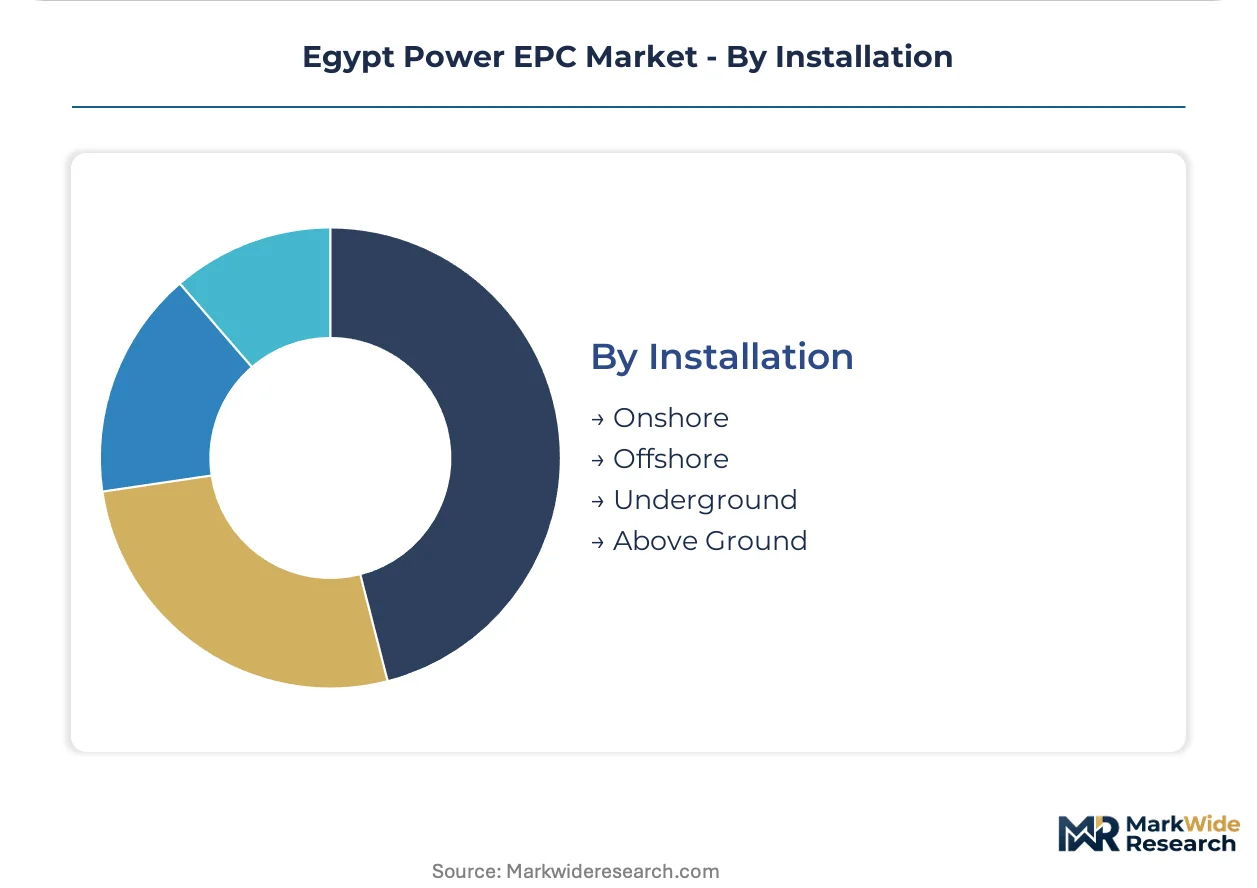
Installation:
Physical deployment configuration determines civil works intensity, environmental permitting complexity, and grid interconnection cost structure.
- Onshore:Utility-scale solar and wind development across Western Desert and Red Sea coastal zones. Land acquisition and transmission spur extensions constitute primary execution challenges.
- Above Ground:Overhead transmission lines and substation infrastructure dominate T&D expansion. Steel tower fabrication local content mandates reshape supplier geography.
- Underground:Urban cable systems for Cairo and Alexandria distribution network densification.
- Offshore:Submarine cable installations for cross-Red Sea interconnection feasibility.
Onshore leads on project count; Above Ground leads on capital deployment scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suez Canal Economic Zone anchors Egypt's power infrastructure expansion, with industrial load centers clustering around port and manufacturing installations driving concentrated demand for captive generation and grid interconnection.
Greater Cairo Metropolitan Area
Distribution network densification and smart metering retrofits dominate procurement activity across Egypt's capital region. The Ministry of Electricity and Renewable Energy mandates advanced metering infrastructure deployment across Cairo and Giza governorates. New Capital City construction is absorbing substantial transmission infrastructure investment with accelerated commissioning timelines.
Nile Delta Industrial Corridor
Textile and food processing facilities require stable power supply for continuous operations across Damietta, Mansoura, and Tanta industrial zones. Egyptian Electric Utility and Consumer Protection Regulatory Agency enforces grid code compliance for medium-voltage interconnections. El Sewedy Electric's cable manufacturing complex in 10th of Ramadan City supplies domestic EPC contractors with reduced procurement lead times.
Western Desert Renewable Zone
Utility-scale solar PV development concentrates around Benban and Kom Ombo sites with mandated domestic content thresholds. The New and Renewable Energy Authority administers land allocation and environmental permitting for desert installations. Benban Solar Park hosts over 30 individual plants with shared transmission spur infrastructure reducing per-project interconnection costs.
Gulf of Suez Wind Corridor
Onshore wind capacity expansion targets Zaafarana and Gabal El Zeit sites with proven wind resource profiles. Egyptian Electricity Holding Company tenders specify hybrid renewable-thermal configurations to address grid stability requirements. Ras Ghareb and Zafarana industrial zones host cement and mining operations purchasing power through bilateral agreements with IPP developers.
Upper Egypt Growth Belt
Sugar processing and fertilizer manufacturing drive industrial electrification demand across Qena, Sohag, and Aswan governorates. The Aswan High Dam rehabilitation program sustains hydropower EPC activity alongside new renewable development. Kom Ombo solar complex and Aswan's emerging industrial zone are attracting private capital through feed-in tariff guarantees.
Egypt Power EPC Market Competitive Landscape
Joint venture formation dominates the current landscape as international contractors partner with local fabricators to satisfy Egyptian Electric Utility and Consumer Protection Regulatory Agency local content mandates. The market exhibits tiered concentration with a handful of integrated conglomerates controlling thermal and transmission infrastructure awards, while specialized renewable developers capture solar and wind EPC contracts. Strategic archetypes include domestic construction-heavy holding companies with in-house manufacturing, international technology providers bundling digital grid solutions, and regional IPPs with captive EPC capabilities. Competitive positioning hinges on fabrication scale for steel-intensive balance-of-plant scope and grid-code certification speed for commissioning handover.
Within the domestic integrated tier, Hassan Allam Holding and Elsewedy Electric exemplify archetypes of construction-led conglomerates with captive supply chain control. Siemens AG occupies a position among international technology providers competing on digital grid integration and complex thermal package execution. These three anchors illustrate the capability convergence required as Egyptian Electricity Holding Company tenders increasingly favor hybrid renewable-thermal configurations with single-point accountability structures.
| Leading Market Players |
|---|
| Hassan Allam Holding |
| Scatec |
| Siemens AG |
| ACWA Power |
| Mitsubishi Corporation |
| Elsewedy Electric |
| General Electric Company |
| PowerChina |
| Orascom Construction |
| Others |
Supply & Pricing Matrix
Captive in-country steel fabrication anchors Egyptian EPC contractor positioning and pricing power against imported structural inputs. Egyptian Electric Utility and Consumer Protection Regulatory Agency local content mandates force foreign firms into joint ventures with domestic fabricators, compressing procurement flexibility while stabilizing milestone payment eligibility.
Pricing Analysis
Imported structural steel and high-voltage transformer costs pass through directly to project owners under cost-plus contracting frameworks prevalent in Egyptian Electricity Holding Company tenders. Price differentiation rests on in-country fabrication scale versus foreign equipment bundling, with contractors possessing captive cable and transformer manufacturing commanding premium positioning. Cost compression in balance-of-plant civil works is intensifying because Suez Canal Economic Zone developers demand accelerated timelines. Industrial captive power buyers exhibit highest price sensitivity due to bilateral negotiation leverage, while utility-scale renewable offtakers accept standard tariff-indexed pricing.
Supply Chain Analysis
Skilled commissioning engineer shortages in Egypt and certification bottlenecks with Egyptian Electricity Transmission Company strain project handover timelines. Equipment sourcing concentrates in China, Germany, and South Korea for gas turbines and high-voltage transformers. Raw material dependencies span structural steel, copper conductors, and rare earth magnets for wind generators. Single-source vulnerability for grid-code certified commissioning specialists creates procurement lead time risk. Distribution runs through Egyptian Electricity Holding Company tender processes with milestone-linked payment structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt Power EPC constitutes a late-cycle quality story as Egyptian Electricity Holding Company tenders pivot toward hybrid renewable-thermal configurations demanding integrated capability portfolios. Procurement officers now weight digital deliverables and local content compliance above pure construction scale.
For Market Incumbents: Acquire grid-code certification capabilities and commissioning specialist teams to defend against international firms bundling digital twin platforms. Egyptian Electricity Transmission Company certification scarcity threatens incumbent handover timelines. Backward integration into steel fabrication preserves bidding eligibility under tightening local content thresholds. For New Entrants and Emerging Players: Mid-tier pricing gaps between premium international technology providers and economy domestic constructors create entry space for hybrid capability specialists. Western Desert renewable zones and Upper Egypt industrial corridors represent most penetrable geographies with underserved transmission infrastructure demand. Joint venture structures with established local fabricators accelerate Egyptian Electric Utility and Consumer Protection Regulatory Agency compliance. For Investors and Strategic Acquirers: Roll-up economics work for regional EPC specialists with captive manufacturing because Egyptian tender designs increasingly favor single-point accountability across generation technologies. Five-to-ten year viability hinges on electrolyzer co-location and power-to-X infrastructure bundling capability. Monitor Egyptian Electricity Holding Company auction design revisions for renewable-to-hybrid configuration shifts as primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | Foreign contractors partner with Egyptian fabricators to satisfy Egyptian Electric Utility and Consumer Protection Regulatory Agency local content mandates. |
| Digital Twin Deployment | SCADA convergence with predictive maintenance platforms enables recurring revenue capture through long-term asset management contracts. |
| Green Hydrogen Integration | Electrolyzer co-location with Red Sea renewable sites opens EPC scope for power-to-X infrastructure bundling. |
| Distribution Modernization | Smart metering mandates from Ministry of Electricity and Renewable Energy create retrofit opportunities across aging medium-voltage infrastructure. |
| Grid-Code Certification Investment | Specialized commissioning capabilities with Egyptian Electricity Transmission Company standards accelerate project handover timelines. |
Research Methodology
Direct dialogue with Egyptian Electricity Holding Company procurement officers, EPC project directors, IPP development leads, and steel fabrication plant managers grounded qualitative findings. Secondary validation drew from Egyptian Electric Utility and Consumer Protection Regulatory Agency tariff filings, New and Renewable Energy Authority land allocation records, Suez Canal Economic Zone investment bulletins, and Egyptian Electricity Transmission Company grid interconnection standards. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling enabled triangulation.
Bottom-up capacity addition tracking across thermal, renewable, and nuclear generation categories informed volume projections throughout the forecast period. Segmentation dimensions modeled encompass service type, generation technology, end-user contracting entity, and installation configuration. CAGRs derived from regression analysis against historical award velocity and regulatory milestone timelines. Forecast inputs incorporated feed-in tariff revision schedules and Suez Canal Economic Zone industrial load growth trajectories.
Caveats apply where Egyptian pound volatility, global steel commodity swings, or grid interconnection capacity constraints could materially shift the outlook. Forecasts reflect assumptions around regulatory enforcement continuity and foreign equipment import licensing efficiency. Material deviation in Suez Canal Economic Zone investment commitments or renewable auction design warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Wind Turbine Equipment Market
Power Equipment
G-3 PLC Solutions Market
Power Equipment
Induction Heating System Market
Power Equipment
Magnetic Bearing Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Turbine Governor Market
Power Equipment
South America Nuclear Power Plant Equipment Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Turbine Control Systems Market
Power Equipment
Ecuador Power EPC Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Industrial Gas Turbine Sales Market
Power Equipment
Qatar Power EPC Market
Power Equipment
Process Plants Gas Turbine Market
Power Equipment
India Nuclear Power Plant Equipment Market