
 Power Amplifier Market | 2026-2036
Power Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Power Amplifier Market Intelligence
REACH is recalibrating the cost-of-entry calculus for European power amplifier vendors by mandating restricted substance documentation across semiconductor supply chains. Qualcomm Technologies leverages its vertical integration into RF front-end modules to sustain margin control across 5G base station deployments. Texas Instruments anchors its competitive position through deep catalog breadth in LDMOS and GaN process technologies for industrial radar.
A power amplifier is an electronic device that increases the amplitude of an input signal to drive a load, typically operating across frequency ranges from DC to millimeter-wave with output power levels spanning milliwatts to kilowatts depending on architecture and thermal design. Its primary commercial purpose centers on enabling reliable signal transmission in wireless infrastructure, satellite links, and military electronic systems where link budget and spectral efficiency determine system viability. Solid-state amplifiers now lead volume shipments for telecommunications providers, while GaN-on-SiC technology captures the fastest expansion in radar systems and military applications where power density and thermal performance command premium positioning. Vacuum tube architectures retain niche dominance in high-power broadcasting and certain legacy defense platforms, though their margin pool contracts as solid-state alternatives achieve comparable output levels.
The FCC in the United States enforces emission masks and spectrum allocation rules that directly shape power amplifier efficiency targets and linearity specifications for wireless communication equipment. ETSI and the EU Green Deal collectively drive efficiency mandates and material restrictions that filter product portfolios available to European defense contractors and telecommunications providers. Stakeholders must monitor how spectrum reframing for 6G research and tightening defense export controls reshape qualification requirements and foundry capacity allocation across the supply base.
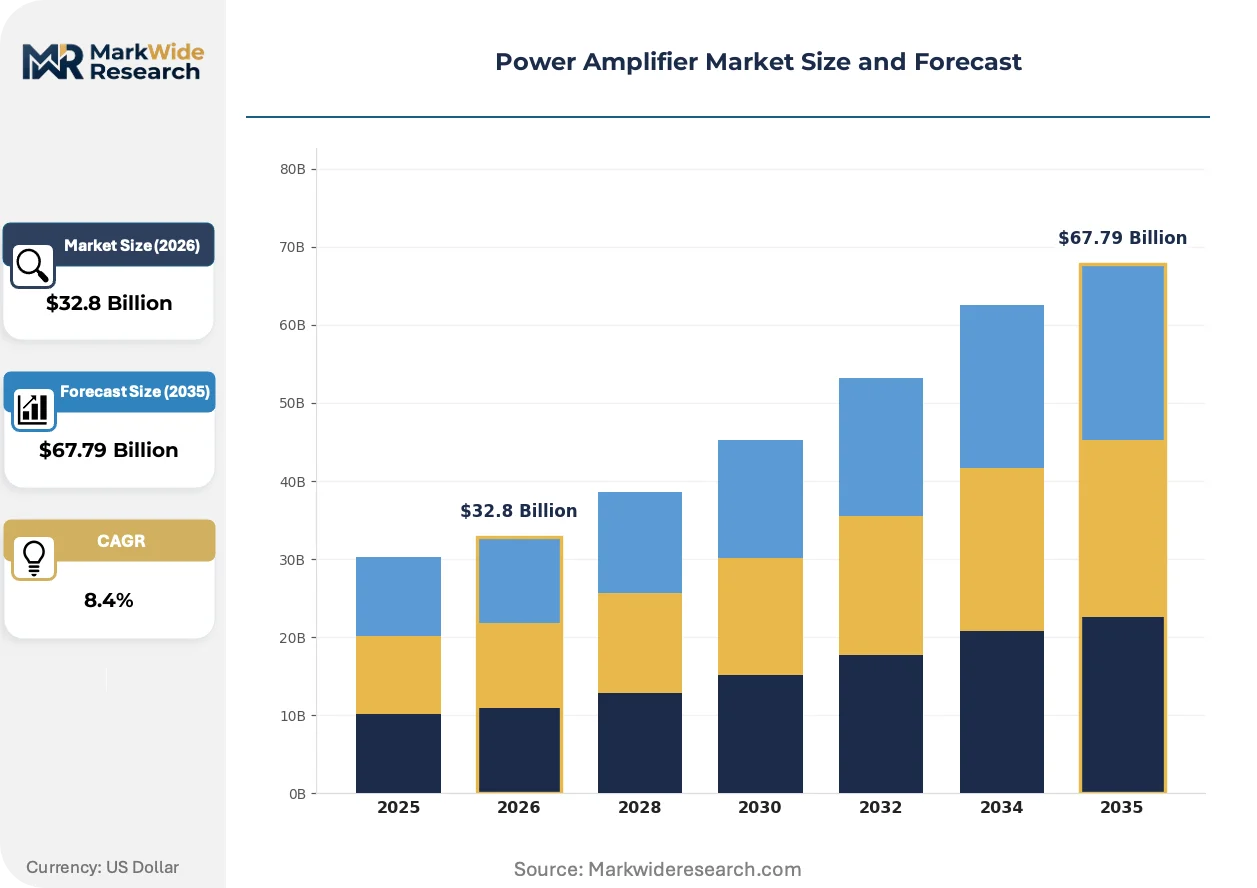
Market Dynamics
The transition from vacuum tube to solid-state architectures is compressing qualification timelines for defense contractors while expanding addressable applications for commercial RF equipment manufacturers.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating replacement cycles for legacy klystron and traveling-wave tube amplifiers across European broadcasting infrastructure.
- GaN-on-SiC thermal performance:Military radar procurement specifications now mandate power density thresholds that only wide-bandgap semiconductor processes can satisfy.
- Automotive radar clustering:Germany's industrial concentration around Munich and Stuttgart is generating localized demand spikes for 77-81 GHz amplifiers in advanced driver-assistance systems.
Market Restraints
- Substrate supply concentration:Silicon carbide wafer production remains geographically concentrated, creating foundry capacity bottlenecks for GaN epitaxy.
- REACH documentation burden:The European Chemicals Agency's substance-of-very-high-concern registry is extending qualification timelines for imported semiconductor components.
- Copper and rare earth volatility:Magnet and thermal management material costs fluctuate with mining output from concentrated supplier geographies.
Strategic Opportunities
- 6G research spectrum reframing:The FCC and NTIA are allocating millimeter-wave bands that require new amplifier architectures for sub-terahertz operation.
- Industrial RF heating:Food processing and materials curing applications in North America are adopting solid-state replacements for magnetron tubes.
- Backward integration into epitaxy:Captive control of GaN-on-SiC wafer production is reducing dependency on external foundry capacity.
Industry Challenges
- Compound semiconductor talent scarcity:RF device physics expertise resides in a narrow demographic of engineers trained in III-V material systems.
- ITAR and EAR compliance complexity:Dual-use technology export controls are fragmenting supply chains for defense-qualified amplifiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Amplifier Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid State, Vacuum Tube, Distributed, Traveling Wave, High-Power, Low-Noise Technology: GaN, LDMOS, Bipolar Junction Transistor, CMOS, SiGe, MESFET Application: Wireless Communication, Radar Systems, Satellite Communication, Test & Measurement, Broadcasting, Military End User Industry: Telecommunications Providers, Defense Contractors, Aerospace Firms, Consumer Electronics Manufacturers, Research Institutions, Broadcasting Companies |
| Companies Covered | Qualcomm Technologies Inc., Texas Instruments Inc., Broadcom Inc., STMicroelectronics, NXP Semiconductors, Qorvo Inc., Infineon Technologies AG, Analog Devices, Skyworks Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Amplifier Market Strategic Shifts & Innovations
Digital predistortion and envelope tracking techniques are reshaping efficiency benchmarks across telecommunications infrastructure, while thermal management innovations unlock higher continuous-wave output from compact solid-state packages.
GaN-on-diamond heat-spreading substrates is automating thermal design optimization for high-duty-cycle radar transmitters. Defense contractors in the United States are qualifying these architectures for next-generation electronic warfare platforms. The technology is compressing the size-weight-and-power trade space that previously constrained airborne and naval installations.
REACH substance restrictions are forcing reformulation of solder alloys and thermal interface materials throughout European supply chains. Component vendors must now document full material declarations across multi-tier supplier networks. The burden falls heaviest on small and medium enterprises serving dual commercial-defense markets.
Buyer consolidation among telecommunications infrastructure providers is concentrating procurement leverage with Ericsson, Nokia, and Samsung network equipment divisions. These OEMs are unbundling amplifier modules from integrated radio units, creating direct sourcing relationships with semiconductor vendors. The shift is most pronounced in North American 5G dense urban deployments where equipment refresh cycles have compressed below historical norms.
Power Amplifier Market Segmentation
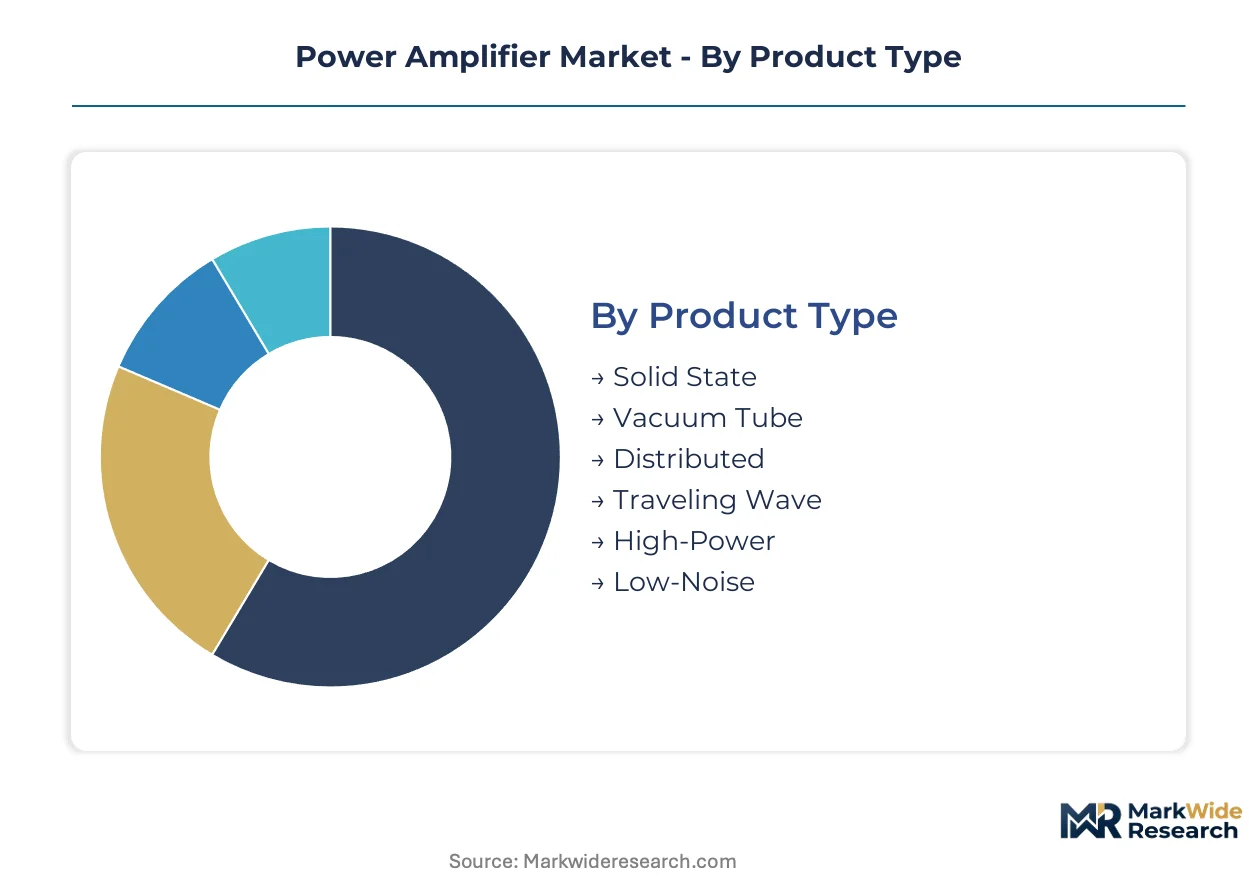
Power amplifier procurement patterns diverge sharply across technology platforms and end-use requirements. Defense contractors prioritize thermal performance and radiation hardness, while telecommunications providers optimize for cost-per-watt and spectral efficiency.
Product Type:
Supply concentration in epitaxial foundries favors solid-state architectures with established packaging ecosystems.
- Solid State:Silicon and compound semiconductor devices dominate volume production for 5G infrastructure and automotive radar. GaN-on-SiC variants capture premium positioning in military electronic warfare systems where power density thresholds exclude legacy alternatives.
- Vacuum Tube:Klystron and traveling-wave tube architectures retain installed base in high-power broadcasting transmitters above 10 kW. ETSI F-Gas Regulation mandates are accelerating replacement timelines across European terrestrial transmission networks.
- Distributed:Traveling-wave transistor arrays enable broadband amplification across octave bandwidths for electronic countermeasures.
- Traveling Wave:Helix-based designs sustain niche demand in satellite uplink terminals requiring high efficiency at Ku-band frequencies.
- High-Power:Multi-kilowatt systems cluster around radar transmitters and particle accelerator RF sources.
- Low-Noise:Cryogenic amplifiers command specialized procurement from radio astronomy observatories and deep-space communication facilities.
Solid State absorbs the bulk of installed capacity; GaN-on-SiC variants within this category are expanding most quickly.
Technology:
Process maturity curves separate cost-optimized volume production from qualification-intensive defense supply chains.
- GaN:Wide-bandgap epitaxy on silicon carbide substrates delivers breakthrough power density for phased-array radar. US Navy surface fleet modernization programs are mandating GaN transmit-receive modules for next-generation air defense systems.
- LDMOS:Laterally-diffused metal-oxide-semiconductor devices anchor cellular base station deployments below 4 GHz. Foundry capacity in Germany and the United States supports dual-source procurement strategies for infrastructure OEMs.
- Bipolar Junction Transistor:Silicon BJTs persist in avionics applications with legacy qualification heritage.
- CMOS:Fully-integrated silicon solutions enable consumer-grade millimeter-wave beamforming at 60 GHz.
- SiGe:Silicon-germanium BiCMOS processes optimize low-noise amplification for automotive radar receivers.
- MESFET:Gallium arsenide metal-semiconductor field-effect transistors retain cost advantage in satellite L-band power blocks.
LDMOS retains the largest cumulative installed base; GaN is climbing the fastest as defense qualification timelines compress.
Application:
Defense export control classifications fragment supply chains according to ITAR and EAR jurisdiction boundaries.
- Wireless Communication:Macro base stations and small-cell densification drive demand for multi-band linear amplifiers. FCC emission mask compliance shapes efficiency specifications for 5G massive MIMO deployments.
- Radar Systems:Active electronically scanned arrays require thousands of phase-coherent transmit modules per aperture. Germany's automotive radar cluster around Munich generates localized demand spikes for 77-81 GHz solid-state sources.
- Satellite Communication:Ka-band and Q/V-band gateways demand high linearity for multi-carrier operation.
- Test & Measurement:Broadband instrumentation amplifiers serve 5G and 6G research laboratories.
- Broadcasting:Terrestrial DVB-T2 transmitters transition from tube to solid-state under EU efficiency mandates.
- Military:Electronic warfare jammers and counter-IED systems prioritize instantaneous bandwidth and ruggedization.
Wireless Communication commands the dominant share of unit volume; Radar Systems are gaining share fastest on military modernization cycles.
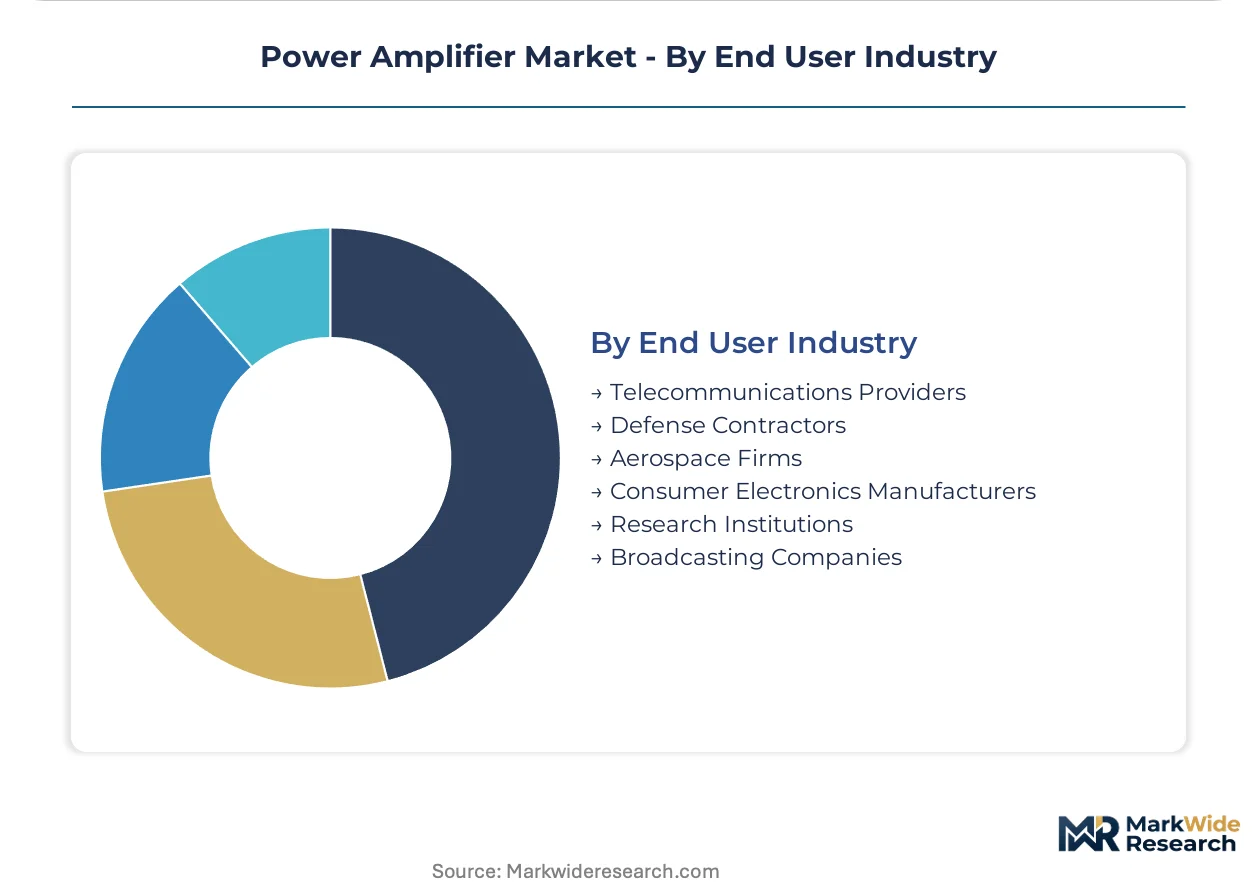
End User Industry:
Procurement consolidation among equipment OEMs is collapsing distributor tiers for high-volume segments.
- Telecommunications Providers:Ericsson, Nokia, and Samsung network divisions are unbundling amplifier modules from integrated radio units. Direct semiconductor sourcing agreements now govern 5G dense urban refresh cycles in North America.
- Defense Contractors:Raytheon, Lockheed Martin, and Northrop Grumman maintain captive GaN foundry relationships for classified programs. ITAR compliance complexity fragments supply chains for dual-use technologies.
- Aerospace Firms:Satellite manufacturers qualify radiation-hardened amplifiers for 15-year orbital lifetimes.
- Consumer Electronics Manufacturers:WiFi 7 and 60 GHz unlicensed devices drive CMOS integration at cost points below defense-qualified alternatives.
- Research Institutions:CERN and national laboratories procure specialized klystrons for accelerator upgrades.
- Broadcasting Companies:European public service broadcasters face F-Gas mandated replacement deadlines for tube-based transmitters.
Telecommunications Providers absorb the bulk of foundry output; Defense Contractors are expanding procurement most aggressively on electronic warfare priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Malaysia and Vietnam are drawing GaN epitaxy equipment investments away from traditional semiconductor hubs. Tax holidays and subsidized utility rates in Penang and Ho Chi Minh City are accelerating foundry buildouts for wide-bandgap semiconductor processing.
United States
The US Navy's surface fleet modernization mandates GaN transmit-receive modules for next-generation air defense radar systems. FCC spectrum reframing for 6G research is allocating millimeter-wave bands that demand new amplifier architectures. Defense contractors cluster around Boston and Washington DC corridors for ITAR-compliant supply chain proximity.
Germany
Automotive radar manufacturers in Munich and Stuttgart generate localized demand spikes for 77-81 GHz solid-state amplifiers. The EU F-Gas Regulation accelerates replacement cycles for legacy klystron transmitters across terrestrial broadcasting networks. Infineon Technologies anchors LDMOS foundry capacity in Dresden for dual-source cellular infrastructure procurement.
China
Domestic 5G base station deployment drives volume demand for multi-band linear amplifiers below 6 GHz. MIIT spectrum allocation rules shape efficiency specifications for massive MIMO equipment refresh cycles. Yangtze River Delta manufacturing clusters around Shanghai concentrate CMOS millimeter-wave integration for consumer-grade beamforming devices.
Japan
Satellite gateway operators in Tokyo and Osaka procure high-linearity amplifiers for Ka-band multi-carrier operation. METI efficiency mandates filter product portfolios available to telecommunications providers and defense contractors. Kanto region research institutions qualify cryogenic low-noise amplifiers for radio astronomy observatories.
South Korea
Samsung network equipment divisions unbundle amplifier modules from integrated radio units for direct semiconductor sourcing. The country's national spectrum regulator allocates bandwidth for dense urban 5G deployments requiring sub-6 GHz linearization. Seoul Capital Area electronics conglomerates backward integrate into RF front-end module production for margin control.
Power Amplifier Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across power amplifier supply chains. Tier-one semiconductor vendors leverage catalog breadth and captive foundry relationships to defend positioning in telecommunications infrastructure. Three archetypes dominate: integrated device manufacturers with in-house epitaxy, fabless designers outsourcing to compound semiconductor foundries, and vacuum tube specialists transitioning to solid-state alternatives. Capacity expansion and strategic partnerships represent the dominant competitive vectors as substrate supply concentration creates bottlenecks for GaN-on-SiC production.
Among diversified semiconductor conglomerates, Qualcomm Technologies Inc., Texas Instruments Inc., and Broadcom Inc. occupy positions spanning RF front-end modules through baseband processing. These entities exemplify the vertical integration archetype, with geographic footprints concentrated in North American and Asia-Pacific design centers. Their competitive positioning rests on multi-decade qualification heritage with telecommunications infrastructure OEMs rather than single-product specialization.
| Leading Market Players |
|---|
| Qualcomm Technologies Inc. |
| Texas Instruments Inc. |
| Broadcom Inc. |
| STMicroelectronics |
| NXP Semiconductors |
| Qorvo Inc. |
| Infineon Technologies AG |
| Analog Devices |
| Skyworks Solutions Inc. |
| Others |
Cost & Logistics Intelligence
Silicon carbide wafer spot price indices cascade through GaN epitaxy foundries into three distinct amplifier pricing tiers, with defense contractors absorbing premiums for ITAR-compliant sourcing while telecommunications providers negotiate volume-driven standard-tier contracts. Copper and rare earth magnet volatility feeds directly into thermal management component costs, compressing margins for amplifier module vendors serving dual commercial-military markets.
Pricing Analysis
Lead-time premiums of 40-60% apply to GaN-on-SiC amplifiers with sub-16-week delivery windows, while spot inventory of LDMOS devices trades at 15-25% discounts to contract pricing. Three-tier pricing structure across ITAR-certified defense-grade, automotive-qualified industrial-grade, and consumer-grade commercial tiers separates procurement pools. Cost compression in the standard tier intensifies because Ericsson, Nokia, and Samsung network divisions unbundle amplifier modules from integrated radio units. Telecommunications infrastructure OEMs exhibit highest price sensitivity due to consolidated procurement leverage, while defense contractors accept premium positioning for radiation-hardened qualification heritage.
Supply Chain Analysis
Reverse logistics flows for end-of-life klystron and traveling-wave tube amplifiers are accelerating under EU F-Gas Regulation mandates, with refurbishment programs recovering rare earth magnets and copper thermal assemblies for solid-state remanufacturing. Silicon carbide substrate production concentrates in the United States, Germany, and Japan, while GaN epitaxy capacity clusters in Taiwan, South Korea, and Malaysia. The supply chain draws from concentrated silicon carbide wafer foundries, high-purity gallium metal refining, and specialized ceramic packaging substrates. Single-source vulnerability persists for 6-inch SiC substrates qualified for military radar programs. Distribution runs through direct semiconductor sourcing agreements with telecommunications OEMs and ITAR-compliant distributor networks for defense contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power amplifier market is consolidating around captive GaN-on-SiC epitaxy capacity as the decisive upstream lever, with foundry-backward integration separating sustainable margin structures from component vendors exposed to substrate supply bottlenecks.
For Market Incumbents: Extend qualification heritage advantages into 6G millimeter-wave amplifier architectures before FCC spectrum reframing finalizes efficiency specifications. Lock in multi-year silicon carbide wafer offtake agreements with Wolfspeed, Coherent, or II-VI to defend against substrate supply concentration risks. Prioritize captive epitaxy investments in Malaysia or Vietnam special economic zones to escape tariff exposure on Chinese-processed substrates.
For New Entrants and Emerging Players: Defense electronics distributors represent the most accessible channel partner type for penetrating ITAR-compliant supply chains without direct OEM qualification burdens. Target industrial RF heating applications in North American food processing and materials curing as the most penetrable white-space segment, where magnetron tube replacement cycles are accelerating. Pursue technical partnership routes with CERN or national accelerator laboratories to establish credibility for high-power klystron alternatives.
For Investors and Strategic Acquirers: The window for entry favors compound semiconductor foundry specialists with existing GaN-on-SiC process libraries and defense qualification heritage. Mid-term viability hinges on substrate supply security and military procurement cycle positioning. Monitor US Navy surface fleet modernization program announcements and European F-Gas Regulation enforcement actions as early signals of demand inflection for solid-state radar transmitters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxy | Captive GaN-on-SiC wafer production reduces dependency on Wolfspeed and Coherent foundry allocations. |
| Defense Qualification Acceleration | ITAR-compliant process libraries unlock Raytheon and Lockheed Martin procurement pipelines for electronic warfare modules. |
| Automotive Radar Partnership | 77-81 GHz amplifier co-development with Munich and Stuttgart clusters captures ADAS deployment cycles. |
| 6G Research Spectrum Positioning | FCC millimeter-wave allocation engagement shapes efficiency specifications before standardization finalizes. |
| REACH Compliance Automation | Full material declaration systems reduce qualification timeline extension risks from ECHA substance registry updates. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with RF device engineering directors, defense procurement officers at Raytheon and Northrop Grumman, telecommunications infrastructure OEM supply chain managers, compound semiconductor foundry operations leads, and ECHA regulatory affairs specialists. Bottom-up triangulation across GaN epitaxy equipment shipment databases, FCC equipment authorization filings, and EU F-Gas Regulation compliance reports validated top-down market sizing from semiconductor trade association aggregates.
Granularity-level modeling deployed separate forecast tracks for GaN, LDMOS, CMOS, and vacuum tube technology platforms, with cross-segment calibration against defense budget appropriation cycles and 5G base station deployment trajectories. CAGRs derived from installation base replacement dynamics, spectrum reallocation timelines, and foundry capacity expansion announcements across the projection horizon. Industry-specific forecast inputs included US Navy radar modernization program schedules and European terrestrial broadcasting transmitter replacement mandates under ETSI efficiency standards.
Caveats apply where silicon carbide substrate supply disruptions, REACH substance restriction expansions, or defense export control reclassifications could materially shift the outlook. Practitioners should monitor Wolfspeed and Coherent capacity utilization disclosures, ECHA SVHC registry updates, and ITAR jurisdiction boundary revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Ultra-Wideband (UWB) Market
RF Components
Tunable Inductors Market
RF Components
Global RF Transceiver Market
RF Components
5G Millimeter Wave RF Transceiver Market
RF Components
RF Switches Market
RF Components
Europe Small Signal Transistor Market
RF Components
Global Ceramic Dielectric Filters Market
RF Components
RF Filters Market
RF Components
RFID Antenna Market
RF Components
Radio Frequency Filters Market
RF Components
RF Power Detector Market
RF Components
UHF RFID Inlays Market
RF Components
Acoustic Wave Filters Market
RF Components
Multiband Booster Market
RF Components
China Small Signal Transistor Market
RF Components
Smartphone RF Power Amplifier Market