
 China Small Signal Transistor Market | 2026-2036
China Small Signal Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
China Small Signal Transistor Market Insights
A-grade reliability tiering is unwinding across the China small signal transistor supply base as domestic fabs narrow the performance gap with imports. ROHM Semiconductor leverages its SiC-adjacent process know-how to sustain premium positioning in automotive switching applications. Onsemi anchors high-volume BJT supply through its Shanghai-backed packaging partnerships. Texas Instruments competes on precision amplifier portfolios tailored to industrial instrumentation demand.
Small signal transistors are three-terminal semiconductor devices engineered for current or voltage modulation at milliwatt power levels, typically fabricated on silicon wafers using planar epitaxial processes and specified by parameters including current gain bandwidth product and collector-emitter saturation voltage. Their primary commercial purpose is signal conditioning in low-power analog and digital circuits. Bipolar junction transistors occupy the mature volume core where margin pools have compressed to commodity levels, while gallium nitride technology leads the fastest-growing tier as RF base stations and EV charging modules demand higher electron mobility. Field-effect transistors dominate switching applications across consumer electronics OEMs in Shenzhen and Dongguan, where gate charge efficiency determines supplier selection.
MIIT's integrated circuit promotion guidelines and GB/T national semiconductor standards shape product certification requirements for domestic market access, while SAMR enforces quality supervision protocols that filter sub-tier imports from non-compliant sources. The dual carbon goals from China's State Council are forcing foundries to document energy consumption per wafer start, adding compliance overhead that favors scaled domestic producers over fragmented traders. Stakeholders must monitor how BIS export control alignments with US technology restrictions reshape equipment access for local fab expansion.
Market Dynamics
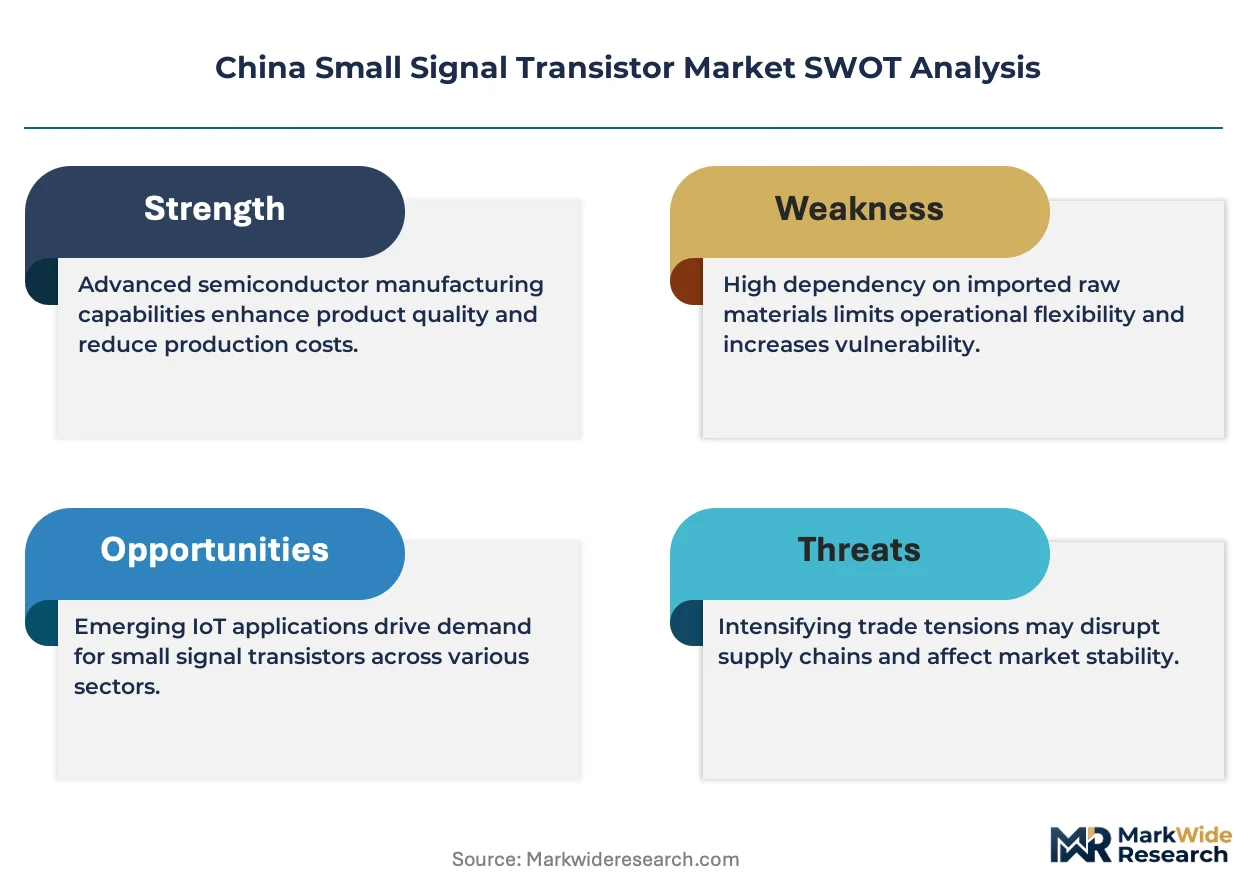
MIIT's semiconductor self-sufficiency mandates are compressing import dependency ratios across China's small signal transistor supply base, forcing domestic fabs to absorb volume previously served by foreign suppliers while narrowing performance parity gaps in automotive-grade applications.
Growth Catalysts
- Yangtze River Delta cluster concentration:Shanghai, Jiangsu and Zhejiang provinces host integrated packaging and testing infrastructure that reduces logistics friction for consumer electronics OEMs in Shenzhen and Dongguan.
- Automotive electronics adoption:Domestic OEM supply chains are qualifying indigenous BJT and FET components for body control modules, creating captive demand pools that insulate local suppliers from commodity pricing pressure.
- Dual carbon goals compliance:China's State Council energy consumption documentation requirements per wafer start are accelerating foundry consolidation toward scaled domestic producers with verified carbon accounting systems.
Market Restraints
- Equipment access restrictions:BIS export control alignments with US technology restrictions are constraining lithography and deposition tool availability for local fab expansion below 40nm nodes.
- Silicon wafer input volatility:Polysilicon purification capacity concentration in Xinjiang and Inner Mongolia exposes cost structures to regional power rationing and environmental compliance disruptions.
- Gallium nitride substitution pressure:RF base station and EV charging module designers are migrating toward GaN HEMT architectures that bypass traditional silicon small signal transistor specifications entirely.
Strategic Opportunities
- GB/T national standards certification:SAMR quality supervision protocols create compliance moats that filter sub-tier imports, rewarding domestic producers with documented traceability systems.
- Industrial instrumentation precision demand:Factory automation upgrades across Anhui and Hubei provinces are sourcing matched transistor pairs for sensor signal conditioning, opening premium margin tiers beyond consumer electronics.
- SiC-adjacent process know-how transfer:Automotive power module foundries are repurposing epitaxial growth expertise to serve small signal transistor die shrinks, compressing development cycles for next-generation geometries.
Industry Challenges
- Compound semiconductor process engineering scarcity:Domestic universities are producing insufficient epitaxial growth specialists to staff both power SiC and small signal silicon fab expansions simultaneously.
- Legacy BJT inventory integration:Shenzhen contract manufacturers maintain multi-year stockpiles of through-hole transistor architectures that resist surface-mount conversion without board redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Small Signal Transistor Market |
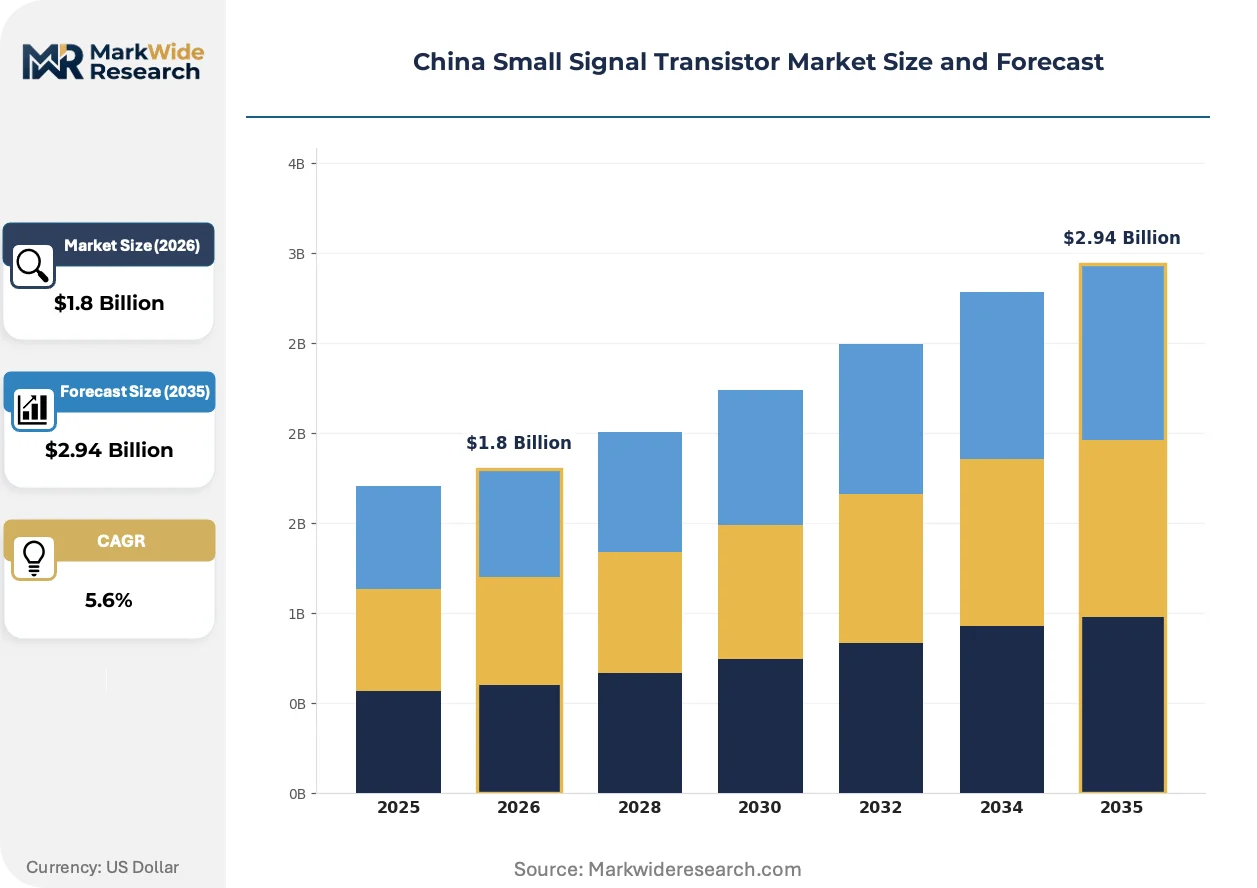
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bipolar Junction, Field-Effect, Phototransistor, Darlington End User: Electronics, Automotive, Telecommunications, Industrial Application: Switching, Amplification, Signal Processing, Audio Equipment Technology: Silicon, Gallium Nitride, Silicon Carbide, Organic |
| Companies Covered | ROHM Semiconductor, Onsemi, Infineon Technologies, NXP Semiconductors, STMicroelectronics, Renesas Electronics, Texas Instruments, Diodes Incorporated, Fuji Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Small Signal Transistor Market Trends and Innovations
Silicon carbide process maturation is spilling into small signal transistor fabrication, compressing the traditional boundary between power and signal semiconductor design rules while enabling unified foundry platforms.
Planar epitaxial silicon processes with optimized collector-emitter saturation voltage specifications are supplanting legacy ion-implanted architectures in automotive switching applications. Tier-1 suppliers in Changshu and Wuxi are qualifying these die shrinks for body electronics modules ahead of 2025 platform refreshes. The transition is compressing margin pools for commodity BJT traders while concentrating volume with integrated IDM operations.
MIIT's integrated circuit promotion guidelines are mandating domestic content verification for state-funded infrastructure procurement. Industrial control OEMs in Suzhou are restructuring supplier qualification workflows to document GB/T compliance certificates ahead of SAMR audit windows. The policy is accelerating procurement pattern bifurcation between government-linked and export-oriented customer segments.
Direct foundry engagement is displacing layered distribution networks for volume transistor consumers. Dongguan power supply manufacturers are negotiating wafer-start allocations with Shanghai-based fabs through dedicated account programs, bypassing Hong Kong-based component traders. The channel compression is most visible in 100V-rated switching transistor categories where demand visibility justifies captive capacity reservations.
China Small Signal Transistor Market Segmentation
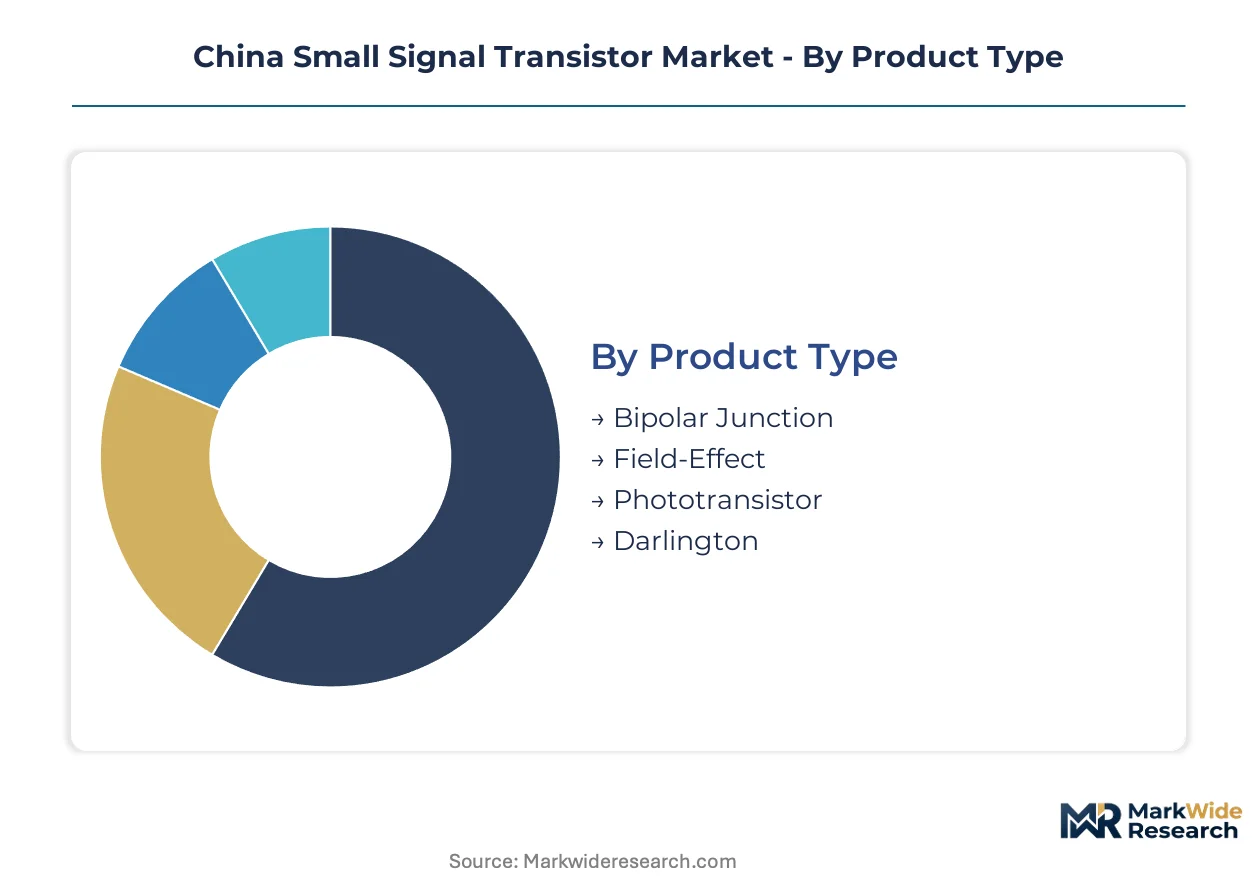
Segmentation in China's small signal transistor market reveals how substitution pressures and policy mandates are reshaping procurement patterns across domestic supply chains. Understanding these divides helps suppliers align certification investments with actual demand concentration.
Product Type:
Gallium nitride and silicon carbide process maturation is exerting substitution pressure on traditional silicon architectures, forcing product type strategists to recalibrate volume forecasts and R&D allocation.
- Bipolar Junction:Silicon-based three-terminal devices relying on electron-hole pair injection for current amplification, specified by current gain bandwidth product and collector-emitter saturation voltage. Demand concentrates in automotive body control modules across Changshu and Wuxi supplier parks as domestic OEMs qualify indigenous BJT die for 2025 platform refreshes.
- Field-Effect:Voltage-controlled devices utilizing gate charge modulation to manage channel conductivity without DC input current draw. Shenzhen and Dongguan consumer electronics OEMs prioritize gate charge efficiency metrics when selecting FET suppliers for switching power supplies.
- Phototransistor:Light-sensitive bipolar variants with base current triggered by photon absorption rather than electrical bias.
- Darlington:Cascaded transistor pairs delivering composite current gain multiplication for high-impedance input stages.
Bipolar junction transistors anchor the volume base while field-effect transistors gain share at the steepest rate.
End User:
Cost tier stratification separates premium-grade automotive qualification from commodity electronics procurement, with certification overhead creating divergent margin structures across end user categories.
- Electronics:Consumer device OEMs in Shenzhen and Dongguan drive high-volume demand for surface-mount switching transistors in power supply and charging applications.
- Automotive:Domestic OEM supply chains are captive-qualifying indigenous BJT and FET components for body electronics, creating insulated demand pools with extended product lifecycles.
- Telecommunications:RF base station designers are migrating toward GaN HEMT architectures that bypass traditional silicon small signal specifications entirely.
- Industrial:Factory automation upgrades across Anhui and Hubei provinces source matched transistor pairs for precision sensor signal conditioning.
Electronics absorbs the highest unit volumes while automotive commands the strongest pricing premium per qualified component.
Application:
Application segmentation tracks how voltage and frequency requirements are pushing designers toward compound semiconductor alternatives in high-performance use cases.
- Switching:Rapid state transition between cutoff and saturation regions for power regulation and digital logic interfacing.
- Amplification:Linear signal gain for analog processing chains, with precision tiers demanding matched pair specifications.
- Signal Processing:Conditioning and filtering operations in communication front-ends and sensor interfaces.
- Audio Equipment:Low-noise amplification stages for consumer and professional sound reproduction systems.
Switching dominates unit demand while amplification sustains the highest margin per die area through precision matching requirements.
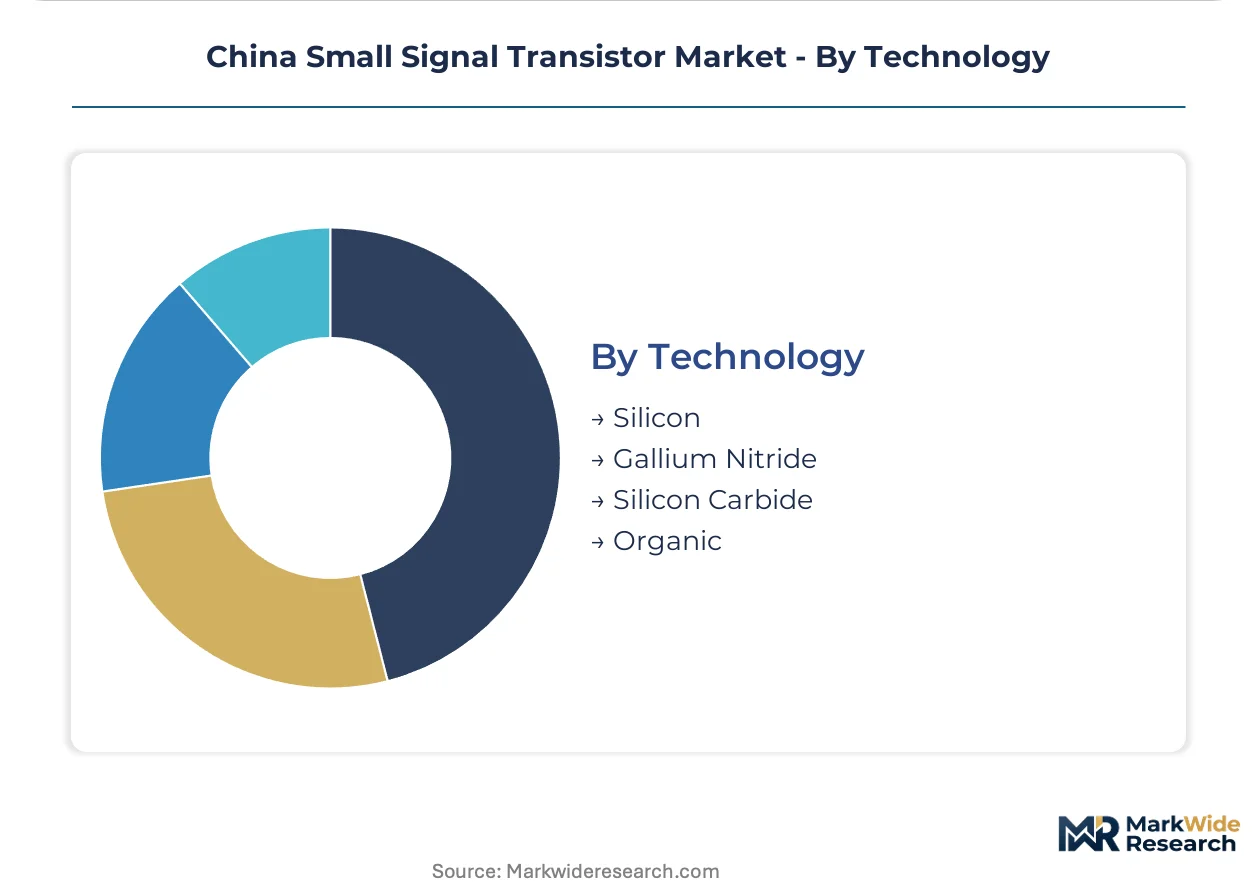
Technology:
Technology segmentation exposes the divergence between mature silicon cost curves and emerging wide-bandgap material performance premiums.
- Silicon:Planar epitaxial processes with optimized collector-emitter saturation voltage specifications are supplanting legacy ion-implanted architectures in automotive switching applications.
- Gallium Nitride:High electron mobility transistors delivering superior switching frequency and efficiency for RF base stations and EV charging modules.
- Silicon Carbide:Process maturation in power module foundries is spilling into small signal fabrication, enabling unified foundry platforms across voltage classes.
- Organic:Emerging flexible substrate compatibility for wearable and bendable electronics form factors.
Silicon retains overwhelming volume dominance while gallium nitride expands most quickly in RF and power conversion segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity clusters along the Yangtze River Delta dominate wafer output for China's small signal transistor base. Provincial industrial policies and MIIT's semiconductor mandates are redistributing demand toward indigenous supply chains across eastern and central manufacturing belts.
Yangtze River Delta
Shanghai, Jiangsu and Zhejiang provinces concentrate packaging and testing infrastructure that serves consumer electronics OEMs in Shenzhen. MIIT's integrated circuit promotion guidelines mandate domestic content verification for state-funded projects. Changshu and Wuxi supplier parks are qualifying indigenous BJT die for 2025 automotive platform refreshes.
Pearl River Delta
Shenzhen and Dongguan drive high-volume demand for surface-mount switching transistors in power supply applications. SAMR quality supervision protocols filter sub-tier imports from non-compliant sources. Direct foundry engagement is displacing Hong Kong-based component traders for 100V-rated switching categories.
Beijing-Tianjin-Hebei
Industrial control OEMs in Beijing are restructuring supplier qualification workflows to document GB/T compliance certificates. The State Council's dual carbon goals force foundries to document energy consumption per wafer start. Tianjin-based fabs are consolidating toward scaled producers with verified carbon accounting systems.
Sichuan-Chongqing
Western China expansion targets polysilicon purification capacity concentration in Xinjiang and Inner Mongolia. Regional power rationing exposes cost structures to environmental compliance disruptions. Chongqing is attracting packaging partnerships to reduce logistics friction for central China industrial automation demand.
Shandong Peninsula
Factory automation upgrades across Shandong are sourcing matched transistor pairs for precision sensor signal conditioning. BIS export control alignments constrain lithography tool availability for local fab expansion below 40nm nodes. Qingdao and Yantai are developing SiC-adjacent process expertise transfer from automotive power module foundries.
China Small Signal Transistor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across China's small signal transistor supply base. Japanese and European IDMs anchor premium automotive-grade qualification tiers while domestic Chinese fabs capture volume share in consumer electronics switching applications. Three archetypes dominate: integrated device manufacturers with captive fab capacity, fabless specialists leveraging foundry partnerships, and state-backed conglomerates consolidating regional supply chains. Competitive moves concentrate on strategic partnerships for packaging localization and portfolio diversification into wide-bandgap materials.
Within the premium-tier vector, ROHM Semiconductor exemplifies SiC-adjacent process know-how transfer into automotive switching applications. Onsemi occupies a position among scale-driven suppliers anchoring high-volume BJT supply through Shanghai-backed packaging partnerships. Texas Instruments represents the precision amplifier portfolio archetype tailored to industrial instrumentation demand across Anhui and Hubei provinces.
| Leading Market Players |
|---|
| ROHM Semiconductor |
| Onsemi |
| Infineon Technologies |
| NXP Semiconductors |
| STMicroelectronics |
| Renesas Electronics |
| Texas Instruments |
| Diodes Incorporated |
| Fuji Electric |
| Others |
Pricing and Supply Chain Analysis
Wafer-start scale economies at Yangtze River Delta foundries compress unit economics for domestic BJT producers while elevating price floors for sub-scale importers. MIIT's semiconductor self-sufficiency mandates amplify this concentration effect by redirecting state-linked procurement toward verified indigenous suppliers.
Pricing Analysis
GB/T national standards certification dictates the pricing tier structure across China's small signal transistor base. Pricing stratifies across automotive-grade qualification, industrial precision matching, and consumer electronics commodity tiers. Cost compression in the consumer switching segment is intensifying because Shenzhen power supply OEMs negotiate direct wafer-start allocations with Shanghai fabs. Automotive body control module buyers exhibit the lowest price sensitivity due to extended qualification cycles and captive supplier relationships.
Supply Chain Analysis
Container availability through Shanghai Port shapes inbound logistics costs for silicon wafer feedstock drawn from South Korea and Japan. Polysilicon purification capacity concentrates in Xinjiang and Inner Mongolia, exposing cost structures to regional power rationing. Single-source vulnerability runs through lithography equipment access below 40nm nodes as BIS export controls constrain deposition tool availability. Distribution runs through direct foundry engagement displacing Hong Kong-based component traders for volume consumers in Dongguan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for automotive qualification support and precision matching calibration are expanding faster than discrete transistor hardware sales, creating recurring revenue pools that offset commodity margin erosion.
For Market Incumbents: Consolidate packaging partnerships in Changshu and Wuxi to defend automotive-grade market share against GaN substitution pressure. Deepen backward integration into epitaxial wafer supply through captive sourcing agreements with Yangtze River Delta silicon growers. Lock in GB/T certification moats ahead of SAMR audit window expansions. For New Entrants and Emerging Players: GB/T fast-track certification for industrial instrumentation precision tiers opens white-space in Anhui and Hubei factory automation upgrades. Target matched transistor pair demand from sensor signal conditioning OEMs underserved by incumbent distribution networks. Pursue foundry-direct engagement models bypassing layered Hong Kong trader structures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors SiC-adjacent process specialists with transferable epitaxial growth expertise across voltage classes. Long-term viability hinges on unified foundry platform economics spanning power and signal semiconductor applications. Watch for BIS export control alignment shifts as the inflection signal for domestic equipment access trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Partnership | Captive demand pools from Changshu OEMs insulate pricing from commodity erosion. |
| GB/T Certification Investment | SAMR compliance moats filter sub-tier imports from state-funded procurement channels. |
| SiC Process Know-How Transfer | Automotive power module expertise compresses small signal transistor development cycles. |
| Direct Foundry Engagement | Dongguan volume consumers bypass Hong Kong traders for 100V switching categories. |
| Precision Matching Service Layer | Industrial automation in Hubei sources calibrated pairs beyond standard component sales. |
Research Methodology
Cross-validation between primary fieldwork with fab operations directors and secondary trade data anchors the qualitative findings. Semiconductor plant managers, procurement leads at Shenzhen consumer electronics OEMs, automotive Tier 1 supplier quality engineers, and distribution channel partners in Hong Kong provided operational perspective. Secondary sources include MIIT policy filings, SAMR quality supervision protocols, customs import records, and SEC disclosures from listed component vendors. Bottom-up wafer-start estimates and top-down end-use consumption patterns were reconciled through iterative triangulation.
Sensitivity analysis around equipment access restrictions and polysilicon input volatility stress-tests the analytical framework across the projection horizon. Segmentation dimensions span product type, end user category, application voltage class, and technology material. CAGRs derive from modeled unit demand against fab capacity expansion schedules and substitution elasticity parameters. GaN HEMT penetration curves and dual carbon compliance cost pass-through assumptions inform scenario boundaries.
Underlying assumptions cover sustained MIIT self-sufficiency policy enforcement and stable Yangtze River Delta logistics connectivity, with deviation risk concentrated in BIS export control escalation and Xinjiang power rationing recurrence. Forecasts reflect these conditions without claiming predictive certainty. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
GPS Low Noise Amplifier Market
RF Components
EMI Microwave Absorber Market
RF Components
5G Driver Amplifier Market
RF Components
Gaas RF Switch Market
RF Components
Radio Frequency (RF) Signal Generators Market
RF Components
Global Bulk Acoustic Wave (BAW) Filters Market
RF Components
Americas Small Signal Transistor Market
RF Components
Multilayer Coupled Inductor Market
RF Components
Flat Antenna Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
Dielectric Resonator Market
RF Components
Phase Shifters Market
RF Components
RF Mixers Market
RF Components
RF Power Amplifiers Market
RF Components
RF-Microwave for 5G Market
RF Components
RFID Antenna Market