
 Hardness Testing Machine Market | 2026-2036
Hardness Testing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Hardness Testing Machine Market Outlook
Equipment leasing and performance-based service contracts is reconfiguring capital deployment across the hardness testing sector, lowering barriers for mid-tier manufacturers that previously deferred metrology investments. Zwick Roell Group leverages its German engineering base to dominate high-force universal testing systems for automotive OEM validation labs. Mitutoyo sustains precision instrument leadership through dense distributor networks across East Asian manufacturing clusters. INNOVATEST competes aggressively on portable hardness solutions for on-site inspection workflows in oil and gas maintenance.
Hardness testing machines measure material resistance to localized plastic deformation through standardized indentation methods using defined loads and indenter geometries, with results expressed on scales such as Rockwell, Brinell, or Vickers for quality assurance and material certification. The Rockwell segment anchors volume demand due to its speed and minimal sample preparation in high-throughput metalworking environments, while the Vickers category captures premium positioning for thin-section and surface-hardened component evaluation. Digital technology platforms are displacing analog readout systems as Industry 4.0 protocols mandate networked data logging and statistical process control integration across manufacturing end users.
ISO 6508 and ASTM E18 standards govern Rockwell test method uniformity, while ISO 6507-1 defines Vickers procedures; compliance with these frameworks determines market access for equipment vendors serving regulated industries. The U.S. FDA and FAA both reference ASTM hardness specifications in medical device and aerospace material approvals, creating downstream specification pull for certified testing infrastructure. Stakeholders must monitor evolving NIST traceability requirements and emerging AI-driven indentation analysis algorithms that promise to reshape operator skill dependencies and equipment value propositions.
Market Dynamics
Digital metrology platforms are compressing equipment replacement cycles as manufacturers retrofit legacy analog hardness testers to capture Industry 4.0 data streams and satisfy Nadcap traceability mandates from aerospace primes.
Growth Catalysts
- Nadcap Special Process Accreditation:Aerospace component suppliers in the United States and Germany are expanding metrology capital budgets to satisfy third-party audit requirements for heat treatment and surface engineering verification.
- VDI/VDE 2620 Machine-Integrated Measurement:German automotive OEMs are mandating inline hardness verification stations to eliminate offline inspection bottlenecks in powertrain machining lines.
- Smart Factory Subsidies:Provincial governments across China's Jiangsu and Guangdong provinces are funding hardness testing equipment upgrades as mandatory components of digital manufacturing transformation grants.
Market Restraints
- Reference Block Supply Concentration:Certified hardness reference materials for Rockwell and Vickers calibration depend on a limited base of NIST-traceable suppliers in the United States and Germany, creating single-source vulnerability.
- Indenter Diamond Cost Volatility:Synthetic monocrystalline diamond indenter tips face price pressure from semiconductor wafer demand competing for identical material grades.
- ASTM E18 Method Revision Lag:Prolonged balloting timelines for updated Rockwell test procedures delay product certification for equipment vendors serving FDA-regulated medical device manufacturers.
Strategic Opportunities
- Portable Hardness for Oil and Gas Maintenance:On-site inspection workflows for pipeline integrity and refinery turnaround operations remain underpenetrated by automated solutions, favoring handheld ultrasonic and rebound technologies.
- AI-Driven Indentation Analysis:Machine vision algorithms for automatic Brinell impression measurement are converging with cloud-based statistical process control platforms to reduce operator skill dependencies.
- Performance-Based Service Contracts:Metrology-as-a-service models are opening mid-tier metalworking shops previously priced out of certified hardness verification infrastructure.
Industry Challenges
- ISO 17025 Calibration Technician Shortage:Accredited hardness testing laboratories face recruitment gaps for personnel qualified to maintain measurement uncertainty documentation under evolving NIST traceability protocols.
- Legacy System Integration Complexity:Brownfield manufacturing facilities struggle to retrofit 1990s-era analog hardness testers with Ethernet-enabled data acquisition modules without disrupting production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hardness Testing Machine Market |
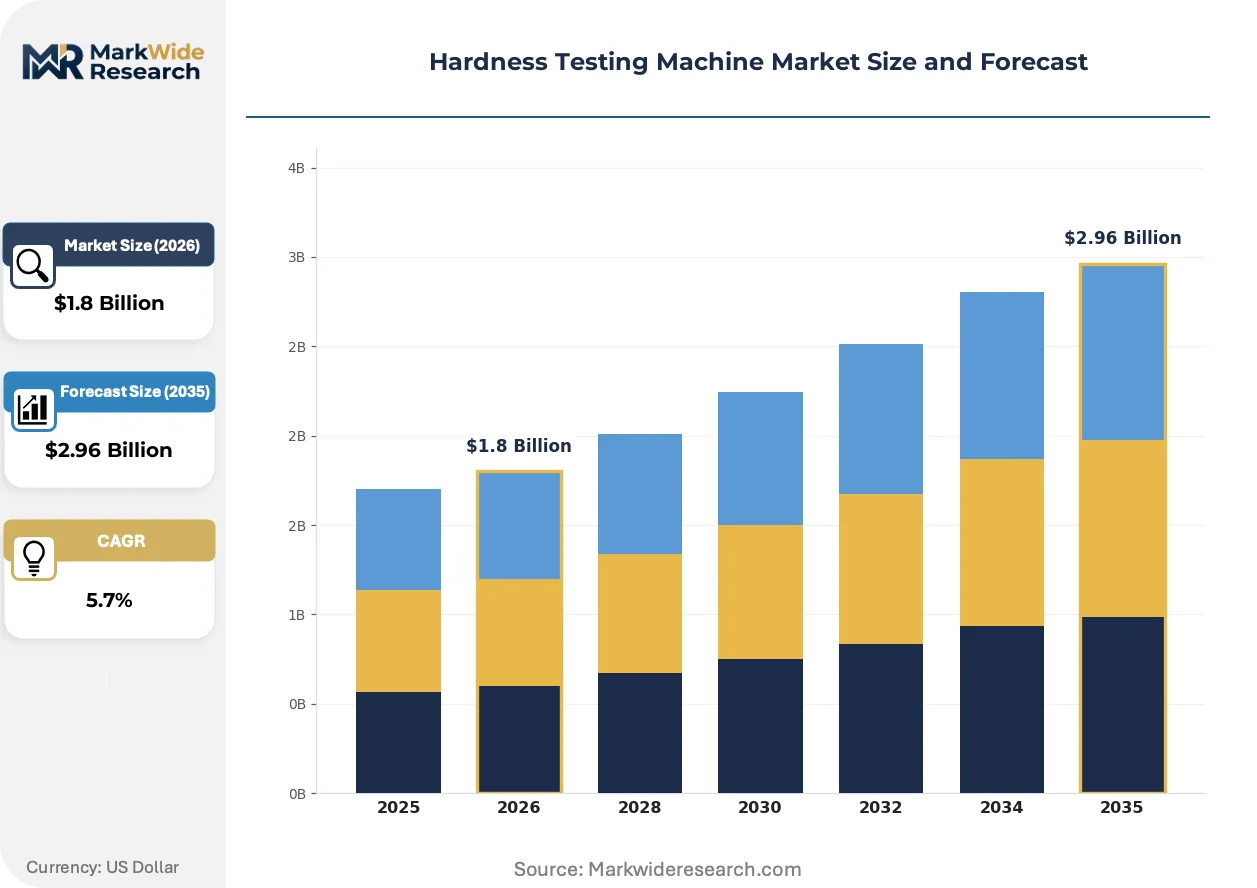
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rockwell, Brinell, Vickers, Mohs Technology: Digital, Analog, Automatic, Semi-automatic End User: Manufacturing, Research Laboratories, Quality Control, Educational Institutions Application: Metal Testing, Polymer Testing, Ceramics Testing, Composites Testing |
| Companies Covered | Zwick Roell Group, Mitutoyo, INNOVATEST, Buehler, Struers, Starrett, Beijing Time High Technology, LECO Corporation, EMCO-TEST, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hardness Testing Machine Market Strategic Shifts
Cloud-connected hardness testing architectures are displacing standalone benchtop units as quality systems migrate toward centralized metrology data lakes and predictive maintenance algorithms.
Automated optical Brinell measurement systems are virtualizing operator judgment in heavy-section steel evaluation. Foundries and forging operations in Germany and Japan are deploying these systems to eliminate manual impression reading errors. The technology is virtualizing the traditional master-apprentice skill transfer model in metallurgical laboratories, compressing training timelines from years to weeks.
REACH substance restrictions on hexavalent chromium surface treatments are forcing hardness equipment vendors to redesign corrosion protection for load frames and indenters. European automotive suppliers must now verify that testing machine coatings comply with SVHC thresholds. The regulation is accelerating adoption of ceramic-coated and stainless steel alternatives in equipment destined for EU assembly plants.
Buying committees at Tier 1 automotive suppliers are consolidating hardness testing vendor relationships to reduce audit burden and secure volume pricing. Single-source agreements covering Rockwell, Vickers, and universal testing equipment are displacing fragmented procurement across multiple metrology specialists. This concentration is most visible in Germany's Baden-Württemberg and Bavaria manufacturing clusters where supplier reduction programs target 40% fewer approved equipment vendors by 2027.
Hardness Testing Machine Market Segmentation
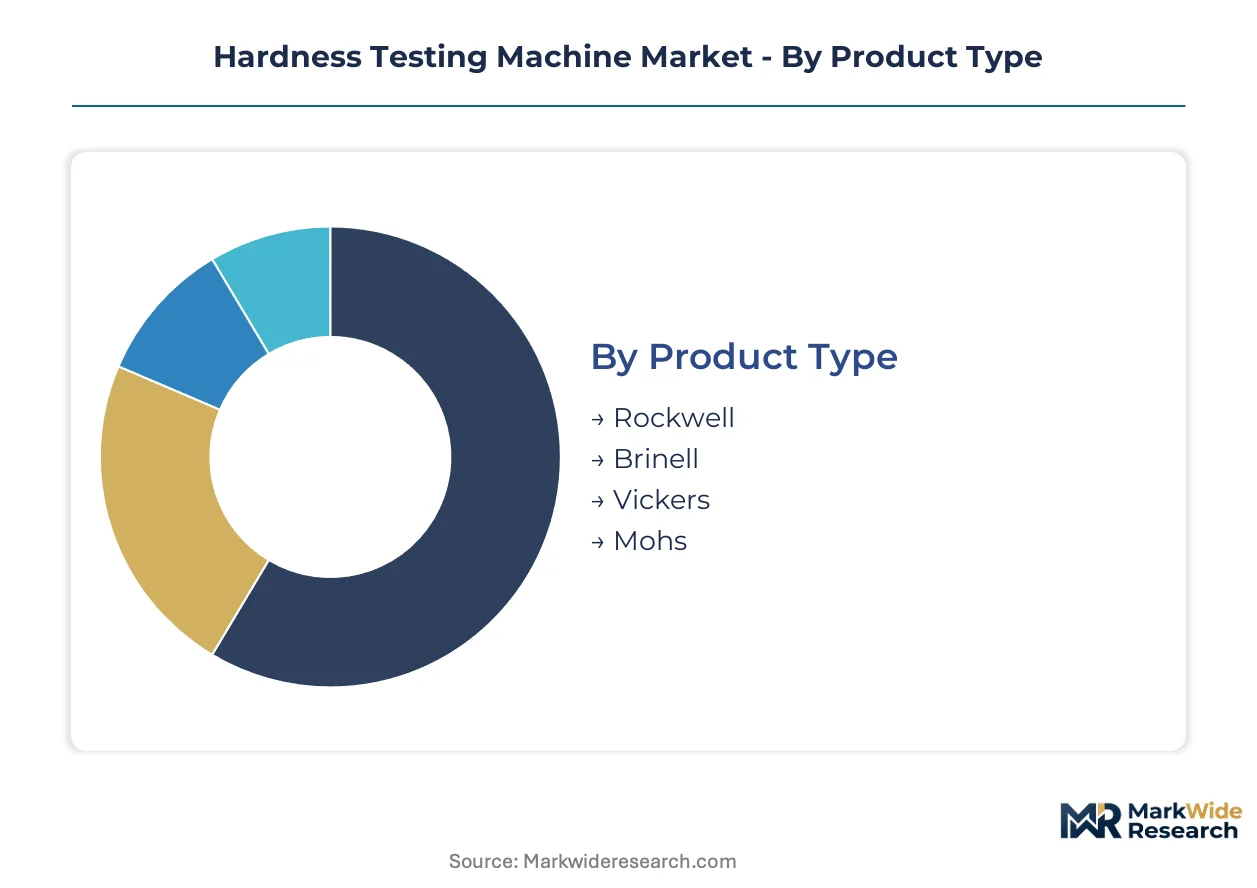
Segmentation in hardness testing machines reveals how test method selection, automation level, and end-use environment dictate equipment specifications and procurement patterns. Manufacturers configure product portfolios across these dimensions to match customer certification requirements and throughput demands.
Product Type:
Mature Rockwell systems dominate high-throughput metalworking floors, while emerging optical Brinell platforms reshape heavy-section evaluation workflows.
- Rockwell:Depth-measurement indentation using conical diamond or hardened steel ball indenters delivers rapid results without microscopic examination. Automotive powertrain plants in Germany and the United States specify Rockwell testers for 100% inspection of crankshafts and camshafts under Nadcap-mandated process control.
- Vickers:Pyramidal diamond indenter geometry enables precise measurement across thin coatings and surface-hardened layers through diagonal impression analysis. Japanese precision component manufacturers favor Vickers platforms for evaluating carburized gears and bearing races where case depth verification determines component life.
- Brinell:10mm ball indenter with variable loads serves foundry and forging operations assessing cast iron and heavy steel sections.
- Mohs:Scratch-hardness comparison method addresses geological and mineralogical applications outside industrial quality assurance.
Rockwell handles the majority of throughput; Vickers is expanding most quickly on share as surface engineering complexity rises.
Technology:
Cost tier stratification separates premium digital platforms from legacy analog installations, with automation level determining labor substitution economics.
- Digital:Load-cell force application with touchscreen interfaces and automatic hardness calculation eliminates operator reading errors. China's Jiangsu province smart factory subsidies specifically target digital hardness tester upgrades for SME metalworking clusters seeking Industry 4.0 certification.
- Automatic:Robotic sample handling and multi-position turrets enable unattended testing sequences for high-volume production lines. German automotive OEMs mandate automatic inline stations under VDI/VDE 2620 machine-integrated measurement standards to eliminate offline inspection bottlenecks.
- Analog:Mechanical dead-weight loading with dial gauge readout persists in budget-constrained maintenance shops and developing economy markets.
- Semi-automatic:Motorized load application with manual sample positioning bridges price-performance gaps for mid-tier manufacturers.
Digital platforms command the premium tier; automatic configurations are climbing the fastest as labor costs and traceability requirements intensify.
End User:
Customer type determines specification stringency, with certified laboratories demanding ISO 17025-compliant uncertainty documentation that production floors often bypass.
- Manufacturing:Production-line hardness verification for heat treatment validation and incoming material inspection anchors equipment volume. Aerospace component suppliers in the United States expand metrology capital budgets to satisfy third-party Nadcap audit requirements for special process accreditation.
- Quality Control:Dedicated inspection departments within Tier 1 automotive suppliers consolidate multi-method testing capabilities under single-source vendor agreements.
- Research Laboratories:Materials science institutes require multi-scale indentation platforms with programmable load profiles for alloy development.
- Educational Institutions:Training laboratories prioritize robust mechanical designs and intuitive operation over advanced automation features.
Manufacturing absorbs the dominant share of unit shipments; quality control departments are gaining share fastest through supplier consolidation programs.
Application:
Material class dictates indenter geometry, load range, and environmental protection requirements, with metal testing representing the established revenue base.
- Metal Testing:Ferrous and non-ferrous alloy evaluation across casting, forging, and machining operations constitutes the core application. FDA-regulated medical device manufacturers reference ASTM E18 specifications for implant material certification, creating specification pull for Rockwell infrastructure.
- Composites Testing:Fiber-reinforced polymer and ceramic matrix composite indentation requires specialized low-load platforms and non-standard indenter geometries.
- Polymer Testing:Shore and ball indentation methods address elastomer and thermoplastic hardness characterization for automotive sealing and medical device applications.
- Ceramics Testing:High-load Vickers platforms with crack-length measurement capabilities serve structural ceramic evaluation for aerospace and energy applications.
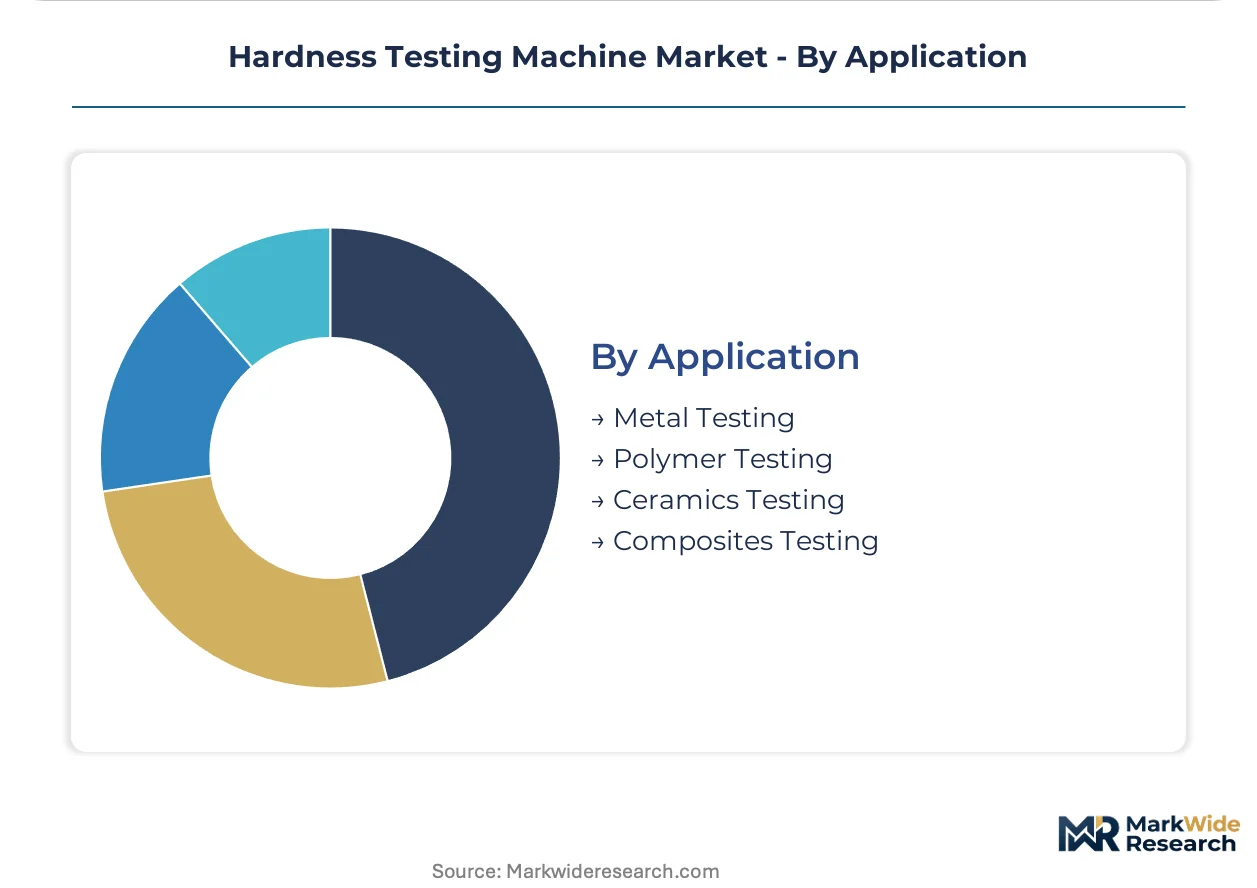
Metal testing commands the volume base; composites testing is advancing fastest as advanced materials penetrate aerospace and automotive structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-funded smart factory programs and aerospace accreditation mandates are redistributing hardness testing equipment demand across manufacturing-intensive economies. Provincial subsidy schemes in China and Nadcap audit requirements in the United States and Germany are accelerating capital deployment in certified metrology infrastructure.
United States
Aerospace component suppliers in California and Washington are expanding metrology budgets to satisfy third-party Nadcap accreditation requirements for heat treatment and surface engineering verification. The FAA references ASTM hardness specifications in aerospace material approvals, creating downstream specification pull for certified testing infrastructure. Greater Seattle and Los Angeles manufacturing clusters anchor equipment procurement for defense and commercial aviation supply chains.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria are mandating inline hardness verification stations under VDI/VDE 2620 machine-integrated measurement standards to eliminate offline inspection bottlenecks in powertrain machining lines. The KBA enforces material certification protocols that cascade into supplier metrology requirements. Stuttgart and Munich industrial corridors concentrate demand for automated testing systems serving Tier 1 supplier networks.
China
Provincial governments across Jiangsu and Guangdong provinces are funding hardness testing equipment upgrades as mandatory components of digital manufacturing transformation grants under national smart factory initiatives. The MIIT oversees GB standards alignment with ISO hardness test methods for export-oriented manufacturers. Suzhou and Dongguan manufacturing clusters are retrofitting analog testers with Ethernet-enabled data acquisition modules to capture Industry 4.0 certification.
Japan
Precision component manufacturers in Aichi and Osaka prefectures favor Vickers platforms for evaluating carburized gears and bearing races where case depth verification determines component life. METI promotes JIS standards harmonization with international hardness test protocols for automotive and machinery exports. Nagoya and Osaka industrial zones sustain demand for high-accuracy surface-hardened component evaluation systems.
South Korea
Automotive and electronics manufacturers in Gyeonggi and Ulsan regions are consolidating hardness testing vendor relationships to reduce audit burden and secure volume pricing under supplier reduction programs. The MFDS references hardness specifications in medical device material approvals, extending metrology requirements into biocompatible alloy supply chains. Seoul Capital Area and Busan-Ulsan manufacturing belts drive procurement for multi-method testing capabilities.
Hardness Testing Machine Market Competitive Environment
On the supply side, the industry is structured around three distinct competitive tiers differentiated by automation level, geographic origin, and service model sophistication. Premium-tier vendors concentrate on automated inline systems for automotive OEM validation labs, while mid-tier specialists compete on portable and benchtop configurations for quality control departments. Equipment leasing and performance-based service contracts are emerging as competitive differentiators, alongside backward integration into diamond indenter and reference block supply chains.
Within the premium automation tier, Zwick Roell Group and Mitutoyo occupy positions anchored by German and Japanese engineering heritage respectively, with dense distributor networks across East Asian manufacturing clusters supporting precision instrument leadership. INNOVATEST exemplifies the portable-specialist archetype competing aggressively on handheld solutions for on-site inspection workflows. Among laboratory-equipment providers, Buehler and Struers represent the materials preparation and testing convergence strategy, while Starrett and LECO Corporation occupy positions in traditional metrology and analytical instrumentation adjacencies. Beijing Time High Technology anchors Chinese domestic supply for cost-optimized digital platforms serving provincial smart factory subsidy programs.
| Leading Market Players |
|---|
| Zwick Roell Group |
| Mitutoyo |
| INNOVATEST |
| Buehler |
| Struers |
| Starrett |
| Beijing Time High Technology |
| LECO Corporation |
| EMCO-TEST |
| Others |
Value Chain & Pricing Dynamics
Synthetic monocrystalline diamond indenter production concentrates in the United States and Germany, anchoring margin capture for certified reference block suppliers while forcing equipment OEMs to absorb volatility through long-term offtake contracts or captive sourcing investments.
Pricing Analysis
Certification level creates the primary spread between premium ISO 17025-compliant systems and economy-grade analog testers. Pricing stratifies across Nadcap-validated, CE-marked, and uncertified tiers, with automotive OEM validation labs showing lowest price sensitivity and mid-tier metalworking shops driving hardest bargain negotiations. Cost compression in the portable segment is intensifying because INNOVATEST and emerging Asian competitors are flooding oil and gas maintenance channels with rebound and ultrasonic alternatives.
Supply Chain Analysis
Extended payment terms from German automotive OEMs and supply-chain finance facilities from Chinese provincial smart factory programs are reshaping working capital requirements for equipment vendors. Manufacturing draws from Germany, Japan, and China for precision load frames, with synthetic diamond indenters and NIST-traceable reference blocks as critical dependencies. Single-source vulnerability in certified reference materials creates structural risk. Distribution runs through dense distributor networks across East Asian manufacturing clusters and direct OEM relationships for automated inline systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardness testing equipment penetration remains below saturation in brownfield metalworking facilities, with Industry 4.0 retrofit mandates and Nadcap accreditation expansion providing durable tailwinds for certified system adoption across the analysis window.
For Market Incumbents: Entrench position through backward integration into diamond indenter and reference block supply chains, eliminating single-source vulnerability that threatens margin stability. Secure exclusive distribution agreements in China's Jiangsu and Guangdong provincial smart factory channels before subsidy windows narrow. Prioritize certification maintenance for FDA and FAA specification pull in medical device and aerospace verticals. For New Entrants and Emerging Players: Pursue portable hardness solutions for oil and gas pipeline integrity workflows, where on-site inspection remains underpenetrated by automated alternatives. Target performance-based service contracts and metrology-as-a-service models for mid-tier manufacturers previously priced out of certified infrastructure. Lead with leasing structures that convert capital expenditure into operational expenditure for budget-constrained maintenance shops. For Investors and Strategic Acquirers: Capital is best deployed toward portable-specialist firms with established ultrasonic or rebound technology platforms and dense field service networks. Long-term viability hinges on software-enabled recurring revenue streams and AI-driven indentation analysis capabilities rather than hardware shipment volumes. Watch for inflection when AI-driven Brinell impression measurement achieves regulatory acceptance for unattended certification workflows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diamond Indenter Supply | Captive sourcing of synthetic monocrystalline tips insulates margin from semiconductor wafer demand competition. |
| Performance-Based Service Contract Rollout | Metrology-as-a-service opens mid-tier metalworking shops previously deferred from certified hardness verification. |
| AI-Driven Indentation Analysis Development | Machine vision algorithms for automatic Brinell measurement reduce operator skill dependencies and training timelines. |
| Nadcap Accreditation Infrastructure Investment | Third-party audit readiness for heat treatment verification captures aerospace supplier capital allocation. |
| Provincial Smart Factory Channel Partnership | Jiangsu and Guangdong subsidy program alignment secures preferential positioning in China's eastern manufacturing corridor. |
Study Parameters
The analysis maps Rockwell, Vickers, Brinell, and portable hardness testing segments, each validated through primary interviews with metrology lab directors, automotive quality engineers, aerospace supplier procurement leads, and aftermarket service heads. Secondary sources include ISO and ASTM standards documentation, NIST traceability protocols, FDA and FAA material specification filings, and customs data for hardness testing equipment trade flows. Bottom-up unit shipment estimates triangulate against top-down capital expenditure patterns across manufacturing verticals.
Assumptions held fixed include continued Nadcap accreditation expansion in aerospace supply chains, sustained German VDI/VDE 2620 inline verification mandates, and stable NIST reference material availability. The forecast framework varies adoption curves across digital, automatic, analog, and semi-automatic technology tiers, with end-user segmentation by manufacturing, quality control, research laboratory, and educational institution. CAGRs derive from equipment replacement cycle compression and retrofit penetration rates in brownfield facilities, with sensitivity to diamond indenter cost volatility and ISO 17025 technician availability.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by Chinese domestic suppliers or accelerated AI-driven automation disruption would shift outcomes. Macroeconomic contraction in automotive capital expenditure, regulatory delay in ASTM E18 method revisions, or REACH substance restriction expansion would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Failure Analysis Market
Test and Measurement
Europe Nondestructive Testing Equipment Market
Test and Measurement
Photostability Chamber Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Sound Level Meter Market
Test and Measurement
Cooling Laser Power Measurement Sphere Market
Test and Measurement
Additively Manufactured Lattice Structure Mechanical Test Systems Market
Test and Measurement
Test Rig Market
Test and Measurement
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market
Test and Measurement
Density Tester Market
Test and Measurement
Industrial Metrology Market
Test and Measurement
Advanced Probe Card and Wafer Probing Test Systems Market
Test and Measurement
Voltage Tester Market
Test and Measurement
Europe Signal Generator Market
Test and Measurement
Megohmmeters Market