
 Circuit Breaker Test Devices Market | 2026-2036
Circuit Breaker Test Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Circuit Breaker Test Devices Market Outlook
Software-defined diagnostic features is decoupling hardware sales from recurring revenue streams in the circuit breaker test devices sector. OMICRON leverages its firmware upgrade architecture to sustain long-term client relationships. Megger anchors its competitive stance through field-service calibration networks. DV Power differentiates by specializing in high-current injection systems for substation commissioning.
Circuit breaker test devices are electromechanical or electronic instruments designed to verify trip characteristics, contact timing, coil resistance, and insulation integrity across medium- and high-voltage switchgear. These units simulate fault conditions to validate protective relay coordination and breaker mechanical performance under rated interrupting duties. Portable testers capture the largest margin pool due to their deployment flexibility across transmission and distribution networks. Microprocessor-based technology is displacing analog architectures as utilities demand automated waveform capture and cloud-synced reporting. Preventive maintenance applications are expanding fastest as asset managers shift from time-based to condition-based intervention schedules.
The US Federal Energy Regulatory Commission mandates periodic testing protocols for bulk power system assets, while the IEC 62271-100 standard governs type-test requirements across European and Asian procurement frameworks. China's State Administration for Market Regulation enforces GB conformity assessment rules that shape local manufacturing specifications and import acceptance criteria. Stakeholders must monitor how digital twin integration and remote diagnostic mandates reshape equipment specification criteria and service contract structures.
Market Dynamics
Microprocessor-based test architectures are compressing hardware replacement cycles while tethering utilities to recurring firmware and calibration revenue streams. This shift from capital sale to subscription-like service models restructures vendor-customer relationships across transmission and distribution networks.
Growth Catalysts
- IEC 62271-100 type-test mandates:European and Asian procurement frameworks now require certified validation protocols, forcing asset owners to upgrade aging analog test equipment.
- China's grid reliability programs:State Grid Corporation and China Southern Power Grid are accelerating substation modernization, creating concentrated demand for high-current injection systems.
- Condition-based maintenance adoption:US utilities under FERC jurisdiction are abandoning time-based schedules in favor of predictive diagnostics, expanding portable tester deployment frequency.
Market Restraints
- Copper and rare-earth magnet cost volatility:High-current injection coils depend on copper windings and neodymium magnets, exposing manufacturers to commodity price swings.
- Specialized technician scarcity:Field commissioning of microprocessor-based units requires fluency in both protective relay logic and software calibration protocols.
- Long asset replacement cycles:Electromechanical test sets from the 1990s remain operational, delaying upgrade decisions at budget-constrained municipal utilities.
Strategic Opportunities
- Digital twin integration:Test device manufacturers can bundle hardware with virtual substation modeling software, capturing recurring SaaS revenue from German transmission operators.
- Remote diagnostic mandates:Post-pandemic workforce constraints are pushing US utilities toward cloud-synced reporting features that enable off-site analysis.
- India's renewable integration surge:Solar and wind farm interconnection rules under CEA guidelines are creating demand for portable commissioning testers at greenfield substations.
Industry Challenges
- Multi-standard certification complexity:Manufacturers must simultaneously satisfy IEC, IEEE, and GB conformity assessment rules, lengthening product launch timelines.
- Legacy system interoperability:Microprocessor-based testers must interface with electromechanical breakers and first-generation digital relays still in service at aging US substations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circuit Breaker Test Devices Market |
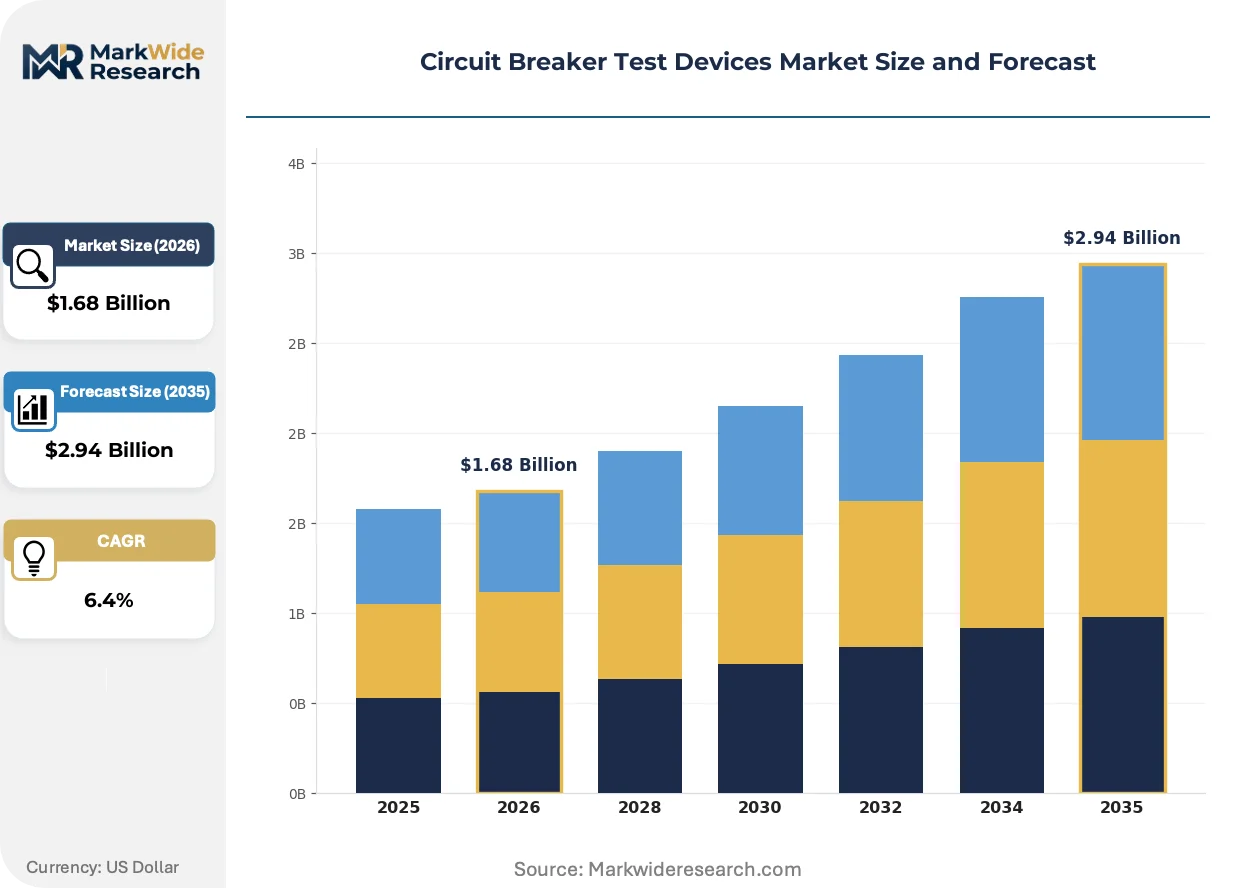
| Market Size in 2026 | $1.68 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Testers, Relay Test Sets, Automated Test Systems, Insulation Testers Technology: Digital, Analog, Hybrid, Microprocessor-Based End User: Utilities, Industrial Facilities, Research Labs, Maintenance Contractors Application: Routine Testing, Commissioning, Preventive Maintenance, Troubleshooting |
| Companies Covered | OMICRON, Megger, Transcat, SMC, SCOPE T&M, DV Power, Madhav Engineers, ESCO Technologies, ISA - Altanova Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circuit Breaker Test Devices Market Strategic Shifts
Software-defined functionality is decoupling diagnostic capability from dedicated hardware, enabling vendors to monetize capability upgrades through firmware rather than replacement sales. This architectural shift compresses equipment lifecycles while expanding recurring revenue pools.
Modular test set architectures are modularizing field service operations. Portable units now accept swappable current injection modules, timing analyzers, and coil resistance meters through standardized backplanes. US transmission maintenance crews are adopting these configurations to reduce truck inventory weight and accelerate setup times at remote substations. The approach is modularizing vendor competition away from monolithic specifications toward ecosystem compatibility and upgrade path guarantees.
EU CSRD disclosure requirements are mandating granular asset condition reporting for grid infrastructure operators. The directive forces utilities to document breaker health metrics with auditable test records, elevating data integrity features in procurement specifications. German and French distribution network operators are now prioritizing testers with tamper-proof timestamping and blockchain-anchored certificate storage.
Asset managers are unbundling after-sales service contracts from initial hardware purchases. US municipal utilities and cooperative networks are negotiating standalone calibration and firmware support agreements, treating test equipment as operational technology requiring continuous vendor engagement. This behavioral shift concentrates purchasing authority within reliability engineering departments rather than capital procurement offices.
Circuit Breaker Test Devices Market Segmentation
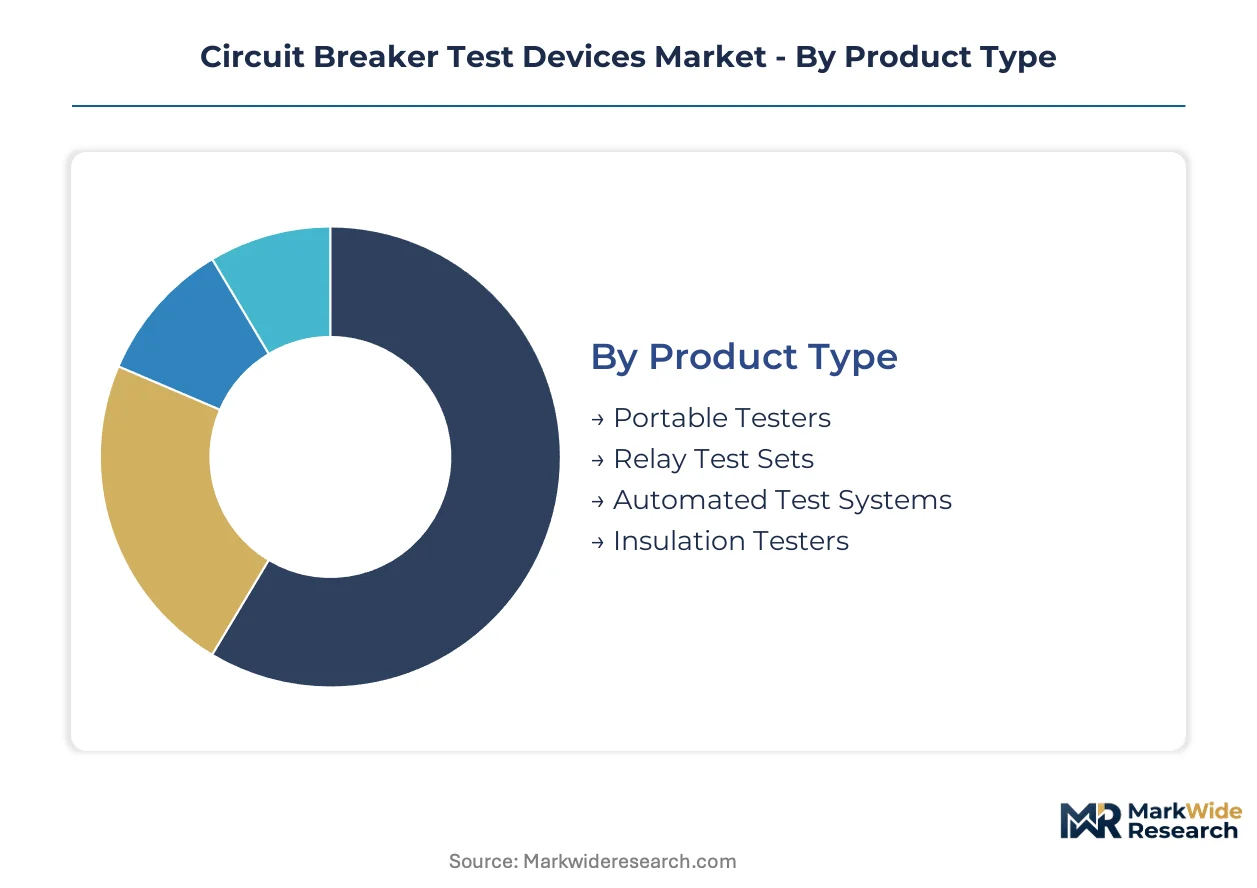
Circuit breaker test devices fragment across four critical dimensions that determine procurement patterns and vendor positioning. Product type and technology architecture drive capital allocation decisions, while end-user verticals and application contexts shape feature requirements and service contract structures.
Product Type:
Standardization dominates portable and relay test sets, while automated systems command extensive customization for substation-specific integration.
- Portable Testers:Battery-powered field units with modular current injection and timing analysis capabilities. US transmission maintenance crews deploy these across FERC-regulated bulk power systems, prioritizing truck inventory reduction and rapid substation setup protocols.
- Relay Test Sets:Specialized instruments validating protective relay coordination through simulated fault injection. German transmission operators under EU CSRD disclosure mandates are prioritizing these units for auditable asset condition documentation.
- Automated Test Systems:Rack-mounted configurations for factory acceptance and type testing per IEC 62271-100 protocols.
- Insulation Testers:Megohm and dielectric loss measurement units for medium-voltage breaker commissioning.
Leading the category by volume: Portable Testers. Growing fastest: Automated Test Systems.
Technology:
Cost tiers separate legacy analog architectures from premium microprocessor-based platforms with firmware upgrade paths.
- Microprocessor-Based:Software-defined architectures enabling automated waveform capture, cloud-synced reporting, and remote diagnostic access. US utilities confronting post-pandemic workforce constraints are mandating these capabilities for off-site analysis.
- Digital:Fixed-function electronic testers with solid-state timing and resistance measurement. Chinese State Grid Corporation procurement favors these for standardized substation modernization programs.
- Hybrid:Electromechanical current injection paired with digital measurement and logging subsystems.
- Analog:Electromechanical meters and manual injection systems from 1990s-era installations still operational at budget-constrained municipal utilities.
Volume concentrates in Microprocessor-Based platforms. Hybrid configurations are expanding most quickly among mid-tier utilities bridging legacy and modern infrastructure.
End User:
Customer type determines service contract intensity, with utilities demanding continuous vendor engagement versus industrial facilities preferring capital-only transactions.
- Utilities:Transmission and distribution operators under regulatory testing mandates. US cooperative networks and municipal utilities are unbundling calibration and firmware support agreements, treating test equipment as operational technology.
- Industrial Facilities:Manufacturing plants and data centers with captive medium-voltage switchgear. These buyers prioritize standalone hardware purchases over recurring service relationships.
- Research Labs:Universities and certification bodies conducting type tests and standard development.
- Maintenance Contractors:Third-party field service providers deploying portable units across multiple client sites.
Utilities command the largest procurement volume. Maintenance Contractors represent the steepest expansion trajectory as asset owners outsource testing functions.
Application:
Application maturity separates established routine testing from emerging predictive diagnostics reshaping intervention schedules.
- Preventive Maintenance:Condition-based monitoring replacing time-based schedules at US utilities under FERC jurisdiction. Asset managers are expanding portable tester deployment frequency to capture breaker health trends.
- Commissioning:Greenfield substation acceptance testing requiring high-current injection for circuit breaker verification. India's renewable integration surge under CEA guidelines is concentrating demand here.
- Routine Testing:Periodic verification protocols mandated by grid codes and insurance requirements.
- Troubleshooting:Reactive diagnostics following relay operations or fault events.
Preventive Maintenance leads application spending. Commissioning activity is climbing the fastest on renewable interconnection investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of circuit breaker test devices concentrates in Germany and China, while consumption patterns diverge across mature grid markets and rapid infrastructure buildouts. Manufacturing clusters leverage precision engineering capabilities and high-current coil winding expertise respectively. End-use demand fragments across regulatory regimes with distinct certification requirements.
United States
FERC-mandated periodic testing protocols for bulk power system assets sustain replacement demand for aging electromechanical test sets. The Infrastructure Investment and Jobs Act channels federal funding toward grid hardening programs that specify microprocessor-based diagnostic equipment. Texas and California transmission operators are unbundling calibration service contracts from hardware purchases, treating test devices as operational technology.
Germany
EU CSRD disclosure requirements mandate granular asset condition reporting with auditable test records for distribution network operators. The country's precision instrumentation cluster in Bavaria anchors manufacturing of high-specification relay test sets. Berlin and Munich utilities prioritize testers with blockchain-anchored certificate storage and tamper-proof timestamping features.
China
State Grid Corporation and China Southern Power Grid are accelerating substation modernization under grid reliability programs. SAMR-enforced GB conformity assessment rules shape local manufacturing specifications and import acceptance criteria for test equipment. Shanghai and Shenzhen industrial zones concentrate production of digital test sets for standardized domestic procurement frameworks.
India
Solar and wind farm interconnection rules under CEA guidelines create concentrated demand for portable commissioning testers at greenfield substations. The country's renewable integration surge requires high-current injection systems for circuit breaker verification at utility-scale projects. Gujarat and Tamil Nadu are deploying field units across rapidly expanding transmission networks.
Circuit Breaker Test Devices Market Competitive Environment
Top-tier vendors anchor the premium microprocessor-based segment, while mid-tier specialists occupy modular and portable configurations. The market structure reflects a tiered hierarchy with consolidated leadership in firmware-upgradeable platforms and fragmented competition in field-service accessories. Strategic archetypes include software-defined diagnostic providers, field-calibration network operators, and high-current injection specialists. Dominant competitive moves center on recurring revenue service contracts and ecosystem compatibility guarantees for modular architectures.
Within the firmware-upgradeable tier, OMICRON and Megger exemplify contrasting approaches to sustaining long-term client relationships. OMICRON leverages its software-defined architecture, while Megger anchors its position through extensive field-service calibration networks. DV Power occupies a specialized position in high-current injection systems for substation commissioning applications. These three companies represent the dominant strategic archetypes shaping vendor-customer dynamics across transmission and distribution networks.
| Leading Market Players |
|---|
| OMICRON |
| Megger |
| Transcat |
| SMC |
| SCOPE T&M |
| DV Power |
| Madhav Engineers |
| ESCO Technologies |
| ISA - Altanova Group |
| Others |
Value Chain & Pricing Dynamics
Microprocessor-based firmware tiers diverge sharply from legacy analog platforms, creating parallel pricing architectures that map onto distinct supply chain configurations. Premium vendors source precision ADCs and FPGA modules from German and Japanese component houses, while commodity digital testers draw from standardized Chinese microcontroller supply chains.
Pricing Analysis
Margin tightening in the portable tester segment reflects copper coil and neodymium magnet cost volatility pressuring high-current injection manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates firmware-upgradeable units with cloud-synced reporting from fixed-function digital testers and aging analog replacements. IEC 62271-100 certification compliance adds 15-25% cost premiums that municipal utilities absorb reluctantly, while transmission operators prioritize capability over price. Maintenance contractors exhibit highest price sensitivity, driving procurement toward modular configurations with swappable subsystems.
Supply Chain Analysis
Copper winding supply rests on Chilean mining output and Chinese smelter capacity, with neodymium magnet feedstock concentrated in Chinese rare-earth processing facilities. Precision instrumentation components source from German sensor manufacturers and Japanese semiconductor fabricators. Single-source vulnerability in FPGA supply chains exposes lead time risks for microprocessor-based architectures. Distribution runs through authorized calibration networks rather than traditional industrial distributors, tying equipment procurement to long-term service relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where FERC-mandated periodic testing protocols erect regulatory moats that favor certified incumbents over unvalidated entrants.
For Market Incumbents: Deepen firmware upgrade architectures to capture recurring calibration revenue streams from US cooperative networks facing post-pandemic technician shortages. Anchor defensive positioning through backward integration into precision current injection coil manufacturing, mitigating copper and rare-earth magnet cost volatility that threatens margin stability in high-current product lines. For New Entrants and Emerging Players: Maintenance contractor channels offer the most penetrable entry vector given their price sensitivity and preference for modular, truck-deployable configurations. Target India's renewable integration surge under CEA guidelines with portable commissioning testers designed for greenfield substation deployment, leveraging local assembly partnerships to navigate SAMR import acceptance barriers. For Investors and Strategic Acquirers: Re-rating potential sits with firmware-upgradeable platform specialists given EU CSRD disclosure mandates forcing auditable asset condition reporting across German and French distribution networks. Watch for inflection signals in maintenance contractor outsourcing ratios, as asset owner disaggregation of testing functions accelerates recurring revenue capture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Subscription Migration | Transforms capital equipment sales into recurring SaaS revenue streams anchored by IEC 62271-100 compliance requirements. |
| Modular Architecture Standardization | Enables swappable current injection and timing modules that reduce truck inventory for US transmission crews. |
| Blockchain-Anchored Certificate Storage | Addresses EU CSRD tamper-proof documentation mandates elevating data integrity in German utility procurement. |
| Remote Diagnostic Capability Buildout | Captures post-pandemic workforce constraints driving cloud-synced reporting adoption across FERC-regulated utilities. |
| High-Current Injection Specialization | Targets India's renewable intercommissioning surge with dedicated substation verification systems under CEA guidelines. |
Study Parameters
Document review covered IEC 62271-100 and IEEE C37.09 standard documentation, FERC regulatory filings, and EU CSRD directive texts, complemented by interviews with utility reliability engineering directors, protective relay specialists, transmission maintenance supervisors, and test equipment calibration technicians. Secondary validation drew from State Grid Corporation procurement disclosures, SAMR conformity assessment bulletins, and CEA renewable interconnection guidelines. Bottom-up unit demand modeling triangulated against top-down infrastructure investment forecasts.
Segment-level projections across product type, technology architecture, end-user vertical, and application context fed into consolidated market sizing throughout the forecast period. CAGRs derived from regression analysis of historical replacement cycles, regulatory mandate implementation timelines, and infrastructure modernization program announcements. Copper price indices and rare-earth magnet supply forecasts informed cost-side sensitivity testing for high-current injection system demand.
Caveats apply where commodity price spikes, certification timeline delays, or workforce availability constraints could materially shift the outlook. A small set of named triggers—FERC mandate expansion, EU CSRD enforcement intensity, and India renewable auction velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Roughness Tester Market
Test and Measurement
Test and Measurement Market
Test and Measurement
Industrial Metrology Market
Test and Measurement
Whiteness Meter Market
Test and Measurement
Voltage Tester Market
Test and Measurement
X-Ray Inspection System Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market
Test and Measurement
Nanomechanical Testing Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
Surface Inspection Market
Test and Measurement
Flash Point Tester Market
Test and Measurement
Digital Depth Gauges Market
Test and Measurement
United States Signal Generator Market
Test and Measurement
Electronic Measuring Device Market