
 Acoustic Wave Filters Market | 2026-2036
Acoustic Wave Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Wave Filters Market Analysis
Filter module customization revenue is rewriting margin capture across the RF supply chain. Murata Manufacturing Co. Ltd leverages its ceramic material science heritage to dominate high-volume SAW production for consumer handsets. Qorvo Inc. anchors its position through in-house BAW fabrication serving defense and aerospace qualification requirements. Broadcom Inc. competes on FBAR density leadership, particularly in carrier aggregation architectures for North American carriers.
Acoustic wave filters are electromechanical devices that convert electrical signals into mechanical acoustic waves on piezoelectric substrates—typically lithium tantalate, lithium niobate, or aluminum nitride—then reconverting to electrical output with precise frequency selectivity, enabling interference rejection in multi-band wireless systems. Surface Acoustic Wave variants occupy the cost-sensitive low-to-mid frequency tier below 3 GHz where volume scale sustains margin compression, while Bulk Acoustic Wave and FBAR technologies command premium positioning above 3.5 GHz as 5G n77/n79 deployment expands. The component stack sees resonators capturing the largest value share, though couplers are gaining traction in massive MIMO antenna configurations.
FCC Part 27 rules and CE marking under the EU Radio Equipment Directive shape emission mask compliance and market access thresholds for filter manufacturers selling into regulated telecommunications infrastructure. China's MIIT radio type approval and Japan's TELEC certification impose additional spurious response limits that drive R&D spending toward temperature-compensated designs. Stakeholders must monitor spectrum auction outcomes and regional 6G research programs to align filter roadmaps with emerging band definitions.
Market Dynamics
5G mid-band spectrum allocation is compressing filter design cycles as smartphone OEMs demand modules supporting n77, n78, and n79 bands simultaneously. This frequency densification forces manufacturers to reconcile thermal drift compensation with miniaturization constraints.
Growth Catalysts
- MIIT 5G mid-band assignments:China's spectrum licensing accelerates domestic base station deployment, pulling filter demand through state-backed carrier procurement tenders.
- Lithium niobate substrate advances:Thin-film lithium niobate is extending SAW performance into previously BAW-dominated frequency ranges, opening cost-optimized design paths.
- Seoul-Pyeongtaek semiconductor cluster:Concentrated foundry and packaging capacity in South Korea reduces logistics friction for module integrators serving Asia-Pacific handset assembly.
Market Restraints
- Aluminum nitride wafer supply:Limited high-purity AlN substrate fabrication capacity concentrates upstream sourcing with Japanese and Korean suppliers.
- FCC Part 27 emission mask compliance:Stringent spurious response limits for US carrier aggregation configurations extend qualification timelines and raise non-recurring engineering costs.
- Temperature-compensated SAW substitution:TC-SAW performance improvements threaten BAW volume in 2.5–3.5 GHz applications where premium pricing previously held.
Strategic Opportunities
- India PLI scheme for telecom equipment:Production-linked incentives for domestic 5G manufacturing create localized filter assembly demand outside established East Asian supply chains.
- Wi-Fi 6E/7 frequency convergence:Unlicensed 6 GHz band expansion positions acoustic filters for coexistence management between cellular and WLAN radios in converged modules.
- EU Radio Equipment Directive harmonization:Streamlined CE marking pathways for multi-band modules reduce regulatory fragmentation costs for vendors targeting European carrier certifications.
Industry Challenges
- Piezoelectric thin-film deposition expertise:Scandium-doped aluminum nitride process engineering talent pools remain shallow relative to demand for high-coupling BAW resonators.
- TELEC certification timeline compression:Japan's type approval procedures for 5G NR devices impose parallel testing requirements that strain regional qualification resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Wave Filters Market |
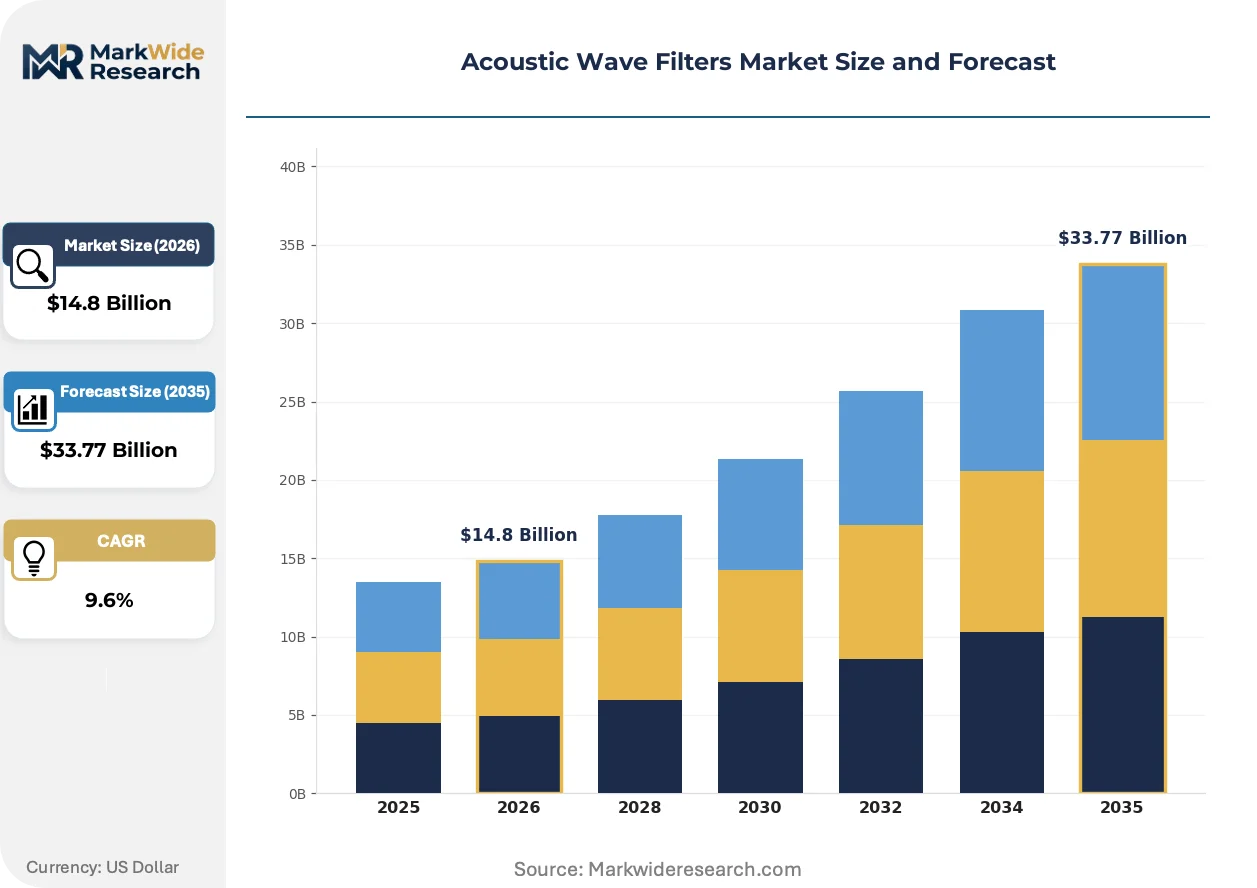
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.77 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SAW Filters, BAWW Filters, FBAR Filters, Others Component: Resonators, Couplers, Amplifiers, Mixers Technology: Surface Acoustic Wave, Bulk Acoustic Wave, High-Frequency Wave, Low-Frequency Wave End User: Telecommunications, Consumer Electronics, Automotive, Aerospace |
| Companies Covered | Broadcom Inc., Kyocera Corporation, Murata Manufacturing Co. Ltd, Qualcomm Technologies Inc., Taiyo Yuden Co. Ltd., Qorvo Inc., TDK Corporation, Akoustis Technologies, Skyworks Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Wave Filters Market Emerging Trajectories
Filter architectures are bifurcating between cost-optimized integration for mass-market handsets and performance-isolated designs for defense and aerospace qualification tiers. Material science breakthroughs and spectrum policy evolution are the twin engines of this divergence.
Thin-film lithium niobate-on-insulator is rendering obsolete conventional quartz-based SAW resonators in sub-3 GHz applications. Smartphone RF front-end module designers are adopting this platform for its electromechanical coupling coefficient advantages. The technology is rendering obsolete legacy temperature-compensated SAW processes that dominated 4G filter volumes, compressing margin structures for incumbents wedded to established lithium tantalate supply chains.
REACH substance restrictions on piezoelectric ceramics are forcing reformulation of dopant chemistries in European-bound components. The European Chemicals Agency's candidate list scrutiny of niobium and tantalum supply chains is elevating traceability documentation burdens. Filter vendors serving EU automotive and industrial telecommunications are responding by qualifying alternative substrate suppliers with certified conflict-free sourcing.
Carrier aggregation complexity is fragmenting procurement specifications across North American, European, and Asian operator requirements. Module integrators now maintain parallel filter SKUs for region-specific band combinations rather than universal platforms. This specification divergence is most acute in North America, where Verizon, AT&T, and T-Mobile maintain non-overlapping n77 sub-band prioritization that prevents component standardization.
Acoustic Wave Filters Market Segmentation
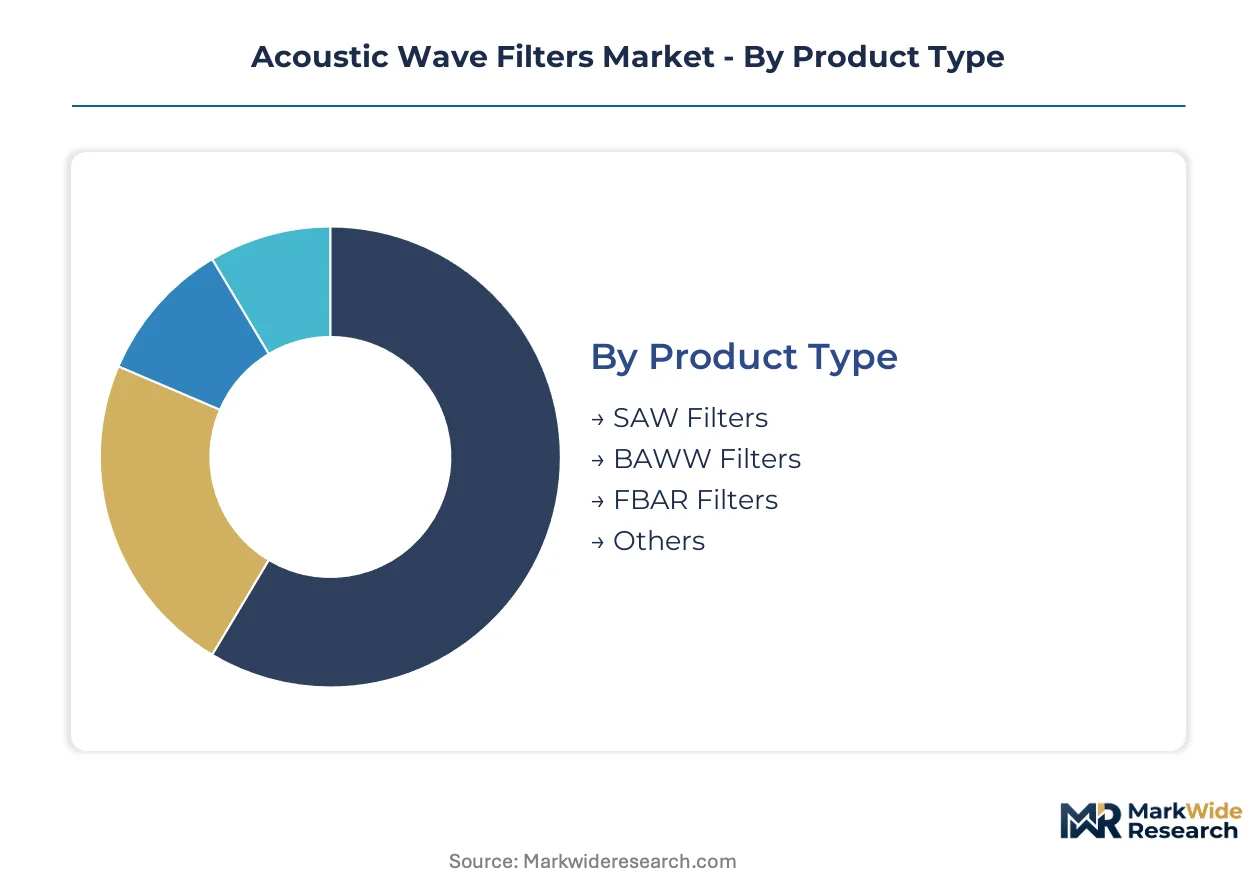
Acoustic wave filter segmentation reflects the tension between frequency performance requirements and cost optimization pressures across divergent end-use applications. Each dimension—product architecture, component hierarchy, signal processing technology, and customer vertical—carries distinct margin profiles and qualification barriers that reshape vendor positioning strategies.
Product Type:
Cost tier differentiation separates mass-market handset procurement from premium infrastructure deployment, with substrate material science determining the price-performance frontier.
- SAW Filters:Surface acoustic wave devices leverage lithium tantalate or lithium niobate substrates for sub-3 GHz frequency selection. Korean smartphone OEMs in Seoul-Pyeongtaek drive procurement volumes for mid-band 5G handsets where cost compression dominates.
- BAW Filters:Bulk acoustic wave architectures employ aluminum nitride thin films sandwiched between electrodes for superior Q-factor above 3.5 GHz. US carrier aggregation requirements under FCC Part 27 rules concentrate demand for n77 band performance where thermal stability commands premium positioning.
- FBAR Filters:Film bulk acoustic resonators achieve the highest electromechanical coupling coefficients for carrier aggregation complexity. North American infrastructure vendors specify these for defense and aerospace qualification tiers.
- Others:Emerging MEMS-based and hybrid acoustic technologies address niche temperature-compensated applications in industrial telemetry.
SAW filters command the established base. The steepest expansion runs through BAW filters.
Component:
Application criticality determines which functional blocks capture module-level value, with antenna configuration complexity reshaping component mix priorities.
- Resonators:Piezoelectric resonant elements establish the fundamental frequency reference through thickness-mode or surface-wave vibration. Massive MIMO base station deployment in China's MIIT-licensed mid-bands concentrates procurement for 64T64R antenna arrays.
- Couplers:Directional coupling devices manage signal distribution between transmit and receive paths in multi-band modules. 5G n77/n78/n79 simultaneous support requirements in South Korean handsets accelerate adoption for antenna diversity configurations.
- Amplifiers:Low-noise and power amplification stages precede or follow filter stages in complete RF front-end chains.
- Mixers:Frequency translation components enable heterodyne architectures in software-defined radio platforms.
Resonators anchor current module economics. Couplers are climbing the fastest as antenna complexity multiplies.
Technology:
Volume concentration follows spectrum allocation patterns, with frequency band definitions in major economies dictating technology mix priorities.
- Surface Acoustic Wave:Interdigital transducer structures on piezoelectric substrates convert electrical to mechanical energy at the surface boundary. India's PLI scheme for telecom equipment is pulling SAW demand into emerging domestic assembly capacity outside established East Asian supply chains.
- Bulk Acoustic Wave:Thickness-extensional vibration modes in thin-film stacks deliver superior power handling and insertion loss performance. Japanese TELEC certification timelines for 5G NR devices concentrate qualification investment in BAW platforms for the 3.5–6 GHz range.
- High-Frequency Wave:Extended frequency operation above 6 GHz for Wi-Fi 6E/7 convergence and prospective 6G research programs.
- Low-Frequency Wave:Sub-1 GHz legacy support for IoT and narrowband-IoT applications in spectrum-constrained environments.
Surface acoustic wave technology holds the volume base. Bulk acoustic wave technology is gaining share fastest as mid-band 5G densifies.
End User:
Customer type segmentation separates consumer-scale procurement cycles from industrial qualification timelines, with regulatory jurisdiction fragmenting specification requirements.
- Telecommunications:Base station and handset OEM procurement dominates absolute volume, with carrier-specific band combinations preventing component standardization. FCC, MIIT, and EU Radio Equipment Directive compliance requirements fragment SKU proliferation across North American, Chinese, and European operator tenders.
- Consumer Electronics:Smartphone, tablet, and wearable device integration prioritizes miniaturization and power efficiency over absolute performance. Thin-film lithium niobate-on-insulator adoption is displacing legacy quartz SAW in sub-3 GHz applications for Korean and Chinese handset programs.
- Automotive:Connected vehicle and V2X communication modules impose AEC-Q200 reliability standards and extended temperature range requirements.
- Aerospace:Satellite communication and defense systems demand hermetic packaging, radiation tolerance, and extended qualification documentation under ITAR and equivalent national regimes.
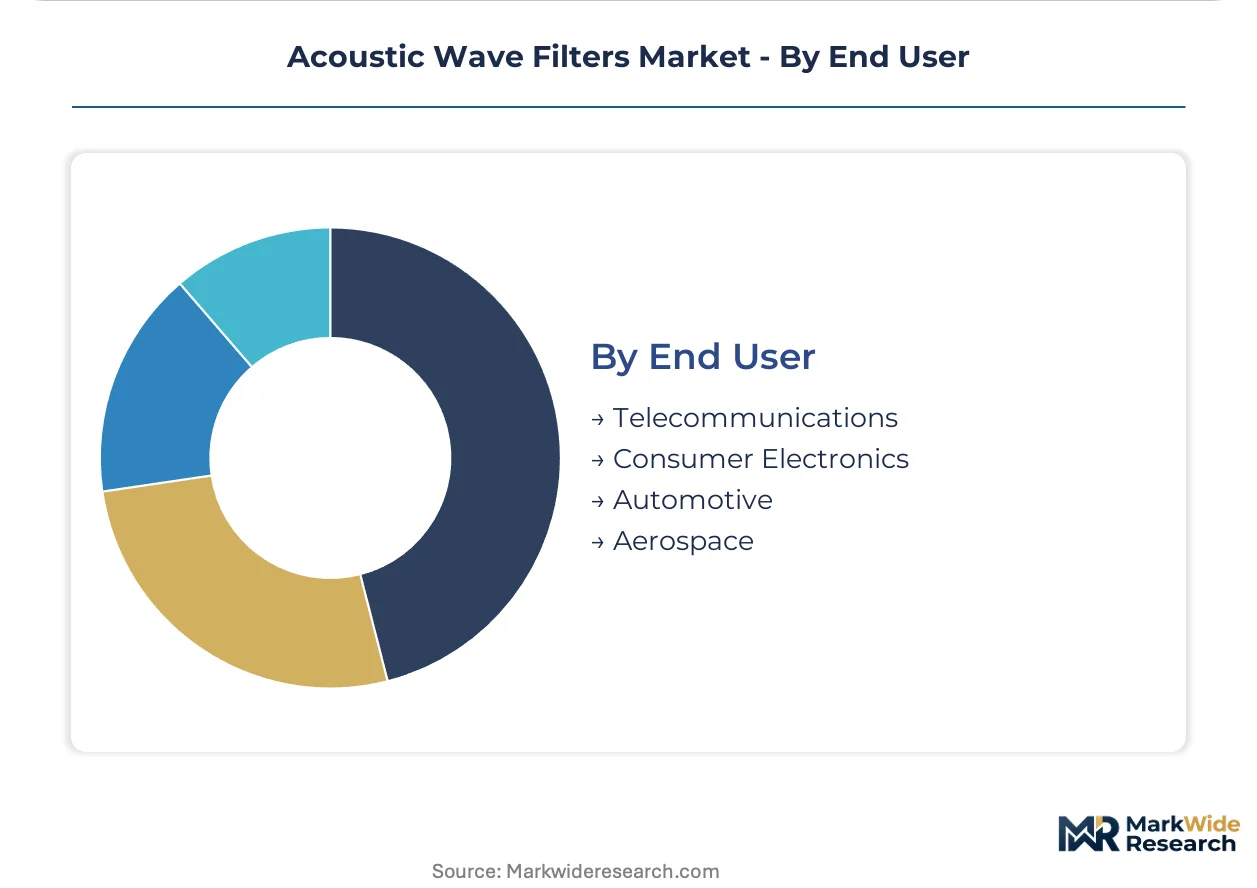
Telecommunications commands the established base. Consumer electronics represents the steepest expansion trajectory as 5G handset refresh cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Handset OEMs in South Korea and China tolerate premium pricing for 5G mid-band filters, while Indian and Southeast Asian procurement prioritizes cost-optimized SAW platforms for sub-3 GHz volume deployment.
South Korea
Samsung Electronics and LG Innotek drive BAW filter procurement for flagship 5G handsets supporting n77/n78/n79 carrier aggregation. The Korea Communications Commission's spectrum licensing accelerates mmWave infrastructure trials. Seoul-Pyeongtaek corridor hosts concentrated foundry packaging capacity serving Asia-Pacific module integrators.
China
MIIT's 5G mid-band assignments pull domestic base station deployment through state-backed carrier tenders. Huawei and ZTE procurement concentrates filter demand for massive MIMO antenna arrays. Yangtze River Delta manufacturing clusters in Suzhou and Wuxi supply ceramic substrate processing for SAW resonator production.
United States
Verizon, AT&T, and T-Mobile maintain non-overlapping n77 sub-band prioritization that fragments filter SKU standardization. FCC Part 27 emission mask compliance extends qualification timelines for carrier aggregation modules. Defense and aerospace procurement in Southern California and Massachusetts sustains hermetic packaging demand for FBAR qualification tiers.
Japan
TELEC certification timelines for 5G NR devices impose parallel testing requirements that strain regional qualification resources. Murata Manufacturing and TDK Corporation anchor domestic thin-film deposition expertise for high-coupling BAW resonators. Kyushu and Kansai industrial corridors concentrate piezoelectric substrate fabrication capacity.
India
PLI scheme production-linked incentives for domestic 5G manufacturing create localized filter assembly demand outside established East Asian supply chains. TRAI spectrum auction outcomes shape mid-band deployment priorities for Reliance Jio and Bharti Airtel. Gujarat and Tamil Nadu emerging electronics manufacturing clusters attract module integrator investment.
Acoustic Wave Filters Market Vendor Landscape
Capability concentration sits with specialized BAW fabricators commanding premium positioning above 3.5 GHz; scale advantage sits with high-volume SAW producers serving cost-sensitive handset procurement below 3 GHz. The market structures around three archetypes: integrated module vendors controlling captive filter supply, pure-play filter specialists leveraging substrate material science heritage, and fabless design houses accessing foundry partnerships. Dominant competitive moves include backward integration into piezoelectric wafer sourcing and strategic partnerships between filter designers and smartphone RF front-end module integrators.
Within the integrated module tier, Broadcom Inc. and Qualcomm Technologies Inc. exemplify vendors controlling captive BAW and SAW fabrication for proprietary RF front-end platforms. Among Japan-based component specialists, Murata Manufacturing Co. Ltd and TDK Corporation occupy positions anchored in ceramic material science heritage for high-volume resonator production. Qorvo Inc. represents the defense-aerospace qualification specialist archetype, with Skyworks Solutions Inc. and Akoustis Technologies situating within fabless and emerging technology vectors respectively.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Kyocera Corporation |
| Murata Manufacturing Co. Ltd |
| Qualcomm Technologies Inc. |
| Taiyo Yuden Co. Ltd. |
| Qorvo Inc. |
| TDK Corporation |
| Akoustis Technologies |
| Skyworks Solutions Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in South Korean lithium tantalate wafer fabrication is compressing foundry margins and forcing tier-one suppliers into aggressive price positioning for SAW filter contracts. This utilization imbalance cascades through module integrators in the Seoul-Pyeongtaek corridor, where pricing power tilts toward handset OEMs consolidating procurement volumes.
Pricing Analysis
Long-term offtake agreements dominate procurement between smartphone OEMs and tier-one filter manufacturers, locking in volume commitments against quarterly price adjustment clauses. Three-tier pricing structure across premium, standard, and economy levels separates defense-qualified FBAR modules from carrier-grade BAW and cost-optimized SAW tiers. Pricing pressure stems from thin-film lithium niobate substitution eroding legacy SAW margins in sub-3 GHz applications. Mid-tier handset manufacturers exhibit highest price sensitivity, while aerospace contractors absorb premium positioning with minimal negotiation leverage.
Supply Chain Analysis
US export controls on aluminum nitride deposition equipment limit technology transfer to Chinese foundries, fragmenting BAW fabrication capacity across Japan, South Korea, and the United States. High-purity lithium niobate substrates, scandium-doped aluminum nitride precursors, and hermetic ceramic packaging draw from concentrated Japanese and Korean suppliers. Single-source vulnerability in AlN wafer supply creates qualification bottlenecks for new BAW entrants. Distribution runs through captive module integrator channels rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acoustic wave filter demand sits in early-cycle expansion as 5G mid-band handset refresh cycles accelerate procurement volumes beyond infrastructure deployment rates. Thin-film lithium niobate commercialization is compressing qualification timelines and opening white-space for substrate specialists.
For Market Incumbents: Harden lithography and deposition IP positions through captive patent licensing to fabless design houses, neutralizing emerging thin-film lithium niobate specialists before scale. Secure backward integration into high-purity lithium tantalate and lithium niobate wafer supply through equity stakes in Yangtze River Delta substrate processors, insulating against Chinese export license volatility.
For New Entrants and Emerging Players: Build out thin-film lithium niobate-on-insulator process capabilities targeting India's PLI scheme assembly incentives, where domestic 5G manufacturing creates filter demand outside established East Asian supply chains. Pursue RF front-end module integrator partnerships as the primary go-to-market path, bypassing direct qualification with tier-one smartphone OEMs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across BAW fabrication as scandium-doped aluminum nitride equipment and cleanroom requirements escalate, favoring scaled incumbents over venture-backed entrants. Acquisition targets should emphasize substrate material science heritage with existing piezoelectric wafer customer relationships. Watch MIIT spectrum auction outcomes for n79 band prioritization as the inflection signal for BAW versus SAW technology mix shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Film Lithium Niobate Process Scale-Up | Extends SAW performance into BAW-dominated frequencies, reshaping cost structures for Korean handset OEMs. |
| Backward Integration into Piezoelectric Wafer Supply | Captures margin from lithium tantalate substrate processors concentrated in Japan and China. |
| India PLI Scheme Localization Partnership | Positions filter assembly capacity outside East Asian supply chains for Reliance Jio and Bharti Airtel procurement. |
| Defense-Aerospace Hermetic Packaging Qualification | Opens ITAR-restricted revenue tiers with Southern California and Massachusetts prime contractors. |
| Carrier Aggregation Module SKU Consolidation | Reduces fragmentation costs from Verizon, AT&T, and T-Mobile non-overlapping n77 sub-band requirements. |
Methodological Framework
Initial hypotheses were tested against primary input from RF front-end module procurement directors, piezoelectric substrate process engineers, semiconductor foundry operations managers, and carrier certification test laboratory heads, then refined against customs records for lithium niobate and lithium tantalate wafer trade flows, FCC equipment authorization databases, MIIT radio type approval registries, and SEC 10-K filings from listed component vendors. Bottom-up smartphone filter content modeling and top-down RF front-end market sizing were cross-validated to establish volume baselines.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across filter architecture type, frequency band tier, substrate material platform, end-use vertical, and regional regulatory cluster. CAGRs were derived from annual shipment trajectory analysis calibrated against carrier deployment schedules and OEM product refresh cycles. Forecast inputs incorporated MIIT 5G base station tender volumes and FCC Part 27 spectrum auction band plan finalizations.
Stress conditions across aluminum nitride wafer supply disruptions, REACH substance restriction enforcement timelines, and TELEC certification backlog scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding smartphone 5G penetration curves and carrier aggregation complexity evolution. Material shifts in FCC n77 sub-band prioritization or MIIT mid-band license reallocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Digital Radio Frequency Memory Market
RF Components
RF Switches Market
RF Components
RF Filters Market
RF Components
Gaas RF Switch Market
RF Components
RFID Antenna Market
RF Components
Analog Phase Shifter Market
RF Components
RF Over Fiber (Rfof) Market
RF Components
Toroid Inductor Market
RF Components
SMD Resonator Market
RF Components
Global Ceramic Dielectric Filters Market
RF Components
5G Driver Amplifier Market
RF Components
Digital Radio Frequency Market
RF Components
5G Millimeter Wave RF Transceiver Market
RF Components
Silicon Tuners Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
RF Antenna Market