
 Amplifier Market | 2026-2036
Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Amplifier Market Analysis
Aftermarket service revenue and firmware upgrade subscriptions is tilting margin pools away from pure hardware sales. Texas Instruments leverages its broad analog portfolio to anchor long-term supply agreements with industrial automation customers. Infineon Technologies specializes in silicon carbide and gallium nitride power stages for high-efficiency audio amplification. STMicroelectronics competes through integrated Class D solutions that reduce bill-of-materials complexity for OEMs.
An amplifier is an electronic device that increases the amplitude of electrical signals, typically characterized by metrics such as total harmonic distortion below 0.1 percent, signal-to-noise ratio exceeding 100 decibels, and power output ranging from milliwatts to kilowatts depending on application. Its primary purpose spans audio reproduction, telecommunications signal conditioning, and sensor signal processing across consumer, industrial, and automotive systems. Class D amplifiers are capturing share in portable and automotive applications where thermal efficiency and battery life dominate design priorities. Professional audio applications sustain premium pricing through ruggedized enclosures, redundant cooling, and touring-grade reliability certifications. Wired connectivity remains the default in studio and installed-sound environments where latency and interference immunity are non-negotiable.
The Federal Communications Commission in the United States governs electromagnetic emissions from amplifier circuitry, while the European Union's Ecodesign Directive mandates minimum energy efficiency and standby power limits for consumer audio equipment. China's Ministry of Industry and Information Technology enforces GB standards on electromagnetic compatibility and safety certification for domestically sold amplification products. Stakeholders must monitor how regional efficiency mandates and material substance restrictions reshape component sourcing and product qualification pathways.
Market Dynamics
Class D and gallium nitride power stages are compressing thermal budgets and physical footprints, forcing incumbent Class AB architectures into niche professional applications where harmonic fidelity remains non-negotiable.
Growth Catalysts
- EU Ecodesign Directive:Minimum energy-efficiency mandates and standby power limits are accelerating OEM migration toward digital amplifier topologies in consumer audio equipment sold across member states.
- Automotive infotainment expansion:Electric vehicle cabin acoustics and head-unit integration are pulling multi-channel Class D modules into tier-1 supplier roadmaps for premium and mass-market vehicle lines.
- Live event infrastructure:Touring-grade amplifier rack density requirements are driving procurement of high-efficiency, lightweight power stages for stadium and festival deployment.
Market Restraints
- Silicon carbide substrate costs:GaN-on-SiC and pure SiC device pricing constrains adoption in cost-sensitive consumer segments where silicon MOSFETs still dominate.
- China manufacturing concentration:Domestic OEM and contract manufacturer clustering creates single-source vulnerability for global brands dependent on Shenzhen and Dongguan assembly ecosystems.
- Electromagnetic compatibility certification:FCC Part 15 and GB 9254 testing timelines extend product qualification cycles by four to eight months for new amplifier platforms.
Strategic Opportunities
- India industrial automation:BIS certification alignment and PLI scheme incentives are opening procurement pathways for precision signal conditioning amplifiers in process control and robotics.
- Firmware-as-a-service monetization:Over-the-air DSP profile updates and tunable crossover algorithms are creating recurring revenue streams detached from hardware replacement cycles.
- 5G small cell infrastructure:Massive MIMO RF power amplifier demand for sub-6 GHz deployment is converging with envelope tracking and Doherty architecture advances.
Industry Challenges
- Analog-digital mixed-signal design talent:Scarcity of engineers proficient in both Class D modulation schemes and thermal management simulation is elongating R&D cycle times.
- Legacy studio integration:AES/EBU and Dante network protocol fragmentation complicates amplifier deployment in hybrid analog-digital broadcast environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amplifier Market |
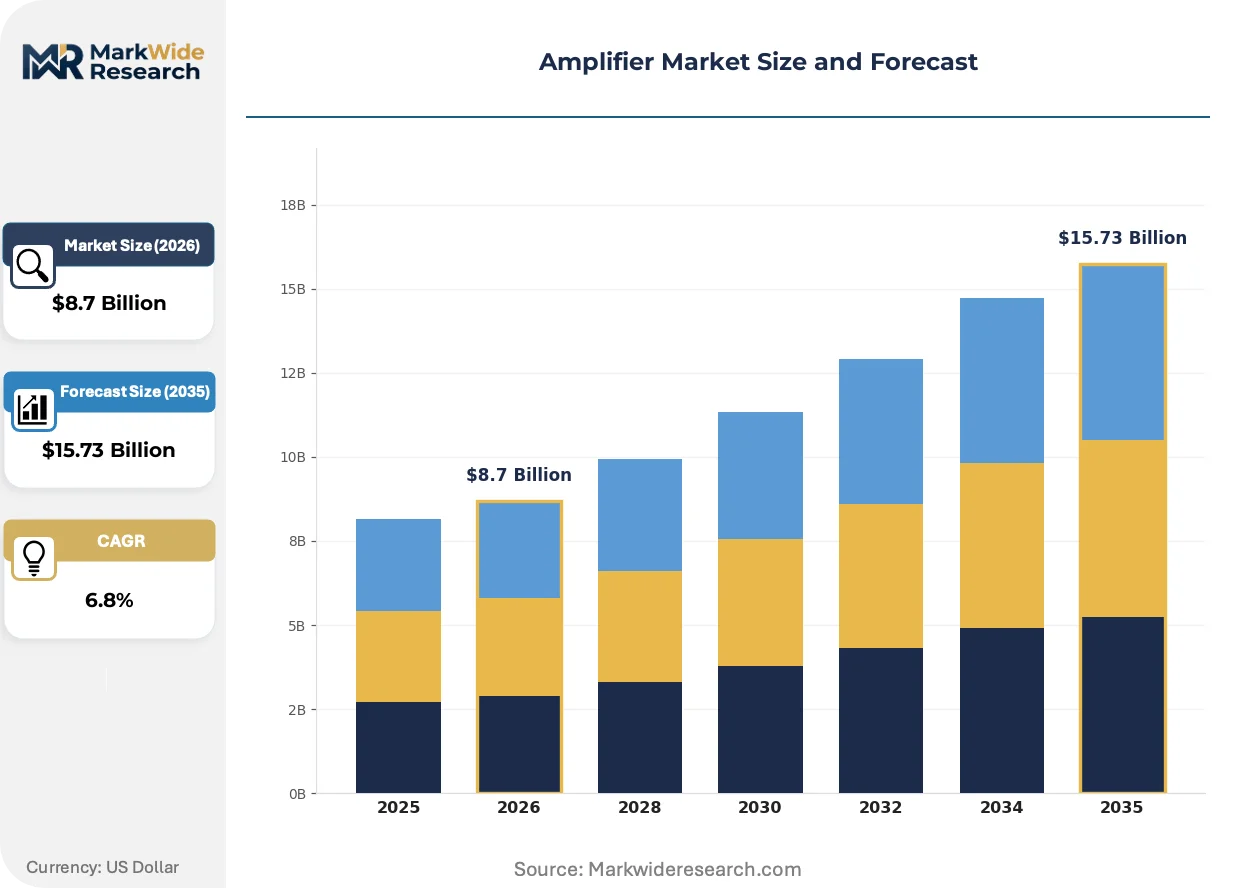
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Amplifiers, Analog Amplifiers, Hybrid Amplifiers, Class D Amplifiers Application: Professional Audio, Home Theater, Musical Instruments, Public Address Systems Connectivity: Wired, Wireless, Bluetooth, USB End User: Music Producers, Audio Engineers, Home Users, Event Organizers |
| Companies Covered | Texas Instruments, Infineon Technologies, STMicroelectronics, NXP Semiconductors, Analog Devices, QUALCOMM Incorporated, Yamaha Corporation, Sony Corporation, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amplifier Market Emerging Trajectories
Distributed DSP architectures and cloud-connected amplifier networks are collapsing the distinction between edge hardware and centralized audio processing, redistributing value toward software-defined signal paths.
GaN HEMT power stages are virtualizing the thermal and magnetic component requirements that previously dictated Class D amplifier physical design. Automotive tier-1 suppliers are adopting these devices at accelerated pace for 12-volt and 48-volt vehicle electrical systems. This transition is compressing magnetics volume and enabling integration of multi-kilowatt channels into single semiconductor packages.
REACH substance restrictions and RoHS recast directives are eliminating lead-based solders and specific flame retardants from amplifier PCB assemblies sold in European markets. Manufacturers are qualifying halogen-free laminates and tin-silver-copper alloy alternatives. Professional audio OEMs with touring-grade certification requirements face the steepest reformulation timelines due to reliability validation protocols.
Live event production companies are unbundling amplifier hardware ownership from operational deployment, preferring rental and managed-service models for festival and corporate staging. This compresses capital expenditure into operating budgets and shifts supplier relationships toward fleet-management platforms. North American touring logistics providers are consolidating procurement through national rental house networks rather than direct manufacturer relationships.
Amplifier Market Segmentation
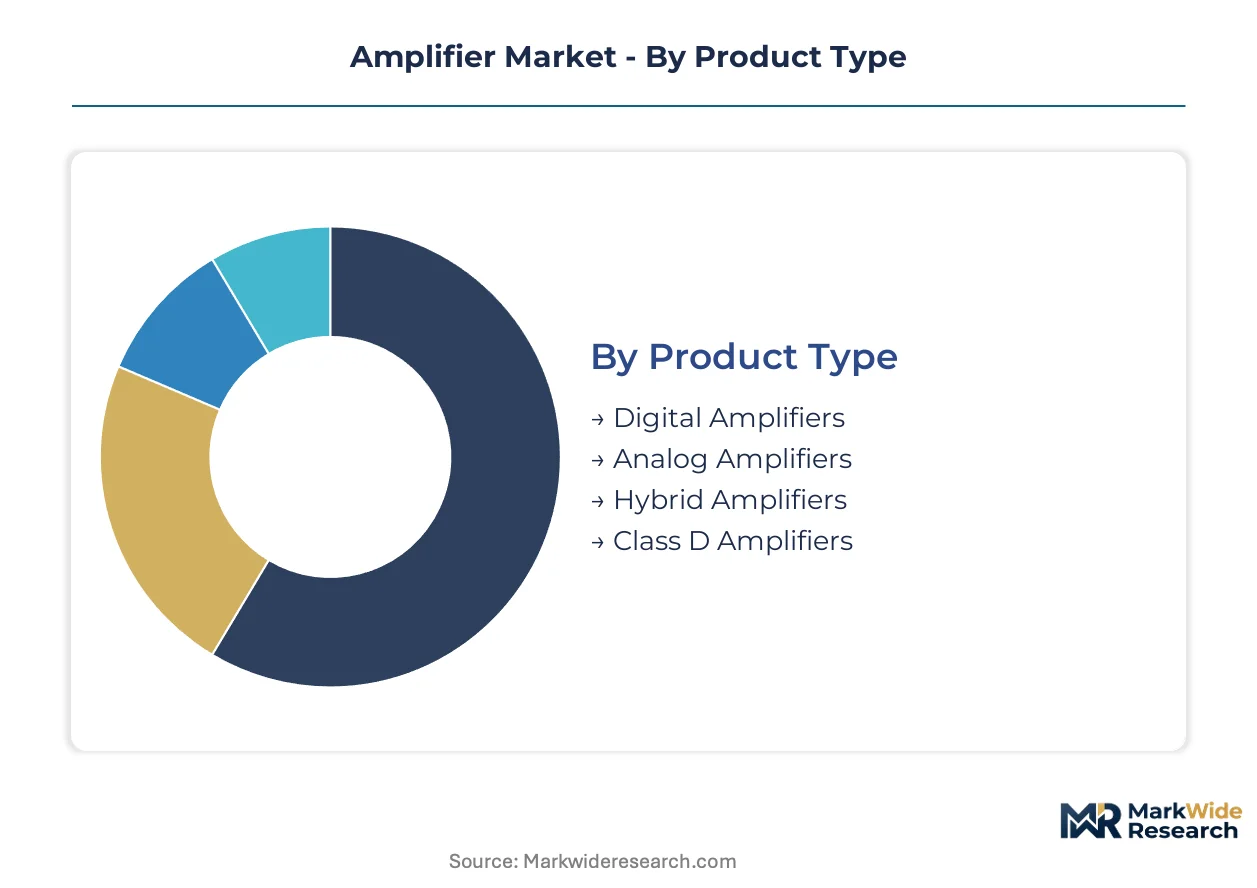
Amplifier segmentation reveals divergent service intensity across product tiers. Professional installations demand firmware subscriptions and field calibration, while consumer segments prioritize replacement cycles over aftermarket engagement.
Product Type:
After-sales-service intensity varies sharply across amplifier architectures, with digital platforms generating recurring DSP update revenue while analog units rely on component-level repair networks.
- Digital Amplifiers:Pulse-code modulation and sigma-delta architectures enable over-the-air firmware updates and cloud-based parametric equalization. Music production studios in Germany and broadcast facilities in the United Kingdom are standardizing on networked digital backbones that monetize through subscription-based DSP profiles rather than hardware refresh cycles.
- Class D Amplifiers:Switching-mode topologies achieve thermal efficiencies above 90 percent, enabling kilowatt-scale output from palm-sized enclosures. Electric vehicle manufacturers in China and portable PA system vendors in the United States are pulling these devices into 12-volt and 48-volt automotive electrical architectures where battery load minimization dominates design specifications.
- Analog Amplifiers:Class AB and Class A discrete transistor designs persist in mastering studios and audiophile installations where harmonic distortion signatures below 0.01 percent justify continuous bias current and substantial heatsinking.
- Hybrid Amplifiers:Combined analog input stages with digital output modulation bridge legacy source compatibility and modern efficiency requirements in mid-tier home theater receivers.
Class D amplifiers hold the largest share; momentum sits with digital amplifiers.
Application:
Cost tier stratification separates touring-grade rack systems from mass-market consumer electronics, with professional segments absorbing 4-8x unit premiums for redundancy certifications and road-case compatibility.
- Professional Audio:Touring amplifiers, broadcast monitoring systems, and installed-sound infrastructure demand redundant cooling, hot-swappable power supplies, and AES/EBU digital audio connectivity. Festival production companies in Brazil and corporate AV integrators in the United States are consolidating procurement through rental house networks rather than direct manufacturer relationships, compressing capital expenditure into operating budgets.
- Home Theater:Multi-channel AV receivers and soundbar amplification modules prioritize HDMI eARC compatibility and room-correction DSP algorithms. Japanese and South Korean consumer electronics OEMs are integrating these functions into single-chip solutions that reduce external component counts.
- Musical Instruments:Guitar and bass amplifiers emphasize tube emulation circuitry and cabinet impulse responses, with boutique builders in the United States and Mexico maintaining hand-wired production for premium tier positioning.
- Public Address Systems:Voice-priority paging amplifiers and emergency notification systems require EN 54-16 certification in European markets and UL 1711 listing in North American installations.
Professional audio commands the highest revenue concentration; home theater represents the steepest expansion trajectory in unit volume.
Connectivity:
Volume concentration in wireless protocols is displacing wired infrastructure in portable and residential applications, though latency-critical professional environments retain copper and fiber connectivity.
- Wireless:Wi-Fi 6E and proprietary low-latency radio protocols enable multi-room synchronization and outdoor event deployment without cable infrastructure. Smart speaker OEMs in China are standardizing on mesh networking stacks that reduce installation labor costs.
- Wired:XLR, TRS, and Speakon connectors dominate studio and stage environments where interference immunity and phantom power distribution are non-negotiable. Post-production facilities in Los Angeles and London maintain extensive analog snake infrastructure.
- Bluetooth:AAC and aptX codec support enables consumer device pairing, though 200-300 millisecond latency excludes professional monitoring applications.
- USB:Audio class 2.0 and Thunderbolt interfaces serve desktop audio production and podcasting workflows with direct digital audio workstation integration.
Wired connectivity retains professional dominance; wireless protocols are climbing the fastest in consumer shipment share.
End User:
Customer type determines margin structure, with music producers and audio engineers purchasing through specialized dealers that bundle technical support while home users transact through mass retail with minimal post-sale engagement.
- Music Producers:Recording studio owner-operators and commercial facility engineers prioritize converter transparency and monitor controller integration. Mastering engineers in Nashville and Berlin specify amplifiers with sub-0.001 percent THD+N for critical listening environments.
- Event Organizers:Corporate meeting planners, wedding coordinators, and festival logistics providers rent amplifier systems rather than purchasing, shifting supplier relationships toward fleet-management platforms and national rental house networks.
- Audio Engineers:Live sound reinforcement professionals and broadcast technicians specify amplifiers with Dante networking and redundant power supplies for touring and fixed-install reliability.
- Home Users:Residential consumers select amplifiers based on streaming service integration and voice assistant compatibility, with price sensitivity highest in this segment.
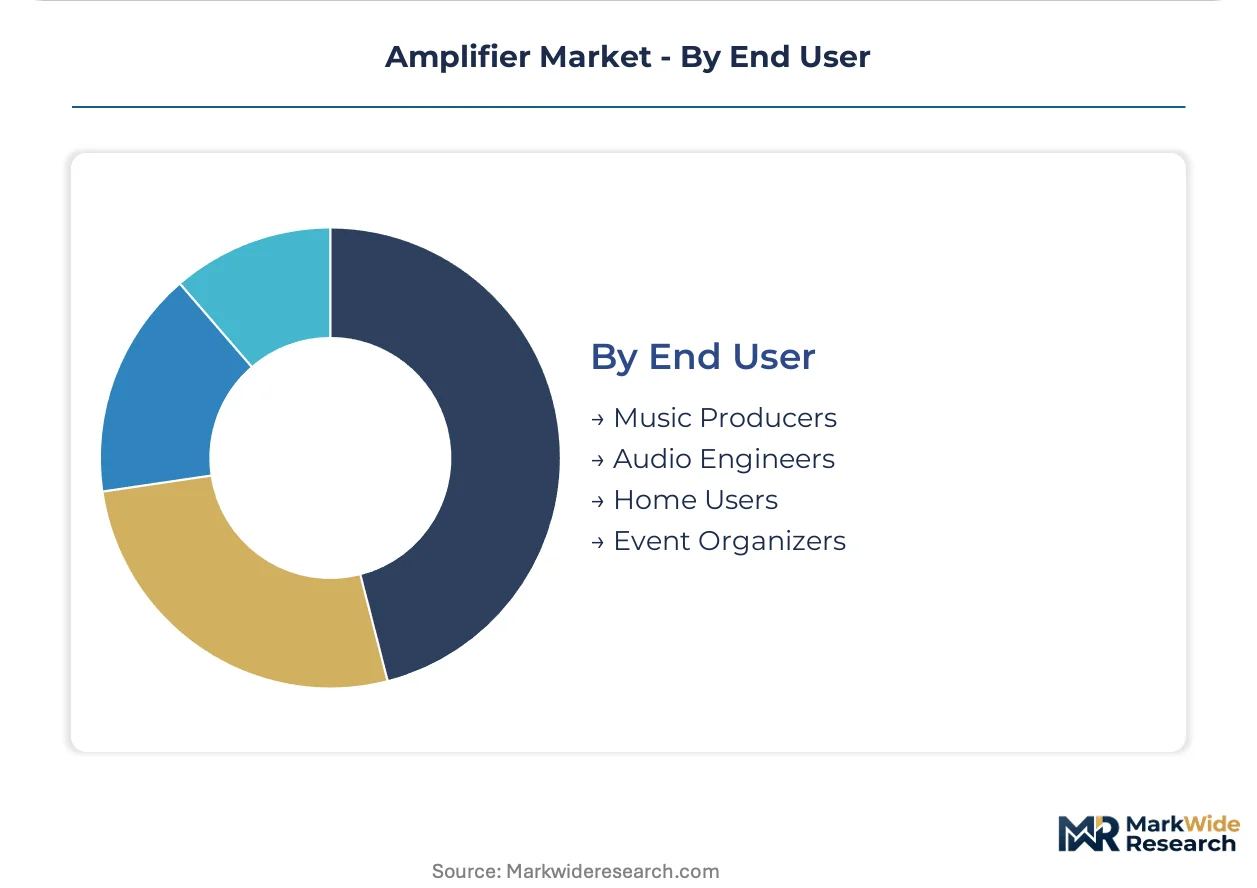
Music producers represent the most concentrated revenue pool; event organizers are expanding most quickly as rental models displace ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Professional audio buyers in Germany absorb substantial premiums for touring-grade reliability, while consumer electronics procurement in China operates on razor-thin margins where Class D silicon costs dominate sourcing decisions.
United States
Live event infrastructure and broadcast studio retrofits sustain demand for high-channel-count amplification. The FCC governs electromagnetic emissions through Part 15 rules, extending product qualification timelines. Nashville and Los Angeles anchor professional audio clusters where mastering engineers specify sub-0.001 percent THD+N for critical listening environments.
Germany
Music production studios and industrial automation drive precision amplifier procurement. The EU Ecodesign Directive mandates standby power limits below 0.5 watts, accelerating migration to digital topologies. Berlin and Hamburg host broadcast facility clusters standardizing on networked digital backbones with subscription-based DSP monetization.
China
Electric vehicle cabin acoustics and smart speaker manufacturing pull multi-channel Class D modules into tier-1 supplier roadmaps. MIIT enforces GB standards on electromagnetic compatibility and safety certification. Shenzhen and Dongguan concentrate contract manufacturing for global consumer electronics brands, creating single-source vulnerability exposure.
Japan
Multi-channel AV receiver integration and semiconductor packaging expertise sustain premium positioning. METI oversees JIS standards alignment for domestic audio equipment. Tokyo and Osaka anchor consumer electronics OEM clusters integrating HDMI eARC and room-correction DSP into single-chip solutions.
India
Industrial automation and process control applications open procurement pathways for precision signal conditioning amplifiers. The PLI scheme and BIS certification alignment incentivize domestic assembly. Bengaluru and Pune concentrate robotics and automation system integrators sourcing amplifiers for manufacturing deployment.
Amplifier Market Vendor Landscape
Capability concentration sits with semiconductor specialists commanding GaN and SiC power stage expertise; scale advantage sits with diversified analog portfolio vendors anchoring long-term supply agreements. The structure splits between integrated device manufacturers with captive fabrication and fabless designers relying on foundry partnerships. Three archetypes dominate: broad-line analog suppliers, wide-bandgap semiconductor specialists, and integrated Class D solution providers. Competitive moves center on silicon carbide substrate qualification for automotive qualification and firmware subscription platforms detaching revenue from hardware cycles.
Among diversified analog portfolio vendors, Texas Instruments exemplifies the scale-driven archetype through supply agreement anchoring. Infineon Technologies and STMicroelectronics occupy positions within the wide-bandgap and integrated solution tiers respectively, representing strategic bets on thermal efficiency and bill-of-materials reduction for OEM customers.
| Leading Market Players |
|---|
| Texas Instruments |
| Infineon Technologies |
| STMicroelectronics |
| NXP Semiconductors |
| Analog Devices |
| QUALCOMM Incorporated |
| Yamaha Corporation |
| Sony Corporation |
| Broadcom |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Shenzhen and Dongguan contract manufacturing clusters compresses margin flexibility at the economy tier while amplifying premium-tier pricing power for vendors with captive fabrication. This geographic concentration simultaneously widens price spreads between mass-market Class D modules and touring-grade professional systems, and forces global brands to absorb extended payment terms or advance inventory commitments to secure allocation.
Pricing Analysis
Firmware subscription revenue and DSP profile licensing now capture lifetime value exceeding the original hardware transaction across networked digital amplifier platforms. Three-tier pricing structure across premium, standard, and economy levels separates touring-certified rack systems with redundant cooling from consumer AV receivers and entry-level portable PA units. Cost compression in the consumer tier intensifies because Chinese domestic OEMs are scaling multi-channel Class D output for electric vehicle and smart speaker programs. Event organizers and rental house networks exhibit the highest price sensitivity, while mastering engineers in Nashville and Berlin absorb substantial premiums for sub-0.001 percent THD+N specifications.
Supply Chain Analysis
Extended payment terms from 60 to 90 days have become standard for tier-1 automotive suppliers sourcing GaN HEMT power stages, with supply-chain finance facilities increasingly intermediating working capital between foundries and amplifier module integrators. Manufacturing gravity centers on China, Taiwan, and South Korea for silicon carbide substrate processing, gallium nitride epitaxy, and Class D controller IC fabrication. Raw material dependencies include high-purity silicon wafers, rare-earth magnetic materials for output inductors, and halogen-free PCB laminates compliant with REACH substance restrictions. Single-source vulnerability for GaN-on-SiC devices creates exposure should export controls tighten. Distribution runs through national rental house networks in North America, specialized AV integrators in Europe, and direct OEM relationships in automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dante network protocol adoption and cloud-connected amplifier fleets are collapsing hardware-software boundaries, creating platform-economics dynamics where DSP subscription retention matters more than unit replacement cycles.
For Market Incumbents: Insulate professional audio margins by deepening captive supply of GaN power stages and locking touring-grade reliability certifications ahead of REACH substance restriction deadlines. Defensive consolidation through acquisition of DSP software specialists will counter emerging entrants bundling firmware-as-a-service with commodity Class D hardware. Channel control via exclusive rental house partnerships protects pricing power against direct-to-event-organizer disintermediation. For New Entrants and Emerging Players: India's industrial automation segment offers underpenetrated white-space for precision signal conditioning amplifiers as PLI scheme incentives and BIS certification alignment lower market entry barriers. Secondary opportunities exist in 5G small cell RF power amplifier deployment where envelope tracking expertise remains scarce. A go-to-market angle anchored to firmware-over-the-air capabilities differentiates against legacy analog incumbents in process control and robotics applications. For Investors and Strategic Acquirers: The market sits at a substitution phase that favors wide-bandgap semiconductor specialists with automotive qualification pathways over diversified analog portfolio vendors. Long-term viability over the next decade hinges on silicon carbide substrate access and Class D integration expertise rather than discrete component scale. Acquisition targets should exhibit captive GaN fabrication or foundry partnerships with tier-1 automotive supplier traction. The signal to monitor is automotive OEM platform standardization toward 48-volt electrical architectures, which would accelerate Class D module penetration and compress qualification timelines for new entrants.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Power Stage Integration | Automotive tier-1 suppliers adopting GaN HEMT devices compress magnetics volume for 48-volt systems. |
| Firmware-as-a-Service Platform | DSP profile subscriptions detach revenue from hardware replacement cycles in broadcast and studio segments. |
| REACH Compliance Repositioning | Halogen-free laminate qualification ahead of substance restrictions protects European market access. |
| Rental House Network Consolidation | Fleet-management platform partnerships shift supplier relationships toward operating budget capture. |
| India Manufacturing Localization | PLI scheme incentives and BIS alignment open procurement pathways for industrial automation amplifiers. |
Methodological Framework
Cross-validation between primary interviews with amplifier OEM procurement directors, semiconductor foundry account managers, live event production company technical directors, and automotive tier-1 supplier engineers anchors the qualitative findings against secondary validation from FCC Part 15 filings, MIIT GB standard publications, EU Ecodesign Directive compliance databases, and SEC 10-K disclosures from diversified analog portfolio vendors. Bottom-up triangulation of unit shipment estimates by product architecture and application segment converges with top-down value analysis across regional consumption patterns.
Calibration against historical adoption curves for Class D and digital amplifier penetration in automotive and professional audio segments shapes the projection framework across the analysis window. Segmentation dimensions modeled include amplifier topology, application vertical, connectivity protocol, and end-user archetype, with regional regulatory cluster effects incorporated for EU Ecodesign, FCC emissions, and MIIT certification pathways. CAGRs derive from fitted S-curve adoption patterns for GaN power stage integration and firmware monetization attach rates.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by fabless designers into captive GaN fabrication would shift outcomes. Macroeconomic contraction in live event spending, regulatory acceleration of standby power limits, or breakthroughs in alternative wide-bandgap materials would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Stretchable and Conformal Electronics Market
Electronic Components
Motherboard Battery Market
Electronic Components
Multilayer Transparent Conductors Market
Electronic Components
Discrete Capacitors Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
Acoustic Diaphragm Market
Electronic Components
Coin Battery Holder Market
Electronic Components
High Density Interconnect (HDI) PCB Market
Electronic Components
Screw Washer Market
Electronic Components
TWS and Noise-Cancelling Headphone with MEMS Chip Market
Electronic Components
Hydrogen Thyratron Market
Electronic Components
Pneumatic Components Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Capacitor Kits Market
Electronic Components
RAID Controller Card Market