
 Europe Small Signal Transistor Market | 2026-2036
Europe Small Signal Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Small Signal Transistor Market Insights
Multi-sourced wafer procurement is consolidating as fabs tighten vendor qualification lists. Infineon Technologies AG anchors German automotive-grade transistor supply through captive fab capacity. Nexperia leverages its discrete semiconductor heritage to dominate low-voltage switching portfolios. STMicroelectronics sustains broad European industrial exposure through diversified foundry partnerships.
Small signal transistors are low-power semiconductor devices engineered for current or voltage manipulation below one watt, typically fabricated on silicon or silicon-germanium substrates using epitaxial growth and ion implantation processes. These components serve precision amplification, switching, and signal conditioning roles across analog and mixed-signal circuits. Bipolar junction transistors retain structural importance in linear amplification where low noise figures matter, while field effect transistors capture share in high-impedance switching applications. Automotive electronics end-use is expanding fastest as 48V mild-hybrid architectures multiply discrete component counts per vehicle.
RoHS and REACH frameworks restrict hazardous substances in semiconductor packaging materials, compelling reformulation of lead-free solders and molding compounds. CE marking under the EU's Radio Equipment Directive governs electromagnetic compatibility for transistors deployed in wireless telecommunications infrastructure. The EU Chips Act is channeling public capital into European wafer fabrication, reshaping local supply security calculations. Stakeholders must weigh qualification timelines against the accelerating pace of automotive electrification platform decisions.
Market Dynamics
Automotive electrification platforms are compressing qualification timelines for European transistor suppliers as 48V mild-hybrid architectures multiply discrete component counts per vehicle. Tier-1 module makers now demand concurrent engineering partnerships that collapse traditional 18-month validation cycles.
Growth Catalysts
- EU Chips Act capital deployment:Public wafer fabrication subsidies are reshoring front-end capacity across Germany and the Netherlands, reducing import dependency for automotive-grade substrates.
- 48V mild-hybrid proliferation:European OEM powertrain strategies are expanding small signal transistor content per vehicle for battery management and DC-DC conversion functions.
- REACH material purity mandates:Elevated substrate standards are filtering out marginal Asian suppliers, consolidating procurement toward qualified European vendors.
Market Restraints
- Epitaxial wafer supply concentration:German and Dutch substrate specialists control 80% of European automotive-qualified silicon supply, creating single-source vulnerability.
- Rare earth processing dependency:Gallium and germanium refining capacity remains concentrated outside Europe, exposing cost volatility for silicon-germanium heterojunction devices.
- Ion implantation equipment lead times:Tooling delivery from Applied Materials and Axcelis now exceeds 14 months, constraining foundry expansion velocity.
Strategic Opportunities
- Polish packaging corridor development:Lower-cost OSAT capacity near Wrocław offers European proximity without Dutch or German labor cost structures.
- Medical device connectivity:Wearable diagnostic platforms are adopting ultra-low-noise bipolar junction transistors for bio-signal amplification.
- CE marking under RED:The Radio Equipment Directive's electromagnetic compatibility requirements are creating certified-product premiums in wireless infrastructure procurement.
Industry Challenges
- Automotive AEC-Q101 qualification backlog:Test house capacity at imec and SGS is fully booked through Q3, delaying new product introductions.
- Mixed-signal design talent scarcity:Analog circuit expertise is retiring faster than university programs in Dresden and Leuven can replenish.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Small Signal Transistor Market |
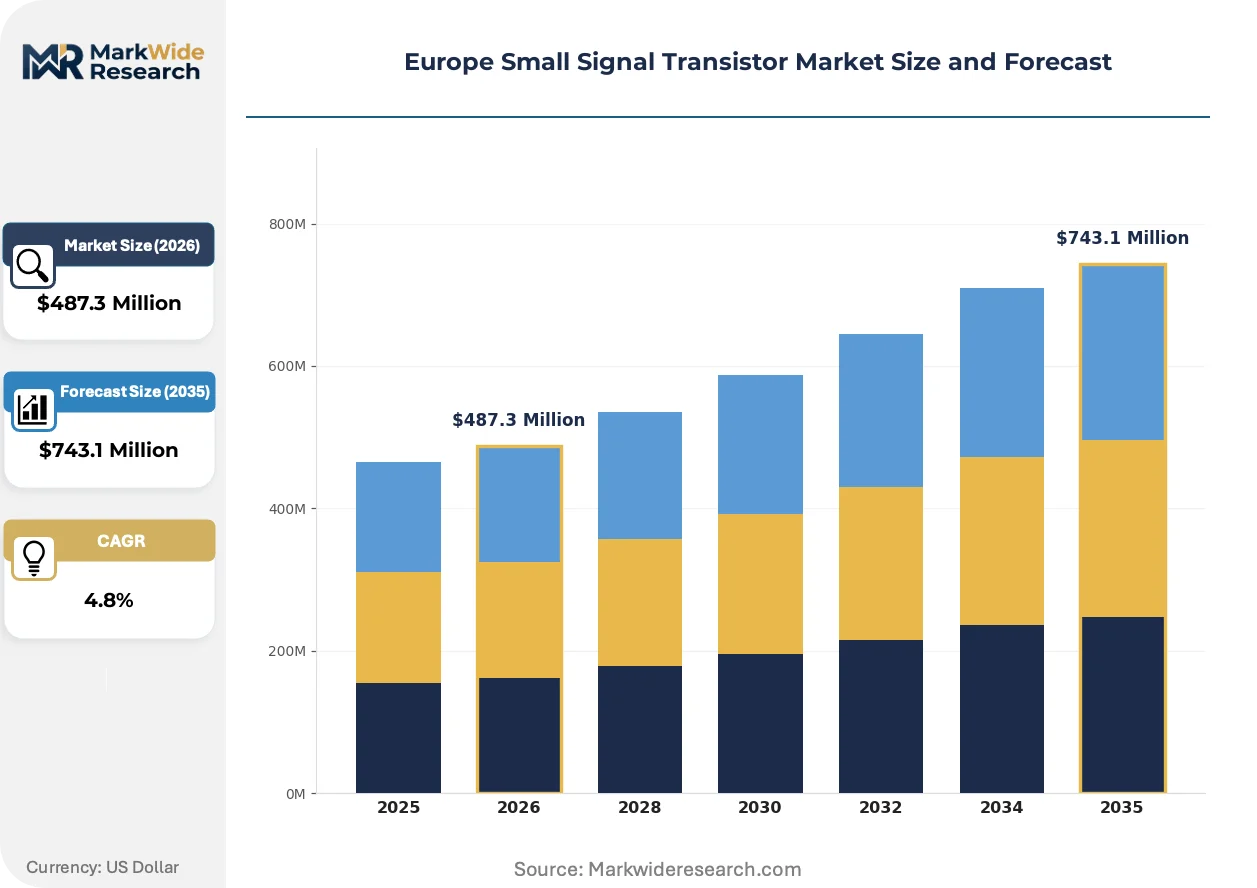
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bipolar Junction Transistor, Field Effect Transistor, Darlington Transistor, Phototransistor End User: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Equipment Technology: Bipolar Technology, CMOS Technology, BiCMOS Technology, Hybrid Technology Application: Signal Processing, Amplification, Switching, Voltage Regulation |
| Companies Covered | Microchip Technology, Renesas Electronics Corporation, Infineon Technologies AG, Diodes Inc, onsemi, NXP Semiconductors, Nexperia, Vishay Intertechnology, STMicroelectronics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Small Signal Transistor Market Trends and Innovations
Process integration and packaging evolution are collapsing the traditional boundaries between discrete and integrated solutions. European foundries are now positioning small signal transistors as building blocks for system-in-package modules rather than standalone components.
Silicon-germanium heterojunction bipolar transistor technology is unifying high-frequency performance with low-noise characteristics previously requiring separate device architectures. Automotive radar module suppliers in Stuttgart and Munich are adopting SiGe BiCMOS processes at accelerated cadences. This convergence is compressing the addressable market for pure-play small signal discretes in RF front-end applications.
RoHS substance restrictions are compelling reformulation of lead-free solder alloys and epoxy molding compounds across European packaging houses. ECHA's persistent organic pollutant screening is eliminating legacy flame retardants from substrate materials. Medical and industrial equipment manufacturers in Switzerland and Denmark are now demanding full material disclosure documentation upstream to component suppliers.
Consolidated procurement frameworks are displacing spot-market purchasing among German automotive tier-1s. Continental and Bosch have established multi-year transistor supply agreements with volume commitments and price corridors. This behavioral shift is most visible in Baden-Württemberg, where module makers are ceding supplier diversification in exchange for allocation security during semiconductor shortages.
Europe Small Signal Transistor Market Segmentation
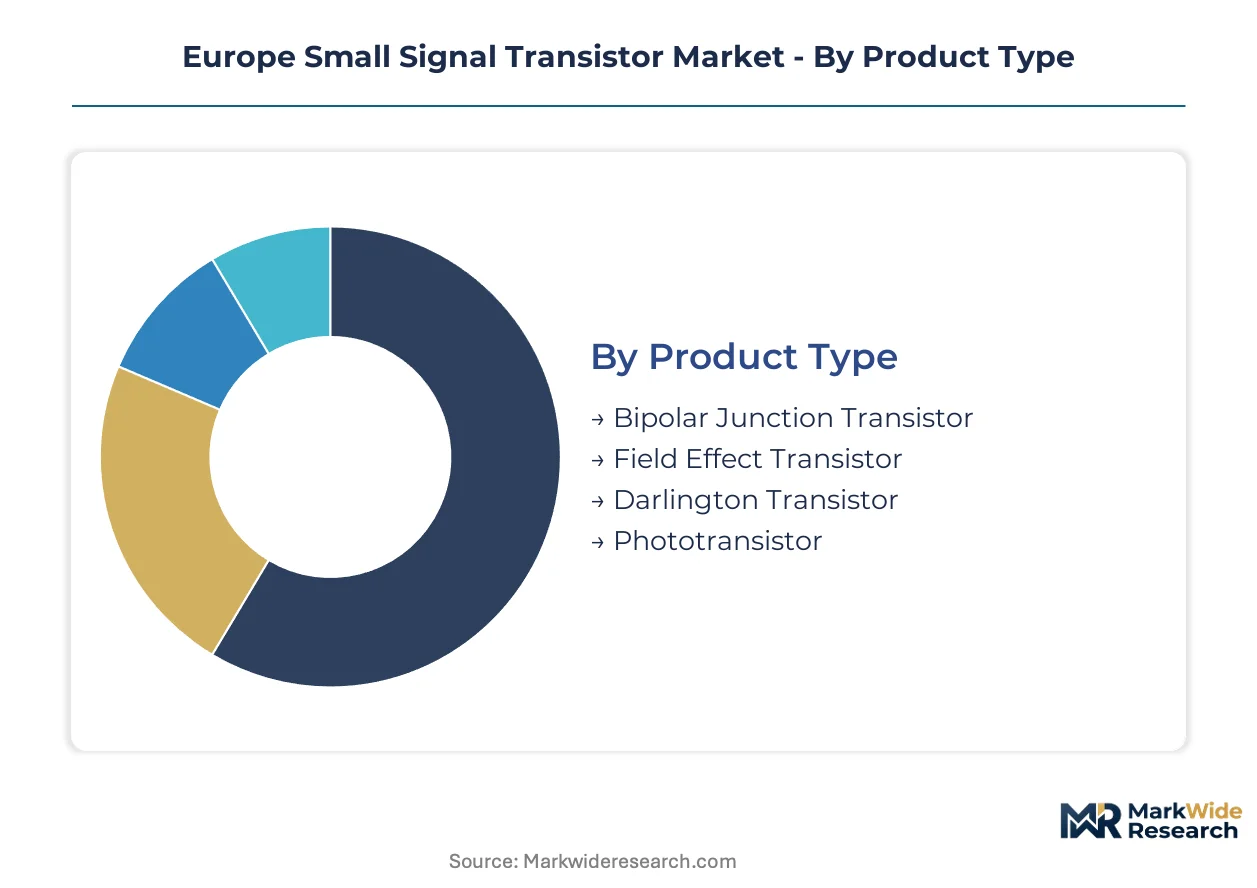
European procurement managers evaluate small signal transistors through four intersecting lenses: device physics, system integration demands, manufacturing process maturity, and circuit function requirements. Each segmentation axis carries distinct qualification protocols and margin structures that reshape supplier competitive positioning.
Product Type:
Buyer specifications pivot on noise performance thresholds and switching speed requirements, with device architecture determining foundry process selection.
- Bipolar Junction Transistor:Silicon-based vertical structures deliver sub-nanovolt noise floors essential for sensor front-ends. German automotive tier-1s in Baden-Württemberg specify BJTs for battery management system precision voltage sensing. REACH-compliant substrate sourcing from Dutch wafer specialists anchors supply security.
- Field Effect Transistor:Voltage-controlled channels achieve gigaohm input impedances for high-impedance instrumentation. Netherlands semiconductor packaging clusters process FET die for industrial automation modules. Gate oxide reliability under automotive temperature cycling drives AEC-Q101 test protocols.
- Darlington Transistor:Cascaded beta multiplication suits relay driver applications with minimal base current.
- Phototransistor:Optically activated base regions enable galvanic isolation in medical diagnostic equipment.
Volume sits with Bipolar Junction Transistor; growth tilts toward Field Effect Transistor.
End User:
Application sector selection determines margin tier and qualification burden, with automotive procurement imposing the most stringent traceability mandates.
- Automotive Electronics:48V mild-hybrid architectures multiply discrete counts per powertrain module. Stuttgart and Munich OEMs demand PPAP documentation and zero-defect ppm targets. CE marking under automotive EMC directives extends validation timelines.
- Industrial Equipment:Extended temperature ratings and hermetic packaging address factory automation longevity requirements. German industrial corridor customers specify 20-year operational lifespans for programmable logic controller interfaces.
- Consumer Electronics:Cost-optimized plastic packages dominate smartphone and wearable production.
- Telecommunications:Low-noise amplification for 5G small cell infrastructure drives RF-specific device selection.
Automotive Electronics commands dominant procurement volumes; Consumer Electronics exhibits the steepest expansion trajectory.
Technology:
Process node availability and IP licensing economics determine technology adoption curves across European foundries.
- BiCMOS Technology:Unified bipolar and CMOS integration enables single-chip mixed-signal solutions. SiGe heterojunction variants from German foundries serve automotive radar modules at 77 GHz. Process complexity limits qualified European suppliers to Dresden and Leuven facilities.
- CMOS Technology:Digital-compatible scaling supports system-on-chip integration for consumer applications. Dutch foundry partnerships leverage ASML lithography for advanced geometry migration.
- Bipolar Technology:Mature linear performance dominates precision analog where CMOS noise floors prove inadequate.
- Hybrid Technology:Multi-die stacking addresses specialized military and aerospace requirements.
BiCMOS Technology captures premium pricing; CMOS Technology scales highest in unit shipments.
Application:
Circuit function dictates electrical parameter prioritization, with switching applications emphasizing speed and amplification prioritizing linearity.
- Signal Processing:Matched transistor pairs achieve differential amplifier balance for audio and instrumentation. Swiss medical device manufacturers specify thermal tracking within microvolts for electrocardiography front-ends. Matched pair availability filters supplier selection toward European vendors with in-house die sorting.
- Amplification:Gain-bandwidth product and noise figure define competitive differentiation. Low-noise bipolar devices from Nexperia's Manchester heritage address RF preamplification in Netherlands telecom infrastructure.
- Switching:Saturation voltage and storage time determine power efficiency in digital interfaces.
- Voltage Regulation:Reference precision and temperature coefficient stability anchor power management subsystem performance.
Signal Processing maintains established revenue concentration; Amplification gains share fastest in emerging medical connectivity platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European demand for small signal transistors clusters in Germany's automotive manufacturing belt and the Netherlands' semiconductor packaging corridor. These two geographies absorb the majority of procurement volumes for automotive-grade and industrial-grade devices.
Germany
Stuttgart OEMs and Munich powertrain suppliers drive qualification-intensive procurement for 48V mild-hybrid battery management systems. REACH substrate mandates from ECHA filter supplier pools toward Dutch wafer specialists with certified material traceability. Baden-Württemberg's industrial corridor concentrates module manufacturing for Continental and Bosch supply chains.
Netherlands
Eindhoven's semiconductor packaging clusters process FET die for industrial automation customers across Northern Europe. CE marking under the Radio Equipment Directive governs electromagnetic compatibility for transistors deployed in wireless telecommunications infrastructure. Dutch foundry partnerships leverage ASML lithography for advanced geometry migration in mixed-signal BiCMOS processes.
France
Île-de-France hosts aerospace and defense contractors specifying hermetic packaging for extended operational lifespans. The EU Green Deal's carbon border adjustments elevate lifecycle documentation requirements for imported substrate materials. Toulouse's satellite manufacturing base demands radiation-hardened small signal devices for space-qualified instrumentation.
Italy
Lombardy's industrial automation sector sources precision amplification components for programmable logic controller interfaces. RoHS substance restrictions compel reformulation of lead-free solder alloys across Italian packaging subcontractors. Emilia-Romagna's machine tool builders specify 20-year operational lifespans for factory floor electronics.
Poland
Wrocław's emerging OSAT corridor offers European proximity packaging without Dutch or German labor cost structures. EU Chips Act capital deployment targets lower-cost eastern European capacity for back-end assembly functions. Polish packaging houses serve German automotive tier-1s seeking geographic diversification of supply risk.
Europe Small Signal Transistor Market Competitive Landscape
Capacity expansion dominates the current landscape as foundries respond to compressed automotive qualification timelines. The vendor base organizes around three tiers: integrated device manufacturers with captive fabrication, fabless specialists leveraging foundry partnerships, and diversified conglomerates with broad semiconductor portfolios. Two competitive vectors define positioning: multi-year supply agreements with volume commitments, and concurrent engineering partnerships that collapse traditional validation cycles.
Among European-anchored integrated device manufacturers, Infineon Technologies AG, Nexperia, and STMicroelectronics occupy distinct archetype positions. Infineon exemplifies the captive-capability model with German automotive-grade substrate supply. Nexperia represents discrete semiconductor heritage specialists dominating low-voltage switching portfolios. STMicroelectronics sits within the diversified foundry-partnership tier sustaining broad European industrial exposure. These three entities anchor procurement consolidation as tier-1 module makers cede supplier diversification in exchange for allocation security.
| Leading Market Players |
|---|
| Microchip Technology |
| Renesas Electronics Corporation |
| Infineon Technologies AG |
| Diodes Inc |
| onsemi |
| NXP Semiconductors |
| Nexperia |
| Vishay Intertechnology |
| STMicroelectronics |
| Others |
Pricing and Supply Chain Analysis
Automotive tier-1 consolidation around multi-year supply agreements is compressing spot-market liquidity and forcing foundries toward contract-based pricing with volume corridors. Continental and Bosch procurement frameworks now prioritize allocation security over supplier diversification, reshaping how European packaging houses negotiate die supply and wafer commitments.
Pricing Analysis
High-volume automotive contracts trade margin for allocation guarantees, while specialty medical and industrial orders retain premium pricing. Three-tier pricing structure across AEC-Q101 certified, industrial-grade, and consumer-grade devices separates qualified automotive supply from standard commercial offerings. Cost compression in consumer-grade plastic packages intensifies as Asian competitors expand European distribution. Price sensitivity concentrates in smartphone and wearable OEMs, whereas German automotive module makers accept sustained premiums for zero-defect ppm performance and full material traceability.
Supply Chain Analysis
Dual-sourcing mandates from Stuttgart OEMs require German tier-1s to qualify at least two substrate vendors, yet Dutch and German wafer specialists control the majority of REACH-compliant automotive-grade silicon supply. Raw material dependencies center on high-purity silicon feedstock, gallium for heterojunction devices, and specialized epoxy molding compounds reformulated for RoHS compliance. Single-source vulnerability in epitaxial wafer supply exposes procurement chains to allocation constraints during capacity crunches. Distribution runs through authorized distributors serving industrial automation customers and direct contracts anchoring automotive module supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European small signal transistor procurement is consolidating around qualified vendors with captive fabrication and AEC-Q101 certification depth, squeezing marginal players lacking automotive validation infrastructure.
For Market Incumbents: Deploy concurrent engineering partnerships to collapse 18-month validation cycles before emerging Polish OSAT capacity matures. Infineon and Nexperia anchor positions through German captive fab supply; challengers must secure imec test house slots and ECHA material certification to defend against tier-1 procurement consolidation. Capacity addition in Dresden or Leuven facilities strengthens substrate security against Dutch wafer specialist bottlenecks. For New Entrants and Emerging Players: Capture Polish packaging corridor development near Wrocław before EU Chips Act capital fully deploys across established Dutch and German clusters. Medical device connectivity in Switzerland and Denmark offers the most penetrable white-space, with ultra-low-noise bipolar junction transistor demand outpacing qualified European supply. Go-to-market positioning should emphasize full material disclosure documentation and REACH substrate traceability that incumbent Asian vendors struggle to match. For Investors and Strategic Acquirers: The window for entry favors mid-cap discrete specialists with existing AEC-Q101 qualification and ECHA-certified material streams. Long-term viability hinges on automotive electrification platform decisions locking in component counts per vehicle. Watch for AEC-Q101 test house capacity releases at imec and SGS as the inflection signal for new product introduction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Concurrent Engineering Partnership | Collapses validation timelines for 48V mild-hybrid battery management system qualification. |
| Polish OSAT Capacity Expansion | Captures lower-cost European proximity without Dutch or German labor cost structures. |
| SiGe BiCMOS Process Migration | Unifies high-frequency performance for Stuttgart automotive radar module suppliers. |
| REACH Material Certification Investment | Filters supplier pools toward ECHA-compliant vendors as substrate mandates tighten. |
| Multi-Year Supply Agreement Structuring | Locks allocation security with Continental and Bosch procurement frameworks. |
Research Methodology
Document review covered ECHA REACH substance restrictions, EU Chips Act capital deployment filings, and AEC-Q101 test protocol documentation, complemented by interviews with tier-1 automotive procurement managers, Dutch semiconductor packaging cluster engineers, and German foundry process integration leads. Secondary validation drew from SEC 10-K filings of listed semiconductor vendors, European customs trade data for discrete component flows, and vehicle production databases tracking 48V mild-hybrid platform rollouts. Bottom-up die shipment estimates triangulated against top-down automotive electronics content-per-vehicle models.
Segmented outputs across device physics, end-use sector, manufacturing process, and circuit function dimensions were generated through the projection horizon. CAGRs were derived from regression analysis against automotive electrification adoption curves and industrial automation capital expenditure patterns. Industry-specific inputs included AEC-Q101 qualification backlog data from imec and SGS, and ECHA persistent organic pollutant screening timelines affecting molding compound reformulation.
The model holds under sustained EU Chips Act capital deployment and REACH enforcement continuity; deviation in automotive platform electrification timing or ECHA substance restriction acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Global RF Power Semiconductor Market
RF Components
GPS Low Noise Amplifier Market
RF Components
Silicon Tuners Market
RF Components
SMD Resonator Market
RF Components
RF Spectrum Analyzer Market
RF Components
RF Semiconductor Market
RF Components
RF Power Detector Market
RF Components
RF Power Amplifiers Market
RF Components
Coaxial Connectors (RF) Market
RF Components
Digital Radio Frequency Market
RF Components
Latin America RFID Tags Market
RF Components
RF Mixers Market
RF Components
Global RF Plasma Generator Market
RF Components
UHF RFID Inlays Market
RF Components
Power Amplifier Market
RF Components
High-Volume RF Front-End Module Test Systems Market