
 Global RF Transceiver Market | 2026-2036
Global RF Transceiver Market Size, Share, and Industry Trends Forecast 2026-2036
Global RF Transceiver Market Outlook
Direct procurement relationships between semiconductor foundries and Tier 1 baseband vendors is reshaping how RF transceivers reach end equipment. Qorvo Inc. leverages captive gallium nitride fabrication to sustain pricing power in defense and satellite applications. Qualcomm Incorporated anchors smartphone RF front-end integration through its modem-to-antenna design philosophy. Broadcom Inc. dominates data center optical interconnect transceivers with silicon photonics manufacturing scale.
An RF transceiver integrates transmitter and receiver circuitry onto a single die or package, converting between baseband digital signals and modulated radio frequencies from 600 MHz to 100 GHz using heterodyne or direct-conversion architectures. These devices enable bidirectional wireless communication in cellular infrastructure, radar systems, and software-defined radios. The integrated circuits segment leads in revenue contribution due to die-level integration trends in 5G massive MIMO arrays, while software-defined transceivers are gaining fastest in aerospace and electronic warfare platforms requiring frequency agility. Mixed-signal designs occupy the highest margin pools by combining data converters with RF synthesizers for instrumentation and test equipment.
The FCC enforces Part 15 and Part 27 emissions rules that constrain spurious output levels and dictate certification costs for transceiver vendors targeting US infrastructure. ETSI harmonized standards under the EU Radio Equipment Directive mandate interoperability testing for cellular and satellite terminals entering European markets. The IEC publishes RF connector and measurement standards that govern how transceivers interface with antenna systems across jurisdictions. Stakeholders must monitor spectrum reallocation proceedings in major economies, as mid-band and mmWave assignments directly determine which frequency ranges command design investment and which legacy architectures face obsolescence.
Market Dynamics
Direct foundry-to-OEM procurement relationships are compressing traditional distribution layers in RF transceiver supply chains, concentrating volume commitments among vertically integrated baseband vendors who now negotiate wafer starts directly with Taiwan Semiconductor Manufacturing and Samsung Foundry.
Growth Catalysts
- 5G Massive MIMO Deployment:Telecommunications operators in China are procuring high-density transceiver arrays for macro base stations, consuming die-level integrated modules at unprecedented scale.
- EU Radio Equipment Directive Harmonization:ETSI interoperability mandates are standardizing cellular terminal certification across European markets, reducing fragmentation costs for transceiver vendors.
- Gallium Nitride Process Maturation:Defense and satellite manufacturers are specifying GaN-on-SiC transceivers for radar applications, leveraging superior power density and thermal performance.
Market Restraints
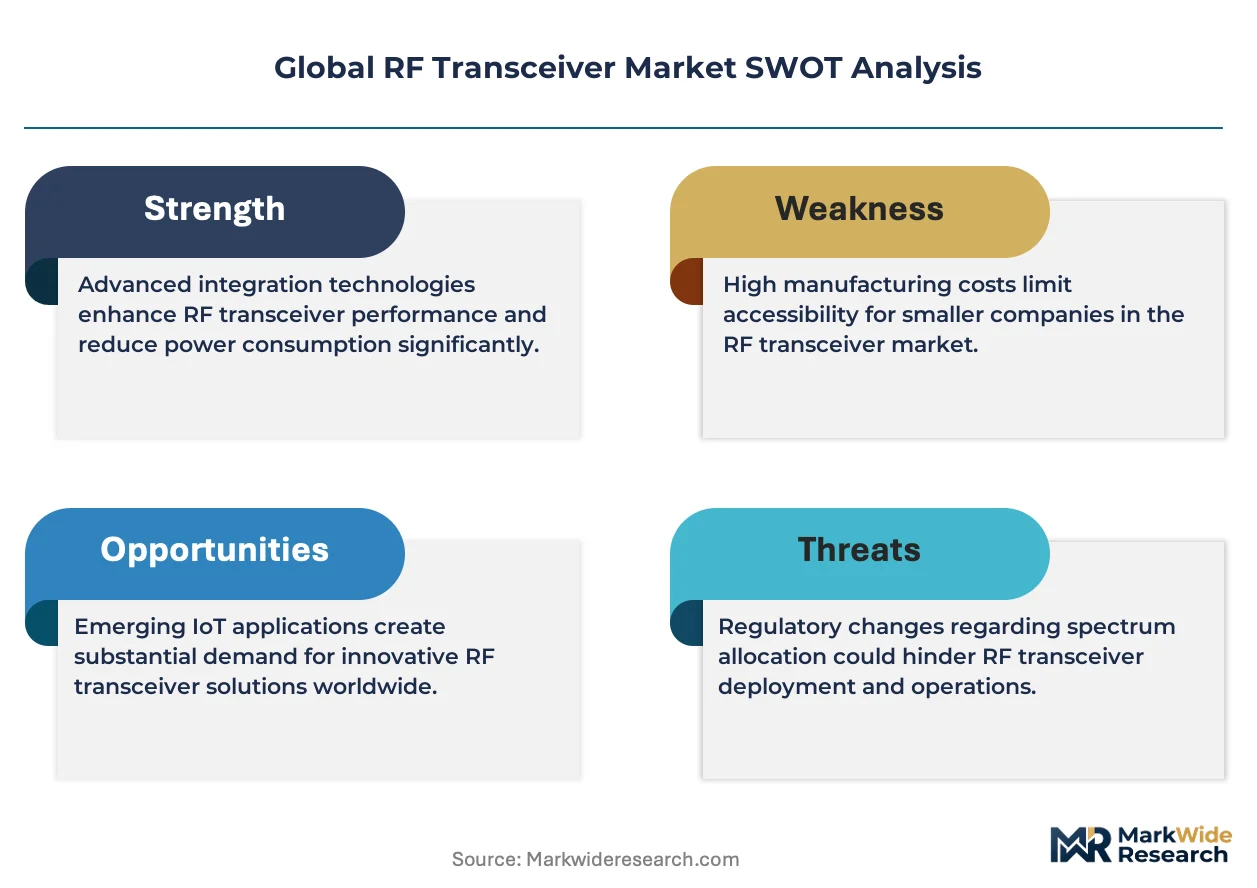
- Advanced Node Wafer Scarcity:7nm and 5nm RF-CMOS capacity at leading foundries remains constrained, extending lead times for smartphone modem integration programs.
- Mid-Band Spectrum Reallocation Uncertainty:FCC proceedings on C-band and 3.45 GHz assignments are freezing design investment for legacy architectures facing potential obsolescence.
- Silicon Photonics Substitution:Data center interconnect demand is migrating from discrete RF transceivers to co-packaged optical engines, eroding merchant silicon market share.
Strategic Opportunities
- India Telecom Infrastructure Buildout:Reliance Jio and Bharti Airtel are accelerating 5G small-cell deployments, creating demand for cost-optimized transceiver modules with domestic assembly requirements.
- Software-Defined Radio Convergence:Aerospace platforms are integrating FPGA-programmable transceivers with AI-driven spectrum sensing, enabling frequency-agile electronic warfare systems.
- US CHIPS Act Incentives:Department of Commerce funding is attracting RF front-end packaging investments to Arizona and Texas, reshaping North American supply geography.
Industry Challenges
- Millimeter-Wave Test Engineering Shortage:Verification of 28 GHz and 39 GHz transceiver performance requires specialized anechoic chamber expertise that remains scarce across contract manufacturers.
- Multi-Jurisdiction Certification Complexity:Simultaneous FCC Part 15, ETSI EN 301 908, and MIIT SRRC approvals are extending time-to-revenue for new cellular transceiver designs by 8-14 months.
- Legacy Baseband Interface Migration:Infrastructure OEMs are struggling to integrate new transceiver generations with installed baseband units using obsolete JESD204B digital interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global RF Transceiver Market |
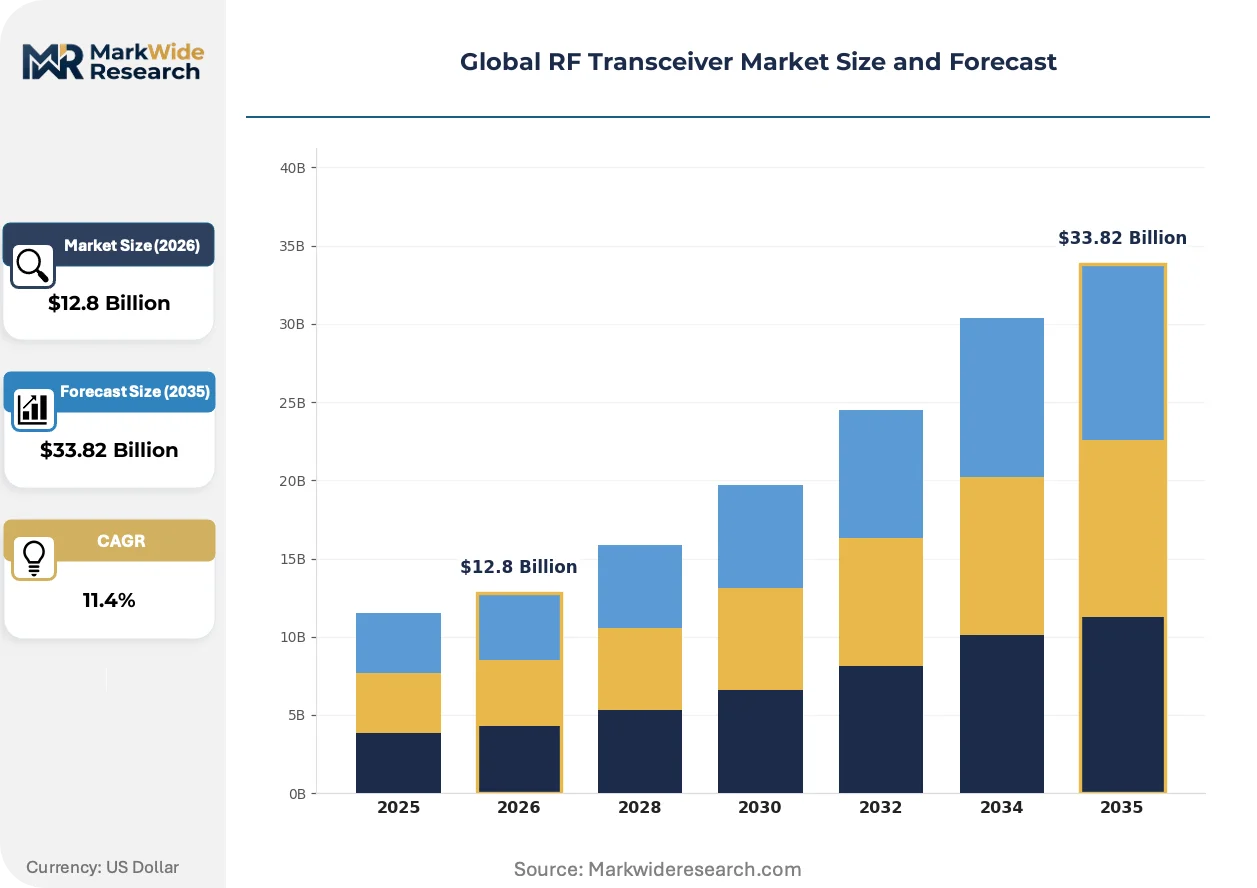
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Circuits, Modules, Chips, Components Technology: Analog, Digital, Mixed-Signal, Software-Defined Application: Telecommunications, Aerospace, Automotive, Consumer Electronics End User: Commercial, Industrial, Government, OEMs |
| Companies Covered | Qorvo Inc., Broadcom Inc., Qualcomm Incorporated, Texas Instruments Incorporated, Infineon Technologies AG, Analog Devices Inc., Skyworks Solutions Inc., STMicroelectronics, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global RF Transceiver Market Strategic Shifts
Digital signal processing integration is dissolving boundaries between hardware-defined RF chains and software-configurable front ends, enabling architectures that adapt to spectrum conditions without physical redesign.
Software-defined transceiver architectures are virtualizing traditional analog signal paths into digital-domain processing blocks. Defense primes including Raytheon and Northrop Grumman are adopting these platforms for electronic warfare suites requiring sub-microsecond frequency hopping. This virtualization is compressing hardware revision cycles from years to months while expanding addressable mission profiles per platform.
ETSI harmonized standards under the EU Radio Equipment Directive are mandating cybersecurity-by-design for cellular and satellite terminals entering European markets. Manufacturers must now embed secure boot and firmware attestation into transceiver baseband interfaces before CE marking approval. Module vendors serving automotive and industrial IoT segments are absorbing the steepest compliance cost increases.
Defense procurement officers are consolidating vendor lists and demanding long-term sustainment guarantees rather than transactional component purchases. Prime contractors are responding by awarding sole-source transceiver development contracts with 10-year availability commitments. This behavioral shift is most pronounced in US Department of Defense programs, where program offices now evaluate total lifecycle cost above unit acquisition price.
Global RF Transceiver Market Segmentation
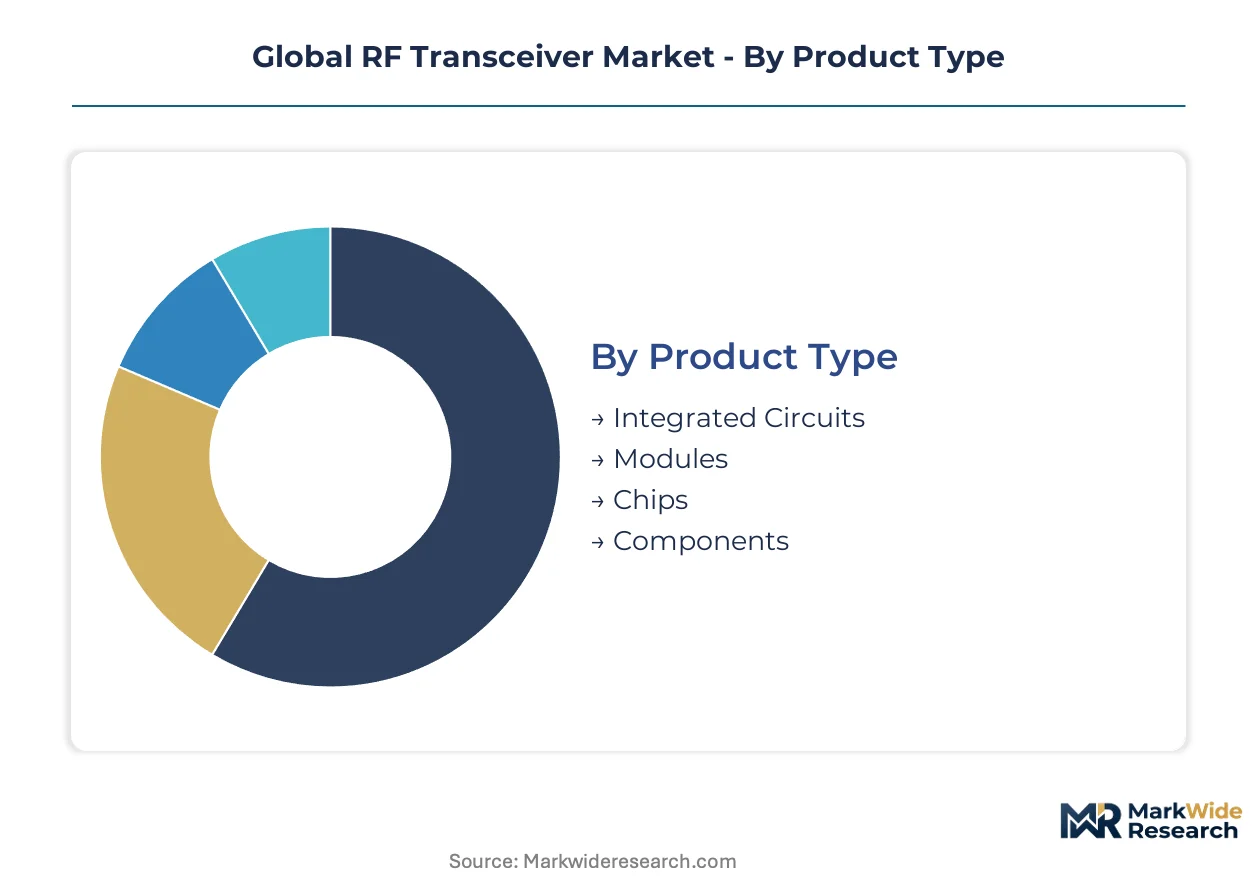
RF transceiver segmentation reveals how technical specifications, integration levels, and end-use requirements fragment procurement patterns across defense, telecommunications, and industrial verticals. Understanding these divides exposes where design investment concentrates and which interface standards command premium positioning.
Product Type:
After-sales service intensity varies sharply across integration levels, with discrete components requiring extensive field calibration support while fully integrated modules shift liability to foundry-level reliability guarantees.
- Integrated Circuits:Die-level transceiver integration combines power amplifiers, mixers, and synthesizers onto monolithic substrates for 5G massive MIMO arrays. China Mobile and China Telecom are consuming these at unprecedented scale for macro base station rollouts, prioritizing thermal efficiency and beamforming channel density over unit cost.
- Modules:Pre-certified transceiver subsystems package RF chains with antenna connectors and baseband interfaces, reducing OEM design cycles for small-cell deployments. India's Reliance Jio and Bharti Airtel favor these for accelerated 5G infrastructure timelines with domestic assembly mandates.
- Chips:Bare transceiver die requires external matching networks and packaging, appealing to smartphone modem integrators with captive assembly capabilities.
- Components:Discrete low-noise amplifiers, filters, and switches serve legacy infrastructure maintenance and specialized instrumentation with long replacement cycles.
By volume, Integrated Circuits leads. By growth pace, Modules is ahead.
Technology:
Cost tier stratification separates commodity RF-CMOS from premium GaN and silicon photonics processes, with each technology node commanding distinct foundry relationships and certification burdens.
- Mixed-Signal:Architectures embedding high-speed data converters alongside RF synthesizers capture the highest margin pools in test equipment and instrumentation. Keysight Technologies and Rohde & Schwarz specify these for vector signal analyzers requiring precise modulation quality measurement.
- Software-Defined:FPGA-programmable transceivers virtualize analog signal paths into reconfigurable digital blocks. Raytheon and Northrop Grumman deploy these for electronic warfare platforms demanding sub-microsecond frequency agility across contested spectrum environments.
- Analog:Traditional heterodyne architectures persist in cost-sensitive satellite ground terminals and legacy cellular infrastructure where digital processing overhead is prohibitive.
- Digital:All-digital RF processing eliminates analog mixer stages, emerging in millimeter-wave research platforms and advanced radar prototyping.
Mixed-Signal commands the steepest pricing premiums. Software-Defined is expanding most quickly.
Application:
Customer maturity cycles stretch from consumer electronics' 18-month replacement cadence to aerospace platforms' 25-year sustainment horizons, fragmenting supplier qualification requirements.
- Telecommunications:Base station transceivers span macro-cell massive MIMO arrays through indoor small-cell nodes, with procurement concentrated among Ericsson, Nokia, and Huawei for operator network builds.
- Aerospace:Satellite communication terminals and radar systems specify radiation-hardened transceivers with guaranteed availability across multi-decade program lifecycles.
- Automotive:V2X communication modules and radar sensors for autonomous driving integrate transceivers under AEC-Q100 automotive reliability standards.
- Consumer Electronics:Smartphone RF front-ends prioritize die size minimization and modem co-integration over absolute performance metrics.
Telecommunications dominates current procurement volumes. Aerospace delivers the longest contract durations.
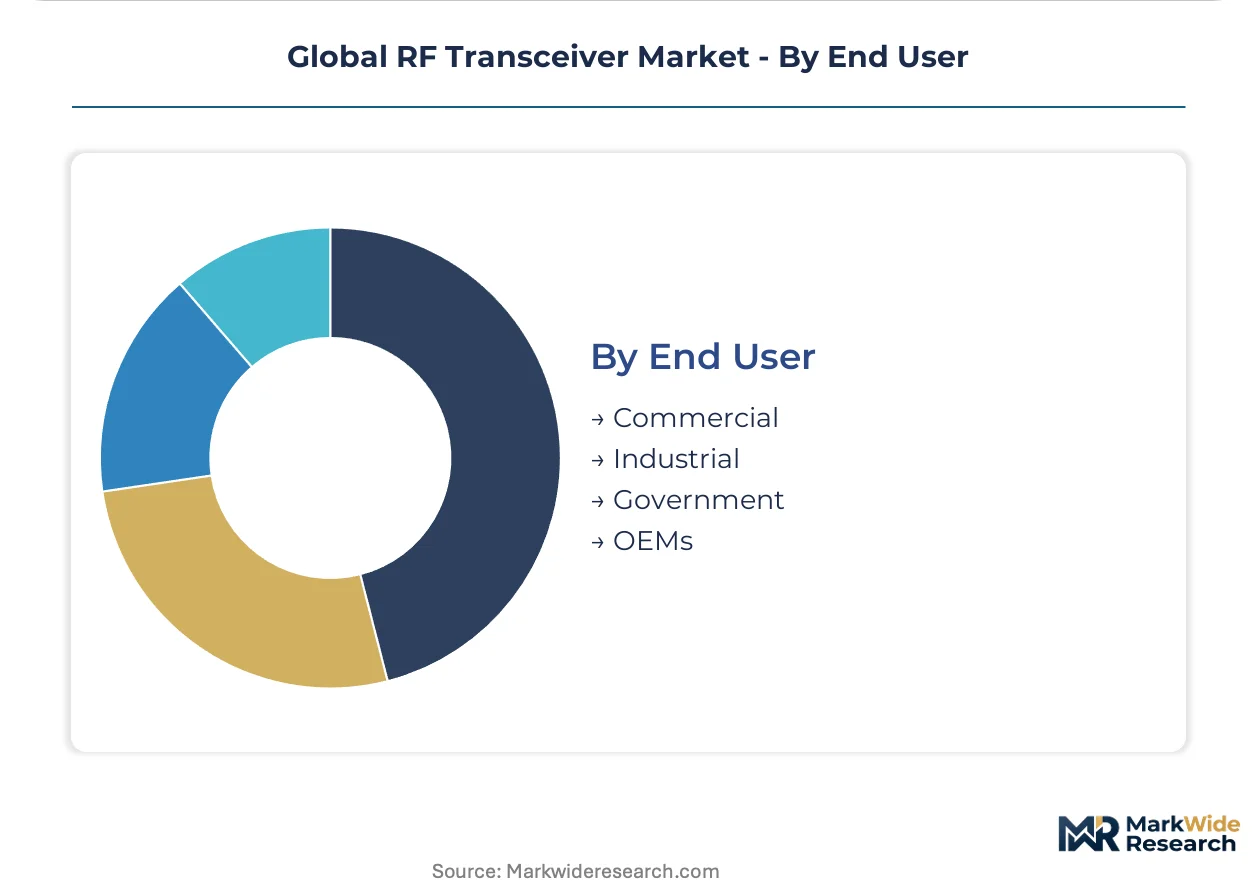
End User:
Supply concentration patterns diverge between government programs with sole-source mandates and commercial markets with multi-vendor qualification requirements.
- Government:Defense procurement officers now demand 10-year sustainment guarantees and long-term availability commitments rather than transactional component purchases, consolidating vendor lists around primes with captive foundry access.
- OEMs:Vertically integrated baseband vendors including Qualcomm and MediaTek negotiate wafer starts directly with Taiwan Semiconductor Manufacturing and Samsung Foundry, compressing traditional distribution layers.
- Commercial:Enterprise wireless infrastructure and private 5G networks balance performance specifications against total cost of ownership across 5-7 year depreciation cycles.
- Industrial:Factory automation and process control applications prioritize electromagnetic immunity and deterministic latency over peak data rates.
OEMs transact the highest unit volumes. Government contracts carry the most stringent qualification overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US CHIPS Act and parallel subsidy programs in Asia are redrawing semiconductor manufacturing geography. Government incentives now determine where RF transceiver packaging and test capacity expands.
United States
Department of Commerce funding under the CHIPS Act is attracting RF front-end packaging investments to Arizona and Texas. FCC spectrum auctions for C-band and 3.45 GHz are shaping design priorities for domestic infrastructure vendors. The Phoenix-Tucson corridor in Arizona hosts expanding advanced packaging facilities serving defense and telecommunications applications.
China
Domestic baseband-RF integration programs and massive MIMO rollouts are consuming high volumes of transceiver modules. MIIT spectrum allocations and SRRC certification requirements govern equipment authorization timelines. Shenzhen and Shanghai anchor design centers where local vendors serve China Mobile and China Telecom deployment schedules.
Germany
Automotive OEMs specify RF transceivers for V2X communication modules under AEC-Q100 reliability standards. The EU Radio Equipment Directive and ETSI harmonized standards mandate interoperability testing for cellular terminals. Bavaria's semiconductor cluster around Munich hosts automotive radar and industrial automation design centers.
India
Reliance Jio and Bharti Airtel are accelerating 5G small-cell deployments with domestic assembly requirements. TRAI spectrum policy and PLI scheme incentives for telecom equipment manufacturing shape procurement patterns. Bangalore and Hyderabad concentrate design engineering talent for cost-optimized transceiver module development.
South Korea
Samsung Foundry and SK Hynix anchor advanced node RF-CMOS capacity serving smartphone modem integration programs. The national regulator manages spectrum assignments that determine millimeter-wave design investment priorities. Seoul's Pangyo Techno Valley hosts fabless design houses specializing in 5G baseband-RF co-integration.
Global RF Transceiver Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated baseband vendors and captive foundry relationships. Tier 1 modem suppliers now negotiate wafer starts directly with Taiwan Semiconductor Manufacturing and Samsung Foundry, compressing traditional distribution layers. Three strategic archetypes dominate: gallium nitride specialists serving defense applications, silicon photonics scale players anchoring data center interconnect, and smartphone RF front-end integrators. Competitive moves center on foundry capacity reservation agreements and long-term sustainment contracts for defense programs.
Among US-based RF semiconductor vendors, Qorvo Inc., Broadcom Inc., and Qualcomm Incorporated exemplify distinct competitive positioning. Qorvo represents the defense-aerospace archetype with captive gallium nitride fabrication capabilities. Broadcom occupies the data center optical interconnect segment through silicon photonics manufacturing scale. Qualcomm anchors smartphone RF front-end integration through modem-to-antenna design philosophy. Each occupies a differentiated tier where technology specialization and foundry access create defensive moats.
| Leading Market Players |
|---|
| Qorvo Inc. |
| Broadcom Inc. |
| Qualcomm Incorporated |
| Texas Instruments Incorporated |
| Infineon Technologies AG |
| Analog Devices Inc. |
| Skyworks Solutions Inc. |
| STMicroelectronics |
| NXP Semiconductors |
| Others |
Value Chain & Pricing Dynamics
Taiwan's Hsinchu Science Park anchors global RF-CMOS foundry capacity, where wafer start allocations at Taiwan Semiconductor Manufacturing and United Microelectronics Corporation translate directly into pricing power for smartphone modem integrators and 5G base station vendors.
Pricing Analysis
Certification level (FCC Part 15/Part 27, ETSI EN 301 908, MIIT SRRC) creates the primary spread between premium and standard tiers. Three-tier pricing structure across defense-aerospace, telecommunications infrastructure, and consumer electronics levels segments buyers by compliance burden and volume commitment. Cost compression in smartphone RF front-ends is intensifying because foundry capacity reservation agreements now demand multi-year offtake guarantees. Consumer electronics OEMs exhibit highest price sensitivity due to 18-month product cycles, while defense primes accept premium positioning for 10-year sustainment contracts.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Taiwan Semiconductor Manufacturing and Samsung Foundry are restructuring working capital requirements for fabless design houses. Geographic concentration centers on Taiwan, South Korea, and the United States for advanced node RF-CMOS, with gallium nitride-on-SiC substrates sourcing from Japan and the United States. Raw material dependencies include high-purity silicon wafers, rare earth elements for permanent magnet components, and specialty gases for epitaxial growth. Single-source vulnerability around 7nm and 5nm EUV lithography equipment feeds into capacity constraints. Distribution runs through direct foundry-to-OEM procurement relationships that have displaced traditional semiconductor distribution layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern RF transceiver value capture, as modem-to-antenna integration and software-defined architectures dissolve hardware boundaries into configurable ecosystems.
For Market Incumbents: Insulate foundry access through multi-year capacity reservation agreements at Taiwan Semiconductor Manufacturing and Samsung Foundry. Secure captive gallium nitride fabrication capabilities to defend margin position against silicon photonics substitution in data center interconnect. Prioritize JESD204C interface migration programs to lock in baseband-RF integration roadmaps before legacy interface obsolescence accelerates. For New Entrants and Emerging Players: Build out cost-optimized transceiver module assembly for India's 5G small-cell buildout under PLI scheme incentives. Target software-defined radio convergence in aerospace electronic warfare platforms where frequency agility requirements outpace incumbent hardware revision cycles. Pursue FPGA-programmable architectures with AI-driven spectrum sensing as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a foundry-access scarcity play because advanced node RF-CMOS capacity constraints will persist regardless of demand cyclicality. Acquisition targets should emphasize vendors with sole-source defense contracts and 10-year availability commitments. Monitor FCC spectrum reallocation proceedings on C-band and 3.45 GHz assignments as the critical signal for design investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation Agreement | Locks wafer starts at Taiwan Semiconductor Manufacturing for 5G massive MIMO die supply. |
| Gallium Nitride Process Migration | Enables Qorvo to sustain pricing power in defense radar and satellite communication terminals. |
| Software-Defined Radio Platform Launch | Positions Raytheon and Northrop Grumman for sub-microsecond frequency hopping in electronic warfare. |
| Domestic Assembly Partnership | Aligns Reliance Jio procurement with India's PLI scheme for cost-optimized 5G small-cell modules. |
| JESD204C Interface Standardization | Resolves legacy baseband integration challenges for infrastructure OEMs upgrading transceiver generations. |
Study Parameters
Desk research of SEC 10-K filings, ETSI harmonized standards documentation, and FCC spectrum auction records preceded structured interviews with RF front-end design engineers, foundry account managers, defense procurement officers, and telecommunications infrastructure procurement leads. Secondary validation drew from Taiwan Semiconductor Manufacturing capacity disclosure statements, MIIT SRRC certification databases, and hyperscaler capex reports. Bottom-up unit shipment estimates across smartphone, base station, and aerospace segments were triangulated against top-down semiconductor wafer consumption data.
Assumptions held fixed include continued 5G massive MIMO deployment schedules in China, sustained Department of Commerce CHIPS Act funding levels, and ETSI cybersecurity-by-design mandates remaining in force. The analytical framework modeled volume and value across product type, technology node, application vertical, and end-user concentration dimensions. CAGRs were derived from regression analysis of historical foundry revenue allocation patterns and projected wafer start commitments. Industry-specific inputs included gallium nitride substrate supply forecasts and millimeter-wave test chamber capacity expansion timelines.
Stress conditions across FCC spectrum reallocation timing, EU Radio Equipment Directive enforcement intensity, and advanced node wafer pricing volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic contraction, regulatory reversal, or breakthrough in all-digital RF processing architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF Antenna Market
RF Components
Multi-Mode Receiver Market
RF Components
Flat Antenna Market
RF Components
RF Passive Component Market
RF Components
Global RF Power Semiconductor Market
RF Components
RF Front End Module Market
RF Components
UHF RFID Inlays Market
RF Components
Noise Suppression Components Market
RF Components
Global RF Plasma Generator Market
RF Components
Wireless Module Market
RF Components
Embedded Antenna Systems Market
RF Components
Radiofrequency Identification (RFID) Market
RF Components
Z-Wave Products Market
RF Components
Radio Frequency (RF) Signal Generators Market
RF Components
Radio Frequency Filters Market
RF Components
RF Components Market