
 Tunable Inductors Market | 2026-2036
Tunable Inductors Market Size, Share, and Industry Trends Forecast 2026-2036
Tunable Inductors Market Analytics
Japanese ferrite core production is hardening around legacy magnetics expertise and captive powder processing. Murata Manufacturing Co Ltd leverages vertical integration from raw ferrite through finished chip inductors to sustain margin control across RF filter supply chains. TDK Corporation anchors high-frequency performance benchmarks through proprietary material science that competitors struggle to replicate at scale.
Tunable inductors are electromagnetic components with variable inductance values adjusted mechanically, electrically, or magnetically, typically operating from nanhenries to millihenries with Q factors exceeding 50 at gigahertz frequencies; they serve primarily to optimize impedance matching and frequency selectivity in RF circuits. Wire wound technology dominates precision applications where thermal stability and current handling justify higher unit costs, while chip inductors capture volume in smartphone RF front-end modules where miniaturization pressures mount. Integrated inductors represent the fastest-growing structural category as system-in-package architectures displace discrete component stacking in 5G millimeter-wave arrays.
FCC Part 15 emissions rules in the United States and EU Radio Equipment Directive with CE marking requirements in Europe jointly constrain spurious performance thresholds that tunable inductor designs must satisfy for market access. Japan's METI circular economy guidelines and China's GB standards for electronic component recyclability add material disclosure layers that reshape supplier qualification protocols. Stakeholders must track how satellite constellation deployments and automotive radar frequency reallocations redirect specification roadmaps before committing to multi-year capacity investments.
Market Dynamics
RF filter deployment in 5G base stations is compressing design cycles and forcing inductor suppliers to reconcile millimeter-wave performance with mass-manufacturing economics. Telecommunications infrastructure upgrades are accelerating specification roadmaps faster than traditional ferrite core production can adapt.
Growth Catalysts
- 5G millimeter-wave densification:Base station OEMs are specifying tunable inductors for beamforming arrays operating above 24 GHz, creating pull for high-Q components that maintain stability across temperature extremes.
- REACH and RoHS compliance tightening:European material specifications for ferrite core formulations are disqualifying legacy powder suppliers, concentrating procurement among qualified vendors with disclosed supply chains.
- Samsung and SK Hynix supplier ecosystems:South Korean memory and RF module manufacturers are consolidating inductor qualification lists, driving volume concentration that rewards scale-capable producers.
Market Restraints
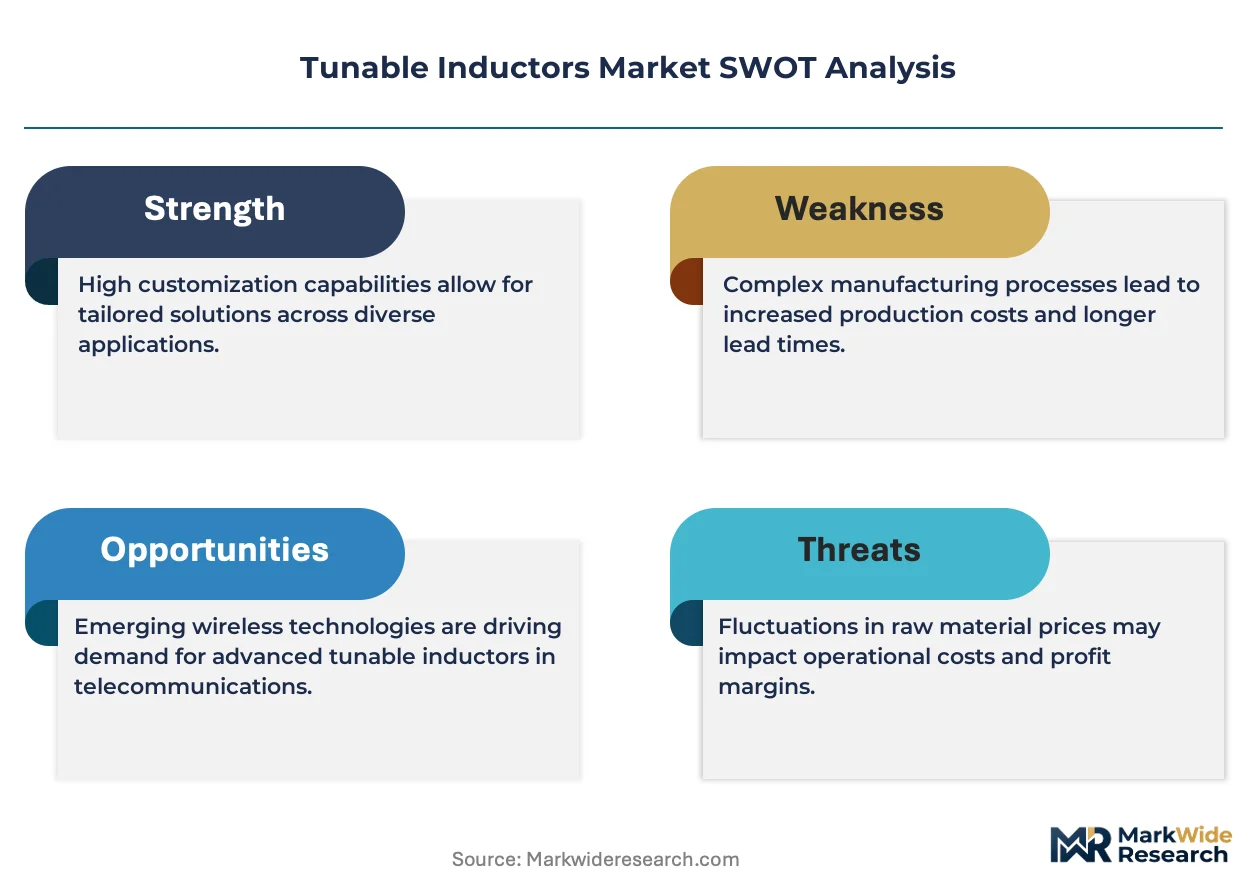
- Raw ferrite powder concentration:Japanese suppliers control proprietary high-frequency formulations, exposing non-integrated competitors to input cost volatility and allocation risk during demand spikes.
- Q-factor ceiling at sub-6 GHz:Chip inductor architectures face fundamental physics limits that wire wound alternatives exploit, fragmenting procurement across incompatible technical platforms.
- FCC Part 15 spurious emissions thresholds:United States market access requires redesign cycles that extend qualification timelines by 8-14 months for non-compliant legacy portfolios.
Strategic Opportunities
- Automotive radar frequency reallocations:77-81 GHz band expansion for adaptive cruise control is opening specification windows for inductors with automotive-grade reliability certifications.
- System-in-package integration:Convergence of RF front-end modules with antenna-in-package designs is unifying discrete component categories into single-source procurement relationships.
- METI circular economy guidelines:Japan's material disclosure mandates are creating first-mover advantage for suppliers with documented end-of-life recyclability protocols.
Industry Challenges
- Electromagnetic simulation talent scarcity:Finite-element modeling for 3D inductor geometries requires specialized RF engineering skills that outpace university pipeline output.
- Multi-physics certification timelines:Simultaneous thermal, mechanical, and electrical validation for automotive and aerospace applications extends development cycles beyond 18 months.
- Legacy test equipment incompatibility:Existing network analyzer configurations lack calibration standards for sub-nanosecond pulse response characterization in tunable configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunable Inductors Market |
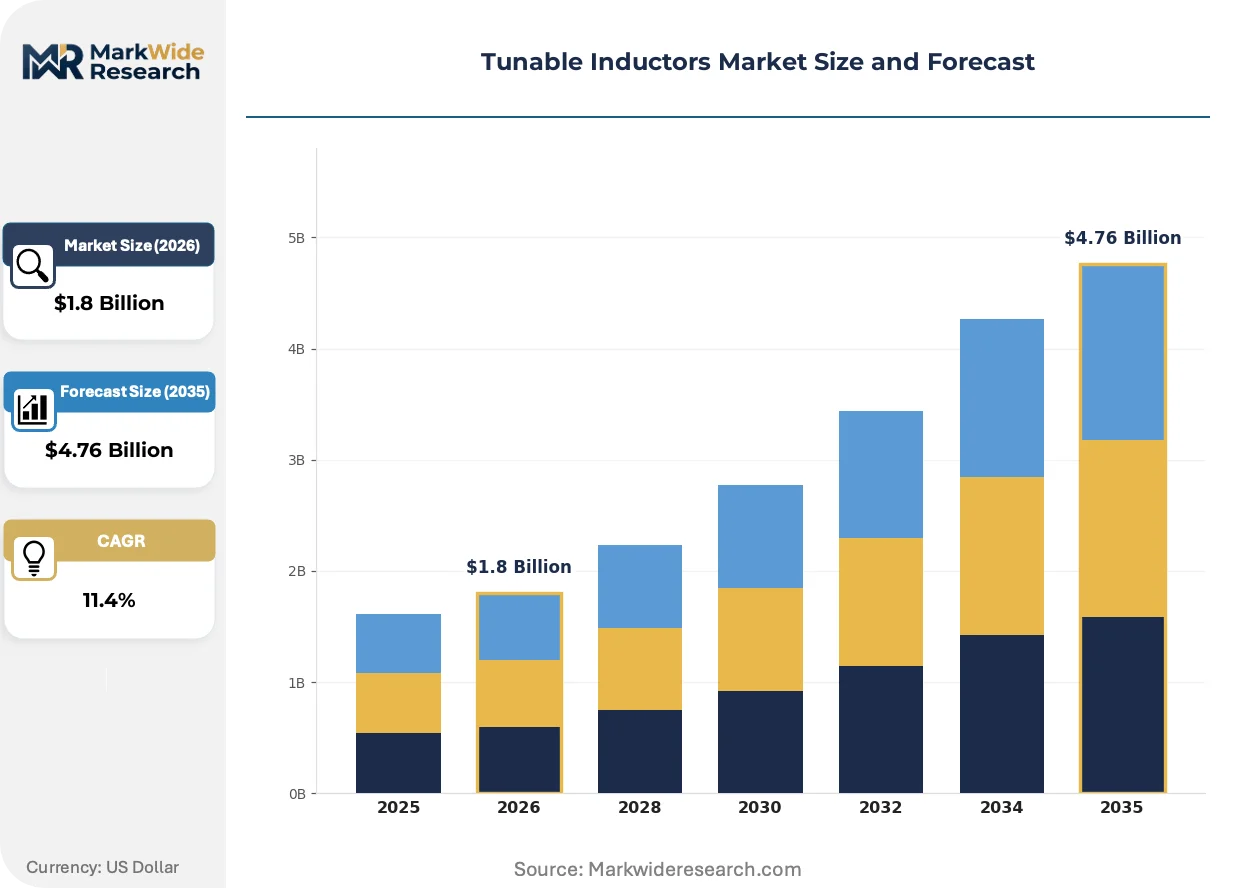
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Inductors, Adjustable Inductors, Variable Inductors, Integrated Inductors Application: RF Filters, Power Amplifiers, Voltage-Controlled Oscillators, Tuned Filters End User: Consumer Electronics, Telecommunications, Automotive, Aerospace Technology: Wire Wound, Air Core, Ferrite Core, Chip Inductors |
| Companies Covered | Knowles Johanson, TOKO, Murata Manufacturing Co Ltd, Taiyo Yuden Co Ltd, Panasonic Corporation, Vishay Intertechnology, Coilcraft, Bourns Inc, TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunable Inductors Market Evolving Landscape
Material science advances and packaging integration are collapsing the traditional separation between passive component manufacturing and semiconductor assembly. The boundary between discrete inductors and active RFICs is dissolving through shared substrate technologies.
Integrated inductors built on glass or silicon interposers are unifying impedance matching networks with power amplifier dies in 5G millimeter-wave modules. Smartphone OEMs are adopting these configurations for sub-7 GHz and mmWave bands simultaneously. This unification is compressing bill-of-materials counts while elevating performance accountability to the module supplier rather than the discrete component vendor.
EU Radio Equipment Directive harmonization with CE marking requirements is tightening spurious emission documentation across all RF equipment categories. Manufacturers must now submit third-party test reports for every inductor variant in qualified designs. High-frequency tunable inductor portfolios are experiencing the longest compliance review queues, forcing suppliers to pre-certify component families rather than custom specifications.
Consolidation of RF front-end procurement among tier-one smartphone OEMs is compressing supplier lists from dozens to single-digit approved vendors. Module houses are displacing discrete component distributors as the primary channel for inductor volume. South Korean and Chinese handset manufacturers are most aggressive in this consolidation, leveraging captive testing facilities to accelerate qualification cycles internally.
Tunable Inductors Market Segmentation
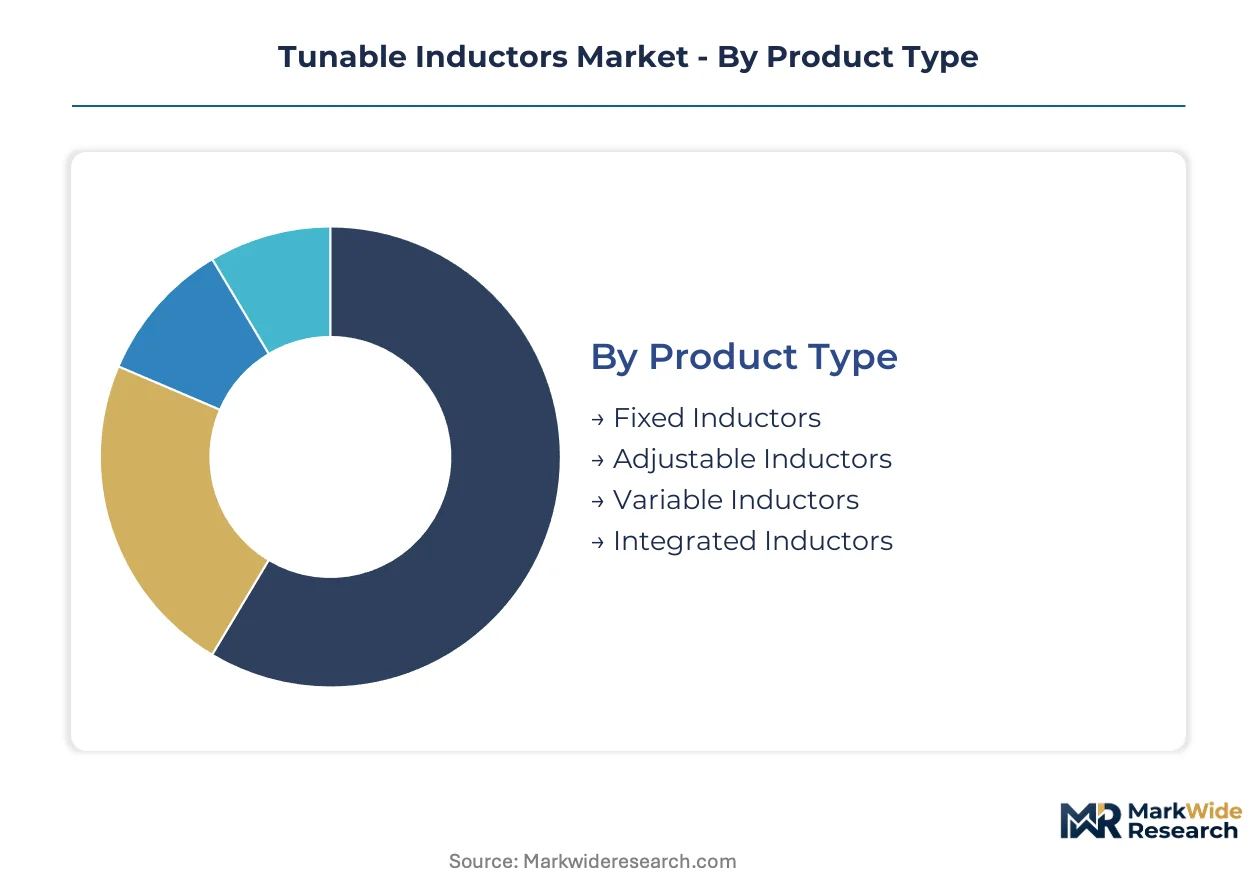
Tunable inductor procurement splits across incompatible technical platforms where certification requirements diverge sharply. RF module suppliers must maintain parallel qualification streams for discrete wire wound components versus integrated silicon-based alternatives, fragmenting vendor relationships and testing budgets.
Product Type:
Certification burdens vary dramatically across this dimension. Integrated inductors embedded in system-in-package modules require full FCC Part 15 and EU CE marking at the module level, while discrete adjustable and variable types face component-level spurious emissions documentation under ECHA REACH substance restrictions.
- Fixed Inductors:Encapsulated ferrite or air-core constructions with immutable inductance values, specified where thermal drift tolerance exceeds tuning flexibility requirements. Samsung and SK Hynix memory module suppliers specify these for DDR5 power delivery networks where board space constraints override adjustability needs.
- Adjustable Inductors:Mechanically tuned via ferrite slug displacement or threaded core positioning, enabling post-assembly impedance matching in prototype and repair scenarios. Telecommunications infrastructure OEMs in South Korea deploy these for 5G base station field calibration where remote electrical tilt antennas demand per-site optimization.
- Variable Inductors:Magnetically controlled through bias current modulation, offering electronic tuning without mechanical wear. Automotive radar suppliers leverage these for 77-81 GHz adaptive cruise control modules requiring real-time frequency agility under NHTSA reliability mandates.
- Integrated Inductors:Thin-film or thick-film constructions on silicon or glass interposers, merging passive matching networks with active RFICs. Smartphone millimeter-wave front-end modules increasingly specify these configurations to satisfy METI circular economy guidelines through reduced component counts.
Fixed inductors sit at the top of the volume ranking, with integrated inductors climbing the fastest.
Application:
Cost tier stratification separates premium beamforming arrays from standard sub-6 GHz infrastructure. Millimeter-wave RF filters command three to five times the unit economics of legacy cellular tuned filters due to Q-factor specifications and temperature stability requirements.
- RF Filters:Frequency-selective networks employing tunable inductors for bandpass and bandstop characteristics in receiver and transmitter chains. 5G base station OEMs specify these for 28 GHz and 39 GHz beamforming arrays where insertion loss directly impacts link budget calculations.
- Power Amplifiers:Impedance matching networks optimizing transistor load lines across operating bandwidths. GaN and GaAs power amplifier designers in Japanese supplier ecosystems favor wire wound tunable inductors for thermal management in high-power radar applications.
- Voltage-Controlled Oscillators:Frequency-determining resonant tanks where varactor-tuned capacitance pairs with fixed or minimally adjustable inductance. Satellite constellation ground terminals specify these for Ka-band upconverters requiring low phase noise under FCC Part 25 rules.
- Tuned Filters:Narrowband rejection or passband networks for interference mitigation in crowded spectrum environments. Legacy cellular infrastructure in Europe continues deploying these under EU Radio Equipment Directive harmonized standards, though volume is plateauing.
RF filters dominate procurement expenditure, with power amplifier applications expanding most quickly through radar and satellite terminal demand.
End User:
Customer type determines margin structure and contract duration. Automotive and aerospace programs lock in three-to-five-year supply agreements with penalty clauses, while consumer electronics operates on quarterly price negotiations with rapid supplier rotation.
- Consumer Electronics:Smartphone, tablet, and wearable OEMs specifying miniaturized chip inductors for RF front-end modules. Chinese handset manufacturers drive the steepest volume concentration, leveraging captive testing facilities to compress qualification cycles internally.
- Telecommunications:Base station and small cell infrastructure suppliers requiring high-Q components for millimeter-wave densification. South Korean 5G network operators specify tunable inductors for 28 GHz beamforming arrays through consolidated procurement relationships with tier-one module houses.
- Automotive:Radar module and electric vehicle power electronics suppliers demanding AEC-Q200 reliability certifications. 77-81 GHz adaptive cruise control expansion is opening specification windows for inductors with automotive-grade thermal cycling endurance.
- Aerospace:Satellite payload and defense communications systems requiring MIL-STD-883 screening and radiation tolerance documentation. Low-earth orbit constellation deployments redirect specification roadmaps toward commercial-grade alternatives with accelerated qualification pathways.
Consumer electronics commands absolute volume leadership, with automotive climbing fastest through radar frequency reallocations and electrification trends.
Technology:
Supply concentration patterns differentiate these categories. Japanese suppliers control proprietary high-frequency ferrite formulations, exposing non-integrated competitors to input cost volatility and allocation risk during demand spikes.
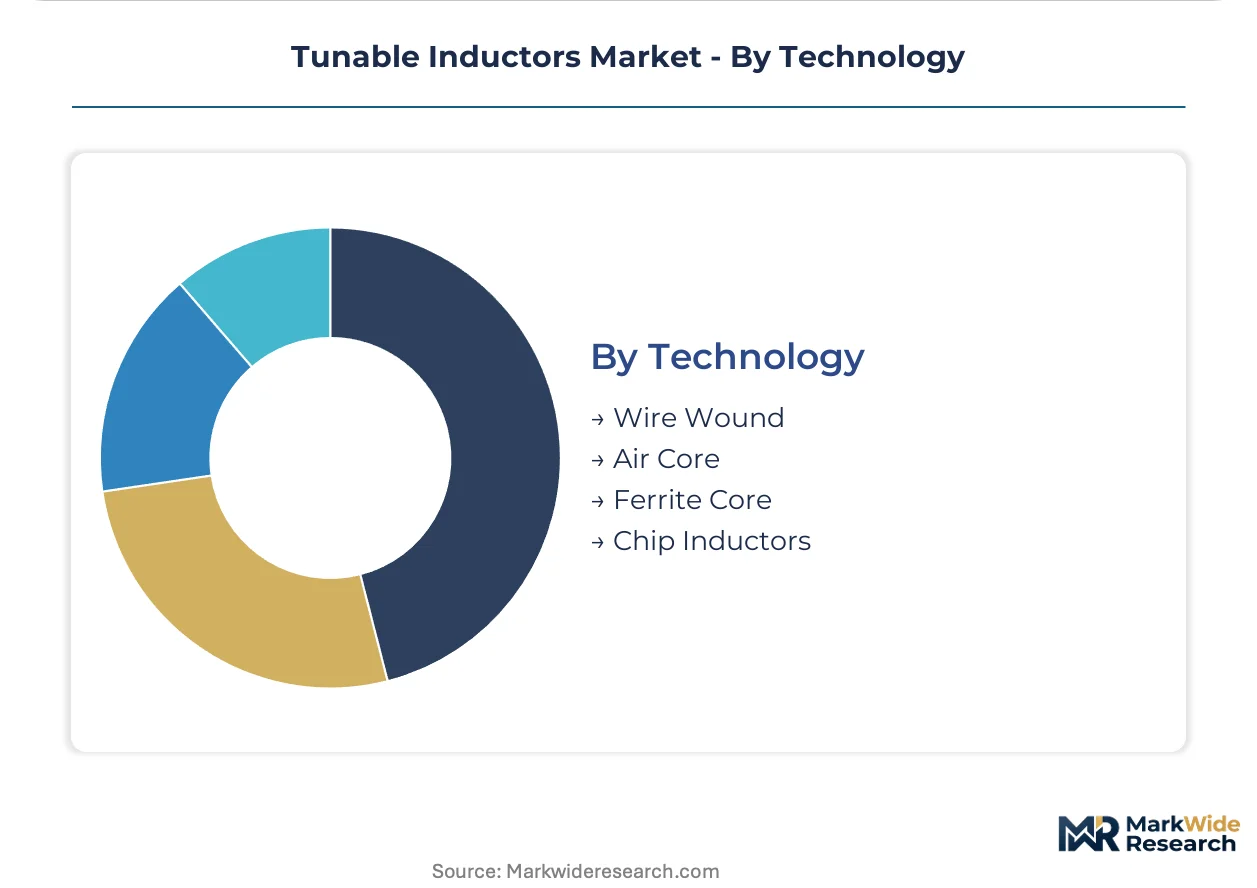
- Wire Wound:Copper wire coils on ceramic or ferrite cores delivering highest Q-factors and current handling. Precision applications in telecommunications infrastructure and military radar specify these where thermal stability justifies higher unit costs.
- Air Core:Self-supporting or molded coil constructions eliminating core losses for ultra-high-frequency operation. 5G millimeter-wave test equipment and satellite communications favor these for minimal parasitic capacitance above 10 GHz.
- Ferrite Core:Pressed and sintered magnetic oxide formulations enabling compact inductance values with controlled temperature coefficients. Murata Manufacturing and TDK Corporation anchor this segment through captive powder processing and proprietary material science.
- Chip Inductors:Surface-mount ceramic or ferrite constructions for high-density PCB assembly. Smartphone RF front-end modules capture volume here where miniaturization pressures mount and Q-factor ceilings at sub-6 GHz are acceptable.
Chip inductors lead by unit shipment volume, with integrated inductor technology gaining share fastest through system-in-package convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan maintains tighter control over ferrite powder formulations than the United States, while South Korean module houses compress supplier lists fastest. These divergent national patterns shape where capacity investments flow and which regulatory frameworks dominate qualification protocols.
United States
FCC Part 15 emissions enforcement drives redesign cycles for tunable inductor portfolios entering the market. The EPA coordinates with industry on material disclosure for end-of-life electronics under evolving circular economy guidance. Greater Boston anchors RF engineering talent pools where electromagnetic simulation specialists command premium compensation.
Japan
METI circular economy guidelines mandate documented recyclability protocols that reshape supplier qualification standards. Captive ferrite powder processing at major producers insulates domestic supply chains from allocation volatility during demand spikes. The Kanto region around Tokyo concentrates legacy magnetics expertise and precision manufacturing infrastructure.
South Korea
Samsung and SK Hynix ecosystems consolidate inductor procurement lists, rewarding scale-capable producers with multi-year volume commitments. The Korea Communications Commission enforces spurious emissions standards aligned with EU Radio Equipment Directive harmonization. Seoul Capital Area module houses displace discrete component distributors as primary volume channels.
Germany
ECHA REACH compliance tightening disqualifies legacy powder suppliers without disclosed supply chain documentation. The KBA coordinates automotive radar frequency reallocations that open specification windows for 77-81 GHz components. Bavaria hosts precision electronics manufacturers serving both automotive and telecommunications OEMs with AEC-Q200 certified portfolios.
China
GB standards for electronic component recyclability add material disclosure layers that reshape supplier qualification protocols. MIIT accelerates 5G base station deployment timelines that compress design cycles for millimeter-wave components. The Yangtze River Delta concentrates system-in-package assembly capacity where integrated inductor demand climbs fastest.
Tunable Inductors Market Competitive Landscape
Japanese producers anchor one tier through captive material science and vertical integration; United States specialists hold differentiated positions in precision wire wound constructions. The vendor base splits between consolidated ferrite core manufacturers and fragmented chip inductor assemblers. Two strategic archetypes dominate: integrated powder-to-component producers and module-focused packaging specialists. Competitive moves center on backward integration into raw ferrite supply and geographic expansion through qualified vendor status in South Korean ecosystems.
Within the integrated producer tier, Murata Manufacturing Co Ltd and TDK Corporation occupy positions that exemplify captive supply chain control from raw ferrite through finished components. Taiyo Yuden Co Ltd represents the module-specialist archetype, sitting within supplier ecosystems where packaging integration determines procurement relationships. These three Japanese entities collectively illustrate how national industrial structure shapes competitive positioning in high-frequency passive components.
| Leading Market Players |
|---|
| Knowles Johanson |
| TOKO |
| Murata Manufacturing Co Ltd |
| Taiyo Yuden Co Ltd |
| Panasonic Corporation |
| Vishay Intertechnology |
| Coilcraft |
| Bourns Inc |
| TDK Corporation |
| Others |
Value Network & Pricing Analysis
Electromagnetic simulation talent concentration in Greater Boston feeds labor-cost differentials that widen pricing-tier spreads between precision wire wound components and commodity chip inductors. Japanese captive powder processing insulates integrated producers from raw material volatility, compressing margins for non-integrated assemblers competing on volume.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade chip inductors while premium wire wound tiers anchored in Japanese material science hold firm. Three-tier pricing structure across automotive-grade, telecommunications-grade, and consumer-grade levels separates AEC-Q200 certified components from basic FCC Part 15 compliant alternatives. Pricing pressure stems from South Korean module houses consolidating procurement lists and squeezing discrete component vendors. Consumer electronics buyers exhibit highest price sensitivity through quarterly renegotiation cycles, while automotive programs lock in multi-year agreements with penalty clauses that insulate suppliers from spot-market volatility.
Supply Chain Analysis
Certification gating through AEC-Q200 and MIL-STD-883 screening fragments vendor qualification pools and extends lead times for specialized tiers. Geographic supply concentrates in Japan, South Korea, and China, with Japanese suppliers controlling proprietary high-frequency ferrite formulations. Raw material dependencies center on nickel-zinc and manganese-zinc ferrite powders, copper magnet wire, and ceramic substrate materials. Single-source vulnerability around Japanese ferrite powder exposes non-integrated competitors to allocation risk during demand spikes. Distribution runs through module houses displacing discrete component distributors as primary volume channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Japanese material-science premiums and Chinese system-in-package assembly cost structures, with METI circular economy disclosure mandates adding compliance-layer differentiation.
For Market Incumbents: Deploy captive ferrite powder processing to defend margin structures against Chinese volume competitors. Deepen backward integration into raw material supply and accelerate AEC-Q200 certification investments to capture automotive radar frequency reallocations. Consolidate channel control through direct module house relationships before South Korean procurement lists harden around tier-one vendors. For New Entrants and Emerging Players: Glass-interposer integrated inductor technology offers entry wedge into smartphone millimeter-wave module supply chains underserved by legacy discrete vendors. Target white-space in 77-81 GHz automotive radar components where AEC-Q200 certification barriers remain penetrable. Pursue qualification-fast-track partnerships with Chinese system-in-package assemblers in the Yangtze River Delta to bypass established Japanese distributor networks. For Investors and Strategic Acquirers: RF module houses are the most active acquirer in this space, consolidating discrete component vendors into single-source procurement relationships. Long-term viability favors targets with documented end-of-life recyclability protocols under METI guidelines and established qualification status in Samsung or SK Hynix ecosystems. Watch for inflection when satellite constellation deployments redirect specification roadmaps toward commercial-grade alternatives with accelerated qualification pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Powder Processing | Murata and TDK sustain margin control through captive raw material supply chains. |
| AEC-Q200 Certification Investment | Automotive radar suppliers lock in 77-81 GHz component specifications ahead of frequency reallocations. |
| System-in-Package Technology Licensing | Glass-interposer integration unifies passive matching networks with active RFIC dies in 5G modules. |
| South Korean Ecosystem Qualification | Samsung and SK Hynix supplier lists reward scale-capable producers with multi-year volume commitments. |
| METI Circular Economy Protocol Documentation | First-mover advantage accrues to suppliers with verified end-of-life recyclability pathways. |
Research Methodology
Bottom-up RF module and base station deployment modeling reconciled against top-down ferrite powder production tracking forms the analytical core of this study. Primary interviews with RF design engineers, telecommunications procurement leads, automotive radar module specialists, and semiconductor packaging directors combined with secondary validation from FCC equipment authorization databases, ECHA REACH substance registrations, METI circular economy disclosures, and SEC filings from listed component manufacturers. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map ferrite powder throughput to finished component shipments across product type, application, end user, and technology dimensions. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion patterns throughout the forecast period. Industry-specific forecast inputs include 5G base station deployment trajectories under MIIT acceleration timelines, automotive radar frequency reallocation schedules coordinated by KBA, and satellite constellation launch manifests.
The model holds under continued REACH and RoHS compliance tightening in Europe; deviation in Japanese export restriction triggers or raw material allocation crises would shift supply-side concentration assumptions. Forecasts reflect documented qualification timelines, certification burden trajectories, and procurement consolidation patterns. A model refresh is warranted upon material change in South Korean module house supplier list consolidation velocity or FCC Part 15 emissions threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
5G Gain Block Amplifier Market
RF Components
Multi-Mode Receiver Market
RF Components
Analog Phase Shifter Market
RF Components
Gan RF Semiconductor Devices Market
RF Components
RF Power Amplifiers Market
RF Components
Americas Small Signal Transistor Market
RF Components
Asia-Pacific Small Signal Transistor Market
RF Components
Small Signal Mosfets Market
RF Components
Acoustic Wave Filters Market
RF Components
Tunable Capacitors Market
RF Components
RF Over Fiber (Rfof) Market
RF Components
Embedded Antenna Systems Market
RF Components
Global RF Plasma Generator Market
RF Components
Noise Suppression Components Market
RF Components
Digital Phase Shifter Market
RF Components
Multiband Booster Market