
 RF Switches Market | 2026-2036
RF Switches Market Size, Share, and Industry Trends Forecast 2026-2036
RF Switches Market Analysis
Market Context
Modular front-end integration is expanding buyer choice as RF switches ship in configurable subsystems rather than discrete components. Qorvo leverages its GaN and GaAs process leadership to dominate high-frequency defense and 5G base station segments. Skyworks Solutions anchors consumer electronics volumes through deep partnerships with smartphone OEMs. Infineon Technologies specializes in automotive-qualified RF switches as connected vehicle architectures multiply antenna count.
Technical Definition and Segment Structure
An RF switch is a signal routing device that directs radio-frequency energy between transmission paths, typically operating from DC to millimeter-wave frequencies with insertion loss below 1 dB and isolation exceeding 30 dB for receiver protection and test-system multiplexing. Solid-state electronic switches lead volume production due to silicon-on-insulator cost curves, while MEMS technology captures premium positioning in aerospace and military applications where near-zero power consumption and exceptional linearity justify higher unit costs. Monolithic integration is displacing hybrid assemblies in telecommunications as carrier aggregation demands tighter phase matching across wider bandwidths.
Regulatory Frame and Outlook
The FCC in the United States, ETSI in Europe, and MIIT in China each enforce distinct spurious emission and spectrum efficiency standards that dictate switch linearity specifications and qualification test matrices. REACH and RoHS constraints from European regulators restrict traditional plating materials, pushing suppliers toward gold-free contact metallurgies and compliant packaging. Stakeholders must monitor spectrum auction calendars and satellite constellation licensing waves, as these determine the frequency bands and power levels that next-generation switches must accommodate.
Market Dynamics
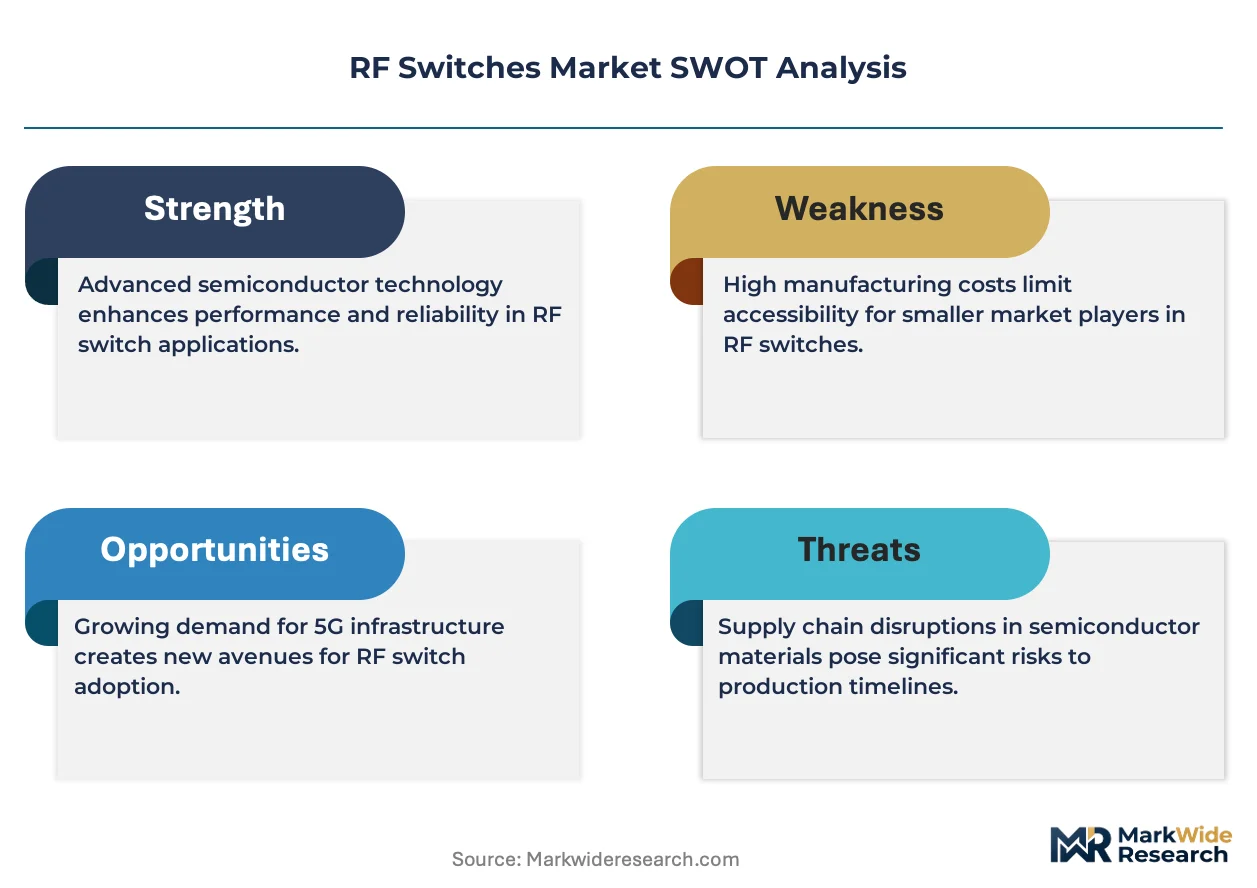
Carrier aggregation in 5G base stations and satellite constellations is forcing RF switch architectures toward wider bandwidth coverage and tighter phase matching, compressing design cycles and elevating qualification thresholds for suppliers.
Growth Catalysts
- 5G Infrastructure Mandates:FCC spectrum reallocation in the United States compels equipment redesign for sub-6 GHz and millimeter-wave bands, multiplying switch counts per base station.
- Silicon-on-Insulator Cost Curves:SOI wafer economics enable solid-state switches to capture volume from legacy hybrid assemblies in telecommunications test equipment.
- China Satellite Terminal Programs:Domestic equipment makers in China source RF switches for massive MIMO arrays and low-earth-orbit user terminals, anchoring regional demand concentration.
Market Restraints
- Gallium Arsenide Wafer Supply:Limited merchant capacity for GaAs substrates constrains high-frequency switch output, concentrating supply risk with Taiwanese foundries.
- MEMS Unit Economics:Near-zero power consumption and exceptional linearity in MEMS switches justify premium positioning only in aerospace and military budgets, capping volume expansion.
- REACH Metallurgy Constraints:European restrictions on traditional plating materials force gold-free contact redesigns, extending qualification timelines for established product lines.
Strategic Opportunities
- Automotive Antenna Multiplexing:Connected vehicle architectures in Germany and Japan multiply RF switch counts per platform as V2X and satellite positioning converge.
- India Telecom Equipment Localization:PLI scheme incentives for domestic 5G manufacturing create captive demand for qualified RF switch suppliers establishing local assembly.
- Monolithic Integration Convergence:SOI and GaN process convergence enables single-die integration of switching with low-noise amplification, collapsing subsystem bill-of-materials.
Industry Challenges
- Millimeter-Wave Test Engineering Talent:Scarcity of engineers proficient in 28 GHz and 39 GHz characterization slows product validation for base station and satellite applications.
- Multi-Band Certification Matrices:FCC, ETSI, and MIIT each enforce distinct spurious emission test protocols, fragmenting qualification resources across geographic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Switches Market |
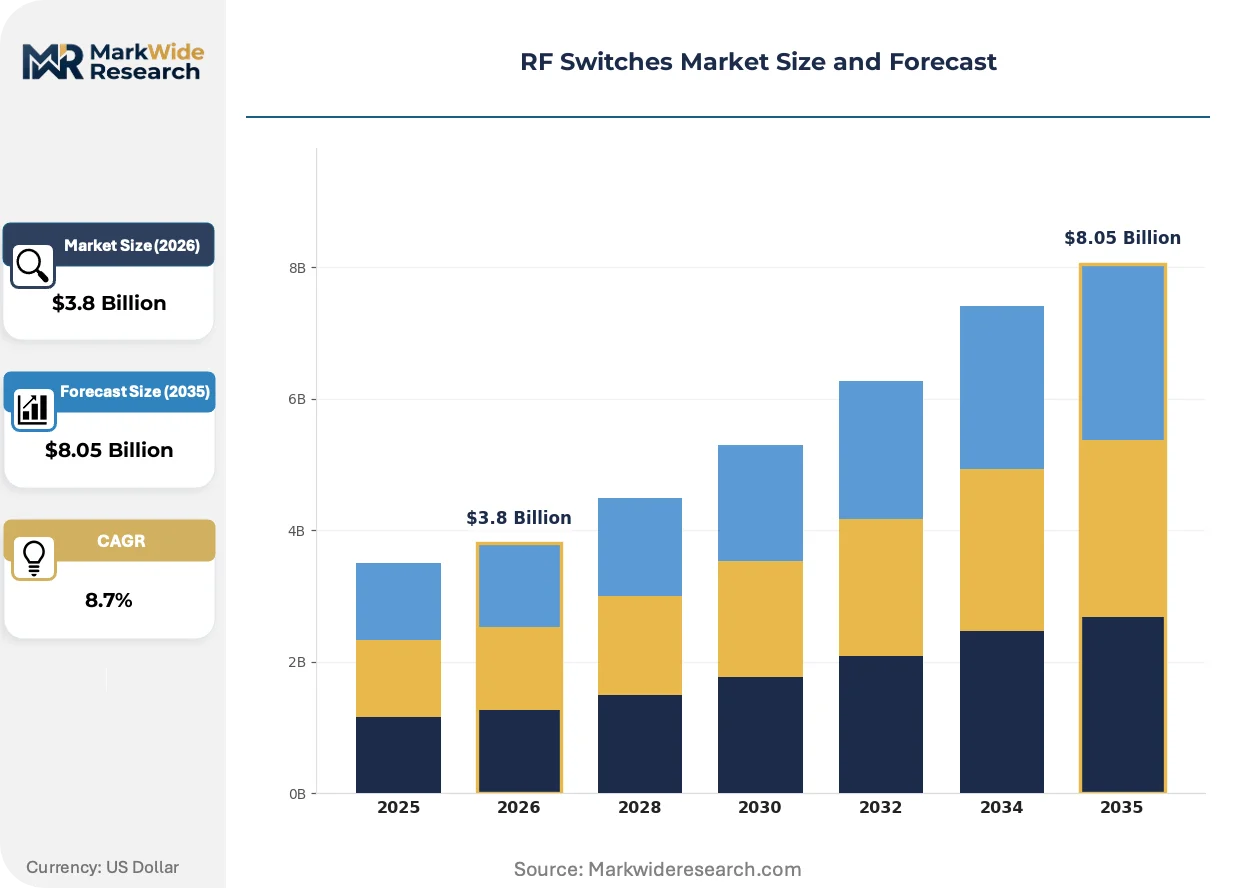
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
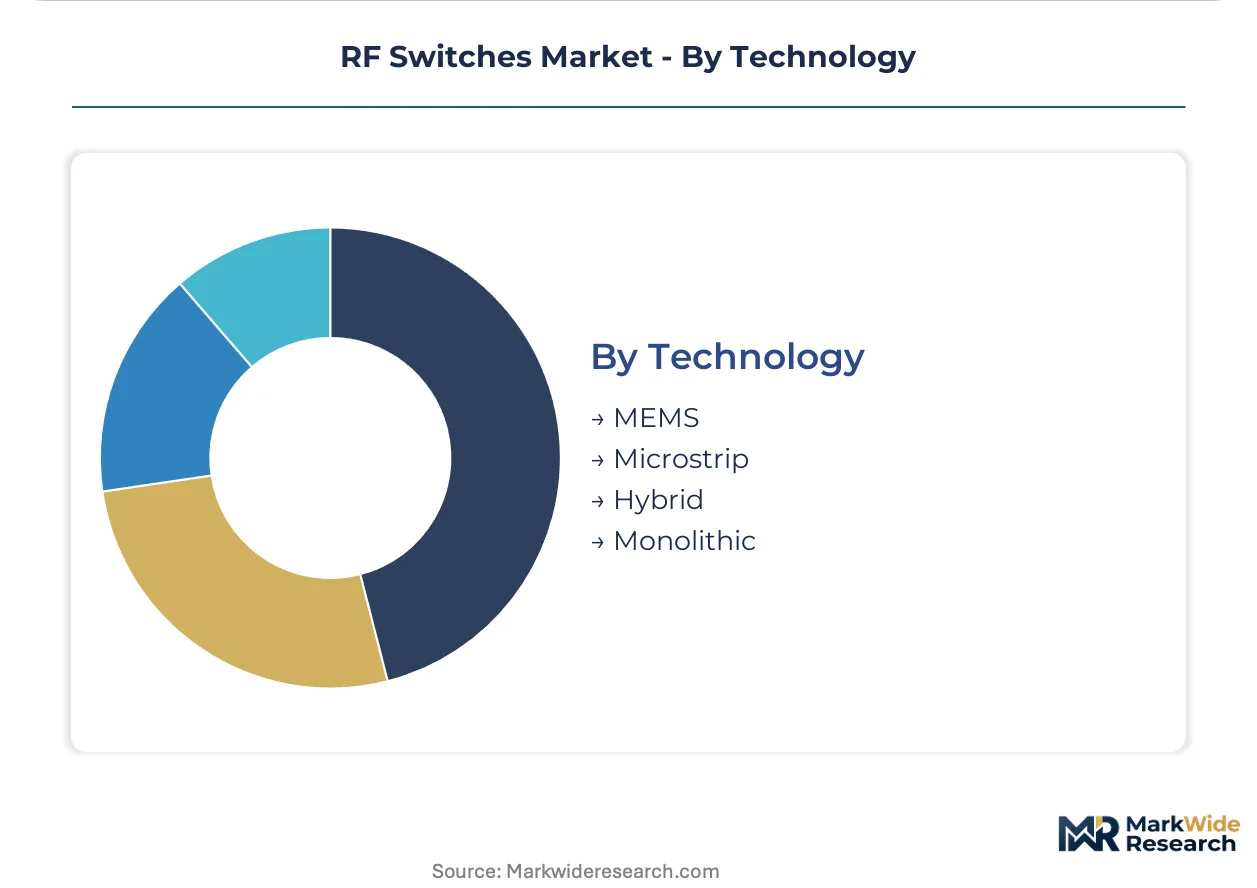
| Segmentation | Product Type: Mechanical, Electronic, Solid-State, RF Memristor Application: Telecommunications, Aerospace, Military, Broadcasting End User: Consumer Electronics, Automotive, Industrial Automation, Healthcare Technology: MEMS, Microstrip, Hybrid, Monolithic |
| Companies Covered | pSemi Corporation, Qorvo, Skyworks Solutions, Renesas Electronics Corporation, Analog Devices, Infineon Technologies, Broadcom, Mini-Circuits, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Switches Market Emerging Trajectories
RF switch technology is pivoting from discrete component supply toward configurable subsystem integration, with process technology choices and regulatory compliance frameworks determining competitive position.
GaN-on-SiC process technology is expanding into high-power transmit-receive modules for defense radar and 5G massive MIMO. Prime contractors in the United States and China are qualifying GaN switches for active electronically scanned arrays, displacing legacy tube-based systems. This expansion is compressing the performance gap between solid-state and electromechanical alternatives in applications above 6 GHz.
ETSI harmonized standards for 5G NR equipment in Europe now mandate stricter linearity specifications for carrier aggregation configurations. Manufacturers must redesign switch cores to maintain intermodulation performance across widening instantaneous bandwidths. Test-system suppliers in Germany and France are first to market with automated compliance platforms addressing these thresholds.
Modular front-end procurement is consolidating switch selection authority with subsystem integrators rather than OEM component teams. Buyers in South Korea and Taiwan now specify switch performance as part of configurable RF front-end contracts, collapsing direct procurement of discrete devices. This pattern concentrates supplier relationships with tier-one module vendors and elevates qualification barriers for specialized switch houses.
RF Switches Market Segmentation
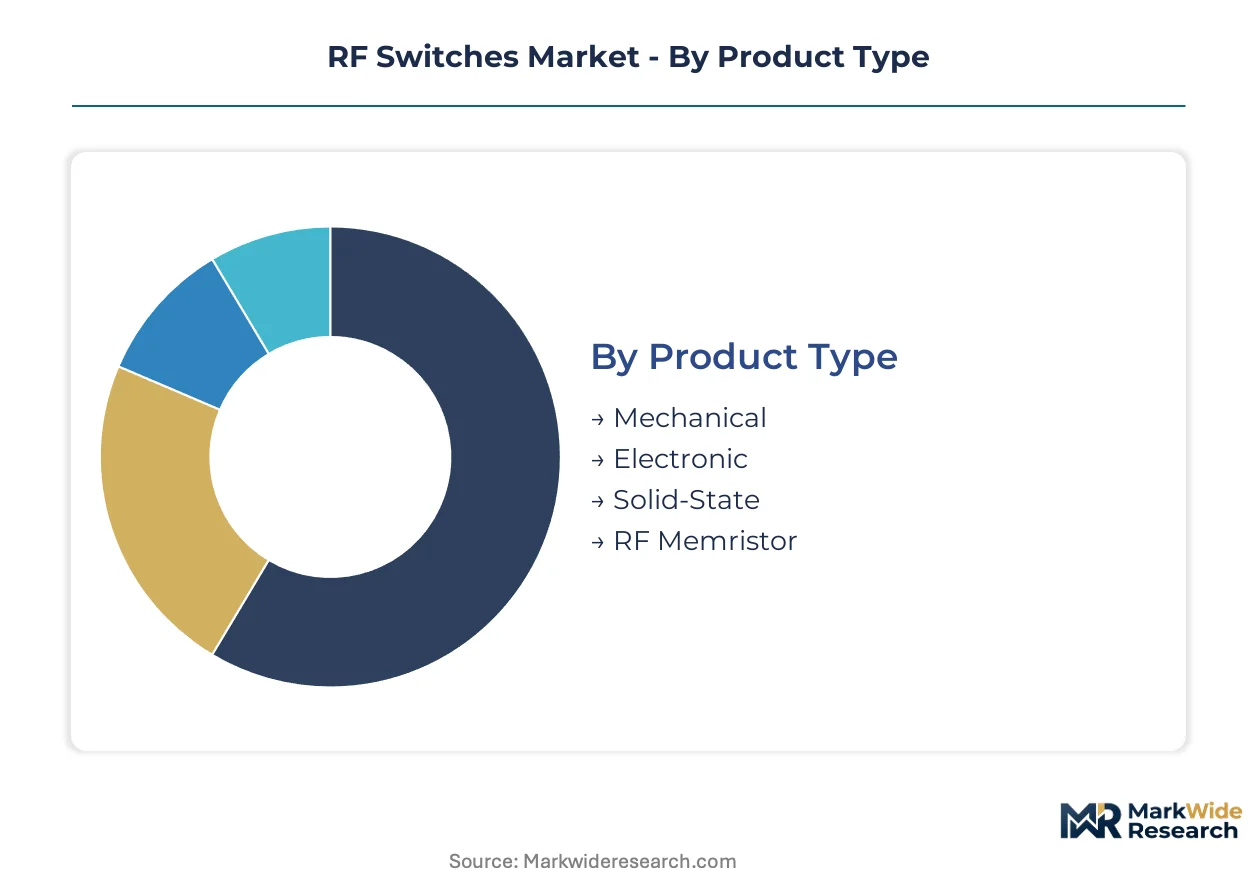
RF switch segmentation reveals divergent integration strategies across telecommunications infrastructure, defense systems, and consumer devices. Product architecture choices determine whether switches ship as discrete components or embed within larger front-end modules.
Product Type:
Integration depth varies sharply—solid-state and electronic switches dominate embedded subsystem designs, while mechanical switches persist in standalone test equipment and maintenance-accessible infrastructure.
- Mechanical:Electromechanical actuation delivers exceptional isolation exceeding 60 dB for high-power transmit-receive applications. Demand concentrates in legacy broadcast transmitters and military maintenance depots where manual override capability outweighs switching speed limitations.
- Electronic:PIN diode and FET-based architectures achieve nanosecond switching speeds essential for 5G carrier aggregation. Base station manufacturers in China and South Korea specify electronic switches for massive MIMO arrays where rapid beam steering is non-negotiable.
- Solid-State:Silicon-on-insulator processes enable monolithic integration with low-noise amplifiers and power detectors.
- RF Memristor:Emerging non-volatile switching technology targets reconfigurable intelligent surfaces and software-defined radio applications.
Volume placements concentrate in Electronic switches; the faster expansion belongs to Solid-State devices as SOI cost curves improve.
Application:
Cost tier stratification separates premium-qualified aerospace and military programs from high-volume telecommunications deployments.
- Telecommunications:Base station and satellite terminal applications drive the largest unit volumes. FCC spectrum reallocation in the United States and MIIT mandates in China force simultaneous multi-band coverage, multiplying switch counts per installation.
- Aerospace:Radiation-hardened specifications and extreme temperature qualification define this segment. Satellite constellation prime contractors in the United States and Europe source switches for phased array antennas where failure tolerance approaches zero.
- Military:Active electronically scanned arrays and electronic warfare systems demand GaN-on-SiC switches for high-power radar.
- Broadcasting:AM/FM and digital terrestrial television transmitters rely on mechanical switches for maintenance bypass.
Telecommunications captures the highest shipment volumes; Aerospace commands the steepest expansion trajectory as low-earth-orbit constellations multiply.
End User:
Customer type determines qualification burden and pricing power, with automotive and healthcare imposing the most stringent reliability standards.
- Consumer Electronics:Smartphone OEMs specify ultra-compact SP4T and SP8T switches for antenna tuning. Skyworks and Qorvo anchor this segment through deep partnerships with tier-one handset manufacturers.
- Automotive:Connected vehicle architectures multiply antenna count for V2X, satellite positioning, and cellular connectivity. German and Japanese OEMs now qualify RF switches to AEC-Q100 standards, extending qualification timelines but securing decade-long supply agreements.
- Industrial Automation:Wireless sensor networks and private 5G deployments drive demand for ruggedized switches.
- Healthcare:MRI equipment and RF ablation systems require medical-grade isolation and biocompatibility certification.
Consumer Electronics maintains dominant volume; Automotive is climbing the fastest as software-defined vehicle architectures proliferate.
Technology:
Supply concentration in foundry capacity shapes competitive positioning, with MEMS and monolithic technologies requiring distinct manufacturing ecosystems.
- MEMS:Microelectromechanical switches achieve near-zero power consumption and exceptional linearity through electrostatic actuation. Aerospace and military budgets in the United States and China justify premium unit costs for satellite and radar applications.
- Monolithic:Single-die integration of switching with amplification and filtering collapses subsystem footprint. SOI and GaN process convergence enables this architecture for 5G base stations where phase matching across carrier aggregation bands is critical.
- Microstrip:Planar transmission line structures suit laboratory test equipment and prototyping.
- Hybrid:Multi-chip assemblies combining different semiconductor processes persist in legacy defense programs.
Monolithic integration captures accelerating volume; MEMS technology is gaining share fastest in premium aerospace applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen, Zhuhai, and Dongguan concentrate RF switch fabrication capacity. These zones offer tax holidays and duty exemptions for semiconductor equipment imports. Cluster effects draw packaging and test houses into proximity with wafer foundries.
United States
Defense prime contractors in Massachusetts and California drive demand for GaN-on-SiC switches in phased array radar. FCC spectrum reallocation mandates compel equipment redesign for millimeter-wave bands. The Boston-Cambridge corridor hosts test-equipment vendors developing automated compliance platforms for 5G NR certification.
China
Domestic equipment makers in Beijing and Shanghai source RF switches for massive MIMO arrays and low-earth-orbit satellite terminals. MIIT enforces distinct spurious emission standards that dictate switch linearity specifications. The Yangtze River Delta cluster integrates SOI foundries with subsystem assemblers serving telecommunications infrastructure programs.
Germany
Automotive OEMs in Stuttgart and Munich qualify RF switches to AEC-Q100 standards for connected vehicle architectures. ETSI harmonized standards mandate stricter linearity for carrier aggregation configurations. The Baden-Württemberg region anchors RF front-end module development for V2X and satellite positioning convergence.
South Korea
Smartphone OEMs in Seoul and Suwon specify ultra-compact switches for antenna tuning applications. The Korea Communications Commission enforces equipment certification protocols that influence switch qualification matrices. The Pangyo Techno Valley hosts subsystem integrators consolidating switch procurement authority within configurable RF front-end contracts.
Japan
Industrial automation vendors in Tokyo and Osaka deploy ruggedized switches for private 5G and wireless sensor networks. METI promotes domestic semiconductor supply chain resilience through targeted subsidies. The Kansai region maintains precision manufacturing capabilities for MEMS switch fabrication serving aerospace applications.
RF Switches Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the RF switch market. The vendor base stratifies into three tiers: integrated device manufacturers with captive foundries, fabless design houses leveraging merchant silicon, and specialized subsystem integrators. Dominant competitive moves include strategic partnerships with telecommunications equipment OEMs and backward integration into SOI wafer supply.
Within the integrated device manufacturer tier, Qorvo, Skyworks Solutions, and Infineon Technologies exemplify divergent strategic positioning. Qorvo represents GaN and GaAs process leadership for high-frequency defense and infrastructure segments. Skyworks Solutions anchors consumer electronics volumes through handset OEM relationships. Infineon Technologies occupies a position in automotive-qualified devices as antenna multiplexing requirements multiply per vehicle platform.
| Leading Market Players |
|---|
| pSemi Corporation |
| Qorvo |
| Skyworks Solutions |
| Renesas Electronics Corporation |
| Analog Devices |
| Infineon Technologies |
| Broadcom |
| Mini-Circuits |
| NXP Semiconductors |
| Others |
Supply Flow & Price Mechanics
FCC spectrum reallocation mandates in the United States compel telecommunications equipment OEMs to redesign for millimeter-wave coverage, forcing switch suppliers to absorb qualification costs or risk volume displacement. This specification pressure concentrates pricing power with GaN and SOI foundries capable of certifying to multi-band linearity thresholds.
Pricing Analysis
Short lead-time premiums dominate RF switch procurement as 5G base station deployments accelerate and buffer inventory thins. Three-tier pricing structure across radiation-hardened aerospace, automotive-qualified, and consumer-grade tiers separates segments by certification burden and failure tolerance. Cost compression in consumer electronics runs through smartphone OEM consolidation, while defense contractors exhibit lowest price sensitivity due to program-specific qualification lock-in.
Supply Chain Analysis
Specialized RF process engineers in Taiwan, South Korea, and the United States constrain foundry expansion as compound semiconductor fabrication demands unique expertise. Gallium arsenide substrates, SOI wafers, and GaN-on-SiC epitaxy draws from merchant suppliers concentrated in East Asian manufacturing corridors. Single-source vulnerability around Taiwanese GaAs foundries elevates supply risk. Distribution runs through subsystem integrators consolidating component procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF switch market consolidation accelerates as FCC, ETSI, and MIIT certification matrices multiply qualification costs beyond mid-tier specialist capacity. Regulatory fragmentation forces weaker players toward exit or acquisition.
For Market Incumbents: Deepen backward integration into SOI wafer supply to secure foundry allocation during capacity crunches. Lock in decade-long supply agreements with automotive OEMs qualifying to AEC-Q100 standards before second-tier competitors complete certification. MEMS technology specialists pose substitution threats in aerospace applications where near-zero power consumption commands premium positioning. For New Entrants and Emerging Players: Subsystem integrators in South Korea and Taiwan represent the most accessible channel partners for penetrating telecommunications infrastructure procurement. Target India's PLI-scheme subsidized 5G equipment manufacturing for captive demand creation. Automotive antenna multiplexing offers white-space opportunity as German and Japanese OEMs multiply RF switch counts per vehicle platform. For Investors and Strategic Acquirers: The window for entry favors fabless design houses with MIIT pre-qualification and existing relationships with Chinese massive MIMO array manufacturers. SOI process convergence with GaN integration capabilities signals acquisition target archetype. Monitor spectrum auction calendars and satellite constellation licensing waves as inflection indicators for frequency band demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| SOI Foundry Capacity Expansion | Captive wafer supply secures allocation during telecommunications infrastructure buildouts. |
| GaN-on-SiC Process Convergence | Single-die integration collapses subsystem footprint for 5G massive MIMO beam steering. |
| AEC-Q100 Certification Investment | Automotive qualification extends supply agreement duration with German and Japanese OEMs. |
| MIIT Pre-Qualification Partnership | Chinese domestic equipment maker relationships anchor regional demand concentration. |
| MEMS Technology Acquisition | Radiation-hardened switch capabilities access aerospace budgets for low-earth-orbit constellations. |
Methodological Framework
Multi-period observation of FCC spectrum auction outcomes, MIIT equipment certification timelines, and GaAs foundry utilization rates anchored the trend analysis, supplemented by interviews with telecommunications infrastructure procurement directors, RF subsystem integrators, compound semiconductor process engineers, and automotive antenna system architects. SEC 10-K filings, ETSI harmonized standards documentation, customs trade data for SOI wafer imports, and carrier aggregation deployment databases provided secondary validation. Bottom-up shipment modeling and top-down semiconductor equipment capex analysis enabled triangulation.
Input-output matrices mapped switch unit volumes against 5G base station deployment trajectories, satellite terminal manufacturing pipelines, and connected vehicle production schedules across the projection horizon. Product type, application, end user, and technology segmentation dimensions structured the analytical framework. CAGRs derived from regression analysis of historical foundry output correlations with telecommunications infrastructure investment cycles. Millimeter-wave test engineering talent scarcity and multi-band certification matrix fragmentation served as industry-specific forecast modifiers.
Caveats apply where FCC spectrum reallocation timing, REACH metallurgy constraint enforcement, or GaAs substrate supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding carrier aggregation adoption rates and low-earth-orbit constellation deployment schedules. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
5G Millimeter Wave RF Transceiver Market
RF Components
Wi-Fi Module Market
RF Components
Flat Antenna Market
RF Components
Phase Shifters Market
RF Components
Embedded Antenna Systems Market
RF Components
High Reliability Oscillators Market
RF Components
Global RF Transceiver Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
RF Microwave MLCC Market
RF Components
Wireless Module Market
RF Components
Small Signal Mosfets Market
RF Components
Radio Frequency Duplexer Market
RF Components
RF Acoustic Wave Filters Market
RF Components
RF Components Market
RF Components
Multilayer Coupled Inductor Market
RF Components
RF Duplexer Market