
 Medical Terahertz Technology Market | 2026-2036
Medical Terahertz Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Terahertz Technology Market Foresight
German photonics manufacturers is pivoting toward medical-grade terahertz systems as clinical validation matures. HÜBNER GmbH & Co. KG leverages its precision optics heritage to dominate spectroscopic instrument production. TOPTICA Photonics AG anchors femtosecond laser supply chains critical for time-domain terahertz generation. Luna Innovations competes through fiber-coupled sensor architectures that reduce alignment complexity in hospital settings.
Medical terahertz technology employs electromagnetic radiation between microwave and infrared frequencies, typically spanning 0.1 to 10 THz, to probe biological tissues through non-ionizing photon-matter interactions that reveal water content, cellular density, and structural anomalies without DNA damage. Imaging systems lead installed base volumes while spectroscopic systems command premium pricing in oncology workflows where molecular fingerprinting differentiates malignant from benign tissue states. Non-contact delivery modes attract dermatology applications where patient throughput demands rapid scanning protocols, whereas handheld configurations remain nascent due to power-density constraints in portable form factors.
The FDA's breakthrough device program compresses premarket review cycles for terahertz-based cancer screening tools, while the EU Medical Device Regulation imposes clinical evidence thresholds that favor well-capitalized applicants with existing notified body relationships. ISO 13485 quality management certification functions as a de facto gate for hospital procurement committees evaluating capital imaging expenditures. Stakeholders must monitor reimbursement coding decisions by national health technology assessment bodies, as positive coverage determinations will determine whether terahertz platforms displace incumbent modalities or remain confined to research budgets.
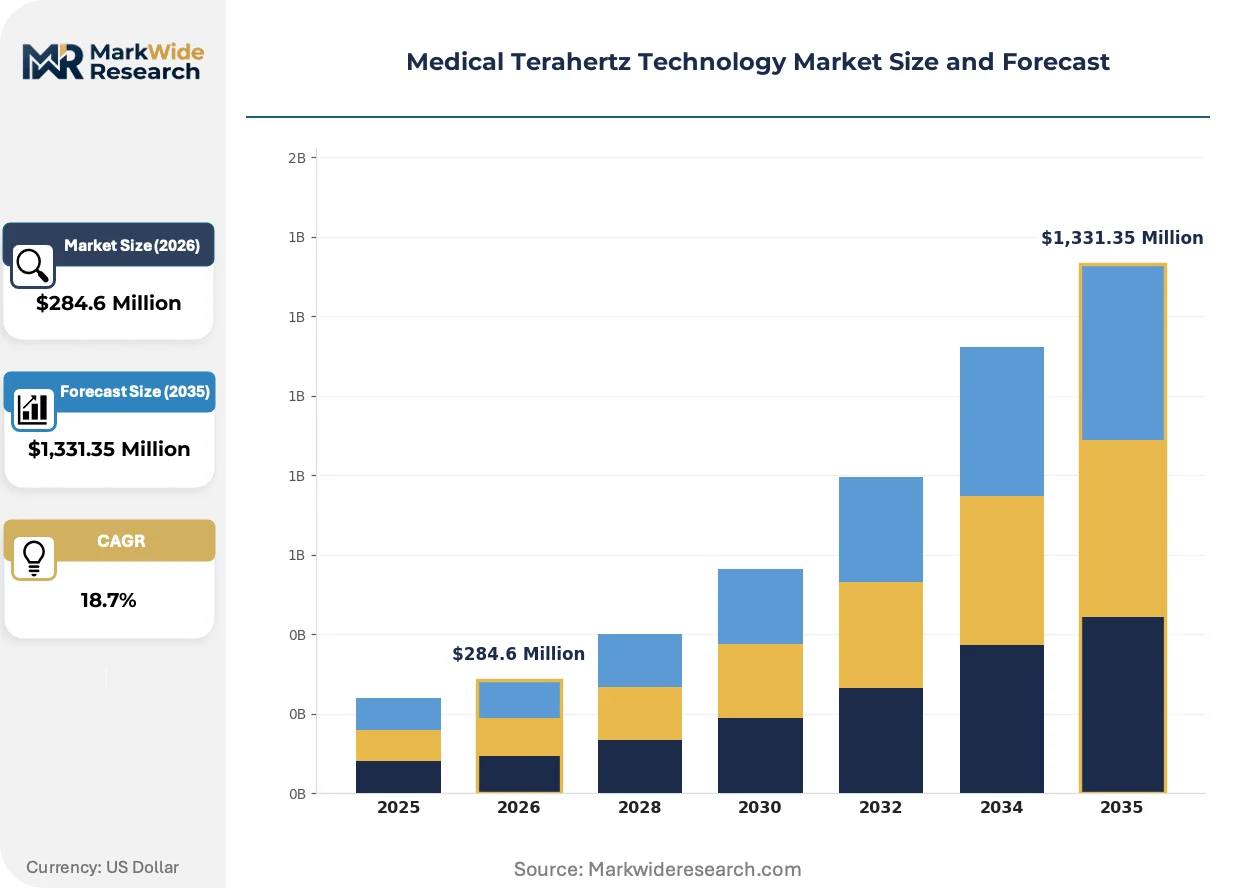
Market Dynamics
The FDA's breakthrough device designation pathway is compressing clinical validation timelines for terahertz-based cancer screening tools, while reimbursement pilot programs in Germany and Japan determine whether these systems displace incumbent imaging modalities or remain confined to research budgets.
Growth Catalysts
- Non-ionizing detection protocols:Terahertz radiation probes biological tissues without DNA damage, attracting oncology departments seeking safer alternatives to X-ray-based screening for early-stage tumor detection.
- Japan's reimbursement pilot programs:METI-backed health technology assessments in Tokyo and Osaka hospital clusters are creating precedents for insurance coverage of terahertz dermatology workflows.
- Water-content sensitivity:The technology's unique responsiveness to cellular hydration levels enables differentiation between malignant and benign tissue states in real-time spectroscopic analysis.
Market Restraints
- Femtosecond laser supply concentration:German and Austrian specialty laser manufacturers control critical time-domain terahertz generation components, creating single-source vulnerability for system integrators.
- EU MDR clinical evidence thresholds:The Medical Device Regulation imposes documentation burdens that favor well-capitalized applicants with existing notified body relationships, excluding smaller photonics firms.
- Liquid helium cooling requirements:Cryogenic infrastructure dependence for high-sensitivity detectors limits deployment to tertiary medical centers with established physics research facilities.
Strategic Opportunities
- Point-of-care dermatology:Handheld terahertz scanners for rapid skin lesion assessment address throughput pressures in Australian and Spanish outpatient clinics where dermatologist shortages extend wait times.
- ISO 13485 certification acceleration:Quality management certification is functioning as a de facto procurement gate, creating first-mover advantage for early certified entrants into hospital capital expenditure committees.
- Pharmaceutical quality control integration:Terahertz spectroscopy is penetrating tablet coating thickness verification and polymorph identification workflows as FDA process analytical technology initiatives expand.
Industry Challenges
- Terahertz physicist talent scarcity:The intersection of photonics engineering and clinical translation requires specialized expertise concentrated in Munich, Cambridge, and Tsukuba research clusters, limiting workforce scalability.
- Legacy imaging system integration:PACS compatibility and radiologist workflow incorporation demands substantial software adaptation, extending hospital sales cycles beyond typical capital equipment procurement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Terahertz Technology Market |
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $1,331.35 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Spectroscopic Systems, Sensors, Accessories Therapy Area: Oncology, Dermatology, Neurology, Dentistry Delivery Mode: Contact-Based, Non-Contact, Handheld, Stationary End User: Hospitals, Research Institutions, Diagnostic Centers, Clinics |
| Companies Covered | HÜBNER GmbH & Co. KG, Luna Innovations, Advantest Corporation, TeTechS, Thorlabs, TeraView, TOPTICA Photonics AG, TeraSense Group, Menlo Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Terahertz Technology Market Shifts & Advancements
Photonics manufacturers are converging femtosecond laser architectures with fiber-coupled sensor designs to reduce alignment complexity in clinical environments, while regulatory bodies on three continents establish divergent evidence standards for novel medical imaging modalities.
Time-domain terahertz systems are unifying spectroscopic and imaging capabilities within single platforms, enabling simultaneous morphological and molecular fingerprinting. Oncology departments at MD Anderson Cancer Center and Charité Berlin are piloting these hybrid configurations for intraoperative margin assessment. This unification is compressing capital expenditure cycles by eliminating the need for separate instrument purchases.
The EU Medical Device Regulation's clinical evidence requirements are forcing terahertz device developers to establish prospective patient registries earlier in product lifecycles. Manufacturers with existing ISO 13485 quality systems are leveraging notified body relationships to accelerate conformity assessments. Dermatology applications face the steepest documentation burdens due to the regulation's emphasis on equivalence arguments for novel energy-based devices.
Hospital procurement committees are bundling terahertz system acquisitions with multi-year service contracts and radiologist training programs. This shift displaces traditional equipment-only purchasing models in the United States and Germany. Academic medical centers with established photonics research partnerships are securing preferential pricing through volume commitments and clinical trial participation agreements.
Medical Terahertz Technology Market Segmentation
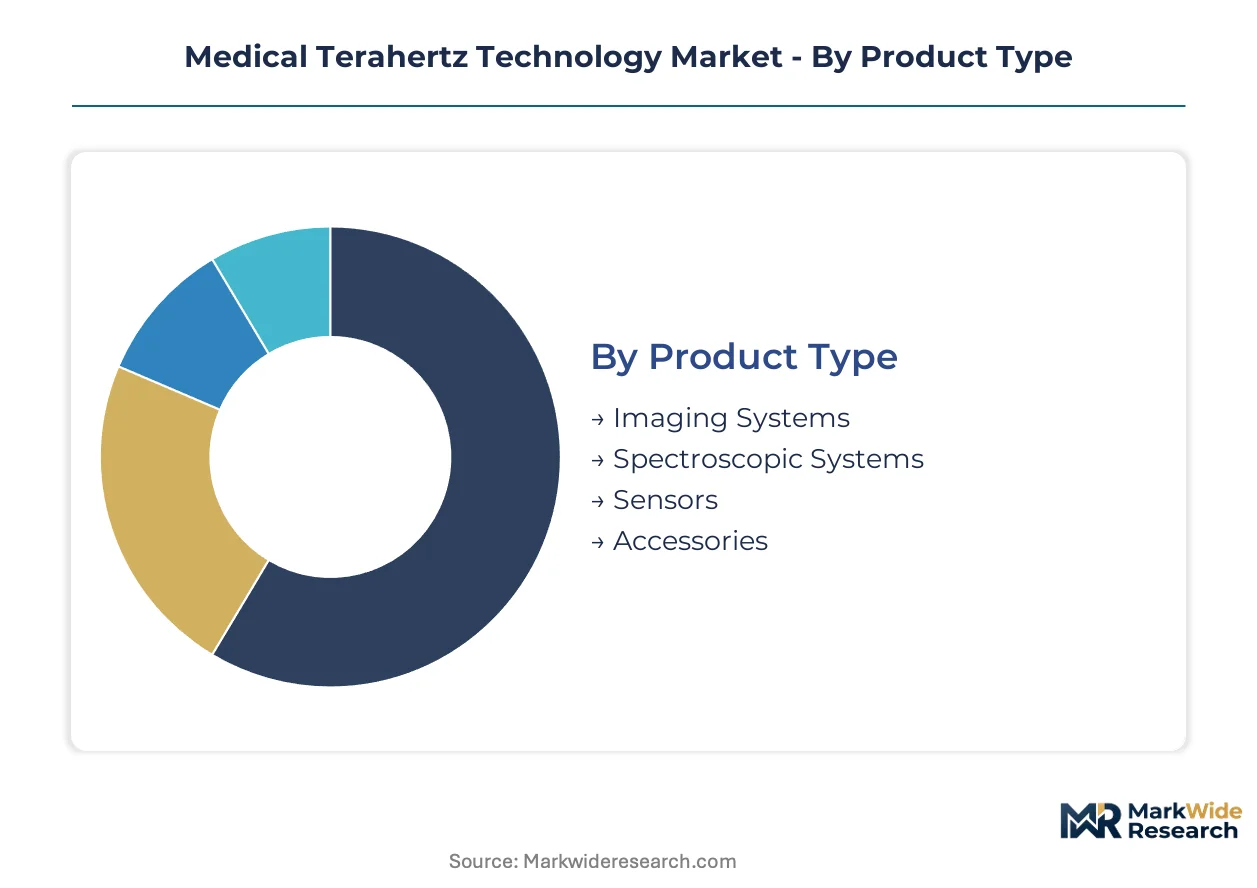
Segmentation in medical terahertz technology reveals distinct procurement patterns across product architectures and clinical settings. System integrators configure offerings differently for tertiary hospitals versus outpatient clinics, while reimbursement pathways vary sharply by therapy area.
Product Type:
Imaging systems dominate standalone capital purchases, whereas spectroscopic modules increasingly embed into multimodal oncology platforms.
- Imaging Systems:Time-domain and frequency-domain architectures generate two-dimensional or three-dimensional tissue maps through terahertz pulse reflection. MD Anderson Cancer Center and Charité Berlin are piloting hybrid configurations for intraoperative margin assessment. These systems lead installed base volumes in tertiary medical centers with established physics research facilities.
- Spectroscopic Systems:Molecular fingerprinting platforms differentiate malignant from benign tissue states through water-content sensitivity and cellular density analysis. German manufacturers leverage precision optics heritage to command premium pricing in oncology workflows where real-time diagnostic certainty justifies capital expenditure.
- Sensors:Fiber-coupled detector arrays reduce alignment complexity in hospital settings.
- Accessories:Cryogenic cooling units and calibration standards complete system configurations.
Imaging systems lead volumes today; spectroscopic systems are gaining share fastest.
Therapy Area:
Oncology commands the highest per-procedure reimbursement rates, while dermatology applications face steeper EU MDR documentation burdens due to equivalence arguments for novel energy-based devices.
- Oncology:Early-stage tumor detection protocols exploit terahertz radiation's non-ionizing properties to screen without DNA damage. The FDA's breakthrough device designation pathway accelerates clinical validation timelines for cancer screening tools, concentrating demand in United States and German hospital clusters.
- Dermatology:Rapid skin lesion assessment addresses throughput pressures in Australian and Spanish outpatient clinics where specialist shortages extend wait times. METI-backed reimbursement pilot programs in Tokyo and Osaka are creating precedents for insurance coverage of terahertz dermatology workflows.
- Neurology:Blood-brain barrier research applications remain confined to academic medical centers.
- Dentistry:Enamel density mapping attracts limited pilot interest in Japanese university hospitals.
Oncology leads volumes today; dermatology is expanding most quickly.
Delivery Mode:
Stationary platforms anchor hospital capital budgets, while handheld configurations remain nascent due to power-density constraints in portable form factors.
- Non-Contact:Rapid scanning protocols enable high patient throughput in dermatology applications where physical probe contact risks cross-contamination or patient discomfort. Australian outpatient clinics are prioritizing these configurations to address specialist shortage pressures.
- Contact-Based:Stabilized probe-tissue interfaces improve signal fidelity for spectroscopic analysis in oncology workflows requiring molecular precision. German photonics manufacturers optimize these systems for integration with existing surgical navigation platforms.
- Handheld:Battery-powered prototypes target point-of-care deployment in resource-limited settings.
- Stationary:Gantry-mounted systems dominate research institution procurement.
Stationary systems lead volumes today; non-contact configurations are climbing the fastest.
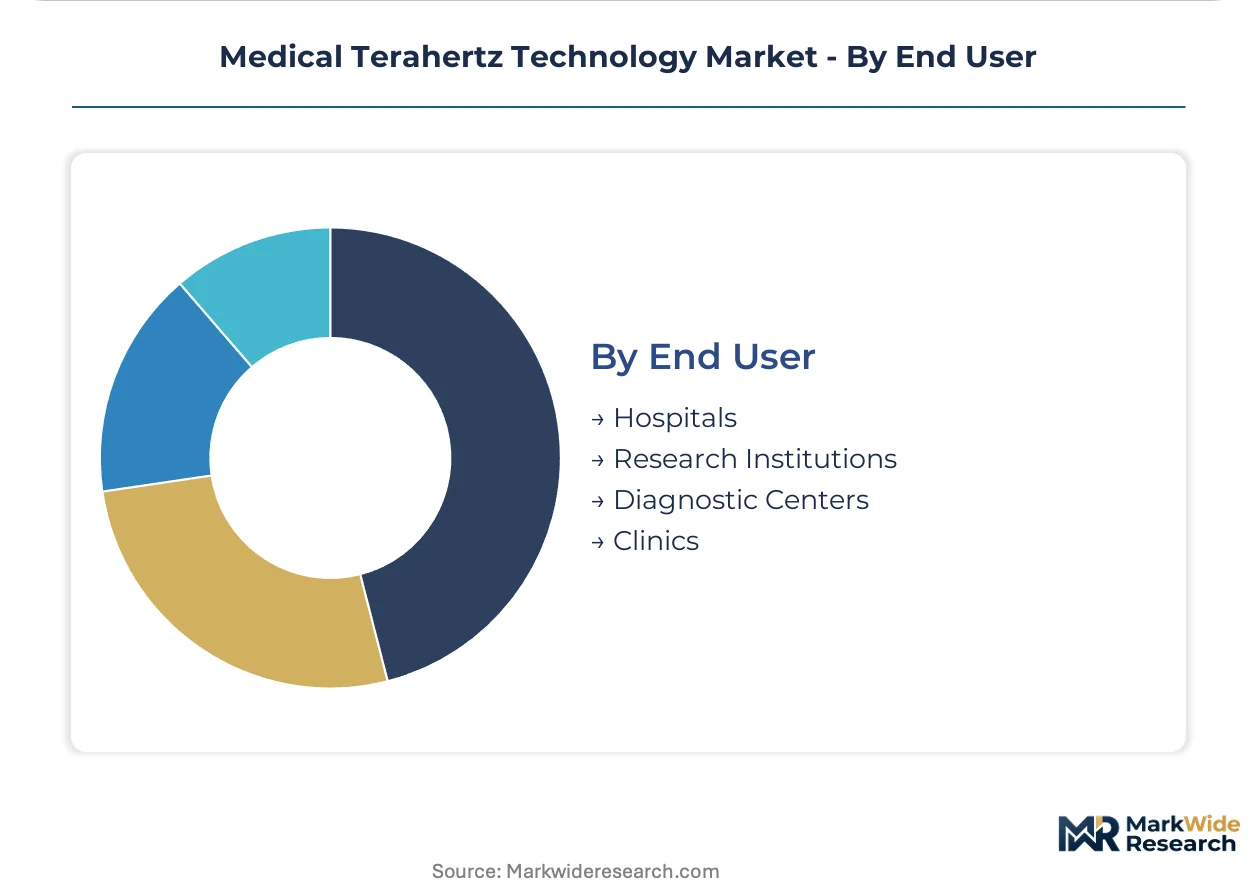
End User:
Hospital procurement committees now bundle terahertz acquisitions with multi-year service contracts, displacing equipment-only purchasing models that previously favored research institutions.
- Hospitals:Tertiary medical centers with established photonics research partnerships secure preferential pricing through volume commitments and clinical trial participation agreements. ISO 13485 quality management certification functions as a de facto gate for capital imaging expenditure committees.
- Research Institutions:Academic medical centers in Munich, Cambridge, and Tsukuba clusters concentrate terahertz physicist talent for prototype validation. These facilities tolerate liquid helium cooling requirements that limit broader clinical deployment.
- Diagnostic Centers:Specialized imaging facilities are emerging in German and Japanese metropolitan areas.
- Clinics:Outpatient settings drive demand for compact, workflow-integrated configurations.
Hospitals lead volumes today; diagnostic centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics concentrate terahertz system production where FDA breakthrough pathways and EU MDR compliance costs diverge most sharply. German and Japanese manufacturers exploit this gap by anchoring precision optics production domestically while targeting US clinical validation programs.
United States
MD Anderson Cancer Center and Memorial Sloan Kettering anchor early-stage tumor detection demand through intraoperative margin assessment pilots. FDA breakthrough device designations compress premarket review cycles for oncology screening tools. Boston and Austin photonics clusters concentrate venture-backed terahertz startups seeking hospital procurement contracts.
Germany
Charité Berlin and University Hospital Heidelberg drive spectroscopic system demand for molecular fingerprinting workflows. EU MDR clinical evidence thresholds favor well-capitalized applicants with established notified body relationships. Munich and Jena precision optics clusters dominate femtosecond laser supply chains for time-domain generation.
Japan
Tokyo and Osaka hospital clusters pilot METI-backed reimbursement programs for dermatology workflows. PMDA consultation pathways accelerate novel medical imaging modality approvals for domestic manufacturers. Tsukuba research institutions concentrate terahertz physicist talent for prototype-to-clinical translation.
United Kingdom
Cambridge and Oxford academic medical centers tolerate liquid helium cooling requirements for blood-brain barrier research applications. MHRA regulatory science strategy prioritizes non-ionizing diagnostic innovation through early engagement programs. London hospital procurement committees bundle terahertz acquisitions with multi-year radiologist training contracts.
Australia
Melbourne and Sydney outpatient clinics prioritize non-contact scanning configurations to address dermatologist shortage pressures. TGA priority review pathways target cancer screening technologies with demonstrated safety profiles. Perth medical physics research facilities anchor spectroscopic system validation for skin lesion assessment protocols.
Medical Terahertz Technology Market Competitive Landscape
German producers anchor the precision-optics tier; US specialists hold fiber-coupled sensor architectures. The vendor base splits between consolidated photonics conglomerates with ISO 13485 certification and fragmented component suppliers facing EU MDR documentation burdens. Two strategic archetypes dominate: vertically integrated system integrators controlling laser generation through detector assembly, and modular platform vendors outsourcing cryogenic cooling subsystems. Capacity expansion and notified body relationship acquisition represent the dominant competitive moves.
Within the German precision-optics tier, HÜBNER GmbH & Co. KG and TOPTICA Photonics AG exemplify vertically integrated archetypes with heritage in femtosecond laser architectures. Luna Innovations occupies a position among North American specialists emphasizing fiber-coupled designs that reduce hospital alignment complexity. These three anchors represent divergent technical bets on time-domain versus frequency-domain system configurations.
| Leading Market Players |
|---|
| HÜBNER GmbH & Co. KG |
| Luna Innovations |
| Advantest Corporation |
| TeTechS |
| Thorlabs |
| TeraView |
| TOPTICA Photonics AG |
| TeraSense Group |
| Menlo Systems |
| Others |
Supply & Pricing Matrix
Terahertz physicist talent scarcity concentrated in Munich, Cambridge, and Tsukuba research clusters widens labor-cost differentials between German precision-optics manufacturers and emerging Asian assembly operations, compressing pricing-tier spreads for spectroscopic systems versus fiber-coupled imaging platforms.
Pricing Analysis
Distributor margins for German femtosecond laser components typically absorb 15-25 points before hospital procurement committees negotiate system-level contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification status and after-sales service bundling. Pricing pressure stems from METI-backed Japanese reimbursement pilots demanding volume commitments in exchange for coverage precedents. Academic medical centers with established photonics research partnerships exhibit lowest price sensitivity due to grant-funded capital cycles, while Australian outpatient clinics face acute budget constraints from dermatologist shortage-driven throughput mandates.
Supply Chain Analysis
Workforce availability for precision optics grinding and femtosecond laser alignment concentrates in German Jena and Munich manufacturing corridors, with secondary talent pools in Austrian Vienna and Swiss Zurich satellite facilities. Critical inputs draw from gallium arsenide wafer foundries in Taiwan, specialty optical glass from Schott AG in Mainz, and cryogenic cooling subsystems sourced from Japanese Osaka engineering clusters. Single-source vulnerability pervades time-domain terahertz generation components controlled by German and Austrian specialty laser manufacturers. Distribution runs through hospital GPO contracts in the United States, direct-to-institution sales in Germany, and METI-coordinated procurement consortia in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
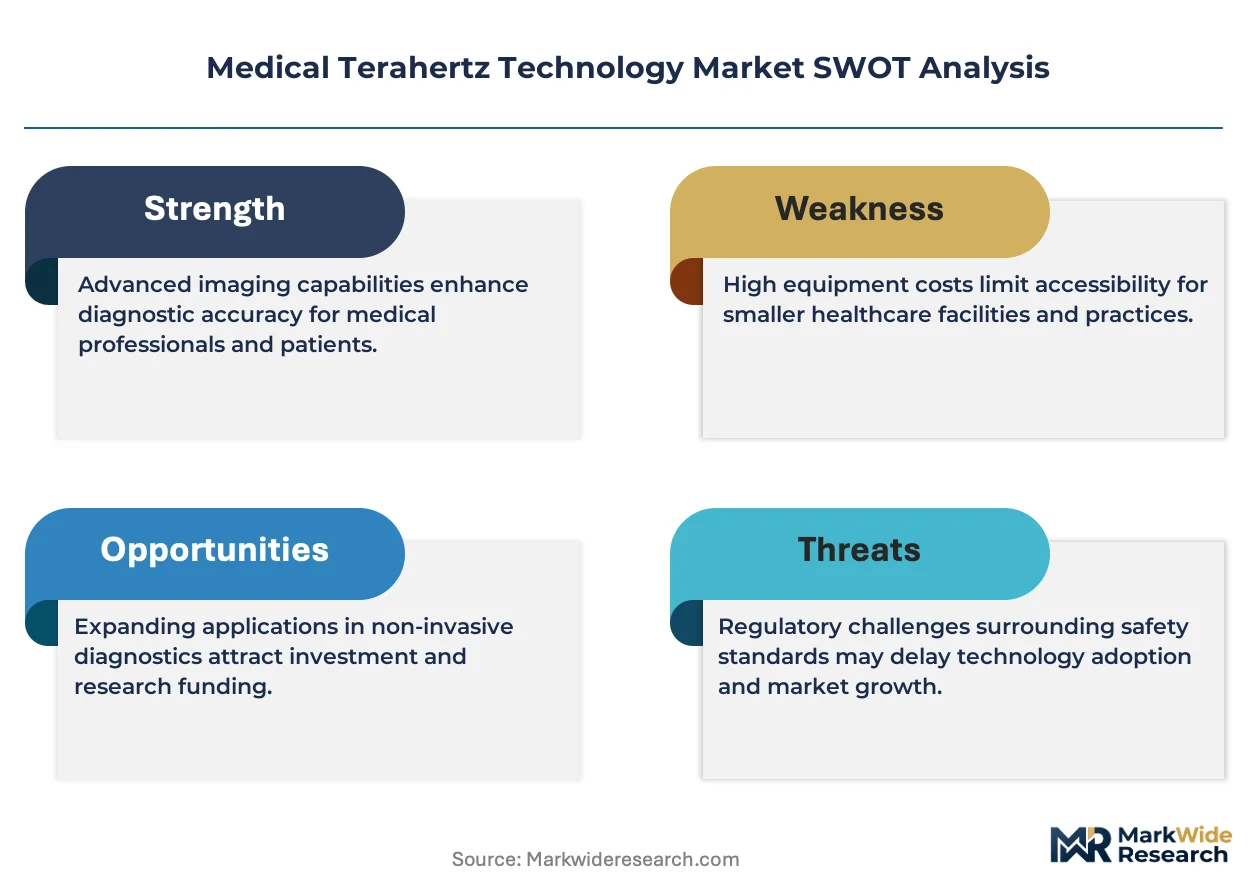
This market functions as a geographic-arbitrage play where FDA breakthrough device designation compresses clinical validation timelines relative to EU MDR documentation burdens, rewarding manufacturers that anchor precision-optics production in Germany while targeting US hospital procurement contracts.
For Market Incumbents: Lock in femtosecond laser supply agreements with TOPTICA Photonics AG and HÜBNER GmbH & Co. KG before capacity constraints intensify, while accelerating ISO 13485 certification for fiber-coupled sensor architectures to preempt Luna Innovations' hospital alignment-complexity advantage. Defend against emerging Asian modular-platform vendors by embedding spectroscopic modules into multimodal oncology platforms at MD Anderson Cancer Center and Charité Berlin, compressing capital expenditure cycles through hybrid configuration unification. For New Entrants and Emerging Players: Capture point-of-care dermatology white space in Australian Melbourne and Sydney outpatient clinics where non-contact scanning configurations address specialist shortage pressures with minimal PACS integration burden. Target METI-backed reimbursement pilot programs in Tokyo and Osaka as the most penetrable geography, leveraging PMDA consultation pathways for accelerated novel medical imaging modality approvals. Pursue radiologist training program bundling as the primary go-to-market angle, displacing equipment-only purchasing models. For Investors and Strategic Acquirers: Photonics conglomerates with existing notified body relationships are the most active acquirer in this space, consolidating fragmented component suppliers facing EU MDR clinical evidence thresholds. Long-term viability hinges on reimbursement coding decisions by national health technology assessment bodies determining whether terahertz platforms displace incumbent modalities or remain confined to research budgets. Target acquisition archetype: fiber-coupled sensor specialists with hospital procurement committee traction. Monitor FDA breakthrough device designation grants to terahertz-based cancer screening tools as the critical inflection signal for commercial deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Compresses premarket review cycles for MD Anderson Cancer Center pilots. |
| ISO 13485 Certification Acceleration | Functions as de facto gate for German hospital capital expenditure committees. |
| Hospital System Partnership | Charité Berlin and Memorial Sloan Kettering anchor intraoperative margin assessment demand. |
| Reimbursement Strategy | METI-backed pilot programs in Tokyo and Osaka create insurance coverage precedents. |
| Software Companion Development | PACS compatibility and radiologist workflow integration extends hospital sales cycles. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down femtosecond laser supply tracking forms the analytical core, combining primary interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and terahertz physicists in Munich and Tsukuba research clusters with secondary validation against FDA 510(k) filings, PMDA consultation pathway records, METI health technology assessment reports, and hospital procurement database extracts.
Historical trendline analysis of time-domain versus frequency-domain system adoption across oncology and dermatology therapy areas informs the projection framework, with segmentation modeling across product architecture, delivery mode, and end-user type throughout the forecast period. CAGRs derive from installed base growth trajectories and replacement cycle assumptions, incorporating reimbursement pilot program expansion rates and ISO 13485 certification velocity as industry-specific forecast inputs.
FDA breakthrough device designation delays, EU MDR notified body capacity constraints, and liquid helium supply disruptions are the dominant revision risks. Practitioners should monitor PMDA approval velocity, German health technology assessment body coverage determinations, and cryogenic infrastructure investment announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Nanoelectronics Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Next-Generation Transistors Market
Emerging and Next Generation Technologies
Lab on Chips Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
Transparent Solar Cells Market
Emerging and Next Generation Technologies
Piezoelectric Nanogenerator Market
Emerging and Next Generation Technologies
Swarm Intelligence Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Deep Tech Market