
 Semiconductor Packaging Material Market | 2026-2036
Semiconductor Packaging Material Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Packaging Material Market Outlook
JEDEC qualification for high-temperature lead-free solder is redrawing the competitive map for advanced substrate suppliers. DuPont sustains R&D intensity across polyimide dielectric formulations for high-density interconnects. Henkel anchors European supply chains with localized epoxy molding compound production. KYOCERA dominates ceramic package output for power modules and RF applications.
Semiconductor packaging material encompasses the substrates, die-attach compounds, encapsulants, and interconnect metals that physically protect integrated circuits while enabling electrical and thermal pathways. Flip-chip underfill materials require precise control of filler loading and coefficient of thermal expansion to manage thermomechanical stress during temperature cycling. Wire bond segments remain mature with stable margin pools in gold and copper bonding wire, while chip-on-wafer formats capture expanding demand from high-bandwidth memory stacking in server accelerators. Epoxy formulations lead volume consumption, though ceramic substrates command premium positioning in automotive and telecommunications power packages.
The EPA regulates hazardous air pollutant emissions from semiconductor manufacturing facilities under the National Emission Standards for Hazardous Air Pollutants, directly affecting encapsulant and solvent-based adhesive formulation choices in U.S. packaging operations. REACH compliance in Europe restricts candidate substance use in polymer hardeners and flame retardants, forcing material suppliers to reformulate or face market exclusion. Japan's METI promotes domestic packaging ecosystem resilience through supply chain security subsidies. Stakeholders must monitor how divergent chemical safety regimes between the United States, European Union, and East Asian economies reshape qualification timelines and regional sourcing strategies.
Market Dynamics
The semiconductor packaging material sector is reconfiguring around heterogeneous integration architectures, where chiplet disaggregation and 2.5D/3D stacking architectures are compressing traditional substrate hierarchy and forcing material suppliers to qualify for finer pitch interconnects and thermal management regimes simultaneously.
Growth Catalysts
- EU Chips Act capital deployment:Subsidy pools in Germany, France, and Italy are accelerating packaging facility construction, directly lifting substrate and encapsulant procurement volumes for advanced node production.
- High-bandwidth memory stacking:Server accelerator demand from AI training clusters is depleting chip-on-wafer underfill inventories and forcing capacity expansion at specialty chemical suppliers.
- Automotive ADAS penetration:Safety system mandates in the European Union and Japan are multiplying ceramic package consumption for radar modules and LiDAR sensor arrays.
Market Restraints
- High-purity alumina supply concentration:Japanese and South Korean ceramic substrate manufacturers control over 70% of sintering-grade powder supply, creating vulnerability for European and North American packaging operations.
- REACH substance restrictions:ECHA candidate list updates are forcing reformulation of brominated flame retardants in epoxy molding compounds, extending qualification cycles by 18-24 months.
- Gold bonding wire cost volatility:Precious metal price swings compress margins in mature wire bond segments where copper substitution remains incomplete due to oxidation reliability concerns.
Strategic Opportunities
- India semiconductor mission:PLI scheme disbursements and state-level infrastructure commitments in Gujarat and Karnataka are creating first-mover advantages for substrate laminators and die-attach adhesive suppliers establishing local compounding.
- Glass core substrate emergence:Interposer replacement using low-CTE glass panels enables finer line/space routing than organic alternatives, opening qualification windows for specialized glass fabricators and surface treatment chemical providers.
- Automotive 800V electrification:Silicon carbide power module packaging is generating premium demand for silver-sintered die-attach pastes and high-thermal-conductivity ceramic substrates in traction inverter applications.
Industry Challenges
- JEDEC qualification timeline compression:Accelerated product roadmaps from cloud service providers are compressing thermal cycling and high-temperature storage test protocols, straining reliability engineering bandwidth at material suppliers.
- Cross-functional packaging engineering scarcity:The intersection of semiconductor fabrication, materials science, and thermal-mechanical simulation expertise remains concentrated at Taiwanese and South Korean research institutes, limiting talent pools for Western facility expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Packaging Material Market |
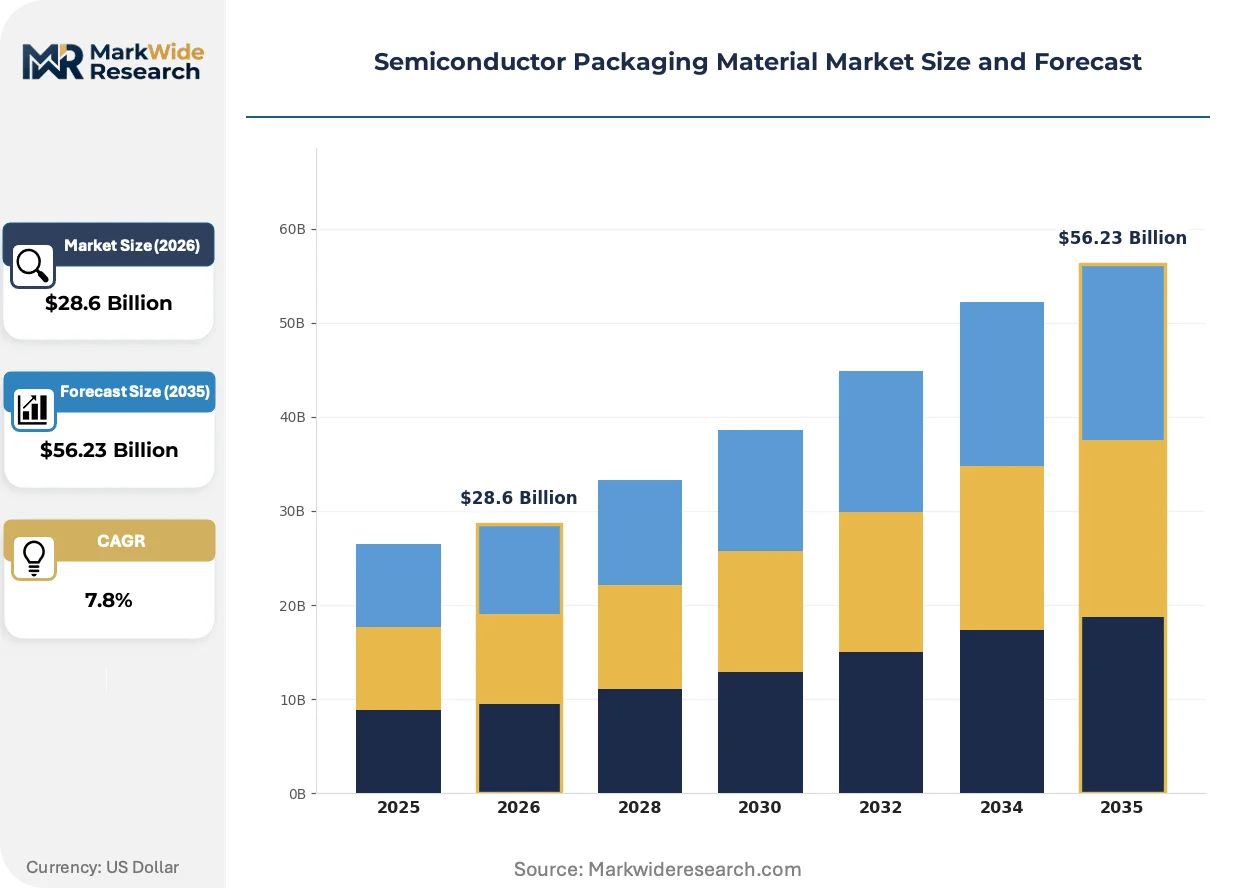
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $56.23 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Chip, Ball Grid Array, Chip On Wafer, Wire Bond Material Type: Epoxy, Polyimide, Ceramic, Metal End User: Consumer Electronics, Automotive, Telecommunications, Industrial Application: Smartphones, Servers, Tablets, IoT Devices |
| Companies Covered | Amkor Technology, DuPont, Henkel, Honeywell, KYOCERA, LG Chem, BASF, Hitachi Chemical, Heraeus Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Packaging Material Market Strategic Shifts
Material innovation is converging on thermal-mechanical co-design, where substrate suppliers, assembly houses, and end-equipment makers simulate package behavior as integrated systems rather than sequential handoffs.
Hybrid bonding technology is decomposing the traditional flip-chip bump paradigm by enabling direct copper-to-copper interconnects at sub-10 micron pitch without underfill. Memory manufacturers in South Korea and Taiwan are adopting this for high-bandwidth memory stacks. The elimination of solder microbumps and capillary underfill is compressing the addressable market for conventional epoxy formulations while expanding atomic-layer deposition and plasma surface activation chemical demand.
REACH authorization requirements for substances of very high concern are forcing systematic substitution of legacy hardeners and curing agents in polymer formulations. European encapsulant suppliers are accelerating bio-based epichlorohydrin and non-bisphenol-A resin development to preempt regulatory exclusion. Automotive power module packaging faces the steepest compliance burden, as underhood temperature requirements conflict with restricted substance lists.
Consolidated procurement by hyperscale cloud operators is compressing supplier bases and extending contract durations. Microsoft, Amazon Web Services, and Google are negotiating direct material qualification rights with substrate and interconnect suppliers, bypassing traditional OSAT intermediaries. This concentration is most visible in North American server supply chains, where captive packaging capacity at Intel and AMD is being supplemented by long-term offtake agreements with Taiwanese substrate specialists.
Semiconductor Packaging Material Market Segmentation
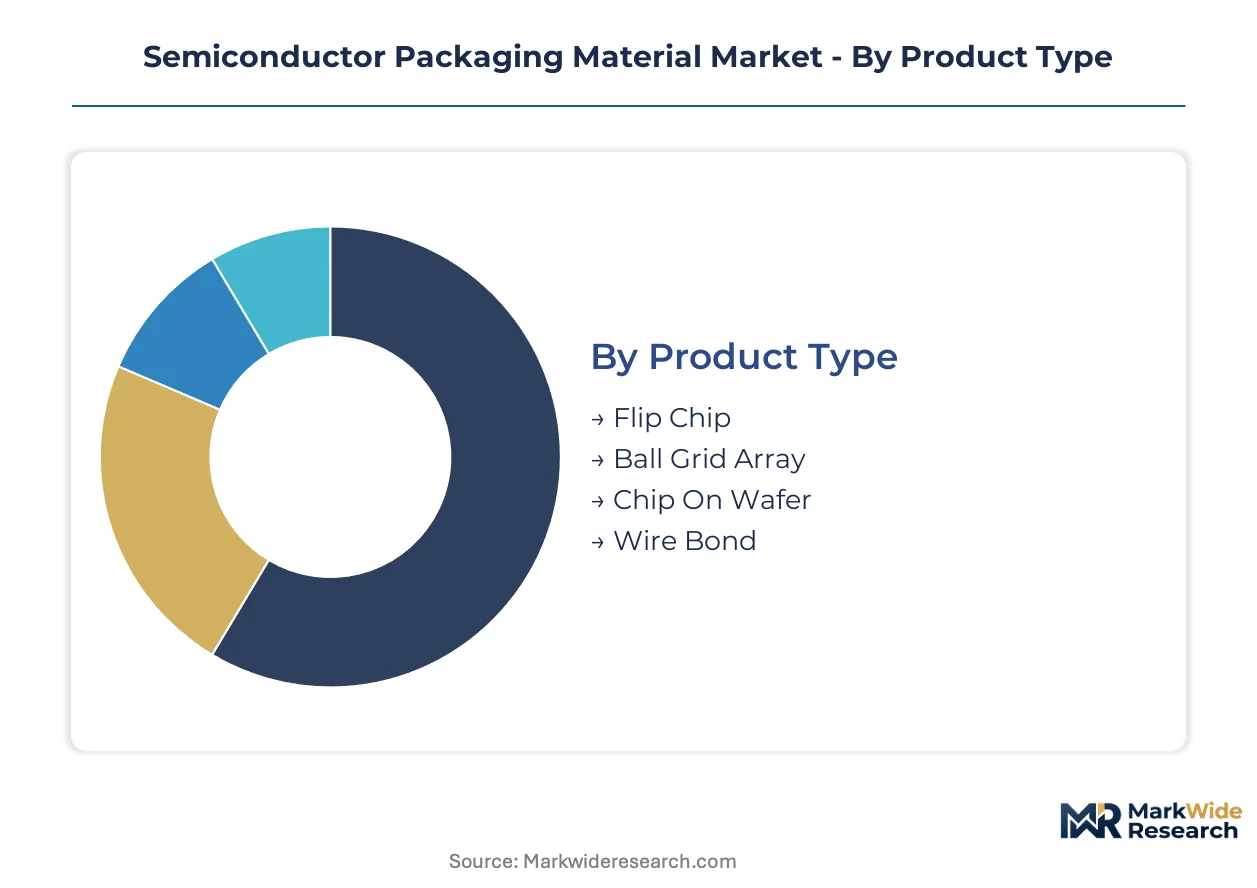
Packaging material selection determines thermal cycling reliability, electrical performance, and regulatory compliance pathways. Each segmentation axis reveals distinct procurement patterns and qualification barriers that suppliers must navigate across automotive, telecommunications, and consumer end-uses.
Product Type:
REACH substance restrictions and JEDEC qualification protocols differentiate product categories by reformulation burden and test cycle length.
- Flip Chip:Underfill materials with precisely controlled filler loading manage thermomechanical stress at bump interconnects. High-bandwidth memory stacking in AI server accelerators concentrates demand in Taiwan and South Korea, where assembly houses face compressed thermal cycling protocols from cloud service providers.
- Ball Grid Array:Organic substrates with buildup dielectric layers enable high I/O density for processor packages. German and French packaging facility expansions under EU Chips Act subsidies are lifting laminate substrate procurement volumes for advanced node production.
- Chip On Wafer:Temporary bonding adhesives and laser debonding materials support wafer-level fan-out processing.
- Wire Bond:Gold and copper bonding wire segments face precious metal price volatility and incomplete copper substitution due to oxidation reliability concerns.
Flip Chip handles the majority of throughput; Chip On Wafer is expanding most quickly on share.
Material Type:
Cost tiers separate commodity epoxy formulations from ceramic substrates commanding premium positioning in power electronics.
- Epoxy:Molding compounds dominate volume consumption but face REACH-driven reformulation of brominated flame retardants. European suppliers are accelerating bio-based epichlorohydrin development to preempt ECHA candidate list exclusion.
- Ceramic:High-purity alumina and aluminum nitride substrates deliver thermal conductivity for silicon carbide power modules. Japanese and South Korean manufacturers control over 70% of sintering-grade powder supply, creating supply vulnerability for Western packaging operations.
- Polyimide:Dielectric formulations for high-density interconnects require sustained R&D intensity to achieve fine-line patterning.
- Metal:Silver-sintered die-attach pastes and lead-free solder alloys enable high-temperature operation under automotive underhood conditions.
Epoxy generates the highest absolute volume; Ceramic captures the steepest expansion trajectory in automotive electrification applications.
End User:
Application-specific reliability requirements drive material specification divergence across temperature ranges and operating environments.
- Automotive:ADAS mandates in the European Union and Japan are multiplying ceramic package consumption for radar modules and LiDAR sensor arrays. 800V electrification is generating premium demand for silver-sintered die-attach pastes in traction inverter packaging.
- Consumer Electronics:Smartphone and tablet form factors prioritize thin-profile substrate laminates with fine-pitch interconnect capability. Assembly houses in China and Vietnam face cost pressure that constrains material specification upgrades.
- Telecommunications:Base station power amplifiers and optical transceivers require hermetic ceramic packages with RF performance stability.
- Industrial:Extended temperature range requirements and long service life expectations favor conservative material qualification strategies.
Consumer Electronics maintains the largest installed base; Automotive is gaining share fastest on electrification and safety system penetration.
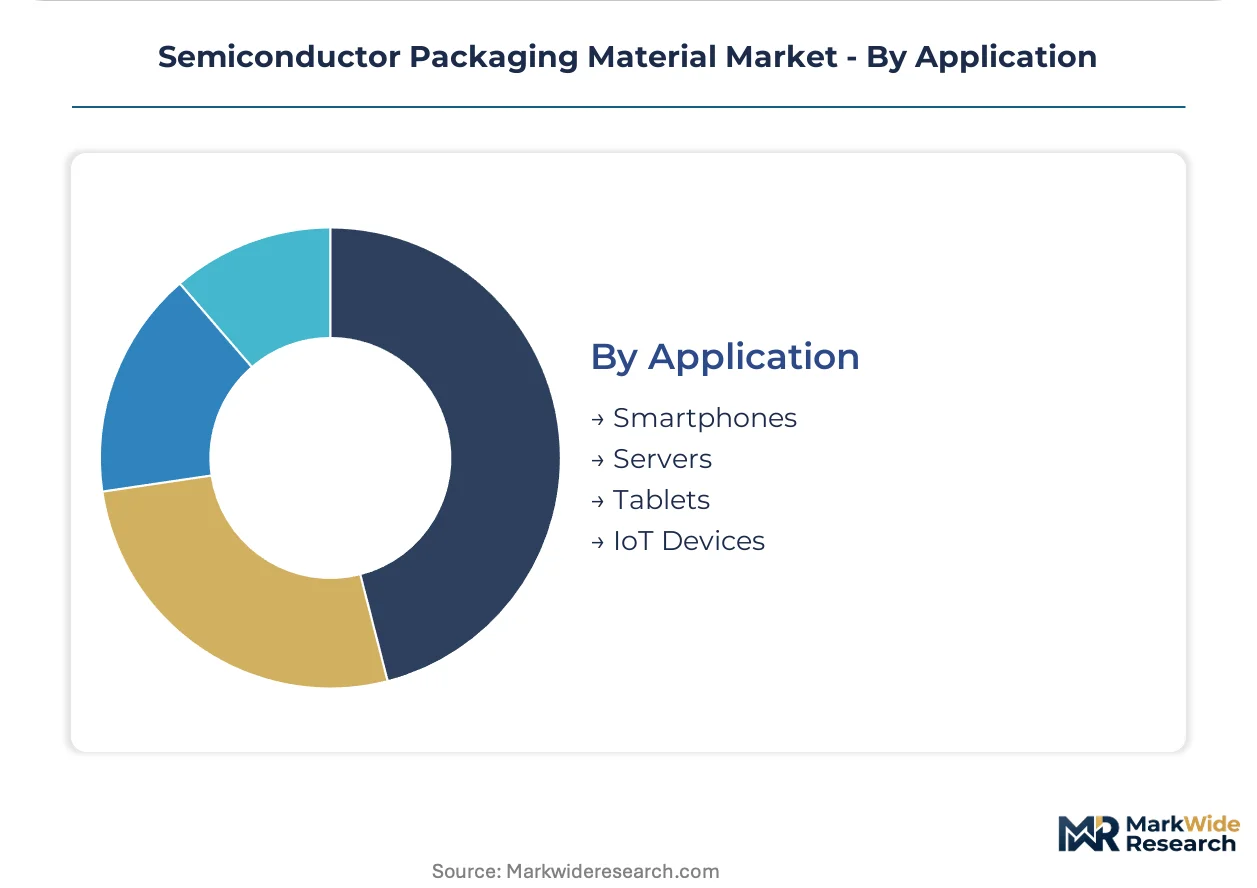
Application:
Server infrastructure buildouts and mobile device refresh cycles create asynchronous demand peaks that strain material inventory positioning.
- Servers:AI training clusters are depleting chip-on-wafer underfill inventories and forcing capacity expansion at specialty chemical suppliers. Hyperscale operators including Microsoft, Amazon Web Services, and Google are negotiating direct material qualification rights with substrate suppliers.
- Smartphones:Annual flagship release cycles drive predictable but concentrated demand for organic substrate laminates and fine-pitch solder materials.
- Tablets:Stagnant unit volumes limit material consumption growth despite premium positioning in enterprise and education segments.
- IoT Devices:Distributed sensor networks favor low-cost wire bond and ball grid array formats with relaxed thermal performance requirements.
Servers absorb the most advanced material formulations; IoT Devices represent the highest-volume, lowest-margin consumption pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators in the United States concentrate procurement of advanced substrate laminates and underfill materials for AI server infrastructure. German automotive OEMs and Japanese electronics conglomerates anchor ceramic package consumption for power modules and radar systems. Taiwanese and South Korean assembly houses dominate flip-chip and 2.5D/3D packaging throughput.
United States
Microsoft, Amazon Web Services, and Google negotiate direct material qualification rights with substrate suppliers for AI training clusters. EPA National Emission Standards for Hazardous Air Pollutants constrain encapsulant formulation choices in domestic packaging operations. Arizona and Texas host Intel and TSMC advanced packaging facility expansions lifting local die-attach adhesive procurement.
Germany
EU Chips Act subsidy pools accelerate packaging facility construction in Dresden and Munich, directly lifting laminate substrate volumes. REACH compliance restricts brominated flame retardants in epoxy molding compounds, forcing 18-24 month reformulation cycles. Bavaria concentrates automotive power module packaging demand for silicon carbide traction inverters.
Japan
METI supply chain security subsidies promote domestic packaging ecosystem resilience against import dependency. JIS standards and automotive underhood temperature requirements drive ceramic substrate specification for radar modules. Kyushu and Nagoya industrial corridors host concentrated sintering-grade alumina powder production for global ceramic package output.
South Korea
Memory manufacturers adopt hybrid bonding for high-bandwidth memory stacks, displacing conventional underfill demand. MFDS chemical safety protocols align with REACH substance restrictions for polymer hardener qualification. Seoul Capital Area and Busan-Ulsan corridors concentrate chip-on-wafer underfill consumption from AI server accelerator production.
Taiwan
Flip-chip and 2.5D/3D packaging demand concentrates at TSMC and ASE facilities serving global fabless semiconductor customers. Local environmental regulations govern solvent-based adhesive emissions from high-volume assembly operations. Hsinchu Science Park anchors the world's densest concentration of advanced substrate qualification and thermal-mechanical reliability testing capacity.
Semiconductor Packaging Material Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with polymer formulation heritage and specialized ceramic fabricators with sintering expertise. The supplier base organizes into three tiers: integrated material science conglomerates commanding premium positioning, mid-scale encapsulant specialists serving regional OSAT networks, and niche ceramic powder producers controlling critical raw material supply. Dominant competitive moves include capacity expansion at EU Chips Act beneficiary sites and strategic partnerships between substrate laminators and hyperscale cloud operators for direct qualification pathways.
Within the integrated chemical conglomerate tier, DuPont and Henkel exemplify sustained R&D intensity across polyimide dielectric and epoxy molding compound formulations respectively. KYOCERA occupies a position representing specialized ceramic fabrication dominance for power module and RF package applications. These three anchors illustrate how material suppliers navigate divergent regulatory regimes while qualifying for heterogeneous integration architectures.
| Leading Market Players |
|---|
| Amkor Technology |
| DuPont |
| Henkel |
| Honeywell |
| KYOCERA |
| LG Chem |
| BASF |
| Hitachi Chemical |
| Heraeus Holding |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between hyperscale cloud operators and Taiwanese substrate specialists lock in multi-year supply access while providing price visibility against volatile precious metal and ceramic powder markets. These contracts insulate procurement volumes from spot market swings in gold bonding wire and high-purity alumina, though they expose buyers to technology obsolescence risk as hybrid bonding displaces conventional underfill.
Pricing Analysis
Cost-plus contracts with precious metal indexation dominate gold and copper bonding wire segments, tying unit pricing to London Bullion Market Association spot rates with quarterly adjustments. Price differentiation separates JEDEC-qualified automotive grades from consumer electronics tiers, with ceramic substrates for silicon carbide power modules commanding substantial premiums over standard epoxy laminates. Cost compression in mature wire bond formats is intensifying because copper substitution remains stalled by oxidation reliability failures. Consumer electronics assembly houses in Vietnam and China exhibit the highest price sensitivity, while automotive OEMs in Germany and Japan prioritize qualification stability over unit cost.
Supply Chain Analysis
Japan and South Korea anchor sintering-grade alumina powder production, controlling over seventy percent of global ceramic substrate feedstock. Raw material dependencies center on high-purity alumina, silver flake for sintered pastes, and bio-based epichlorohydrin for REACH-compliant epoxy formulations. Single-source vulnerability concentrates in Kyushu-based powder producers, where earthquake exposure threatens global ceramic package output. Distribution runs through captive supply agreements between OSATs and chemical conglomerates, bypassing traditional distributor networks for advanced node materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against hybrid bonding technology, which eliminates conventional underfill and solder microbump demand while expanding atomic-layer deposition chemical requirements.
For Market Incumbents: Consolidate formulation expertise around thermal-mechanical co-design capabilities, embedding reliability engineers directly at TSMC and Intel packaging facilities. Acquire specialized glass fabricators advancing low-CTE core substrates before qualification windows close to new entrants. Vertical integration into ceramic powder production mitigates Japanese supply concentration risk for Western facility expansions. For New Entrants and Emerging Players: JEDEC automotive qualification fast-tracks offer the most penetrable entry path, as incumbent epoxy suppliers struggle with eighteen-month REACH reformulation cycles. Target India's Gujarat and Karnataka semiconductor corridors, where PLI subsidies and absence of entrenched supplier relationships create first-mover advantages for die-attach adhesive compounders. Lead with silver-sintered paste formulations for 800V traction inverters, where automotive electrification outpaces incumbent R&D bandwidth. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale encapsulant specialists with existing EPA-compliant U.S. production assets and pending automotive qualifications. Long-term viability hinges on exposure to heterogeneous integration architectures rather than mature wire bond segments. Monitor hybrid bonding adoption rates at Samsung and SK Hynix as the critical inflection signal for conventional underfill demand destruction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Production | Reduces Japanese supply concentration vulnerability for European packaging facility expansions under EU Chips Act subsidies. |
| JEDEC Automotive Qualification Fast-Track | Accelerates market entry windows as REACH-driven reformulation extends incumbent epoxy qualification timelines. |
| Long-term Supply Agreement with Hyperscale Cloud Operators | Secures volume commitments from Microsoft and Amazon Web Services for AI server substrate procurement. |
| Green Manufacturing Transition to Bio-based Epichlorohydrin | Preempts ECHA candidate list exclusion for European encapsulant suppliers serving automotive power module packaging. |
| Joint Venture with Glass Core Substrate Fabricators | Captures qualification windows for low-CTE interposer replacement as Intel and AMD evaluate organic alternatives. |
Study Parameters
Initial hypotheses were tested against primary input from substrate laminator procurement directors, epoxy formulation R&D leads, OSAT reliability engineers, and ceramic powder plant managers, then refined through secondary validation against SEMI shipment data, EPA enforcement records, ECHA substance restriction updates, and SEC filings from listed chemical conglomerates. Bottom-up triangulation across material consumption volumes at TSMC, Intel, and Amkor facilities converged with top-down market sizing derived from semiconductor packaging equipment spend patterns.
Variance decomposition across product type, material grade tier, end-use industry, and regional regulatory cluster shaped the analytical framework throughout the projection horizon. CAGRs were derived from elasticity modeling against wafer start forecasts and content-per-package evolution for high-bandwidth memory stacks. Industry-specific inputs included JEDEC qualification pipeline tracking and EU Chips Act disbursement schedules for German and French packaging facility construction.
The analysis sits within stated boundaries; outcomes outside sustained EU subsidy deployment or accelerated hybrid bonding adoption at South Korean memory manufacturers would require recalibration. Forecasts reflect documented assumptions regarding REACH substance restriction timelines and EPA enforcement intensity. Recalibration cycles align with material shifts in JEDEC protocol updates and ECHA candidate list revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
System-On-Package Market
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
Global MEMS Packaging Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
Chip Carrier Socket Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Test Services (OSAT) Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market
Semiconductor Packaging
Global Bare Die Shipping and Handling and Processing and Storage Market
Semiconductor Packaging
Microtube Box Market