
 Global Ceramic Dielectric Filters Market | 2026-2036
Global Ceramic Dielectric Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ceramic Dielectric Filters Market Analysis
Software-defined tuning and remote filter management is broadening what suppliers bundle into dielectric filter contracts. Murata Manufacturing Co., Ltd. leverages its multilayer ceramic expertise to anchor premium positions in high-frequency base station applications. Qorvo, Inc. competes through integrated RF front-end portfolios that extend filter value into module-level sales. TDK Corporation sustains manufacturing scale across cylindrical and rectangular formats for diversified telecommunications OEMs.
Ceramic dielectric filters are passive RF components constructed from temperature-stable ceramic compounds such as barium titanate or zirconium stannate, formed through precision sintering and metallization to achieve sharp frequency selectivity with minimal insertion loss in microwave and millimeter-wave bands. Their primary purpose is to isolate desired signal bands while suppressing interference in dense spectrum environments including 5G massive MIMO arrays and satellite communication terminals. Low-temperature co-fired ceramic technology dominates volume production due to its compatibility with integrated passive device architectures and cost-efficient multilayer stacking. Custom geometries represent the fastest-expanding product category as mmWave spectrum allocations force antenna designers toward application-specific filter footprints.
FCC spectrum auctions and China's MIIT base station certification standards collectively tighten insertion loss and power handling specifications, forcing reformulation of dielectric materials and electrode metallization. REACH substance restrictions and RoHS compliance in Europe constrain traditional lead-based ceramic stabilizers, redirecting R&D toward alkaline earth zirconate compositions. Stakeholders must monitor evolving 3GPP release timelines and corresponding national spectrum assignments to align filter development cycles with infrastructure deployment waves.
Market Dynamics
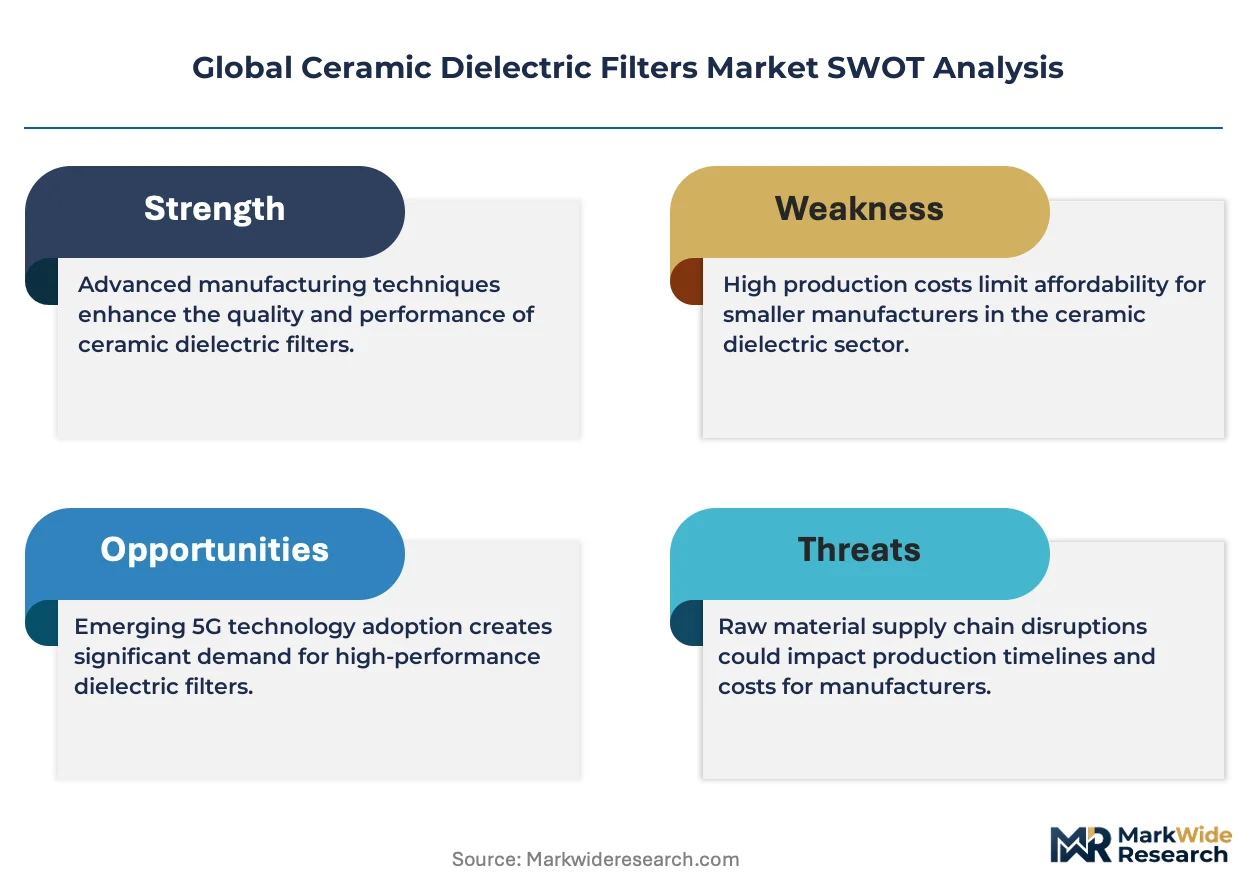
5G massive MIMO antenna densification is compressing filter development cycles from 18 months to 9 months, forcing simultaneous reformulation of ceramic dielectric constants and electrode metallurgy to meet sub-3dB insertion loss thresholds at 28GHz and 39GHz bands.
Growth Catalysts
- MIIT base station certification:China's accelerated 5G rollout mandates domestic filter sourcing for 700MHz and 2.6GHz infrastructure, concentrating procurement within Shenzhen and Suzhou manufacturing clusters.
- mmWave spectrum allocation:FCC auctions in the 24-47GHz range are driving demand for temperature-stable barium titanate formulations that maintain Q-factor stability across -40°C to +125°C operational windows.
- Low-temperature co-fired ceramic (LTCC):This multilayer stacking process enables integrated passive device architectures that reduce footprint by 60% in smartphone RF front-end modules.
Market Restraints
- Raw material concentration:High-purity zirconium oxide supply concentrates in Australian and South African mining operations, exposing filter manufacturers to extraction bottlenecks and spot price volatility.
- REACH substance restrictions:ECHA's tightening limits on lead-based ceramic stabilizers force costly reformulation toward alkaline earth zirconate compositions with unproven long-term reliability data.
- Silver electrode costs:Precious metal metallization accounts for 35-40% of bill-of-materials expense, with no technically viable copper substitution above 6GHz due to oxidation-driven Q-factor degradation.
Strategic Opportunities
- India's delayed 5G spectrum auction:Reliance Jio and Bharti Airtel infrastructure buildouts create fresh demand for sub-6GHz filters with localized thermal cycling specifications for tropical humidity conditions.
- Satellite terminal integration:LEO constellation ground equipment manufacturers seek custom rectangular filter geometries that integrate with phased array architectures for Starlink and OneWeb competitor systems.
- EU Green Deal material incentives:Horizon Europe funding for lead-free piezoelectric ceramics accelerates R&D timelines for compliant dielectric formulations targeting European telecommunications OEMs.
Industry Challenges
- Electromagnetic simulation talent scarcity:Finite element modeling expertise for 3D electromagnetic field distribution in complex filter geometries remains concentrated within a handful of Japanese and German research institutes.
- 3GPP release alignment:Filter qualification cycles must synchronize with evolving 5G-Advanced and 6G study group timelines, creating inventory risk for pre-certified component stockpiling.
- Legacy test equipment incompatibility:Vector network analyzers calibrated for sub-6GHz measurements require costly upgrades to characterize mmWave filter performance above 24GHz.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ceramic Dielectric Filters Market |
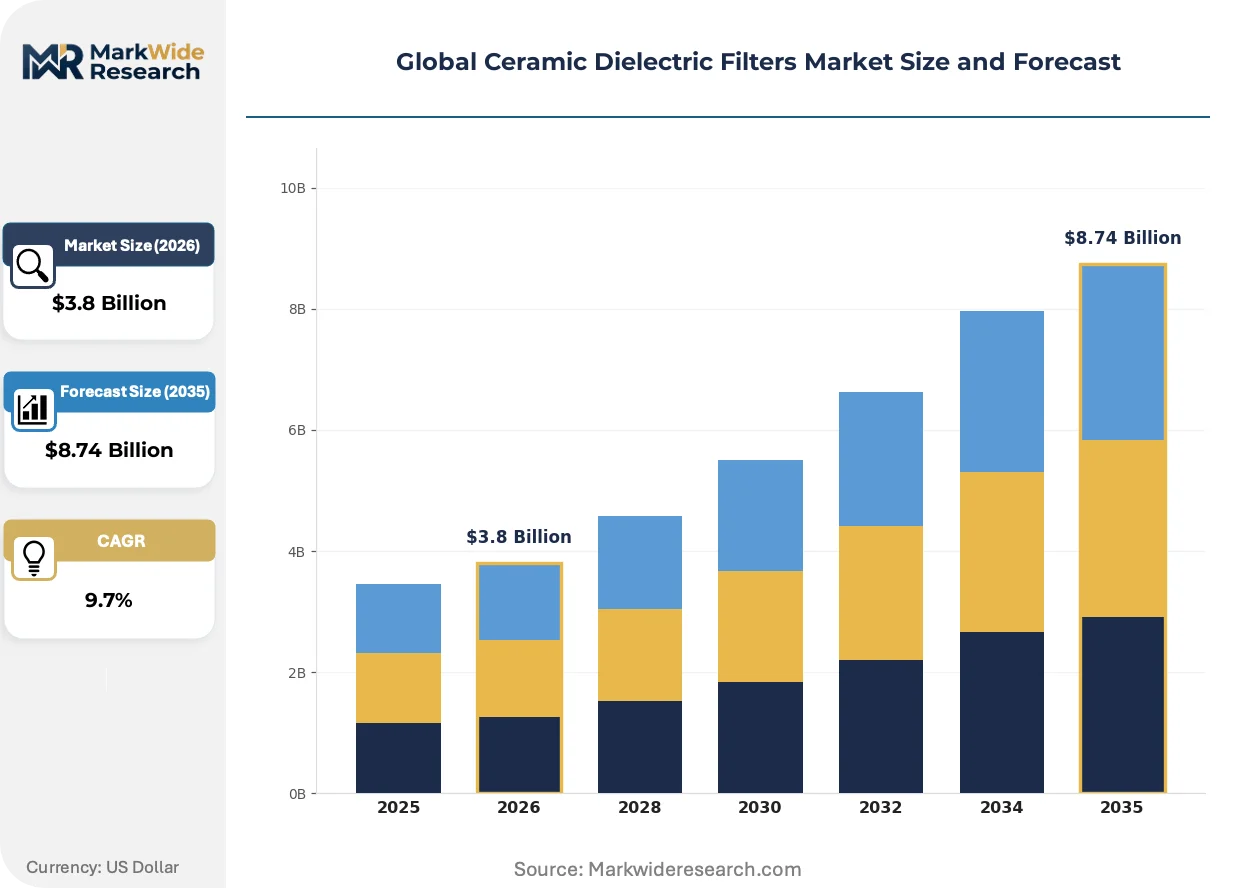
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical, Rectangular, Tubular, Custom Use Case: Wireless Communication, RF Applications, Automotive Electronics, Military End User: Telecommunications, Consumer Electronics, Aerospace, Industrial Technology: Multilayer, Low-Temperature Co-Fired Ceramic, High-Frequency, Others |
| Companies Covered | Skyworks Solutions, Inc., CTS Corporation, Murata Manufacturing Co., Ltd., Ube Electronics, Partron, TDK Corporation, Qorvo, Inc., Broadcom Inc., KYOCERA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ceramic Dielectric Filters Market Emerging Trajectories
Dielectric filter manufacturing is pivoting from standardized cylindrical formats toward application-specific geometries as spectrum fragmentation and antenna integration complexity accelerate. Three developments dominate this transition.
Photolithographic patterning of silver-palladium electrodes onto thin-film ceramic substrates is rewriting the cost-performance tradeoff for millimeter-wave filters. Base station OEMs in South Korea and Japan are adopting this approach for 28GHz small cell deployments. The technology is compressing traditional thick-film processing margins and enabling 50-micron feature resolution previously unattainable with screen printing.
REACH Annex XVII restrictions on lead compounds in electrical and electronic equipment are forcing ceramic composition changes across European supply chains. Manufacturers are qualifying calcium zirconate and strontium titanate alternatives that sacrifice some temperature stability for regulatory compliance. German automotive radar suppliers face the tightest compliance deadlines, with 2026 cutoff dates for lead-containing ceramics in new platform designs.
Antenna-filter co-design contracts are displacing discrete component procurement at major telecommunications infrastructure vendors. Chinese base station manufacturers now require filter suppliers to participate in electromagnetic simulation workflows during early antenna architecture phases. This integration is most advanced in Shenzhen and Chengdu design centers, where filter vendors maintain resident engineering teams inside OEM facilities.
Global Ceramic Dielectric Filters Market Segmentation
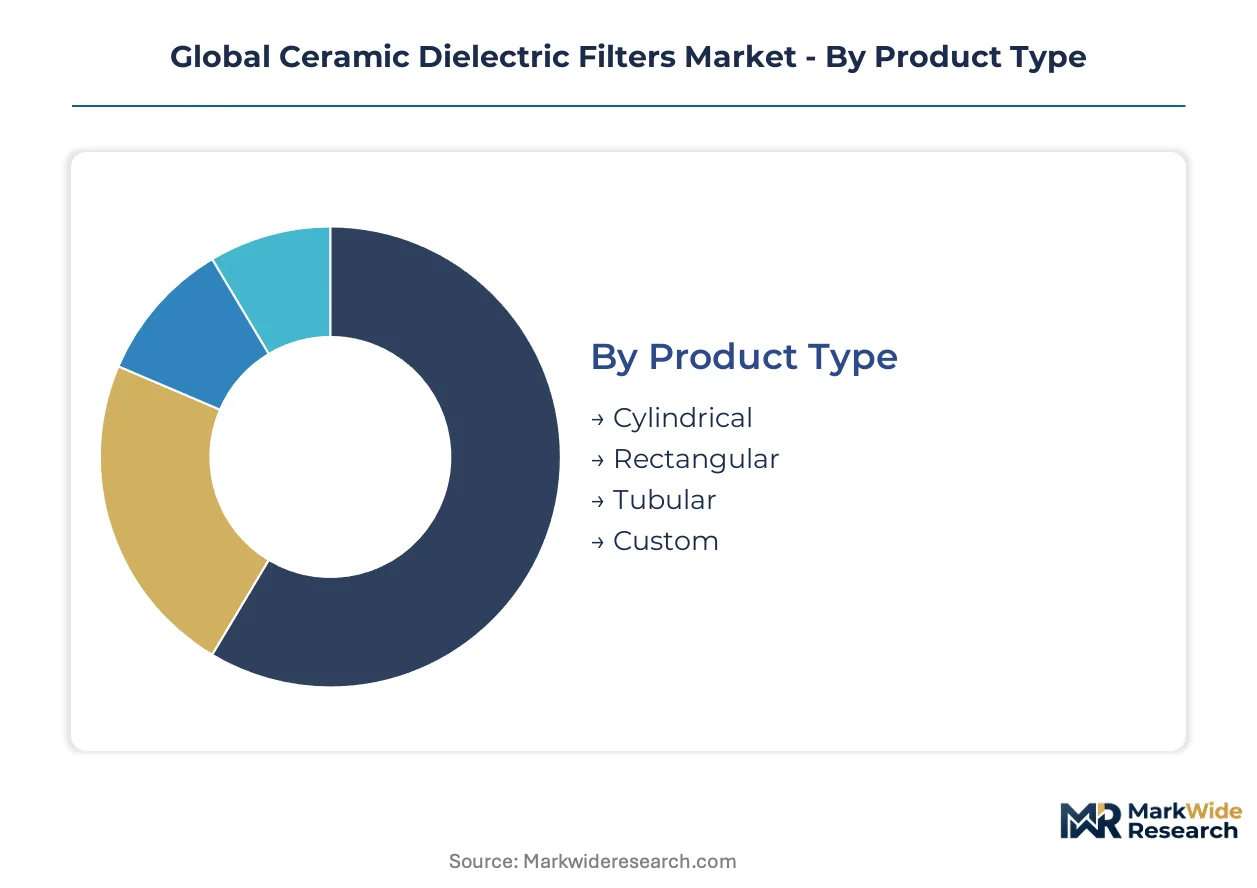
Ceramic dielectric filter procurement patterns diverge sharply between high-volume standardized formats and premium custom geometries. Understanding these splits reveals where margin concentration and technology leadership concentrate across the value chain.
Product Type:
Volume production anchors cylindrical formats while premium positioning shifts toward application-specific footprints.
- Cylindrical:These axisymmetric resonators dominate base station infrastructure through mature sintering processes and repeatable Q-factor performance. Chinese OEMs in Shenzhen and Suzhou absorb the majority of cylindrical output for 700MHz and 2.6GHz massive MIMO deployments. The format's manufacturing simplicity supports 9-month qualification cycles demanded by MIIT certification timelines.
- Custom:Application-specific geometries command premium positioning as mmWave spectrum fragmentation forces antenna-filter co-design. South Korean 28GHz small cell manufacturers and Japanese satellite terminal OEMs drive specification complexity. Photolithographic electrode patterning enables 50-micron feature resolution for these non-standard footprints.
- Rectangular:Phased array integration favors these planar formats for LEO constellation ground equipment.
- Tubular:Niche applications in legacy RF infrastructure maintain steady but limited demand.
Today's leader: Cylindrical. Tomorrow's challenger: Custom.
Use Case:
Application maturity separates established wireless infrastructure from emerging automotive and defense requirements.
- Wireless Communication:5G base station densification compresses development cycles and concentrates procurement among Shenzhen and Suzhou manufacturing clusters. MIIT certification mandates domestic filter sourcing for China's accelerated 700MHz rollout.
- RF Applications:Smartphone RF front-end modules drive LTCC multilayer adoption for 60% footprint reduction. FCC spectrum auctions in the 24-47GHz range tighten insertion loss specifications.
- Automotive Electronics:German radar suppliers face REACH Annex XVII compliance deadlines forcing calcium zirconate qualification.
- Military:Harsh-environment specifications sustain demand for temperature-stable barium titanate formulations.
Wireless Communication captures current volume. RF Applications offer the steepest expansion trajectory as mmWave penetrates consumer devices.
End User:
Customer concentration patterns mirror regional infrastructure investment cycles and regulatory enforcement intensity.
- Telecommunications:Base station OEMs in China, South Korea, and Japan dominate procurement through antenna-filter co-design contracts. Resident engineering teams now embed inside Shenzhen and Chengdu design centers.
- Consumer Electronics:Smartphone manufacturers drive LTCC volume through integrated passive device architectures.
- Aerospace:Satellite terminal manufacturers seek rectangular geometries for Starlink competitor systems.
- Industrial:Process automation and test equipment sustain steady demand for standardized cylindrical formats.
Telecommunications holds installed base dominance. Aerospace emerges as the margin expansion frontier.
Technology:
Process maturity and frequency capability define competitive positioning across manufacturing methods.
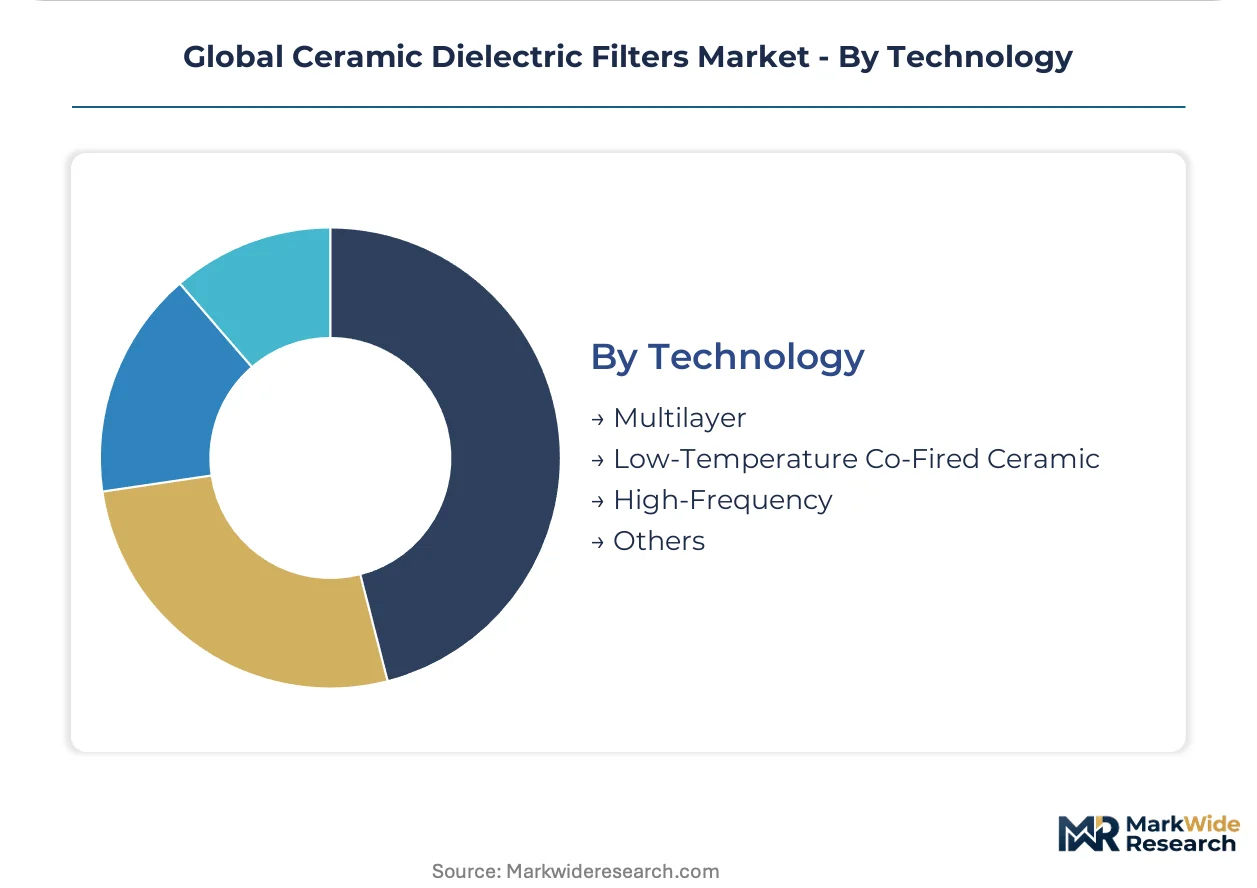
- Low-Temperature Co-Fired Ceramic:Multilayer stacking enables integrated passive device architectures with 60% footprint reduction. Consumer electronics and smartphone RF modules absorb the majority of LTCC output.
- Multilayer:Murata Manufacturing leverages this expertise for premium base station positioning.
- High-Frequency:mmWave characterization above 24GHz demands upgraded vector network analyzers and specialized simulation talent.
- Others:Emerging dielectric formulations including alkaline earth zirconate compositions address REACH compliance requirements.
LTCC commands current volume leadership. High-Frequency technology gains share fastest as spectrum allocations push into mmWave bands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT certification timelines compress filter development cycles to nine months, while Germany's REACH Annex XVII deadlines force material reformulation at slower automotive radar cadences. This divergence in regulatory pacing splits procurement patterns between telecommunications infrastructure and industrial applications.
China
MIIT mandates domestic filter sourcing for 700MHz and 2.6GHz base station infrastructure, concentrating procurement within Shenzhen and Suzhou manufacturing clusters. The accelerated 5G rollout absorbs cylindrical format output for massive MIMO deployments. Resident engineering teams from filter suppliers now embed inside Chengdu design centers to synchronize antenna-filter co-design workflows.
United States
FCC spectrum auctions in the 24-47GHz range drive demand for temperature-stable barium titanate formulations with sub-3dB insertion loss thresholds. Small cell deployments in the 28GHz band favor photolithographic electrode patterning for millimeter-wave performance. Base station OEM procurement concentrates around Dallas-Fort Worth and San Diego technology corridors.
Germany
ECHA's REACH Annex XVII restrictions on lead-based ceramic stabilizers force calcium zirconate qualification for automotive radar applications. German automotive suppliers face 2026 compliance deadlines for new platform designs. Industrial filter demand clusters in Baden-Württemberg and Bavaria, where precision manufacturing equipment requires standardized cylindrical formats.
Japan
METI guidelines on 5G-Advanced infrastructure deployment tighten insertion loss specifications for base station filter procurement. Japanese satellite terminal OEMs drive specification complexity for custom rectangular geometries in LEO constellation ground equipment. Manufacturing activity concentrates in Nagoya and Osaka metropolitan areas with established precision ceramics expertise.
South Korea
28GHz small cell manufacturers adopt photolithographic patterning for millimeter-wave filter production ahead of nationwide 5G densification targets. Domestic spectrum allocation priorities align filter development cycles with national infrastructure deployment waves. Seoul and Suwon host the primary design centers where antenna-filter integration occurs.
Global Ceramic Dielectric Filters Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with volume production consolidating around established ceramic houses while custom geometries fragment toward application-specific boutiques. The vendor base organizes into three tiers: multilayer ceramic specialists with captive sintering capacity, RF front-end integrators bundling filter value into module sales, and precision metallization houses serving photolithographic niches. Capacity expansion and strategic partnerships dominate competitive moves, with antenna-filter co-design contracts displacing discrete component procurement.
Among Japanese multilayer ceramic specialists, Murata Manufacturing Co., Ltd. and TDK Corporation occupy positions that exemplify scale-driven manufacturing across cylindrical and rectangular formats. KYOCERA Corporation represents the precision ceramics archetype with established sintering expertise. Qorvo, Inc. and Skyworks Solutions, Inc. anchor the RF front-end integration tier, bundling filter functionality into broader module portfolios for telecommunications infrastructure. These five entities collectively span the technology spectrum from raw ceramic formulation through system-level integration.
| Leading Market Players |
|---|
| Skyworks Solutions, Inc. |
| CTS Corporation |
| Murata Manufacturing Co., Ltd. |
| Ube Electronics |
| Partron |
| TDK Corporation |
| Qorvo, Inc. |
| Broadcom Inc. |
| KYOCERA Corporation |
| Others |
Supply Flow & Price Mechanics
MIIT-mandated domestic sourcing for China's 700MHz base station rollout is compressing procurement timelines to nine months, forcing filter manufacturers to absorb precious metal volatility while locking in long-term silver-palladium contracts. This buyer-driven specification tightening reshapes supplier economics across cylindrical and custom geometries.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for photolithographic electrode patterning at 28GHz. Three-tier pricing structure across premium, standard, and economy levels separates antenna-filter co-design contracts from discrete component sales. Cost compression in standard cylindrical formats is intensifying because Chinese OEMs consolidate procurement around Shenzhen and Suzhou clusters. Base station OEMs exhibit lowest price sensitivity due to insertion loss certification requirements, while industrial automation buyers drive hardest bargaining on legacy tubular formats.
Supply Chain Analysis
Domestic-content mandates under China's MIIT certification are redirecting filter sourcing toward captive Shenzhen and Suzhou manufacturing clusters, displacing former Taiwanese supply routes. High-purity zirconium oxide draws from Australian and South African mining operations; silver-palladium electrode metallization rests on precious metals spot markets. Single-source vulnerability concentrates in zirconium oxide extraction bottlenecks. Distribution runs through telecommunications infrastructure OEMs with resident engineering teams embedded at design centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Sub-3dB insertion loss thresholds at 28GHz and 39GHz bands are elevating specification premiums above commodity filter economics.
For Market Incumbents: Extend antenna-filter co-design capabilities through resident engineering deployments at Chengdu and Shenzhen OEM design centers. Deepen backward integration into high-purity zirconium oxide sourcing to offset Australian and South African extraction bottlenecks. Photolithographic patterning expertise at 50-micron resolution represents the priority capability moat against thick-film commoditization. For New Entrants and Emerging Players: Launch via specialized mmWave simulation services targeting South Korean 28GHz small cell manufacturers lacking finite element modeling talent. India's delayed 5G spectrum auction creates the most penetrable geography for sub-6GHz filters with tropical humidity thermal cycling specifications. Satellite terminal integration for LEO constellation ground equipment offers the cleanest go-to-market angle outside telecommunications infrastructure concentration. For Investors and Strategic Acquirers: Asymmetric upside sits with precision metallization houses mastering silver-palladium photolithography for millimeter-wave applications. Five-to-ten year viability hinges on 3GPP release alignment capabilities and REACH-compliant ceramic formulation pipelines. Acquisition target archetype: German or Japanese boutiques with captive sintering capacity and established ECHA compliance pathways. The signal to watch is FCC spectrum auction velocity in the 24-47GHz range as infrastructure deployment inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Antenna-Filter Co-Design Contracts | Resident engineering teams at Shenzhen OEMs lock in multi-year procurement relationships. |
| Photolithographic Patterning Scale-Up | South Korean 28GHz deployments favor 50-micron electrode resolution over screen printing. |
| REACH-Compliant Formulation Investment | Calcium zirconate qualification secures German automotive radar platform access. |
| Backward Integration into Zirconium Oxide | Australian and South African mining partnerships reduce spot price exposure. |
| mmWave Simulation Capability Acquisition | Japanese and German electromagnetic modeling talent scarcity creates defensive moats. |
Methodological Framework
Bottom-up telecommunications infrastructure modeling reconciled against top-down ceramic materials tracking forms the analytical core of this study. Primary interviews with base station procurement directors, RF front-end module engineers, dielectric materials R&D leads, and precision ceramics plant managers combined with secondary validation from MIIT certification databases, FCC spectrum auction records, ECHA REACH Annex XVII filings, and 3GPP release documentation. Trade flow analysis across zirconium oxide customs data and silver-palladium precious metals exchanges anchored supply-side calibration.
Input-output matrices map dielectric constant formulations to frequency band specifications across cylindrical, custom, rectangular, and tubular product categories. Modeled segmentation spans wireless communication, RF applications, automotive electronics, and military end uses against LTCC, multilayer, and high-frequency technology tiers. CAGRs derive from infrastructure deployment wave alignment with national spectrum assignments. Forecast inputs include MIIT base station certification timelines and ECHA compliance deadline pacing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under 3GPP release delays or zirconium oxide supply disruptions. Forecasts reflect documented assumptions regarding 5G-Advanced infrastructure deployment cadence and REACH substance restriction enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Global Gan RF Devices Market
RF Components
Multi-Mode Receiver Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
Smart Antenna Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
Global RF Power Semiconductor Market
RF Components
Flat Panel Antenna Market
RF Components
RF Semiconductor Market
RF Components
RF Isolator Market
RF Components
RF Power Dividers Market
RF Components
Global RF Transceiver Market
RF Components
Coaxial Splitters Market
RF Components
Phase Shifters Market
RF Components
RF Acoustic Wave Filters Market
RF Components
High Reliability Oscillators Market
RF Components
5G Driver Amplifier Market