
 Smartphone RF Power Amplifier Market | 2026-2036
Smartphone RF Power Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone RF Power Amplifier Market Analytics
Direct procurement channels between smartphone OEMs and RF component vendors is reshaping how amplifier modules reach final assembly lines. Qorvo Inc. leverages captive GaAs fabrication to sustain pricing power across mid-tier handset portfolios. Qualcomm Inc. anchors premium 5G modem-to-antenna platforms through tight integration of its RF front-end solutions. Skyworks Solutions Inc. differentiates via filter-amplifier co-design expertise that occupies strategic slots in Apple and Samsung supply chains.
A smartphone RF power amplifier is a solid-state device that boosts radio-frequency signals to sufficient power levels for wireless transmission, typically operating across frequency bands from 600 MHz to 7.125 GHz with output power ranging from 24 dBm to 34 dBm depending on cellular standard. These components enable voice and data connectivity in mobile handsets by ensuring transmitted signals overcome path loss and interference to reach cellular base stations. GaN technology is capturing margin pools in high-power 5G millimeter-wave applications where thermal efficiency requirements exceed legacy GaAs capabilities. SOI-based switch-mode architectures are extending into sub-6 GHz 5G phones as OEMs prioritize battery life over peak output power. BiCMOS solutions retain cost-sensitive slots in 4G-only handsets across emerging markets where telecommunications infrastructure upgrades lag.
FCC spectrum auctions and CE marking requirements under the EU Radio Equipment Directive are tightening linearity and spurious emission standards that amplifier designs must satisfy for market access. China's MIIT mandates specific GB standards for radio transmission equipment that foreign suppliers must navigate through local certification laboratories. ETSI harmonized standards across Europe are accelerating R&D investment in envelope-tracking and Doherty architectures that meet stringent efficiency targets. Stakeholders must monitor how 3GPP Release 18 specifications redefine power class requirements before committing to next-generation amplifier architectures.
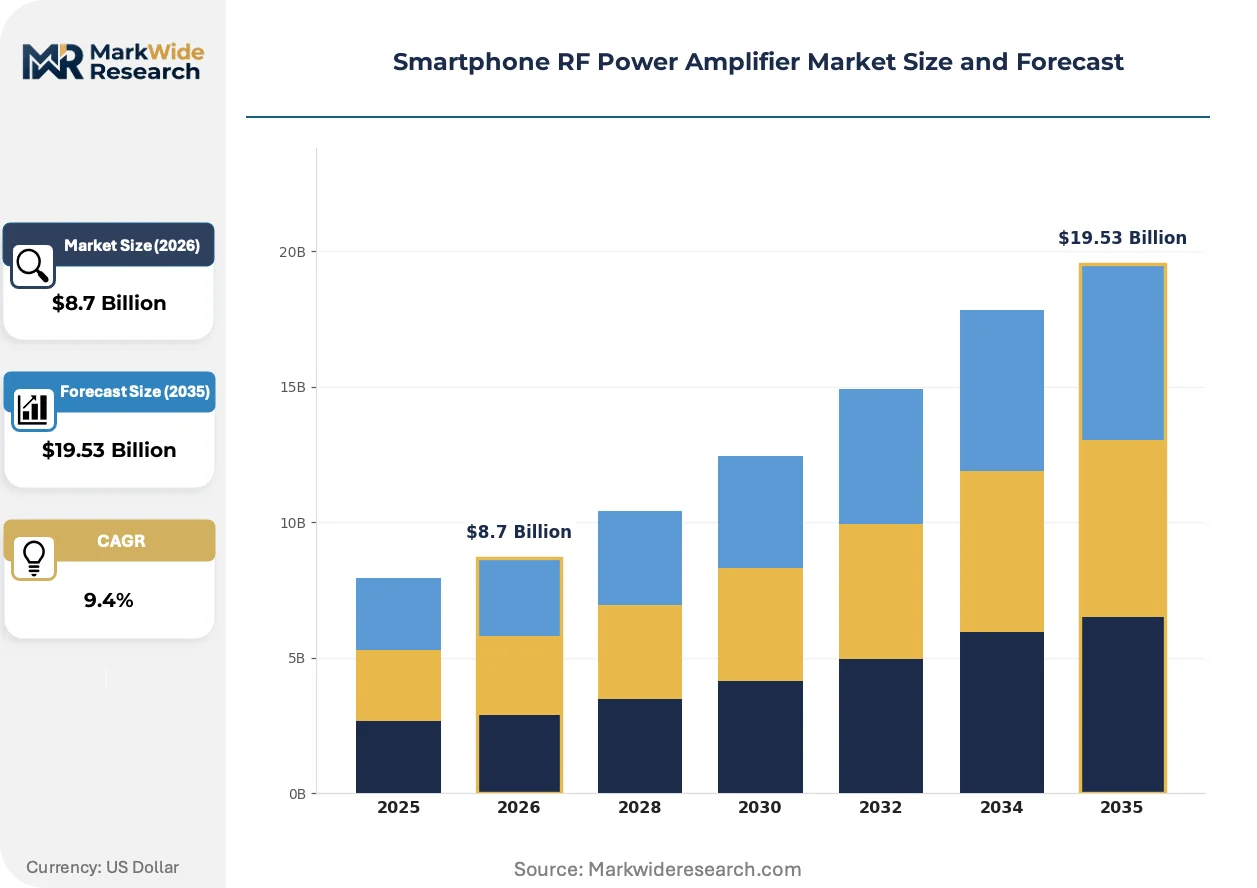
Market Dynamics
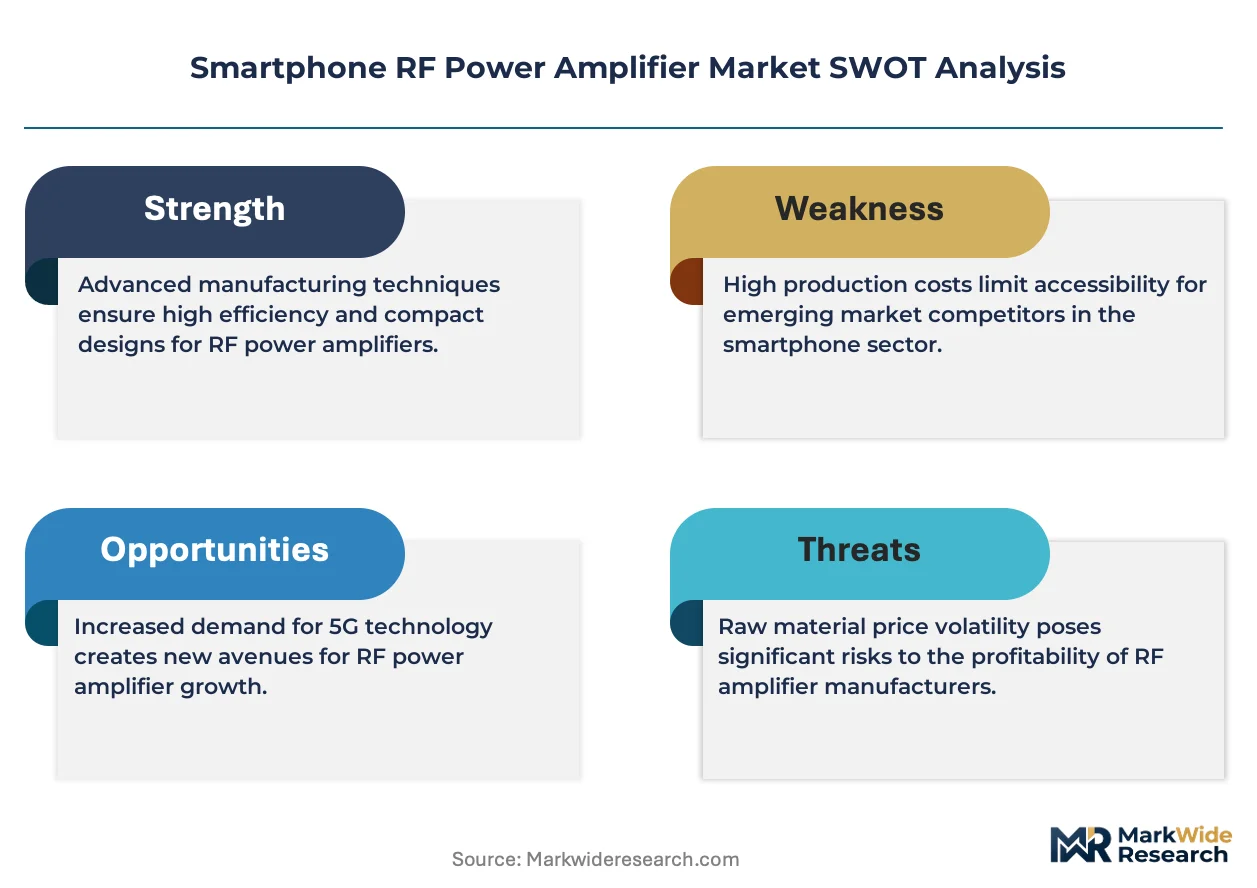
GaN-on-SiC process technology is displacing legacy GaAs architectures in flagship smartphone designs, compressing thermal budgets while extending battery endurance. This materials transition concentrates margin capture among foundries with captive compound semiconductor capability.
Growth Catalysts
- 5G millimeter-wave deployment:FCC spectrum auctions in the United States are releasing 24-47 GHz bands that demand high-efficiency amplification. Smartphone OEMs are expanding module orders to support these frequency ranges.
- Envelope-tracking architectures:ETSI harmonized efficiency standards across Europe are accelerating R&D investment in advanced modulation schemes. Doherty amplifier designs are capturing design wins in premium handset platforms.
- China MIIT certification pathways:GB standards for radio transmission equipment are creating structured procurement pipelines for qualified foreign suppliers. Local certification laboratories are streamlining market access timelines.
Market Restraints
- GaN substrate cost volatility:Silicon carbide wafer supply concentrates among Japanese and US substrate manufacturers. Price fluctuations in 6-inch SiC substrates compress amplifier module margins.
- Linearization complexity:3GPP Release 18 power class specifications are tightening spurious emission requirements. Design cycles are extending to meet pre-certification testing thresholds.
- BiCMOS substitution in emerging markets:Cost-sensitive 4G-only handsets retain legacy amplifier architectures where telecommunications infrastructure upgrades lag. SOI-based alternatives are capturing sub-6 GHz slots in mid-tier devices.
Strategic Opportunities
- India PLI scheme localization:Production-linked incentives for electronics manufacturing are attracting RF module assembly investments. Domestic handset brands are qualifying local supply chain partners.
- Filter-amplifier co-design convergence:Integration of acoustic wave filters with power amplification stages is reducing front-end footprint. Samsung and Apple supply chain slots are rewarding this architectural consolidation.
- South Korea MFDS fast-track certification:Streamlined electromagnetic compatibility approvals are accelerating time-to-market for new amplifier variants. Seoul-based design houses are leveraging this regulatory efficiency.
Industry Challenges
- Compound semiconductor talent scarcity:GaN HEMT process engineering expertise concentrates among a narrow cohort of foundry veterans. University pipeline output lags industry absorption rates.
- Multi-band integration complexity:Supporting 600 MHz through 7.125 GHz with unified amplifier stages demands sophisticated impedance matching networks. Design verification cycles are compressing against annual handset refresh timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone RF Power Amplifier Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GaAs, BiCMOS, SOI, GaN Technology: D-Class, LDMOS, Linear, Switch Mode End User: OEMs, Smartphone Manufacturers, Component Suppliers, Telecommunications Application: 2G, 3G, 4G, 5G |
| Companies Covered | Analog Devices Inc., Infineon Technologies AG, Qorvo Inc., MACOM Technology Solutions Holdings Inc., NXP Semiconductors NV, Skyworks Solutions Inc., Broadcom Inc., Murata Manufacturing Co. Ltd., Qualcomm Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone RF Power Amplifier Market Evolving Landscape
Digital pre-distortion and intelligent bias control are transforming how RF power amplifiers manage linearity-efficiency tradeoffs. These innovations are compressing the gap between laboratory performance and mass-production yields.
GaN-on-SiC high-electron-mobility transistors are digitizing envelope-tracking implementations by enabling real-time adaptive impedance matching. Premium 5G smartphone platforms are adopting these devices for millimeter-wave transmission chains. The technology is digitizing thermal management architectures that previously relied on passive spreading solutions.
CE marking requirements under the EU Radio Equipment Directive are tightening spurious emission limits for sub-6 GHz operation. Amplifier manufacturers are investing in advanced Doherty architectures to meet these harmonized standards. Mid-tier European handset portfolios are prioritizing efficiency certification over peak output power specifications.
Direct procurement channels between smartphone OEMs and RF component vendors are consolidating amplifier module sourcing. Flagship manufacturers are bypassing traditional distribution layers to secure capacity allocation at captive foundries. This pattern is most visible in China and South Korea where module assembly clusters concentrate final integration activity.
Smartphone RF Power Amplifier Market Segmentation
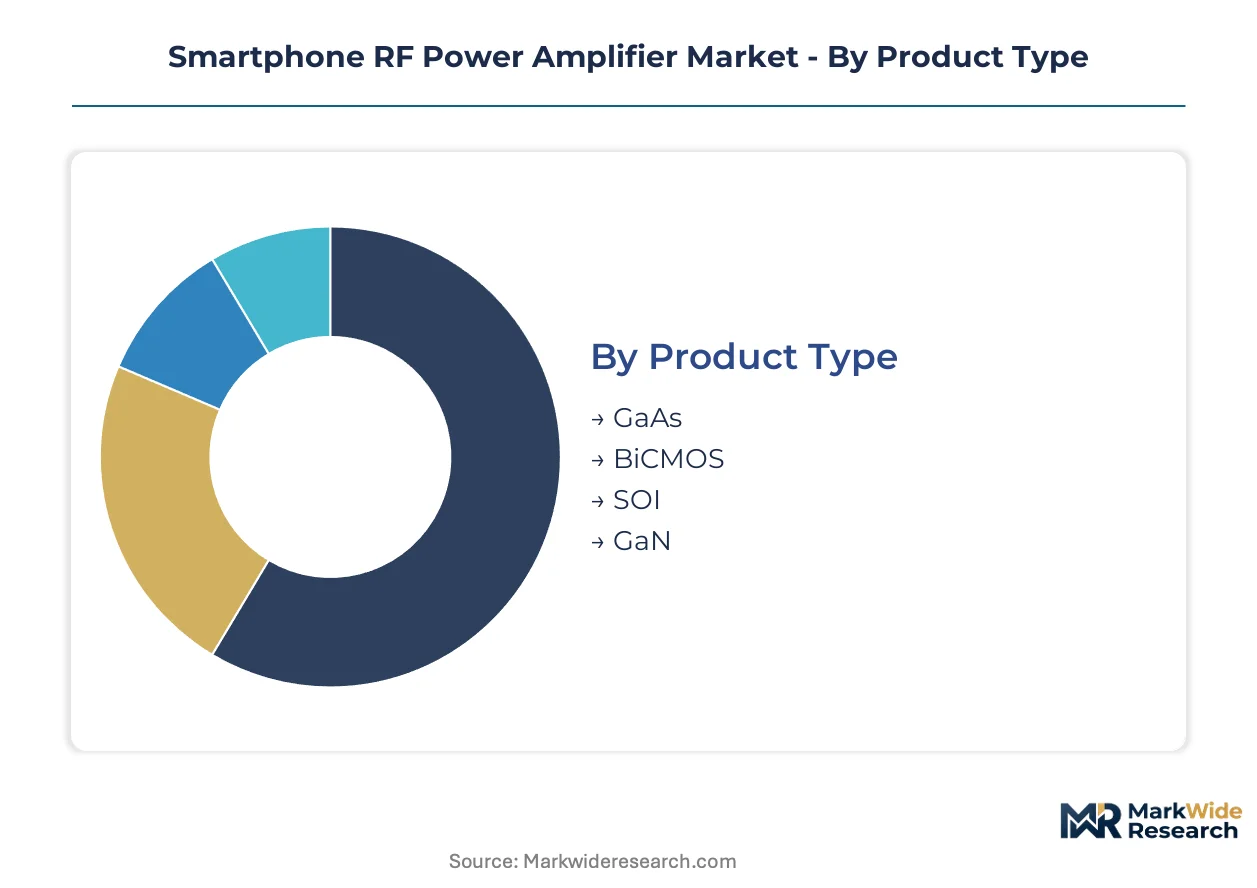
Technology heterogeneity in smartphone RF power amplifiers reflects divergent thermal, efficiency, and cost requirements across cellular generations. Segmentation by process node, amplifier class, supply chain position, and cellular standard reveals where margin pools concentrate and which architectures face substitution pressure.
Product Type:
Cost tier determines which compound semiconductor or silicon-based architecture captures design wins in each handset price band.
- GaAs:Gallium arsenide HBT and HEMT devices dominate mid-tier and legacy 4G amplification with mature epitaxial growth and established back-end packaging. Foundries in China and South Korea sustain captive supply for Apple and Samsung mid-range portfolios where thermal budgets tolerate moderate efficiency trade-offs.
- GaN:Gallium nitride-on-silicon carbide HEMTs enable millimeter-wave 5G transmission with superior power density and thermal conductivity. Premium flagship designs from Seoul and Shenzhen OEMs are expanding orders as FCC spectrum auctions release 24-47 GHz bands demanding high-efficiency amplification.
- SOI:Silicon-on-insulator substrates support switch-mode architectures in sub-6 GHz 5G phones prioritizing battery endurance over peak output power.
- BiCMOS:Bipolar-CMOS integration retains cost-sensitive slots in 4G-only handsets across emerging markets where telecommunications infrastructure upgrades lag.
GaAs commands the established base. The steepest expansion runs through GaN.
Technology:
Amplifier operating class shapes efficiency-linearity trade-offs and determines which modulation schemes each architecture supports.
- Switch Mode:Class-D and switch-mode topologies maximize power-added efficiency through reduced conduction angle, enabling envelope-tracking implementations. European handset portfolios under ETSI harmonized standards are prioritizing these architectures for sub-6 GHz operation where efficiency certification outweighs peak power specifications.
- Linear:Class-A and Class-AB linear amplifiers maintain signal fidelity for complex modulation formats including 256-QAM and 1024-QAM. 3GPP Release 18 power class specifications are tightening spurious emission requirements that extend design verification cycles for these traditional architectures.
- D-Class:Digital amplifier implementations integrate digital pre-distortion for real-time linearization, compressing the gap between laboratory performance and mass-production yields.
- LDMOS:Lateral diffused metal-oxide-semiconductor devices retain select applications in base station infrastructure rather than handset terminals due to voltage handling characteristics.
Linear architectures command the established base. The steepest expansion runs through Switch Mode.
End User:
Supply chain position determines procurement scale, technical specification authority, and margin capture proximity to final assembly.
- Smartphone Manufacturers:OEMs including Apple, Samsung, and Xiaomi exercise direct procurement channels bypassing traditional distribution layers. These manufacturers anchor demand concentration with annual handset refresh cycles compressing amplifier qualification timelines.
- OEMs:Original equipment manufacturers with captive RF front-end divisions integrate amplification stages with filter and switch components. Qorvo and Skyworks maintain these verticalized relationships through co-design partnerships.
- Component Suppliers:Specialized RF vendors supply discrete amplifier modules to integrators lacking captive compound semiconductor fabrication.
- Telecommunications:Network equipment providers specify amplifier performance requirements that cascade into handset design parameters.
Smartphone Manufacturers command the established base. The steepest expansion runs through OEMs.
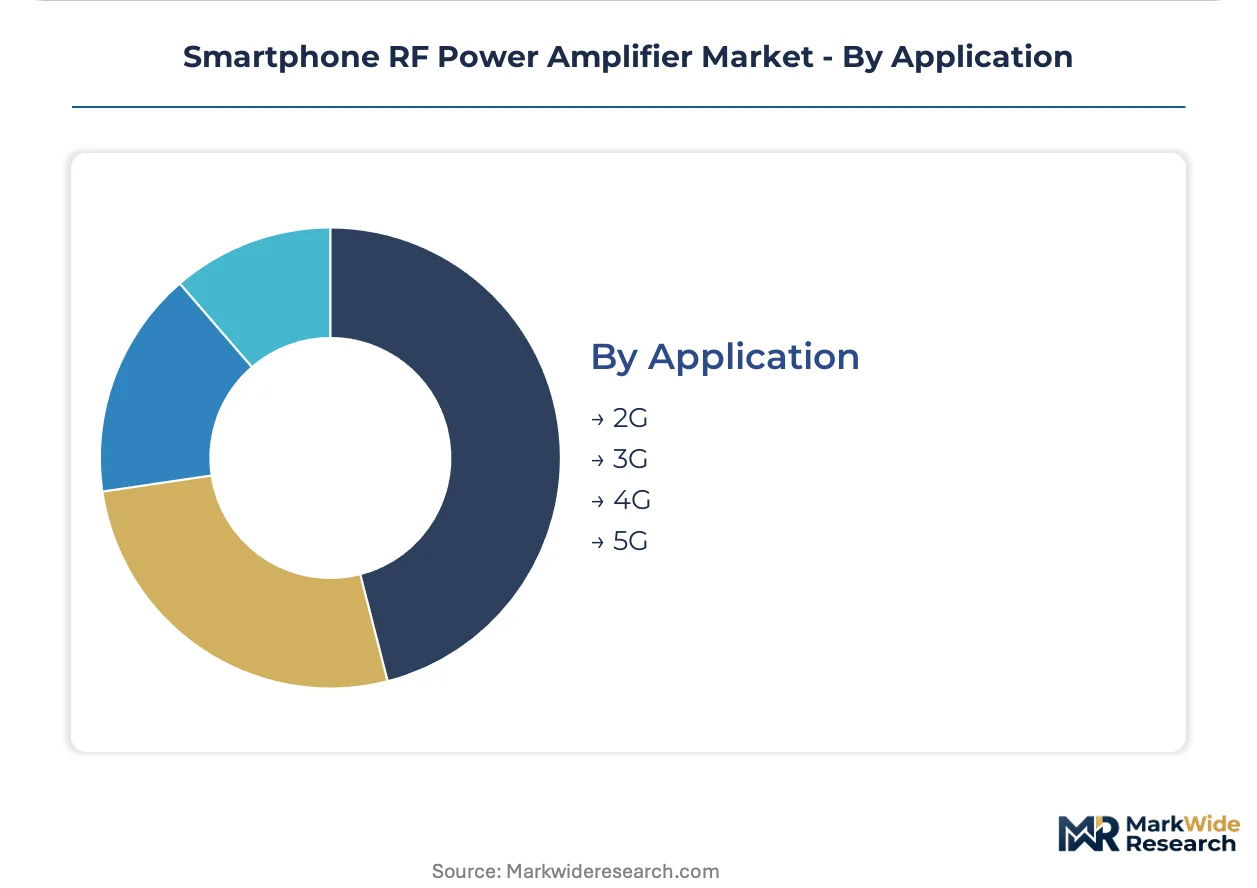
Application:
Cellular generation determines frequency range, bandwidth, and power class requirements that cascade into amplifier architecture selection.
- 5G:New radio specifications span sub-6 GHz and millimeter-wave bands requiring high-efficiency amplification with envelope-tracking and adaptive impedance matching. China MIIT certification pathways and South Korea MFDS fast-track approvals are accelerating module qualification for these premium platforms.
- 4G:LTE-Advanced Pro retains volume concentration in emerging markets where telecommunications infrastructure upgrades lag. BiCMOS and legacy GaAs architectures dominate this cost-sensitive segment.
- 3G:W-CDMA and CDMA2000 amplification persists in rural coverage extensions and legacy network maintenance.
- 2G:GSM/GPRS/EDGE transmitters approach end-of-life with network sunsets in Europe and North America.
4G commands the established base. The steepest expansion runs through 5G.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korean and Chinese module assembly clusters while European and North American markets absorb premium-tier markups through direct OEM procurement channels.
United States
FCC spectrum auctions releasing 24-47 GHz bands drive millimeter-wave amplifier demand from Seattle and San Diego design centers. The FCC tightens linearity standards for 5G NR equipment certification. Austin and Boston host RF front-end R&D facilities where envelope-tracking architectures undergo pre-certification testing.
China
MIIT mandates GB standards for radio transmission equipment that structure procurement for Shenzhen and Beijing OEMs. GB certification pathways streamline market access for qualified foreign suppliers. Dongguan and Suzhou concentrate module assembly activity where GaN-on-SiC devices integrate into flagship handset platforms.
South Korea
Seoul-based smartphone manufacturers expand orders for high-efficiency amplifiers supporting sub-6 GHz and millimeter-wave transmission. MFDS fast-track electromagnetic compatibility approvals accelerate time-to-market for new amplifier variants. Suwon and Pyeongtaek anchor RF front-end integration clusters serving Samsung supply chains.
Japan
METI industrial policy supports compound semiconductor foundry investments for 5G base station and handset applications. JIS standards govern reliability testing protocols for RF power devices. Yokohama and Kyoto host epitaxial growth facilities supplying GaAs and GaN wafers to regional module assemblers.
Germany
ETSI harmonized efficiency standards under the EU Radio Equipment Directive accelerate R&D investment in Doherty amplifier architectures. CE marking requirements tighten spurious emission limits for sub-6 GHz operation. Munich and Dresden concentrate RF component design houses serving European automotive and handset OEMs.
Smartphone RF Power Amplifier Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base organizes around three strata: captive compound semiconductor foundries, filter-amplifier co-design houses, and fabless RF front-end architects. Strategic differentiation runs through backward integration into epitaxial growth, co-development partnerships with smartphone OEMs, and certification pre-positioning in MIIT and FCC pipelines.
Among diversified semiconductor conglomerates, Analog Devices Inc., Infineon Technologies AG, and NXP Semiconductors NV occupy positions spanning precision signal chain and power management portfolios that extend into RF amplification. These entities represent scale-driven archetypes where manufacturing breadth supports cost absorption across cellular infrastructure and handset terminal markets. Their positioning exemplifies how multi-product lines buffer against cyclicality in any single RF component category.
| Leading Market Players |
|---|
| Analog Devices Inc. |
| Infineon Technologies AG |
| Qorvo Inc. |
| MACOM Technology Solutions Holdings Inc. |
| NXP Semiconductors NV |
| Skyworks Solutions Inc. |
| Broadcom Inc. |
| Murata Manufacturing Co. Ltd. |
| Qualcomm Inc. |
| Others |
Value Network & Pricing Analysis
The Shanghai-Shenzhen logistics corridor carries GaN-on-SiC substrates and finished amplifier modules between Dongguan assembly clusters and Shenzhen OEM headquarters, with freight cost volatility feeding directly into module pricing spreads and reinforcing geographic concentration in premium-tier sourcing decisions.
Pricing Analysis
The customization-premium spread separates configured-to-order GaN HEMT modules for flagship 5G millimeter-wave handsets from standard GaAs volumes for mid-tier portfolios. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under FCC Part 27 and MIIT GB standards. Cost compression in economy-tier BiCMOS amplifiers is intensifying because Chinese domestic handset brands are consolidating orders at captive foundries. Emerging market OEMs exhibit highest price sensitivity; Seoul and Cupertino flagship manufacturers show lowest sensitivity to module cost fluctuations.
Supply Chain Analysis
Contract-manufacturing concentration sits with Taiwan Semiconductor Manufacturing Company and Samsung Foundry for GaN-on-SiC HEMT fabrication, with ASE Technology and Amkor Technology anchoring back-end packaging. Geographic supply concentration centers on Taiwan, South Korea, and Japan for compound semiconductor substrates and epitaxial growth. Raw material dependencies draw from 6-inch silicon carbide wafers, gold wire bonding materials, and ceramic packaging substrates. Single-source vulnerability concentrates in Japanese SiC substrate supply from Sumco and Showa Denko. Distribution runs through direct procurement channels between smartphone OEMs and RF component vendors, bypassing traditional distribution layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from 5G frequency band proliferation, as sub-6 GHz and millimeter-wave specifications multiply amplifier variants beyond the scale efficiency of any single supplier's portfolio.
For Market Incumbents: Build process-technology moats through captive GaN HEMT fabrication at 6-inch SiC nodes. Consolidate filter-amplifier co-design partnerships with Apple and Samsung to lock strategic supply chain slots. Defend against SOI-based switch-mode substitution in mid-tier sub-6 GHz phones by accelerating envelope-tracking R&D investment under ETSI efficiency mandates. For New Entrants and Emerging Players: Pursue white-space opportunities in India PLI scheme localization for RF module assembly serving domestic handset brands. Target cost-optimized GaAs amplifier variants for 4G-only emerging market portfolios where BiCMOS substitution pressure remains muted. Enter through qualification partnerships with Seoul-based design houses leveraging MFDS fast-track certification pathways. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified semiconductor conglomerates seeking to exit non-core RF amplification portfolios. Long-term viability hinges on compound semiconductor process expertise concentration through the next cellular generation transition. Monitor 3GPP Release 18 power class specification finalization as inflection indicator for architecture investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Foundry Capacity Expansion | Captive 6-inch SiC fabrication secures margin pools in millimeter-wave 5G flagship designs. |
| Filter-Amplifier Co-Design Partnership | Integration with Murata or Skyworks acoustic wave filters reduces front-end footprint for Samsung. |
| MIIT GB Certification Pre-Positioning | Early qualification through Shenzhen laboratories accelerates market access for China OEM procurement. |
| Envelope-Tracking Architecture Investment | Doherty amplifier R&D meets ETSI harmonized efficiency standards for European handset portfolios. |
| India PLI Scheme Localization | Dongguan-style module assembly clusters attract production-linked incentive qualification for domestic brands. |
Research Methodology
Operator-level perspectives from RF front-end engineering directors, smartphone OEM procurement managers, compound semiconductor foundry operations heads, and MIIT certification laboratory technical leads anchored the qualitative base. Primary interview data combined with secondary validation from FCC equipment authorization databases, 3GPP specification releases, SEC 10-K filings of listed RF component vendors, and MIIT radio transmission equipment certification records. Bottom-up module shipment estimates triangulated against top-down smartphone production forecasts across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling across technology node, amplifier operating class, cellular generation application, and supply chain position. CAGRs derived from regression analysis of historical shipment patterns and technology substitution curves. Industry-specific forecast inputs included FCC spectrum auction timelines and 3GPP Release 18 specification development status.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, smartphone replacement demand elasticity, or China-US trade policy would shift the trajectory. Forecasts reflect documented assumptions regarding GaN substrate cost stabilization and 5G millimeter-wave handset penetration rates. Quarterly review of FCC certification filings, MIIT GB standard updates, and foundry capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Low Noise Amplifier Market
RF Components
Gan RF Semiconductor Devices Market
RF Components
EMI Microwave Absorber Market
RF Components
Multiband Booster Market
RF Components
Global Small Cell Power Amplifier Market
RF Components
RF Mixers Market
RF Components
Global RF Power Semiconductor Market
RF Components
Analog Phase Shifter Market
RF Components
GPS Low Noise Amplifier Market
RF Components
Wi-Fi Module Market
RF Components
RF Duplexer Market
RF Components
RF Semiconductor Market
RF Components
RF Passive Component Market
RF Components
Z-Wave Products Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
High Reliability Oscillators Market