
 Radio Frequency Filters Market | 2026-2036
Radio Frequency Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Radio Frequency Filters Market Outlook
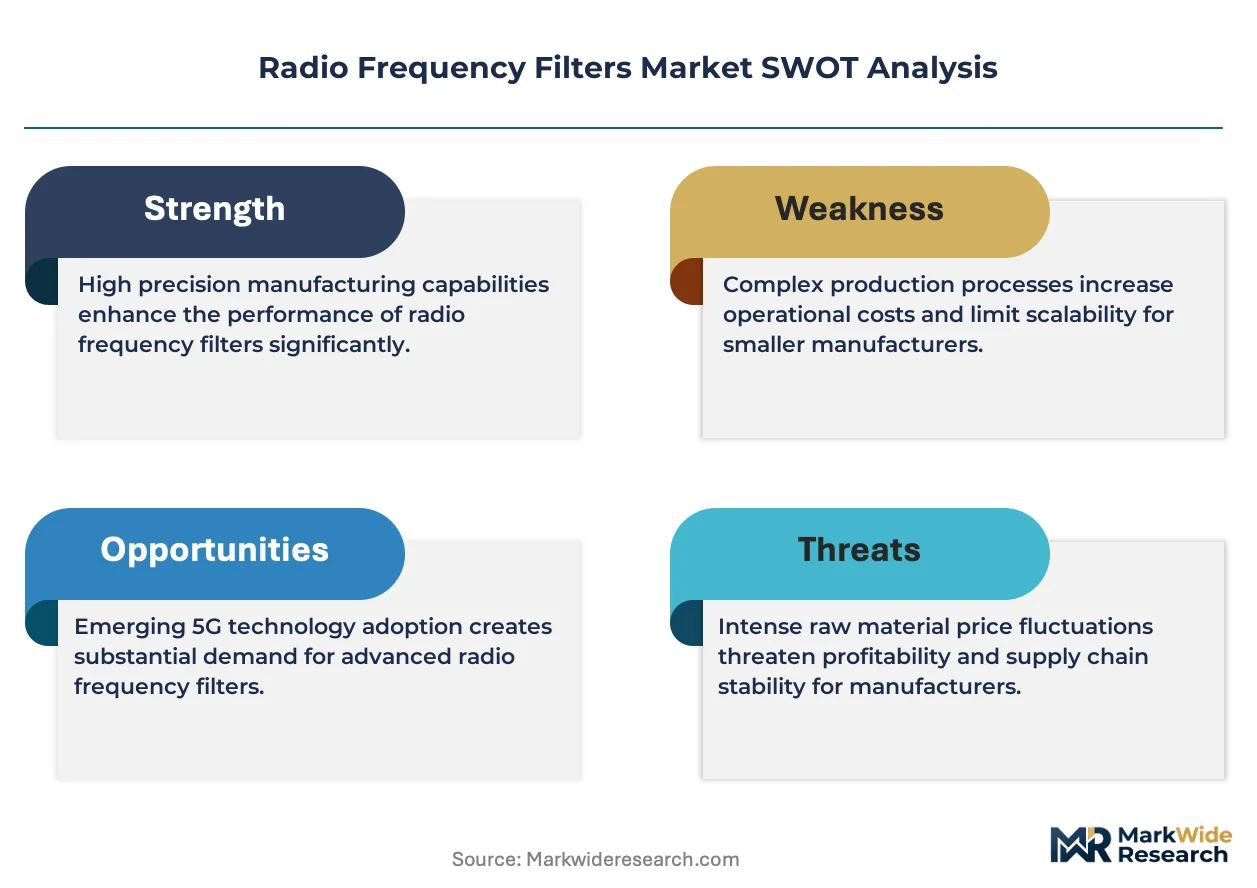
The FCC's spectrum reallocation mandate is pivoting filter design priorities toward sub-6 GHz and mmWave architectures. Murata Manufacturing Co., Ltd. leverages its ceramic material expertise to dominate SAW filter production at scale. Qorvo, Inc. anchors its position through in-house BAW fabrication, insulating supply from external foundry constraints. Broadcom Inc. competes by integrating filter modules with its front-end portfolio for streamlined OEM procurement.
Radio frequency filters are passive electronic components constructed from piezoelectric substrates, dielectric resonators, or cavity structures that selectively attenuate signals outside designated passbands while maintaining insertion loss below 3 dB in premium designs. Their primary purpose is spectral purification in transmit-receive chains, preventing adjacent-channel interference in dense wireless environments. SAW technology occupies mature, cost-sensitive smartphone slots where volume throughput outweighs performance margins. BAW filters command premium positioning in 5G mid-band infrastructure due to sharper roll-off and superior temperature stability. Cavity filters sustain niche dominance in broadcast and radar systems where power handling exceeds solid-state limits.
The FCC, ETSI, and China's MIIT collectively shape filter demand through divergent spectrum auction timelines and emission mask requirements that force region-specific product variants. REACH compliance in Europe restricts certain piezoelectric dopants, pushing suppliers toward alternative substrate formulations. Stakeholders must monitor pending spectrum reallocations in India and Brazil to preempt filter architecture commitments before regulatory lock-in.
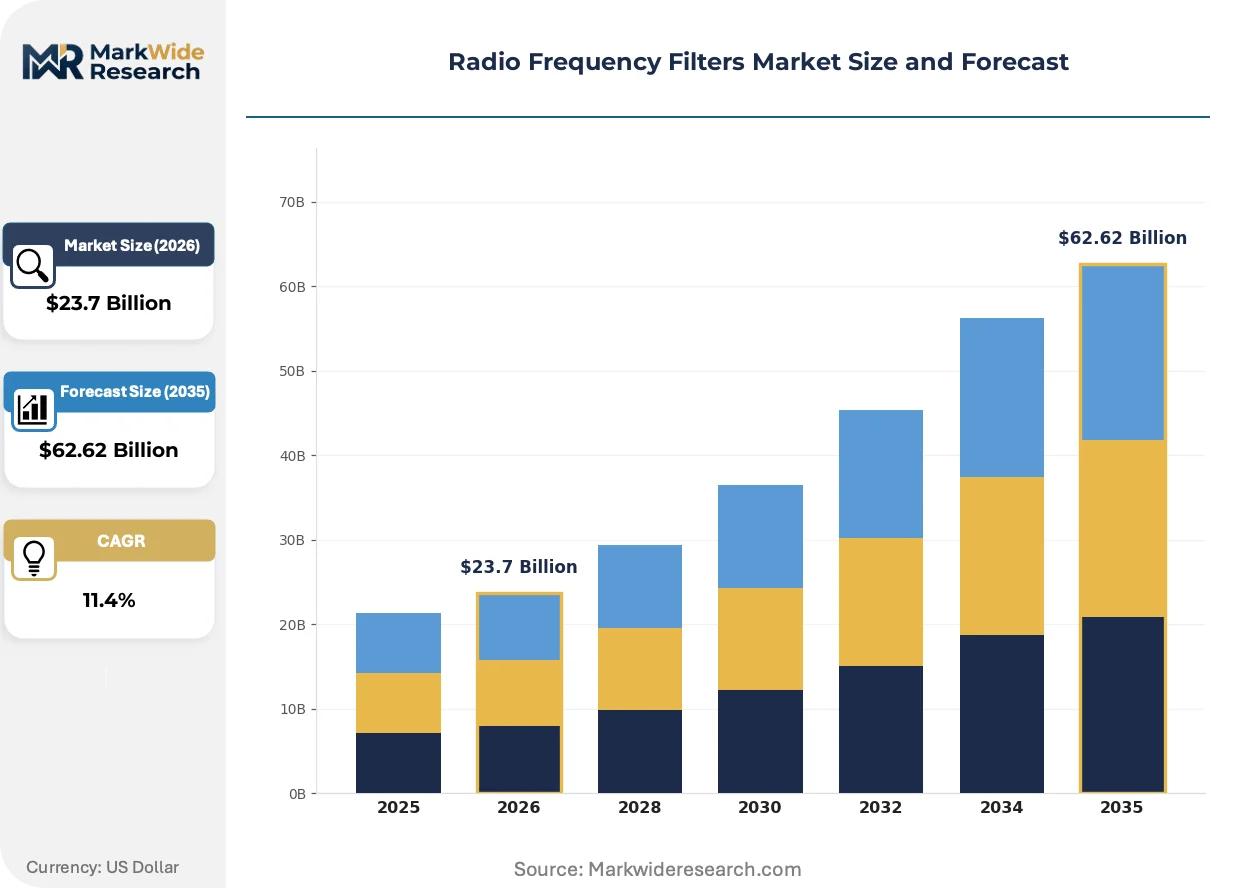
Market Dynamics
5G base station deployment is compressing filter design cycles while forcing architecture shifts toward sub-6 GHz and mmWave bands. The FCC's spectrum reallocation mandates are compelling manufacturers to abandon legacy band configurations before amortization.
Growth Catalysts
- SAW filter miniaturization:Piezoelectric substrate advances enable smaller form factors for wearable IoT devices. Smartphone OEMs in China's manufacturing clusters are absorbing record volumes.
- FCC spectrum reallocation:Mandates for new frequency bands are triggering wholesale filter redesign across US telecommunications infrastructure. Equipment vendors must certify fresh architectures.
- mmWave infrastructure buildout:5G mid-band and high-band base stations require BAW filters with sharper roll-off characteristics. Tower operators are procuring temperature-stable variants.
Market Restraints
- Piezoelectric material concentration:High-purity lithium niobate and tantalate supply concentrates among Japanese and Chinese substrate vendors. Foundry access constraints limit BAW filter output scaling.
- REACH compliance costs:ECHA restrictions on certain dopant materials force European suppliers toward alternative formulations. Reformulation cycles extend qualification timelines.
- Power handling limitations:Solid-state filter technologies face thermal dissipation ceilings that sustain cavity filter dominance in broadcast and radar transmit chains.
Strategic Opportunities
- India spectrum auctions:Pending TRAI reallocations in sub-GHz and mid-band ranges will open fresh filter procurement cycles. Vendors can preempt architecture commitments before regulatory lock-in.
- Automotive V2X integration:C-V2X modules for connected vehicles are embedding RF filters alongside cellular transceivers. Tier-1 automotive suppliers are qualifying dual-band variants.
- Filter-PA module convergence:Integration of filtering with power amplification is streamlining OEM procurement. Module suppliers are capturing front-end subsystem value.
Industry Challenges
- BAW process engineering scarcity:Thin-film resonator fabrication requires specialized MEMS expertise concentrated among legacy IDM workforces. Foundry training programs lag demand.
- Multi-band certification complexity:Region-specific emission mask requirements from FCC, ETSI, and MIIT force parallel qualification tracks. Test matrix expansion strains validation resources.
- Legacy inventory stranding:Rapid spectrum reallocation is devaluing filter stocks configured for bands being repurposed. Distributors face write-down exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radio Frequency Filters Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: SAW, DIPLEXER, BAW, Cavity Product Type: Low Pass, High Pass, Band Pass, Notch End User: Aerospace, Telecommunications, Consumer Electronics, Automotive Application: Wireless Communications, Broadcast, IoT Devices, Radar Systems |
| Companies Covered | Broadcom Inc., Murata Manufacturing Co., Ltd., Qorvo, Inc., Skyworks Solutions, Inc., Analog Devices, Inc., TDK Corporation, Anatech Electronics, Inc., API Technologies Corp., RS Microwave Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radio Frequency Filters Market Strategic Shifts
Filter architectures are converging with active front-end components while substrate materials evolve to meet thermal and miniaturization demands. Regulatory fragmentation is forcing modular, region-configurable designs.
Temperature-compensated SAW (TC-SAW) technology is integrating dopant-modified piezoelectric layers to stabilize frequency drift across automotive and industrial temperature ranges. Tier-1 automotive suppliers are adopting TC-SAW for V2X and telematics modules. The technology is integrating filtering with thermal management in ways that compress discrete component counts.
REACH compliance deadlines from ECHA are restricting hexavalent chromium and certain rare-earth dopants in piezoelectric formulations. European suppliers are accelerating qualification of lead-free and reduced-tantalum substrates. BAW filter manufacturers serving EU infrastructure markets are absorbing reformulation costs and extending qualification cycles.
Consolidated procurement of front-end modules is displacing discrete filter purchasing among smartphone OEMs. Module integrators are capturing filter value while compressing direct filter vendor relationships. China's domestic OEMs are expanding captive sourcing agreements that bypass traditional distribution channels.
Radio Frequency Filters Market Segmentation
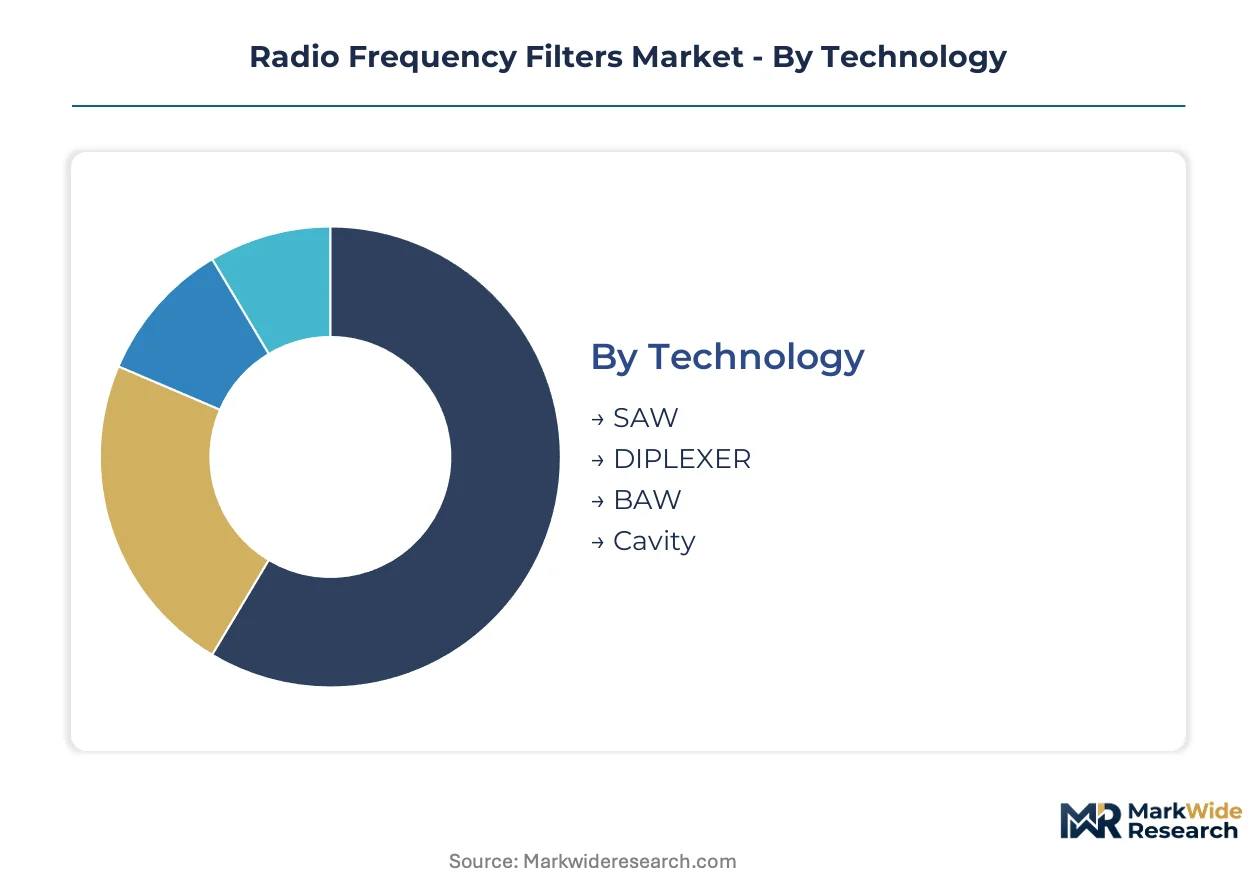
Filter architectures diverge sharply across frequency handling, physical construction, and thermal requirements. Segmentation reveals where capital intensity concentrates and which technology-platform combinations command premium positioning versus commodity procurement cycles.
Technology:
BAW fabrication demands the steepest upfront capital, with thin-film resonator processing requiring specialized MEMS equipment and cleanroom infrastructure that SAW lines avoid entirely.
- SAW:Surface acoustic wave devices deploy interdigitated transducers on piezoelectric lithium niobate or tantalate substrates. China's smartphone manufacturing clusters absorb the majority of volume, driven by wearable IoT miniaturization and cost-sensitive consumer electronics procurement.
- BAW:Bulk acoustic wave filters sandwich piezoelectric thin films between electrode layers to achieve sharper roll-off and superior temperature stability. 5G mid-band infrastructure deployment in the United States and tower operator procurement of temperature-stable variants concentrate demand here.
- DIPLEXER:Integrated dual-filter assemblies combine receive and transmit paths into single packages for space-constrained mobile devices. OEMs in China's manufacturing clusters specify these for flagship smartphone architectures.
- Cavity:Metallic resonant chambers handle power levels exceeding solid-state limits in broadcast transmitters and radar systems. Niche dominance persists where thermal dissipation requirements preclude ceramic or thin-film alternatives.
SAW absorbs the bulk of installed capacity; BAW is expanding most quickly.
Product Type:
Band-selective architectures dominate procurement volumes, with passband configurations commanding premium pricing against simpler single-edge attenuation designs.
- Band Pass:Center-frequency selective architectures attenuate both below and above designated passbands, essential for dense spectral environments. 5G base station deployment across telecommunications infrastructure and FCC spectrum reallocation mandates drive procurement of multi-octave variants.
- Notch:Narrow rejection-band designs suppress specific interference frequencies without degrading adjacent spectrum performance. Military radar systems and precision broadcast transmitters specify these for co-channel interference mitigation.
- Low Pass:Single-edge attenuation below cutoff frequencies suits baseband signal conditioning and harmonic suppression. Cost-sensitive consumer electronics applications standardize on these for simplified procurement.
- High Pass:Attenuation above specified thresholds enables DC blocking and sub-harmonic rejection in receiver front-ends. Niche deployment in satellite communications and specialized test equipment.
Band Pass captures the majority of design wins; Notch is climbing the fastest on radar and defense procurement.
End User:
Customer-type segmentation tracks directly to certification burden and volume scale, with automotive and aerospace imposing the most stringent qualification protocols.
- Consumer Electronics:Smartphone, tablet, and wearable OEMs drive the highest unit volumes with the shortest product lifecycles. China's domestic manufacturing clusters are expanding captive filter sourcing agreements that bypass traditional distribution.
- Telecommunications:Base station and network infrastructure operators prioritize temperature stability and power handling over miniaturization. FCC spectrum reallocation mandates in the United States force wholesale architecture redesigns before legacy band amortization completes.
- Automotive:C-V2X module integration and telematics systems are embedding RF filters alongside cellular transceivers. Tier-1 suppliers are qualifying TC-SAW variants for extended temperature range operation.
- Aerospace:Satellite communications and avionics systems demand hermetic packaging and radiation-hardened specifications. Qualification timelines extend years beyond commercial consumer electronics cycles.
Consumer Electronics absorbs the bulk of unit volume; Automotive is gaining share fastest on connected vehicle deployment.
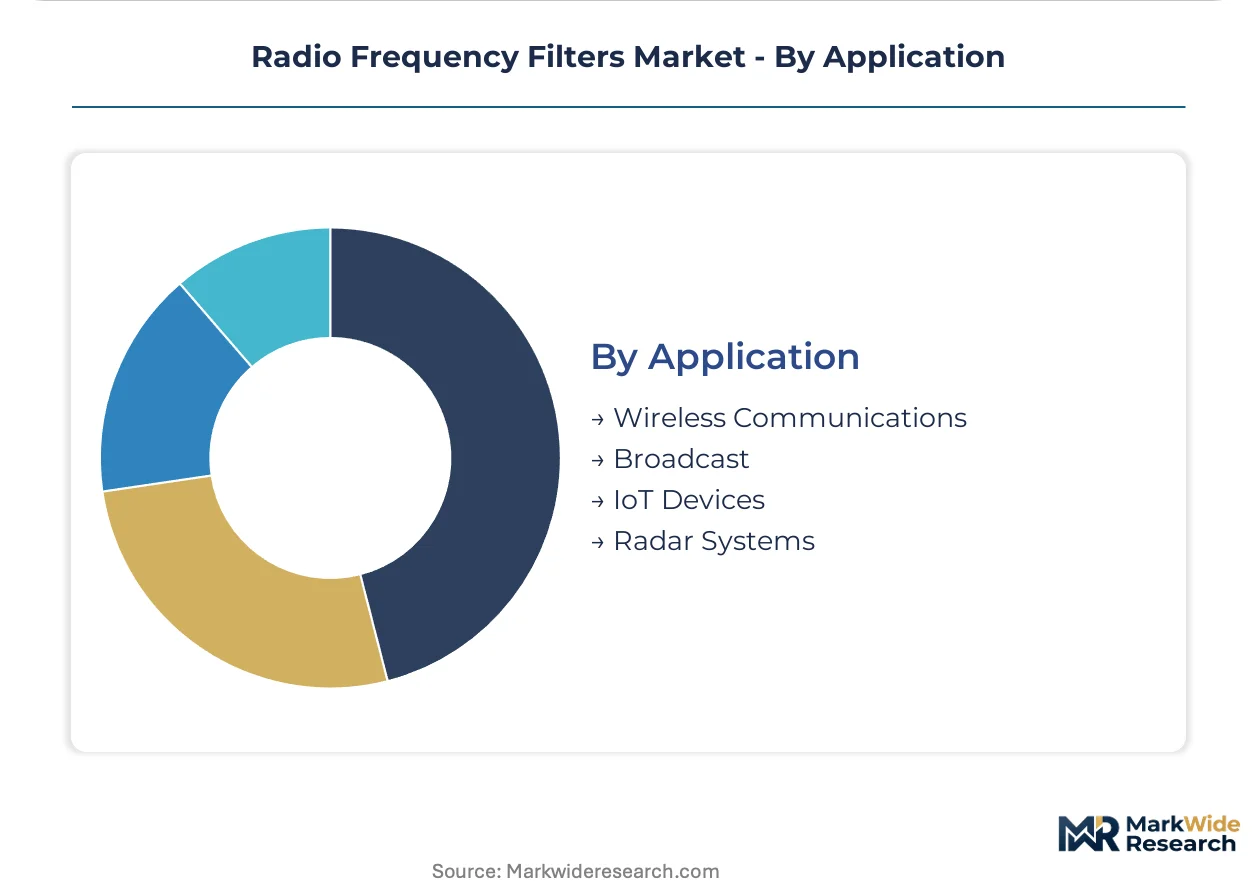
Application:
Use-case segmentation separates high-volume, short-lifecycle deployments from long-term infrastructure and defense programs with decade-plus procurement horizons.
- Wireless Communications:Cellular base stations, small cells, and distributed antenna systems constitute the largest addressable market. Sub-6 GHz and mmWave 5G buildout across multiple national infrastructure programs compresses filter design cycles.
- IoT Devices:Low-power wide-area networks and mesh sensor deployments are absorbing miniaturized SAW and BAW variants. Smart home and industrial monitoring segments specify compact, low-insertion-loss designs.
- Radar Systems:Military and civilian aviation radar depend on cavity filters for power handling and BAW for precision ranging. Coexistence requirements between commercial 5G and radar allocations intensify spectral purity demands.
- Broadcast:Terrestrial television and radio transmitters sustain cavity filter dominance where kilowatt-scale power handling exceeds solid-state thermal limits. Spectrum reallocation is devaluing legacy band configurations.
Wireless Communications commands the majority of revenue; IoT Devices shows the steepest expansion trajectory on wearable and sensor network deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate filter substrate fabrication capacity alongside smartphone OEM captive sourcing operations. These tax-advantaged manufacturing parks anchor the industry's supply-side geography.
United States
5G mid-band infrastructure deployment drives BAW filter procurement across tower operator networks. The FCC's spectrum reallocation mandates force equipment vendors toward sub-6 GHz and mmWave architectures before legacy band amortization completes. Austin and Dallas-Fort Worth clusters host RF front-end design centers serving defense and telecommunications verticals.
China
Domestic OEMs in Shenzhen and Dongguan manufacturing clusters expand captive filter sourcing agreements that bypass traditional distribution channels. MIIT spectrum allocation policies for 5G and satellite communications shape regional product variant requirements. Shanghai-based substrate vendors concentrate high-purity lithium niobate supply for SAW production at scale.
Japan
Piezoelectric material expertise concentrates among legacy substrate vendors in Kyushu and Kansai regions. METI industrial policy supports domestic BAW and SAW fabrication capacity for automotive and telecommunications export markets. Osaka-area ceramic specialists maintain process knowledge for temperature-compensated filter formulations.
Germany
Automotive Tier-1 suppliers in Baden-Württemberg qualify TC-SAW variants for C-V2X and telematics modules. ECHA REACH compliance deadlines restrict certain piezoelectric dopants, pushing suppliers toward lead-free substrate reformulations. Munich and Stuttgart engineering centers focus on filter-PA module integration for connected vehicle platforms.
South Korea
Seoul Capital Area conglomerates anchor RF front-end module production for flagship smartphone export programs. MFDS and RRA certification requirements for telecommunications equipment shape filter qualification protocols. Suwon and Pyeongtaek manufacturing complexes concentrate BAW filter fabrication for 5G infrastructure export contracts.
Radio Frequency Filters Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct technology-platform tiers. The vendor base organizes around three strategic archetypes: integrated module suppliers capturing front-end subsystem value, captive substrate specialists controlling piezoelectric material supply, and discrete component vendors serving cost-sensitive consumer electronics procurement. Consolidation pressure intensifies as smartphone OEMs reduce direct filter vendor relationships in favor of consolidated module procurement. Geographic expansion and technology licensing represent the dominant competitive moves as suppliers navigate region-specific certification requirements.
Among diversified RF component conglomerates, Broadcom Inc. and Qorvo, Inc. occupy positions exemplifying module-integration strategy, while Murata Manufacturing Co., Ltd. represents the substrate-specialist archetype with ceramic material expertise. These three entities anchor distinct competitive vectors: module-level subsystem capture, in-house fabrication insulation from foundry constraints, and piezoelectric substrate scale advantages respectively.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Murata Manufacturing Co., Ltd. |
| Qorvo, Inc. |
| Skyworks Solutions, Inc. |
| Analog Devices, Inc. |
| TDK Corporation |
| Anatech Electronics, Inc. |
| API Technologies Corp. |
| RS Microwave Company, Inc. |
| Others |
Value Chain & Pricing Dynamics
Piezoelectric substrate costs transmit directly from lithium niobate refiners in Japan and China through SAW filter pricing tiers, with premium BAW variants absorbing thin-film deposition equipment depreciation at the module level. Contract structures stratify across automotive qualification cycles, telecommunications infrastructure offtake agreements, and spot procurement for consumer electronics.
Pricing Analysis
Lead-time compression commands measurable premiums in BAW filter procurement, with tower operators paying up for six-week delivery windows against standard twelve-week cycles. Three-tier pricing structure across automotive-qualified, infrastructure-grade, and economy consumer variants separates certification investment recovery from commodity volume plays. Pricing pressure stems from China's domestic OEMs expanding captive sourcing that bypasses traditional distribution markups. Consumer electronics procurement shows highest price sensitivity, while aerospace and defense buyers absorb premiums for hermetic packaging and radiation-hardened specifications.
Supply Chain Analysis
Specialized MEMS process engineering availability concentrates in Kyushu, Osaka, and Austin engineering clusters, constraining BAW fabrication scaling regardless of capital deployment. High-purity lithium niobate and tantalate supply draws from Japanese and Chinese substrate vendors, with thin-film electrode materials sourcing from South Korean and German specialty chemical suppliers. Single-source vulnerability in piezoelectric material refining creates chokepoint exposure for SAW production. Distribution runs through consolidated front-end module integrators capturing filter value, compressing direct vendor relationships with smartphone OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained through BAW process engineering scarcity, with thin-film resonator fabrication expertise limiting output expansion despite infrastructure demand acceleration.
For Market Incumbents: Anchor position through backward integration into piezoelectric substrate supply, securing lithium niobate offtake before China's domestic OEMs lock captive sourcing. Accelerate TC-SAW qualification for automotive V2X modules before Tier-1 suppliers finalize dual-source architectures. Defend against module integrators displacing discrete filter relationships by embedding filtering deeper into power amplifier subsystems. For New Entrants and Emerging Players: Begin with India spectrum auction preparation cycles, positioning filter architectures for TRAI sub-GHz and mid-band reallocations before regulatory lock-in freezes design commitments. Target automotive C-V2X qualification as the most penetrable segment, where TC-SAW temperature stability requirements create entry barriers below BAW capital intensity. Pursue direct qualification with Baden-Württemberg Tier-1 suppliers seeking dual-source resilience for connected vehicle platforms. For Investors and Strategic Acquirers: FCC spectrum reallocation acceleration is the leading indicator that BAW capacity utilization will tighten further, validating foundry-independent fabrication assets. Long-term viability centers on substrate-to-module integration plays over discrete component specialists facing margin compression. Target acquisition archetype: mid-cap BAW specialists with in-house MEMS lines and automotive qualification pipelines. Monitor MIIT spectrum allocation announcements for China infrastructure export contract inflections.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | Captive lithium niobate sourcing insulates Murata and Japanese vendors from Chinese export controls. |
| Automotive TC-SAW Qualification | Temperature-compensated variants unlock C-V2X and telematics procurement from Bosch and Continental. |
| Filter-PA Module Convergence | Integration with power amplification captures front-end subsystem value from Qorvo and Broadcom. |
| India Spectrum Pre-positioning | Early TRAI alignment secures architecture commitments before sub-GHz auction finalization. |
| REACH-Compliant Substrate Reformulation | Lead-free piezoelectric layers maintain ECHA-compliant access to German automotive and EU infrastructure markets. |
Study Parameters
Multi-period observation of 5G base station deployment rates, FCC spectrum auction timelines, and MIIT allocation announcements anchored the trend analysis, supplemented by interviews with RF front-end procurement managers at smartphone OEMs, tower operator network engineers, Tier-1 automotive supplier quality directors, and piezoelectric substrate vendor sales executives. Secondary validation drew from FCC docket filings, ECHA REACH substance restriction updates, TRAI consultation papers, and SEC 10-K disclosures from diversified RF component conglomerates. Bottom-up filter unit demand modeling triangulated against top-down telecommunications infrastructure capex forecasts.
Input-output matrices mapped SAW and BAW unit volumes through technology platform, product type, end-user certification tier, and application use-case across the projection horizon. Segmentation dimensions included filter architecture, passband configuration, customer-type qualification burden, and regional regulatory cluster. CAGRs derived from curve-fitting historical deployment patterns against announced infrastructure buildout schedules, with 5G mid-band spectrum release timing and automotive V2X mandate adoption curves as primary forecast inputs.
Underlying measurement precision varies by segment; consumer electronics volume estimates carry tighter precision than aerospace qualification pipeline projections. Forecasts embed assumptions regarding spectrum reallocation timing, substrate material supply continuity, and MEMS fabrication capacity expansion. Material deviation in FCC auction acceleration, ECHA restriction expansion, or China export control tightening warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Space Traveling Wave Tube Amplifiers Market
RF Components
Japan Small Signal Transistor Market
RF Components
Microwave Devices Market
RF Components
China Small Signal Transistor Market
RF Components
Radio Frequency Duplexer Market
RF Components
RFID Antenna Market
RF Components
RF Duplexer Market
RF Components
EMI Microwave Absorber Market
RF Components
RF-Microwave for 5G Market
RF Components
Silicon Tuners Market
RF Components
Acoustic Wave Filters Market
RF Components
Global Ceramic Dielectric Filters Market
RF Components
Frequency Synthesizer Market
RF Components
Digital Phase Shifter Market
RF Components
RF Tester Market
RF Components
433MHz Active RFID Reader Market