
 Pottery Ceramics Market | 2026-2036
Pottery Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Pottery Ceramics Market Intelligence
The gap between premium studio ceramics and commodity-grade tableware is rebalancing as raw-material costs and energy tariffs compress mid-tier margins. Laguna Clay Company leverages its vertical control over domestic kaolin deposits to sustain pricing power in the artist-supply channel. Dick Blick Holdings Inc. anchors its position through a dense North American retail and e-commerce network that reaches hobbyists and educational institutions. CCGNZ Group Limited differentiates via specialized stoneware formulations tailored to Australasian firing conditions and local glaze preferences.
Pottery ceramics encompass fired clay bodies shaped by hand or mold and vitrified at temperatures ranging from 1,000°C for porous earthenware to 1,400°C for fully dense porcelain, serving functional, decorative, and architectural purposes across consumer and industrial markets. Porcelain commands the highest value per kilogram due to its translucency and strength in fine-dining tableware, while earthenware retains volume leadership in decorative art and hobbyist segments where lower firing costs matter. The sanitary ware application sits at a mature plateau in developed markets but draws replacement demand from water-efficiency mandates that favor advanced ceramic trapway designs.
REACH in Europe and EPA emissions guidelines in the United States constrain lead-based glaze formulations and kiln particulate output, pushing manufacturers toward certified raw-material suppliers and afterburner retrofits. India's BIS ceramicware safety standards and China's GB standards for domestic tableware further fragment compliance requirements for exporters serving multiple jurisdictions. Stakeholders must monitor how tightening energy-efficiency codes interact with artisanal production methods that rely on traditional kiln architectures.
Market Dynamics
Energy-efficiency mandates from the EPA and REACH are compressing mid-tier kiln operations while concentrating production in Vietnam's ceramics belt near Hanoi, where legacy craft skills intersect with export-oriented infrastructure.
Growth Catalysts
- Boutique hospitality procurement:Handcrafted tableware demand from independent hotel and restaurant chains favors artisanal supply chains over mass-manufactured alternatives.
- REACH compliance premium:European lead-free glaze certifications create pricing power for certified raw-material suppliers serving fine-dining porcelain segments.
- Water-efficiency retrofits:Municipal mandates for low-flow sanitary ware drive replacement cycles for advanced ceramic trapway designs in aging building stock.
Market Restraints
- Natural gas price volatility:Kiln firing costs swing with European and Asian energy markets, squeezing earthenware producers dependent on continuous high-temperature processes.
- Kaolin deposit concentration:Domestic US clay mining control by vertically integrated suppliers limits pricing leverage for mid-size pottery studios and educational distributors.
- Sanitary ware substitution:Engineered stone and solid-surface bathroom fixtures capture share in premium residential renovations where ceramic once dominated.
Strategic Opportunities
- Vietnam export manufacturing:Labor-cost advantages and craft heritage in the Red River Delta attract contract production for European and North American tableware brands.
- Carbon-capture kiln retrofits:EU Green Deal funding streams subsidize afterburner and heat-recovery installations that reduce emissions while preserving traditional firing aesthetics.
- Direct-to-artist e-commerce:Specialized clay and glaze formulations bypass wholesale distributors through subscription replenishment models targeting hobbyist and educational segments.
Industry Challenges
- Master-craft succession gaps:Traditional wheel-throwing and kiln-firing expertise concentrates in aging practitioners without structured apprenticeship pipelines.
- Multi-jurisdiction certification lag:India's BIS ceramicware safety standards, China's GB domestic tableware rules, and US FDA food-contact requirements impose overlapping testing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pottery Ceramics Market |
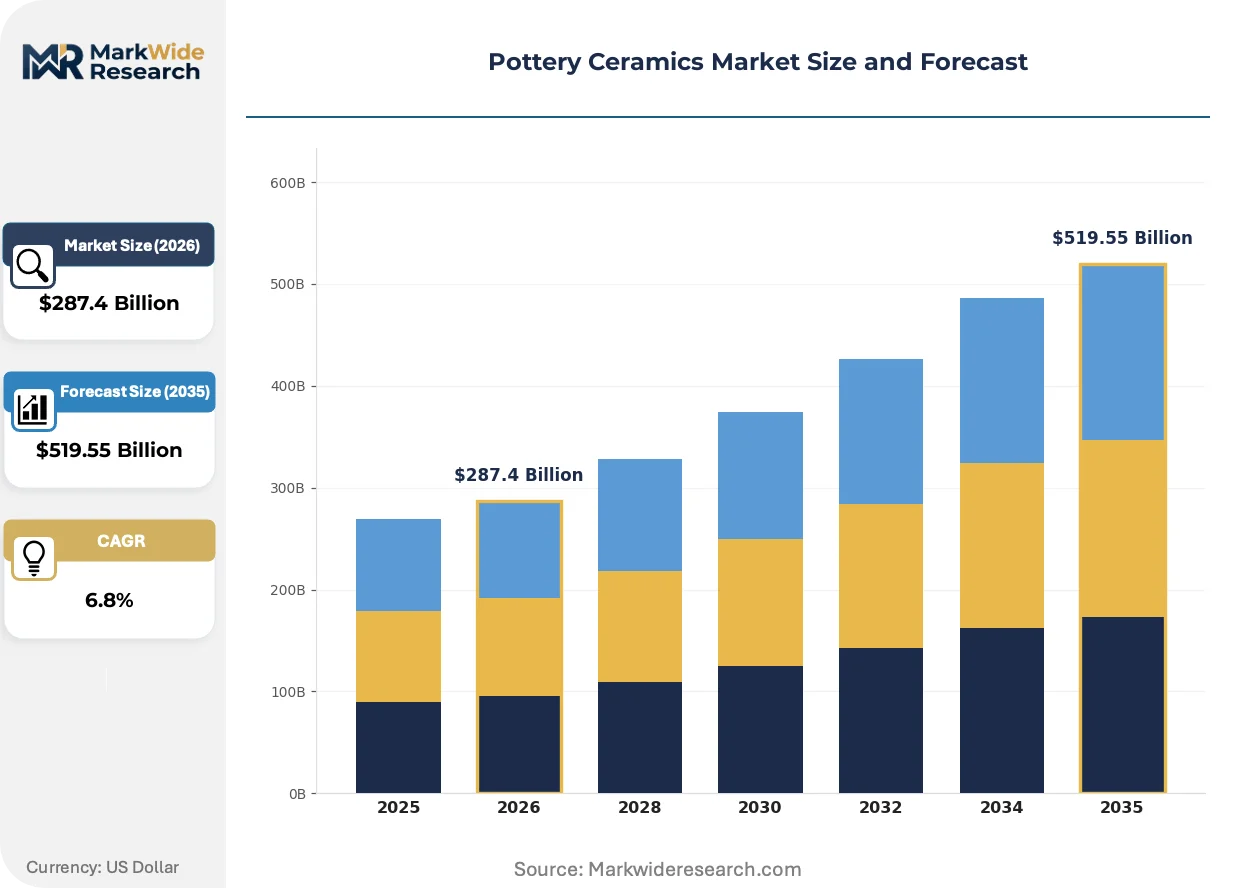
| Market Size in 2026 | $287.4 Billion |
| Market Size in 2035 | $519.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Earthenware, Stoneware, Porcelain, Bone China Application: Tableware, Decorative Art, Tiles, Sanitary Ware Technique: Handcrafted, Wheel-Thrown, Slip-Casting, Slip-Trailing End User: Household, Commercial, Industrial, Artists |
| Companies Covered | American Art Clay Co., Inc. (AMACO), Laguna Clay Company, Sheffield Pottery Inc., Dick Blick Holdings Inc., CCGNZ Group Limited, Bluematchbox Potters Supplies Ltd, Clay-King, Bhoomi Pottery, Saho Ceramics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pottery Ceramics Market Strategic Shifts & Innovations
Digital design tools and emissions-monitoring systems are penetrating pottery production workflows, altering how studios prototype, fire, and certify ceramic outputs for commercial distribution.
Electric kiln controllers with programmable ramp-soak profiles are unifying precision temperature management across studio and industrial scales. Boutique tableware manufacturers adopt these systems to replicate hand-built aesthetics with batch consistency. The technology is unifying previously separate artisanal and automated production quality tiers.
REACH Annex XVII restrictions on lead and cadmium in ceramic glazes tighten enforcement across EU member states. Manufacturers reformulate legacy recipes or source certified raw materials from ECHA-registered suppliers. Fine-dining porcelain exporters to Europe face the steepest compliance costs and timeline pressures.
Certification-driven purchasing now dominates hospitality procurement decisions. Independent restaurant groups prioritize FDA-compliant and California Proposition 65-tested tableware over uncertified artisanal alternatives. This preference shift concentrates volume with suppliers maintaining documented testing protocols, particularly in coastal US and Western European urban markets.
Pottery Ceramics Market Segmentation
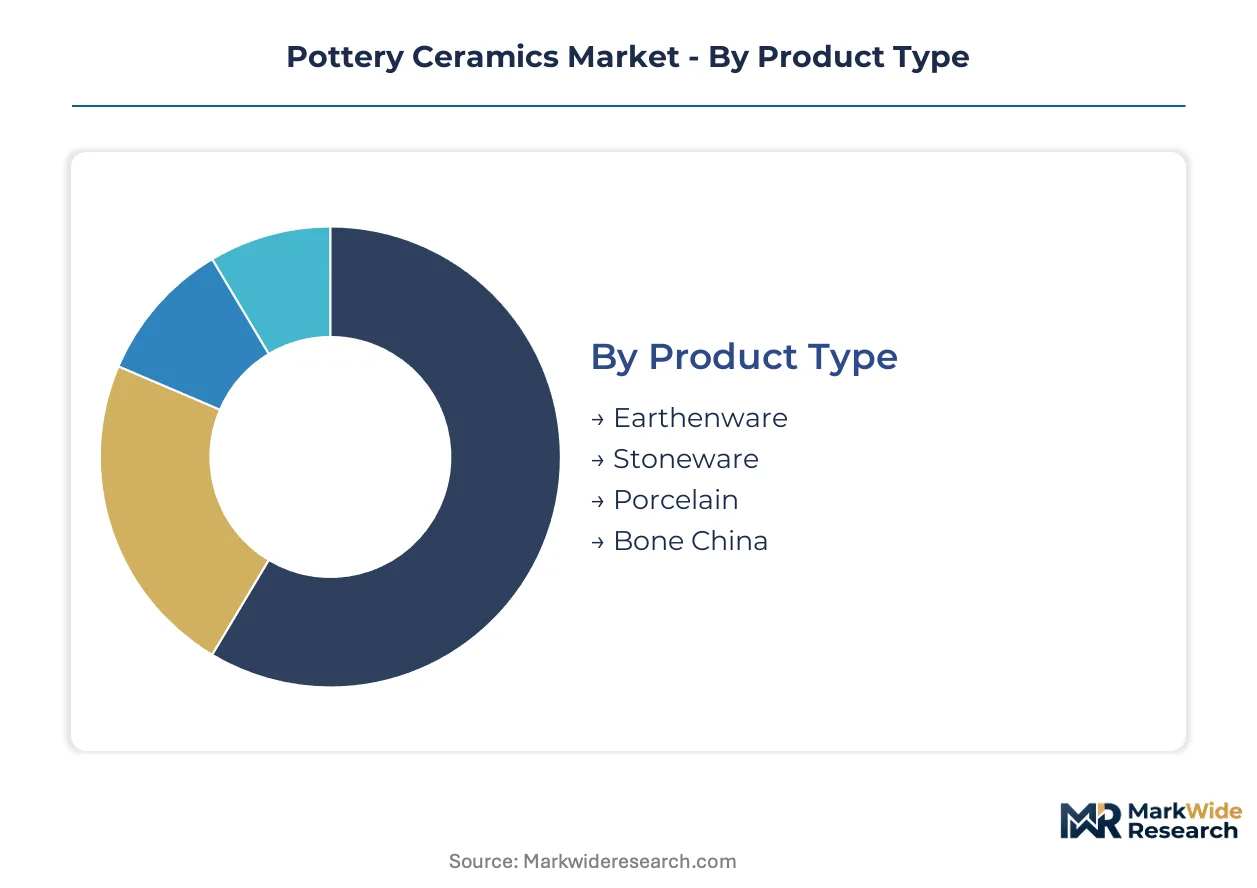
Pottery ceramics segmentation reveals how firing temperature, clay composition, and end-use durability requirements partition value capture across the supply chain. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier positioning.
Product Type:
Supply concentration in high-purity kaolin deposits determines which ceramic bodies command pricing power in artist and hospitality channels.
- Porcelain:Fired above 1,200°C to achieve vitrification and translucency, this body demands premium-grade kaolin with low iron content. Demand concentrates in fine-dining tableware procurement from boutique hotel chains in France and Japan where REACH-compliant lead-free glazes are mandatory. The EPA emissions retrofit burden falls heaviest here due to extended high-temperature firing cycles.
- Stoneware:Dense and non-porous at 1,200-1,300°C, this segment tolerates lower-grade clay bodies with higher flux content. Australia's CCGNZ Group specializes in formulations adapted to local kiln atmospheres and wood-firing traditions. Water-efficiency mandates in California and Germany drive replacement demand for stoneware-based sanitary ware trapways.
- Earthenware:Porous below 1,100°C, this low-fire body dominates hobbyist supply chains and decorative art where Laguna Clay's domestic deposit control anchors North American distribution.
- Bone China:Incorporates bone ash for exceptional whiteness and strength, serving formal tableware segments in the United Kingdom and Commonwealth markets with heritage procurement preferences.
Today's leader: Porcelain. Tomorrow's challenger: Stoneware.
Application:
Cost tier stratification separates commodity volume from certified premium channels where compliance documentation commands price premiums.
- Tableware:Functional dining and serving pieces face the steepest certification stack—FDA food-contact, California Proposition 65, and REACH Annex XVII converge here. Dick Blick's e-commerce density captures educational and hobbyist volume while independent studios serve boutique hospitality.
- Sanitary Ware:Toilets, sinks, and bidets sit at replacement-driven maturity in the United States and Europe. India's BIS standards and water-efficiency codes in Germany and California favor advanced ceramic trapway geometries over legacy designs.
- Decorative Art:Sculptural and ornamental ceramics operate outside food-contact regulation, allowing traditional lead-based glazes where local law permits.
- Tiles:Architectural surfacing demands scale production with pressed-body uniformity; Vietnam's Red River Delta cluster attracts contract manufacturing for European specification.
Certification intensity peaks in tableware. Volume scale concentrates in tiles.
Technique:
Customer type determines whether production tolerates artisanal variability or requires automated repeatability.
- Handcrafted:Coil-building and slab-construction methods serve studio potters and limited-edition tableware where irregularity signals authenticity. Master-craft succession gaps in Japan and Italy threaten supply continuity.
- Wheel-Thrown:Centered rotational forming produces functional vessels with radial symmetry; Dick Blick's educational channel distributes tools and clay bodies to university programs across the United States.
- Slip-Casting:Liquid clay poured into plaster molds enables complex hollow forms at production scale, dominating sanitary ware and architectural tile manufacture.
- Slip-Trailing:Decorative line application with liquid clay serves ornamental traditions in British studio pottery and Korean celadon revival movements.
Handcrafted commands the highest per-unit margin. Slip-casting captures the widest volume base.
End User:
Maturity gradients separate saturated replacement markets from expansion segments where penetration depth still varies.
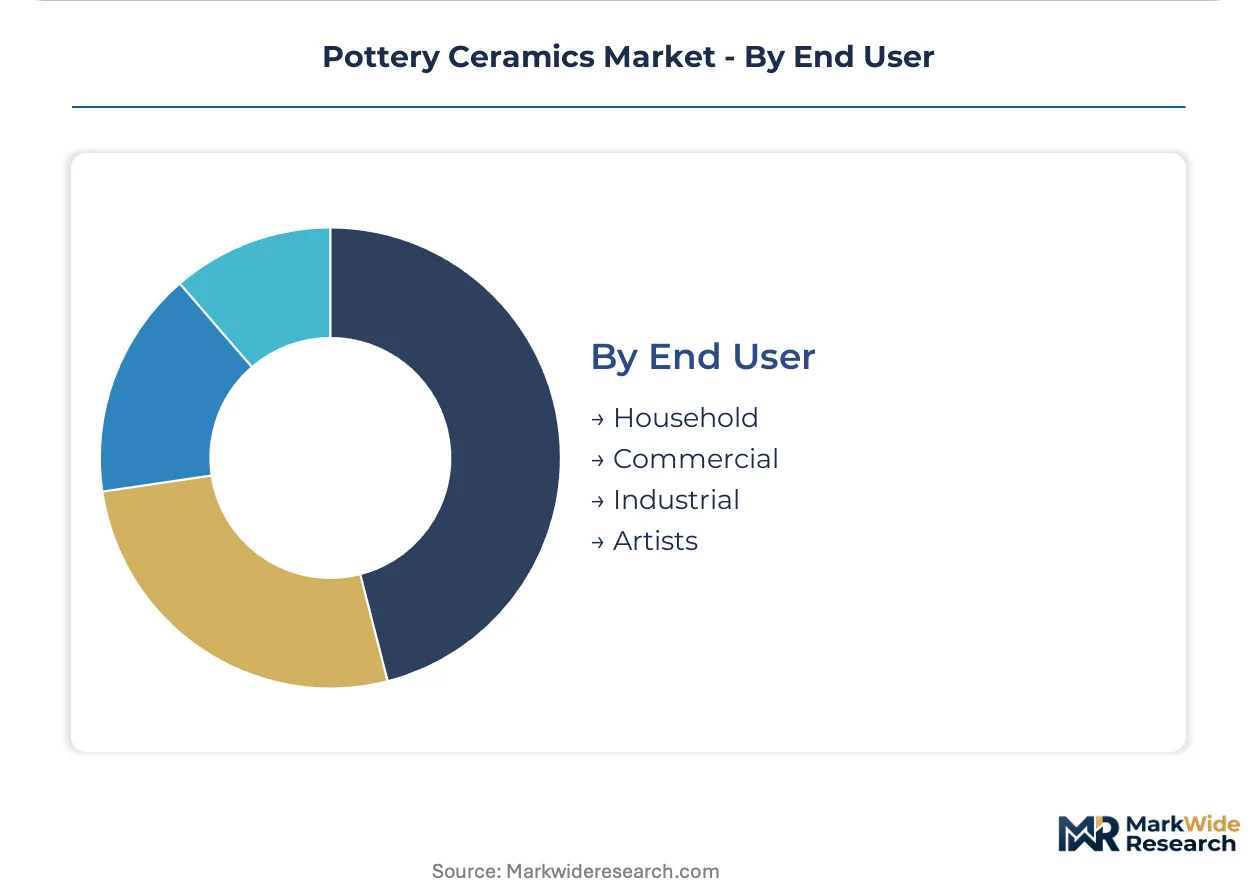
- Commercial:Restaurants, hotels, and institutional foodservice drive certified tableware procurement with documented testing protocols. REACH compliance premiums filter supplier pools to ECHA-registered raw-material sources.
- Household:Consumer replacement cycles stretch 10-15 years for dinnerware, compressing to 5-7 years for casual entertaining sets. E-commerce subscription models for clay and glaze replenishment target this segment.
- Artists:Studio potters and ceramic sculptors purchase through specialized distributors requiring technical support and firing consultation. Laguna Clay's vertical kaolin control sustains artist-channel pricing power.
- Industrial:Technical ceramics for aerospace and electronics fall outside traditional pottery scope; this category captures refractory and insulator applications with specification-grade alumina bodies.
Commercial procurement enforces the tightest compliance standards. Artist channels preserve the deepest craft heritage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master potters and kiln technicians concentrate in Vietnam's Red River Delta, Italy's Emilia-Romagna, and Japan's Arita region, anchoring export-oriented production clusters that supply hospitality and artist channels across North America and Europe.
United States
Boutique hospitality chains in California and New York drive handcrafted tableware procurement with documented FDA food-contact testing. EPA emissions guidelines constrain natural gas kiln operations in Ohio and Pennsylvania ceramics belts. Dick Blick's educational distribution network reaches university programs from Illinois to Texas.
Vietnam
Export contract manufacturing for European tableware brands expands near Hanoi where labor costs intersect with craft heritage. The country's national standards body aligns ceramicware safety protocols with import market requirements. Bat Trang village anchors production of REACH-compliant porcelain for French and German hospitality procurement.
Italy
Fine-dining restaurant groups in Milan and Florence source lead-free glazed stoneware from Emilia-Romagna workshops. ECHA-registered raw material suppliers serve reformulation needs under REACH Annex XVII. Faenza maintains its historic ceramics district with EU Green Deal subsidies for kiln efficiency retrofits.
Japan
Arita and Seto master craftsmen face succession gaps as aging practitioners retire without structured apprenticeship pipelines. METI industrial heritage programs fund knowledge transfer initiatives in Saga and Gifu prefectures. Kyoto's Kiyomizu-dera district preserves traditional wood-firing aesthetics for luxury hospitality export.
Germany
Water-efficiency mandates in Bavaria and Baden-Württemberg drive replacement demand for advanced ceramic sanitary ware. EU Green Deal funding streams subsidize afterburner installations in industrial kilns. The country's central environmental authority enforces particulate emissions standards that favor certified raw-material sourcing.
Pottery Ceramics Market Key Industry Players
Top-tier vendors anchor artist-supply and educational channels, while mid-tier specialists serve regional hospitality procurement with localized formulations. The vendor base spans vertically integrated clay miners, dense retail networks, and craft-heritage workshops. Three archetypes dominate: domestic deposit controllers, distribution density builders, and firing-condition specialists. Competitive moves concentrate on backward integration into kaolin sourcing and e-commerce subscription models for hobbyist replenishment.
Among North American deposit controllers, Laguna Clay Company exemplifies upstream captive supply strategies. Dick Blick Holdings Inc. represents distribution density archetypes reaching educational institutions through combined retail and digital channels. CCGNZ Group Limited occupies a position as a firing-condition specialist tailoring stoneware bodies to Australasian kiln atmospheres.
| Leading Market Players |
|---|
| American Art Clay Co., Inc. (AMACO) |
| Laguna Clay Company |
| Sheffield Pottery Inc. |
| Dick Blick Holdings Inc. |
| CCGNZ Group Limited |
| Bluematchbox Potters Supplies Ltd |
| Clay-King |
| Bhoomi Pottery |
| Saho Ceramics |
| Others |
Cost & Logistics Intelligence
Premium-mid-economy pricing differentiation in pottery ceramics manifests through REACH certification ladders that reshape both margin capture and sourcing geography. European hospitality procurement demands ECHA-registered glaze suppliers, compressing mid-tier studios unable to absorb compliance costs while concentrating volume with vertically integrated deposit controllers.
Pricing Analysis
Service bundling splits the market between certified tableware with documented testing protocols and unbundled raw-material supply for hobbyist segments. Price differentiation hinges on REACH Annex XVII compliance grade and volume scale, with boutique hospitality chains least sensitive to per-unit premiums. Cost compression in earthenware intensifies because natural gas volatility erodes continuous-firing margins, while educational distributors face acute price sensitivity from institutional budget cycles.
Supply Chain Analysis
Regional distribution centers in Vietnam's Red River Delta, Italy's Emilia-Romagna, and the United States' Ohio-Pennsylvania belt anchor hub-and-spoke fulfillment to hospitality and artist channels. Kaolin deposits in Georgia, Devon, and Jiangxi feed formulation dependencies, with single-source vulnerability concentrated in high-purity porcelain-grade clay. Distribution runs through specialized ceramics distributors rather than general industrial channels, reflecting technical consultation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII enforcement compounds demand for certified supply chains, with ECHA registration deadlines accelerating procurement consolidation toward documented producers.
For Market Incumbents: To counter natural gas cost volatility, secure captive kaolin supply in Georgia or Devon deposits while retrofitting kilns with EU Green Deal-subsidized afterburners. Certification investment in FDA food-contact documentation preserves hospitality channel access against uncertified artisanal substitutes. For New Entrants and Emerging Players: Capture Vietnam's export manufacturing white space by contracting Bat Trang village production for European tableware brands. Direct-to-artist e-commerce subscriptions offer the most penetrable entry vector, bypassing Dick Blick's educational distribution density through replenishment automation. For Investors and Strategic Acquirers: Consolidation pressure builds where master-craft succession gaps intersect with REACH compliance cost burdens. Long-term viability favors acquisition targets with ECHA-registered raw-material sourcing and established apprenticeship pipelines. Watch EPA emissions guideline tightening as the inflection signal for kiln retrofit capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kaolin Deposits | Captive supply of Georgia or Devon clay secures margin control against commodity price swings. |
| REACH Certification Investment | ECHA-registered glaze formulations unlock fine-dining hospitality procurement in France and Germany. |
| EU Green Deal Kiln Retrofit | Afterburner installations preserve traditional firing aesthetics while meeting emissions standards. |
| Direct-to-Artist E-commerce Launch | Subscription replenishment models bypass wholesale distributors serving hobbyist segments. |
| Vietnam Export Manufacturing Partnership | Bat Trang village production leverages labor-cost advantages and craft heritage for European brands. |
Research Approach
Multiple input streams — primary interviews with kiln operators, glaze formulators, and hospitality procurement managers; secondary validation against ECHA registration databases, EPA emissions filings, and ceramics trade association records; plus customs data on kaolin and finished ware flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include ceramic body type, firing technique, end-use application, and regional regulatory cluster. CAGRs were derived from trend extrapolation of artisanal production capacity, energy cost trajectories, and certification adoption curves, with kiln efficiency retrofits and master-craft succession rates as pottery-specific forecast inputs.
Natural gas price spikes, ECHA enforcement intensity shifts, and apprenticeship pipeline collapse are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global Industrial Clay Market
Ceramics
Aragonite Market
Ceramics
Refractory Material Market
Ceramics
Global Alumina Market
Ceramics
Global Thermal Ceramics Market
Ceramics
China Ceramic Market
Ceramics
Kaolin Market
Ceramics
Clay Market
Ceramics
Calcite Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
Calcined Kaolin Market
Ceramics
Lithium Silicate Market
Ceramics
Ceramic Frit Market
Ceramics
Lithium Zirconate Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
US Kaolin Market